
 Stainless Steel Toilet Paper Dispenser Market | 2026-2036
Stainless Steel Toilet Paper Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Stainless Steel Toilet Paper Dispenser Market Insights
Wholesale distribution is fragmenting across the stainless steel toilet paper dispenser landscape as direct-to-facility procurement gains ground. Bobrick leverages its long-standing relationships with institutional buyers to sustain specification-grade positioning in North American commercial construction. Georgia-Pacific competes through backward integration into paper products, bundling dispensers with consumables contracts. Rentokil Initial anchors its presence across European hospitality chains through integrated hygiene service agreements that embed hardware placement.
Stainless steel toilet paper dispensers are wall-mounted or surface-mounted fixtures fabricated from austenitic grades, typically 304 or 316 stainless steel with brushed or polished finishes, designed to house and dispense toilet paper rolls in high-use environments. The primary commercial purpose centers on vandal resistance, hygiene compliance, and reduced maintenance intervals in airports, stadiums, hospitals, and office complexes. Jumbo roll configurations lead in institutional settings where refill frequency directly impacts labor costs, while wall-mounted designs dominate new construction where recessed installation preserves corridor width. The hospitality end user segment shows the fastest structural expansion as boutique hotels and restaurant groups specify designer-grade finishes to align restroom aesthetics with brand identity.
OSHA workplace sanitation guidelines and the EPA's WaterSense program indirectly shape fixture specifications by elevating overall restroom infrastructure standards in US commercial buildings. REACH compliance in the European Union governs surface treatment chemicals used in passivation and electropolishing processes, adding cost layers for exporters. FDA sanitation requirements in healthcare settings drive specification of seamless welded constructions that eliminate bacterial harborage points. Stakeholders must monitor evolving green building certification thresholds that increasingly weight embodied carbon in metal fixtures against operational durability.
Market Dynamics
Facilities managers across commercial real estate are consolidating vendor relationships to reduce restroom maintenance complexity, compressing procurement decisions toward integrated hygiene service contracts that bundle hardware, consumables, and scheduled maintenance into single-source agreements.
Growth Catalysts
- OSHA workplace sanitation guidelines:Elevated restroom infrastructure standards in US commercial buildings mandate durable, easily sanitized fixtures that resist bacterial harborage. Building operators specify grade 304 stainless steel to satisfy inspection protocols.
- Hospitality brand differentiation:Boutique hotel chains and restaurant groups invest in designer-grade brushed finishes to align restroom aesthetics with interior design narratives. This specification tier commands premium positioning.
- Japan's public building codes:Vandal-resistant fixture mandates in transit hubs, government facilities, and educational institutions create steady replacement demand for surface-mounted jumbo roll dispensers.
Market Restraints
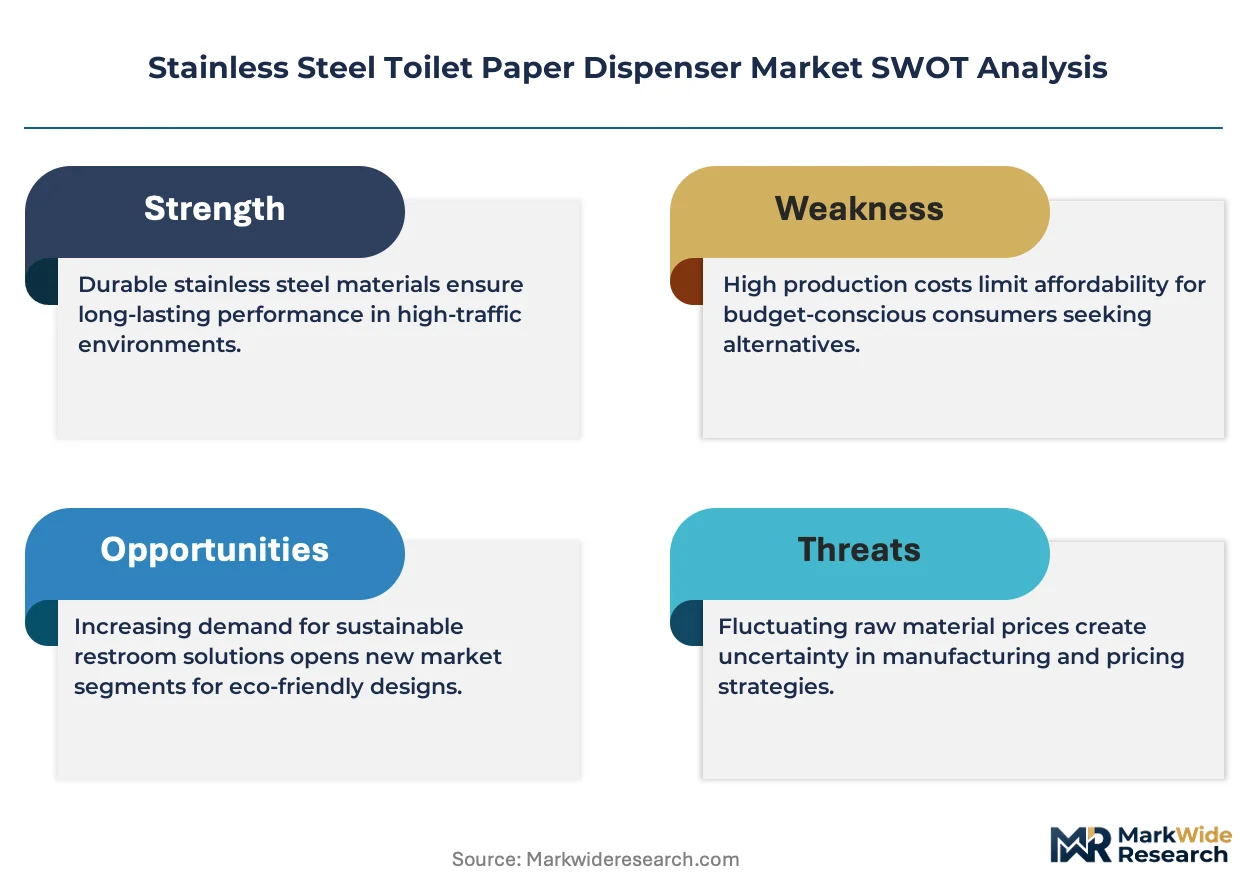
- Nickel price volatility:Austenitic grades 304 and 316 contain 8-10.5% nickel by weight. Mining supply disruptions in Indonesia and the Philippines transmit directly to mill pricing, squeezing fabricator margins.
- REACH compliance layers:European Union surface treatment regulations govern passivation and electropolishing chemicals. Exporters face documentation burdens and testing costs that disadvantage smaller manufacturers.
- Plastic dispenser substitution:ABS and polycarbonate alternatives offer 40-60% lower unit costs for budget-constrained municipal procurement. Price-sensitive segments in developing economies default to polymer options.
Strategic Opportunities
- Smart restroom convergence:IoT-enabled fill-level sensors integrated with stainless housings enable predictive maintenance routing. Facility management platforms in Germany and the United States pilot these configurations.
- Green building certification thresholds:LEED and BREEAM frameworks increasingly weight embodied carbon against operational durability. Extended service life of metal fixtures versus plastics creates specification advantage.
- Healthcare construction expansion:FDA sanitation requirements for seamless welded constructions eliminate bacterial harborage points. Hospital renovation cycles in the United States favor electropolished 316 grade specifications.
Industry Challenges
- Skilled welder shortage:Seamless construction for healthcare-grade dispensers requires certified TIG welders proficient in sanitary finishing. Fabricators in Germany and Japan compete for this limited labor pool.
- Legacy infrastructure incompatibility:Surface-mounted retrofit installations must accommodate irregular wall substrates in aging commercial buildings. Mounting hardware standardization lags across regional construction practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stainless Steel Toilet Paper Dispenser Market |
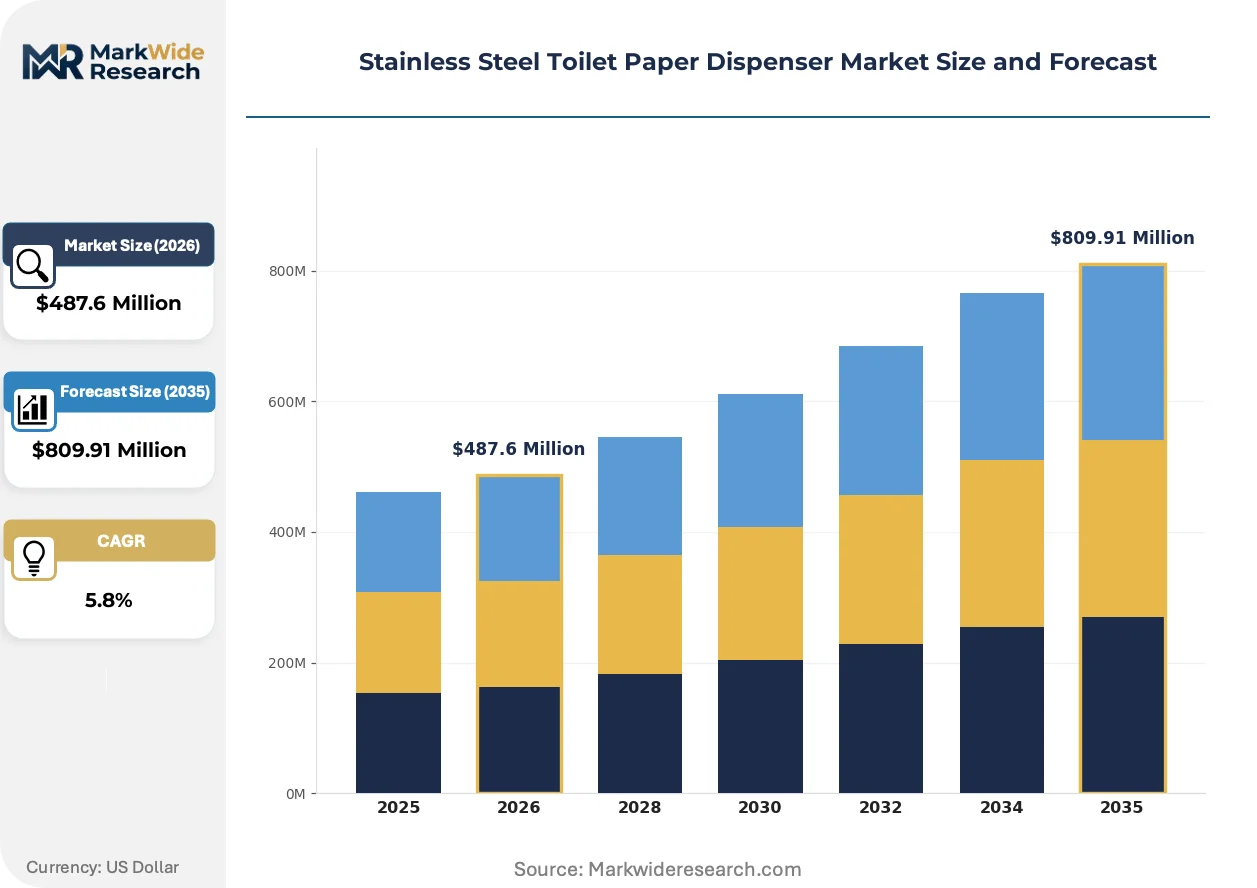
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Roll, Double Roll, Jumbo Roll, Wall-mounted End User: Commercial, Residential, Hospitality, Healthcare Design: Modern, Classic, Minimalist, Industrial Distribution Channel: Online, Offline, Direct Sales, Wholesale |
| Companies Covered | Bobrick, ASI, Bradley, Essity, Dolphin Solutions, Rentokil Initial, Georgia-Pacific, Ningbo Power (Joro) Sanitary Electrical Appliance, SCA Hygiene Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stainless Steel Toilet Paper Dispenser Market Trends and Innovations
Digital monitoring capabilities are penetrating restroom infrastructure, transforming passive fixtures into data collection nodes that optimize janitorial labor deployment and consumable replenishment cycles.
Touchless dispensing mechanisms utilizing infrared proximity sensors are virtualizing the user interaction layer in high-traffic environments. Airport authorities and stadium operators in the United States and Germany prioritize these configurations to reduce surface contact transmission vectors. The technology is virtualizing competitive positioning by embedding sensor hardware into specification-grade housings, compressing differentiation toward software integration rather than metal fabrication alone.
REACH authorization requirements for chromium trioxide in passivation processes are tightening chemical supply chains serving European fabricators. Manufacturers must submit substitution plans or secure time-limited authorizations, adding regulatory compliance overhead. German and French producers respond by accelerating transition to citric acid-based passivation alternatives that satisfy corrosion resistance specifications without restricted substances.
Bundled hygiene service contracts are displacing transactional hardware procurement across European hospitality chains. Rentokil Initial and similar integrated facility service providers embed dispenser placement within multi-year consumables agreements. This model concentrates buyer power with fewer decision-makers and compresses distributor margins, particularly visible in United Kingdom and German hotel portfolio renewals.
Stainless Steel Toilet Paper Dispenser Market Segmentation
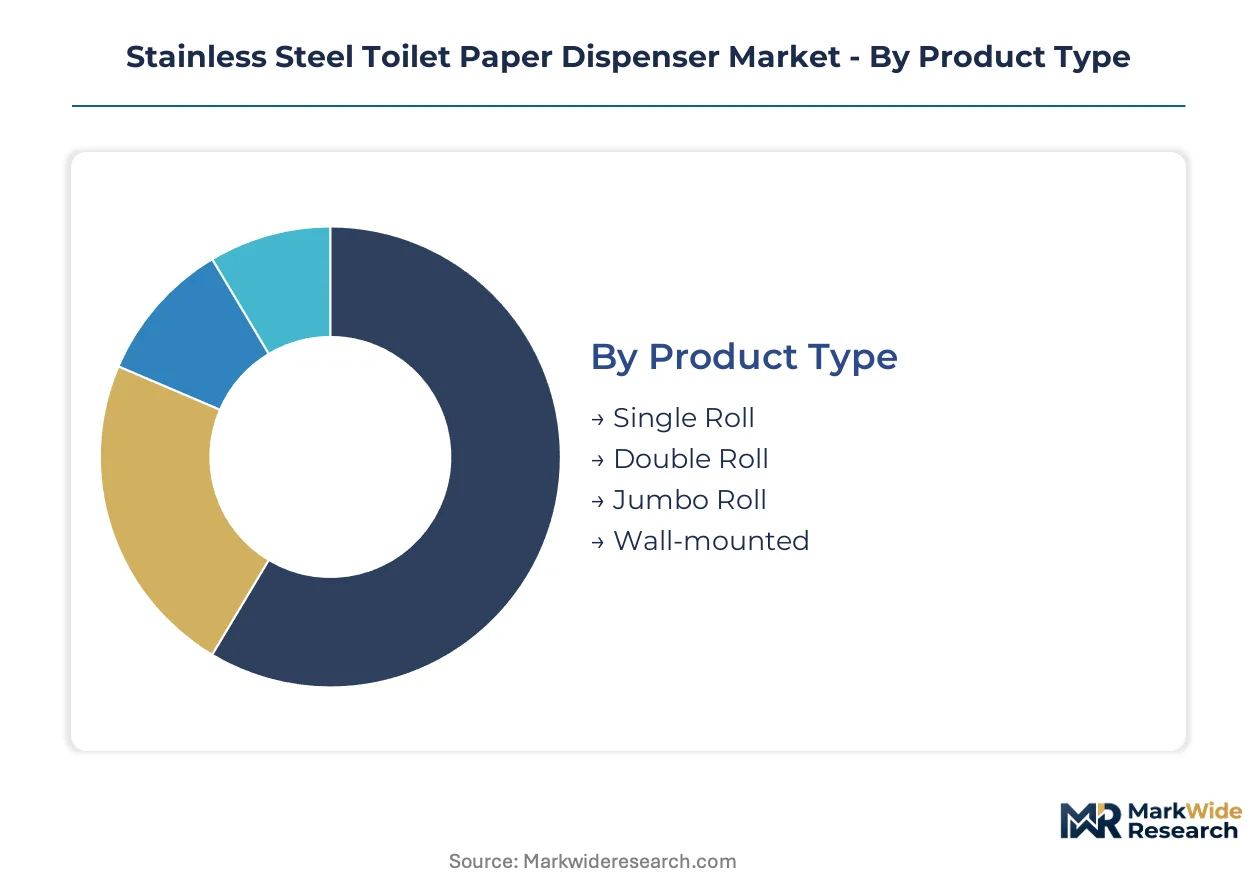
Segmentation in the stainless steel toilet paper dispenser market reflects divergent procurement logics across facility types, from vandal-resistant institutional specifications to aesthetic-driven hospitality interiors. Procurement channels and design preferences further stratify competitive positioning among fabricators serving distinct buyer workflows.
Product Type:
Use-case spectrum spans high-frequency institutional environments to compact residential installations, with roll capacity and mounting configuration determining labor economics and spatial compatibility.
- Jumbo Roll:High-capacity configurations accommodate 9-12 inch diameter rolls in grade 304 housings with reinforced spindle mechanisms. Airport authorities in Germany and stadium operators in the United States specify these to minimize refill frequency and janitorial labor deployment.
- Wall-mounted:Recessed or surface-mounted designs integrate with commercial restroom architecture, preserving corridor width in new construction. Demand concentrates in Japan's transit hubs where building codes mandate vandal-resistant surface mounting in high-traffic public facilities.
- Single Roll:Compact housings suit low-traffic restrooms in small offices and retail locations where space constraints override capacity requirements.
- Double Roll:Dual-spindle configurations provide backup roll availability, reducing stockout risk in medium-traffic commercial settings.
Established volume favors wall-mounted; emerging adoption favors jumbo roll.
End User:
Cost tier stratification separates specification-grade institutional procurement from price-sensitive residential replacement cycles.
- Hospitality:Boutique hotel chains and restaurant groups specify brushed or polished grade 304 finishes to align restroom aesthetics with interior design narratives. This specification tier commands premium positioning and fastest volume expansion among end-user categories.
- Healthcare:FDA sanitation requirements drive seamless welded constructions in grade 316 stainless steel with electropolished surfaces that eliminate bacterial harborage points. Hospital renovation cycles in the United States favor these specifications.
- Commercial:Office complexes and retail locations prioritize vandal resistance and durability in high-traffic environments.
- Residential:Homeowners and small landlords select based on aesthetic preference with lower corrosion resistance requirements than institutional grades.
Procurement scale favors commercial; margin expansion favors hospitality.
Design:
Application context determines whether functional anonymity or deliberate aesthetic statement drives specification.
- Modern:Clean lines and brushed finishes dominate hospitality and corporate restroom renovations seeking contemporary alignment with interior architecture.
- Minimalist:Reduced visual mass and concealed mounting hardware appeal to design-forward boutique properties in Germany and Japan.
- Classic:Traditional profiles with visible hinges and rounded edges persist in heritage building restorations and conservative institutional settings.
- Industrial:Exposed fasteners and utilitarian finishes serve manufacturing facilities and warehouse operations where function dominates form.
Specification frequency favors modern; design fee premiums favor minimalist.
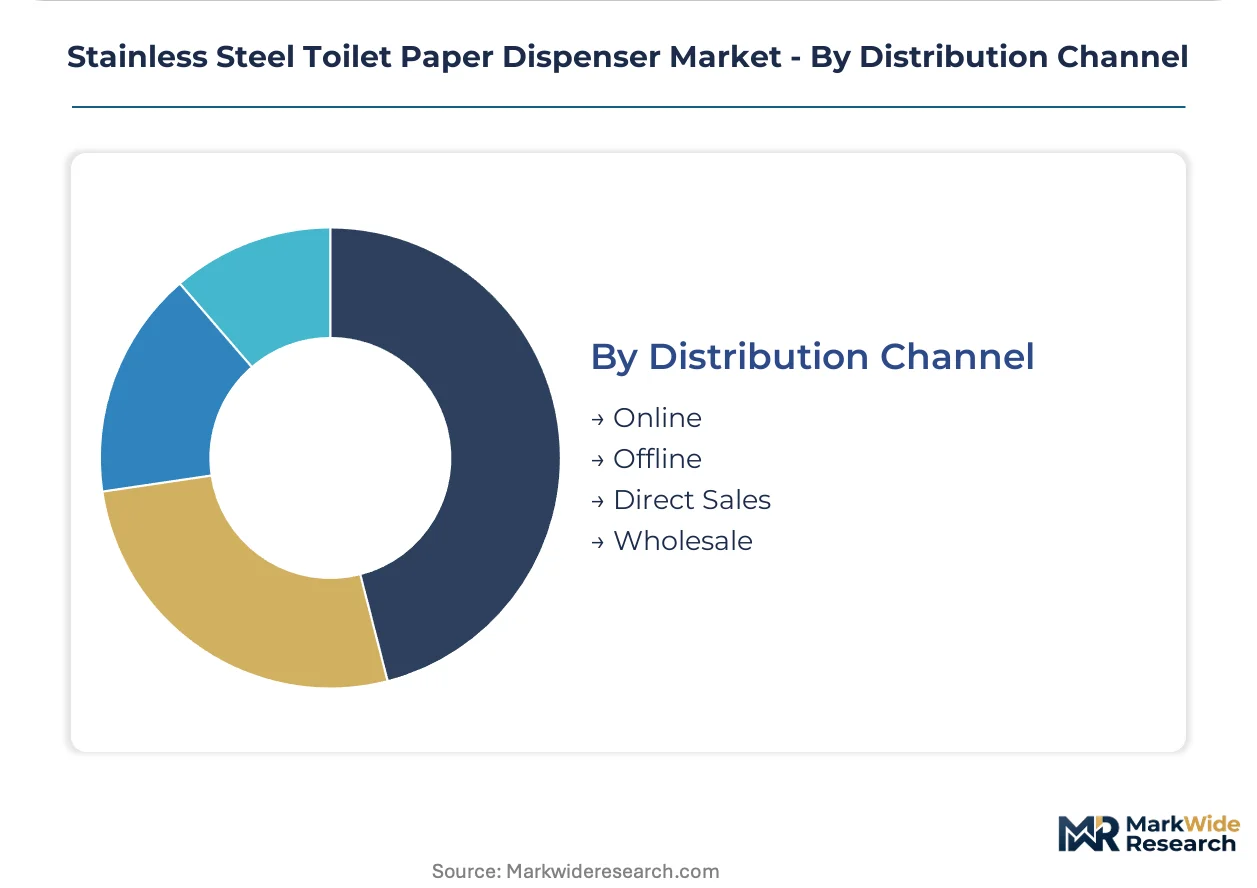
Distribution Channel:
Customer type and order scale determine whether transactional efficiency or relationship-based service drives channel selection.
- Direct Sales:Large hospitality chains and healthcare systems negotiate multi-year agreements with fabricators for specification-grade product with customized finishes. Rentokil Initial leverages this channel across European hotel portfolios.
- Wholesale:Distributors serve contractors and facilities managers in fragmented commercial real estate markets, though this channel faces compression from integrated hygiene service contracts.
- Online:E-commerce platforms capture residential and small commercial replacement demand with standardized product configurations and rapid fulfillment.
- Offline:Showroom-based specification persists for hospitality design consultants requiring tactile finish evaluation before bulk procurement.
Transaction volume favors wholesale; contract value favors direct sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fabricators command premium pricing power through REACH-compliant surface treatment expertise, while Chinese producers compete on mill-direct stainless steel sourcing. This asymmetry shapes procurement patterns across institutional and hospitality segments.
United States
Airport authorities and stadium operators drive specification-grade demand for vandal-resistant fixtures. OSHA workplace sanitation guidelines mandate durable, easily sanitized dispensers in commercial buildings. Fabrication clusters in the Midwest serve healthcare renovation cycles with FDA-compliant seamless welded constructions.
Germany
Transit hub operators and boutique hotel chains prioritize designer-grade finishes with corrosion-resistant specifications. REACH authorization requirements for chromium trioxide tighten chemical supply chains, accelerating citric acid-based passivation alternatives. Industrial fabricators in Baden-Württemberg lead this regulatory transition.
Japan
Public building codes mandate vandal-resistant surface-mounted dispensers in educational institutions and government facilities. METI standards govern stainless steel grades in high-traffic environments. Manufacturing concentration in the Chubu region around Nagoya supplies jumbo roll configurations for rail network restrooms.
United Kingdom
Hospitality portfolio renewals favor integrated hygiene service contracts over transactional procurement. BREEAM green building certification weights embodied carbon against operational durability. London-based facilities managers specify brushed grade 304 finishes for boutique hotel restroom renovations.
China
Domestic mill capacity for austenitic grades 304 and 316 supports cost-competitive fabrication for export markets. GB standards govern surface finish specifications in public infrastructure projects. Yangtze River Delta producers supply wall-mounted configurations for Southeast Asian hospitality developments.
Stainless Steel Toilet Paper Dispenser Market Competitive Landscape
Integrated hygiene service providers and standalone fixture fabricators split the market between bundled contracts and specification-grade hardware procurement. The vendor base concentrates around three strategic archetypes: multinational facility service platforms, regional mill-direct fabricators, and design-forward specialty producers. Competitive moves center on backward integration into consumables supply and geographic expansion through distributor partnerships.
Among European-anchored service platforms, Rentokil Initial exemplifies the integrated hygiene contract model across hotel portfolios. Georgia-Pacific represents backward integration into paper products, bundling dispensers with consumables agreements. Bobrick occupies a position within the North American specification-grade tier, leveraging institutional buyer relationships. These three anchors illustrate divergent paths to procurement influence without overlapping strategic territory.
| Leading Market Players |
|---|
| Bobrick |
| ASI |
| Bradley |
| Essity |
| Dolphin Solutions |
| Rentokil Initial |
| Georgia-Pacific |
| Ningbo Power (Joro) Sanitary Electrical Appliance |
| SCA Hygiene Products |
| Others |
Pricing and Supply Chain Analysis
Nickel price volatility in Indonesian and Philippine mining operations compresses fabricator margins while simultaneously widening spreads between specification-grade and commodity-tier procurement. This raw material instability forces buyers toward longer-term offtake contracts and drives supply chain regionalization around mill-direct sourcing in Germany, China, and Japan.
Pricing Analysis
The customization-premium spread separates electropolished 316 grade healthcare specifications from brushed 304 standard commercial configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with hospitality design-forward finishes commanding substantial premiums. Cost compression in economy tiers intensifies because ABS plastic substitution erodes stainless steel share in municipal procurement. Budget-constrained developing economy buyers exhibit highest price sensitivity; integrated hygiene service contract signatories in European hospitality show lowest.
Supply Chain Analysis
REACH authorization restrictions on chromium trioxide in European surface treatment processes constrain passivation chemical flows and accelerate supply chain restructuring. Manufacturing concentration centers on Germany, China, and Japan, with Yangtze River Delta producers leveraging domestic austenitic grade capacity for export competitiveness. Raw material sourcing draws from Indonesian nickel laterite, Chinese ferrochrome, and Japanese precision spindle components. Single-source vulnerability concentrates in certified TIG welder availability for seamless healthcare-grade construction. Distribution runs through integrated facility service providers displacing traditional wholesale channels across European hospitality portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated hygiene service contract consolidation across European hotel chains and North American healthcare systems. This procurement centralization compresses distributor margins and elevates specification influence for bundled service providers.
For Market Incumbents: Build switching-cost moats through embedded IoT sensor integration and predictive maintenance platform lock-in. Deepen backward integration into consumables supply to defend against Georgia-Pacific's paper-product bundling. Capture certified welder talent pools in Germany and Japan before healthcare renovation cycles accelerate. Prioritize REACH-compliant citric acid passivation investment to preempt regulatory displacement of chromium-based processes. For New Entrants and Emerging Players: Establish a beachhead in smart restroom convergence by partnering with German facility management platforms piloting fill-level sensor deployments. Target mid-tier hospitality chains in Southeast Asia seeking designer-grade finishes without legacy vendor relationships. Exploit the skilled welder shortage through automated laser welding differentiation for healthcare specifications. Pursue direct-to-facility digital sales channels bypassing wholesale compression. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated service platforms with captive hardware placement. Long-term viability hinges on recurring revenue attachment rates rather than transactional fixture margins. Acquisition targets should display established hygiene service contract portfolios with multi-year renewal visibility. Monitor nickel price trajectory and REACH authorization timelines as inflection indicators for margin structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Consumables | Bundling toilet paper supply with dispenser placement locks in multi-year hospitality contracts against standalone competitors. |
| Smart Sensor Integration | IoT-enabled fill-level monitoring transforms passive fixtures into data nodes for predictive janitorial routing in German airports. |
| Green Certification Transition | Citric acid passivation alternatives satisfy REACH compliance while preserving corrosion resistance for European export markets. |
| Healthcare-Grade Welding Capacity | Certified TIG welder acquisition enables seamless 316 grade construction for FDA-compliant hospital renovation cycles. |
| Direct-to-Facility Digital Channel | E-commerce platforms bypass wholesale margin compression for small commercial and residential replacement demand. |
Research Methodology
The analysis maps jumbo roll, wall-mounted, single roll, and double roll configurations, each validated through facilities managers, hospitality procurement directors, healthcare biomedical engineers, and stainless steel fabrication plant managers. Primary interviews with these stakeholders combined with secondary validation from customs trade data, SEC filings of integrated hygiene service providers, building code documentation from Germany and Japan, and REACH authorization databases. Bottom-up unit economics triangulate against top-down market sizing across product type, end user, design, and distribution channel dimensions.
Assumptions held fixed include current OSHA workplace sanitation guideline enforcement levels, REACH authorization timelines for restricted substances, and nickel price banding consistent with recent mining supply patterns. Variables tested across the projection horizon encompass hospitality brand differentiation investment rates, healthcare construction cycle timing, and smart restroom technology adoption curves. CAGRs derive from segment-level volume buildups incorporating replacement cycle frequencies and new construction fixture intensity by building type. Forecast inputs include airport passenger traffic projections and boutique hotel development pipelines.
Macroeconomic conditions sit as an overlay; deviation in construction spending, nickel commodity pricing, or hospitality capital expenditure cycles would shift the trajectory. Forecasts reflect these documented assumptions and industry-specific risk factors including regulatory acceleration of chemical restrictions and plastic substitution thresholds in municipal procurement. Material shifts in integrated hygiene service contract penetration or REACH substance authorization outcomes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Bladeless Neck Fan Market
Household Items
Powered Lawn Mowers Market
Household Items
Stainless Steel Water Bottles Market
Household Items
Cutlery Steel Market
Household Items
Global Residential Robotic Vacuum Cleaner Market
Household Items
Industrial Floor Mats Market
Household Items
Stick Vacuum Cleaner Market
Household Items
HEPA Vacuum Cleaners Market
Household Items
Pet Fur Remover Market
Household Items
Toilet Care Wipes Market
Household Items
Drain Cleaners Market
Household Items
Europe Coin-Operated Laundries Market
Household Items
Smart Toilet Market
Household Items
Handheld Fans Market
Household Items
Heated Mattress Pads Market
Household Items
Electric Mop Market