
 Global Electric Scissors Market | 2026-2036
Global Electric Scissors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electric Scissors Market Analysis
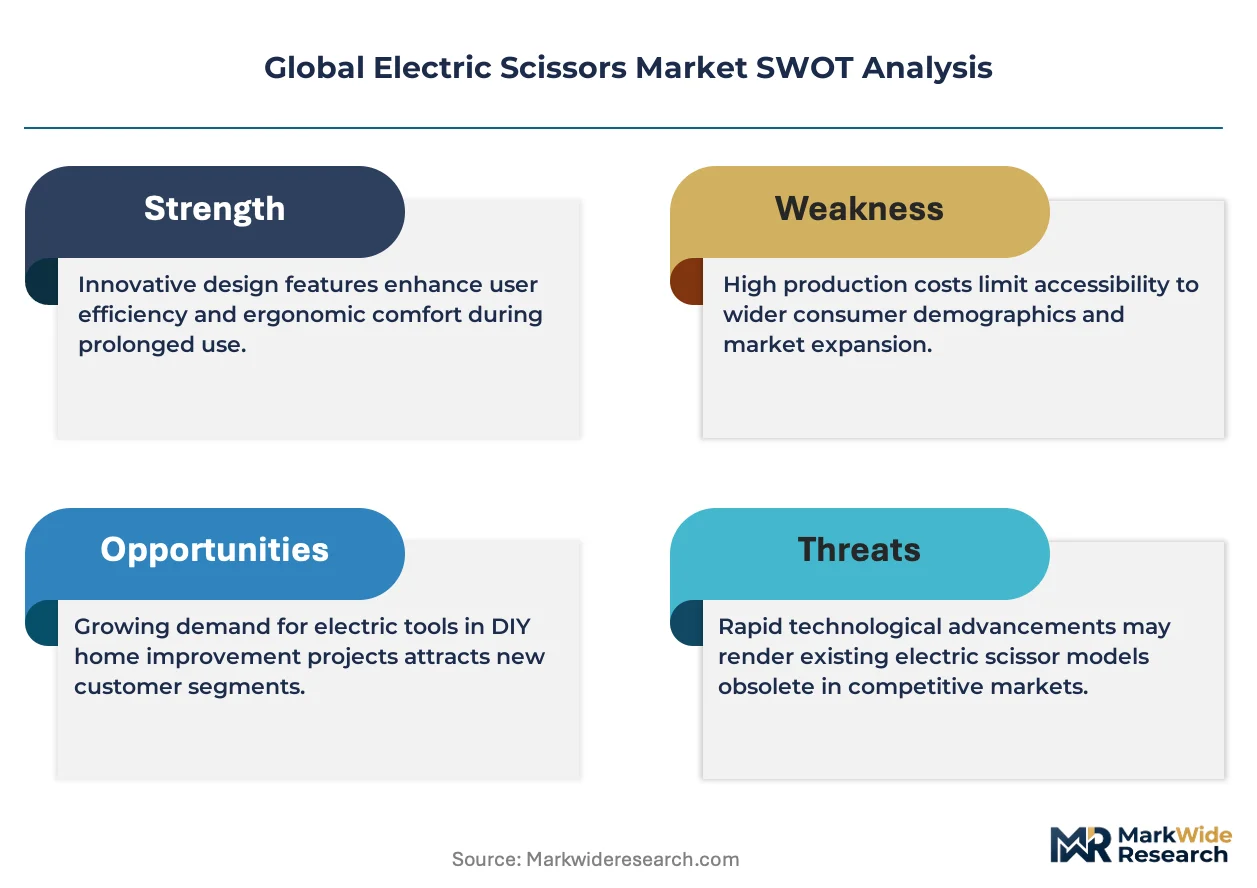
China's Zhejiang province is fragmenting as new OEM entrants challenge established export-focused manufacturers. Stanley Black & Decker leverages its cordless power-tool ecosystem to cross-sell electric scissors through shared battery platforms. Makita Corporation anchors its position with brushless motor technology originally developed for its professional-grade rotary tools. Robert Bosch GmbH competes on precision engineering standards transferred from its automotive sensor division.
Electric scissors are motorized cutting instruments powered by rechargeable lithium-ion cells or AC adapters, typically employing rotary or electromechanical drive mechanisms with hardened steel blades rated for specific material gauges. These devices serve industrial and commercial users requiring repetitive, fatigue-reducing cuts through textiles, composites, or medical dressings. Battery-operated models capture expanding share among mobile artisans and field medical units where cord tethering limits maneuverability. Electromechanical technology leads in factory settings demanding programmable cut depths and cycle counts, while rotary mechanisms dominate household and crafting segments for their simplicity and lower maintenance burden.
FCC certification governs electromagnetic emissions for cordless models sold in the United States, while the EU's REACH framework restricts hazardous substances in blade coatings and plastic housings. China's GB standards, administered by SAMR, mandate safety interlocks and battery thermal protection for domestic and export-bound production. Japan's METI enforces PSE marking on lithium-ion power systems, creating a compliance threshold that filters lower-tier suppliers from premium distribution channels. Stakeholders must monitor how divergent battery safety protocols across these jurisdictions reshape sourcing strategies and product platform architectures.
Market Dynamics
Battery platform standardization across cordless power tools is forcing electric scissors manufacturers to redesign motor housings and electronic controllers for cross-compatibility with existing lithium-ion ecosystems.
Growth Catalysts
- REACH compliance migration:European blade coating reformulations are accelerating demand for ceramic-based alternatives that eliminate hexavalent chromium. Manufacturers retooling for ECHA standards capture premium retail placement.
- Textile automation:Garment factories in Vietnam and Bangladesh deploy electric scissors for pattern cutting to reduce repetitive strain injuries. Industrial safety inspectors mandate motorized alternatives for high-volume facilities.
- Brushless motor diffusion:Rotor designs eliminating carbon brushes extend duty cycles and reduce maintenance intervals. Workshop operators in Germany and Japan specify brushless models for continuous production environments.
Market Restraints
- Lithium-ion cell cost volatility:Cathode material price swings, particularly nickel and cobalt, compress gross margins on battery-operated units. OEMs face margin pressure when long-term supply contracts expire.
- Zhejiang supplier concentration:Over 60% of global blade forging capacity sits within 150 kilometers of Ningbo port. Disruptions to this cluster propagate through export channels with limited alternative sourcing.
- Manual shear substitution resilience:Artisan tailors in India and Indonesia retain hand-operated tools for delicate fabrics. Price-sensitive segments resist motorized premiums despite ergonomic benefits.
Strategic Opportunities
- Medical field deployment:Surgical dressing and orthotic fabrication units in the United States and Germany require sterile, portable cutting instruments. Battery-operated models with autoclavable housings address unmet clinical demand.
- EU Green Deal alignment:Circular economy mandates for repairable electronics create openings for modular designs with replaceable battery packs and blade cartridges. Products scoring high on durability indices qualify for public procurement preferences.
- Aerospace composite processing:Carbon fiber and Kevlar cutting applications demand precision depth control. Electromechanical systems with programmable stops penetrate aircraft maintenance and satellite manufacturing workflows.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous FCC, CE, and PSE approvals extend product launch cycles by 8-14 months. Testing laboratory capacity constraints in Shenzhen and Tokyo create bottlenecks.
- Legacy equipment integration:Factory automation retrofits require electric scissors to communicate with existing PLC networks via proprietary protocols. Middleware development consumes engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electric Scissors Market |
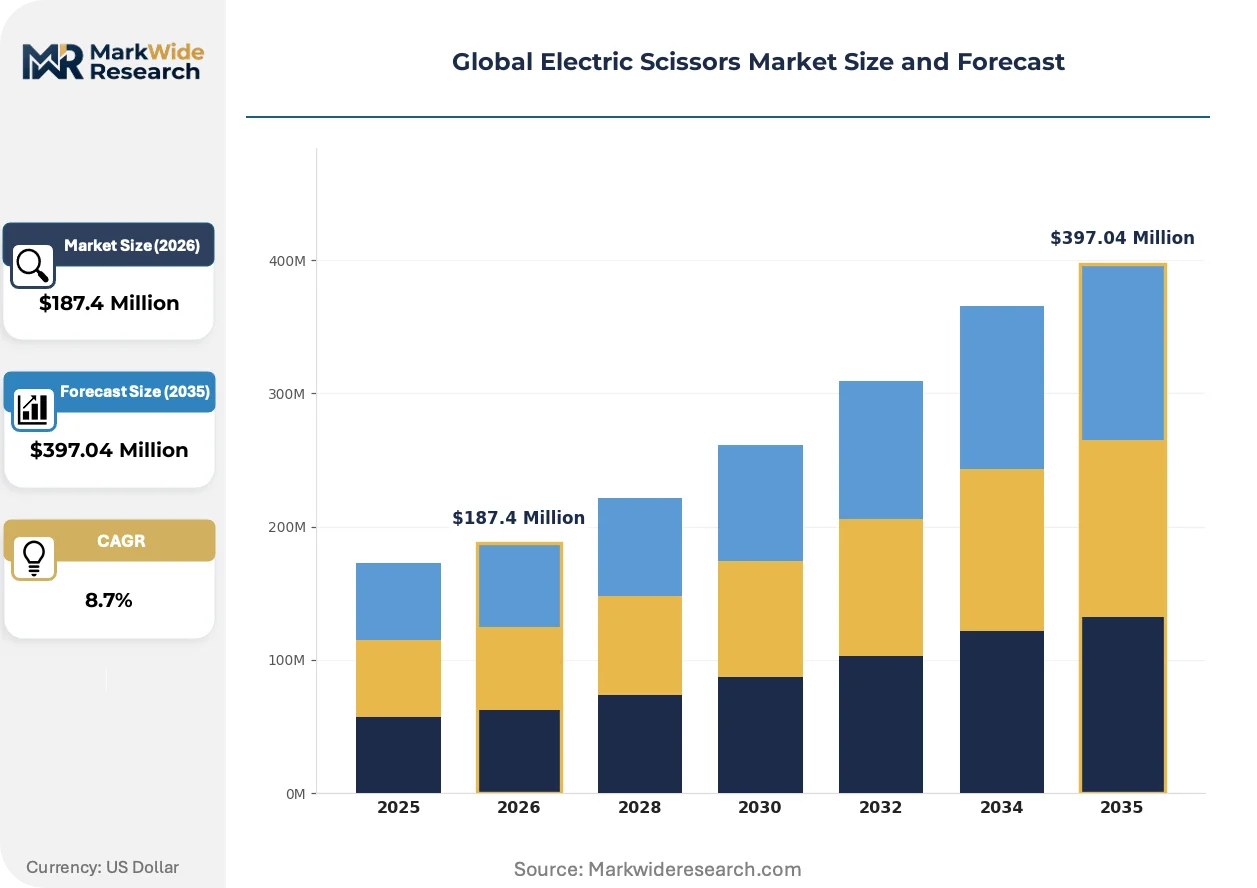
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
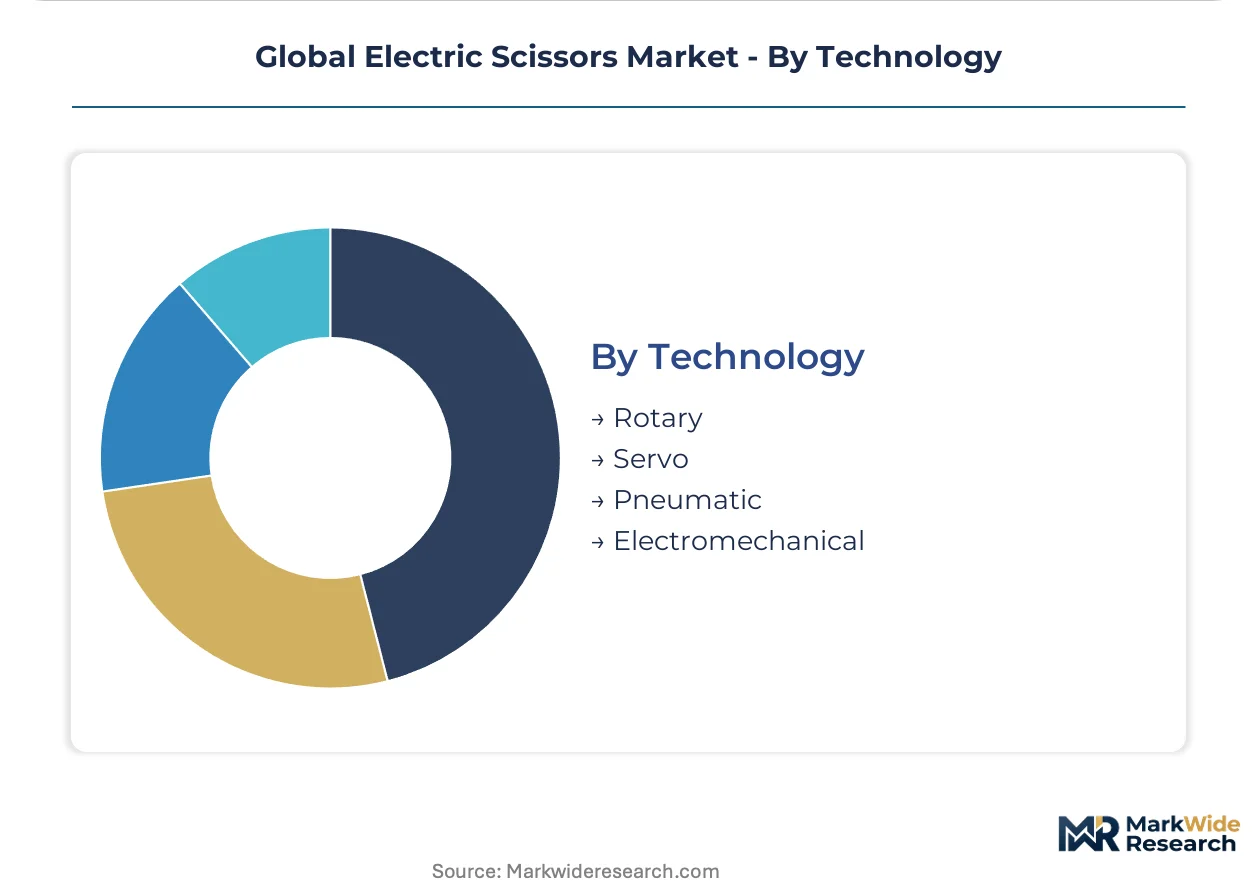
| Segmentation | Product Type: Battery-operated, Corded, Professional, Household Application: Textile Cutting, Crafting, Medical Usage, Industrial Manufacturing End User: Hospitals, Tailoring Shops, Artisans, Factories Technology: Rotary, Servo, Pneumatic, Electromechanical |
| Companies Covered | Stanley Black & Decker, Robert Bosch GmbH, Makita Corporation, WORX (Positec Tool Corp.), DeWALT, Infaco, Pink Power Tools, Xiamen WBT Electric Industrial Trade, Zhejiang Feihu New Energy Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electric Scissors Market Emerging Trajectories
Digital twin technology is penetrating electric scissors development cycles, compressing prototyping phases and enabling predictive maintenance algorithms before hardware reaches factory floors.
Brushless DC motor controllers with integrated Hall-effect sensors are virtualizing traditional mechanical limit switches and contact-based safety interlocks. Medical device manufacturers in Germany adopt these solid-state systems for sterilization tolerance. The elimination of physical switches reduces failure points and enables firmware-updatable safety profiles.
ECHA's 2023 amendment to REACH Annex XVII restricts per- and polyfluoroalkyl substances in non-stick blade coatings. Coating suppliers in the Netherlands and Finland accelerate ceramic-silicone hybrid formulations. Industrial buyers in France and Italy now specify PFAS-free certifications in tender documents, filtering suppliers unable to reformulate.
Direct-to-workshop e-commerce channels are disintermediating traditional industrial distributors for replacement blade and battery sales. Amazon Business and Alibaba 1688 capture growing share from regional tool wholesalers. This pattern concentrates in North American small contractor segments where buyers prioritize price transparency and rapid delivery over technical consultation.
Global Electric Scissors Market Segmentation
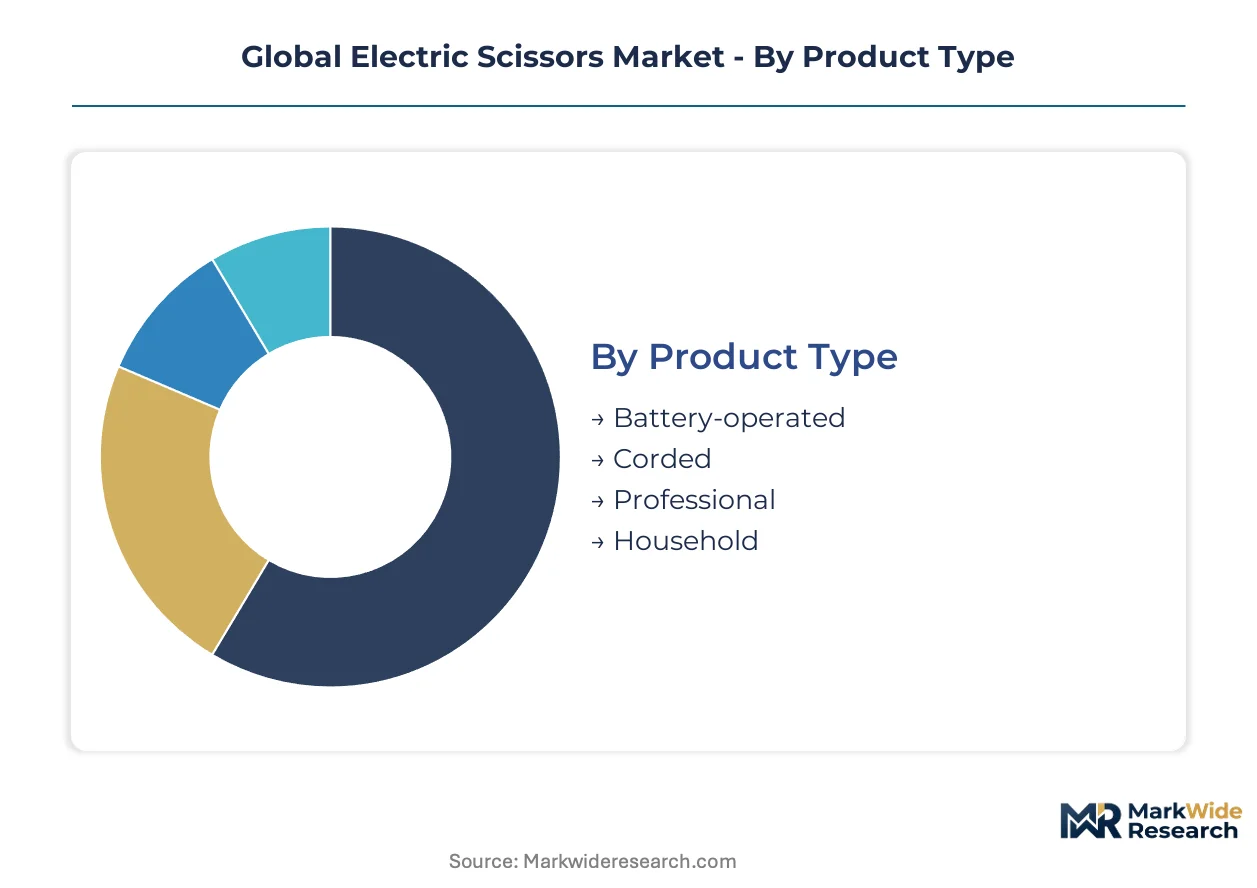
Segmentation in electric scissors reveals divergent service lifecycles and replacement part economics. Battery platforms and blade geometries create distinct aftermarket revenue streams that separate profitable OEMs from commodity assemblers.
Product Type:
After-sales intensity varies sharply across power architectures, with battery ecosystems demanding firmware updates and cell replacement programs that corded units never require.
- Battery-operated:Lithium-ion cells with standardized voltage rails enable cross-brand battery sharing. Demand clusters among mobile artisans in Vietnam and Bangladesh where grid reliability fluctuates; replacement cell programs generate recurring revenue.
- Professional:Brushless motor systems with thermal overload protection and duty-cycle ratings exceeding 8 hours. German automotive trim shops and French aerospace contractors specify these for Kevlar and carbon fiber processing where blade precision determines material yield.
- Corded:AC adapter systems with continuous power delivery for fixed workstation deployment. Italian textile mills favor these for pattern-cutting stations where mobility is unnecessary.
- Household:Lightweight polymer housings with reduced torque output for intermittent crafting use. Japanese consumers drive premium positioning through design-forward retail channels.
Battery-operated holds the largest share; momentum sits with Professional as industrial safety mandates accelerate motorized adoption.
Application:
Application segmentation tracks material thickness tolerances and cut frequency, with medical and aerospace applications commanding certification premiums that crafting cannot support.
- Industrial Manufacturing:Programmable electromechanical systems with force feedback and cycle logging. Aircraft maintenance facilities in Toulouse and Hamburg require cut-depth documentation for composite panel processing.
- Medical Usage:Sterilizable housings with sealed motor compartments and autoclavable blade assemblies. Orthotic fabrication units in Munich and surgical supply chains in Boston specify battery models for sterile field mobility.
- Textile Cutting:High-speed rotary mechanisms with fabric-specific blade geometries. Garment factories in Dhaka and Ho Chi Minh City deploy these to reduce repetitive strain injury claims.
- Crafting:Entry-level torque settings with decorative blade options. North American hobbyist channels through Michaels and Jo-Ann dominate volume.
Industrial Manufacturing commands the highest unit economics; Medical Usage is climbing the fastest as clinical procurement standards formalize.
End User:
End user structure reflects procurement authority concentration, with hospital systems and factory networks negotiating enterprise pricing that fragmented artisans cannot access.
- Factories:Centralized purchasing departments with technical specification committees. Vietnamese and Bangladeshi garment exporters mandate motorized cutting to satisfy buyer audit requirements.
- Hospitals:Infection control committees and biomedical engineering oversight. German Klinikum networks standardize on autoclavable models with traceable sterilization cycles.
- Tailoring Shops:Owner-operated procurement with price sensitivity and local distributor relationships. Jakarta and Bangkok neighborhood clusters drive Southeast Asian volume.
- Artisans:Individual tool selection with brand loyalty to established power-tool ecosystems. Japanese craft guilds maintain preference for domestic manufacturers.
Factories absorb the highest absolute volume; Hospitals show the steepest expansion trajectory as clinical applications multiply.
Technology:
Technology segmentation determines maintenance intervals and control precision, with servo and electromechanical systems requiring calibration services that rotary mechanisms avoid.
- Electromechanical:Stepper motor drives with programmable stop positions and force modulation. Satellite manufacturing cleanrooms in California and Bavaria specify these for composite layup trimming.
- Brushless Servo:Closed-loop position control with Hall-effect feedback eliminating mechanical limit switches. German medical device manufacturers adopt these for sterilization tolerance.
- Rotary:Simplified drive trains with direct blade coupling and minimal electronic content. Household and crafting segments favor these for reliability and field repairability.
- Pneumatic:Compressed air actuation for explosion-risk environments and high-torque industrial cutting. Chemical processing facilities in Texas and Rotterdam maintain legacy installations.
Electromechanical dominates precision applications; Brushless Servo is gaining share fastest as solid-state reliability displaces mechanical switches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German aerospace workshops demand programmable precision systems with cut-depth documentation, while Vietnamese garment factories prioritize battery portability for unreliable grid environments. Japanese consumers drive premium household positioning through design-forward retail channels.
United States
Medical device manufacturers and orthotic fabrication units in Boston and Minneapolis drive demand for autoclavable battery models. FDA oversight of surgical instruments shapes sterilization protocol requirements. California's satellite manufacturing cleanrooms in Los Angeles County specify electromechanical systems with programmable stops for composite trimming operations.
Germany
Automotive trim shops in Stuttgart and aerospace contractors in Hamburg require brushless systems for Kevlar and carbon fiber processing. ECHA's REACH Annex XVII restrictions on PFAS in blade coatings force coating reformulations. Bavarian medical device manufacturers adopt solid-state Hall-effect sensor systems for sterilization tolerance.
China
OEM clusters in Zhejiang province feed export channels while domestic demand concentrates in Shenzhen electronics assembly and Dongguan textile operations. SAMR-administered GB standards mandate safety interlocks and battery thermal protection. Ningbo port proximity concentrates over sixty percent of global blade forging capacity within a 150-kilometer radius.
Vietnam
Garment factories in Ho Chi Minh City and Hanoi deploy electric scissors to satisfy buyer audit requirements and reduce repetitive strain injury claims. Industrial safety inspectors mandate motorized alternatives for high-volume export facilities. Local procurement prioritizes battery-operated models addressing grid reliability fluctuations in provincial manufacturing zones.
Japan
Craft guilds in Osaka and Tokyo maintain preference for domestic manufacturers through design-forward retail channels. METI-enforced PSE marking on lithium-ion power systems filters lower-tier suppliers from premium distribution. Kansai region household consumers drive premium positioning for lightweight polymer-housed crafting models.
Global Electric Scissors Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct tiers: premium engineering specialists, battery-platform ecosystem players, and OEM assemblers serving price-sensitive export channels. Strategic archetypes include cordless power-tool ecosystem extenders, precision engineering transplants from adjacent industrial sectors, and Zhejiang-based blade-forging clusters. Dominant competitive moves center on cross-brand battery platform standardization and ceramic coating reformulations eliminating hexavalent chromium.
Among the named players, Stanley Black & Decker and Robert Bosch GmbH occupy positions on the premium-engineering and ecosystem-extension vectors. Makita Corporation exemplifies the brushless motor technology specialist archetype. Zhejiang Feihu New Energy Technology represents the OEM cluster model concentrated in Ningbo export channels. These three anchors demonstrate how geographic origin and corporate structure map to distinct competitive positioning within the market's tiered architecture.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Robert Bosch GmbH |
| Makita Corporation |
| WORX (Positec Tool Corp.) |
| DeWALT |
| Infaco |
| Pink Power Tools |
| Xiamen WBT Electric Industrial Trade |
| Zhejiang Feihu New Energy Technology |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Zhejiang province's blade-forging cluster is compressing export pricing while forcing OEMs toward higher-margin ceramic coating reformulations and battery-platform standardization to defend margins.
Pricing Analysis
Long-term offtake contracts dominate procurement between Vietnamese garment exporters and Ningbo-based OEMs, insulating volume buyers from lithium-ion cell cost volatility while spot purchases by Indonesian tailoring shops absorb price swings. Three-tier pricing structure across premium brushless systems, standard rotary mechanisms, and economy corded units separates German aerospace contractors from Bangladeshi factory networks from Southeast Asian artisans. Cost compression in battery-operated tiers is intensifying because cathode material price swings compress gross margins when supply contracts expire. Indonesian tailoring shops exhibit highest price sensitivity; German Klinikum networks and California satellite manufacturers show lowest sensitivity due to sterilization certification requirements.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for Zhejiang OEMs serving North American medical device distributors. Blade forging capacity concentrates in China, Japan, and Germany; lithium-ion cell supply rests on South Korean and Japanese cathode material networks. Raw material dependencies span hardened steel alloys, ceramic-silicone hybrid coatings, and Hall-effect sensor components. Single-source vulnerability in Ningbo port logistics creates chokepoint exposure for global export channels. Distribution runs through Amazon Business and Alibaba 1688 direct-to-workshop channels for replacement parts, bypassing traditional industrial distributors in North American contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric scissors penetration in medical and aerospace applications remains early-cycle, with clinical procurement standardization and composite processing documentation requirements accelerating motorized adoption beyond textile automation saturation.
For Market Incumbents: Entrench battery-platform ecosystem control by locking Vietnamese and Bangladeshi garment exporters into multi-year cell replacement programs. Secure REACH-compliant ceramic coating supply through backward integration into Netherlands and Finland formulation suppliers before ECHA restrictions tighten. Defend against Zhejiang OEM price erosion by embedding firmware-updatable safety profiles that commodity assemblers cannot replicate.
For New Entrants and Emerging Players: Build out sterile field mobility offerings targeting Munich orthotic fabrication units and Boston surgical supply chains where autoclavable battery models face limited competition. Capture share in Indonesian tailoring shops through local distributor relationships and grid-reliability messaging. Prioritize direct-to-workshop e-commerce channels for blade and battery replacement sales over traditional wholesale partnerships.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because REACH compliance migration and FDA sterilization protocol formalization create durable certification moats that filter commodity suppliers. Target acquisition profiles center on brushless servo specialists with Hall-effect sensor integration and medical device manufacturing pedigree. Watch for inflection when ECHA announces PFAS restriction amendments that force coating reformulation investments beyond smaller OEM capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Stanley Black & Decker and Makita leverage shared lithium-ion ecosystems to cross-sell electric scissors through existing cordless power-tool customer bases. |
| Ceramic Coating Reformulation | REACH Annex XVII PFAS restrictions force suppliers toward Netherlands and Finland ceramic-silicone hybrid formulations for blade coatings. |
| Autoclavable Housing Development | German medical device manufacturers adopt sealed motor compartments and autoclavable blade assemblies to satisfy Munich Klinikum sterilization requirements. |
| Direct-to-Workshop E-Commerce | Amazon Business and Alibaba 1688 disintermediate regional tool wholesalers by capturing North American contractor replacement part demand. |
| Brushless Servo Integration | Hall-effect sensor systems eliminate mechanical limit switches, enabling firmware-updatable safety profiles for California satellite manufacturing cleanrooms. |
Methodological Framework
A standing panel of plant engineers at Vietnamese garment exporters, biomedical engineering directors at German Klinikum networks, procurement leads at California aerospace contractors, aftermarket service heads at Ningbo OEM clusters, and ceramic coating R&D directors at Netherlands suppliers provided ongoing calibration. Primary interview findings triangulated against SAMR GB standard filings, ECHA REACH restriction amendments, METI PSE marking databases, FCC electromagnetic emission certifications, and customs trade data for lithium-ion powered cutting tool categories. Bottom-up volume builds across product type, application, end user, and technology segments reconciled against top-down macroeconomic indicators.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with segmentation dimensions spanning power architecture, material processing requirement, procurement authority concentration, and drive mechanism sophistication. CAGRs derived from fitted growth curves applied to historical shipment data and penetration rate assumptions. Industry-specific forecast inputs included ECHA regulatory amendment timelines, Vietnamese industrial safety inspector mandate enforcement patterns, and lithium-ion cell cost curve projections from cathode material supply contracts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by brushless motor technology specialists or Zhejiang-based OEM clusters pursuing vertical integration would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Asia-Pacific Handheld Vacuum Cleaner Market
Household Items
Portable Iron Market
Household Items
Toilet Care Wipes Market
Household Items
North America Tankless Water Heater Market
Household Items
Electric Shoe Polisher Market
Household Items
Global Electronic Bidet Seats Market
Household Items
Toilet Deodorant Market
Household Items
Aquarium Hydrometers Market
Household Items
Sorting Hampers Market
Household Items
Folded Tissues Market
Household Items
Oman Gas Hobs Market
Household Items
Plastic Bathtub Market
Household Items
Nebulizing Diffuser Market
Household Items
China Digital Showers Market
Household Items
Household Scales Market
Household Items
Dryer Sheets Market