
 Facial Tissue Paper Market | 2026-2036
Facial Tissue Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Tissue Paper Market Analysis
Biodegradable pulp processing and plant-based fiber sourcing is reshaping how facial tissue paper is engineered for sustainability. Essity leverages integrated forestry operations to secure virgin pulp supply chains across Northern Europe. Kimberly-Clark Corporation anchors North American retail shelf presence through decades of brand equity in household channels. Svenska Cellulosa AB (SCA) dominates Nordic production scale with some of the region's largest tissue mills.
Facial tissue paper consists of lightweight, creped cellulose sheets typically ranging from 13 to 22 grams per square meter, engineered for gentle nasal and facial contact through controlled softness and absorbency. The material segment splits sharply: virgin pulp commands premium positioning in healthcare facilities, while bamboo and recycled fiber gain traction among sustainability-focused households. Lotion-infused and hydrating variants within product type capture widening margin pools as consumers trade up from basic unscented grades.
The EPA regulates pulp mill effluent discharge under Clean Water Act permits, while the EU Ecodesign for Sustainable Products Regulation mandates fiber traceability and recyclability disclosures for tissue products sold in member states. China's GB standards set baseline limits for fluorescent agents and microbial content in tissue paper distributed domestically. Stakeholders must monitor evolving extended producer responsibility frameworks and decide whether to front-run compliance costs or risk market exclusion in jurisdictions tightening packaging and fiber provenance rules.
Market Dynamics
The EU Ecodesign for Sustainable Products Regulation is forcing facial tissue manufacturers to reengineer supply chains around fiber traceability and recyclability disclosures, compressing margins for virgin pulp-dependent producers while opening margin pools for certified bamboo and recycled fiber specialists.
Growth Catalysts
- EU Ecodesign for Sustainable Products Regulation:Mandated fiber provenance tracking accelerates investment in certified recycled and alternative fiber capacity across Northern European mills.
- Urban Chinese households:Premium lotion-infused and hydrating variants capture widening adoption as disposable income shifts toward hygiene upgrades in tier-one cities.
- Bamboo pulp processing:Mechanical refining advances reduce production energy intensity, enabling cost-competitive positioning against virgin wood pulp in Asian manufacturing hubs.
Market Restraints
- Softwood pulp price volatility:Nordic and Canadian sawmill capacity constraints transmit directly to tissue producer input costs, compressing gross margins during supply shocks.
- Recycled fiber contamination limits:Post-consumer waste streams contain non-paper contaminants that degrade tissue softness, restricting medical-grade applications to virgin fiber.
- Extended producer responsibility frameworks:Germany's Verpackungsgesetz and France's AGEC law impose packaging recovery fees that scale with volume, disadvantaging high-SKU producers.
Strategic Opportunities
- India's tier-two and tier-three cities:Per capita tissue consumption remains below Southeast Asian benchmarks, creating whitespace for economy-format bulk positioning.
- Subscription replenishment channels:Direct-to-consumer auto-replenishment models bypass traditional retail slotting fees, capturing lifetime value through predictable consumption patterns.
- China's dual carbon goals:National carbon intensity targets incentivize provincial governments to fast-track bamboo plantation permits and carbon-neutral mill certifications.
Industry Challenges
- Short-fiber specialty engineering:Bamboo and agricultural residue pulps require modified creping chemistry and dryer hood configurations, demanding capital retrofit cycles at legacy mills.
- GB standard compliance timelines:China's microbial content and fluorescent agent testing protocols impose batch validation delays that extend new product introduction cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Tissue Paper Market |
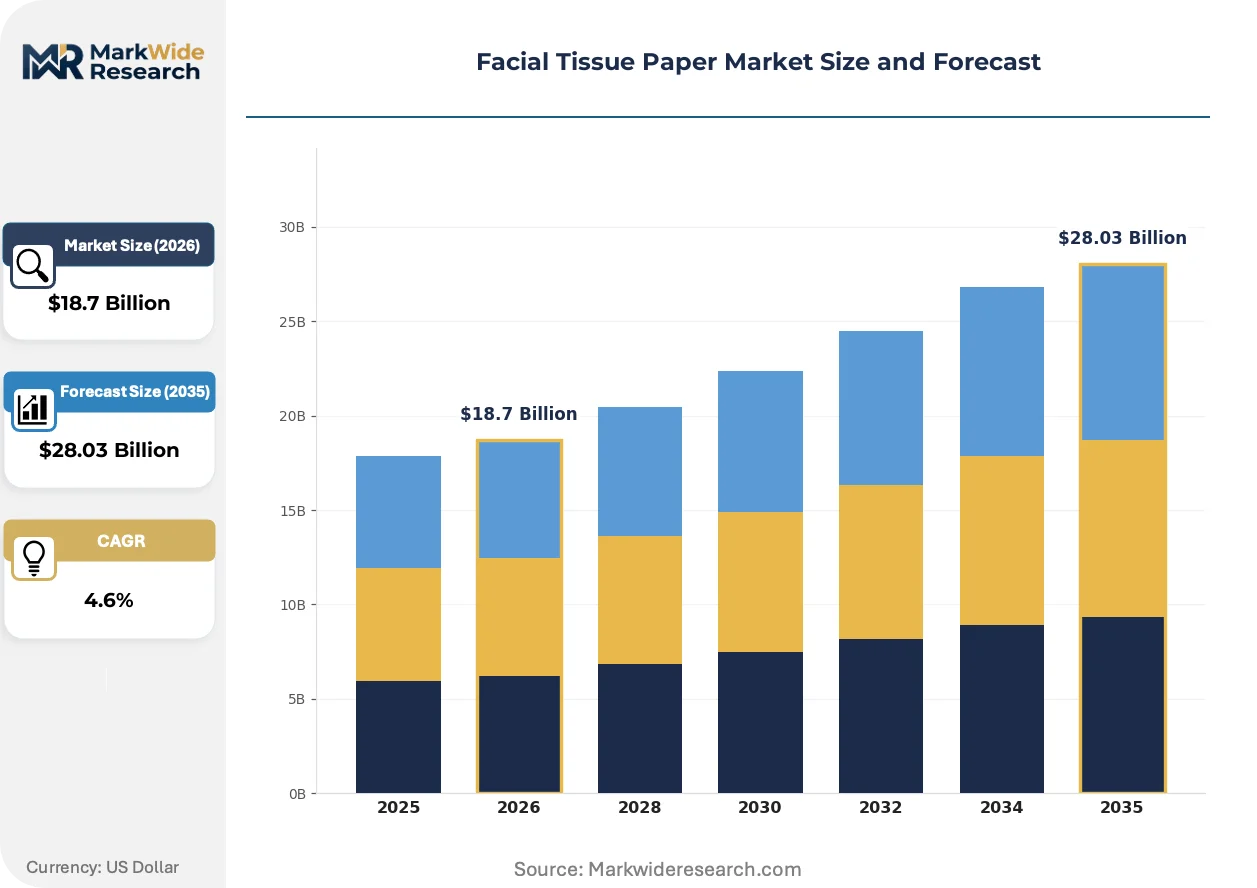
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrating, Lotion-Infused, Scented, Unscented Material: Pulp, Recycled Fiber, Bamboo, Synthetic Fiber Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesalers End User: Households, Healthcare Facilities, Hospitality Industry, Educational Institutions |
| Companies Covered | Svenska Cellulosa AB (SCA), Hengan International Group Company Limited, Procter & Gamble, Sofidel Group, Essity, Kimberly-Clark Corporation, Asia Pulp & Paper Group, Vinda International Holdings Limited, Georgia-Pacific LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Tissue Paper Market Emerging Trajectories
Moisture-activated lotion infusion chemistry and precision creping control systems are redefining softness benchmarks, while regulatory pressure on fiber sourcing accelerates capital deployment toward alternative pulp technologies.
Air-laid nonwoven lamination is rendering obsolete traditional wet-pressed tissue structures in premium facial wipe segments. Japanese and South Korean beauty retailers are adopting these hybrid formats at accelerating pace. The technology is compressing volume for conventional three-ply products in skincare-adjacent categories.
REACH chemical restriction expansions are tightening allowable limits on lotion additives and fragrance compounds in tissue products sold across EU member states. Manufacturers face reformulation costs or market exclusion for non-compliant SKUs. Premium scented variants and pediatric-positioned lines bear the highest compliance burden and are accelerating shift toward hypoallergenic, additive-free positioning.
Healthcare procurement consolidation is compressing supplier rosters as hospital systems centralize purchasing through group purchasing organizations. Smaller regional tissue converters are losing shelf position to integrated manufacturers with dedicated medical-grade certification. The United States exhibits the most pronounced buyer concentration, with Catholic health initiatives and for-profit chains driving standardization around virgin pulp, lotion-free specifications.
Facial Tissue Paper Market Segmentation
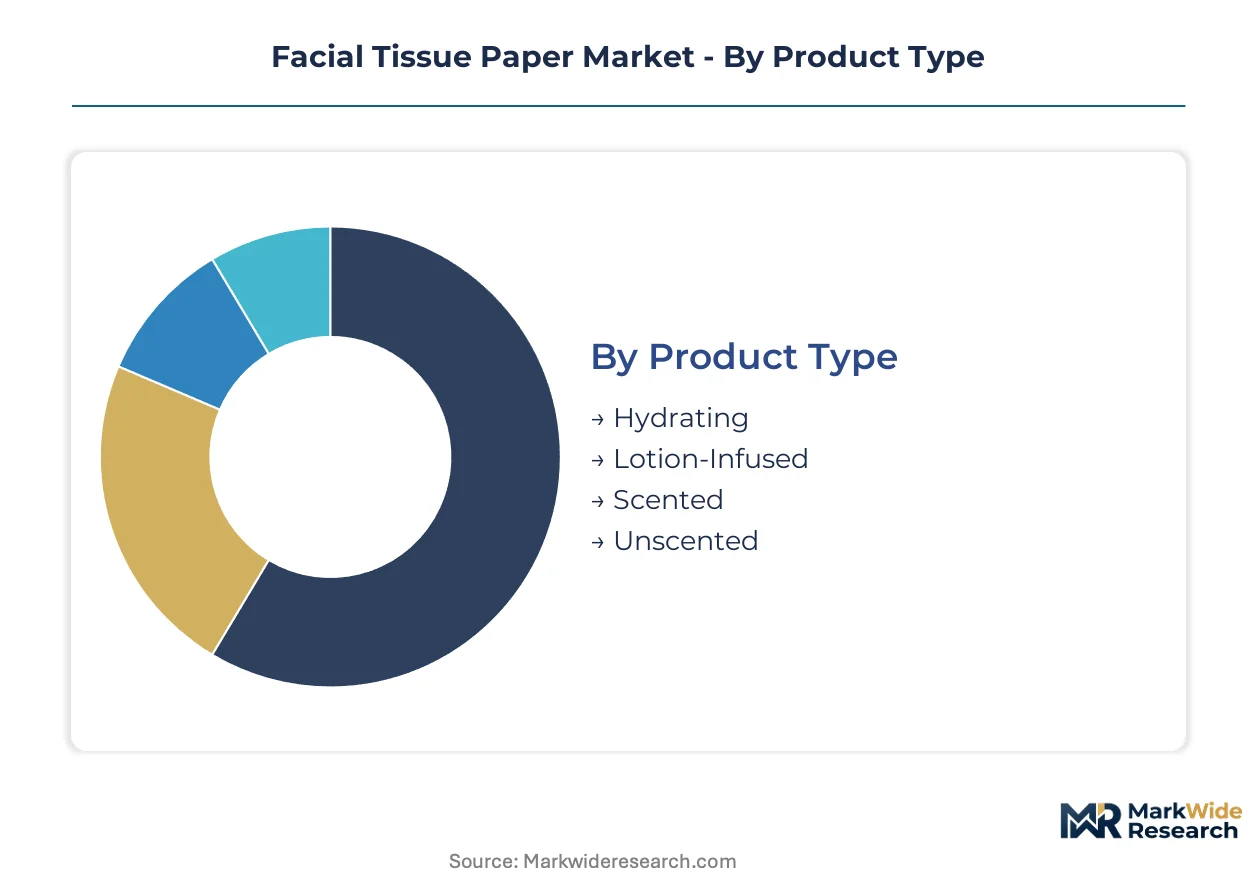
Facial tissue paper segmentation reveals how formulation chemistry, fiber sourcing, and channel access determine margin capture. Manufacturers engineer distinct value propositions across product tiers while regulatory pressure on material provenance reshapes competitive boundaries.
Product Type:
After-sales intensity concentrates in premium-positioned variants where formulation stability and skin sensitivity claims drive repeat purchase validation and consumer complaint resolution.
- Lotion-Infused:Emollient coatings containing aloe vera, vitamin E, or glycerin deliver calibrated moisturization for frequent-use scenarios. Demand clusters in urban Chinese households and Japanese beauty retail channels where skincare-adjacent positioning commands price premiums. REACH chemical restrictions in Europe are forcing reformulation cycles for fragrance and preservative systems.
- Hydrating:Water-based humectant blends penetrate sheet structures to maintain epidermal moisture barriers during cold and allergy seasons. Adoption accelerates in South Korean pharmacy chains and US direct-to-consumer subscription models targeting dermatological sensitivity concerns.
- Scented:Microencapsulated fragrance release systems provide sensory differentiation in mass retail environments. EPA and ECHA scrutiny on volatile organic compound emissions constrains formulation latitude in North American and European markets.
- Unscented:Additive-free construction serves pediatric, geriatric, and immunocompromised user segments with minimal irritation risk. Procurement standardization across US hospital group purchasing organizations favors this specification for institutional contracts.
Lotion-infused holds the largest share; momentum sits with hydrating variants.
Material:
Cost tier stratification separates virgin fiber premium positioning from alternative fiber economy plays, with carbon accounting costs increasingly embedded in procurement decisions.
- Pulp:Virgin softwood and hardwood cellulose delivers superior tensile strength and softness consistency for medical-grade applications. Nordic and Canadian sawmill capacity constraints transmit price volatility directly to tissue producer input costs.
- Bamboo:Rapid-growth grass species with mechanical refining advances reducing production energy intensity. China's dual carbon goals accelerate provincial plantation permitting and carbon-neutral mill certifications for domestic supply security.
- Recycled Fiber:Post-consumer waste streams processed through deinking and bleaching sequences. EU Ecodesign fiber traceability mandates and Germany's Verpackungsgesetz packaging recovery fees compress margins for high-volume producers.
- Synthetic Fiber:Polyester and polypropylene blends in hybrid nonwoven structures for premium facial wipe segments. Japanese and South Korean beauty retailers adopt air-laid lamination formats at accelerating pace.
Pulp retains dominant volume; bamboo climbs the fastest on sustainability credentialing.
Distribution Channel:
Volume concentration in traditional retail coexists with channel shift toward auto-replenishment models that bypass slotting fee structures and capture lifetime value.
- Supermarkets:Mass-market shelf presence depends on trade promotion spend and category captain arrangements with retail consolidators. Kimberly-Clark and Essity anchor household channel visibility through decades of brand equity investment.
- Online Retail:Direct-to-consumer platforms enable subscription replenishment and personalized bundle configurations. China's tier-one cities exhibit the steepest e-commerce penetration for premium lotion-infused and hydrating variants.
- Convenience Stores:Impulse-oriented pack sizing and localized assortment for immediate-need consumption. India's tier-two and tier-three cities present whitespace for economy-format bulk positioning in this channel.
- Wholesalers:Institutional procurement consolidation through group purchasing organizations favors standardized specifications and volume discounts. US healthcare systems drive virgin pulp, lotion-free standardization at scale.
Supermarkets maintain largest transaction volume; online retail gains share fastest on subscription model adoption.
End User:
Application-driven specification divergence separates household discretionary upgrade cycles from institutional procurement rigor around certification and compliance documentation.
- Healthcare Facilities:Virgin pulp requirements predominate due to microbial content limits and absorbency consistency mandates. US hospital system consolidation through Catholic health initiatives and for-profit chains compresses supplier rosters toward integrated manufacturers with dedicated medical-grade certification.
- Households:Discretionary premium trading toward lotion-infused and hydrating variants tracks disposable income elasticity. Urban Chinese consumption patterns in tier-one cities demonstrate the most pronounced upgrade trajectory.
- Hospitality Industry:Branded amenity positioning in luxury hotels versus cost-optimized bulk procurement in economy chains. GB standards in China and EPA guidelines in the US set baseline compliance floors for fluorescent agent and microbial content.
- Educational Institutions:Budget-constrained procurement favors economy-format unscented specifications with volume pricing. Extended producer responsibility frameworks in France and Germany impose packaging recovery fees that scale with institutional purchase volume.
Households represent the largest addressable base; healthcare facilities deliver the most stable contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net trade positions diverge sharply across major tissue-producing economies. Nordic and North American mills export virgin pulp to Asian converters, while China increasingly substitutes domestic bamboo fiber for imported softwood. Regulatory carbon accounting is beginning to reshape these flows.
United States
Healthcare procurement consolidation through Catholic health initiatives and for-profit hospital chains drives virgin pulp standardization at scale. EPA Clean Water Act permits govern mill effluent discharge across Wisconsin and Georgia manufacturing clusters. The Southeast pulp-tissue corridor anchors North American production capacity with integrated softwood supply chains.
China
Tier-one cities exhibit steep premiumization toward lotion-infused and hydrating variants as disposable income shifts toward hygiene upgrades. GB standards impose batch validation delays for microbial content and fluorescent agent testing that extend new product introduction cycles. Sichuan-Chongqing bamboo processing hubs benefit from provincial fast-tracking of plantation permits under national dual carbon goals.
Germany
Verpackungsgesetz packaging recovery fees scale with volume, disadvantaging high-SKU producers in the household segment. EU Ecodesign fiber traceability mandates accelerate capital deployment toward certified recycled fiber capacity at Northern European mills. The North Rhine-Westphalia tissue converting cluster is retrofitting legacy equipment for alternative pulp compatibility.
Japan
Beauty retail channels adopt air-laid nonwoven lamination formats at accelerating pace, compressing conventional three-ply volume in skincare-adjacent categories. METI energy efficiency standards drive dryer hood reconfigurations at mills processing short-fiber agricultural residues. The Kansai region hosts specialized converters engineering precision creping control systems for premium softness benchmarks.
India
Per capita tissue consumption remains below Southeast Asian benchmarks, creating whitespace for economy-format bulk positioning in tier-two and tier-three cities. BIS standards set baseline quality parameters for domestic tissue distribution. Maharashtra and Gujarat manufacturing zones are expanding capacity to serve emerging convenience store channels with localized pack sizing.
Facial Tissue Paper Market Vendor Landscape
On the supply side, the industry is consolidating around integrated pulp-to-tissue manufacturers with captive fiber security and dedicated medical-grade certification capabilities. Three strategic archetypes dominate: Nordic forestry-integrated giants with virgin pulp dominance, Asian bamboo fiber specialists leveraging carbon-neutral credentials, and North American brand equity holders anchoring retail shelf presence. Competitive intensity centers on backward integration into pulp supply and geographic expansion into underpenetrated South Asian markets.
Among the forestry-integrated tier, Essity and Svenska Cellulosa AB exemplify the Nordic model of captive pulp supply chains across Northern European mill networks. Kimberly-Clark Corporation occupies a position as the North American retail anchor, while Asia Pulp & Paper Group represents the scale-driven Asian production complex. These three archetypes illustrate how fiber sourcing strategy and channel access determine margin capture across regulatory jurisdictions.
| Leading Market Players |
|---|
| Svenska Cellulosa AB (SCA) |
| Hengan International Group Company Limited |
| Procter & Gamble |
| Sofidel Group |
| Essity |
| Kimberly-Clark Corporation |
| Asia Pulp & Paper Group |
| Vinda International Holdings Limited |
| Georgia-Pacific LLC |
| Others |
Supply Flow & Price Mechanics
Sichuan-Chongqing bamboo processing hubs anchor Asian supply capacity and transmit cost advantages to domestic converters, compressing import-dependent virgin pulp pricing power in coastal Chinese markets. Nordic softwood pulp producers defend premium positioning through medical-grade certification while facing margin pressure from alternative fiber scale-up.
Pricing Analysis
Conventional wet-pressed tissue structures command commodity pricing while air-laid nonwoven lamination formats capture 40-60% premiums in Japanese and South Korean beauty retail channels. Three-tier pricing structure across premium lotion-infused, standard unscented, and economy recycled-fiber levels segments buyer archetypes. Cost compression in virgin pulp tiers is intensifying because Nordic sawmill capacity constraints elevate input costs. Household consumers in India's tier-two cities exhibit highest price sensitivity; US hospital group purchasing organizations show lowest sensitivity due to standardization mandates.
Supply Chain Analysis
Essity and Svenska Cellulosa AB dominate contract-manufacturing concentration through captive Northern European pulp mills with integrated tissue converting. China, Sweden, and the United States anchor geographic supply concentration for distinct fiber sourcing strategies. Raw material dependencies center on softwood pulp, bamboo grass feedstock, and post-consumer recycled fiber streams. Single-source vulnerability concentrates in Nordic softwood supply chains exposed to sawmill capacity constraints. Distribution runs through supermarket retail consolidators, direct-to-consumer subscription platforms, and institutional group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EU fiber traceability mandates, US healthcare procurement consolidation, and China's dual carbon goals creates niche entry points for specialized producers. Sustainability credentialing and medical-grade certification separate addressable segments.
For Market Incumbents: Pre-empt bamboo fiber specialists by securing provincial plantation permits in Sichuan and carbon-neutral mill certifications before China's dual carbon deadlines accelerate. Backward integration into certified recycled fiber capacity defends against EU Ecodesign compliance cost compression. Channel control through hospital group purchasing organization contracts protects against integrated manufacturer consolidation. For New Entrants and Emerging Players: India's tier-two and tier-three convenience store channels represent the most penetrable entry point given per capita consumption gaps against Southeast Asian benchmarks. Subscription replenishment models in US direct-to-consumer segments bypass slotting fee barriers and capture predictable lifetime value. Economy-format bulk positioning with localized pack sizing addresses immediate-need consumption patterns. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors bamboo pulp processing specialists with mechanical refining capabilities and carbon-neutral credentials over legacy virgin pulp converters. Long-term viability across the next decade hinges on regulatory compliance cost absorption and alternative fiber yield consistency. Watch provincial permitting velocity in Chinese bamboo regions as inflection indicator for domestic supply security shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Bamboo Plantation Permit Securement | Sichuan provincial fast-tracking under dual carbon goals locks in domestic fiber supply security for carbon-neutral mill certifications. |
| Medical-Grade Certification Investment | FDA and EPA compliance documentation opens US hospital group purchasing organization contracts to virgin pulp specialists. |
| Direct-to-Consumer Subscription Launch | Auto-replenishment models bypass supermarket slotting fees and capture household lifetime value through predictable consumption patterns. |
| Air-Laid Nonwoven Lamination Scale-Up | Japanese beauty retailer adoption of hybrid formats displaces conventional three-ply volume in skincare-adjacent premium segments. |
| Recycled Fiber Capacity Expansion | EU Ecodesign fiber traceability mandates and Germany's Verpackungsgesetz fees compress margins for non-compliant high-SKU producers. |
Methodological Framework
A standing panel of tissue mill operations directors, retail category buyers, hospital procurement managers, and bamboo plantation licensing officers provided ongoing calibration across primary fieldwork and secondary validation. Secondary sources included EPA Clean Water Act permit filings, EU Ecodesign regulatory documentation, Chinese GB standard protocols, and Nordic trade association production statistics. Bottom-up capacity modeling and top-down demand elasticity estimation triangulated volume and value outputs.
Scenario-bracketing around softwood pulp price volatility, regulatory compliance timeline acceleration, and alternative fiber yield improvement bounded projection ranges across the analysis window. Segmentation dimensions encompassed product type chemistry, fiber sourcing material, distribution channel structure, and end-user application with regulatory cluster overlays. CAGRs derived from historical elasticity patterns and forward capacity buildout announcements. Industry-specific inputs included bamboo plantation permitting velocity and hospital group purchasing organization contract renewal cycles.
Practitioners should monitor Nordic sawmill capacity utilization rates, EU Ecodesign enforcement granularity, and Chinese provincial carbon-neutral certification timelines for early signals requiring forecast revision. Cross-checking against EPA effluent discharge permit trends and BIS quality parameter updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Wax Removal Aids Market
Household Items
Coffin and Cremation Urn Market
Household Items
Heated Towel Rail Market
Household Items
Dishwasher Detergent Market
Household Items
Asean Cookware Market
Household Items
Folded Tissues Market
Household Items
Gas Hobs Market
Household Items
Window Rain Guards Market
Household Items
Dryer Sheets Market
Household Items
Industrial Floor Mats Market
Household Items
Mosquito Lamps Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Range Hood Cleaning Service Market
Household Items
Mirror Holder Market
Household Items
US Handheld Vacuum Cleaners Market
Household Items
Qatar Gas Hobs Market