
 Book Light Market | 2026-2036
Book Light Market Size, Share, and Industry Trends Forecast 2026-2036
Book Light Market Outlook
Shortages of optical engineers and LED thermal management specialists is unwinding production scalability across mid-tier manufacturers. Vekkia leverages its direct-to-consumer channel infrastructure to sustain margin capture in North American markets. Glocusent anchors its competitive stance through proprietary flexible neck designs that dominate specialty bookstore placements. Mighty Bright competes on brand heritage and library institutional contracts.
A book light is a portable, low-intensity illumination device engineered for personal reading environments, typically employing LED arrays rated below 5 watts with color temperatures spanning 2700K to 6500K and lithium-ion or AAA battery configurations. Its primary commercial purpose centers on glare-free task lighting that preserves circadian rhythms during extended reading sessions. Rechargeable units now lead volume shipments as USB-C standardization and integrated battery management systems reduce total cost of ownership across consumer segments. LED-based book lights command the widest margin pools due to semiconductor cost curves and extended operational lifespans exceeding 50,000 hours.
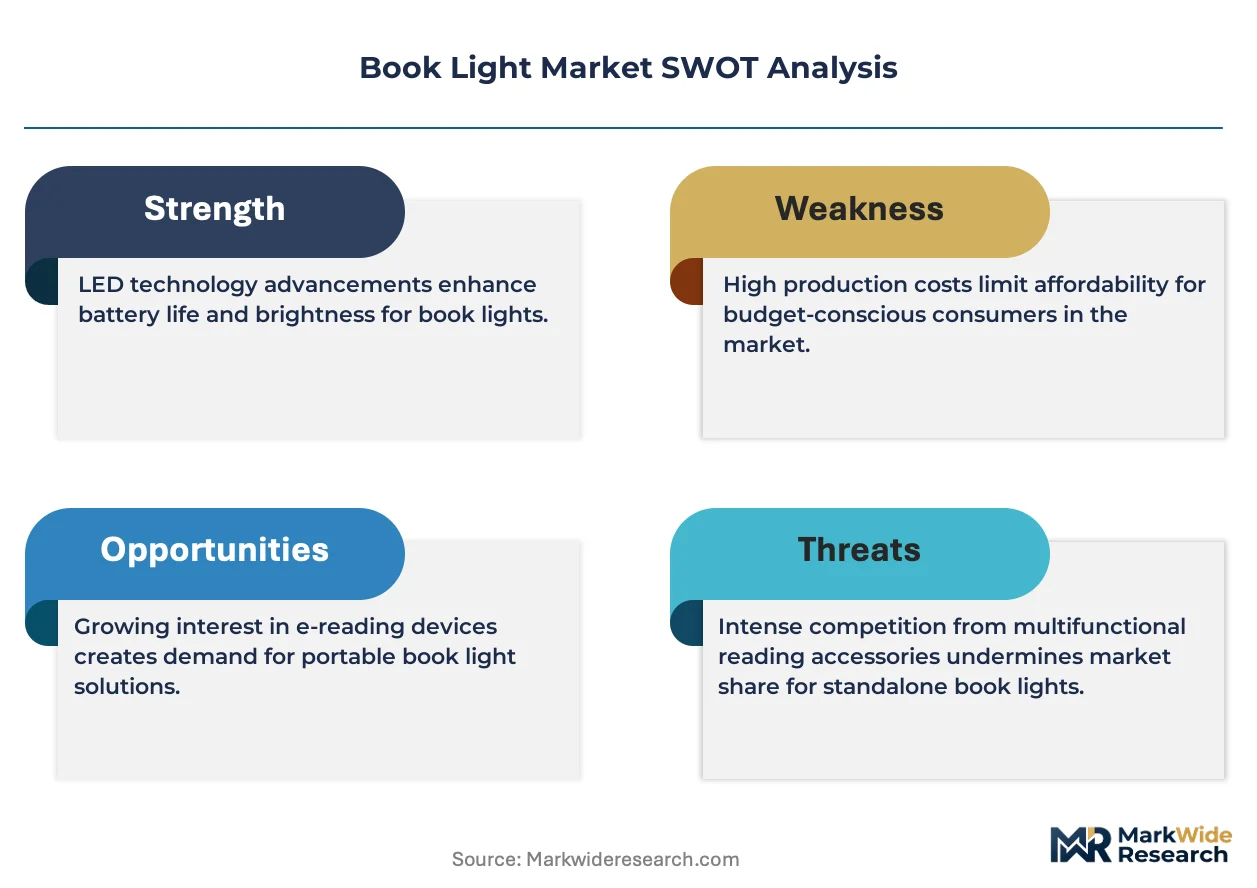
The EU Ecodesign Directive and REACH chemical compliance frameworks constrain material selection and energy efficiency thresholds for book lights sold across European markets. The US Consumer Product Safety Commission and California Title 20 appliance efficiency standards shape battery safety testing and standby power limits for devices distributed through American retail channels. Stakeholders must monitor evolving right-to-repair mandates and battery replaceability requirements that threaten sealed-unit designs and could force hardware architecture decisions within the next product development cycle.
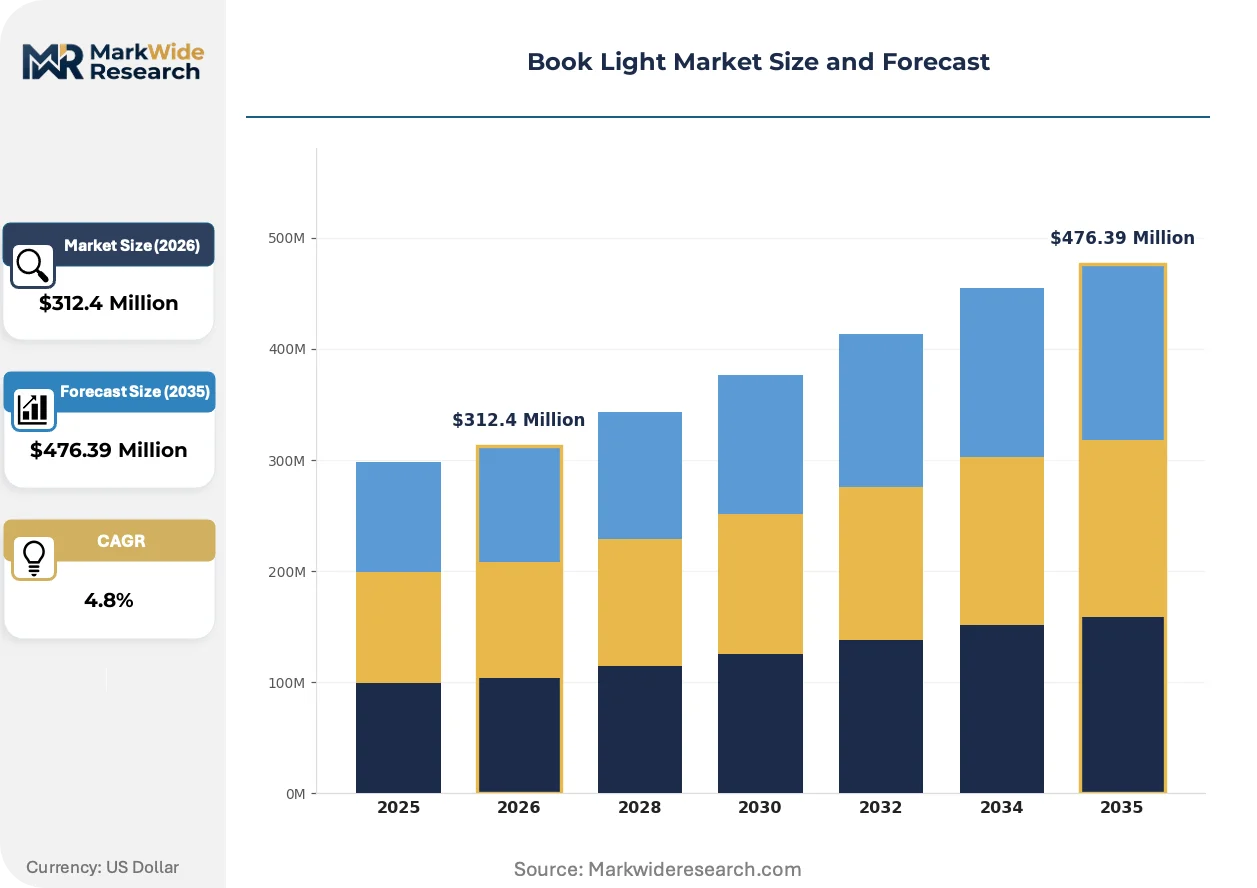
Market Dynamics
The book light market is undergoing structural recalibration as USB-C standardization and integrated battery management systems compress replacement cycles while elevating performance expectations across all price tiers.
Growth Catalysts
- EU Ecodesign Directive:Energy efficiency mandates accelerate LED adoption and disqualify incandescent alternatives from European retail channels, expanding addressable market for compliant manufacturers.
- Remote worker cohorts:Distributed professionals operating from home offices sustain demand for circadian-friendly task lighting that minimizes blue light exposure during evening work sessions.
- Lithium-ion cell cost curves:Declining battery component prices enable rechargeable configurations to displace disposable AAA-powered units at comparable retail price points.
Market Restraints
- Optical engineering talent scarcity:Shortages of LED thermal management specialists constrain mid-tier manufacturers from scaling production to meet seasonal demand spikes.
- Sealed-unit design vulnerability:Emerging right-to-repair mandates in multiple jurisdictions threaten hardware architectures that lack battery replaceability, forcing premature product redesign cycles.
- Smartphone flashlight substitution:Built-in LED flash functionality on mobile devices captures casual reading illumination needs among price-sensitive consumer segments.
Strategic Opportunities
- German premium retail channels:Specialty bookstores and design-forward lifestyle retailers command strong placement fees for reading accessories with distinctive industrial design credentials.
- University student housing:Campus residential contracts represent concentrated procurement volumes for institutional-grade book lights with theft-resistant mounting features.
- EU Green Deal alignment:Products certified under extended producer responsibility frameworks gain preferential shelf positioning in European electronics retail chains.
Industry Challenges
- REACH chemical compliance complexity:Restricted substance testing for plastics and solder materials extends product development timelines and increases certification costs for European market entry.
- California Title 20 standby power limits:Manufacturers must re-engineer idle-state power draw to satisfy efficiency thresholds for distribution through American retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Book Light Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Rechargeable, Battery-operated, Clip-on, Folding Light Source: LED, Incandescent, Halogen, Fluorescent Distribution Channel: Online Retail, Specialty Stores, Mass Merchandisers, Direct Sales Features: Dimming, Adjustable Neck, USB Charging, Color Temperature Options |
| Companies Covered | iZELL, Vekkia, Glocusent, Hooga, Mighty Bright, Gritin, EastPin, Gloseent, 86lux, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Book Light Market Strategic Shifts
Product architecture is diverging along usage-pattern lines as manufacturers optimize for discrete reading environments rather than generic portable lighting applications.
Flexible neck mechanisms with multi-axis rotation are fragmenting the accessory segment into specialized configurations for bed readers, desk workers, and travel users. University students and remote professionals adopt these differentiated form factors at accelerating rates based on primary use location. This specialization is fragmenting what was previously a commoditized product category into distinct margin pools with divergent feature requirements.
REACH and RoHS frameworks are tightening material restrictions on halogenated flame retardants and specific phthalates used in cable sheathing and plastic housings. Manufacturers serving European markets must reformulate supply chains to maintain compliance with evolving substance restriction lists. Battery-powered portable lighting categories face particular scrutiny due to proximity to skin contact and extended indoor use patterns.
Direct-to-consumer channel migration is compressing traditional retail markups as specialized reading light brands build proprietary e-commerce infrastructure. Specialty bookstore placements and library institutional contracts are losing volume share to manufacturer-owned digital storefronts with subscription accessory programs. North American and German markets exhibit the most pronounced channel shift velocity among developed economies.
Book Light Market Segmentation
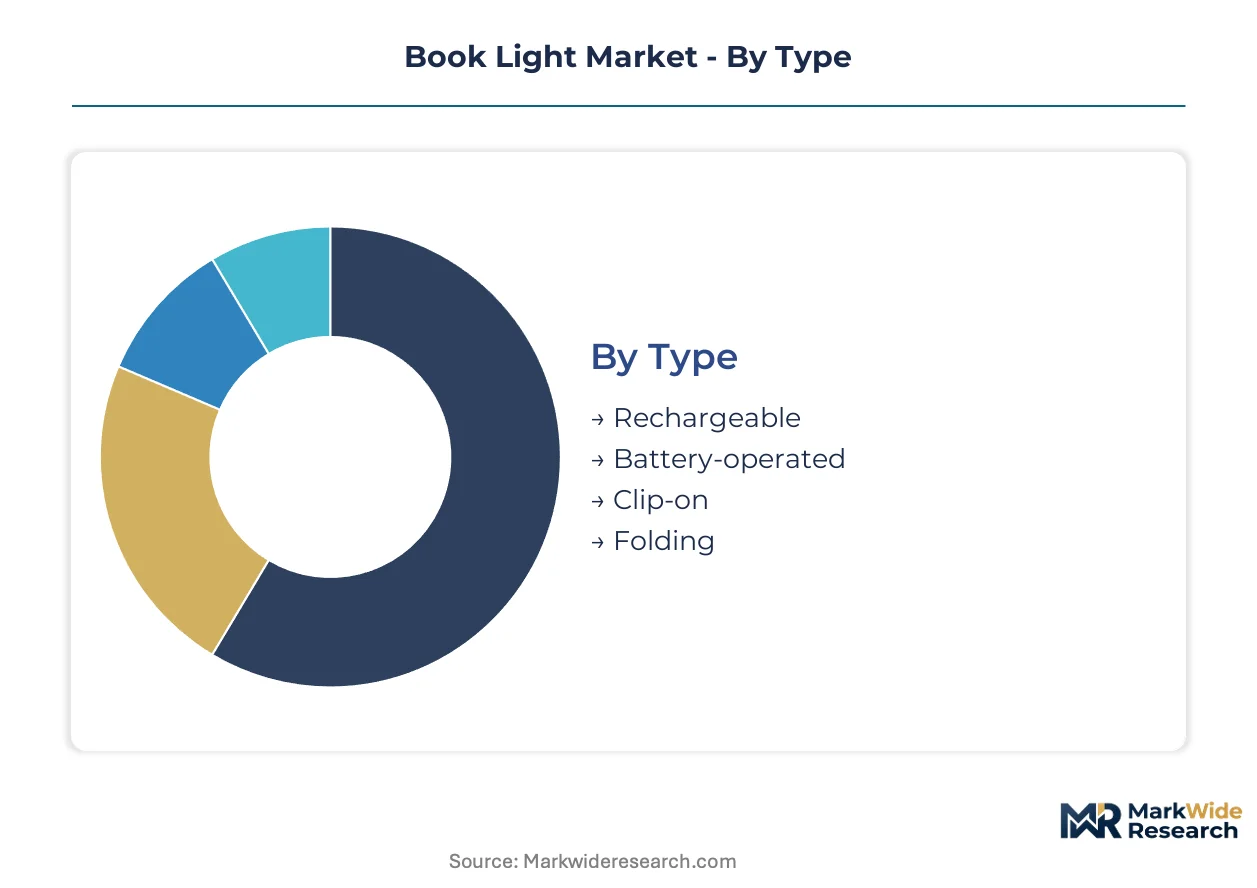
Book light segmentation reveals how channel strategy, power architecture, and feature bundling fragment what appears as a commoditized category. Manufacturers optimize product lines for distinct procurement contexts rather than uniform consumer profiles.
Type:
Rechargeable configurations flow through direct-to-consumer channels and electronics retailers, while battery-operated units dominate mass merchandiser shelves and impulse-buy displays.
- Rechargeable:Lithium-ion cells with USB-C ports and integrated battery management systems deliver operational lifespans exceeding 50,000 hours. Demand concentrates among university students and remote workers in Germany and the United States where total cost of ownership calculations favor upfront premium pricing over disposable battery replacement cycles.
- Battery-operated:AAA-powered units with alkaline or NiMH configurations retain price-sensitive casual readers. These units sustain volume in airport retail and pharmacy chains where immediate utility outweighs lifecycle economics.
- Clip-on:Spring-loaded clamps with silicone-padded jaws attach to hardcover spines and tablet edges. These serve bed readers and travel users through specialty bookstore placements.
- Folding:Hinged armatures that collapse into pocket-dimensions target ultralight travelers. These units command placement in luggage and travel accessory retail.
Rechargeable units dominate installed base among committed readers. Battery-operated is where expansion concentrates in emerging markets with unreliable grid infrastructure.
Light Source:
Semiconductor cost curves and EU regulatory mandates are reshaping the technology mix across price tiers.
- LED:Solid-state arrays rated below 5 watts with color temperatures spanning 2700K to 6500K. German specialty retailers and North American direct-to-consumer channels favor these for margin retention and extended warranty positioning.
- Incandescent:Tungsten filament designs with warm color rendering but excessive heat generation. EU Ecodesign Directive compliance thresholds have eliminated these from European retail channels entirely.
- Halogen:Compact filament capsules with improved efficacy over incandescent alternatives. These retain niche placement in veterinary and medical inspection applications where color accuracy requirements exceed consumer specifications.
- Fluorescent:Cold cathode tubes with diffuse output patterns. These persist in institutional library contracts where procurement specifications predate LED adoption timelines.
LED captures essentially all new unit demand. Fluorescent and incandescent constitute residual replacement cycles in legacy institutional installations.
Distribution Channel:
Margin capture varies sharply by channel control, with manufacturer-owned infrastructure displacing traditional retail intermediaries.
- Online Retail:Amazon Marketplace and proprietary e-commerce storefronts aggregate comparison shoppers and subscription accessory programs. These channels compress traditional retail markups while enabling feature customization.
- Specialty Stores:Independent bookstores and design-forward lifestyle retailers in Germany command placement fees for distinctive industrial design credentials. These outlets sustain premium pricing through curated merchandising.
- Mass Merchandisers:Big-box retail and pharmacy chains move standardized SKUs through seasonal promotional cycles. These channels prioritize theft-resistant packaging and point-of-sale display compatibility.
- Direct Sales:Manufacturer-owned digital storefronts with subscription accessory programs are climbing the fastest in North American markets where brand loyalty programs reduce customer acquisition costs.
Online retail dominates volume throughput. Direct sales is where margin expansion concentrates as brands build proprietary infrastructure.
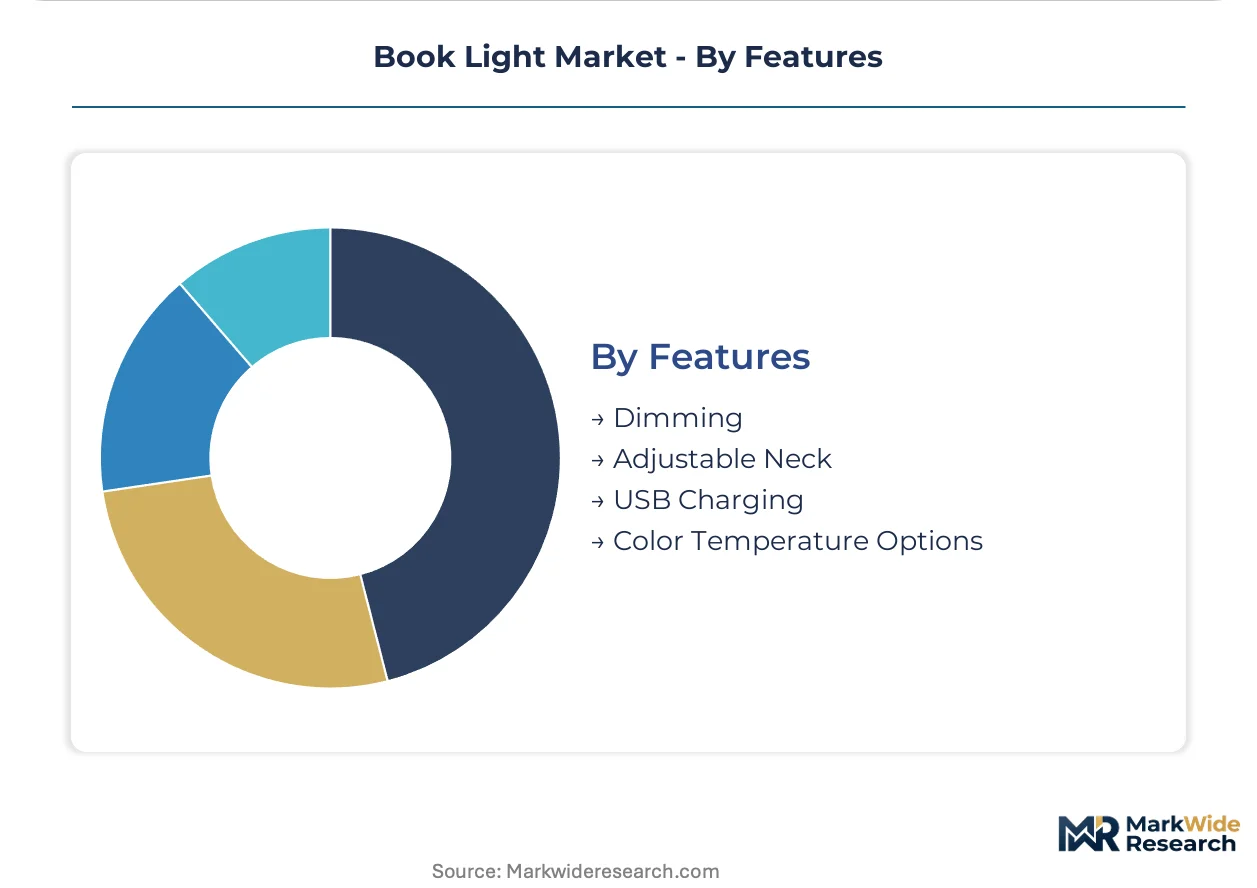
Features:
Feature bundling strategies diverge between circadian-health positioning and pure utility optimization.
- Dimming:Pulse-width modulation circuits enabling 10-100% luminance adjustment. These serve evening readers concerned with sleep disruption through blue light exposure management.
- Adjustable Neck:Multi-axis gooseneck or segmented arm mechanisms with 360-degree rotation. These dominate specialty bookstore placements where demonstration displays justify premium pricing.
- USB Charging:USB-C standardization with integrated battery management systems. These align with California Title 20 standby power limits and EU energy efficiency mandates.
- Color Temperature Options:Tunable white outputs from warm 2700K to cool 6500K. These target remote workers managing circadian rhythm alignment across extended work sessions.
Adjustable neck mechanisms dominate specialty channel differentiation. USB charging is where standardization pressure concentrates across all retail tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance obligations and California Title 20 efficiency standards anchor regulatory complexity across the two largest demand centers for portable reading illumination.
United States
Remote worker cohorts in Austin and Seattle sustain demand for circadian-friendly task lighting with tunable color temperature. California Title 20 standby power limits force manufacturers to re-engineer idle-state power draw for retail distribution. Brooklyn-based design studios pioneer industrial design credentials that command premium placement in specialty bookstore channels.
Germany
Specialty bookstores in Munich and Hamburg command placement fees for reading accessories with distinctive aesthetic positioning. The EU Ecodesign Directive disqualifies incandescent alternatives from retail channels, expanding addressable market for LED-compliant manufacturers. Baden-Württemberg industrial clusters concentrate precision engineering capabilities for flexible neck mechanisms.
China
Shenzhen electronics manufacturing hubs supply lithium-ion cells and USB-C standardization components at compressed cost curves. GB standards for battery safety testing shape export-oriented production architectures. Yangtze River Delta assembly facilities dominate volume shipments for rechargeable configurations.
United Kingdom
London design-forward lifestyle retailers curate premium reading accessories for affluent urban consumers. RoHS material restrictions constrain halogenated flame retardant selection in cable sheathing. Cambridge university residential contracts represent concentrated procurement volumes for institutional-grade units.
Japan
METI energy efficiency guidelines accelerate LED adoption in consumer electronics categories. Kanto region electronics retailers emphasize extended operational lifespan warranties. Osaka-based industrial design houses specialize in ultralight folding configurations for travel accessory segments.
Book Light Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the book light market, producing a tiered competitive structure rather than consolidated dominance. Mid-tier manufacturers face production scalability constraints due to optical engineering talent scarcity. Three strategic archetypes have emerged: direct-to-consumer specialists with proprietary e-commerce infrastructure, heritage brands with library institutional contracts, and flexible-neck design innovators with specialty retail placement strength. Competitive moves concentrate on channel infrastructure investment and industrial design differentiation rather than manufacturing scale expansion.
Within the direct-to-consumer archetype, Vekkia and Glocusent occupy positions shaped by digital storefront ownership and subscription accessory program development. Mighty Bright anchors the heritage-brand tier, exemplifying competitive positioning built on institutional contract relationships rather than channel markup compression. These three companies represent how margin capture now depends on proprietary infrastructure control rather than traditional retail intermediation.
| Leading Market Players |
|---|
| iZELL |
| Vekkia |
| Glocusent |
| Hooga |
| Mighty Bright |
| Gritin |
| EastPin |
| Gloseent |
| 86lux |
| Others |
Value Chain & Pricing Dynamics
USB-C standardization displacing proprietary charging interfaces simultaneously redraws component sourcing maps around Shenzhen electronics hubs and compresses margin capture for manufacturers locked into legacy battery architectures. This substitution dynamic forces pricing recalibration across rechargeable and disposable battery tiers as total cost of ownership calculations shift buyer preferences.
Pricing Analysis
German specialty retailers command 40-60% placement premiums over North American mass merchandisers for equivalent lumen-output units. Three-tier pricing structure across premium, standard, and economy levels separates industrial design credentials from basic utility specifications. Price differentiation hinges on certification grade (CE marking tier) and after-sales service bundling. Cost compression in the economy tier is intensifying because smartphone flashlight substitution captures casual readers. University students exhibit highest price sensitivity; remote workers in Austin and Seattle demonstrate lowest sensitivity due to circadian-health positioning.
Supply Chain Analysis
Inventory strategy favors just-in-time lithium-ion cell procurement from Yangtze River Delta assembly facilities rather than strategic stockpiling of LED semiconductor inventory. Supply concentrates in China for battery cells and flexible neck precision components, Germany for optical engineering subassemblies, and Vietnam for cable sheathing and plastic housings. Raw material dependencies include lithium carbonate, rare-earth phosphors for LED color temperature tuning, and RoHS-compliant halogen-free flame retardants. Single-source vulnerability in precision gooseneck mechanisms constrains scaling. Distribution runs through direct-to-consumer digital storefronts displacing traditional retail intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among direct-to-consumer channel specialists as procurement shifts from fragmented bookstore networks to consolidated e-commerce platforms with subscription accessory programs.
For Market Incumbents: Consolidate control over proprietary flexible neck manufacturing capabilities in Baden-Württemberg industrial clusters to defend against mid-tier manufacturers scaling production. Deepen backward integration into lithium-ion cell supply through captive partnerships with Shenzhen electronics hubs. Channel control through owned digital infrastructure remains the critical lever against Amazon Marketplace commission compression.
For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission consultations opens European specialty retail placement ahead of REACH compliance completion. The most penetrable white-space target is university student housing procurement contracts with theft-resistant mounting specifications. Campus residential RFP channels represent underserved volume concentration. Go-to-market angle: circadian-health certification partnerships with sleep medicine clinics.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer specialists possessing proprietary e-commerce infrastructure but limited manufacturing depth. Long-term viability across the analysis window favors targets with EU Green Deal alignment and extended producer responsibility certification. Acquisition target archetype: flexible-neck design innovators with specialty bookstore placement strength. Signal to watch: right-to-repair mandate passage triggering hardware architecture redesign cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Migration | Proprietary e-commerce infrastructure compresses retail markups and enables subscription accessory programs. |
| EU Green Deal Certification Alignment | Extended producer responsibility frameworks unlock preferential shelf positioning in European electronics retail chains. |
| Flexible Neck Precision Manufacturing Scale-Up | Baden-Württemberg engineering capabilities anchor differentiation in specialty bookstore channels. |
| USB-C Standardization Integration | California Title 20 compliance and EU energy efficiency mandates converge on unified power architecture. |
| Circadian-Health Feature Bundling | Tunable color temperature and dimming circuits capture remote worker demand in Austin and Seattle. |
Study Parameters
A spread of perspectives from product development leads at LED lighting manufacturers, procurement managers at university housing departments, specialty bookstore category buyers, and optical engineering specialists converged on the working assumptions. Secondary validation drew from EU Ecodesign Directive compliance filings, REACH substance restriction updates, California Title 20 appliance efficiency standards, and customs records for lithium-ion cell trade flows. Bottom-up shipment data triangulated against top-down retail audit estimates.
Segmentation dimensions modeled include power architecture, light source technology, distribution channel control, and feature bundling strategy across the projection horizon. CAGRs were derived from unit shipment trajectories and average selling price movements. Industry-specific forecast inputs incorporated USB-C adoption curves and right-to-repair regulatory probability assessments.
Decision-makers should treat outputs as directional under stable regulatory enforcement and intact semiconductor cost curves; material deviation would warrant model refresh. Revision becomes warranted when EU battery replaceability mandates cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Bottle Openers Market
Household Items
Pocket Tissues Market
Household Items
Air Care Market
Household Items
Facial Tissue Market
Household Items
High-Efficiency Laundry Liquid Detergent Market
Household Items
Smart Bathroom Market
Household Items
Smart Faucets Market
Household Items
Toilet Cistern Blocks Market
Household Items
North America Robotic Pool Cleaner Market
Household Items
Smart Bathtub Market
Household Items
Commercial Lawnmower Market
Household Items
Tiki Torch Market
Household Items
Russia Residential Water Heaters Market
Household Items
Gel Warmers Market
Household Items
Electric Mop Market
Household Items
Hands-Free Faucet Market