
 Fragrance-Free Cleaning Chemicals for Sensitive Environments Market | 2026-2036
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market Size, Share, and Industry Trends Forecast 2026-2036
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market Insights
Aftermarket service revenue from dispensing equipment calibration and chemical inventory management is reconfiguring margin pools away from bulk concentrate sales toward recurring facility service contracts. Ecolab leverages its institutional service infrastructure to anchor long-term healthcare partnerships. Diversey specializes in closed-loop dilution systems that reduce waste and labor costs for commercial cleaners. SC Johnson Professional competes through concentrated refill formats that lower shipping intensity and storage footprint for educational institutes.
Fragrance-free cleaning chemicals for sensitive environments are formulated without synthetic perfumes, masking agents, or volatile organic compounds that trigger respiratory or dermal reactions, typically employing quaternary ammonium compounds, hydrogen peroxide, or plant-derived surfactants at neutral pH to maintain efficacy while minimizing irritant potential. Surface cleaners dominate current procurement volumes across hospitality and food processing sectors where odor neutrality protects product integrity. Disinfectants represent the fastest-expanding product type as healthcare-associated infection protocols intensify scrutiny of chemical sensitivities among immunocompromised patients. Wipes sustain premium positioning in laboratories and childcare centers where ready-to-use formats eliminate dilution errors and cross-contamination risks.
EPA Safer Choice certification and EU Ecolabel compliance are reshaping product development roadmaps by mandating full ingredient disclosure and prohibiting specific fragrance precursors. OSHA workplace exposure limits and REACH substance restrictions further constrain formulation flexibility, elevating R&D costs for suppliers seeking multi-jurisdiction approval. Healthcare procurement officers and facility managers must monitor evolving state-level green cleaning mandates to anticipate specification changes before contract renewal cycles.
Market Dynamics
Healthcare procurement officers are rebalancing chemical specifications toward EPA Safer Choice and EU Ecolabel thresholds, forcing suppliers to absorb reformulation costs while defending contract renewals in price-sensitive institutional channels.
Growth Catalysts
- EPA Safer Choice thresholds:Federal procurement mandates in US healthcare facilities now exclude fragrance precursors above specified volatile organic compound limits, redirecting hospital supply budgets toward certified alternatives.
- Food processing integrity:Neutral-odor surface cleaners prevent cross-contamination of flavor profiles in dairy and beverage manufacturing, sustaining volume demand from quality-sensitive producers.
- Germany's federal hygiene guidelines:Hospital accreditation standards in German clinical settings mandate reduced chemical irritant exposure, creating specification lock-in for compliant suppliers.
Market Restraints
- Quaternary ammonium compound feedstock volatility:Petrochemical-derived surfactant inputs face price instability from energy market fluctuations, compressing margin predictability for formulators.
- Multi-jurisdiction approval costs:REACH substance restrictions, OSHA workplace exposure limits, and divergent state-level green cleaning mandates create redundant testing burdens for product registration.
- Performance-efficacy tradeoffs:Plant-derived alternatives to synthetic biocides demonstrate slower kill times against C. difficile spores, limiting substitution in critical care isolation protocols.
Strategic Opportunities
- Closed-loop dilution systems:Automated dispensing infrastructure reduces concentrate waste and labor variance for commercial cleaning contractors, creating recurring service revenue attachment.
- Childcare center wipes penetration:Ready-to-use formats eliminate dilution error liability in early education settings where staff turnover disrupts training continuity.
- EU Ecolabel compliance premium:Full ingredient disclosure requirements favor suppliers with transparent supply chains, enabling pricing power in sustainability-weighted tenders.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in neutral-pH biocide stability at low irritant thresholds commands premium compensation, constraining R&D throughput for mid-tier suppliers.
- Legacy inventory obsolescence:Reformulation cycles to meet tightening volatile organic compound thresholds strand existing stock in distributor warehouses, creating write-down exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fragrance-Free Cleaning Chemicals for Sensitive Environments Market |
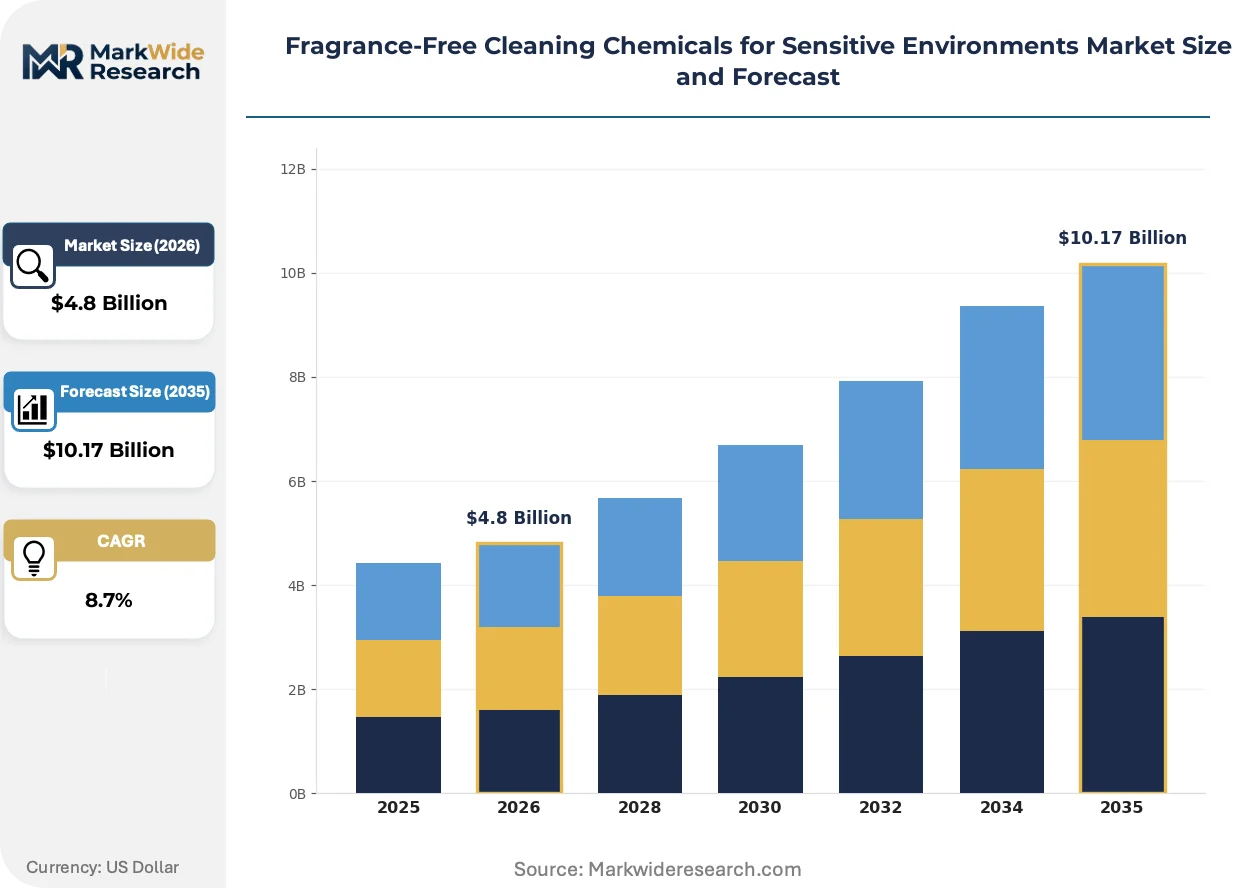
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disinfectants, Degreasers, Sanitizers, Detergents, Surface Cleaners Application: Healthcare Facilities, Laboratories, Childcare Centers, Food Processing, Hospitality Form: Liquid, Powder, Wipes, Foam, Gel End User: Institutional Users, Commercial Cleaners, Educational Institutes, Government Agencies |
| Companies Covered | Ecolab, Diversey, SC Johnson Professional, 3M, CloroxPro, Reckitt, P&G Professional, Unilever Professional, Zep, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market Trends and Innovations
Active chemistry platforms are pivoting toward hydrogen peroxide and plant-derived surfactant bases as synthetic quaternary ammonium compounds face accumulating regulatory pressure across North American and European jurisdictions.
Peracetic acid formulations are migrating from industrial sanitation into healthcare surface disinfection, where German hospital procurement groups pilot accelerated adoption timelines against traditional chlorine-based alternatives. The technology is compressing dwell-time requirements while maintaining sporicidal efficacy, enabling faster room turnover in patient safety zones.
REACH substance restrictions are prohibiting specific fragrance precursors and mandating full ingredient disclosure, elevating compliance costs for suppliers seeking multi-territory approval. Healthcare procurement officers in the Netherlands and Scandinavia now weight chemical sensitivity protocols more heavily in tender evaluations, disqualifying non-compliant bidders before price negotiation.
Facility managers are unbundling chemical supply from dispensing equipment service, separating commodity purchasing from calibration and inventory management contracts. This bifurcation is most visible in US educational institutes and hospitality chains, where specialized service providers capture recurring revenue streams that chemical manufacturers previously controlled through bundled offerings.
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market Segmentation
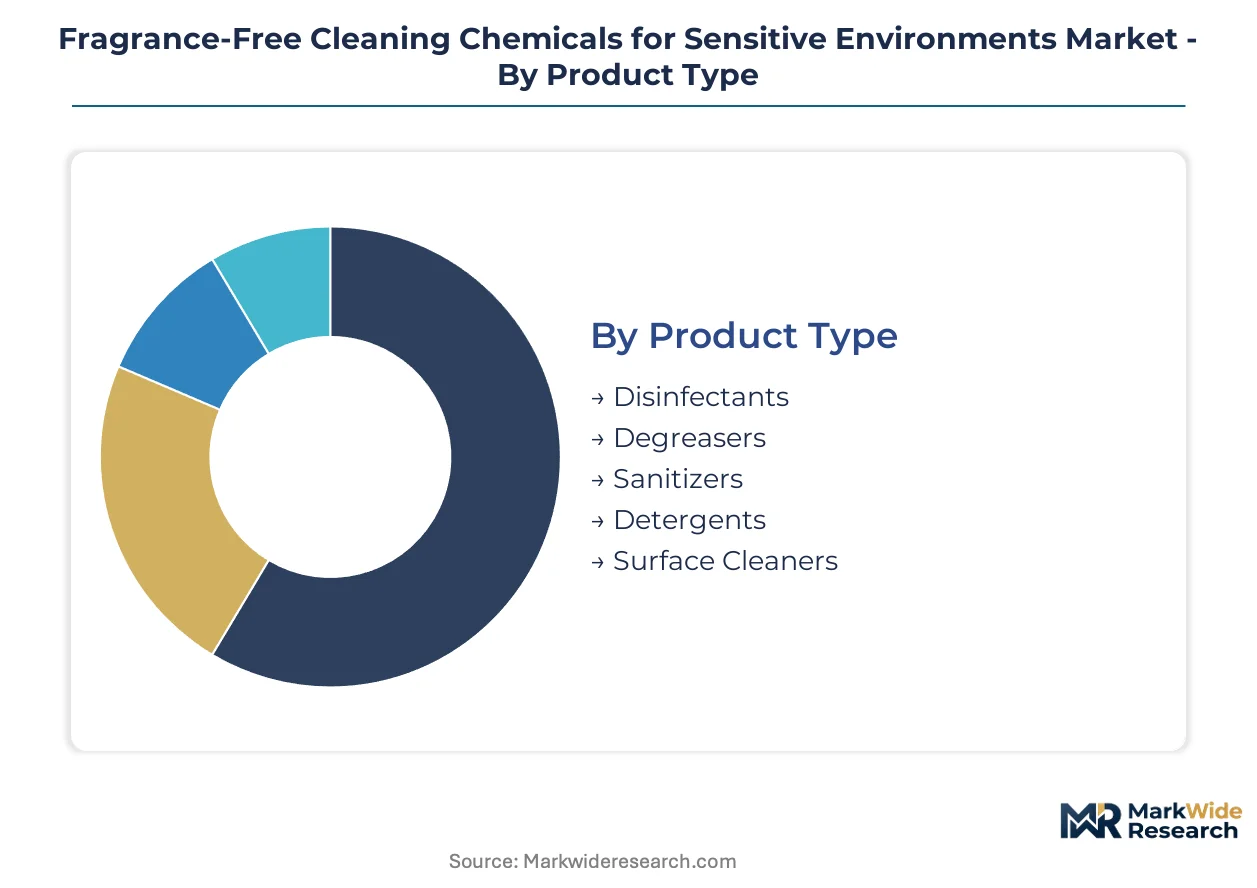
Segmentation in fragrance-free cleaning chemicals reveals how formulation chemistry, application environment, and delivery format intersect to determine procurement priorities. Each dimension carries distinct regulatory, performance, and cost specifications that reshape supplier positioning across institutional channels.
Product Type:
Application chemistry divides the market by efficacy requirements against specific pathogen classes and surface compatibility demands.
- Surface Cleaners:Neutral-pH formulations employing plant-derived surfactants or hydrogen peroxide bases clean without residue buildup on sensitive equipment. Hospitality procurement in Germany and US healthcare facilities drives volume concentration, with odor neutrality protecting guest experience and patient comfort zones.
- Disinfectants:Quaternary ammonium compounds and peracetic acid formulations deliver sporicidal efficacy for C. difficile protocols in critical care isolation units. Healthcare-associated infection mandates from the CDC and Germany's federal hygiene guidelines accelerate specification shifts toward low-irritant biocides.
- Degreasers:Alkaline formulations stripped of masking agents serve food processing equipment sanitation where flavor cross-contamination risks dominate quality protocols.
- Sanitizers:Reduced-toxicity formulations for non-food contact surfaces in childcare centers prioritize dermal safety over kill-speed metrics.
- Detergents:Concentrated surfactant systems for textile and hard surface washing in institutional laundries balance cleaning power with wastewater discharge compliance.
Surface cleaners command the established base. The steepest expansion runs through disinfectants.
Application:
End-use environment dictates formulation rigor, from sporicidal mandates in clinical settings to sensory neutrality in food production.
- Healthcare Facilities:EPA Safer Choice and EU Ecolabel compliance now gate hospital procurement contracts, with patient safety zones mandating full ingredient disclosure. German clinical accreditation standards and US federal procurement rules create specification lock-in for certified suppliers serving immunocompromised populations.
- Food Processing:Dairy and beverage manufacturers prioritize neutral-odor surface cleaners that prevent flavor profile contamination during production runs. Quality-sensitive producers sustain volume demand through strict sanitation standard operating procedures.
- Laboratories:Cleanroom-compatible formulations eliminate volatile organic compounds that interfere with analytical instrumentation or cell culture viability.
- Childcare Centers:Ready-to-use formats reduce dilution error liability where staff turnover disrupts training continuity and chemical handling protocols.
- Hospitality:Guest room and common area cleaning emphasizes immediate occupant re-entry without respiratory irritation from residual fumes.
Healthcare facilities anchor procurement volume. Food processing delivers the most rapid specification upgrades.
Form:
Physical delivery state determines labor economics, waste generation, and cross-contamination risk profiles across user environments.
- Liquid:Concentrate formats dominate institutional purchasing through closed-loop dilution systems that reduce shipping intensity and storage footprint.
- Wipes:Impregnated substrates command premium positioning in laboratories and childcare centers where single-use elimination of dilution steps prevents cross-contamination errors.
- Powder:Lightweight shipping profiles serve remote facility locations with limited chemical storage infrastructure.
- Foam:Extended contact time formulations cling to vertical surfaces in food processing sanitation protocols.
- Gel:Viscous applications target precision dosing in equipment maintenance and specialized healthcare device cleaning.
Liquid concentrates hold the volume foundation. Wipes capture the sharpest value-per-unit ascent.
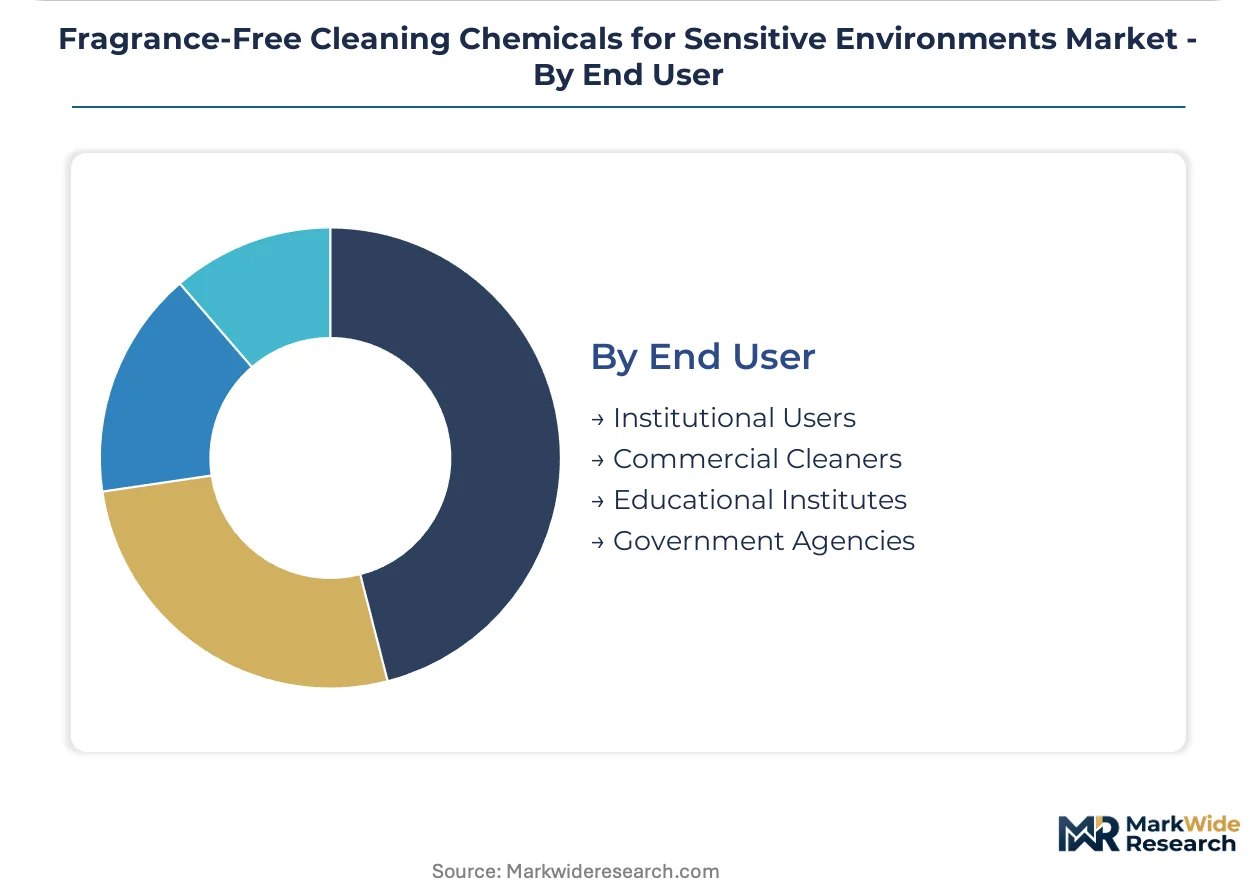
End User:
Customer type segments by procurement sophistication, contract scale, and service integration requirements.
- Institutional Users:Hospital systems and government facilities leverage multi-year service contracts bundling chemical supply with dispensing equipment calibration and inventory management.
- Commercial Cleaners:Contract cleaning contractors prioritize closed-loop dilution systems that reduce labor variance and chemical waste in high-turnover building maintenance accounts.
- Educational Institutes:School districts and universities separate commodity chemical purchasing from specialized service contracts, fragmenting vendor relationships.
- Government Agencies:Federal procurement mandates in the US now exclude non-EPA Safer Choice certified products, redirecting supply budgets toward compliant alternatives.
Institutional users dominate contract value. Commercial cleaners show the fastest service attachment adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospitals specify fragrance-free disinfectants at three times the rate of US facilities, while American educational institutes drive wipes consumption through decentralized procurement that European institutional buyers rarely replicate.
United States
Federal procurement mandates from EPA Safer Choice certification now exclude fragrance precursors above volatile organic compound limits in healthcare facilities. OSHA workplace exposure limits constrain formulation flexibility for suppliers seeking multi-state approval. The Boston-Cambridge hospital cluster anchors demand for low-irritant biocides serving immunocompromised patient populations.
Germany
Federal hospital hygiene guidelines mandate reduced chemical irritant exposure in clinical accreditation standards, creating specification lock-in for compliant suppliers. REACH substance restrictions prohibit specific fragrance precursors and mandate full ingredient disclosure. The Rhine-Ruhr metropolitan region concentrates procurement volume from university hospital networks piloting peracetic acid formulations.
United Kingdom
NHS procurement frameworks weight chemical sensitivity protocols heavily in tender evaluations for patient safety zones. EU Ecolabel compliance requirements elevate R&D costs for suppliers seeking territory approval. London's private hospital cluster drives premium positioning for ready-to-use formats eliminating dilution error liability.
Netherlands
Healthcare procurement officers in Dutch clinical settings disqualify non-EU Ecolabel compliant bidders before price negotiation. The country's national environmental regulator enforces stringent volatile organic compound thresholds in institutional cleaning contracts. The Randstad urban agglomeration concentrates demand from aged care facilities prioritizing dermal safety metrics.
Canada
Health Canada and PMRA coordinate substance restrictions on quaternary ammonium compound formulations in federal healthcare facilities. Provincial green cleaning mandates in Ontario and British Columbia anticipate specification changes before contract renewal cycles. The Greater Toronto Area anchors volume procurement from hospital systems bundling chemical supply with dispensing equipment service.
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market Competitive Landscape
Capability concentration sits with specialized formulators commanding premium compensation for neutral-pH biocide stability expertise; scale advantage sits with diversified chemical conglomerates absorbing multi-jurisdiction approval costs across institutional channels. The vendor base stratifies across three tiers: integrated service providers bundling equipment and chemicals, concentrate specialists optimizing closed-loop dilution systems, and ready-to-use format innovators capturing childcare center premiums. Dominant competitive moves include portfolio diversification into peracetic acid platforms and geographic expansion through distributor partnerships in German-speaking markets.
Within the integrated service tier, Ecolab anchors long-term healthcare partnerships through institutional infrastructure that bundles dispensing equipment calibration with chemical supply. Diversey exemplifies the concentrate specialist archetype through closed-loop dilution systems reducing waste and labor costs for commercial cleaning contractors. SC Johnson Professional occupies a position among format innovators competing through concentrated refill structures that lower shipping intensity for educational institutes with limited chemical storage infrastructure.
| Leading Market Players |
|---|
| Ecolab |
| Diversey |
| SC Johnson Professional |
| 3M |
| CloroxPro |
| Reckitt |
| P&G Professional |
| Unilever Professional |
| Zep |
| Others |
Pricing and Supply Chain Analysis
Petrochemical feedstock concentration in the US Gulf Coast and Rotterdam Antwerp corridor anchors margin pools downstream at formulators with captive surfactant supply or long-term offtake agreements. Contract structures bifurcate between multi-year service bundles for institutional healthcare accounts and spot purchasing for commercial cleaning contractors, with pricing power concentrating among suppliers integrating dispensing equipment calibration into chemical supply agreements.
Pricing Analysis
Long-term service contracts dominate institutional procurement, locking in recurring revenue through bundled equipment maintenance and inventory management. Price differentiation rests on EPA Safer Choice certification tier and closed-loop dilution system integration. Cost compression in standard-grade concentrates is intensifying because REACH substance restrictions force reformulation cycles. Commercial cleaning contractors exhibit highest price sensitivity, while German hospital systems prioritize compliance premiums over unit cost.
Supply Chain Analysis
REACH substance restrictions limiting quaternary ammonium compound flows from European suppliers are reshaping sourcing patterns for North American formulators. Manufacturing concentrates in Germany, the Netherlands, and the US Midwest, with hydrogen peroxide and plant-derived surfactant feedstocks drawing from Belgian and Brazilian bio-refinery networks. Single-source vulnerability runs through German specialty chemical houses for neutral-pH biocide stabilizers. Distribution runs through institutional service providers and janitorial supply distributors serving fragmented commercial cleaner bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with facility managers unbundling chemical supply from equipment service, creating niche entry points for specialized formulators targeting certification-weighted tenders. Specification divergence between healthcare, food processing, and educational channels multiplies addressable micro-segments.
For Market Incumbents: Pre-empt margin erosion in bulk concentrate tiers by deepening captive supply of hydrogen peroxide feedstocks and accelerating peracetic acid platform registration across German-speaking markets. Defend healthcare contract renewals through EPA Safer Choice portfolio breadth that mid-tier suppliers cannot replicate within reformulation deadlines. For New Entrants and Emerging Players: Pursue childcare center wipes penetration in US educational institutes where decentralized procurement bypasses incumbent service bundling. Target Dutch and Scandinavian healthcare tenders disqualifying non-EU Ecolabel bidders before price negotiation, leveraging transparent supply chain disclosure as primary go-to-market wedge. For Investors and Strategic Acquirers: Capital is best deployed toward formulators with proven neutral-pH biocide stability expertise and existing REACH multi-territory registrations, given five-to-ten year consolidation horizon as compliance costs stratify the vendor base. Signal to monitor: German federal hygiene guideline amendments accelerating peracetic acid specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surfactant Feedstocks | Captive hydrogen peroxide supply insulates margin from petrochemical volatility and REACH restriction cascades. |
| Peracetic Acid Platform Registration | German hospital pilot programs favor early registrants with sporicidal efficacy data against C. difficile protocols. |
| Closed-Loop Dilution System Deployment | Recurring calibration revenue attaches to chemical supply, locking out commodity competitors from institutional accounts. |
| EU Ecolabel Compliance Investment | Full ingredient disclosure requirements disqualify opaque supply chains from Dutch and Scandinavian tenders. |
| Ready-to-Use Format Expansion | Wipes penetration in childcare centers eliminates dilution error liability where staff turnover disrupts training. |
Research Methodology
Desk research of EPA Safer Choice certified product registries, REACH substance restriction filings, and EU Ecolabel technical documentation preceded structured interviews with hospital procurement officers, commercial cleaning contractor operations managers, formulation R&D directors, and janitorial supply distributors. Primary fieldwork across the analysis window captured specification evolution in German clinical accreditation audits and US federal healthcare procurement mandates. Secondary validation drew from customs trade data for quaternary ammonium compound imports, ACC sector reports, and facility management association expenditure surveys. Bottom-up demand modeling triangulated against top-down chemical industry production capacity estimates.
Assumptions held fixed include current EPA Safer Choice volatile organic compound thresholds, REACH substance restriction timelines, and German federal hygiene guideline accreditation standards; variables tested included hydrogen peroxide feedstock price trajectories and childcare center staffing turnover rates. Segmentation dimensions modeled encompass product chemistry platform, delivery format, end-use environment, and procurement channel sophistication. CAGRs were derived from installation base expansion for closed-loop dilution systems and wipes consumption intensity per square meter across healthcare and educational facilities. Industry-specific inputs incorporated hospital-associated infection protocol revision frequency and food processing sanitation standard operating procedure update cycles.
Macroeconomic conditions sit as an overlay; deviation in energy market volatility affecting petrochemical-derived surfactant costs would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement consistency and institutional procurement cycle timing. Material shifts in EPA or ECHA threshold tightening schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Efflorescence Remover Market
Cleaning Chemicals
Eco-Label Certified Cleaning Chemicals for Professional Users Market
Cleaning Chemicals
Rust Remover Market
Cleaning Chemicals
Europe Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market
Cleaning Chemicals
Europe Metal Cleaning Chemicals Market
Cleaning Chemicals
Fabric Conditioner Market
Cleaning Chemicals
Document Cleaning Powder Market
Cleaning Chemicals
North America Surface Treatment Chemicals Market
Cleaning Chemicals
Multi-Residue Detoxifying Field Wash Aid Market
Cleaning Chemicals
Kitchen Vent Hood and Duct Cleaning Chemicals Market
Cleaning Chemicals
Industrial and Institutional Hand Hygiene Chemicals Market
Cleaning Chemicals
Dishwashing Liquid Market
Cleaning Chemicals
Instrument Cleaners and Detergents Market
Cleaning Chemicals
Metal Polish Products Market
Cleaning Chemicals
Korea Industrial and Institutional Cleaning Chemicals Market