
 Floor Wax Market | 2026-2036
Floor Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Wax Market Foresight
The EU F-Gas Regulation and California Air Resources Board mandates on volatile organic compound emissions is hardening compliance requirements for solvent-based formulations. Ecolab leverages its institutional channel network to sustain contract coverage across healthcare and education verticals. SC Johnson & Son anchors retail shelf presence with consumer-focused water-based lines, while Diversey Holdings dominates commercial janitorial supply through direct facility management partnerships.
Floor wax comprises a protective coating formulation, typically incorporating acrylic polymers, polyurethane, or natural carnauba derivatives suspended in aqueous or hydrocarbon carriers, applied to hard surface flooring to enhance abrasion resistance and optical gloss. Water-based emulsion waxes now lead volume due to compatibility with automated scrubber-dryer equipment and same-day re-coating protocols. Solvent-based wax retains margin concentration in industrial surfaces where chemical resistance and extended wear cycles justify higher material costs and specialized application labor.
The EPA Safer Choice label, REACH restrictions on aromatic solvents, and OSHA workplace exposure limits collectively constrain formulation chemistry and drive R&D toward bio-based polymer alternatives. Product registration with state environmental agencies now determines market access for new introductions, particularly in the Northeast and California corridors. Stakeholders must weigh reformulation investment against regional compliance fragmentation when allocating manufacturing capacity and distribution infrastructure.
Market Dynamics
Water-based emulsion systems are displacing solvent carriers as the dominant formulation platform, driven by EPA Safer Choice certification requirements and automated scrubber-dryer compatibility in commercial facilities.
Growth Catalysts
- California CARB VOC mandates:Facility managers in healthcare and hospitality sectors accelerate specification of compliant water-based finishes to avoid penalty exposure and secure LEED certification credits.
- Automated scrubber-dryer penetration:Same-day re-coating protocols enabled by rapid-cure aqueous polymers reduce labor downtime in retail and logistics flooring maintenance programs.
- Healthcare facility upgrades:Infection control protocols in United States hospitals drive demand for durable, chemical-resistant floor coatings that withstand aggressive disinfection cycles.
Market Restraints
- Petrochemical feedstock volatility:Acrylic polymer and polyurethane precursor costs fluctuate with crude oil derivatives, compressing margin stability for formulators without backward integration into resin production.
- Specialized application labor scarcity:Solvent-based industrial wax installation requires certified technicians with OSHA exposure limit training, constraining deployment speed in manufacturing environments.
- Natural carnauba supply concentration:Brazilian harvest variability and climate sensitivity of palm wax sources create raw material security risks for bio-based premium product lines.
Strategic Opportunities
- United States Northeast corridor:State environmental agency registration requirements in New York and Massachusetts create first-mover advantage for pre-approved water-based formulations.
- EU F-Gas Regulation alignment:Reformulation investment to meet aromatic solvent restrictions opens parallel access to European commercial janitorial markets with harmonized compliance documentation.
- Bio-based polymer R&D:Cellulose-derived and lignin-based alternatives to petroleum acrylics address sustainability procurement criteria in institutional purchasing contracts.
Industry Challenges
- Multi-jurisdiction registration timelines:State-by-state environmental product approvals in the United States extend new formulation launch cycles by 18-24 months.
- Legacy solvent infrastructure stranded costs:Manufacturers face write-downs on hydrocarbon carrier storage and handling equipment as water-based capacity scales.
- Performance parity gaps:Aqueous systems struggle to match solvent-based chemical resistance in heavy industrial settings, limiting vertical expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Wax Market |
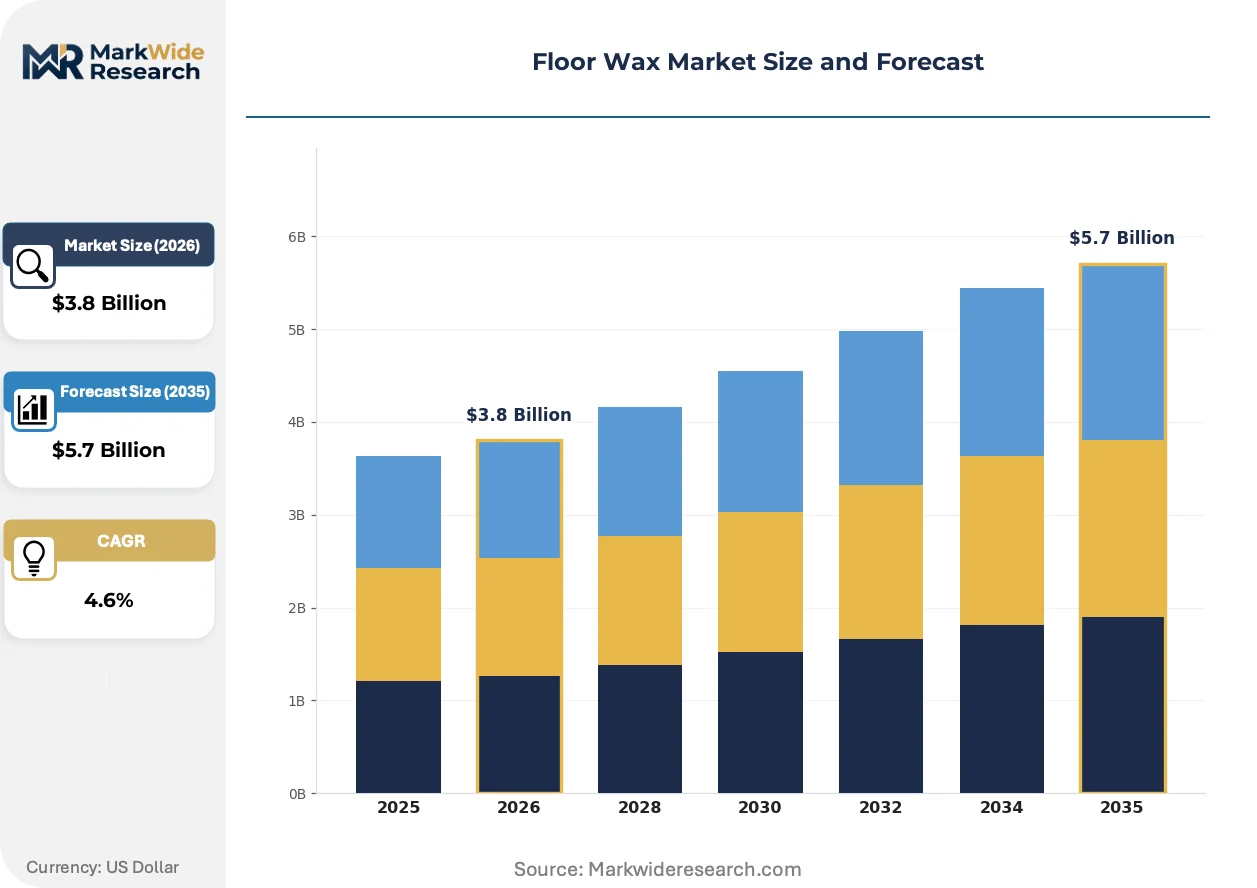
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Wax, Solvent-Based Wax, Paste Wax, Spray Wax, Emulsion Wax Application: Residential Flooring, Commercial Flooring, Industrial Surfaces, Hospitality Venues, Educational Institutions Form: Liquid, Paste, Powder, Cream, Aerosol End User: Cleaning Companies, Facility Management, Janitorial Services, Property Management Firms, DIY Consumers |
| Companies Covered | Diversey Holdings, Nilfisk, SC Johnson & Son, Zep, Kärcher, Ecolab, Tennant Company, Betco Corporation, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Wax Market Shifts & Advancements
Formulation chemistry is pivoting toward bio-derived polymers and low-VOC aqueous carriers, while application equipment digitization and procurement platform consolidation reshape how buyers source and deploy floor maintenance systems.
Polyurethane-acrylic hybrid emulsions are integrating cross-linking density improvements that match solvent-based abrasion resistance without hydrocarbon carriers. Large-format retail chains in the United States specify these systems for high-traffic zones, compressing re-coating intervals from quarterly to monthly cycles while reducing VOC exposure liability.
REACH restrictions on aromatic solvents are forcing European formulators to eliminate xylene and toluene carriers from industrial-grade waxes. German manufacturing facilities and Dutch logistics hubs face the tightest compliance deadlines, accelerating adoption of water-based alternatives with equivalent chemical resistance profiles.
Facility management procurement platforms are consolidating vendor relationships into integrated supply contracts that bundle floor wax with application equipment and maintenance scheduling. Healthcare systems in the United States favor these arrangements, shifting purchasing authority from decentralized maintenance departments to centralized supply chain functions with sustainability scorecards.
Floor Wax Market Segmentation
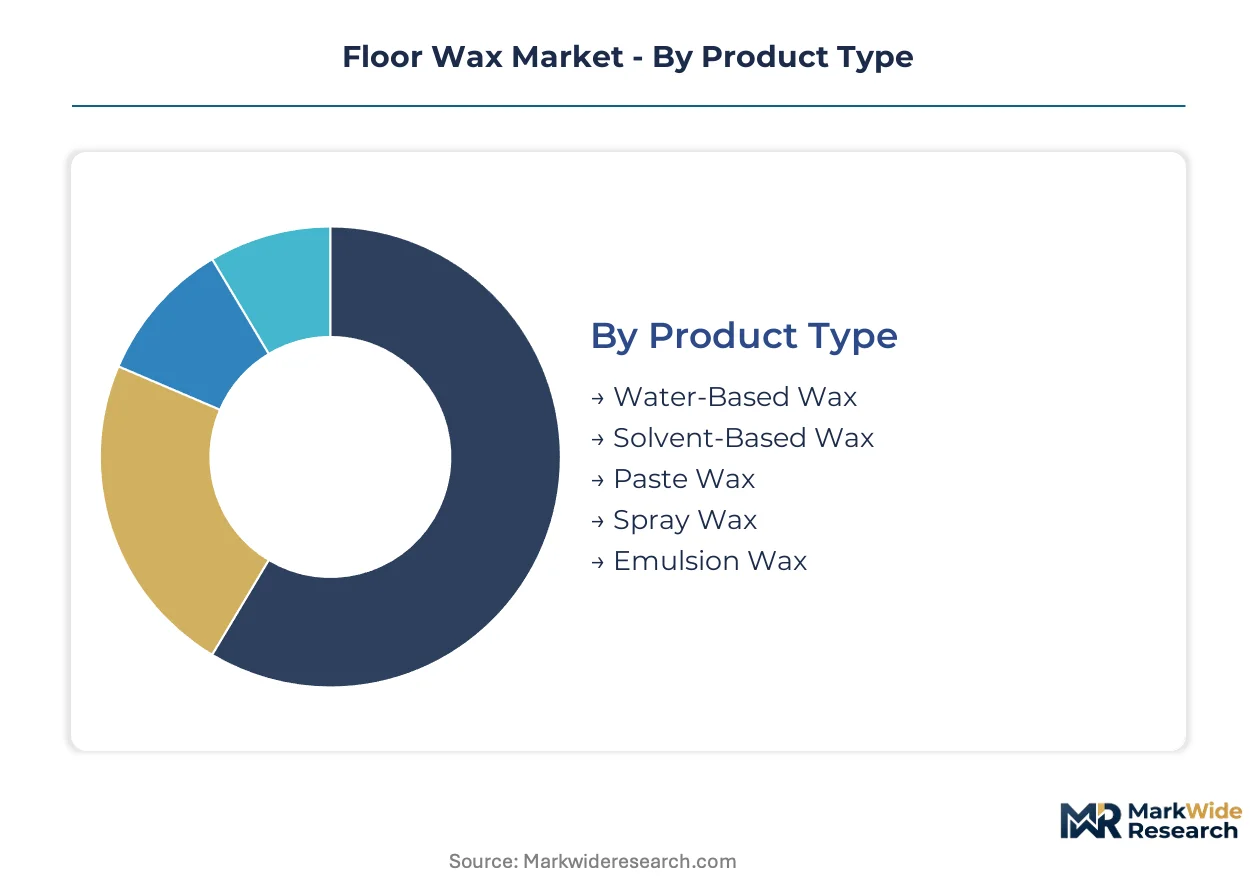
Floor wax procurement varies sharply by buyer sophistication, application environment, and regulatory exposure. Segmentation reveals where formulation investments concentrate and which channels command premium positioning.
Product Type:
Buyers differentiate primarily by compliance burden and equipment compatibility, not merely gloss performance.
- Water-Based Wax:Acrylic-polyurethane hybrid emulsions suspended in aqueous carriers cure rapidly for same-day re-coating protocols. Healthcare systems in the United States specify these formulations to satisfy EPA Safer Choice requirements and LEED certification criteria while maintaining automated scrubber-dryer throughput.
- Solvent-Based Wax:Hydrocarbon carriers deliver superior chemical resistance and extended wear cycles on manufacturing floors. Industrial facilities in the United States tolerate higher material costs and specialized OSHA-certified application labor where aqueous systems fail performance parity tests.
- Paste Wax:High-solids carnauba or synthetic blends for manual buffing applications in heritage residential settings.
- Spray Wax:Convenience-oriented aerosol or pump formats targeting spot maintenance and DIY retail channels.
- Emulsion Wax:Stabilized oil-in-water dispersions bridging cost and performance for mid-market commercial contracts.
Volume sits with water-based systems; growth tilts toward emulsion hybrids that balance compliance and cost.
Application:
Surface traffic intensity and disinfection protocol severity determine specification rigor across verticals.
- Commercial Flooring:Retail chains and logistics hubs demand rapid-cure finishes compatible with overnight maintenance windows. Large-format operators in the United States compress re-coating cycles through monthly aqueous polymer applications rather than quarterly solvent-based regimes.
- Hospitality Venues:Hotels and conference centers prioritize optical gloss and slip resistance for guest-facing areas. Facility managers specify low-VOC water-based systems to avoid penalty exposure under California CARB mandates while sustaining 24-hour operational turnaround.
- Residential Flooring:Homeowners favor paste and spray formats for hardwood and vinyl maintenance.
- Industrial Surfaces:Manufacturing plants require chemical-resistant coatings surviving aggressive solvent spills and heavy forklift traffic.
- Educational Institutions:K-12 and university facilities balance budget constraints with indoor air quality standards.
Commercial flooring commands the revenue base; hospitality venues are climbing the fastest as post-pandemic renovation cycles accelerate.
Form:
Physical state dictates application labor requirements and storage logistics throughout distribution channels.
- Liquid:Bulk concentrate and ready-to-use formulations dominate institutional procurement through dilution-control dispensing systems. Janitorial supply houses in the United States Northeast corridor stock liquid SKUs pre-registered with state environmental agencies to accelerate contract fulfillment.
- Paste:High-viscosity solids for professional restoration of natural stone and hardwood surfaces.
- Powder:Water-soluble polymer blends for industrial-scale mixing operations.
- Cream:Intermediate viscosity for controlled application on ornate or damaged substrates.
- Aerosol:Propellant-driven convenience formats for touch-up maintenance and consumer retail.
Liquid formulations anchor procurement volume; paste formats retain margin concentration in specialized restoration segments.
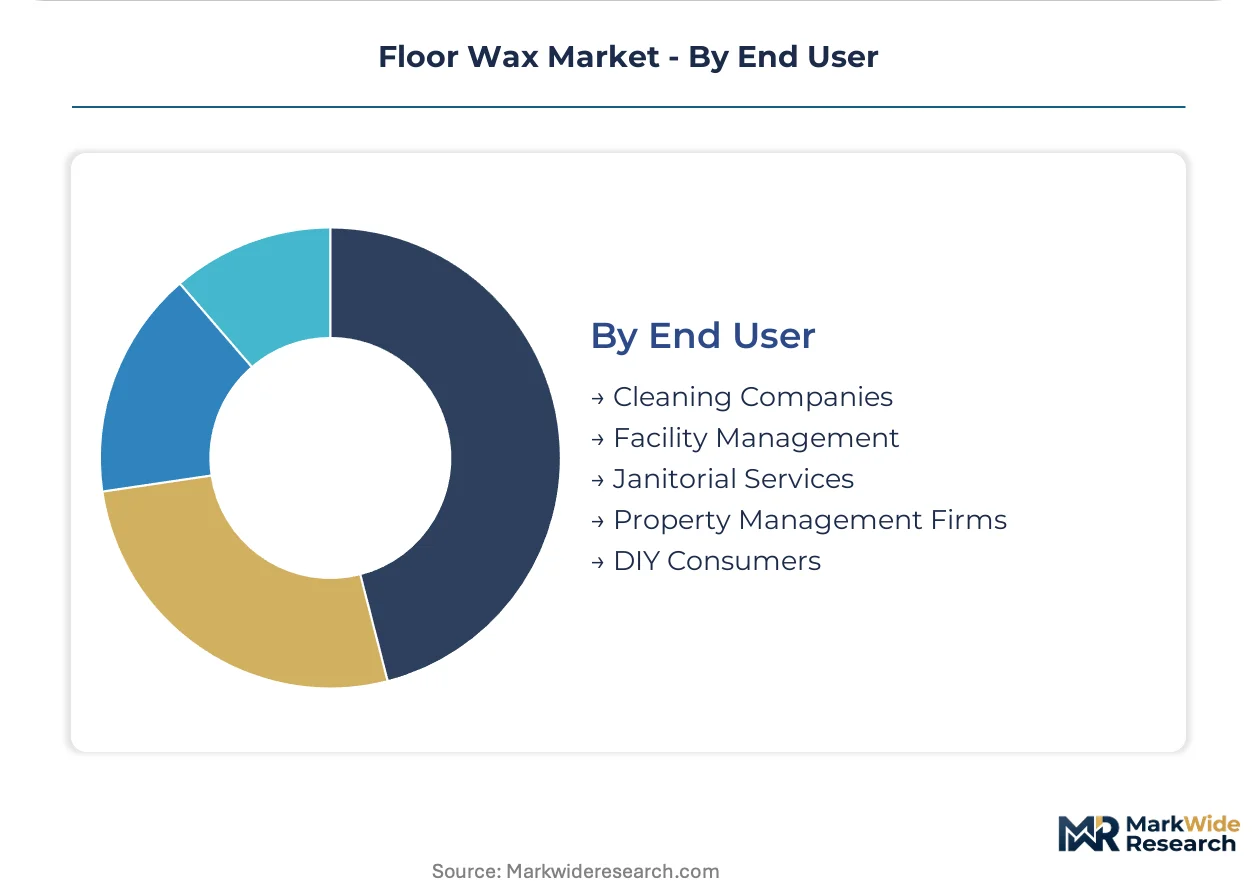
End User:
Purchasing authority centralization and sustainability scorecard adoption separate institutional buyers from fragmented consumer demand.
- Facility Management:Integrated service providers bundle floor wax with application equipment and maintenance scheduling through multi-year contracts. Healthcare systems in the United States shift purchasing authority from decentralized maintenance departments to centralized supply chain functions with mandatory EPA Safer Choice specifications.
- Janitorial Services:Contract cleaners demand cost-optimized aqueous emulsions compatible with rapid crew deployment across multiple client sites.
- Cleaning Companies:Specialized operators serving premium commercial accounts.
- Property Management Firms:Multi-tenant residential and mixed-use portfolio operators.
- DIY Consumers:Retail-driven purchasers selecting spray and paste formats for residential application.
Facility management concentrates contract value; janitorial services are expanding most quickly as outsourcing penetrates mid-market commercial accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Chicago metropolitan corridor anchors North American floor wax procurement volume through its dense concentration of healthcare systems, logistics hubs, and institutional facility management headquarters. Distribution networks radiate from this hub to serve nationwide retail chains and hospital networks.
United States
Healthcare facility upgrades and large-format retail renovation cycles drive specification of EPA Safer Choice-certified water-based formulations. California CARB VOC mandates harden compliance requirements for solvent-based products in the Northeast and West Coast corridors. The Dallas-Fort Worth metroplex concentrates distribution infrastructure for janitorial supply houses serving the South Central region.
Germany
Industrial manufacturing facilities and Dutch logistics hubs accelerate adoption of REACH-compliant water-based alternatives to aromatic solvent carriers. The EU F-Gas Regulation alignment creates export documentation advantages for formulators serving adjacent European markets. The Rhine-Ruhr industrial belt generates concentrated demand for chemical-resistant coatings in heavy-traffic manufacturing environments.
China
Rapid urban commercial construction and hospitality sector expansion sustain volume growth for emulsion-based maintenance products. The country's national environmental protection ministry enforces tightening VOC emission standards in Tier-1 cities. The Yangtze River Delta manufacturing cluster houses domestic formulators scaling water-based polymer production for regional supply.
United Kingdom
Post-pandemic hospitality renovation and educational facility refurbishment concentrate procurement authority in London-based facility management groups. The Health and Safety Executive workplace exposure guidelines constrain solvent-based application in enclosed commercial spaces. The Midlands logistics corridor supports distribution of pre-registered compliant formulations to institutional buyers.
Brazil
Expanding retail infrastructure and multi-tenant commercial property development drive demand for cost-optimized aqueous emulsions. The national health surveillance agency maintains registration requirements for industrial chemical products entering commercial channels. The São Paulo metropolitan area concentrates janitorial service providers and property management firms with centralized purchasing functions.
Floor Wax Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance certification and institutional contract coverage. The vendor base clusters around three strategic archetypes: institutional channel specialists with direct facility management partnerships, retail-shelf dominant consumer brands, and equipment-integrated service providers bundling chemistry with application hardware. Capacity expansion in water-based emulsion production and strategic partnerships with automated scrubber-dryer manufacturers represent the dominant competitive moves reshaping positioning.
Among North American institutional specialists, Diversey Holdings and Ecolab occupy positions exemplifying the facility management contract archetype, while SC Johnson & Son anchors the consumer-facing retail tier with water-based product lines. These three entities represent distinct strategic postures: direct B2B contract coverage, integrated equipment-chemistry bundling, and mass-market brand equity.
| Leading Market Players |
|---|
| Diversey Holdings |
| Nilfisk |
| SC Johnson & Son |
| Zep |
| Kärcher |
| Ecolab |
| Tennant Company |
| Betco Corporation |
| 3M Company |
| Others |
Supply & Pricing Matrix
California CARB VOC mandates gate qualified supply and premium-tier pricing access, as only pre-registered water-based formulations command institutional contract premiums while solvent-based alternatives face penalty-driven cost compression. Facility managers in healthcare and hospitality sectors now treat EPA Safer Choice certification as a threshold condition for vendor qualification, bifurcating the supplier base into compliance-premium and commodity-margin tiers.
Pricing Analysis
Re-coating interval guarantees anchor value-based pricing, with large-format retail chains contracting for monthly aqueous polymer applications versus quarterly solvent regimes. Three-tier pricing structure across premium, standard, and economy levels separates EPA-certified hybrids from state-registered emulsions and unregistered commodity blends. Cost compression in solvent-based tiers is intensifying because OSHA-certified application labor scarcity inflates service bundling costs. Janitorial services exhibit highest price sensitivity; healthcare systems with centralized procurement functions show lowest sensitivity due to sustainability scorecard mandates.
Supply Chain Analysis
Domestic-content requirements in United States Northeast corridor state registration programs reshape sourcing toward regional formulators with pre-approved environmental agency filings. Acrylic polymer production concentrates in the United States, Germany, and China; carnauba wax supply draws from Brazilian palm cultivation. Petrochemical feedstock volatility and Brazilian harvest variability constitute the primary structural risks. Distribution runs through janitorial supply houses and direct facility management partnerships, with liquid concentrate SKUs dominating institutional fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-registered water-based formulation capacity represents the binding constraint propping pricing premiums, as multi-jurisdiction approval timelines extend 18-24 months for new entrants.
For Market Incumbents: Cement contract renewals through integrated equipment-chemistry bundling with automated scrubber-dryer manufacturers. Accelerate backward integration into acrylic polymer resin production to offset petrochemical feedstock volatility. Prioritize capacity addition in the Dallas-Fort Worth metroplex to capture South Central distribution efficiency gains against emerging regional formulators. For New Entrants and Emerging Players: Mid-market educational institutions represent an underserved buyer archetype with decentralized maintenance departments and limited sustainability procurement expertise. Target K-12 facilities in the United States Northeast corridor awaiting state environmental agency registration compliance deadlines. Deploy direct-to-facility sales teams with dilution-control dispensing system demonstrations to bypass entrenched janitorial supply house relationships. For Investors and Strategic Acquirers: First-mover state registration approvals in New York and Massachusetts are the leading indicator that regional market access premiums will persist. Acquire formulators with captive resin production and pre-approved Northeast corridor registrations. Monitor Brazilian carnauba harvest yield reports as the inflection signal for bio-based premium product line margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Polymer Production | Captive resin supply insulates margin stability against crude derivative volatility in aqueous emulsion manufacturing. |
| Multi-Jurisdiction Registration Pre-Approval | First-mover status in California CARB and Northeast state programs secures institutional contract access before competitors complete filings. |
| Automated Scrubber-Dryer Equipment Partnership | Same-day re-coating protocol compatibility with Tennant and Nilfisk systems locks in healthcare and retail facility specifications. |
| Bio-Based Polymer R&D Investment | Cellulose-derived alternatives address sustainability procurement criteria in institutional purchasing contracts ahead of petroleum acrylic substitution. |
| Centralized Supply Chain Function Targeting | Direct relationships with healthcare system procurement offices bypass fragmented maintenance department decision-making. |
Research Methodology
Multi-period observation of EPA Safer Choice certification adoption rates and state registration approval timelines anchored the trend analysis, supplemented by interviews with facility management procurement directors, janitorial supply house category managers, formulator R&D directors, and automated scrubber-dryer equipment manufacturers. Secondary validation drew from EPA Safer Choice product listings, California CARB consumer product regulations, customs trade data on acrylic polymer imports, and SEC filings of institutional cleaning chemical suppliers. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Segment-weighting across product type, application environment, and end-user procurement authority shaped the analytical framework throughout the projection horizon. Modeled dimensions included water-based versus solvent-based formulation chemistry, commercial flooring versus industrial surface application, and facility management versus janitorial services purchasing structure. CAGRs derived from regression analysis of historical volume trends against regulatory compliance deadline schedules and healthcare facility capital expenditure cycles. Feedstock cost indices and automated equipment penetration rates served as industry-specific forecast inputs.
Revisions become necessary when Brazilian carnauba harvest yields diverge materially from baseline assumptions or when additional United States states adopt California-equivalent VOC restrictions ahead of modeled timelines. Forecasts reflect documented assumptions regarding regulatory compliance cost pass-through rates and institutional buyer sustainability scorecard weightings. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Brazil Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Europe Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Sanitizing Agents Market
Cleaning Chemicals
Electrostatic Liquid Cleaner Market
Cleaning Chemicals
Industrial Degreaser Market
Cleaning Chemicals
Commercial Deodorizers Market
Cleaning Chemicals
Autonomous Floor Cleaning Machine Detergent and Care Chemicals Market
Cleaning Chemicals
Metal Polish Products Market
Cleaning Chemicals
Lens Cleaning Product Market
Cleaning Chemicals
North America Surface Treatment Chemicals Market
Cleaning Chemicals
Chlorhexidine Gluconate (CHG) Cloth Market
Cleaning Chemicals
Concentrated Laundry Powder Market
Cleaning Chemicals
Cleanroom Consumables Market
Cleaning Chemicals
Mask Reticle Cleaning Agent Market
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
Commercial Cleaning Products Market