
 Copovidone Market | 2026-2036
Copovidone Market Size, Share, and Industry Trends Forecast 2026-2036
Copovidone Market Outlook
Pharmaceutical end-use is shifting toward complex oral solid dosage forms as generic manufacturers reformulate off-patent drugs for bioequivalence. Ashland leverages its polymeric excipient portfolio to sustain North American supply relationships with major tablet producers. BASF competes through integrated vinyl pyrrolidone chemistry capabilities that anchor European pharmaceutical supply chains.
Copovidone is a water-soluble copolymer of N-vinyl-2-pyrrolidone and vinyl acetate, typically supplied in K-value ranges of 25–35 and functioning as a tablet binder, film former, and solubility enhancer in pharmaceutical processing. Powder grades dominate current volume consumption due to their compatibility with direct compression and wet granulation methods, while granule formats are gaining traction in continuous manufacturing lines where flow uniformity commands premium positioning. Tablet formulations occupy the largest application share, though coating applications are expanding as functional film barriers gain adoption in moisture-sensitive drug delivery.
The FDA maintains Current Good Manufacturing Practice oversight of excipient suppliers through drug master file expectations, while the EMA enforces European Pharmacopoeia monograph compliance for polyvinylpyrrolidone copolymers used in human medicines. REACH registration requirements in Europe and evolving USP-NF standards for excipient functionality testing are elevating documentation burdens for new market entrants. Stakeholders must monitor regulatory divergence between pharmacopoeial standards as a determinant of cross-border formulation approval timelines and supplier switching costs.
Market Dynamics
Immediate-release and sustained-release tablet demand is reshaping excipient qualification requirements as generic manufacturers reformulate off-patent molecules for bioequivalence. Regulatory tightening by the FDA and EMA around polymeric excipient standards is forcing supplier consolidation and documentation upgrades.
Growth Catalysts
- Tablet binder standardization:Direct compression adoption in high-volume generic manufacturing is elevating copovidone specification consistency across United States and German production facilities.
- FDA drug master file alignment:Current Good Manufacturing Practice enforcement for excipient suppliers is accelerating formal qualification partnerships between polymer producers and finished-dose manufacturers.
- Continuous manufacturing integration:Flow uniformity requirements in continuous processing lines are pulling granule-grade copovidone into new equipment configurations.
Market Restraints
- Vinyl acetate feedstock volatility:N-vinyl-2-pyrrolidone monomer supply concentration in select chemical manufacturing clusters creates input cost exposure.
- REACH documentation burden:European copolymer registration requirements and evolving USP-NF functionality testing standards are elevating compliance costs for new market entrants.
- Hydroxypropyl cellulose substitution:Alternative polymeric binders with established pharmacopoeial monographs compete for wet granulation applications in cost-sensitive formulations.
Strategic Opportunities
- Moisture-sensitive coating expansion:Functional film barrier applications for hygroscopic active pharmaceutical ingredients are opening specialized copovidone grades in controlled-release segments.
- Indian generic manufacturing scale-up:CDSCO-aligned excipient qualification pathways and domestic production incentives are creating supplier entry points for export-oriented tablet producers.
- Continuous line granule adoption:Flow-optimized copovidone formats are penetrating pharmaceutical continuous manufacturing installations where powder uniformity commands premium positioning.
Industry Challenges
- Pharmacopoeial divergence management:Cross-border formulation approval timelines suffer from non-harmonized polyvinylpyrrolidone copolymer monographs between FDA and EMA jurisdictions.
- Excipient functionality certification:USP-NF performance testing documentation requirements extend supplier onboarding cycles for multi-source generic drug applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copovidone Market |
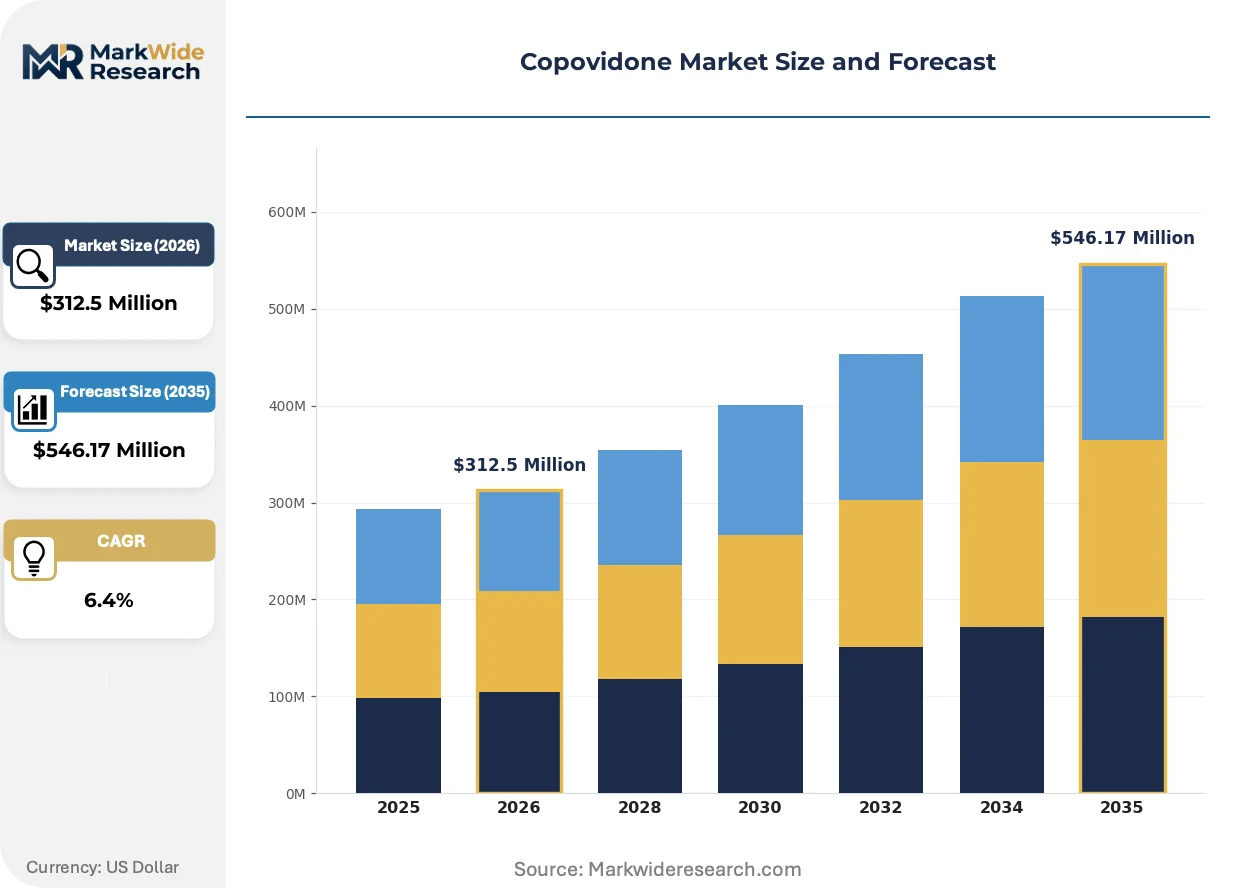
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Pellets, Sheets Formulation: Tablets, Capsules, Solutions, Coatings End User: Pharmaceuticals, Cosmetics, Nutraceuticals, Food Industry Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Ashland, BASF, JH Nanhang, Resonac Corporation, JRS Pharma, BOC Sciences, Clinivex, Glentham Life Sciences, BOAI NKY MEDICAL HOLDINGS LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copovidone Market Strategic Shifts
Tablet manufacturing technology is converging with regulatory documentation demands to reshape how polymeric excipients qualify for commercial supply. Process innovation and compliance automation are compressing traditional supplier selection timelines.
Continuous manufacturing equipment is consolidating copovidone specification requirements around flow-optimized granule formats. Generic drug producers in high-volume United States manufacturing clusters are adopting these grades at accelerated pace to meet uniformity targets in direct compression lines. This consolidation is compressing demand for conventional powder grades in new facility investments while elevating technical service expectations.
EMA European Pharmacopoeia monograph revisions for polyvinylpyrrolidone copolymers are tightening identity and impurity specifications for human medicine applications. Finished-dose manufacturers must revalidate existing supplier qualifications or absorb switching costs to compliant sources. German and Swiss pharmaceutical clusters are responding fastest, with documentation upgrades preceding formal regulatory deadlines.
Buyer concentration among large-scale generic manufacturers is consolidating procurement leverage over excipient suppliers. Multi-year supply agreements with integrated technical support are displacing spot purchasing in tablet binder categories. This shift is most visible in United States generic manufacturing corridors where formulary access depends on manufacturing cost control.
Copovidone Market Segmentation
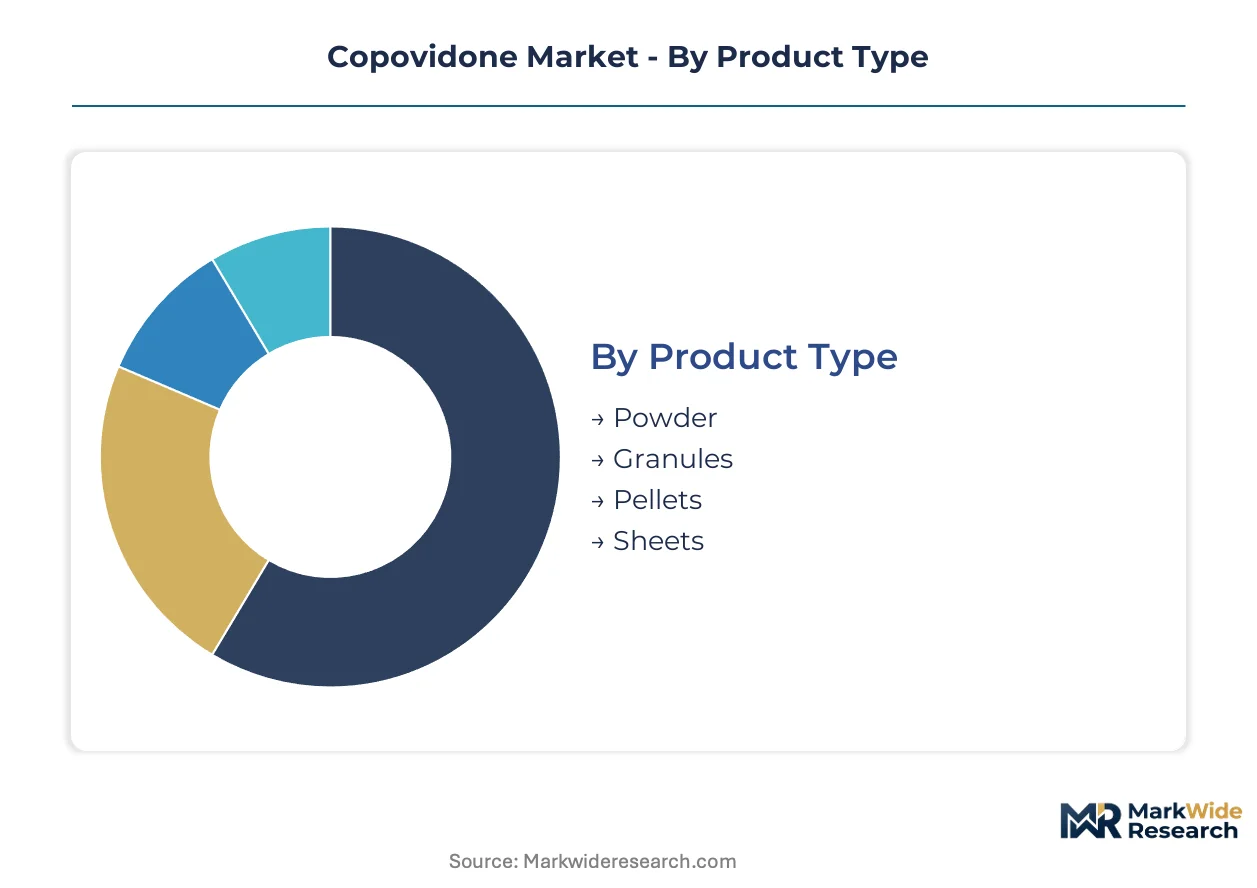
Copovidone specification requirements diverge sharply across pharmaceutical processing methods. Each segment demands distinct capital commitments for manufacturing equipment, quality systems, and regulatory documentation.
Product Type:
Capital intensity peaks in granule and pellet production, where continuous manufacturing compatibility requires specialized fluid bed and extrusion investments.
- Powder:Direct compression compatibility dominates current volume consumption. United States generic manufacturers specify K-value 25–35 grades for high-speed tablet presses, though flow uniformity limitations constrain continuous line adoption.
- Granules:Flow-optimized formats command premium positioning in continuous manufacturing installations. German pharmaceutical clusters are retrofitting fluid bed granulation capacity to supply these grades for moisture-sensitive active ingredient formulations.
- Pellets:Specialized extrusion-spheronization production serves multiparticulate controlled-release applications.
- Sheets:Niche film-forming grades for transdermal and buccal delivery systems.
Most installed capacity flows through Powder. Expansion is steepest in Granules.
Formulation:
Application complexity determines margin structure, with functional coatings requiring the most extensive technical service support.
- Tablets:Immediate-release and sustained-release oral solid dosage forms absorb the largest copovidone volumes. FDA Current Good Manufacturing Practice enforcement is elevating drug master file documentation requirements for binder suppliers serving United States generic manufacturers.
- Coatings:Functional film barriers for hygroscopic drugs represent the fastest-climbing specification tier. EMA European Pharmacopoeia monograph revisions are tightening impurity limits for these moisture-protective applications.
- Capsules:Hard-shell and soft-gel binding applications with lower technical barriers to entry.
- Solutions:Liquid formulation solubility enhancement for parenteral and ophthalmic delivery.
Tablet formulations anchor procurement volumes. Coating applications are gaining share fastest.
End User:
Regulatory stringency separates customer tiers, with pharmaceutical qualification cycles extending 18–24 months versus cosmetic-grade onboarding.
- Pharmaceuticals:Human medicine applications impose the most rigorous pharmacopoeial compliance burdens. United States and German manufacturing clusters concentrate demand for excipient grades with validated USP-NF and European Pharmacopoeia documentation.
- Cosmetics:Hair fixative and film-forming applications in personal care products.
- Nutraceuticals:Dietary supplement binding with intermediate regulatory oversight.
- Food Industry:Encapsulation and stabilizer applications with FSSAI or FDA food-grade compliance.
Pharmaceuticals command the largest qualified supplier base. Nutraceuticals are expanding most quickly.
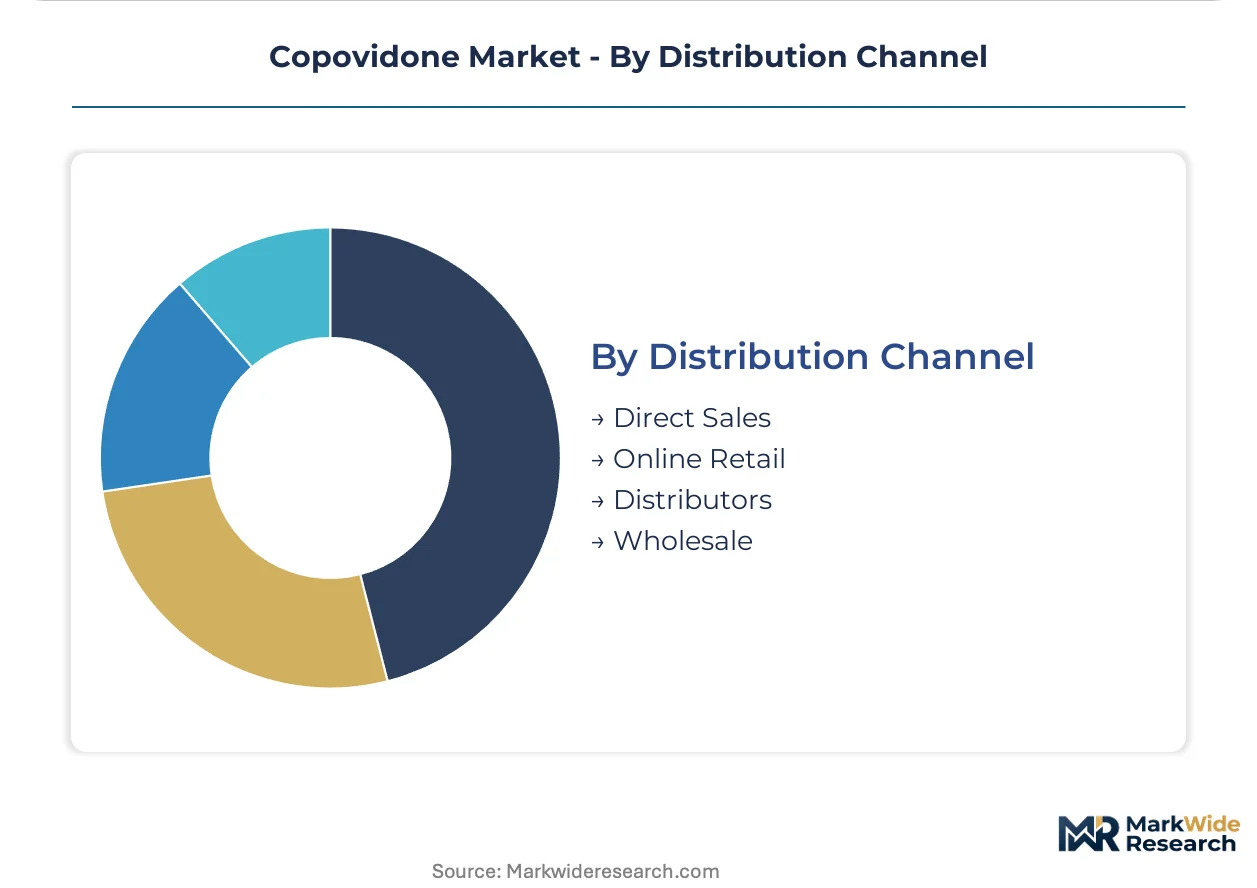
Distribution Channel:
Customer scale dictates channel economics, with direct sales relationships capturing the highest lifetime value accounts.
- Direct Sales:Multi-year supply agreements with integrated technical support dominate large generic manufacturer procurement. Ashland and BASF maintain dedicated account teams for United States tablet producers with annual excipient volumes exceeding contractual thresholds.
- Distributors:Regional chemical distributors serve mid-tier pharmaceutical and nutraceutical compounders with fragmented order patterns.
- Online Retail:Small-scale cosmetic and research-grade purchases through specialized chemical marketplaces.
- Wholesale:Commodity-grade volumes for food industry and industrial applications.
Direct sales relationships capture the highest margin accounts. Distributor channels are expanding fastest in Indian generic manufacturing corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting copovidone procurement toward jurisdictions where excipient documentation costs diverge. Manufacturers migrate qualification investments to markets with streamlined pharmacopoeial alignment.
United States
Generic tablet production clusters in New Jersey and North Carolina drive copovidone specification demand. FDA Current Good Manufacturing Practice enforcement through drug master file requirements elevates supplier onboarding costs for domestic manufacturers. Indianapolis-area pharmaceutical campuses are consolidating binder procurement under multi-year technical service agreements.
Germany
Ludwigshafen and Frankfurt chemical corridors anchor European vinyl pyrrolidone chemistry capacity. EMA European Pharmacopoeia monograph revisions for polyvinylpyrrolidone copolymers impose revalidation deadlines on existing supplier qualifications. Bavarian pharmaceutical manufacturing zones are retrofitting fluid bed granulation lines for continuous processing compatibility.
India
Hyderabad and Ahmedabad generic drug export hubs are scaling excipient qualification pathways aligned with CDSCO and USP-NF standards. Domestic production incentives under PLI scheme provisions reduce import dependency for tablet binder supply. Mumbai-Pune pharmaceutical corridors are attracting copovidone distributors serving mid-tier compounders.
China
Zhejiang and Jiangsu province chemical parks concentrate N-vinyl-2-pyrrolidone monomer production for regional copolymer synthesis. NMPA alignment with ICH Q3D elemental impurity guidelines shapes excipient export documentation for human medicine applications. Shanghai pharmaceutical R&D clusters are qualifying local copovidone grades for multinational generic manufacturer supply.
Switzerland
Basel pharmaceutical innovation centers demand premium-grade copovidone for specialized coating applications. Swissmedic enforcement of European Pharmacopoeia compliance creates qualification barriers for non-European suppliers. Geneva-area clinical trial material manufacturers are specifying validated excipient grades for bioequivalence study formulations.
Copovidone Market Competitive Environment
Capacity expansion dominates the current landscape as incumbent suppliers retrofit fluid bed and spray-drying assets for granule-grade output. The vendor base stratifies between integrated chemical conglomerates with captive monomer supply and specialized excipient houses with dedicated pharmaceutical quality systems. Three archetypes prevail: vinyl pyrrolidone chemistry integrators, pharmaceutical-focused excipient specialists, and regional distributors with qualification documentation capabilities. Competitive intensity concentrates on drug master file completeness and continuous manufacturing technical service depth.
Among integrated chemical producers, Ashland and BASF exemplify the vinyl pyrrolidone chemistry archetype with backward control over N-vinyl-2-pyrrolidone monomer supply. JH Nanhang occupies a position within the Asia-Pacific specialist tier serving export-oriented generic manufacturers. These named entities anchor industry-level commentary on supplier qualification timelines and pharmacopoeial documentation breadth without implying specific strategic actions or market share positions.
| Leading Market Players |
|---|
| Ashland |
| BASF |
| JH Nanhang |
| Resonac Corporation |
| JRS Pharma |
| BOC Sciences |
| Clinivex |
| Glentham Life Sciences |
| BOAI NKY MEDICAL HOLDINGS LTD |
| Others |
Value Chain & Pricing Dynamics
EMA European Pharmacopoeia monograph revisions for polyvinylpyrrolidone copolymers gate qualified supply access and premium-tier pricing power, separating pharmaceutical-grade copovidone suppliers from commodity chemical producers. REACH registration completeness and USP-NF functionality testing documentation determine which manufacturers can command technical service premiums in United States and German tablet manufacturing corridors.
Pricing Analysis
Distributor margins in regional chemical channels compress pricing by 15-25% below direct sales relationships, though multi-year supply agreements with integrated technical support capture the highest lifetime value accounts. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade levels reflects certification burden differentiation, with FDA drug master file alignment commanding substantial premia. Cost compression in standard powder grades is intensifying because hydroxypropyl cellulose substitution threatens wet granulation applications. Mid-tier generic manufacturers exhibit highest price sensitivity, while Swiss and Basel-area innovators prioritize specification consistency over unit cost.
Supply Chain Analysis
Pharmacopoeial certification gating restricts qualified supply to Germany, United States, and select Indian pharmaceutical corridors with validated documentation systems. N-vinyl-2-pyrrolidone monomer production concentrates in Zhejiang and Jiangsu province chemical parks, with vinyl acetate feedstock drawing from regional petrochemical complexes. Single-source vulnerability in N-vinyl-2-pyrrolidone monomer supply creates input cost exposure during cluster disruptions. Distribution runs through direct sales relationships for large generic manufacturers and regional chemical distributors for mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Copovidone functions as a late-cycle quality story where immediate-release and sustained-release tablet demand shifts toward granule-grade specifications with validated continuous manufacturing compatibility. Premium-tier positioning accrues to suppliers with complete pharmacopoeial documentation and fluid bed granulation capacity.
For Market Incumbents: Anchor drug master file completeness against hydroxypropyl cellulose substitution threats by retrofitting fluid bed assets for granule-grade output in German manufacturing zones. Prioritize backward integration into N-vinyl-2-pyrrolidone monomer supply to defend margin position during vinyl acetate feedstock volatility episodes. For New Entrants and Emerging Players: Mid-tier Indian generic manufacturers represent an underserved buyer archetype seeking CDSCO-aligned excipient qualification with domestic production incentives. Penetrate Hyderabad and Ahmedabad export hubs through distributor partnerships offering USP-NF documentation bundles, then scale toward direct technical service relationships as volumes cross contractual thresholds. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with qualification documentation capabilities but limited manufacturing assets. Five-to-ten year viability hinges on pharmacopoeial convergence between FDA and EMA jurisdictions; monitor European Pharmacopoeia monograph revision timelines as inflection indicators for supplier switching cost realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive N-vinyl-2-pyrrolidone production insulates BASF and Ashland from vinyl acetate feedstock volatility in Ludwigshafen corridors. |
| Fluid Bed Granulation Capacity Expansion | Granule-grade output retrofitting captures continuous manufacturing adoption in New Jersey and North Carolina tablet clusters. |
| Drug Master File Alignment Investment | FDA Current Good Manufacturing Practice documentation completeness accelerates supplier onboarding for United States generic manufacturers. |
| CDSCO Qualification Pathway Development | Domestic Indian excipient certification under PLI scheme provisions reduces import dependency for export-oriented tablet producers. |
| Moisture-Sensitive Coating Grade Development | Functional film barrier specialization serves hygroscopic active pharmaceutical ingredient formulations in Swiss-controlled release segments. |
Study Parameters
Bottom-up tablet formulation modeling reconciled against top-down vinyl pyrrolidone chemistry capacity tracking forms the analytical core of this study. Primary interviews with pharmaceutical formulation scientists, generic manufacturing procurement directors, excipient regulatory affairs specialists, and continuous manufacturing equipment engineers combined with secondary validation from FDA drug master file databases, EMA European Pharmacopoeia monograph revisions, USP-NF functionality testing standards, and REACH registration disclosures. Triangulation between demand-side prescription volume projections and supply-side polymerization capacity announcements ensures segmentation consistency.
Input-output matrices map N-vinyl-2-pyrrolidone monomer availability through copolymer synthesis, grade differentiation, and end-use qualification across product type, formulation, and end user dimensions. CAGRs derive from regression analysis of historical pharmaceutical excipient consumption against generic drug approval volumes and continuous manufacturing adoption curves. Forecast inputs incorporate regulatory documentation burden indices and pharmacopoeial harmonization probability assessments across the analysis window.
Inputs from FDA drug master file disclosures and EMA qualification databases were available through the study window; gaps in private-label excipient functionality testing records introduce uncertainty bands around granule-grade adoption timelines. Forecasts reflect assumptions regarding pharmacopoeial convergence and continuous manufacturing penetration without guaranteed regulatory alignment. A model refresh is warranted upon material change in European Pharmacopoeia monograph implementation schedules or vinyl acetate feedstock supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Hydroxyproline Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
Magnesium Chelates Market
Specialty Chemicals
Brominated Flame Retardants Market
Specialty Chemicals
Silicone Oil Market
Specialty Chemicals
North America Aerosol Cans Market
Specialty Chemicals
Spiroglycol Market
Specialty Chemicals
Free-From Titanium Dioxide Market
Specialty Chemicals
Biocides for Leather Market
Specialty Chemicals
Diisononyl Adipate (DINA) Market
Specialty Chemicals
Acrylic Powder Market
Specialty Chemicals
Silver Sulfate Market
Specialty Chemicals
Asia Pacific Methyl Glucose Market
Specialty Chemicals
Bond Breaker Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
Phenylbenzimidazole Sulfonic Acid Market