
 US Smart Building Market | 2026-2036
US Smart Building Market Size, Share, and Industry Trends Forecast 2026-2036
US Smart Building Market Insights
Platform licensing revenue is reshaping competitive economics in the US Smart Building Market as vendors migrate from hardware margins to recurring software income. Johnson Controls leverages its extensive installed base of HVAC equipment to anchor long-term service contracts. Schneider Electric SE differentiates through integrated energy management platforms that span multiple building systems. Honeywell International Inc. dominates fire safety and security integration, extending its footprint into unified building operating systems.
A smart building integrates IoT sensors, building automation systems, and energy management software to monitor and control mechanical, electrical, and plumbing infrastructure in real time, typically operating through IP-based networks with edge computing capabilities that process data locally before cloud transmission. The primary purpose is reducing operational expenditure while maintaining occupant productivity and safety. IoT Sensors and Building Automation represent the most mature technology segments with established margin pools, while Energy Management Systems capture the fastest expansion as carbon accounting requirements tighten. Commercial Properties anchor end-user demand, though Healthcare Facilities are emerging as a high-growth vertical due to stringent indoor air quality mandates and 24/7 operational reliability requirements.
The US Department of Energy enforces building energy codes that directly shape product specifications and retrofit timelines for smart building vendors. The Inflation Reduction Act directs federal tax incentives toward energy efficiency upgrades, creating compliant demand pathways for integrated platform providers. OSHA indoor air quality guidelines and emerging SEC climate disclosure rules for commercial real estate portfolios add compliance layers that favor automated environmental monitoring systems. Stakeholders must weigh capital allocation between greenfield smart building construction and brownfield retrofit opportunities as regulatory thresholds tighten.
Market Dynamics
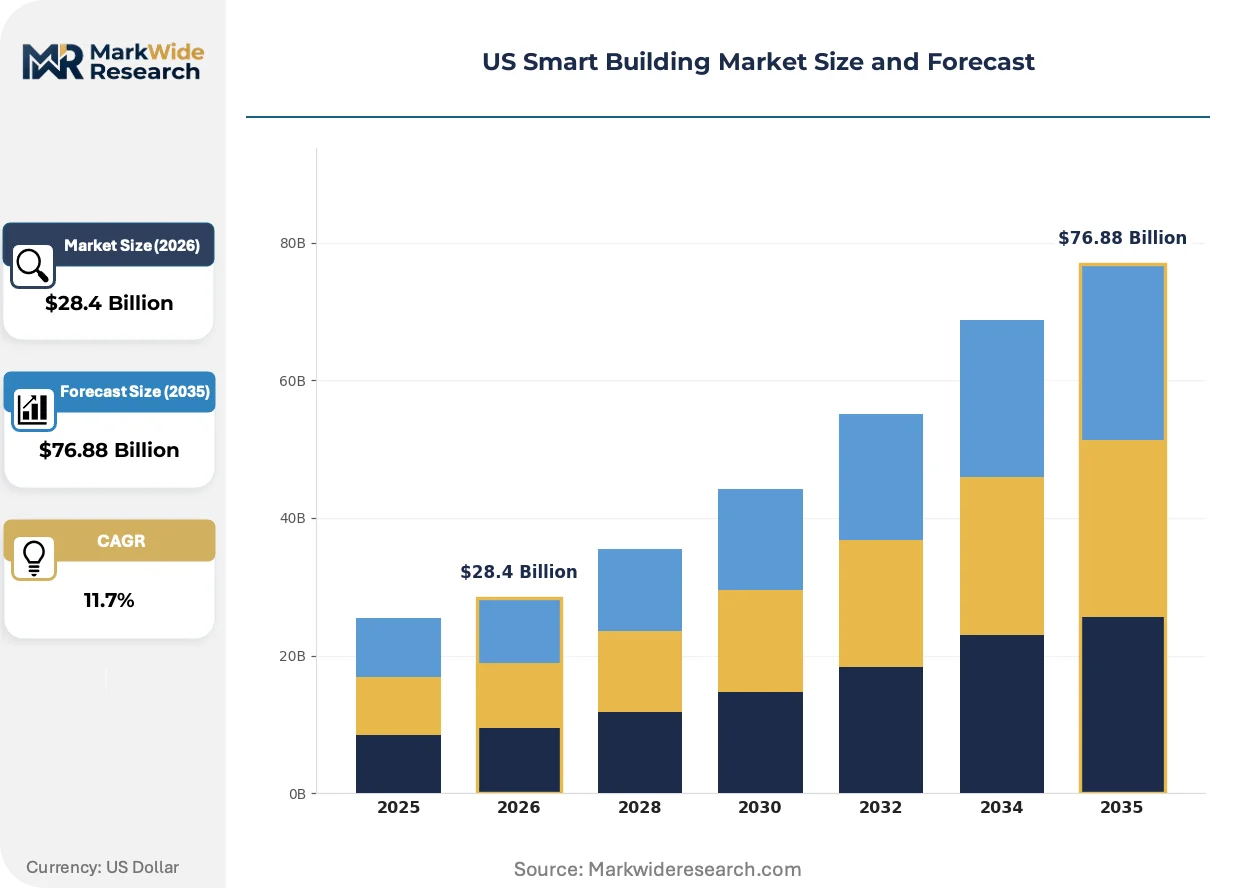
The Inflation Reduction Act's tax incentive architecture is compressing payback periods for building automation retrofits, redirecting capital flows from new construction toward brownfield modernization across US commercial property portfolios.
Growth Catalysts
- IRA Energy Efficiency Tax Credits:Federal incentives covering up to 30% of qualified smart building upgrade costs are unlocking multi-year retrofit pipelines in Class A office and healthcare facilities.
- Healthcare Indoor Air Quality Mandates:Joint Commission accreditation standards and OSHA ventilation guidelines are compelling hospitals to deploy continuous environmental monitoring with automated HVAC response.
- Edge Computing Architectures:On-premise data processing at the building level is reducing latency for critical safety systems while lowering recurring cloud connectivity costs.
Market Restraints
- Semiconductor Supply Concentration:Protracted lead times for industrial-grade sensors and controllers from concentrated Asian foundries are extending project timelines and inflating equipment costs.
- Interoperability Protocol Fragmentation:Competing communication standards between BACnet, Modbus, and proprietary vendor ecosystems are forcing costly middleware investments.
- Skilled Technician Scarcity:Shortages of certified building automation specialists are constraining deployment velocity and inflating implementation labor rates.
Strategic Opportunities
- SEC Climate Disclosure Rules:Mandatory emissions reporting for commercial real estate investment trusts is creating compliant demand for automated carbon accounting and energy benchmarking platforms.
- Texas and Florida Sun Belt Expansion:Rapid commercial construction in Dallas-Fort Worth, Houston, and Miami metro corridors offers greenfield smart building penetration without legacy system constraints.
- Digital Twin Convergence:Integration of 3D building information modeling with real-time IoT data streams is enabling predictive maintenance contracts with multi-year recurring revenue structures.
Industry Challenges
- Cybersecurity Certification Burden:NIST cybersecurity framework compliance and emerging FDA guidance for connected healthcare facilities are extending vendor qualification timelines.
- Legacy BAS Integration Complexity:Pneumatic control systems and 20-year-old proprietary networks in aging commercial stock require expensive gateway hardware and custom protocol translation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Smart Building Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $76.88 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Sensors, Energy Management Systems, Building Automation, HVAC Controls End User: Commercial Properties, Residential Buildings, Educational Institutions, Healthcare Facilities Application: Security Management, Energy Efficiency, Environmental Monitoring, Occupant Comfort Solution: Integrated Platforms, Smart Lighting, Asset Management, User Interfaces |
| Companies Covered | Siemens AG, IBM Corporation, Honeywell International Inc., Jacobs Solutions Inc., Delta Electronics, Inc., Johnson Controls, ABB Ltd., AECOM, Schneider Electric SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Smart Building Market Trends and Innovations
Platform unification and AI-driven optimization are compressing vendor margins while elevating software recurring revenue as the dominant profit pool in US smart building deployments.
AI-powered fault detection and diagnostics is rendering obsolete rule-based building management systems that rely on static setpoints and scheduled maintenance intervals. Large commercial real estate investment trusts are deploying machine learning platforms across portfolios exceeding 50 million square feet within 18-month rollout cycles. This capability shift is compressing vendor differentiation around hardware specifications while elevating predictive algorithm performance as the primary procurement criterion.
OSHA's updated indoor air quality ventilation guidelines are mandating continuous monitoring and automated response capabilities in commercial and institutional buildings. The standard requires real-time tracking of carbon dioxide, particulate matter, and humidity with documented corrective action protocols. Healthcare facilities and K-12 school districts in California, New York, and Illinois are accelerating compliance-driven procurement of integrated environmental management platforms.
Building owners are unbundling long-term service contracts from initial equipment procurement, compressing vendor lock-in and elevating third-party systems integrator influence. Traditional single-source vendor relationships are fragmenting into multi-vendor technology stacks managed by independent facility management firms. This pattern is most visible in Class B and C office properties in secondary Midwest and Southeast markets where capital constraints favor best-of-breed component selection over integrated platform premiums.
US Smart Building Market Segmentation
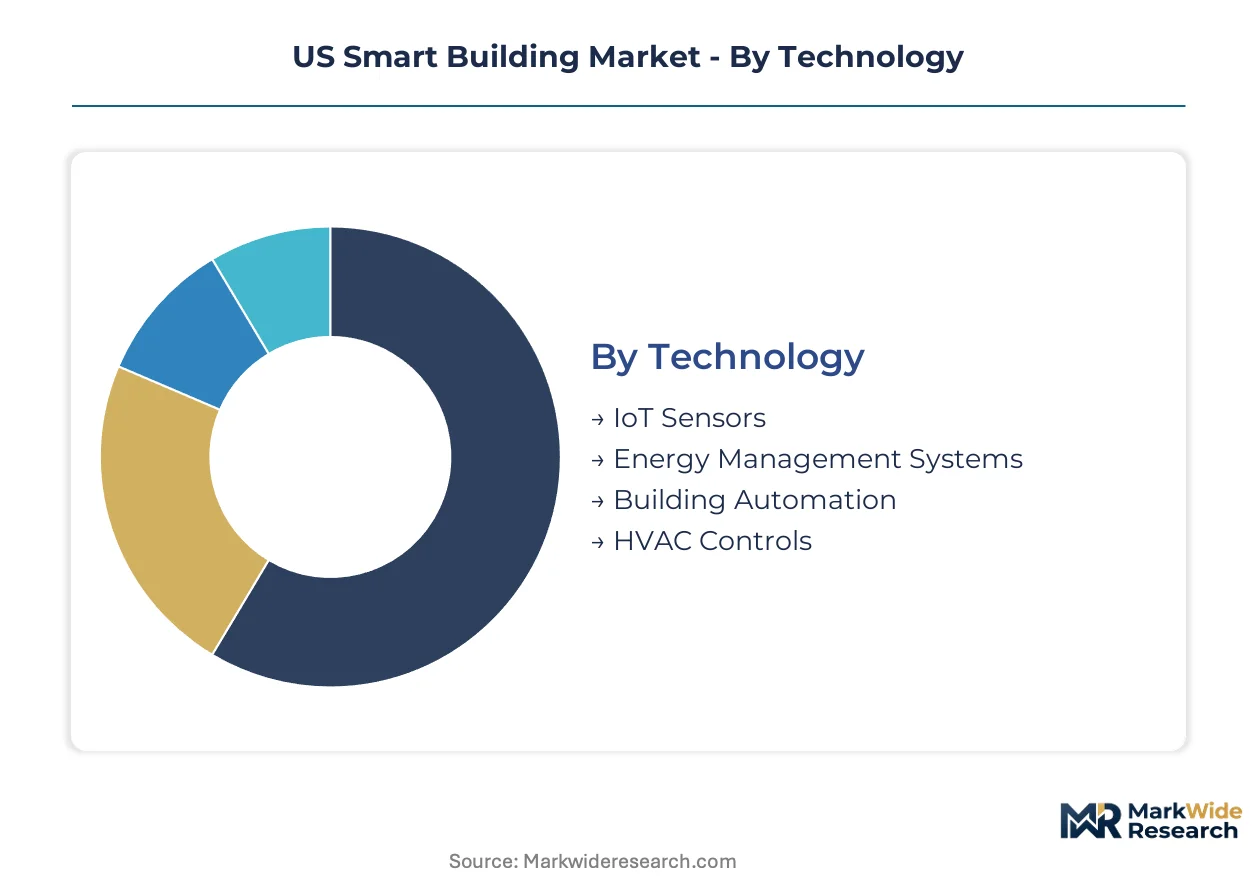
Technology deployment cycles vary sharply across the US Smart Building Market, with some segments requiring decade-long capital planning while others refresh on 3-5 year software cadences. Understanding these velocity mismatches is critical for vendor resource allocation and buyer procurement timing.
Technology:
Replacement cycles stretch from 15-year HVAC hardware rotations to 18-month sensor firmware upgrades, creating divergent revenue recognition patterns across vendor portfolios.
- IoT Sensors:These devices capture environmental, occupancy, and equipment performance data through wireless mesh networks or Power over Ethernet connections. Demand clusters in California healthcare facilities and Class A office towers where OSHA ventilation mandates and LEED certification requirements drive continuous monitoring investments.
- Energy Management Systems:Software platforms that aggregate utility consumption data, benchmark performance against baselines, and automate demand response protocols. Deployment concentrates in Texas and Florida commercial corridors where new construction bypasses legacy integration burdens and IRA tax incentives accelerate payback calculations.
- Building Automation:Centralized control systems coordinating HVAC, lighting, and security through unified programming interfaces. These systems anchor long-term service relationships in aging Midwest commercial stock where pneumatic-to-digital retrofits extend project timelines.
- HVAC Controls:Zone-level temperature and airflow management devices ranging from programmable thermostats to variable air volume terminals. Johnson Controls and Carrier leverage extensive installed bases to defend replacement cycles against integrated platform competitors.
Building Automation dominates installed base. Energy Management Systems is where expansion concentrates.
End User:
Capital availability and regulatory exposure create tiered adoption velocities, with federally subsidized healthcare and tax-incentivized commercial properties outpacing budget-constrained residential and educational segments.
- Commercial Properties:Office towers, retail centers, and mixed-use developments exceeding 100,000 square feet. SEC climate disclosure rules for real estate investment trusts are mandating automated carbon accounting across portfolios in Los Angeles, San Francisco, and Manhattan.
- Healthcare Facilities:Hospitals, outpatient clinics, and long-term care centers with 24/7 operational requirements. Joint Commission accreditation standards and FDA guidance on connected medical devices are compelling continuous environmental monitoring with automated HVAC response capabilities.
- Educational Institutions:K-12 districts and university campuses managing deferred maintenance backlogs. Federal ESSER funding expiration is compressing procurement timelines for indoor air quality upgrades in Illinois and New York school systems.
- Residential Buildings:Multifamily apartments and condominiums with fragmented ownership structures. Smart home platform competition from Amazon and Google is constraining professional building automation penetration in this price-sensitive segment.
Commercial Properties anchor vendor revenue stability. Healthcare Facilities is climbing the fastest as regulatory compliance hardens.
Application:
Functional priorities shift with building lifecycle stage—security and comfort dominate tenant experience discussions while energy and environmental monitoring absorb capital allocation in retrofit scenarios.
- Security Management:Access control, video surveillance, and intrusion detection systems integrated through IP-based networks. Honeywell and LenelS2 defend strong positions in federal government and critical infrastructure facilities with cybersecurity certification requirements.
- Energy Efficiency:Load scheduling, demand response, and renewable energy integration optimizing utility expenditure. IRA tax credits covering 30% of qualified upgrade costs are unlocking multi-year retrofit pipelines in Class A office properties.
- Environmental Monitoring:Continuous tracking of carbon dioxide, particulate matter, temperature, and humidity with documented corrective action protocols. OSHA's updated ventilation guidelines are accelerating compliance-driven procurement in California and New York healthcare and educational facilities.
- Occupant Comfort:Personal environmental control, wayfinding, and space reservation systems enhancing tenant experience. These applications face budget pressure in hybrid work environments where office utilization rates remain depressed.
Security Management holds the deepest incumbent relationships. Environmental Monitoring is gaining share fastest from regulatory tailwinds.
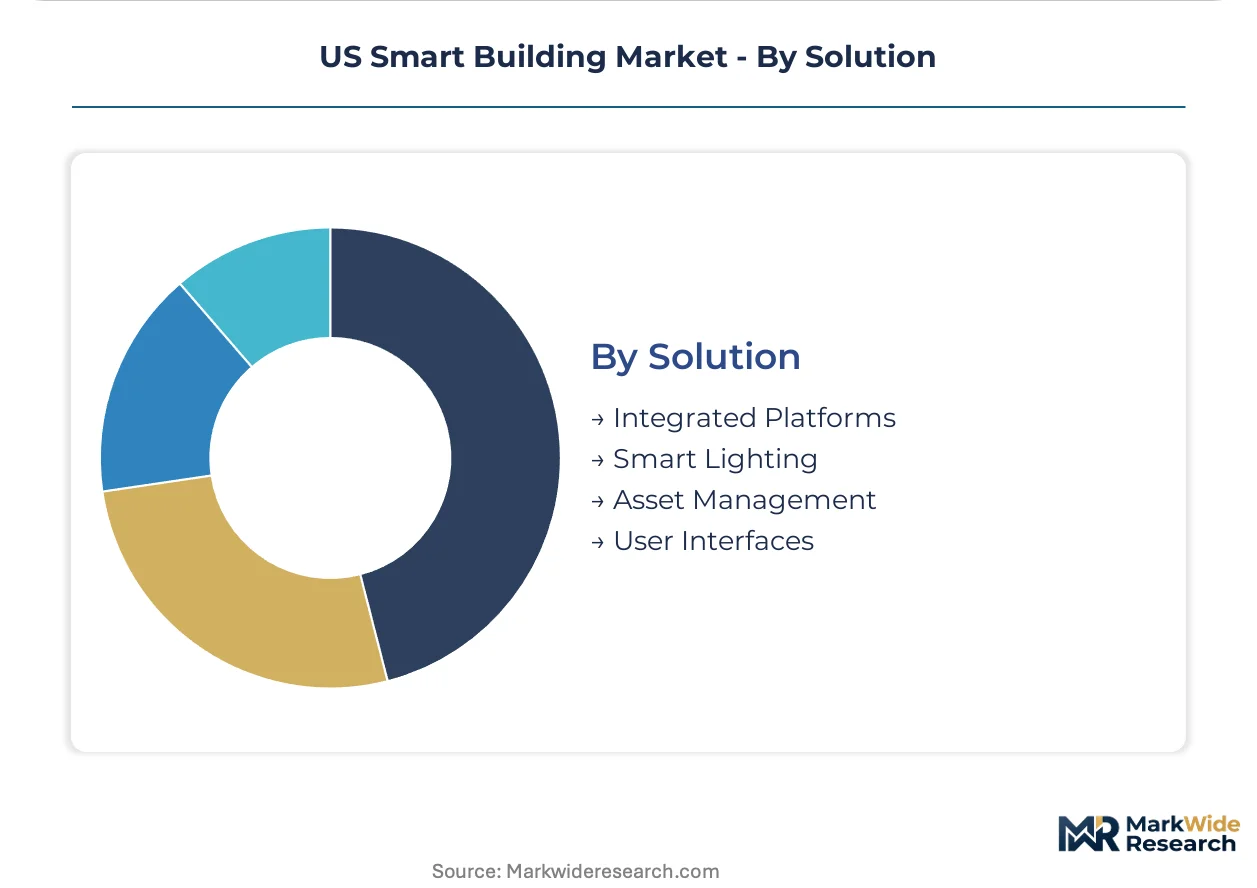
Solution:
Procurement unbundling is fragmenting what were historically single-vendor relationships, elevating systems integrator influence over component selection in cost-constrained deployments.
- Integrated Platforms:Unified software environments spanning multiple building systems through open APIs and normalized data models. Schneider Electric and Siemens compete on energy management integration while Johnson Controls emphasizes HVAC-centric unification.
- Smart Lighting:LED fixtures with embedded sensors and network connectivity enabling occupancy-based dimming and daylight harvesting. Rapid payback periods from energy savings are sustaining replacement demand despite construction cycle softness.
- Asset Management:Digital twin and predictive maintenance platforms extending equipment lifecycle through condition-based intervention. These solutions face sales cycle elongation as facilities teams weigh SaaS subscription costs against deferred capital expenditure.
- User Interfaces:Mobile applications, kiosk displays, and voice-activated controls enabling occupant interaction with building systems. Tenant experience differentiation is compressing margins as these capabilities become table stakes in Class A properties.
Integrated Platforms command the highest contract values. Smart Lighting is expanding most quickly through standalone retrofit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across US metropolitan corridors, with Sun Belt developers prioritizing first-cost optimization while coastal gateway cities absorb premium pricing for compliance-grade environmental monitoring systems.
California
Los Angeles and San Francisco commercial towers drive demand for integrated environmental platforms that satisfy CALGreen Tier 1 and Tier 2 standards. The California Energy Commission enforces Title 24 building efficiency codes that mandate automated daylight harvesting and demand-responsive controls in new construction over 10,000 square feet. San Jose and San Diego healthcare clusters are deploying continuous air quality monitoring to meet Joint Commission ventilation requirements ahead of accreditation cycles.
Texas
Dallas-Fort Worth and Houston metro areas anchor greenfield smart building deployment without legacy BAS integration burdens. ERCOT grid instability has amplified demand for automated demand response and battery-integrated microgrids in Class A office developments. Austin's technology corridor is attracting headquarters relocations that specify WELL Building Standard certification requiring sensor-dense indoor environmental quality systems.
New York Metro
Manhattan and Brooklyn commercial portfolios face Local Law 97 carbon emissions caps that activate in 2024 with escalating penalties through 2030. The New York City Department of Buildings requires automated energy benchmarking and retro-commissioning for buildings exceeding 25,000 square feet. Hudson Yards and Long Island City developments are specifying unified building operating platforms that consolidate HVAC, lighting, and access control through single-pane dashboards.
Illinois
Chicago's aging commercial stock dominates brownfield retrofit activity as property owners respond to Commonwealth Edison utility incentives and City of Chicago energy benchmarking ordinances. The Illinois Commerce Commission oversees demand response programs that reward automated load curtailment during peak pricing events. O'Hare corridor logistics facilities and downtown Loop office towers represent contrasting deployment profiles—greenfield spec buildings versus 1980s-era pneumatic system replacements.
Florida
Miami and Tampa commercial construction is accelerating without the retrofit constraints binding Northeast and Midwest markets. The Florida Building Commission adopted the 2021 International Energy Conservation Code with amendments that preserve local flexibility for HVAC efficiency thresholds. Miami-Dade County's hurricane-resistant construction standards are driving specification of hardened building automation networks with redundant edge computing nodes for post-storm operational continuity.
US Smart Building Market Competitive Landscape
Capability concentration sits with integrated platform specialists commanding multi-system unification expertise; scale advantage sits with established controls manufacturers leveraging century-old installed bases. The market structures around three tiers: diversified industrial conglomerates with building technology divisions, pure-play building automation specialists, and emerging software-native entrants attacking vertical applications. Dominant competitive moves include portfolio unification through middleware acquisitions and service contract extension through predictive maintenance algorithm deployment.
Within the diversified industrial tier, Siemens AG and ABB Ltd. represent European-origin conglomerates with building technology divisions that compete on energy management integration across power distribution and automation portfolios. Johnson Controls exemplifies the installed-base defender archetype, converting legacy HVAC equipment relationships into long-term service contracts. Honeywell International Inc. anchors the safety-and-security integration position, extending fire and access control dominance into unified building operating systems.
| Leading Market Players |
|---|
| Siemens AG |
| IBM Corporation |
| Honeywell International Inc. |
| Jacobs Solutions Inc. |
| Delta Electronics, Inc. |
| Johnson Controls |
| ABB Ltd. |
| AECOM |
| Schneider Electric SE |
| Others |
Pricing and Supply Chain Analysis
Tariff exposure on Taiwanese semiconductor foundries is compressing hardware margins while elevating recurring software revenue as the primary profit pool, forcing vendors to restructure supply chains around domestic EMS partners and nearshore component sourcing. This structural cost pressure widens spreads between premium integrated platforms and economy-tier point solutions while accelerating the shift toward subscription-based service contracts.
Pricing Analysis
After-sales service revenue from predictive maintenance contracts and extended warranty tiers now drives lifetime value for smart building vendors, displacing upfront equipment margins. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation in cybersecurity certification grade and integration complexity rather than hardware specifications alone. Cost compression in the economy tier is intensifying because commodity sensor manufacturers from Shenzhen are flooding the market with uncertified alternatives. Class B and C office properties in secondary Midwest markets exhibit highest price sensitivity, while healthcare facilities in California absorb premium pricing for Joint Commission-compliant environmental monitoring systems.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn, Jabil, and Flex holding dominant capacity for industrial IoT gateway assembly and edge computing node production. Taiwan and South Korea anchor semiconductor supply for sensor microcontrollers and wireless communication chipsets, while Mexico and Vietnam are absorbing final assembly migration to mitigate tariff exposure. Raw material dependencies center on rare earth elements for magnetic components in HVAC actuators, lithium-ion cells for backup power systems, and copper wiring for PoE sensor networks. Single-source vulnerability in advanced node chip fabrication at TSMC represents the critical structural risk. Distribution runs through authorized systems integrator networks and direct OEM relationships with national facility management firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Smart Building Market functions as a defensive-moat story where regulatory entrenchment creates durable switching costs. Compliance mandates from OSHA, SEC, and Joint Commission accreditation standards embed incumbent platforms deeply into buyer operations.
For Market Incumbents: Harden defensive positioning by deepening backward integration into domestic semiconductor packaging capacity to insulate against tariff volatility on Asian foundry output. Extend service contract duration through AI-powered predictive maintenance algorithm deployment that increases replacement part attach rates. Certification investment in NIST cybersecurity framework compliance creates additional barriers against software-native entrants attacking healthcare verticals.
For New Entrants and Emerging Players: Texas and Florida Sun Belt corridors offer the most penetrable geography where greenfield construction bypasses legacy BAS integration burdens and IRA tax incentives accelerate procurement timelines. Target Class A office developments in Dallas-Fort Worth and Miami where WELL Building Standard certification requirements favor sensor-dense environmental quality systems. A go-to-market angle through independent facility management firms as trusted systems integrator partners bypasses direct competition with entrenched OEM relationships.
For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors software-native specialists with proven AI fault-detection algorithms over hardware-centric incumbents. Long-term viability over the next decade hinges on recurring revenue ratio and vertical integration depth into edge computing hardware. Acquisition target archetypes include predictive maintenance software platforms with healthcare facility deployment footprints. The signal to watch is SEC climate disclosure rule enforcement intensity for commercial real estate investment trusts as demand inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Unification Acquisition | Consolidates middleware capabilities to reduce BACnet-Modbus interoperability friction for healthcare clients. |
| Predictive Maintenance Algorithm Deployment | Extends service contract duration through condition-based HVAC intervention at Joint Commission-accredited hospitals. |
| Domestic EMS Partnership | Insulates margin structure from tariff exposure on Taiwanese semiconductor foundry output. |
| Cybersecurity Certification Investment | Accelerates vendor qualification timelines under NIST framework for connected healthcare facilities. |
| Sun Belt Geographic Expansion | Captures greenfield construction demand in Dallas-Fort Worth without legacy pneumatic system replacement burdens. |
Research Methodology
The analysis maps building automation systems, energy management platforms, IoT sensor networks, and HVAC control segments, each validated through facilities directors, building automation specialists, healthcare compliance officers, and commercial real estate portfolio managers. Primary interviews with systems integrators and OEM service contract managers combined with secondary validation against SEC climate disclosure filings, OSHA ventilation guideline updates, Department of Energy building code databases, and IRA tax incentive program documentation. Bottom-up deployment volume estimates triangulated against top-down commercial construction spending data.
Assumptions held fixed include IRA tax credit extension timelines and OSHA indoor air quality enforcement intensity, while variables tested encompass semiconductor supply chain disruption duration and Sun Belt commercial construction velocity. Segmentation dimensions modeled span technology maturity tier, end-user regulatory exposure level, application functional priority, and solution bundling architecture across the projection horizon. CAGRs derived from deployment pipeline analysis weighted by incentive program eligibility and retrofit payback period calculations. Industry-specific forecast inputs include Joint Commission accreditation cycle timing and ERCOT grid instability frequency.
The forecast holds incumbent behavior within observed patterns; aggressive platform unification moves by diversified industrial conglomerates or software-native vertical specialists would shift outcomes beyond modeled ranges. Specific risk factors encompass semiconductor supply concentration disruption and cybersecurity framework compliance timeline extension. Cross-checking against McGraw Hill Construction Dodge project starts data and CoStar commercial property transaction volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Infrastructure
Smart Pipeline Networks Market
Smart Infrastructure
Infrastructure Solution Integration Service Market
Smart Infrastructure
Smart Airport Construction Market
Smart Infrastructure
Asia-Pacific Smart Building Market
Smart Infrastructure
Smart Infrastructure Market
Smart Infrastructure
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market
Smart Infrastructure
Global IoT in Construction Market
Smart Infrastructure
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market
Smart Infrastructure
Big Data in Construction Market
Smart Infrastructure
IoT in Commercial Construction Market
Smart Infrastructure
Construction 4.0 Market
Smart Infrastructure
Smart Hydrants Market
Smart Infrastructure
Smart Concrete Market