
 Asia-Pacific Smart Building Market | 2026-2036
Asia-Pacific Smart Building Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Smart Building Market Insights
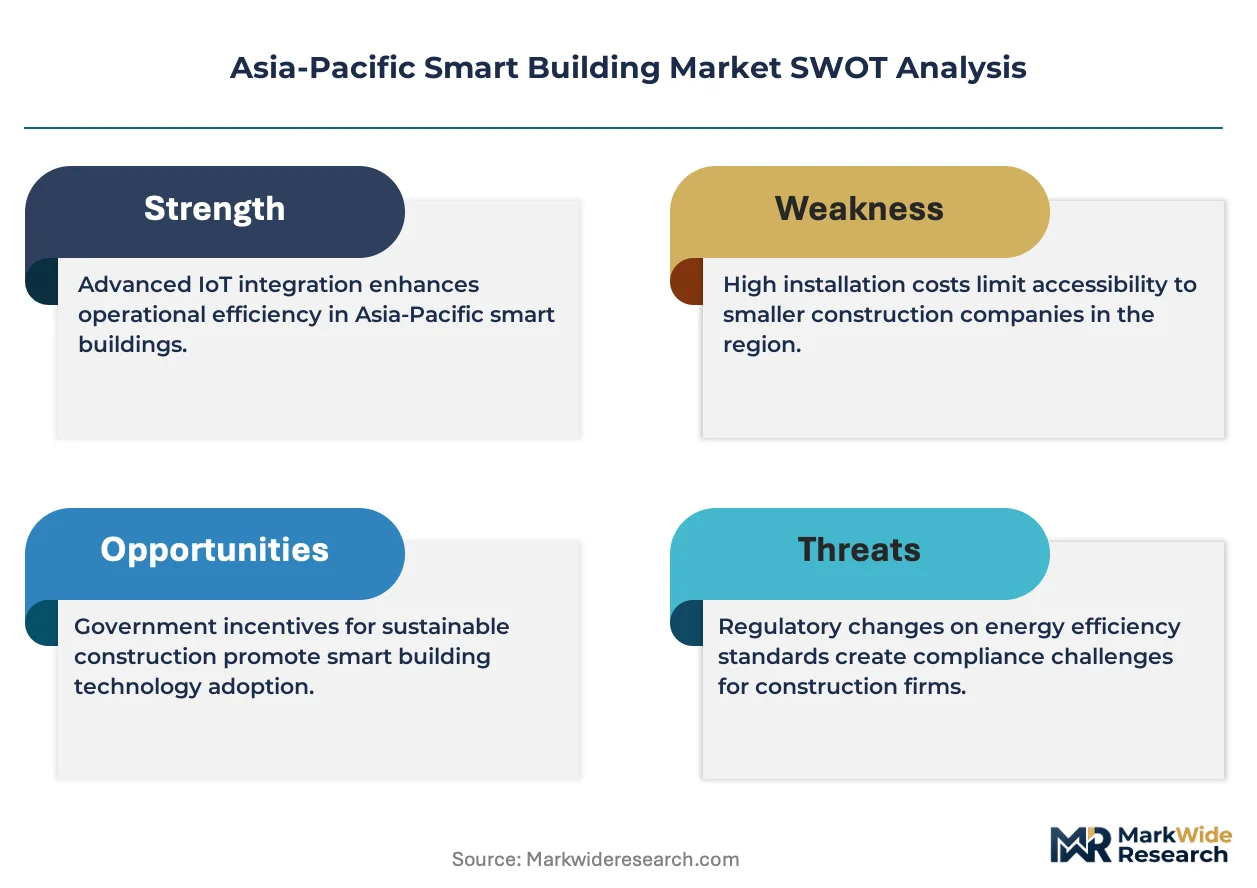
Green leasing and performance-linked project finance are reshaping competitive entry in the Asia-Pacific smart building sector. ABB leverages its electrification portfolio to anchor large-scale commercial retrofits across Singapore and Sydney. Huawei Technologies competes through integrated IoT-to-cloud stacks that dominate data-intensive verticals in Chinese smart city deployments. Johnson Controls sustains its position via deep controls expertise and long-term facility management contracts with premium-grade property developers.
Smart buildings integrate sensor networks, automation controllers, and digital twin software to monitor and optimize energy consumption, occupancy patterns, and environmental conditions in real time. The primary purpose centers on reducing operational expenditure while meeting tightening carbon accountability thresholds for commercial and institutional asset owners. Building Management Systems currently occupy the largest installed base, though Security Systems represents the fastest-expanding technology segment as biometric and AI-driven surveillance penetration deepens across retail and industrial applications. Facility Managers constitute the most concentrated end-user revenue pool, while Property Developers are shifting procurement toward full-lifecycle service contracts that bundle Consulting with Integration and Maintenance.
China's MEE enforces dual carbon compliance timelines that mandate real-time energy disclosure for public buildings above specified floor areas. Japan's METI coordinates with JIS standards bodies to upgrade building energy codes, while India's BIS develops IoT interoperability frameworks for smart infrastructure procurement. These regulatory layers determine product certification pathways and shape vendor qualification criteria for government-linked tenders. Stakeholders must track which standardization regime gains cross-border recognition first, as this will determine where platform investments achieve scale without redundant compliance costs.
Market Dynamics
China's dual carbon mandates from MEE and Japan's METI building efficiency directives are compressing compliance timelines, forcing asset owners to accelerate platform procurement ahead of regulatory deadlines rather than follow traditional replacement cycles.
Growth Catalysts
- Dual Carbon Enforcement:China's MEE mandates real-time energy disclosure for public buildings above specified floor areas, creating immediate retrofit demand across municipal portfolios in tier-one cities.
- Smart City Budget Expansion:India's tier-one metro corridors are channeling central government allocations into integrated building automation, with Facility Managers gaining procurement authority over standalone BMS upgrades.
- Biometric Surveillance Penetration:Security Systems are expanding fastest as retail and industrial applications deploy AI-driven access control, displacing legacy card-based systems across Southeast Asian commercial developments.
Market Restraints
- IoT Interoperability Fragmentation:India's BIS frameworks remain incomplete, forcing vendors to maintain multiple protocol stacks and raising integration costs for cross-border projects.
- Semiconductor Supply Concentration:Automation controller production depends on concentrated East Asian foundry capacity, exposing lead time volatility for Building Management Systems deployments.
- Technical Debt in Legacy Assets:Pre-2010 commercial stock in Australia and Japan lacks structured cabling infrastructure, requiring costly rip-and-replace versus overlay sensor deployments.
Strategic Opportunities
- Tier-Two India Penetration:Underpenetrated smart city budgets in Ahmedabad and Pune offer first-mover positioning before BIS standards harden procurement specifications.
- Digital Twin Convergence:Integration of BIM models with live sensor streams enables predictive maintenance contracts, shifting vendor revenue from hardware to recurring software services.
- Green Leasing Tailwinds:Performance-linked project finance in Singapore and Sydney rewards developers who bundle energy accountability into tenant agreements, creating premium pricing power.
Industry Challenges
- Controls Engineering Talent Scarcity:Facility Managers face acute shortages of technicians certified across multiple BMS protocols, delaying commissioning timelines and escalating service costs.
- Multi-Standard Certification Burden:Vendors must simultaneously satisfy China's GB standards, Japan's JIS codes, and India's emerging BIS frameworks, fragmenting R&D resources and extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Smart Building Market |
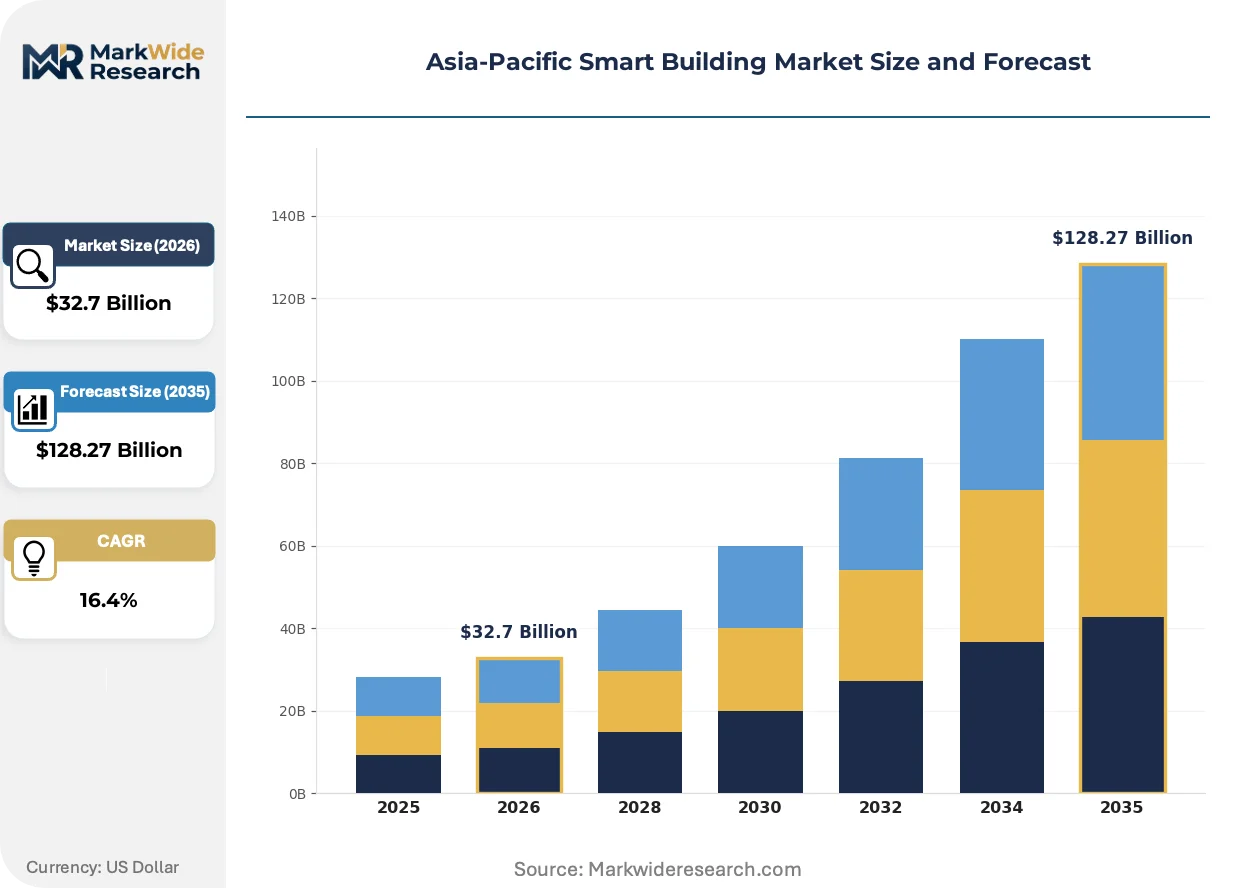
| Market Size in 2026 | $32.7 Billion |
| Market Size in 2035 | $128.27 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, Automation Systems, Building Management Systems, Security Systems Application: Residential, Commercial, Industrial, Retail End User: Property Developers, Facility Managers, Homeowners, Tenants Service Type: Consulting, Integration, Maintenance, Support |
| Companies Covered | Honeywell International, ABB, Huawei Technologies, Cisco Systems, Schneider Electric, Hitachi, Johnson Controls, IBM Corporation, Siemens, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Smart Building Market Trends and Innovations
Building automation architectures are decoupling from proprietary hardware stacks, enabling software-defined control layers that compress upgrade cycles and shift competitive advantage toward data analytics capabilities.
Digital twin platforms are migrating from static BIM repositories to live operational systems that ingest real-time occupancy and energy data. Premium-grade property developers in Singapore and Sydney are deploying these tools to optimize HVAC sequencing. This migration from design-phase documentation to operational intelligence is compressing the traditional handover gap between construction teams and Facility Managers.
Japan's METI coordination with JIS standards bodies is upgrading building energy codes to mandate automated demand response for commercial assets above threshold consumption levels. Industrial facilities face the steepest compliance curves, with automotive and electronics manufacturing plants accelerating controller procurement. Chinese vendors are responding with pre-certified product bundles that reduce JIS testing timelines for domestic system integrators.
Property Developers are unbundling long-term facility management contracts from initial construction procurement, creating discrete revenue pools for controls specialists. Full-lifecycle service agreements that bundle Consulting with Integration and Maintenance are displacing transactional hardware sales in India's tier-one corridors. This restructuring is most visible in Mumbai and Bangalore, where REITs now require ten-year performance guarantees as a condition of vendor qualification.
Asia-Pacific Smart Building Market Segmentation
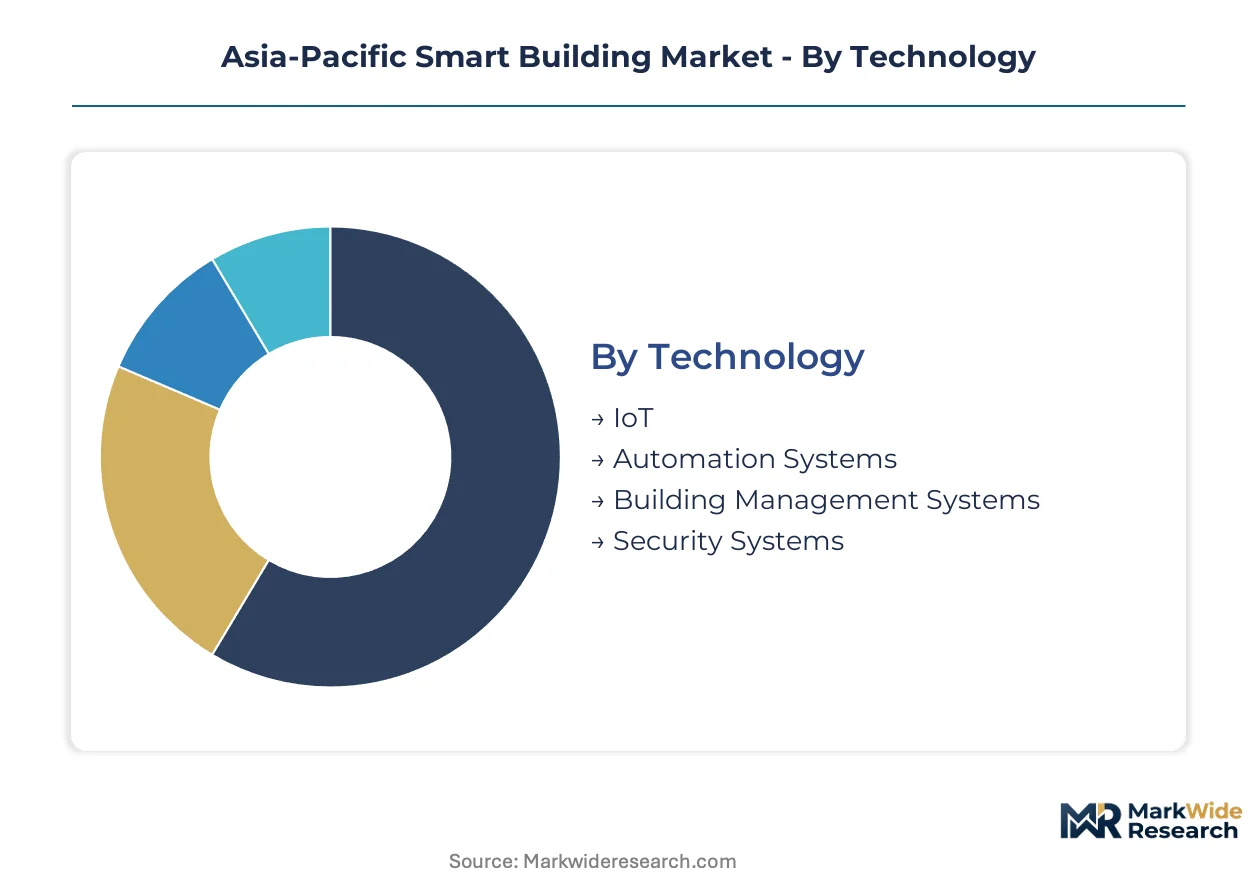
Smart building procurement across the Asia-Pacific region fragments across technology maturity, asset class requirements, and service lifecycle stages. Buyers in Singapore and Sydney prioritize full-stack integration, while tier-one Indian metros concentrate demand in discrete automation modules. Understanding these segment boundaries clarifies where vendor specialization yields pricing power versus where bundling captures recurring revenue.
Technology:
The use-case spectrum spans passive monitoring infrastructure through autonomous building orchestration, with each layer demanding distinct integration depth and data governance frameworks.
- Building Management Systems:Centralized control platforms managing HVAC, lighting, and energy distribution through programmable logic controllers. Facility Managers in China's tier-one cities deploy these most intensively as MEE mandates compress compliance timelines for public building portfolios.
- Security Systems:Biometric access control, AI-driven surveillance, and perimeter monitoring networks. Retail developments across Southeast Asia are displacing legacy card-based infrastructure fastest as tenant safety specifications tighten.
- IoT:Distributed sensor networks capturing occupancy, air quality, and equipment performance telemetry. Indian smart city tenders specify these for environmental monitoring in municipal buildings.
- Automation Systems:Rule-based controllers executing predefined responses to sensor triggers. Industrial facilities in Japan adopt these for METI-mandated demand response compliance.
The dominant share belongs to Building Management Systems, while Security Systems is closing the gap fastest.
Application:
Cost tier stratification separates premium-grade new construction from retrofit-constrained existing stock, with each application imposing distinct technical debt burdens on system design.
- Commercial:Office towers and mixed-use developments requiring integrated tenant experience platforms. Singapore REITs bundle ten-year performance guarantees into procurement specifications, forcing vendors toward full-lifecycle service models.
- Industrial:Manufacturing plants and logistics facilities with high-energy process loads. Japanese automotive and electronics producers face steepest METI compliance curves for automated demand response.
- Retail:Shopping centers and flagship stores deploying biometric surveillance and footfall analytics. Southeast Asian developers prioritize security integration over energy optimization in this segment.
- Residential:High-rise apartments and gated communities with home automation features. India's tier-one metros see concentrated developer investment in premium residential automation.
Commercial assets command the largest installed base, though Industrial applications are expanding most quickly under regulatory pressure.
End User:
Customer type determines contract structure complexity, from transactional hardware sales to multi-decade facility management partnerships with embedded performance accountability.
- Facility Managers:Professional operators responsible for ongoing building performance and regulatory compliance. This cohort gains procurement authority in India's smart city corridors as standalone BMS upgrades precede full integration.
- Property Developers:Asset owners and construction firms shaping initial system specification. Mumbai and Bangalore REITs now unbundle long-term management contracts from construction procurement, creating discrete vendor qualification pools.
- Tenants:Commercial lessees demanding green lease provisions with energy accountability clauses. Sydney and Singapore premium office markets see tenant-driven specification of digital twin platforms.
- Homeowners:Individual purchasers of residential automation features. This segment concentrates in China's tier-one cities and India's premium residential developments.
Facility Managers represent the most concentrated revenue pool, while Property Developers are shifting procurement fastest toward bundled service contracts.
Service Type:
Margin structure varies sharply across the project lifecycle, with front-loaded consulting and integration giving way to sticky maintenance revenue with superior renewal economics.
- Integration:System deployment, protocol harmonization, and commissioning services. Vendors face acute controls engineering scarcity across China's tier-one markets, extending project timelines.
- Maintenance:Ongoing technical support, software updates, and predictive service contracts. Premium developers in Singapore and Sydney favor ten-year agreements that shift vendor revenue toward recurring streams.
- Consulting:Energy audits, compliance pathway design, and technology selection advisory. India's incomplete BIS frameworks force multi-protocol planning, raising consulting intensity.
- Support:Help desk services, remote diagnostics, and emergency response. This tier expands as digital twin platforms require continuous data pipeline monitoring.
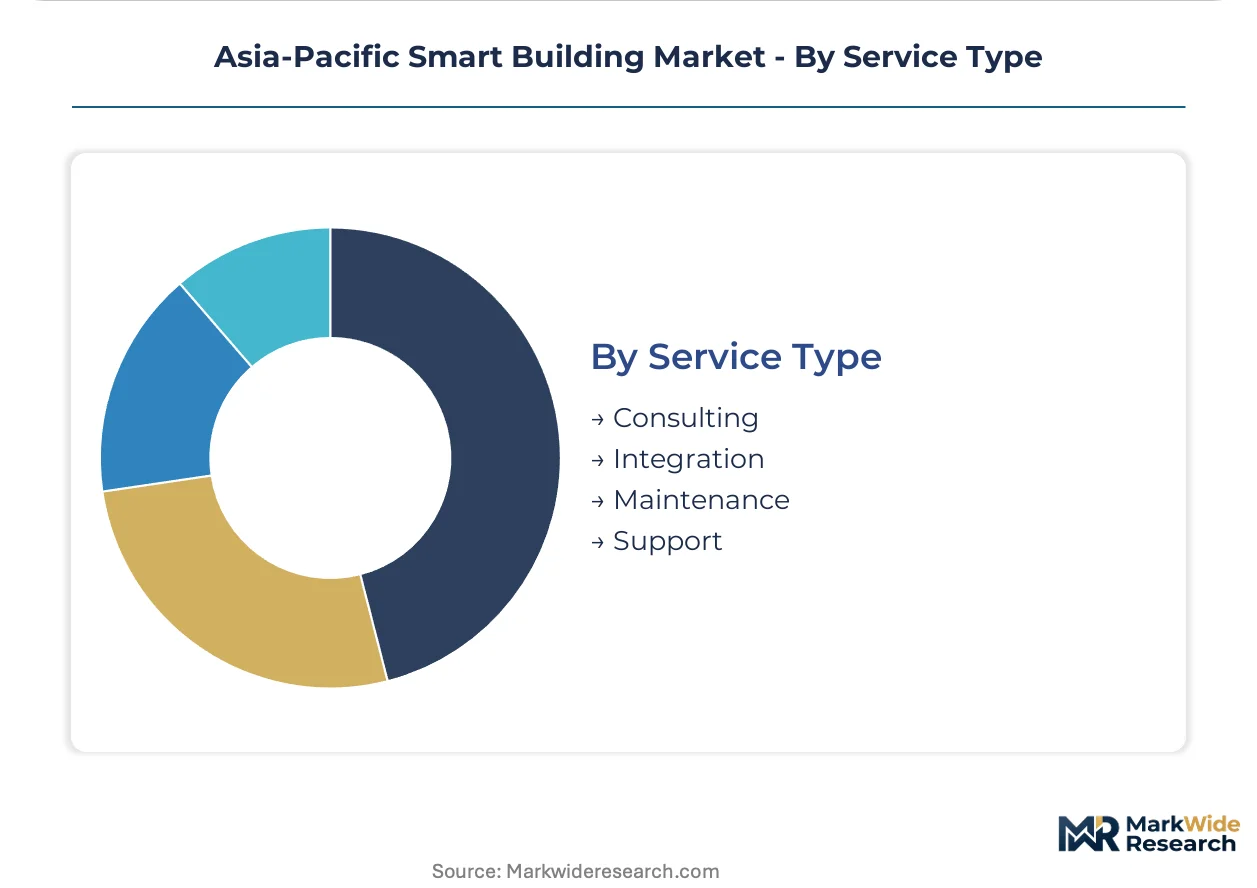
Integration captures the dominant project value share, though Maintenance is climbing the fastest as full-lifecycle contracts displace transactional sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform exports from East Asian automation hubs dominate regional trade flows, while import dependency persists for specialized sensor components and edge computing hardware. Southeast Asian markets absorb integrated systems through Singapore distribution nodes. Australia's retrofit demand draws consulting services from regional headquarters in Sydney.
China
Dual carbon mandates from MEE compress compliance timelines for municipal building portfolios. Real-time energy disclosure rules apply to public structures above specified floor areas in tier-one cities. Beijing and Shanghai accelerate controller procurement ahead of regulatory deadlines.
Japan
METI building efficiency directives upgrade automated demand response requirements for commercial assets. JIS standards bodies coordinate certification pathways for industrial facility upgrades. Automotive and electronics manufacturing clusters in Nagoya and Osaka face steepest compliance curves.
India
Smart city budget expansion concentrates procurement authority with Facility Managers in tier-one corridors. BIS develops IoT interoperability frameworks for municipal infrastructure tenders. Mumbai and Bangalore REITs unbundle long-term management contracts from construction procurement.
Singapore
Green leasing frameworks reward developers bundling energy accountability into tenant agreements. Performance-linked project finance structures shape premium-grade property specifications. The city-state serves as regional distribution hub for integrated platform deployments across Southeast Asia.
Australia
Technical debt in pre-2010 commercial stock drives retrofit demand for overlay sensor deployments. Structured cabling infrastructure gaps force rip-and-replace decisions in Sydney premium office markets. Consulting intensity rises for compliance pathway design under evolving state-level efficiency codes.
Asia-Pacific Smart Building Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensors, controllers, and edge hardware. The vendor base stratifies across three tiers: diversified industrial conglomerates with electrification portfolios, pure-play automation specialists with deep controls expertise, and telecommunications equipment vendors with IoT-to-cloud integration capabilities. Dominant competitive moves include strategic partnerships between hardware fabricators and software analytics providers, plus geographic expansion through pre-certified product bundles that reduce local testing timelines.
Among diversified industrial conglomerates, ABB leverages its electrification portfolio to anchor large-scale commercial retrofits. Johnson Controls sustains positioning via deep controls expertise and long-term facility management relationships. Huawei Technologies competes through integrated IoT-to-cloud stacks that dominate data-intensive verticals. These three exemplify how vendor archetypes map to distinct procurement channels across the region's regulatory environments.
| Leading Market Players |
|---|
| Honeywell International |
| ABB |
| Huawei Technologies |
| Cisco Systems |
| Schneider Electric |
| Hitachi |
| Johnson Controls |
| IBM Corporation |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
Semiconductor supply concentration in East Asian foundries compresses pricing tier spreads across Building Management Systems while forcing buyers toward longer-term offtake contracts that reshape procurement cadence. MEE disclosure mandates and BIS interoperability delays amplify cost volatility for cross-border project integration, tethering vendor margins to protocol standardization timelines.
Pricing Analysis
Industrial OEM buyers anchor project-based pricing structures across Japanese automotive and electronics manufacturing clusters, where METI-mandated demand response compliance drives premium certification investments. Price differentiation rests on JIS certification tier and after-sales service bundling, with ten-year performance guarantees commanding substantial uplifts. Cost compression in mid-market BMS tiers intensifies as Chinese vendors introduce pre-certified product bundles. Facility Managers in India's tier-one corridors exhibit highest price sensitivity due to fragmented smart city budget allocation, while Singapore REITs prioritize lifecycle accountability over unit economics.
Supply Chain Analysis
Silicon wafer and edge controller fabrication feeds from concentrated Taiwan, South Korea, and China foundry capacity, with sensor module assembly distributed across Malaysia and Vietnam. Raw material dependencies span rare earth magnets for actuator motors, high-purity silicon for sensor substrates, and copper for structured cabling infrastructure. Single-source vulnerability concentrates in advanced logic chip supply for AI-driven surveillance systems. Distribution runs through Singapore hub operations serving Southeast Asian commercial developments, with direct vendor relationships dominating tier-one city procurement in China and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controls engineering certification scarcity across multiple BMS protocols constrains commissioning velocity and inflates service costs, compressing margins for vendors unable to secure trained technician pipelines. This capability gap rewards early investments in workforce development and automated commissioning tools.
For Market Incumbents: Harden protocol interoperability stacks against BIS framework finalization, securing first-mover certification in India's emerging standards environment. Acquire specialized commissioning firms in Pune and Ahmedabad to preempt talent scarcity before REIT procurement specifications harden. Defensive consolidation around digital twin software layers protects against pure-play analytics entrants displacing hardware-anchored revenue streams.
For New Entrants and Emerging Players: Build out tier-two Indian metro penetration in environmental monitoring IoT, where municipal tender specifications remain fluid and Facility Manager procurement authority is expanding fastest. Target biometric surveillance retrofit opportunities in Southeast Asian retail developments, where legacy card-based displacement creates discrete upgrade cycles. Pursue partnership-based go-to-market models with Singapore-based system integrators to bypass direct certification burden across multiple national standards regimes.
For Investors and Strategic Acquirers: China's dual carbon enforcement milestones reshape the acquisition landscape, elevating vendors with pre-certified MEE compliance bundles above retrofit-dependent competitors. Long-term viability favors platform integrators with recurring maintenance revenue exceeding fifty percent of total mix. Monitor JIS standards body coordination timelines as inflection indicator for Japanese industrial automation procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Integration | Shifts vendor revenue from hardware sales to predictive maintenance subscriptions across Singapore REIT portfolios. |
| Pre-Certified Product Bundling | Compresses JIS testing timelines for Chinese vendors penetrating Japanese automotive manufacturing clusters. |
| Workforce Development Partnerships | Secures controls engineering pipelines ahead of BIS framework hardening in India's tier-one smart city corridors. |
| Green Leasing Service Packaging | Captures premium pricing power through performance-linked project finance structures in Sydney premium office markets. |
| Protocol Harmonization Investment | Reduces integration cost burden for cross-border projects spanning China's GB standards and India's emerging BIS frameworks. |
Research Methodology
Cross-validation between facility manager interviews and regulatory filing analysis anchors the qualitative findings across the Asia-Pacific smart building sector. Primary fieldwork engaged controls engineers, REIT procurement directors, BMS protocol specialists, and smart city tender officials in tier-one Indian, Chinese, and Southeast Asian markets. Secondary sources encompassed MEE disclosure rule publications, METI efficiency directive updates, BIS draft framework consultations, and municipal budget allocation records. Bottom-up project pipeline assessment triangulated against top-down vendor revenue segmentation.
Calibration against historical retrofit adoption curves and smart city expenditure patterns shaped the projection framework across technology, application, end-user, and service type dimensions. CAGRs derived from segment-level growth rate convergence analysis incorporating regulatory deadline compression effects and semiconductor supply lead time volatility. Forecast inputs included MEE compliance timeline enforcement intensity, JIS standards upgrade adoption velocity, and BIS interoperability framework completion probability.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified industrial conglomerates would shift outcomes substantially. Cross-checking against municipal procurement database tracking and foundry capacity utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Infrastructure
Smart Hydrants Market
Smart Infrastructure
Big Data in Construction Market
Smart Infrastructure
Smart Airport Construction Market
Smart Infrastructure
Global IoT in Construction Market
Smart Infrastructure
US Smart Building Market
Smart Infrastructure
IoT in Commercial Construction Market
Smart Infrastructure
Smart Infrastructure Market
Smart Infrastructure
Infrastructure Solution Integration Service Market
Smart Infrastructure
Smart Pipeline Networks Market
Smart Infrastructure
Construction 4.0 Market
Smart Infrastructure
Smart Concrete Market
Smart Infrastructure
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market
Smart Infrastructure
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market