
 Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market | 2026-2036
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market Insights
Direct sales channels for structural monitoring hardware is tilting toward integrated platform providers that bundle sensors with cloud analytics. HBK leverages its measurement technology heritage to anchor premium positioning in vibration and strain sensing systems. MISTRAS Group sustains broad inspection service capabilities that compete across ultrasonic and acoustic emission modalities. Campbell Scientific specializes in ruggedized environmental and structural data loggers that dominate remote bridge monitoring installations in North American transportation networks.
Bridge and tunnel condition assessment sensor networks and test platforms encompass instrumented systems that acquire, transmit, and analyze structural response data using accelerometers, strain gauges, fiber Bragg gratings, and piezoelectric transducers operating at sampling rates from 100 Hz to 10 kHz depending on fatigue monitoring requirements. These systems enable continuous or periodic evaluation of load capacity, deterioration progression, and residual service life in reinforced concrete and steel superstructures. Wireless sensor networks now lead technology adoption where cabling costs and accessibility constraints penalize wired architectures, while fiber optic sensors capture margin pools in long-span suspension bridges requiring electromagnetic immunity and distributed strain mapping. IoT-based platforms represent the fastest-expanding segment as municipalities consolidate fragmented sensor estates into unified dashboards for maintenance planning and safety inspection workflows.
FHWA National Bridge Inspection Standards and AASHTO LRFD guidelines shape sensor deployment thresholds and data reporting protocols for US state transportation departments. European infrastructure operators navigate EN 1990 Eurocode basis of structural design requirements alongside national mandates from Germany's KBA-relevant federal transport administration and Japan's METI-promoted infrastructure IoT initiatives. Stakeholders must decide whether to prioritize sensor standardization across mixed-vendor estates or accept integration complexity in exchange for best-of-breed performance in critical measurement channels.
Market Dynamics
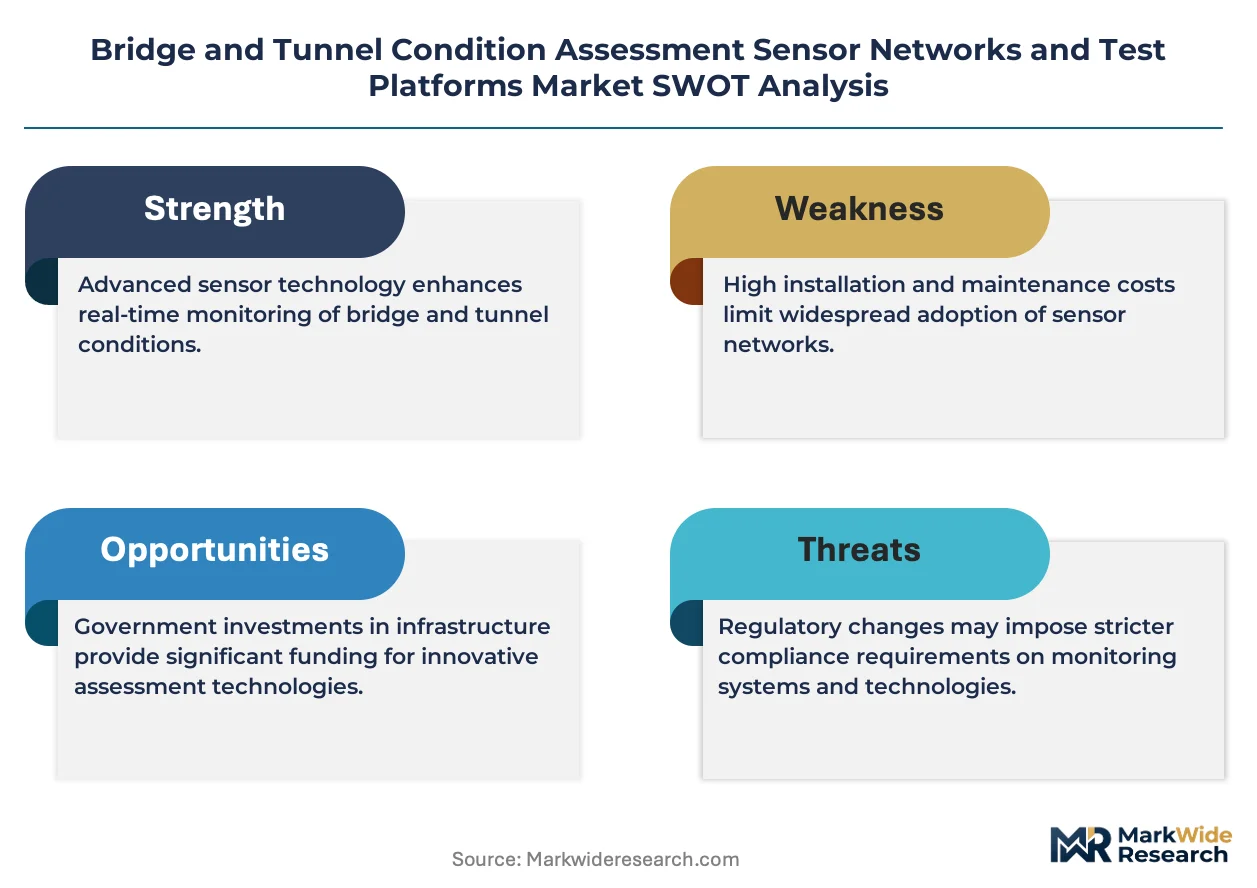
Wireless sensor networks are compressing the economics of continuous bridge monitoring by eliminating cable installation costs and enabling rapid deployment on aging steel and concrete superstructures where accessibility constraints previously mandated periodic manual inspection.
Growth Catalysts
- FHWA National Bridge Inspection Standards:Federal mandates in the United States require enhanced monitoring protocols for structurally deficient bridges, compelling state transportation departments to instrument critical corridors with automated sensing systems.
- Fiber Bragg grating sensors:These optical strain measurement devices deliver electromagnetic immunity essential for long-span suspension bridges, capturing premium deployment opportunities where electrical interference degrades conventional sensor performance.
- Germany's KBA-relevant federal transport administration:National infrastructure rehabilitation programs prioritize sensor deployment on autobahn bridge networks, establishing procurement templates adopted by neighboring European operators.
Market Restraints
- Silicon photonics component shortages:Concentrated fabrication capacity in East Asian foundries creates supply vulnerability for fiber optic interrogator units, extending lead times for distributed sensing systems.
- Specialized calibration labor scarcity:Qualified technicians capable of validating strain gauge installations on post-tensioned concrete segments command premium wages, inflating total cost of ownership for owner-operators.
- EN 1990 Eurocode compliance complexity:Divergent national annex interpretations across European member states fragment sensor specification requirements, forcing manufacturers to maintain multiple product variants.
Strategic Opportunities
- Japan's METI infrastructure IoT initiatives:Government-subsidized pilot programs for tunnel ventilation and structural monitoring create early-mover advantages for integrated platform providers.
- AI-driven predictive maintenance convergence:Machine learning algorithms processing accelerometer time-series data enable crack propagation forecasting, differentiating vendors who bundle analytics with hardware.
- Performance-based service contracts:Municipalities in the United States are transitioning from capital procurement to subscription models where sensor network operators guarantee inspection compliance outcomes.
Industry Challenges
- Structural engineer data science competency gaps:Bridge owners struggle to staff interpretation roles capable of translating raw vibration spectra into maintenance prioritization decisions, slowing realization of monitoring investments.
- Multi-vendor integration complexity:Legacy wired sensor estates from disparate manufacturers resist consolidation into unified IoT dashboards, fragmenting operational workflows and diluting platform economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market |
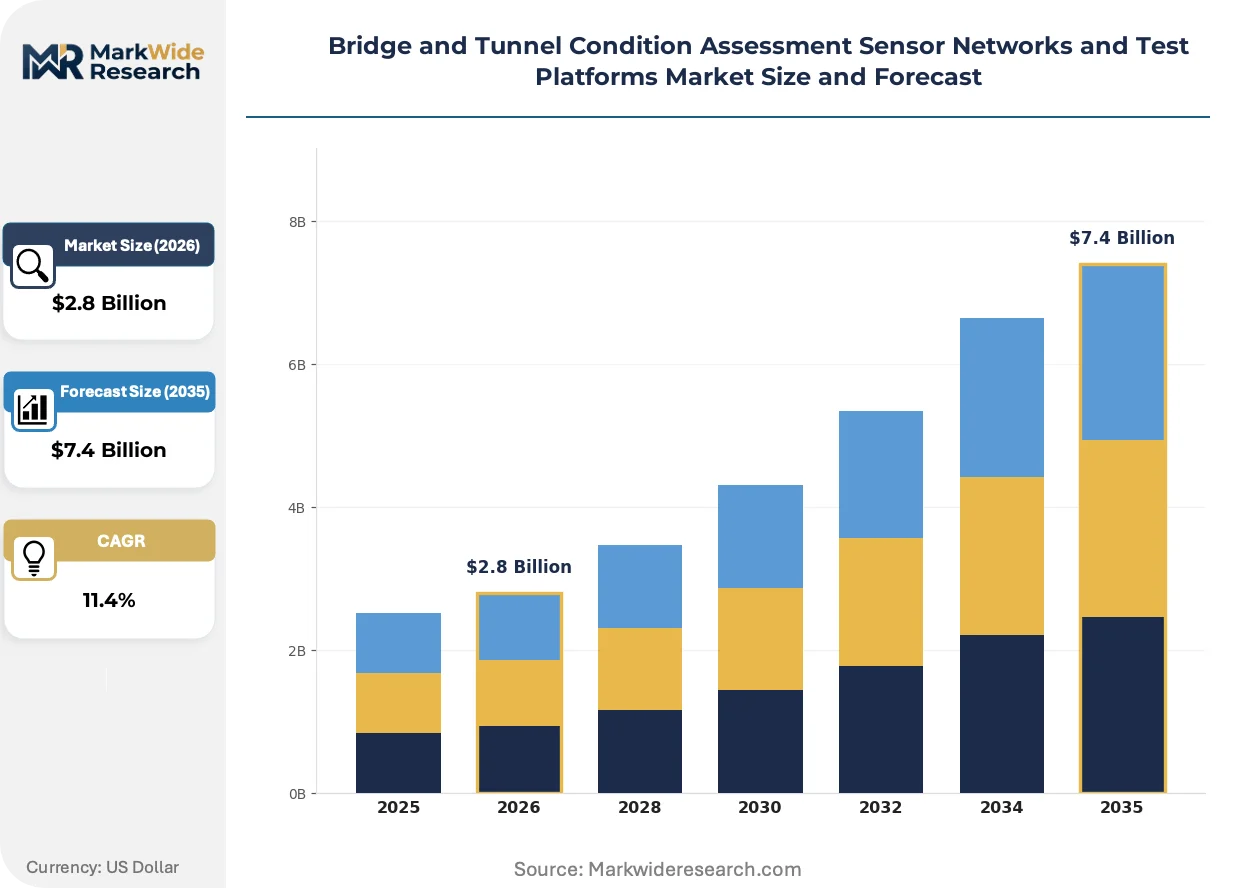
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strain Sensors, Vibration Sensors, Displacement Sensors, Corrosion Sensors, Acoustic Emission Sensors Technology: Wireless Sensor Networks, Fiber Optic Sensors, Ultrasonic Testing, Remote Monitoring Systems, IoT-based Platforms Application: Structural Health Monitoring, Safety Inspection, Maintenance Planning, Load Testing, Environmental Impact Analysis End User: Infrastructure Management Companies, Civil Engineering Firms, Government Agencies, Private Construction Consultants |
| Companies Covered | HBK, MISTRAS Group, Campbell Scientific, GEOKON, Sisgeo, Kinemetrics, Geocomp, Fugro, WSP Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market Trends and Innovations
Energy harvesting and edge computing architectures are transforming how structural data is acquired and processed, shifting analytical workloads from centralized servers to sensor nodes while eliminating battery maintenance cycles on remote bridge installations.
Self-powered wireless sensor nodes utilizing piezoelectric energy conversion from traffic-induced vibration are rendering obsolete battery-dependent architectures that require lane closures for replacement. State transportation departments in California and Texas have accelerated pilot deployments on interstate corridors where traffic density sustains continuous power generation. The elimination of battery logistics is compressing lifecycle operating costs and enabling permanent installation in conduits where manual access is prohibitively expensive.
CSRD sustainability disclosure requirements in the European Union now mandate granular reporting of infrastructure asset residual service life, compelling operators to instrument tunnel linings and bridge decks with continuous deterioration tracking systems. The directive's scope encompasses publicly listed construction firms and infrastructure funds, expanding addressable demand beyond traditional public agency buyers. German and French operators are responding by consolidating fragmented sensor estates into unified environmental, social, and governance data pipelines.
Asset managers are unbundling hardware procurement from analytics subscriptions, demanding interoperability guarantees before committing to multi-year platform contracts. This behavioral shift pressures integrated vendors to expose application programming interfaces and adopt open data standards, while pure-play sensor manufacturers capture margin by supplying white-label hardware to software-agnostic system integrators. The pattern is most pronounced in United States municipal markets where procurement officers prioritize vendor flexibility over single-source accountability.
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market Segmentation
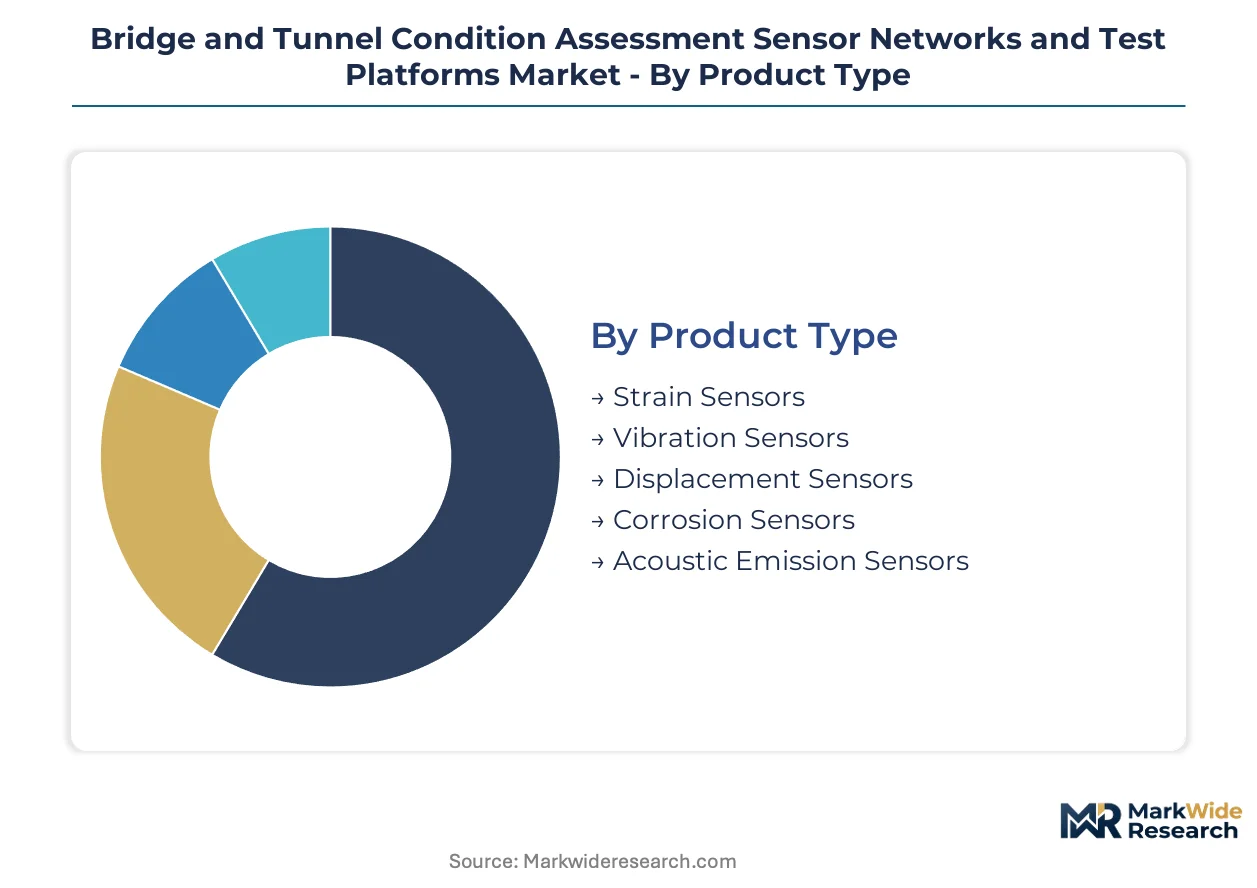
Sensor selection and platform architecture vary sharply across bridge and tunnel assessment workflows. Procurement decisions hinge on structural material, accessibility constraints, and regulatory compliance mandates.
Product Type:
Cost tier differentiation separates commodity strain gauges from premium distributed fiber systems requiring specialized interrogator hardware.
- Strain Sensors:Resistive foil and vibrating wire configurations measure deformation in reinforced concrete decks and steel girders. State transportation departments in California and Texas specify these for fatigue-prone details on interstate corridors.
- Vibration Sensors:Piezoelectric accelerometers and MEMS devices capture modal frequencies at sampling rates up to 10 kHz. Long-span suspension bridges deploy these for dynamic load characterization under traffic and wind excitation.
- Displacement Sensors:LVDT and laser-based systems track joint movements and bearing rotations.
- Corrosion Sensors:Embedded half-cell potential probes monitor chloride ingress in marine-exposed substructures.
- Acoustic Emission Sensors:Piezoelectric transducers detect crack propagation energy releases in post-tensioned concrete.
Strain sensors command the established base. The steepest expansion runs through vibration sensors.
Technology:
Application context determines whether wireless architectures or fiber optic immunity delivers superior lifecycle economics.
- Wireless Sensor Networks:Low-power radio protocols eliminate cabling costs on aging structures with difficult access. Municipalities facing lane closure restrictions favor rapid deployment without conduit installation.
- Fiber Optic Sensors:Fiber Bragg gratings and distributed acoustic sensing provide electromagnetic immunity for long-span bridges near power transmission corridors. German autobahn operators specify these for high-voltage proximity zones.
- Ultrasonic Testing:Pulse-echo and through-transmission methods map internal concrete defects and weld integrity.
- Remote Monitoring Systems:Cellular and satellite telemetry extend coverage to rural bridge inventories.
- IoT-based Platforms:Cloud-integrated dashboards consolidate multi-vendor sensor estates into unified maintenance workflows.
Wireless sensor networks anchor volume deployment. IoT-based platforms are climbing the fastest as municipalities consolidate fragmented estates.
Application:
Volume concentration tracks regulatory inspection cycles rather than discretionary asset management.
- Structural Health Monitoring:Continuous data acquisition enables residual service life estimation and load rating updates. FHWA mandates drive state DOT procurement for structurally deficient inventory.
- Safety Inspection:Automated sensing supplements visual bridge inspection protocols under National Bridge Inspection Standards. Federal compliance deadlines compress procurement timelines.
- Maintenance Planning:Deterioration forecasting optimizes repair scheduling and budget allocation.
- Load Testing:Instrumented diagnostic loading validates analytical models for posting decisions.
- Environmental Impact Analysis:Vibration and noise monitoring satisfies construction mitigation requirements.
Structural health monitoring holds the revenue base. Safety inspection is expanding most quickly under tightening federal mandates.
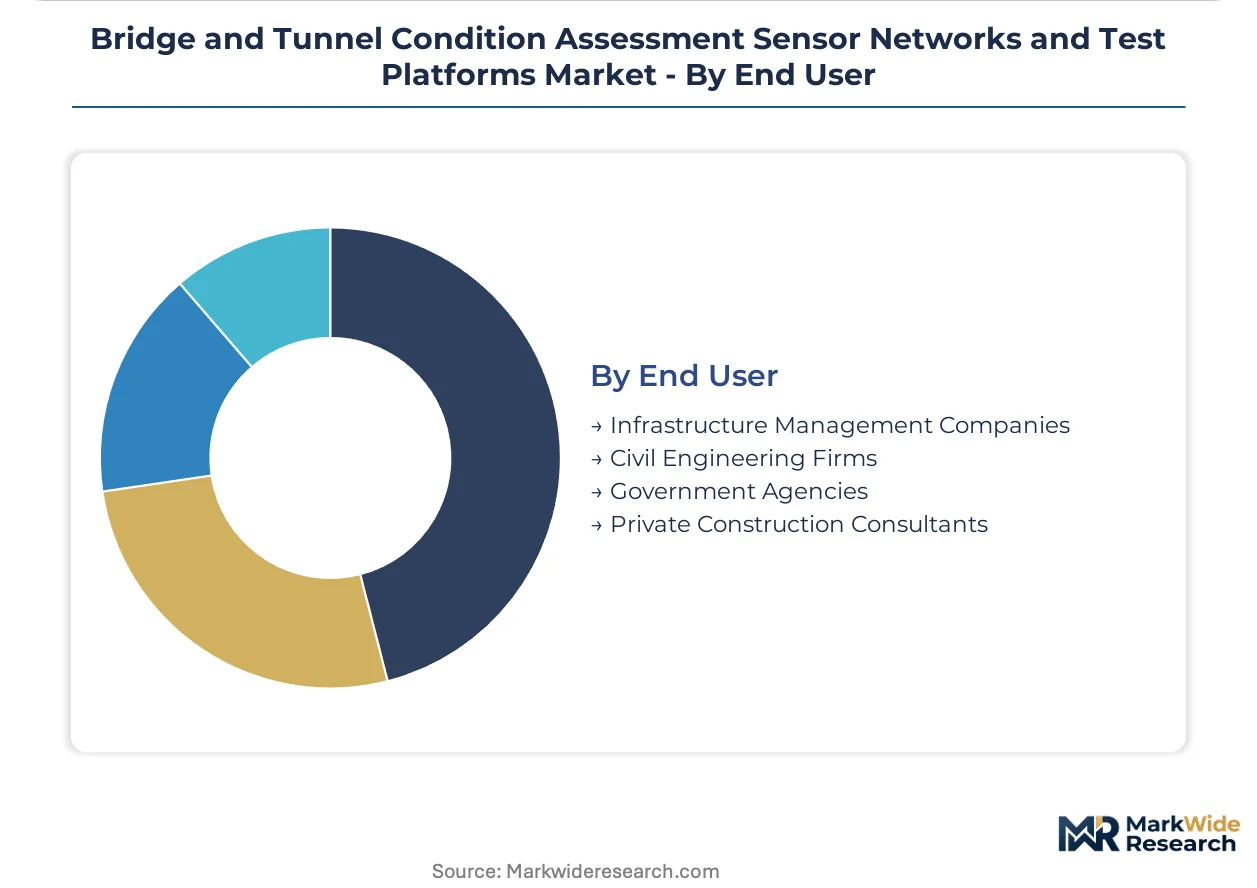
End User:
Customer type shapes procurement modality from capital equipment to performance-based service contracts.
- Infrastructure Management Companies:Specialized asset operators bundle sensor deployment with long-term O&M contracts. These firms favor integrated platforms with guaranteed uptime SLAs.
- Civil Engineering Firms:Design-build contractors specify monitoring systems during rehabilitation projects. Their procurement prioritizes interoperability with existing structural analysis software.
- Government Agencies:State and federal transportation departments dominate public bridge inventory assessment.
- Private Construction Consultants:Third-party inspection firms deploy portable systems for project-specific evaluations.
Government agencies command the established base. Infrastructure management companies show the steepest expansion trajectory as municipalities outsource monitoring operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FHWA mandates in the United States anchor structural health monitoring procurement volumes, while KBA regulations in Germany and METI initiatives in Japan establish complementary demand centers across three continents.
United States
State transportation departments in California and Texas drive sensor deployment on interstate corridors where aging steel superstructures require continuous fatigue monitoring. The FHWA National Bridge Inspection Standards compel automated instrumentation for structurally deficient inventory. Greater Boston's research universities collaborate with Massachusetts DOT on vibration-based predictive maintenance pilots.
Germany
Autobahn operators prioritize fiber optic immunity for long-span bridges near high-voltage transmission corridors. KBA-relevant federal transport administration procurement templates influence neighboring European markets. The Ruhr industrial cluster hosts specialized calibration laboratories serving post-tensioned concrete monitoring contracts across Central Europe.
Japan
Seismic resilience requirements accelerate adoption of high-sampling-rate accelerometer networks on critical transportation infrastructure. METI infrastructure IoT initiatives subsidize tunnel ventilation and structural monitoring pilot programs. Osaka-based engineering consortiums integrate sensor data with earthquake early warning systems for highway operators.
United Kingdom
Network Rail and Highways England consolidate fragmented sensor estates into unified asset management dashboards. CSRD sustainability disclosure mandates extend monitoring requirements to infrastructure funds and listed construction firms. The Midlands manufacturing corridor supplies ruggedized data loggers for remote bridge installations.
Australia
State road authorities in New South Wales and Victoria deploy remote monitoring systems across rural bridge inventories with cellular telemetry backhaul. ISO standards for structural health monitoring guide procurement specifications. Sydney's engineering consultancies bundle sensor deployment with long-term performance-based maintenance contracts.
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market Competitive Landscape
Integrated platform providers and specialized sensor manufacturers split the market along the hardware-analytics boundary. Measurement technology heritage anchors premium positioning for vibration and strain sensing systems, while inspection service capabilities compete across ultrasonic and acoustic emission modalities. Two strategic archetypes dominate: heritage instrumentation firms with calibration expertise, and diversified engineering consultancies bundling deployment with long-term operations contracts. Competitive moves concentrate on API interoperability commitments and performance-based service contract structuring.
Within the heritage instrumentation tier, HBK and Campbell Scientific exemplify divergent specialization paths. HBK leverages its measurement technology legacy to anchor premium positioning in high-frequency vibration and dynamic strain sensing systems for suspension bridge applications. Campbell Scientific occupies a position focused on ruggedized environmental and structural data loggers that dominate remote installations in North American transportation networks where cellular telemetry and solar power integration prove decisive.
| Leading Market Players |
|---|
| HBK |
| MISTRAS Group |
| Campbell Scientific |
| GEOKON |
| Sisgeo |
| Kinemetrics |
| Geocomp |
| Fugro |
| WSP Global |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's concentrated MEMS fabrication capacity feeds directly into downstream pricing power for accelerometer modules, compressing margins for European sensor integrators while enabling aggressive SaaS bundling from Asia-Pacific platform providers.
Pricing Analysis
Price spreads between German calibration-certified systems and Asian commodity hardware now exceed three-to-one across equivalent strain sensing specifications. Three-tier pricing structure across premium, standard, and economy levels separates fiber optic interrogator suites from wireless node clusters and basic resistive gauge installations. Pricing pressure stems from municipal procurement officers demanding interoperability guarantees before multi-year platform commitments. State transportation departments exhibit highest price sensitivity, while long-span suspension bridge operators prioritize electromagnetic immunity over unit cost.
Supply Chain Analysis
Silicon wafers and piezoelectric ceramics draw from fabrication centers in Taiwan, Japan, and Germany, with specialty optical fiber drawing concentrated in the United States and Netherlands. Raw material dependencies center on lithium niobate crystals for acoustic emission transducers, boron-doped silicon for MEMS devices, and germanium-doped silica for fiber Bragg grating cores. Single-source vulnerability concentrates in East Asian foundry capacity for photonic integrated circuits. Distribution runs through authorized system integrators who bundle hardware deployment with calibration services and cloud analytics subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified technicians capable of validating strain gauge installations on post-tensioned concrete segments command premium wages, creating a persistent capability gap that constrains market expansion and elevates total cost of ownership for owner-operators.
For Market Incumbents: Entrench calibration expertise as a defensive moat by acquiring specialized laboratories in the Ruhr industrial cluster and securing exclusive technician training partnerships with German technical universities. Fiber optic interrogator supply shortages from East Asian foundries threaten hardware margins; backward integration into optical component sourcing secures delivery reliability for premium contracts. For New Entrants and Emerging Players: Build out white-label hardware supply relationships with municipal system integrators who prioritize vendor flexibility over single-source accountability. Rural bridge inventories in Australia and the American Southwest present the most penetrable geography, where cellular telemetry requirements favor lightweight platform entrants over heritage instrumentation firms. Lead with API-first architecture and open data standards to bypass incumbent lock-in. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because FHWA mandates and CSRD sustainability disclosure requirements structurally expand addressable demand beyond discretionary asset management budgets. Acquisition targets should demonstrate bundled deployment-to-operations capabilities with performance-based contract structuring. The signal to watch is municipal procurement modality shift from capital equipment to subscription-guaranteed inspection outcomes.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Acquisition | Ruhr-based facilities anchor technician scarcity solutions for Central European contracts. |
| API Interoperability Certification | Open data standards unlock municipal procurement preference for multi-vendor flexibility. |
| Energy-Harvesting Node Development | Piezoelectric power elimination compresses lifecycle costs on remote interstate corridors. |
| Performance-Based Service Contracting | Subscription models align vendor incentives with FHWA compliance outcome guarantees. |
| Fiber Optic Interrogator Backward Integration | Captive photonic integrated circuit supply insulates against East Asian foundry volatility. |
Research Methodology
Cross-validation between primary interviews with bridge maintenance engineers, state DOT procurement officers, fiber optic sensor calibration technicians, and IoT platform integration specialists anchors the qualitative findings against secondary validation from FHWA bridge inventory databases, AASHTO LRFD guideline documentation, EN 1990 Eurocode national annex interpretations, and SEC filings from listed infrastructure technology providers. Bottom-up sensor deployment estimates triangulate against top-down government procurement budget allocations.
Calibration against historical installation records from California and Texas state transportation departments validates the analytical framework across the projection horizon. Segmentation dimensions encompass sensor modality, communication architecture, structural material compatibility, and regulatory compliance tier. CAGRs derive from slope analysis of procurement velocity curves and infrastructure rehabilitation funding trajectories. Forecast inputs incorporate FHWA structurally deficient bridge counts and METI infrastructure IoT subsidy allocation patterns.
Stress conditions across silicon photonics component availability, specialized calibration labor wage inflation, and municipal procurement modality shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding federal infrastructure rehabilitation funding continuity and wireless protocol standardization adoption curves. Cross-checking against state DOT capital improvement plan disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Infrastructure
Construction 4.0 Market
Smart Infrastructure
Smart Hydrants Market
Smart Infrastructure
Smart Infrastructure Market
Smart Infrastructure
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market
Smart Infrastructure
Big Data in Construction Market
Smart Infrastructure
Smart Pipeline Networks Market
Smart Infrastructure
US Smart Building Market
Smart Infrastructure
Smart Concrete Market
Smart Infrastructure
Asia-Pacific Smart Building Market
Smart Infrastructure
Smart Airport Construction Market
Smart Infrastructure
IoT in Commercial Construction Market
Smart Infrastructure
Global IoT in Construction Market
Smart Infrastructure
Infrastructure Solution Integration Service Market