
 Construction 4.0 Market | 2026-2036
Construction 4.0 Market Size, Share, and Industry Trends Forecast 2026-2036
Construction 4.0 Market Intelligence
A widening capability gap in cloud-native platform development is bifurcating the competitive landscape between capital-heavy incumbents and agile specialists. Autodesk Inc. leverages its design-to-construction workflow integration to anchor premium positioning among architectural firms. Trimble, Inc. competes through hardware-software convergence in field positioning and site monitoring equipment. SAP SE extends its enterprise resource planning dominance into construction-specific project cost controls.
Construction 4.0 denotes the digitization of building processes through cyber-physical systems, encompassing sensor-enabled equipment, machine learning algorithms for schedule optimization, and interoperable data environments governed by ISO 19650 information management protocols. Its primary purpose is to compress project delivery timelines while reducing material waste and safety incidents through predictive analytics. IoT-enabled site monitoring and AI-driven risk assessment represent the fastest-expanding technology-application intersection, where margin pools concentrate in subscription-based analytics layers rather than hardware sales. Building Information Modeling remains the most mature application segment, though robotics for repetitive assembly tasks is displacing labor-intensive methods in high-cost labor markets.
The EU Green Deal and F-Gas Regulation shape equipment specifications and energy performance benchmarks across European projects, while OSHA standards in the United States mandate wearable technology deployment for worker safety compliance on federally funded sites. ISO 19650 and national building codes in Germany, Japan, and Australia create fragmented but demanding certification pathways that filter market access. Stakeholders must evaluate regulatory convergence trajectories when prioritizing platform standardization investments versus localized compliance modules.
Market Dynamics
Federal digitization mandates in Germany are compressing procurement timelines for AI-driven project management platforms while fragmenting vendor qualification pathways across ISO 19650 certification tiers.
Growth Catalysts
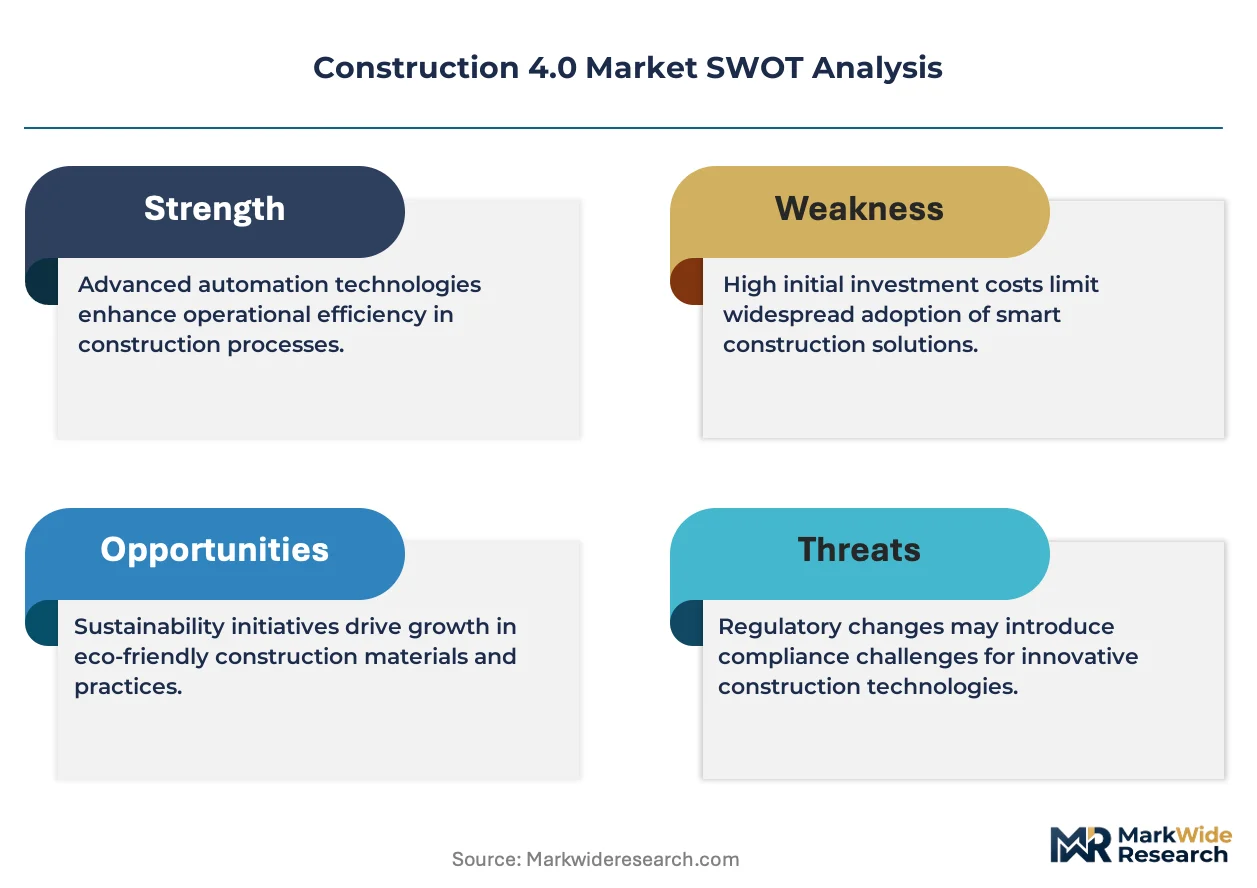
- EU Green Deal compliance:Building energy performance standards are mandating sensor-enabled equipment retrofits across existing commercial stock in France, Italy, and Spain.
- AI schedule optimization:Machine learning algorithms for predictive resource allocation are cutting material waste on large-scale infrastructure sites in Germany and the Netherlands.
- Japan's METI digitization push:Public construction procurement guidelines are requiring BIM submission standards for projects above defined contract thresholds.
Market Restraints
- Semiconductor supply concentration:IoT sensor and edge computing component sourcing remains concentrated among East Asian foundries, exposing platform developers to input volatility.
- ISO 19650 fragmentation:National adoption variants in Germany, Japan, and Australia create multi-track certification costs for software vendors seeking cross-border deployment.
- Labor substitution limits:Robotics for repetitive assembly faces technical boundaries in unstructured outdoor environments, constraining deployment to prefabrication facilities.
Strategic Opportunities
- India's smart cities mission:Municipal infrastructure digitization programs are creating procurement channels for integrated project management platforms in tier-1 urban clusters.
- Wearable safety convergence:OSHA-mandated worker monitoring on US federally funded sites is opening subscription revenue pools for biometrics-software bundles.
- Digital twin integration:Real-time sensor data feeds into operational building models represent an underdeveloped application layer for facility management contracts.
Industry Challenges
- Cloud-native engineering scarcity:Platform developers face acute competition for full-stack architects capable of ISO 19650-compliant data environment design.
- Legacy ERP integration:Construction firms with entrenched SAP or Oracle installations encounter data migration friction when adopting specialized project cost control modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction 4.0 Market |
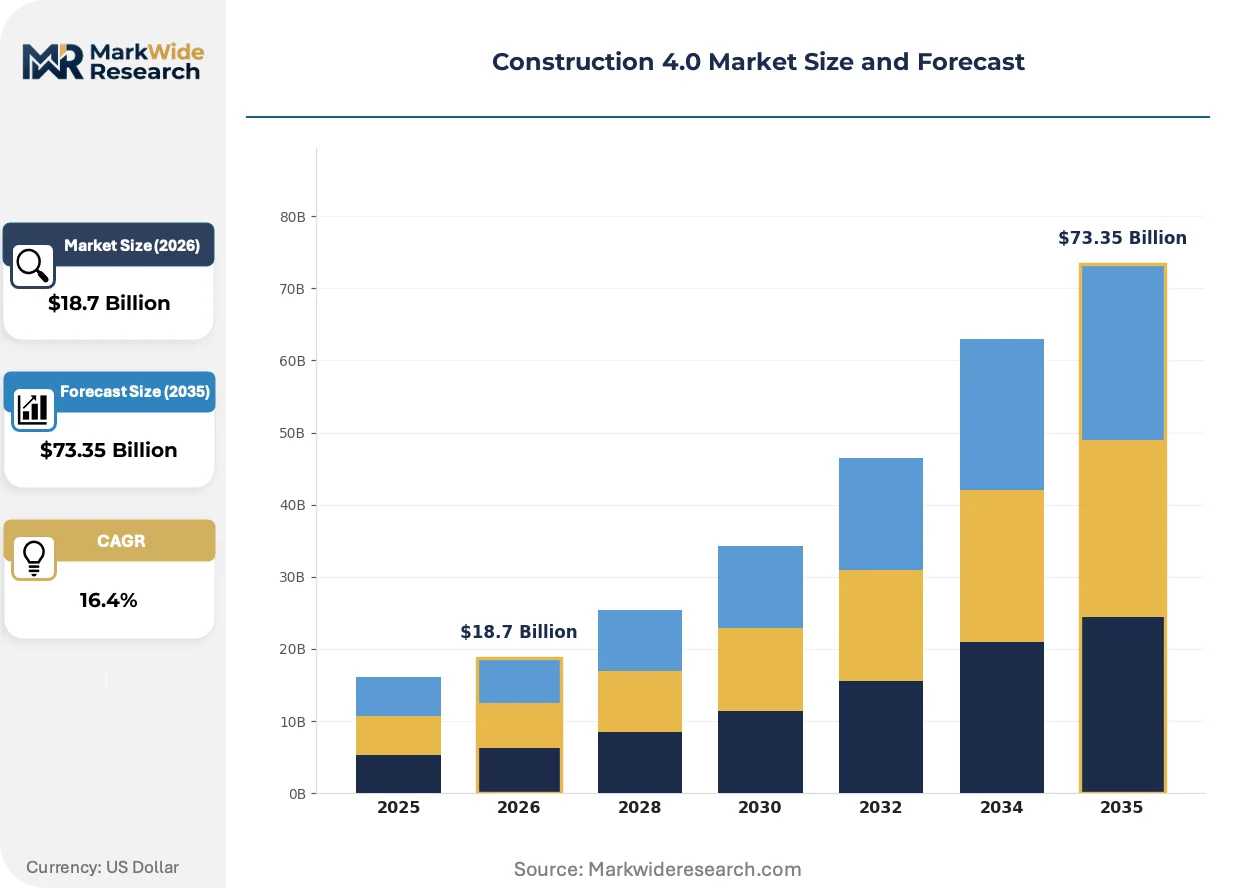
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 3D Printing, IoT, AI, Robotics Application: Project Management, Building Information Modeling, Site Monitoring, Safety Management End User: General Contractors, Subcontractors, Architectural Firms, Engineering Firms Product Type: Construction Software, Equipment Automation, Wearable Technology, Drones |
| Companies Covered | ABB Ltd, Autodesk Inc., Hexagon AB, Hilti Corporation, Oracle Corporation, Trimble, Inc., Topcon Corporation, Bentley Systems, SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction 4.0 Market Strategic Shifts & Innovations
Edge computing architectures are compressing latency thresholds for real-time site analytics while regulatory pressure on embodied carbon is reshaping equipment specification protocols across procurement frameworks.
Sensor-enabled concrete maturity monitoring is miniaturizing from trailer-mounted laboratory units to embedded wireless nodes. Infrastructure contractors in Germany and Japan are deploying these systems on bridge and tunnel projects to eliminate destructive core sampling. The technology is miniaturizing quality assurance workflows from batch-based testing to continuous in-situ verification, compressing inspection timelines and reducing material over-specification.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in construction equipment climate control systems. Equipment lessors and fleet operators must retrofit or replace affected machinery to maintain compliance on public works contracts. German rental companies are accelerating electric HVAC unit procurement to defend qualification status under federal procurement rules.
Subscription-based analytics layers are displacing perpetual license models for BIM and project management software. Tier-1 architectural firms in the United Kingdom and Australia are consolidating vendor relationships around integrated design-to-construction workflows with usage-based pricing. This shift concentrates margin pools with platforms demonstrating proven interoperability across ISO 19650-certified data environments.
Construction 4.0 Market Segmentation
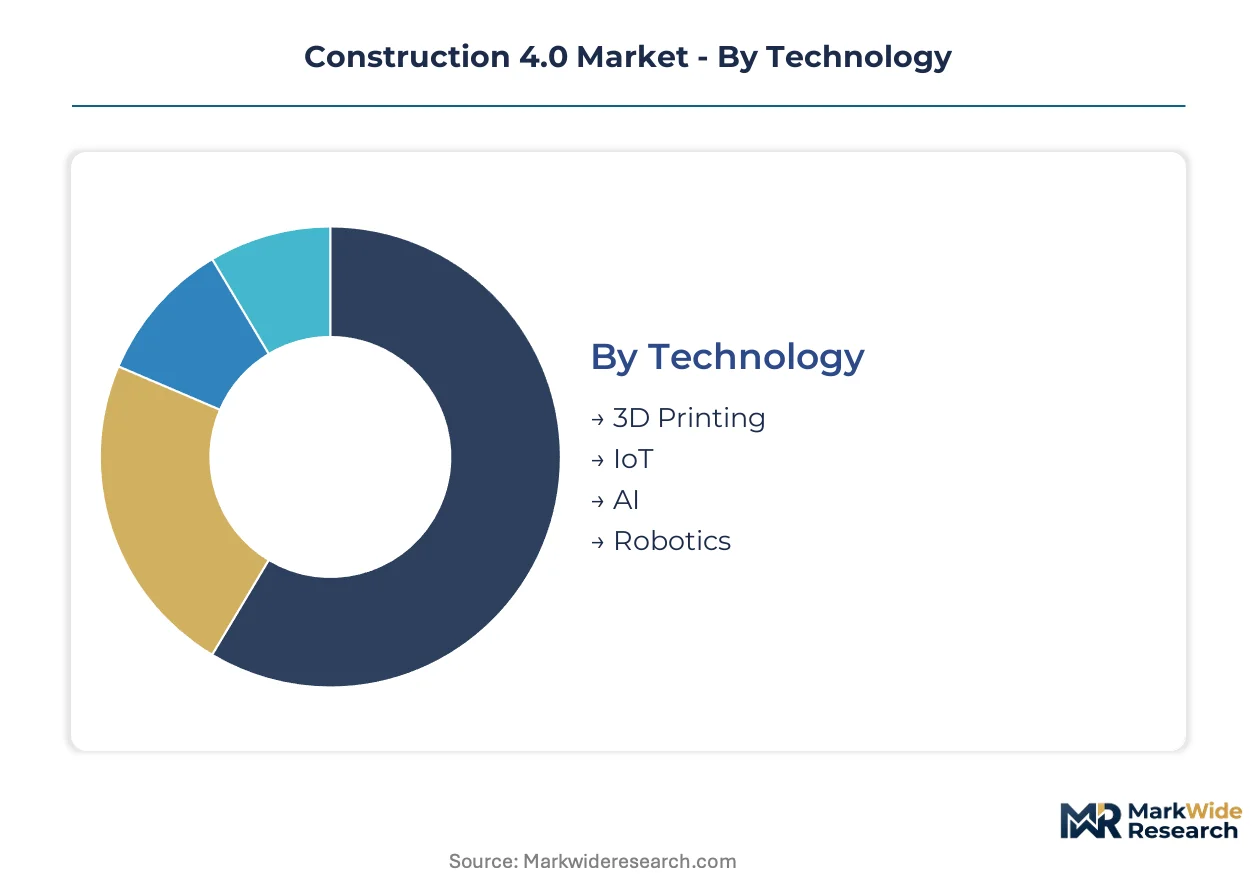
Construction 4.0 segmentation reveals distinct procurement patterns across technology maturity tiers. Buyers in Germany and Japan cluster around certified data environments, while emerging markets prioritize hardware-first automation bundles.
Technology:
Geographic deployment patterns split between export-led platform licensing and domestic hardware integration. European vendors dominate software exports, while East Asian manufacturers anchor sensor and robotics supply.
- IoT:Sensor networks for concrete maturity monitoring and equipment telemetry now deploy as embedded wireless nodes rather than trailer-mounted units. German bridge contractors and Japanese tunnel specialists are eliminating destructive core sampling through continuous in-situ verification, compressing inspection timelines.
- AI:Machine learning algorithms for predictive resource allocation and schedule optimization are cutting material waste on large-scale infrastructure sites. Dutch and German project managers are deploying these tools for real-time risk assessment, shifting procurement toward subscription-based analytics layers.
- 3D Printing:Additive manufacturing for construction components remains concentrated in prefabrication facilities due to technical boundaries in unstructured outdoor environments.
- Robotics:Automated systems for repetitive assembly tasks face deployment constraints outside controlled factory settings, limiting adoption to high-cost labor markets with established prefabrication infrastructure.
IoT holds the largest share; momentum sits with AI.
Application:
Cost tier differentiation separates enterprise-grade integrated suites from point solutions targeting mid-market contractors. Premium positioning concentrates in design-to-construction workflow bundles.
- Building Information Modeling:The most mature application segment, BIM now operates under ISO 19650 protocols with tiered certification requirements. Tier-1 architectural firms in the United Kingdom and Australia are consolidating vendor relationships around usage-based pricing models.
- Site Monitoring:IoT-enabled real-time analytics represent the fastest-expanding intersection, where margin pools concentrate in subscription layers rather than hardware sales. Edge computing architectures are compressing latency thresholds for immediate field decision-making.
- Project Management:AI-driven platforms are accelerating procurement timelines under German federal digitization mandates, fragmenting vendor qualification pathways across certification tiers.
- Safety Management:OSHA-mandated worker monitoring on US federally funded sites is opening subscription revenue pools for biometrics-software bundles.
BIM commands established revenue bases; site monitoring is climbing the fastest.
End User:
Customer type determines procurement authority and integration complexity. Large-scale developers wield specification power; smaller trades follow mandated standards.
- Architectural Firms:Design-to-construction workflow integration anchors premium positioning among practices seeking ISO 19650-certified data environments. These buyers prioritize interoperability over point solution pricing.
- General Contractors:Large-scale infrastructure developers are accelerating adoption of AI-driven project management platforms, with German federal mandates creating concentrated procurement pull.
- Engineering Firms:Technical consultancies require specialized modules for structural analysis and compliance verification.
- Subcontractors:Smaller trades face data migration friction when adopting specialized cost control modules, often operating within entrenched ERP installations.
General contractors hold the largest share; momentum sits with architectural firms.
Product Type:
Supply concentration in East Asian foundries shapes hardware procurement risk profiles, while software margins concentrate with platforms demonstrating cross-border interoperability.
- Construction Software:Subscription models are displacing perpetual licenses for BIM and project management tools. Tiered pricing stratifies across enterprise, mid-market, and entry-level certification grades.
- Wearable Technology:Biometrics-software bundles for worker safety compliance are gaining procurement traction on federally funded sites in the United States.
- Equipment Automation:Sensor-enabled retrofits are spreading across existing commercial stock in France, Italy, and Spain under EU Green Deal energy performance standards.
- Drones:Aerial site surveying and progress monitoring face regulatory fragmentation across national aviation authorities.
Construction software holds the largest share; wearable technology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German platform vendors under federal digitization mandates, while Indian municipal procurement operates on compressed hardware-first budgets that favor East Asian sensor manufacturers.
Germany
Federal digitization mandates for public construction projects are compressing procurement timelines for AI-driven project management platforms. ISO 19650 certification tiers fragment vendor qualification pathways, creating multi-track compliance costs. Infrastructure contractors in Bavaria and North Rhine-Westphalia are deploying sensor-enabled concrete maturity monitoring on bridge and tunnel projects.
United States
OSHA-mandated wearable technology deployment on federally funded sites is opening subscription revenue pools for biometrics-software bundles. The FAA regulates drone-based site surveying and progress monitoring across national aviation jurisdictions. General contractors in Texas and California are accelerating adoption of edge computing architectures for real-time field analytics.
Japan
METI public construction procurement guidelines require BIM submission standards for projects above defined contract thresholds. JIS standards create demanding certification pathways that filter software vendor market access. Engineering consultancies in the Kanto and Kansai regions are consolidating vendor relationships around integrated design-to-construction workflows.
India
Municipal infrastructure digitization programs under the smart cities mission are creating procurement channels for integrated project management platforms in tier-1 urban clusters. BIS standards govern equipment specifications for federally funded construction. Developers in Maharashtra and Karnataka face data migration friction when adopting specialized cost control modules alongside entrenched ERP installations.
United Kingdom
Tier-1 architectural firms are consolidating vendor relationships around subscription-based BIM and project management software with usage-based pricing. GDPR compliance requirements shape data environment governance for cross-border project collaboration. Practices in London and the Southeast are prioritizing interoperability over point solution pricing in platform selection.
Construction 4.0 Market Key Industry Players
Concentration sits with design-to-construction workflow integrators and enterprise resource planning extenders. The vendor base splits between capital-heavy incumbents with captive hardware-software convergence and agile cloud-native specialists competing on ISO 19650 certification velocity. Two strategic archetypes dominate: workflow bundlers anchoring premium positioning among architectural firms, and field equipment convergence players competing through sensor-software integration. Competitive moves center on M&A for cloud-native engineering talent and strategic partnerships for East Asian sensor supply security.
Among enterprise software incumbents, Autodesk Inc., SAP SE, and Trimble, Inc. occupy positions across the workflow integration spectrum. Autodesk exemplifies the design-to-construction bundler archetype through its architectural firm anchor positioning. SAP SE represents the ERP extension model into construction-specific project cost controls. Trimble sits within the hardware-software convergence tier, anchoring field positioning and site monitoring equipment supply.
| Leading Market Players |
|---|
| ABB Ltd |
| Autodesk Inc. |
| Hexagon AB |
| Hilti Corporation |
| Oracle Corporation |
| Trimble, Inc. |
| Topcon Corporation |
| Bentley Systems |
| SAP SE |
| Others |
Cost & Logistics Intelligence
Ninety-day component lead times for IoT sensors and edge computing modules compress procurement windows while amplifying pricing power for East Asian foundries serving platform developers under German federal digitization mandates. This inventory pressure concentrates cost control leverage with hardware-software bundlers who can absorb input volatility through subscription pricing models.
Pricing Analysis
The customization-premium spread between ISO 19650-certified enterprise suites and entry-level project management tools spans three certification grades. Subscription-based SaaS tiers dominate, with price differentiation driven by interoperability depth and after-sales analytics bundling. Cost compression in mid-market segments intensifies as cloud-native specialists undercut legacy ERP extenders. General contractors show highest price sensitivity; architectural firms prioritize interoperability over point-solution discounts.
Supply Chain Analysis
Just-in-time inventory strategies dominate among software vendors, while hardware integrators maintain strategic stockpiles of sensor components given Taiwan, South Korea, and China concentration. Semiconductor fabrication for edge computing modules and wireless telemetry chips draws from East Asian foundries. Single-source vulnerability in advanced node production threatens platform delivery timelines. Distribution runs through authorized systems integrators and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where ISO 19650 certification velocity creates regulatory entrenchment that locks out uncertified competitors and cements switching costs for enterprise buyers.
For Market Incumbents: Secure cloud-native engineering talent through targeted acquisition of full-stack architects capable of ISO 19650-compliant data environment design. Defend against agile specialists by accelerating certification velocity across German, Japanese, and Australian national adoption variants. Prioritize backward integration into sensor supply partnerships to mitigate East Asian foundry concentration risk.
For New Entrants and Emerging Players: Subscription analytics layers for digital twin integration represent an underdeveloped service-layer gap where incumbents under-serve facility management contracts. India's smart cities mission offers the most penetrable procurement channel for integrated project management platforms in tier-1 urban clusters. Pursue usage-based pricing models to bypass entrenched perpetual license relationships.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native platform development as subscription models displace hardware-heavy field equipment convergence. Long-term viability favors workflow bundlers with proven interoperability across certified data environments. Target acquisition profiles center on agile specialists with ISO 19650 certification velocity. Watch for inflection when German federal procurement timelines compress further under digitization mandate acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Autodesk anchors premium positioning through design-to-construction workflow bundling for architectural firms. |
| Strategic Partnership | East Asian sensor supply security partnerships defend against semiconductor input volatility for Trimble field equipment. |
| Acquisition of Specialist Firm | Cloud-native engineering talent scarcity drives M&A for full-stack architects capable of ISO 19650 data environment design. |
| Geographic Expansion | India's smart cities mission creates procurement channels for integrated project management platforms in Maharashtra and Karnataka. |
| Product Launch | Wearable biometrics-software bundles capture OSHA-mandated subscription revenue pools on US federally funded sites. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with construction technology executives, BIM implementation leads, federal procurement officers, and systems integration specialists; and secondary validation through SEC filings, EU public procurement databases, ISO certification registries, and national building code repositories. Bottom-up segment sizing triangulated against top-down market envelope checks.
Across the analysis window, forecasts modeled technology deployment patterns, application maturity tiers, end-user procurement authority, and product type margin structures. CAGRs derived from segment-level growth trajectory synthesis incorporating AI adoption curves, regulatory mandate timelines, and infrastructure investment cycles. Construction-specific inputs included federal digitization procurement velocity and ISO 19650 certification penetration rates.
Material uncertainties — semiconductor supply disruptions, regulatory fragmentation across national ISO 19650 variants, and labor substitution technical boundaries — sit outside the modeled envelope. Forecasts reflect assumptions about mandate continuity and certification pathway stability. Revision becomes warranted when East Asian foundry concentration triggers input volatility exceeding historical bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Infrastructure
Smart Hydrants Market
Smart Infrastructure
Infrastructure Solution Integration Service Market
Smart Infrastructure
Smart Pipeline Networks Market
Smart Infrastructure
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market
Smart Infrastructure
Smart Concrete Market
Smart Infrastructure
Smart Airport Construction Market
Smart Infrastructure
US Smart Building Market
Smart Infrastructure
Smart Infrastructure Market
Smart Infrastructure
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market
Smart Infrastructure
Asia-Pacific Smart Building Market
Smart Infrastructure
Global IoT in Construction Market
Smart Infrastructure
IoT in Commercial Construction Market
Smart Infrastructure
Big Data in Construction Market