
 Smart Concrete Market | 2026-2036
Smart Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Concrete Market Outlook
North American ready-mix producers is realigning capacity toward low-carbon and sensor-integrated formulations. BASF SE leverages its chemical additives portfolio to embed self-healing chemistry directly at the batch plant. Sika AG anchors European specification channels through its certified structural monitoring systems. CEMEX competes on geographic scale, operating production networks that span high-growth infrastructure corridors across multiple continents.
Smart concrete denotes cementitious systems engineered with embedded sensing, responsive additives, or nanoscale modifications that autonomously monitor structural health, repair micro-cracks, or adapt to thermal and mechanical loads; typical formulations incorporate piezoelectric sensors, microcapsulated healing agents, or graphene-enhanced matrices achieving compressive strengths exceeding standard Portland blends while reducing embodied carbon. Self-healing concrete commands premium specification in bridge decks where maintenance access is costly, while embedded sensors generate recurring data-service revenue streams beyond material supply. Nanotechnology-enabled formulations remain laboratory-intensive but attract venture allocation from infrastructure funds seeking de-risked asset life extension.
The EPA enforces Buy America provisions on federally funded concrete procurement, tightening domestic content thresholds for smart material components. The EU Green Deal and REACH constrain carbon-intensive binder chemistries, pushing producers toward Seratech-style mineralization and Sublime Systems electrochemical processes. China's MEE and GB standards mandate green building material certification for public projects above specified scale. Stakeholders must track how regulatory divergence across these jurisdictions fragments certification costs and shapes partnership strategies for multi-territory project bids.
Market Dynamics
The convergence of embedded sensing infrastructure with low-carbon binder mandates is compressing procurement timelines for infrastructure agencies while fragmenting certification requirements across jurisdictions.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Civil infrastructure agencies in Germany and France now specify self-healing concrete for bridge rehabilitation projects exceeding defined contract values.
- Sensor-embedded highway corridors:The United States Department of Transportation prioritizes smart concrete for interstate expansion zones requiring real-time structural monitoring.
- China's GB green building certification:Public construction above specified scale thresholds must incorporate certified low-carbon cementitious materials, accelerating batch plant upgrades.
Market Restraints
- Healing agent microcapsule supply concentration:Specialty chemical production for autonomous crack repair concentrates among limited European additive suppliers, creating input bottlenecks.
- Buy America domestic content thresholds:The EPA enforces strict local sourcing requirements for federally funded smart concrete components, complicating cross-border material flows.
- Graphene-enhanced matrix cost structure:Nanoscale carbon additive prices remain prohibitive for standard infrastructure budgets outside premium specification segments.
Strategic Opportunities
- Japan's METI infrastructure resilience targets:Seismic monitoring integration creates specification pathways for piezoelectric sensor networks in public building retrofits.
- Data-service revenue unbundling:Ready-mix producers can separate structural health monitoring subscriptions from material supply contracts, extending customer lifetime value.
- Electrochemical binder mineralization:Emerging low-carbon production processes align with REACH-constrained supply chains in the European Union.
Industry Challenges
- Multi-jurisdiction certification complexity:Producers bidding cross-border projects must reconcile divergent green material standards from China's MEE, the EU's ECHA, and the EPA.
- Embedded sensor integration expertise:Batch plant operators lack technical personnel capable of calibrating piezoelectric systems during concrete mixing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Concrete Market |
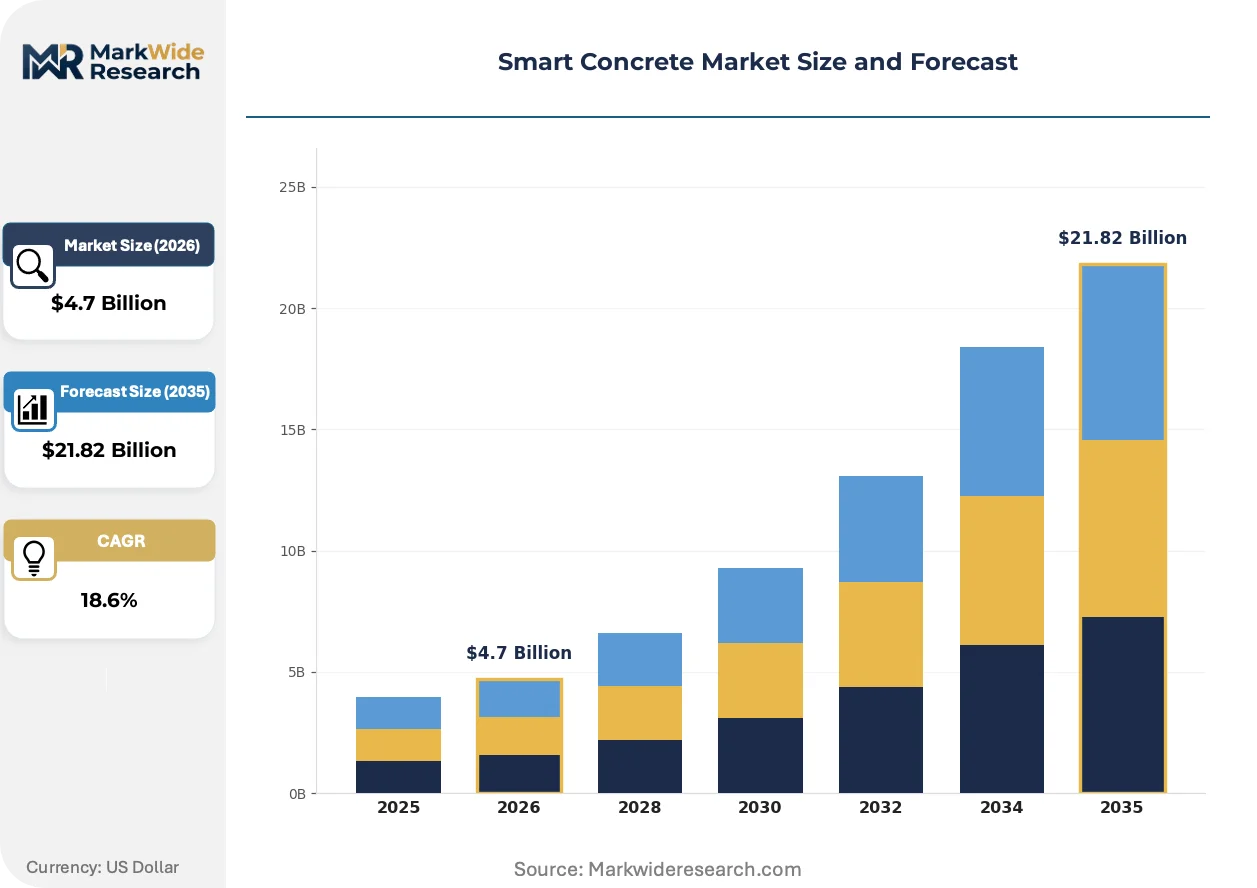
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat-Resistant Concrete, Self-Healing Concrete, High-Performance Concrete, Lightweight Concrete Application: Infrastructure, Residential Construction, Roads, Bridges Technology: Embedded Sensors, Smart Monitoring, Chemical Additives, Nanotechnology End User: Contractors, Manufacturers, Engineers, Architects |
| Companies Covered | CEMEX, Sublime Systems, Sika AG, Carbon Limit, AICrete, BASF SE, MAPEI S.p.A., Seratech, Holcim Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Concrete Market Strategic Shifts
Material science convergence with digital infrastructure is redefining how concrete suppliers capture value beyond commodity delivery, shifting competitive advantage toward integrated sensing and service capabilities.
Self-healing chemistry is integrating directly into ready-mix batching workflows, enabling autonomous micro-crack repair without external intervention. Highway agencies in the United States specify these formulations for bridge decks where maintenance access requires lane closures and traffic disruption. The technology is integrating structural durability guarantees with traditional material supply contracts, compressing procurement evaluation criteria toward life-cycle performance metrics.
The EU Green Deal's embodied carbon thresholds are forcing binder suppliers toward mineralization and electrochemical production pathways that eliminate process emissions. REACH constraints on carbon-intensive chemistries are accelerating pilot deployments of Seratech-style carbon capture in concrete manufacturing. European specification channels now penalize standard Portland cement blends in public tender scoring, advantaging producers with certified low-carbon supply chains.
Infrastructure funds are compressing asset life extension into upfront material selection criteria, prioritizing suppliers offering predictive structural health data. Bridge owners in Germany and Japan now contract separately for sensing hardware, data analytics, and maintenance scheduling rather than purchasing concrete as a standalone commodity. This unbundling is visible most acutely in toll highway concessions where private operators bear full life-cycle cost responsibility.
Smart Concrete Market Segmentation
Smart concrete procurement decisions cascade through multiple technical and commercial dimensions simultaneously. Infrastructure agencies evaluate formulations against structural performance requirements while contractors weigh batch plant integration complexity against life-cycle cost guarantees.
Product Type:
Bridge rehabilitation cycles and highway expansion timelines are compressing specification windows for next-generation formulations.
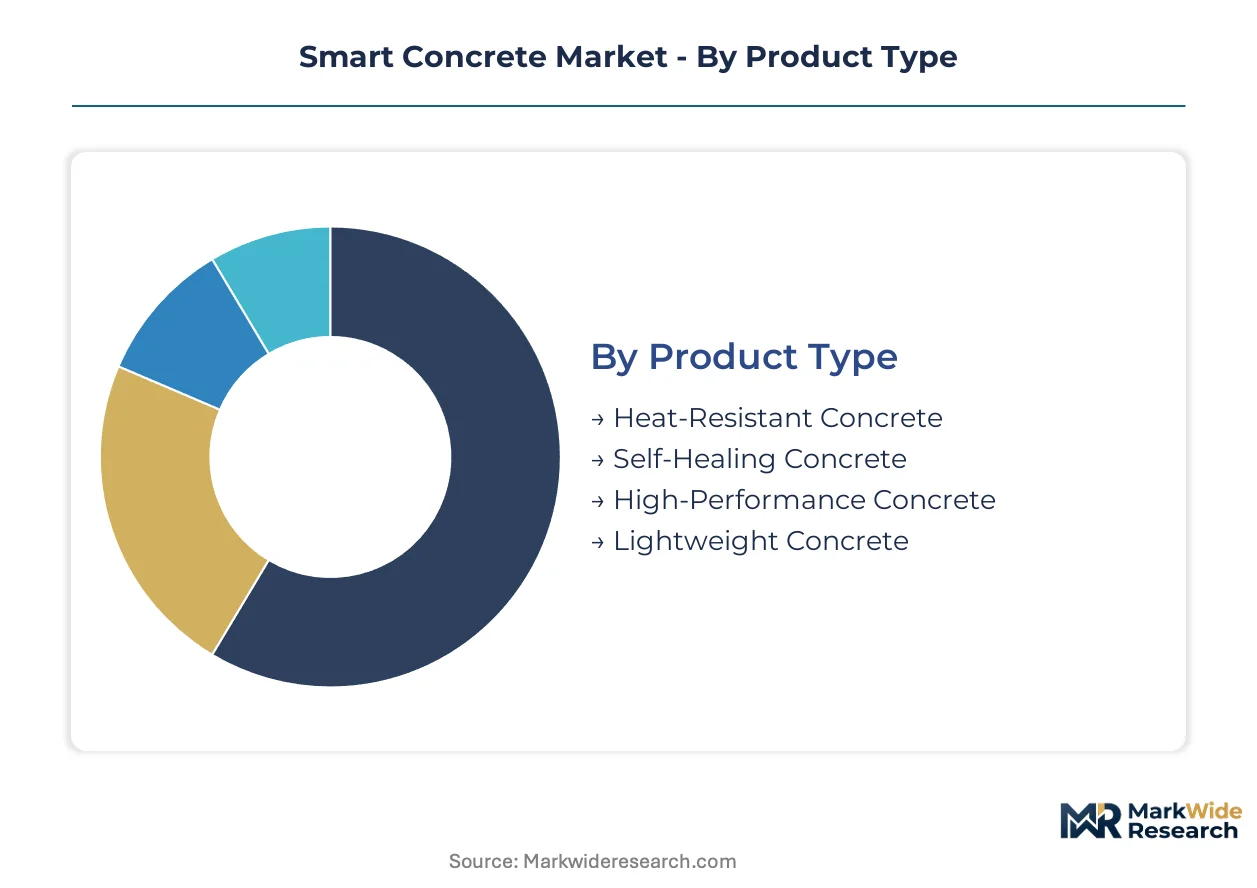
- Self-Healing Concrete:Microcapsulated healing agents autonomously seal micro-cracks through bacterial or chemical activation. German civil infrastructure agencies specify this formulation for bridge decks where maintenance access triggers traffic disruption penalties.
- High-Performance Concrete:Engineered matrices achieve compressive strengths exceeding standard Portland blends through optimized particle packing and supplementary cementitious materials. Japan's METI resilience targets are accelerating specification for seismic-critical public building retrofits in Tokyo and Osaka corridors.
- Heat-Resistant Concrete:Specialized binder systems maintain structural integrity under thermal cycling stress. Industrial furnace foundations and tunnel linings represent primary demand concentration.
- Lightweight Concrete:Cellular or aggregate-modified formulations reduce dead loads in high-rise structural elements. Mid-rise residential towers in dense urban cores are adopting these systems for foundation load reduction.
High-performance concrete sits at the top of the volume ranking, with self-healing concrete climbing the fastest.
Application:
Project scale thresholds and maintenance access economics are fragmenting demand across construction verticals.
- Infrastructure:Federal and state procurement channels dominate volume, with embedded sensor mandates compressing evaluation criteria toward predictive performance metrics. United States Department of Transportation specifications now require real-time structural monitoring for interstate expansion corridors exceeding defined contract values.
- Bridges:Self-healing formulations command premium specification where lane closure costs outweigh material price differentials. German and French civil engineering standards are converging on autonomous crack repair requirements for rehabilitation contracts.
- Roads:Highway agencies prioritize sensor-embedded pavement sections for traffic load monitoring and predictive maintenance scheduling.
- Residential Construction:Green building certification requirements in China's urban centers are accelerating low-carbon binder adoption for public housing above specified scale thresholds.
Infrastructure captures the dominant procurement volume, while bridge applications are expanding most quickly.
Technology:
Integration complexity at the batch plant level is stratifying competitive capability across technical approaches.
- Embedded Sensors:Piezoelectric and fiber-optic networks enable real-time strain, temperature, and corrosion monitoring. Toll highway operators in Germany and Japan are unbundling data-service subscriptions from material supply contracts.
- Chemical Additives:Self-healing agents and rheology modifiers integrate directly into ready-mix workflows without specialized equipment. BASF and Sika are anchoring specification channels through certified additive supply agreements.
- Smart Monitoring:Cloud-connected analytics platforms transform raw sensor data into predictive maintenance schedules. Infrastructure funds are compressing asset life extension into upfront material selection criteria.
- Nanotechnology:Graphene-enhanced matrices achieve exceptional mechanical properties at prohibitive cost structures. Laboratory-intensive development attracts venture allocation but remains confined to premium demonstration projects.
Chemical additives command the highest procurement volume, with embedded sensors gaining share fastest.
End User:
Technical specification authority and procurement execution responsibility are diverging across project stakeholder structures.
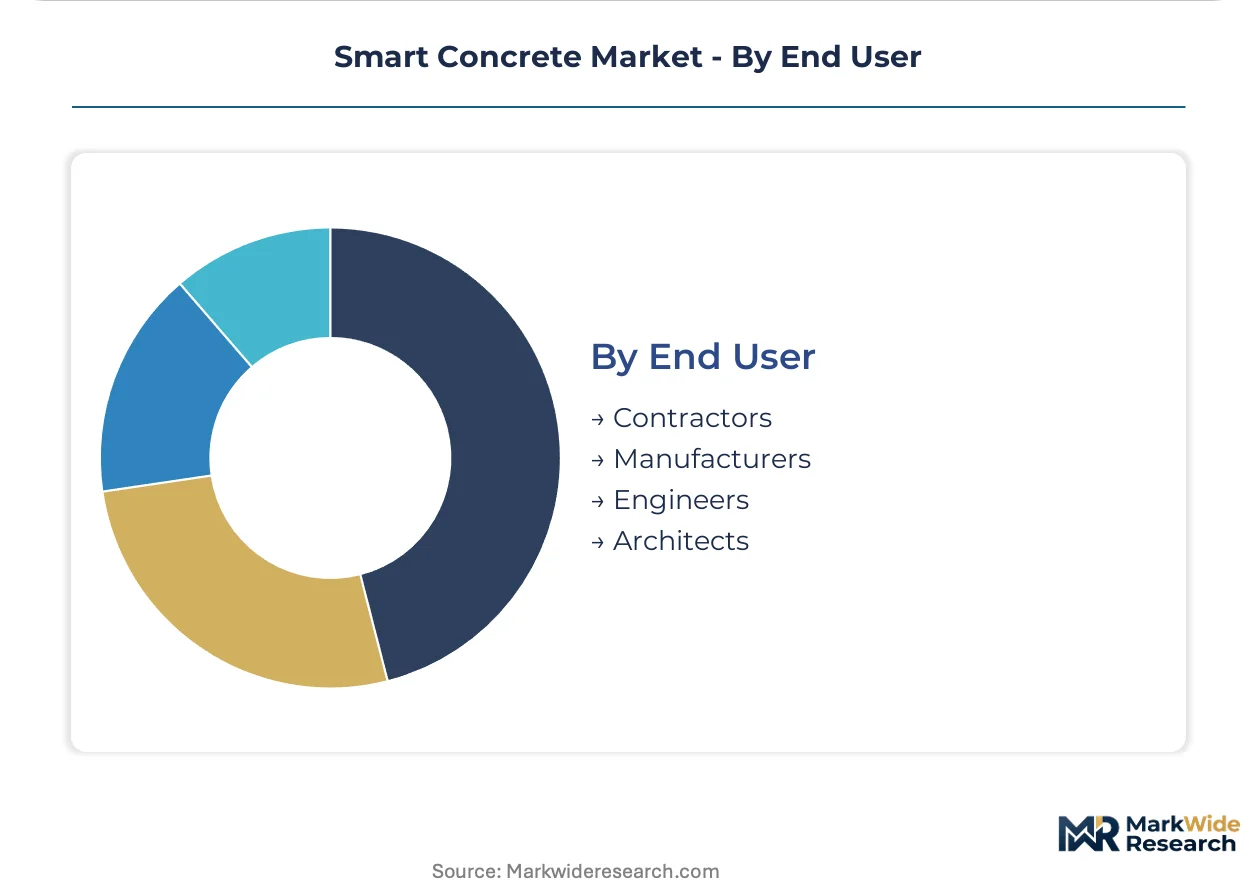
- Contractors:Ready-mix producers and construction firms execute batch plant integration and field placement. North American producers are realigning capacity toward sensor-integrated and low-carbon formulations.
- Engineers:Structural design consultants specify performance requirements and certification standards. Multi-jurisdiction project bids require reconciliation of EPA, EU ECHA, and China MEE green material criteria.
- Architects:Building envelope and aesthetic integration drive specification for exposed concrete finishes in high-visibility structures.
- Manufacturers:Precast concrete producers integrate smart formulations into standardized structural components for repetitive deployment.
Contractors anchor procurement execution volume, with engineers driving the steepest expansion trajectory through tightened specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German civil infrastructure agencies specify self-healing concrete for bridge rehabilitation at higher contract values than their French counterparts, while Japanese METI resilience targets accelerate seismic monitoring integration faster than comparable programs in South Korea.
United States
Federal highway expansion corridors and bridge deck rehabilitation cycles drive procurement volume for sensor-embedded formulations. The EPA enforces Buy America domestic content thresholds on federally funded smart concrete components. Texas and California infrastructure agencies lead specification adoption for real-time structural monitoring systems.
Germany
Bridge maintenance access economics and traffic disruption penalties prioritize autonomous crack repair specifications. The EU Green Deal embodied carbon thresholds compress timelines for low-carbon binder adoption. The Rhine-Ruhr industrial corridor concentrates batch plant upgrades toward certified green material production.
China
Urban public housing construction above scale thresholds mandates certified low-carbon cementitious materials. The MEE and GB standards on green building materials accelerate batch plant certification requirements. The Yangtze River Delta region leads infrastructure investment in smart concrete for highway and bridge applications.
Japan
Seismic-critical public building retrofits in dense urban corridors drive piezoelectric sensor network demand. METI infrastructure resilience targets create specification pathways for structural health monitoring integration. The Tokyo-Osaka corridor concentrates procurement for high-performance concrete in seismic retrofit programs.
United Arab Emirates
Large-scale infrastructure concessions and toll highway developments prioritize life-cycle cost guarantees over upfront material pricing. Green building certification requirements for public projects above specified scales accelerate low-carbon binder evaluation. Dubai and Abu Dhabi infrastructure agencies lead specification trials for heat-resistant and sensor-embedded formulations.
Smart Concrete Market Competitive Environment
European producers anchor one tier; North American specialists hold another through differentiated regulatory positioning. The vendor base stratifies across three structural tiers: multinational chemical conglomerates with certified additive portfolios, regional ready-mix producers with sensor integration capabilities, and venture-backed electrochemical process developers. Strategic moves concentrate on batch plant partnership networks and data-service revenue unbundling from material supply contracts.
Within the multinational chemical tier, BASF SE and Sika AG occupy positions as specification anchors through certified additive supply agreements. CEMEX represents the geographic scale archetype, with production networks spanning multiple high-growth infrastructure corridors. Sublime Systems and Seratech exemplify the emerging process technology segment, attracting infrastructure fund allocation toward de-risked electrochemical and mineralization pathways. These players collectively illustrate how competitive advantage shifts toward integrated sensing capabilities and low-carbon certification authority rather than commodity volume alone.
| Leading Market Players |
|---|
| CEMEX |
| Sublime Systems |
| Sika AG |
| Carbon Limit |
| AICrete |
| BASF SE |
| MAPEI S.p.A. |
| Seratech |
| Holcim Ltd |
| Others |
Value Chain & Pricing Dynamics
Federal Buy America mandates on U.S. highway procurement are forcing ready-mix producers to re-source sensor components domestically, compressing channel margins and fragmenting pricing power across certification tiers.
Pricing Analysis
Channel margins concentrate at the specification-anchor tier, where certified additive suppliers capture 15-20 point premiums over commodity batch-plant pricing. Three-tier pricing structure across premium certified, standard performance, and economy-grade formulations reflects divergence in green-material certification levels and embedded sensor bundling. Cost compression in the standard tier is intensifying because European REACH compliance adds certification overhead that North American producers avoid. Municipal infrastructure agencies exhibit highest price sensitivity due to fixed-budget procurement cycles, while toll-highway operators show lowest sensitivity given life-cycle cost accounting frameworks.
Supply Chain Analysis
EPA and EU Green Deal domestic-content thresholds are reshaping sourcing patterns for piezoelectric sensors and microencapsulated healing agents. Manufacturing concentrates in Germany, China, and the United States for specialized additives, with sensor assembly anchored in Japan and South Korea. Raw material dependencies rest on graphene nanoplatelets, bacterial healing precursors, and fiber-optic strain cables. Single-source vulnerability runs through European specialty chemical suppliers for autonomous crack-repair formulations. Distribution feeds through certified batch-plant networks rather than traditional building-material wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in smart concrete rests on electrochemical binder mineralization driving 30-40% production cost reduction against Portland cement baselines, while data-service unbundling shifts revenue mix toward recurring high-margin subscriptions.
For Market Incumbents: To counter venture-backed electrochemical entrants like Sublime Systems and Seratech, established producers must deepen backward integration into carbon-capture mineralization feedstocks and lock exclusive batch-plant certification partnerships across the Rhine-Ruhr and Texas-California corridors. Control over specification-channel relationships with state DOTs and EU Green Deal procurement officers remains the critical defensive lever. For New Entrants and Emerging Players: Mid-size Japanese general contractors represent the most penetrable buyer archetype given METI seismic-monitoring mandates and limited domestic sensor-integration capabilities. White-space targets include piezoelectric calibration services for batch-plant operators and low-carbon binder supply to China's Yangtze River Delta public housing developers. A certification-first go-to-market angle—securing EU ECHA and China MEE green-material credentials before volume scaling—accelerates specification access. For Investors and Strategic Acquirers: Asymmetric upside sits with electrochemical process developers holding pilot-scale validation and offtake agreements with infrastructure funds seeking de-risked asset life extension. Long-term viability favors players integrating sensing hardware, data analytics platforms, and material supply into unified service contracts. Watch for inflection when German or Japanese civil agencies mandate real-time structural monitoring as default procurement specification rather than optional add-on.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon-Capture Feedstocks | Seratech-style mineralization secures EU Green Deal compliance advantage against Portland cement competitors. |
| Data-Service Revenue Unbundling | Toll-highway operators in Germany and Japan now contract structural health monitoring separately from material supply. |
| Batch-Plant Certification Partnerships | Exclusive agreements with CEMEX and Holcim lock specification channels across North American infrastructure corridors. |
| Electrochemical Production Scale-Up | Sublime Systems' pilot deployments demonstrate REACH-aligned pathways eliminating process emissions from binder manufacturing. |
| Sensor-Integration Capability Acquisition | Sika AG's structural monitoring systems anchor European specification channels through certified additive supply agreements. |
Study Parameters
Coverage spans Germany, Japan, the United States, China, and the United Arab Emirates, with primary inputs from each market combining interviews with ready-mix plant managers, civil infrastructure procurement officers, structural engineering consultants, and electrochemical process developers. Secondary validation draws from EPA procurement filings, EU ECHA substance registrations, China MEE green-building certification databases, and Japan METI infrastructure resilience program disclosures. Bottom-up volume modeling triangulates against top-down spending projections from infrastructure fund allocation data.
Granularity-level modeling extends to product-type splits across self-healing, high-performance, heat-resistant, and lightweight formulations; application segmentation across infrastructure, bridges, roads, and residential construction; technology tiers spanning embedded sensors, chemical additives, smart monitoring platforms, and nanotechnology; and end-user categories covering contractors, engineers, architects, and manufacturers. CAGRs derive from regression analysis against historical procurement volumes and projected infrastructure spending corridors. Industry-specific forecast inputs include EU Green Deal embodied-carbon threshold implementation timelines and U.S. DOT sensor-embedment mandate adoption curves.
Underlying measurement precision varies by segment; self-healing concrete and embedded sensor applications carry tighter precision than nanotechnology-enabled formulations given earlier-stage commercial deployment. Forecasts reflect assumptions around regulatory enforcement consistency, supply-chain input cost stability, and infrastructure fund allocation continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Infrastructure
Smart Hydrants Market
Smart Infrastructure
IoT in Commercial Construction Market
Smart Infrastructure
US Smart Building Market
Smart Infrastructure
Construction 4.0 Market
Smart Infrastructure
Global IoT in Construction Market
Smart Infrastructure
Asia-Pacific Smart Building Market
Smart Infrastructure
Infrastructure Solution Integration Service Market
Smart Infrastructure
Smart Infrastructure Market
Smart Infrastructure
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market
Smart Infrastructure
Big Data in Construction Market
Smart Infrastructure
Smart Pipeline Networks Market
Smart Infrastructure
Smart Airport Construction Market
Smart Infrastructure
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market