
 Smart Hydrants Market | 2026-2036
Smart Hydrants Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Hydrants Market Insights
Multi-source component procurement is repositioning how smart hydrant manufacturers secure pressure sensors and telemetry modules. Mueller Systems leverages in-house foundry capacity to control casting quality for hydrant bodies. Hawle sustains European market presence through specialized flange designs and regional certification depth. Aquam competes on retrofit-focused installation kits that reduce civil works for utility deployments.
Smart hydrants are pressure-rated valve assemblies equipped with IoT sensors, wireless telemetry, and cloud-connected data layers that monitor flow status, pressure anomalies, and tamper events in real time. Cellular connected units command premium positioning due to wide-area coverage without gateway dependency, while solar powered variants address rural and backup-power scenarios where grid reliability is constrained. Water management applications lead current deployment volumes as utilities prioritize non-revenue water reduction, though fire protection segments show faster growth curves where real-time pressure verification supports insurance and liability frameworks.
EPA regulations on water system resilience, FCC Part 15 rules for unlicensed radio devices, and AWWA standards for hydrant performance collectively shape product certification requirements and procurement eligibility. The FCC governs spectrum use for cellular and Bluetooth telemetry modules embedded in smart hydrant communications stacks. Stakeholders must monitor evolving cybersecurity mandates for critical water infrastructure as federal agencies harden IoT device requirements.
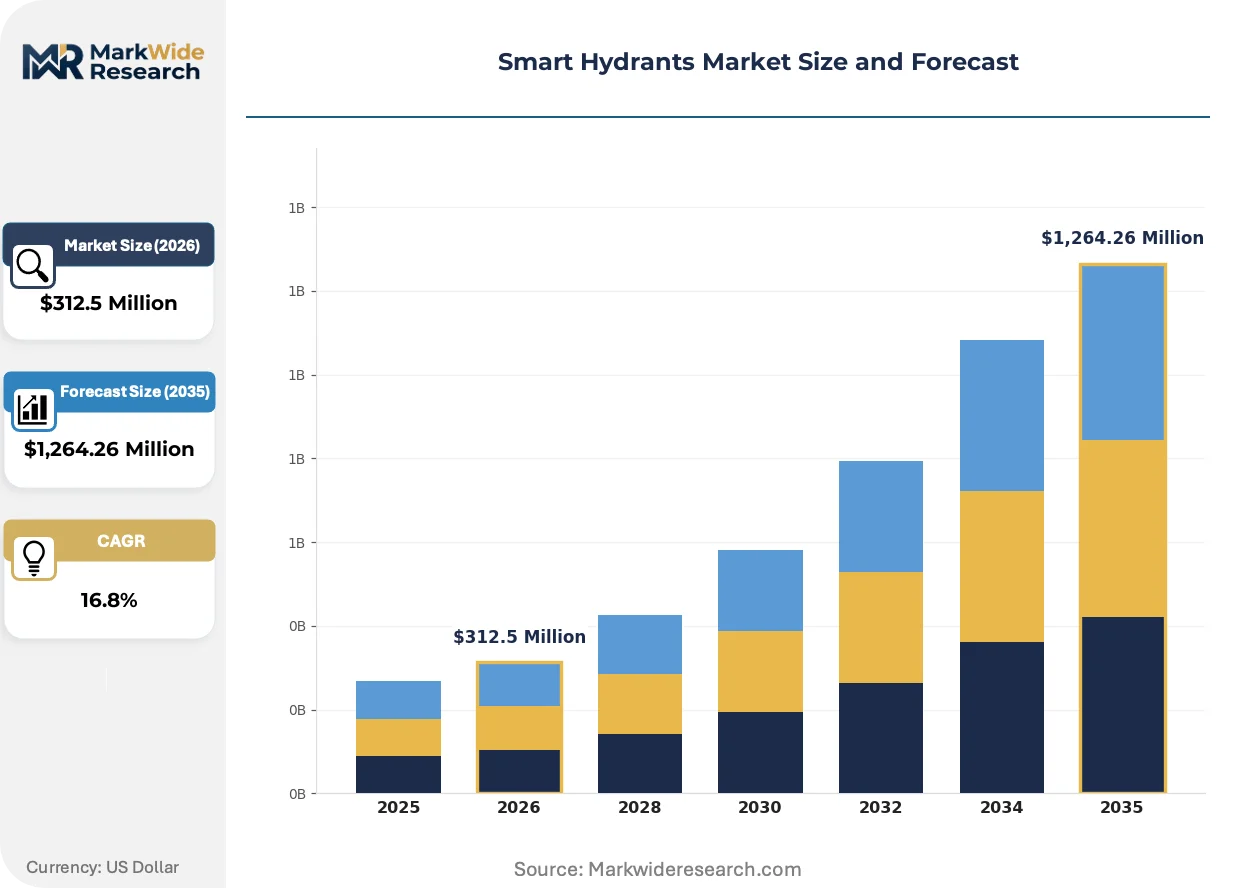
Market Dynamics
Water utilities face simultaneous pressure from EPA lead and copper rule compliance deadlines and AMI infrastructure mandates, forcing synchronized capital deployment across telemetry-enabled hydrant networks and legacy pipe replacement programs.
Growth Catalysts
- EPA Lead and Copper Rule Revisions:Utilities in California, Texas, and Florida accelerate smart hydrant procurement to meet sampling point density requirements and real-time contamination monitoring mandates.
- Non-Revenue Water Reduction Targets:Pressure anomaly detection through IoT-enabled valve assemblies allows utilities to pinpoint distribution losses before they surface as customer complaints or infrastructure damage.
- Cellular Module Cost Compression:Wide-area telemetry without gateway dependency now matches the installed cost of mesh-network alternatives, removing a key adoption barrier for rural and suburban deployments.
Market Restraints
- Bronze and Ductile Iron Input Volatility:Foundry-grade metal pricing swings compress margin visibility for hydrant body manufacturers dependent on spot market purchasing.
- Telemetry Module Supply Concentration:Cellular modem and pressure sensor sourcing clusters in East Asian contract manufacturers expose lead time vulnerability for North American assembly operations.
- Legacy Thread Standard Lock-In:AWWA C502 mechanical compatibility requirements constrain rapid design iteration for smart variants seeking to differentiate on sensor integration density.
Strategic Opportunities
- Fire Protection Insurance Verification:Real-time pressure certification from connected hydrants supports liability frameworks where property underwriters demand documented system readiness.
- Solar-Powered Rural Deployment:Off-grid telemetry variants unlock municipal budgets in grid-constrained regions where trenching for power connectivity exceeds hardware costs.
- Retrofit Installation Kit Standardization:Reduced civil works requirements position aftermarket conversion as a faster path to smart infrastructure than full asset replacement cycles.
Industry Challenges
- Cybersecurity Certification Timeline:Federal IoT device hardening mandates for critical water infrastructure extend product validation cycles before procurement eligibility.
- Pressure Sensor Calibration Drift:Field-deployed IoT assemblies require recalibration protocols that utilities lack internal competency to execute without vendor dependency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Hydrants Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $1,264.26 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wi-Fi Connected, Cellular Connected, Bluetooth Enabled, Solar Powered End User: Municipalities, Fire Departments, Water Utilities, Emergency Services Technology: IoT Integration, Remote Monitoring, Data Analytics, Cloud Computing Application: Fire Protection, Water Management, Infrastructure Monitoring, Urban Planning |
| Companies Covered | Mueller Systems, Hawle, Aquam, Silversmith Data, Hangzhou Zhibin, Zhejiang Kelong, Hanwei Electronics, Meter Instruments, Guizhou Zhianda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Hydrants Market Trends and Innovations
Telemetry architecture choices are compressing competitive differentiation around power autonomy, wireless protocol selection, and cloud platform interoperability rather than mechanical hydrant design alone.
Cellular-connected telemetry stacks is overtaking mesh-network alternatives in utility procurement specifications. Water districts in drought-stressed regions prioritize wide-area coverage without gateway infrastructure. The shift compresses vendor differentiation toward data platform integration rather than radio hardware performance.
EPA cybersecurity mandates for critical infrastructure IoT devices are tightening device authentication and firmware update requirements. Manufacturers face extended certification timelines before federal procurement eligibility. California utilities are responding by inserting cybersecurity audit clauses into RFP technical specifications ahead of formal federal rule finalization.
Subscription-based data platform licensing is displacing perpetual hardware-and-software bundles in municipal procurement. Water districts prefer operational expenditure treatment for analytics layers while retaining capital classification for physical assets. Texas and Florida municipalities lead this preference shift due to bond capacity constraints and rate-case timing pressures.
Smart Hydrants Market Segmentation
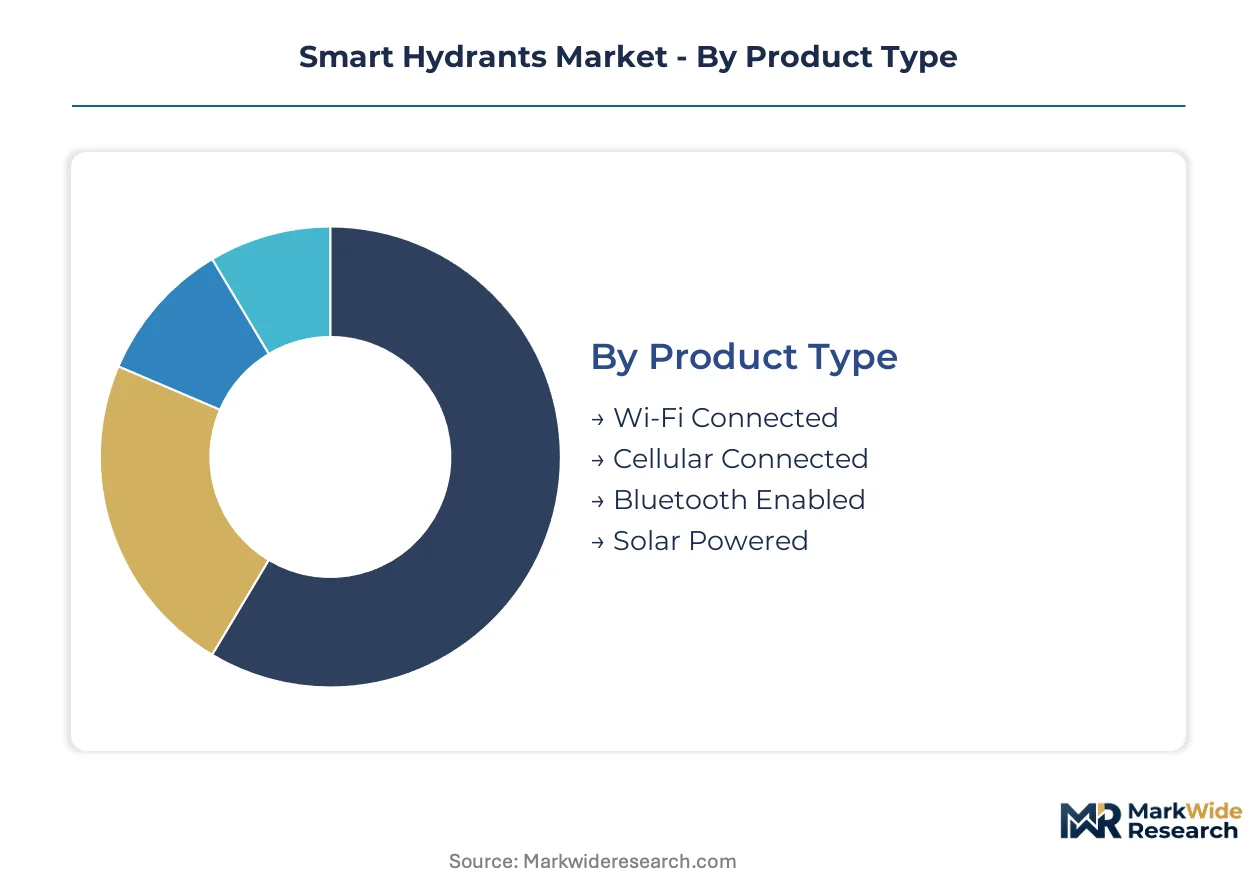
Smart hydrant procurement patterns diverge sharply across connectivity architectures and operational mandates. Capital allocation priorities differ between utilities optimizing for non-revenue water reduction and fire departments seeking real-time pressure verification for liability coverage.
Product Type:
Cellular-connected variants demand the highest upfront capital outlay due to embedded modem hardware and recurring carrier subscription obligations.
- Cellular Connected:Wide-area telemetry modules eliminate gateway infrastructure requirements. Water utilities in California and Texas prioritize these units for rural distribution networks where mesh deployment costs exceed hardware premiums.
- Solar Powered:Photovoltaic arrays with battery backup enable off-grid operation in grid-constrained municipalities. Florida counties facing hurricane-season power reliability issues are expanding procurement of these autonomous units.
- Wi-Fi Connected:Short-range protocols suit dense urban deployments with existing municipal fiber backbones.
- Bluetooth Enabled:Proximity-based commissioning and maintenance access reduces field technician data costs.
Cellular-connected units absorb the bulk of installed capacity; solar-powered variants are expanding most quickly in disaster-prone regions.
End User:
Procurement authority fragmentation shapes specification requirements across distinct operational hierarchies.
- Water Utilities:Distribution network operators prioritize pressure anomaly detection and leak localization capabilities. AMI infrastructure mandates from state public utility commissions are accelerating replacement cycles for these buyers.
- Municipalities:General-purpose procurement offices balance fire protection compliance with water conservation targets. Budget constraints favor retrofit installation kits over full asset replacement.
- Fire Departments:Emergency response agencies demand documented pressure certification for insurance liability frameworks.
- Emergency Services:Cross-agency coordination units require interoperable data platforms for disaster response scenarios.
Water utilities command the largest procurement volumes; fire departments are gaining specification influence through insurance underwriting requirements.
Technology:
Integration depth determines recurring revenue potential for platform vendors beyond initial hardware sales.
- IoT Integration:Embedded sensor arrays combining pressure, flow, and tamper detection into unified telemetry stacks. EPA cybersecurity mandates for critical infrastructure are extending validation timelines for these complex assemblies.
- Data Analytics:Predictive algorithms processing historical pressure patterns to flag incipient main breaks. Subscription licensing models are displacing perpetual software bundles in municipal procurement.
- Remote Monitoring:Cloud-dashboard accessibility for field operations without specialized technician dispatch.
- Cloud Computing:Scalable data storage architectures supporting multi-year trend analysis and regulatory reporting.
IoT integration layers anchor current deployment economics; data analytics subscriptions are climbing the fastest as utilities shift toward operational expenditure treatment.
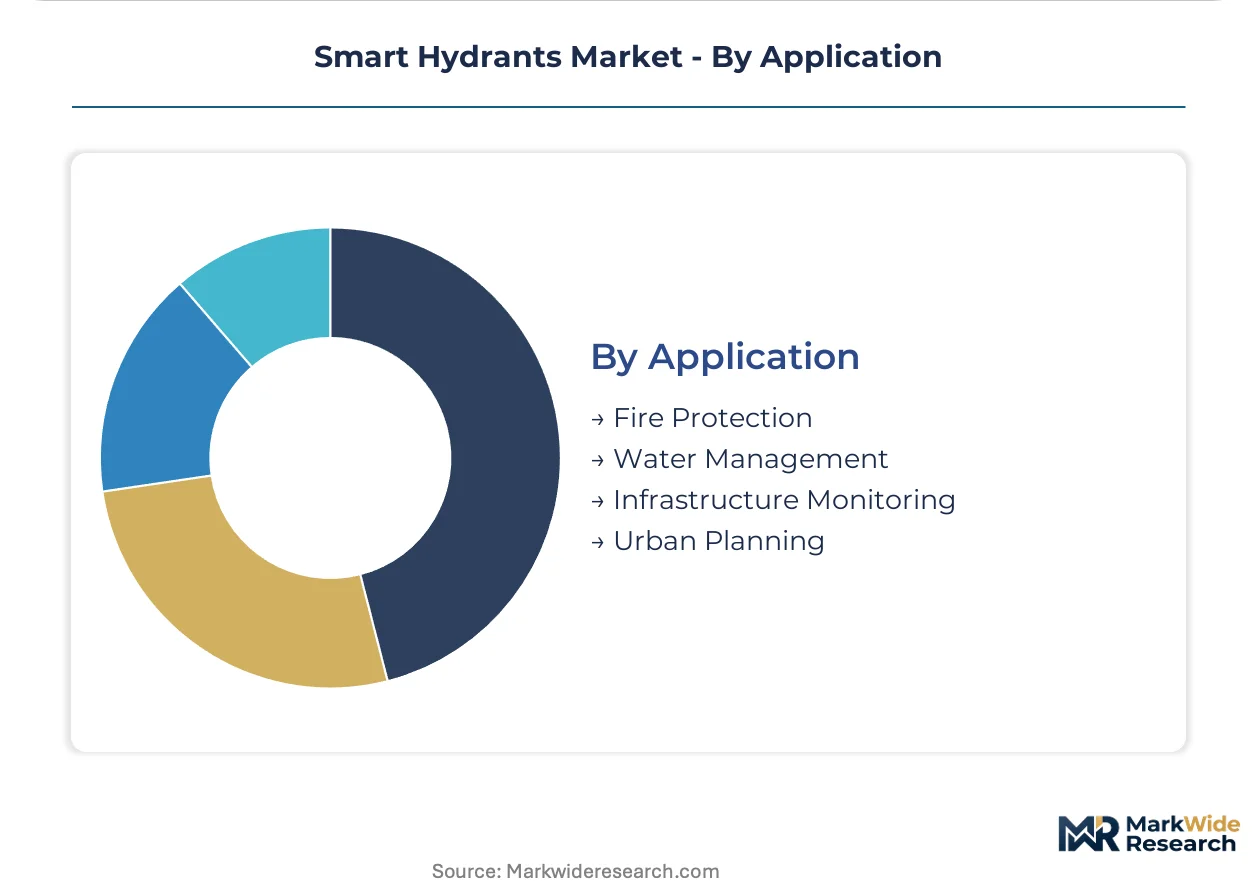
Application:
Functional use cases dictate sensor density, telemetry frequency, and certification requirements.
- Water Management:Non-revenue water reduction programs leverage continuous pressure monitoring to pinpoint distribution losses. California drought-stressed districts are mandating minimum telemetry coverage percentages for rate-case approval.
- Fire Protection:Real-time pressure verification supports property underwriter documentation requirements. Texas municipalities face accelerating insurance audit frequency driving specification upgrades.
- Infrastructure Monitoring:Structural health assessment for aging distribution networks approaching replacement horizons.
- Urban Planning:Development impact studies utilizing historical flow data for capacity planning.
Water management applications dominate current installed base; fire protection segments are gaining share fastest through liability framework tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bronze and ductile iron foundry capacity concentrates in the United States, Germany, and China, anchoring smart hydrant manufacturing clusters near raw material sources and major utility procurement centers.
United States
California utilities deploy cellular-connected hydrants under drought-mandated telemetry coverage rules, while Texas municipalities face accelerating fire protection insurance audits. EPA lead and copper rule revisions drive sampling point density requirements. Houston and Dallas-Fort Worth clusters concentrate retrofit installation activity for aging distribution networks.
Germany
Industrial water districts prioritize pressure anomaly detection for non-revenue water programs in the Ruhr and Rhine-Ruhr metropolitan regions. REACH chemical compliance and CE marking requirements shape sensor module certification timelines. Bavaria-based manufacturers supply specialized flange designs for European utility specifications.
China
MIIT standards for IoT device interoperability accelerate domestic smart hydrant deployment in Yangtze River Delta water districts. Dual carbon goals pressure municipalities to reduce distribution losses through real-time monitoring. Zhejiang and Jiangsu provinces concentrate pressure sensor and telemetry module contract manufacturing.
Japan
Tokyo and Osaka metropolitan water bureaus upgrade legacy hydrant networks under METI infrastructure resilience directives. JIS standards for valve performance constrain rapid design iteration for smart variants. Kansai region utilities pilot solar-powered telemetry for earthquake-preparedness scenarios.
United Kingdom
Thames Water and United Utilities deploy AMI-integrated hydrants under Ofwat performance commitment frameworks. GDPR compliance requirements shape cloud platform data handling specifications. Midlands engineering clusters supply casting components for European hydrant assemblers.
Smart Hydrants Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to control telemetry module supply and secure utility data platform contracts. The vendor base stratifies across three tiers: integrated foundry-to-cloud providers, sensor-telemetry specialists, and regional mechanical fabricators. Two strategic archetypes have emerged: backward-integrated foundry operators controlling casting quality, and retrofit-focused kit assemblers minimizing civil works. M&A activity and technology licensing deals represent the dominant competitive moves as players address cybersecurity certification bottlenecks.
Among North American integrated providers, Mueller Systems exemplifies the foundry-control archetype through in-house casting capacity, while Aquam occupies a position within the retrofit-specialist tier focused on reduced-civil-works installation. Hawle represents the European certification-depth archetype, anchoring regional market presence through specialized mechanical designs. Chinese fabricators including Hangzhou Zhibin and Zhejiang Kelong sit within the component-supply tier, serving pressure sensor and telemetry module demand for global assembly operations.
| Leading Market Players |
|---|
| Mueller Systems |
| Hawle |
| Aquam |
| Silversmith Data |
| Hangzhou Zhibin |
| Zhejiang Kelong |
| Hanwei Electronics |
| Meter Instruments |
| Guizhou Zhianda |
| Others |
Pricing and Supply Chain Analysis
Municipal water utilities in California, Texas, and Florida concentrate procurement authority and favor subscription-based data platform licensing over perpetual hardware bundles. This buyer archetype preference compresses upfront capital outlays while embedding recurring telemetry costs into operational budgets, reshaping how manufacturers structure pricing across product lifecycles.
Pricing Analysis
Warranty and field service bundling separate premium cellular-connected hydrants from unbundled retrofit kit alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with EPA cybersecurity-compliant units commanding sustained premiums. Pricing pressure stems from bronze and ductile iron input volatility squeezing foundry margins. Municipal procurement offices exhibit highest price sensitivity; fire departments demonstrate lowest sensitivity due to insurance liability documentation requirements.
Supply Chain Analysis
Dual-sourcing mandates from North American utilities pressure assembly operations to qualify secondary suppliers for cellular modems and pressure sensors. Manufacturing draws from foundry capacity in the United States, Germany, and China, with Zhejiang and Jiangsu provinces anchoring telemetry module contract production. Raw material dependencies center on foundry-grade bronze, ductile iron, and lithium-ion battery cells. Single-source vulnerability in East Asian sensor manufacturing exposes lead time risk. Distribution runs through direct municipal procurement channels and specialized water infrastructure distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
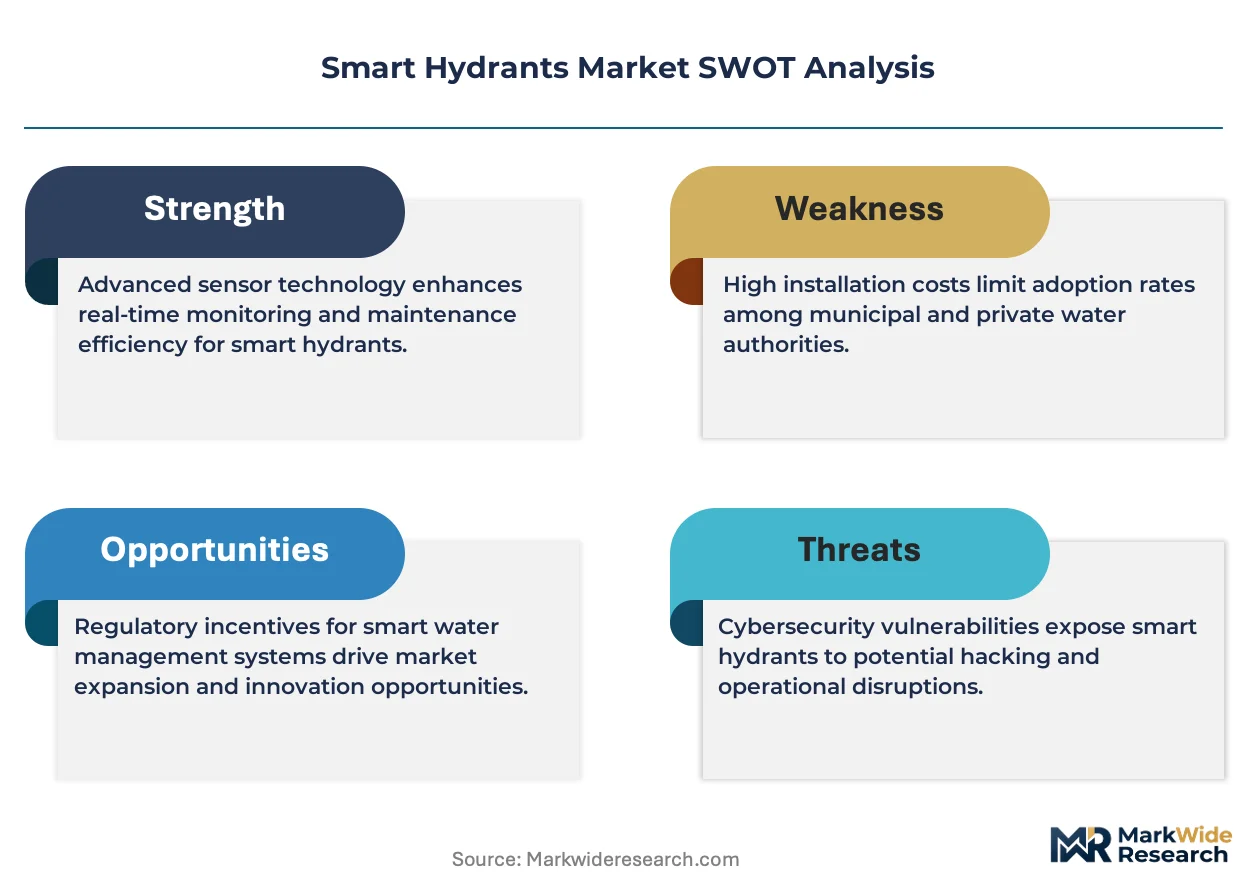
The smart hydrants market sits in a technology-transition phase as cellular-connected telemetry stacks displace mesh-network alternatives. Legacy mechanical hydrant manufacturers face compressed differentiation windows unless they secure cloud platform integration capabilities.
For Market Incumbents: Lock in foundry-to-cloud integration by acquiring telemetry module specialists or licensing data platform technology. Secure EPA cybersecurity certification ahead of federal procurement eligibility deadlines. Backward integration into pressure sensor sourcing mitigates East Asian supply concentration risk.
For New Entrants and Emerging Players: Direct-to-utility SaaS platforms offer the fastest penetration route for software-native entrants lacking mechanical fabrication heritage. Target fire protection insurance verification segments where real-time pressure certification commands premium positioning. Lead with retrofit installation kits minimizing civil works for municipal buyers with constrained capital budgets.
For Investors and Strategic Acquirers: The window for entry favors data platform specialists with existing utility cloud contracts over pure hardware fabricators. Long-term viability hinges on recurring revenue attachment rates rather than unit shipment volumes. Watch for EPA cybersecurity rule finalization as inflection indicator for procurement eligibility consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | EPA compliance timelines determine federal procurement eligibility for IoT-enabled hydrant assemblies. |
| Telemetry Module Supply Agreement | Dual-sourcing cellular modems from East Asian contract manufacturers reduces lead time vulnerability. |
| Retrofit Installation Kit Development | Reduced civil works requirements accelerate municipal deployment cycles for aging infrastructure upgrades. |
| Data Platform Integration Partnership | Cloud-dashboard interoperability supports subscription licensing models displacing perpetual hardware bundles. |
| Solar-Powered Product Line Expansion | Off-grid telemetry variants unlock municipal budgets in hurricane-prone Florida counties and rural Texas districts. |
Research Methodology
Independent corroboration across utility procurement officers, foundry operations managers, and telemetry module engineers underwrites the qualitative findings. Primary interviews with water district planning directors, fire department equipment specifications leads, and municipal bond counsel supplemented secondary validation through EPA regulatory filings, AWWA technical standards, FCC Part 15 equipment authorization databases, and state public utility commission AMI infrastructure orders. Bottom-up unit deployment estimates triangulated against top-down municipal capital expenditure projections.
Rate-of-change decomposition across connectivity architecture, end-user procurement authority, and technology integration depth structured the analytical framework. Segmentation dimensions modeled include product type, end user hierarchy, technology layer, and application mandate across the analysis window. CAGRs derived from utility replacement cycle timing, EPA compliance deadline clustering, and cellular module cost compression trajectories. Forecast inputs incorporated drought-stressed district telemetry coverage mandates and fire protection insurance audit frequency trends.
The model holds under stable EPA regulatory timelines and continued cellular carrier subscription pricing; deviation in bronze and ductile iron commodity volatility or East Asian supply chain disruption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Infrastructure
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market
Smart Infrastructure
Smart Concrete Market
Smart Infrastructure
Infrastructure Solution Integration Service Market
Smart Infrastructure
Smart Airport Construction Market
Smart Infrastructure
Big Data in Construction Market
Smart Infrastructure
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market
Smart Infrastructure
Smart Pipeline Networks Market
Smart Infrastructure
US Smart Building Market
Smart Infrastructure
Construction 4.0 Market
Smart Infrastructure
Global IoT in Construction Market
Smart Infrastructure
Smart Infrastructure Market
Smart Infrastructure
Asia-Pacific Smart Building Market
Smart Infrastructure
IoT in Commercial Construction Market