
 Smart Infrastructure Market | 2026-2036
Smart Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Infrastructure Market Intelligence
Utility sector procurement is shifting toward integrated grid-edge intelligence as power distributors seek real-time load balancing and predictive maintenance capabilities. Siemens leverages deep domain expertise in energy automation to anchor European utility modernization programs. Honeywell International competes across building automation and fire-safety integration, while Schneider Electric specializes in microgrid controllers and distributed energy resource management systems for industrial campuses.
Smart infrastructure encompasses digitally networked physical systems that embed sensors, edge computing nodes, and communication protocols to enable autonomous monitoring, control, and optimization of civil assets. These systems typically operate on sub-100-millisecond latency thresholds for critical control loops and rely on redundant fiber or licensed-spectrum wireless backbones to ensure operational continuity in transportation, energy, and built-environment applications. Smart Buildings applications command substantial current deployment value as owners pursue net-zero operational targets, though Smart Grids infrastructure is expanding fastest where regulators mandate renewable interconnection standards. IoT technology layers form the foundational connectivity substrate, while AI analytics concentrate margin pools in predictive asset management and automated demand-response orchestration.
The Federal Energy Regulatory Commission shapes US market access through interconnection reliability standards, while the EU AI Act imposes risk-classification requirements on autonomous infrastructure decision systems. Germany's Federal Network Agency and Japan's Ministry of Economy, Trade and Industry enforce divergent cybersecurity certification regimes that fragment vendor compliance burdens. Stakeholders must weigh regulatory divergence against scale economies when selecting architecture standards and partnership structures for multi-jurisdiction deployment portfolios.
Market Dynamics
Municipal budget pressures are compressing procurement cycles for intelligent traffic and grid systems, forcing vendors to pre-integrate hardware-software bundles that accelerate deployment timelines and reduce total cost of ownership for constrained public agencies.
Growth Catalysts
- EU AI Act risk classification:Infrastructure operators in Germany and France must upgrade autonomous decision systems to meet conformity requirements, triggering replacement demand for legacy control platforms.
- Edge computing latency thresholds:Sub-100-millisecond control loops now enable real-time grid balancing and predictive traffic signal optimization, expanding addressable use cases beyond monitoring into active asset management.
- Japan METI digital infrastructure mandates:National programs for renewable interconnection standards are accelerating smart meter and microgrid controller procurement across industrial campuses and utility networks.
Market Restraints
- Licensed-spectrum wireless backbone costs:Fiber redundancy requirements and dedicated frequency licensing impose capital barriers that exclude smaller municipal operators from full-function deployments.
- Semiconductor supply concentration:Edge node chip fabrication concentrates in East Asian foundries, exposing project timelines to geopolitical disruption and extended lead times for critical components.
- Cybersecurity certification fragmentation:Divergent requirements between Germany's Federal Network Agency and Japan's METI force vendors to maintain parallel compliance tracks, elevating engineering overhead.
Strategic Opportunities
- Industrial campus microgrids:Net-zero operational targets at manufacturing facilities in the United States are creating demand for integrated distributed energy resource management systems with predictive maintenance modules.
- Building automation convergence:Fire-safety integration with HVAC and lighting controls represents underpenetrated white space where unified platforms can displace siloed vendor relationships.
- Utility outcome-based contracting:Power distributors are migrating from capital purchase models to performance-guaranteed service agreements for grid-edge intelligence, opening recurring revenue streams.
Industry Challenges
- Cross-functional talent scarcity:Deployment of autonomous infrastructure systems requires engineers fluent in both OT cybersecurity and civil asset operations, a combination rarely found in single labor pools.
- Legacy system integration friction:Brownfield environments with decades-old SCADA architectures demand custom protocol gateways that extend commissioning timelines and elevate project risk.
- Interoperability standard delays:Fragmented communication protocols between IoT device manufacturers force systems integrators to develop and maintain proprietary middleware layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Infrastructure Market |
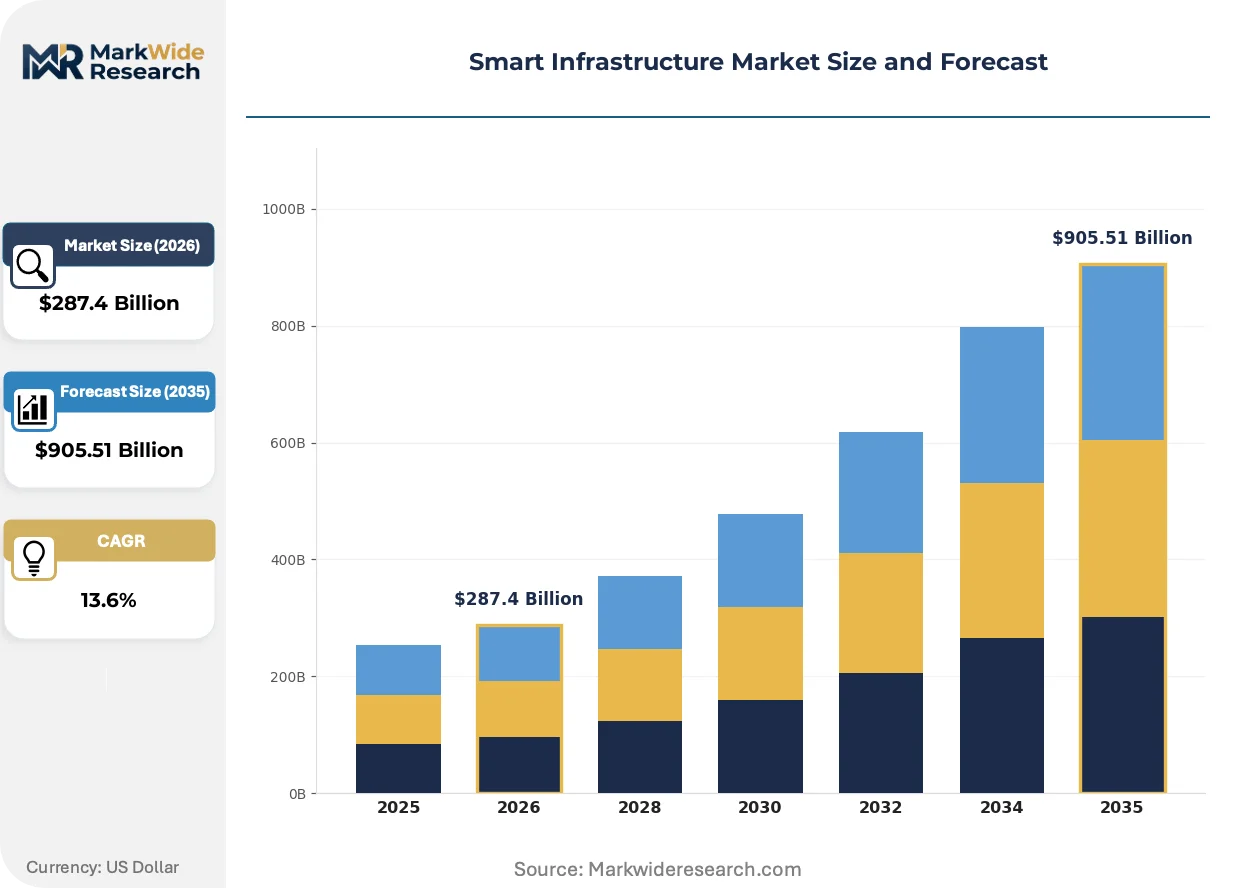
| Market Size in 2026 | $287.4 Billion |
| Market Size in 2035 | $905.51 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, Cloud Computing, AI, Big Data Application: Smart Buildings, Smart Grids, Smart Transportation, Smart Utilities End User: Government, Commercial, Residential, Industrial Service Type: Installation, Maintenance, Consulting, Integration |
| Companies Covered | Bentley Systems, Autodesk, Siemens, Hexagon AB, Johnson Controls, Honeywell International, Schneider Electric, Trimble Solutions, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Infrastructure Market Strategic Shifts & Innovations
Artificial intelligence inference at the network edge is compressing decision latency from seconds to milliseconds, enabling autonomous infrastructure responses that were previously impossible with cloud-dependent architectures.
Digital twin simulation platforms are overtaking traditional CAD-based planning methods for civil asset design. Engineering firms in Germany and the United States now deploy physics-based models that predict structural degradation under variable load conditions. This capability is compressing design validation cycles and reducing physical prototype requirements for bridge and tunnel projects.
The EU AI Act's high-risk system classification is mandating human-in-the-loop oversight for autonomous traffic management decisions. Infrastructure operators must retrofit existing platforms with explainability interfaces and audit trails. German utility regulators are enforcing these requirements most aggressively, creating compliance-driven procurement waves for control system upgrades.
Public agencies are consolidating vendor relationships around integrated platform providers rather than procuring sensors, software, and integration services separately. Municipal procurement offices in Japan and the United States now favor single-contractor accountability for full-system performance. This concentration is marginalizing component specialists and elevating systems integrators with end-to-end delivery capabilities.
Smart Infrastructure Market Segmentation
Segmentation in smart infrastructure reveals how technology layers, application domains, and service models align with distinct procurement patterns and margin structures. Understanding these divisions exposes where vendor capabilities must concentrate to capture value across fragmented buyer ecosystems.
Technology:
Component supply concentrates around semiconductor foundries and cloud hyperscalers, with tier-one vendors controlling foundational layers while specialists extract value at the edge.
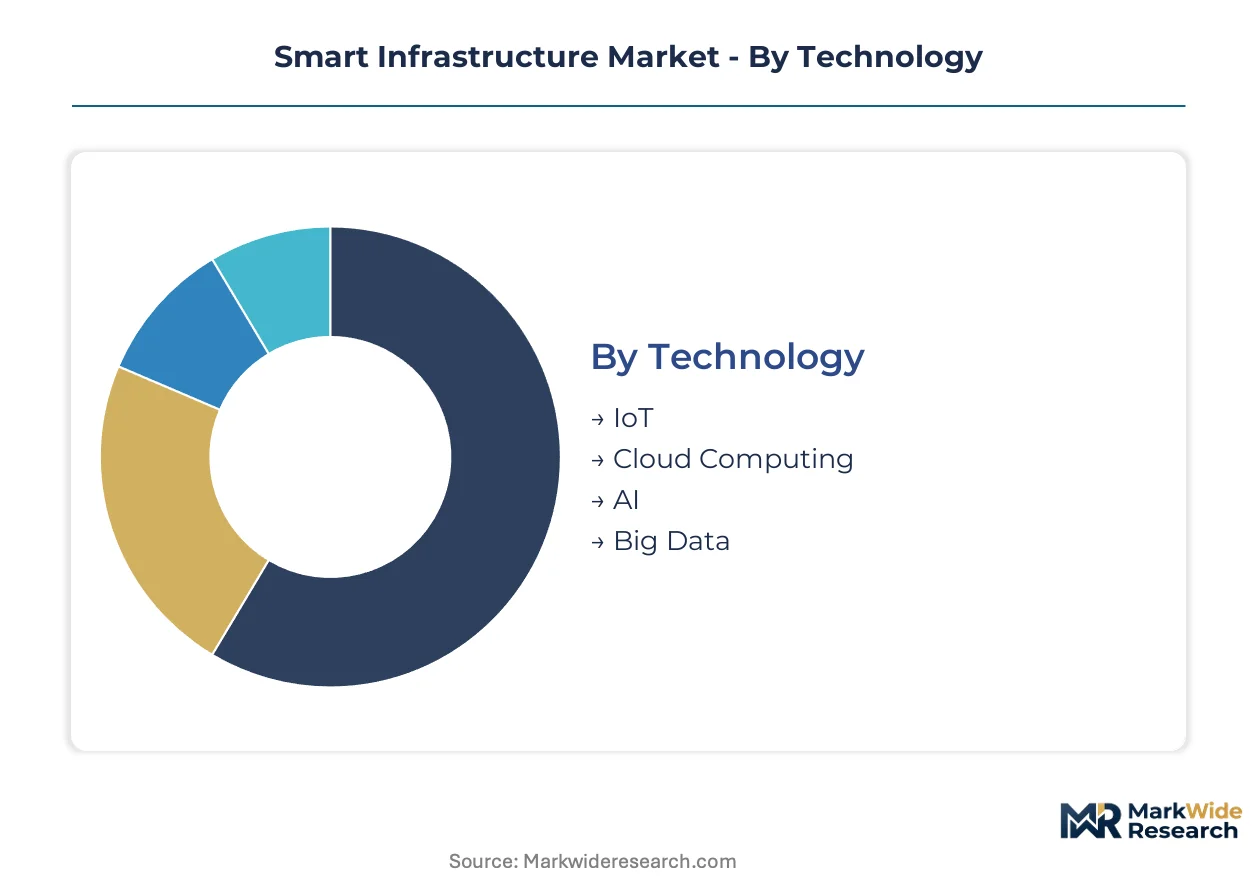
- IoT:Sensor networks and edge nodes form the connectivity substrate for civil asset monitoring, with demand clustering in German utility modernization programs and Japanese industrial campus deployments driven by renewable interconnection mandates.
- Cloud Computing:Centralized data reservoirs and elastic compute resources enable historical analytics and model training, though latency constraints limit real-time control applications to non-critical monitoring functions.
- AI:Machine learning inference engines process telemetry streams for predictive maintenance and demand-response orchestration, with EU AI Act compliance requirements forcing architecture redesigns for autonomous decision systems.
- Big Data:Storage and analytics platforms aggregate multi-source infrastructure telemetry, serving planning and optimization workflows where sub-second response is unnecessary.
IoT absorbs the bulk of installed capacity; AI is expanding most quickly as regulators mandate explainability and human-in-the-loop oversight for high-risk autonomous systems.
Application:
Application domains diverge sharply in procurement velocity, with regulated utilities moving faster than municipal transportation agencies constrained by budget compression.
- Smart Grids:Distributed energy resource management and microgrid controllers enable real-time load balancing and predictive maintenance, with procurement accelerating in the United States where FERC interconnection standards and state renewable mandates create compliance-driven replacement cycles.
- Smart Buildings:Integrated HVAC, lighting, and fire-safety automation systems command substantial current deployment value as owners pursue net-zero operational targets through unified control platforms.
- Smart Transportation:Intelligent traffic signal optimization and autonomous intersection management require sub-100-millisecond latency, limiting deployments to fiber-backbone corridors in major metropolitan clusters.
- Smart Utilities:Water and waste network monitoring extends sensor coverage beyond electricity distribution, though margin pools remain thinner due to lower regulatory pressure and slower capital replacement cycles.
Smart Buildings captures the largest share of current investment; Smart Grids posts the steepest expansion trajectory as grid-edge intelligence becomes essential for renewable integration.
End User:
Buyer sophistication and procurement scale vary dramatically across end-user categories, with industrial campuses demanding integrated performance guarantees while residential deployments fragment across small-scale installations.
- Industrial:Manufacturing facilities and logistics campuses procure microgrid controllers and building automation as unified capital projects, with net-zero targets in the United States and Germany driving integrated energy management investments.
- Government:Municipal and national agencies procure intelligent traffic and grid systems under compressed budget cycles, favoring pre-integrated hardware-software bundles that reduce total cost of ownership.
- Commercial:Office and retail property owners prioritize fire-safety integration with HVAC controls, representing underpenetrated white space where unified platforms displace siloed vendor relationships.
- Residential:Single-family and multi-family deployments concentrate on smart metering and home energy management, with adoption constrained by consumer price sensitivity and fragmented installer networks.
Industrial end users absorb the bulk of high-value deployments; Government procurement is climbing the fastest as EU AI Act and cybersecurity directives force control system upgrades.
Service Type:
Revenue model evolution is shifting margin pools from one-time installation toward recurring maintenance and outcome-based performance contracts.
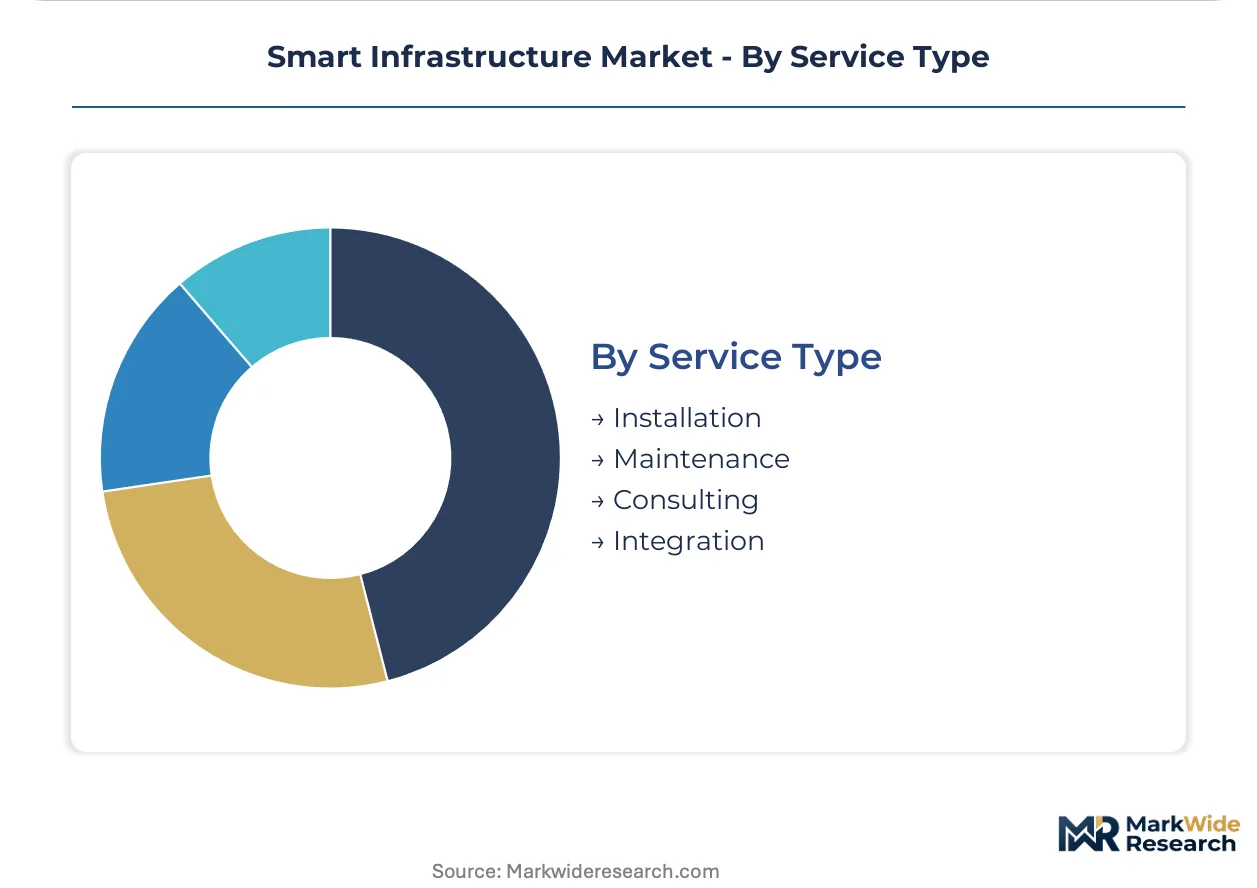
- Integration:Systems engineering and protocol gateway development for brownfield SCADA environments commands premium pricing, though project timelines extend due to custom middleware requirements.
- Maintenance:Predictive service agreements and remote monitoring subscriptions generate recurring revenue streams, with utility outcome-based contracting migrating from capital purchase models to performance-guaranteed arrangements.
- Installation:Physical deployment and commissioning of sensor networks and edge nodes faces margin compression as vendors bundle hardware-software packages to accelerate public agency procurement cycles.
- Consulting:Digital twin simulation and physics-based modeling services compress design validation cycles for bridge and tunnel projects, with engineering firms in Germany and the United States leading adoption.
Installation retains the largest share of historical revenue; Maintenance is gaining share fastest as power distributors and industrial operators prioritize uptime guarantees over capital ownership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart infrastructure deployment concentrates in economies with mature civil engineering sectors and aggressive decarbonization mandates. Manufacturing capacity for edge computing hardware clusters in East Asian foundries, while system integration and software development concentrate in Western Europe and North America.
United States
Utility sector procurement accelerates as FERC interconnection reliability standards force grid-edge intelligence upgrades. State renewable portfolio mandates in California and Texas trigger microgrid controller investments at industrial campuses. The Pacific Northwest corridor hosts dense clusters of smart building deployments driven by municipal net-zero targets.
Germany
The Federal Network Agency enforces stringent cybersecurity certification for critical infrastructure operators, creating compliance-driven replacement cycles. Bavaria and North Rhine-Westphalia industrial zones deploy integrated energy management systems under EU AI Act risk-classification requirements. Berlin-Brandenburg municipalities consolidate vendor relationships around pre-integrated traffic management platforms.
Japan
METI digital infrastructure mandates accelerate smart meter and microgrid procurement across manufacturing facilities. The Kanto region around Tokyo hosts concentrated deployment of predictive maintenance systems for aging transportation assets. Osaka-Kansai industrial corridors integrate building automation with fire-safety controls under national efficiency standards.
China
Dual carbon goals drive massive smart grid investments in Yangtze River Delta and Pearl River Delta manufacturing clusters. MIIT standards for industrial internet platforms shape procurement patterns for edge computing nodes. Beijing-Tianjin-Hebei corridor municipalities deploy intelligent traffic systems with sub-100-millisecond latency requirements.
United Kingdom
Net-zero operational targets for commercial real estate accelerate smart building retrofits in London and Southeast England. Ofgem regulatory frameworks push distributed energy resource management into Midlands industrial zones. Scottish cities consolidate water and waste network monitoring under unified platform contracts.
Smart Infrastructure Market Key Industry Players
Top-tier vendors anchor utility-scale deployments and national digital infrastructure programs, while mid-tier specialists capture industrial campus and municipal sub-system niches. The market structures around three strategic archetypes: integrated platform providers with end-to-end delivery capabilities, domain specialists in grid-edge intelligence or building automation, and engineering-software hybrids leveraging digital twin capabilities. Competitive dynamics center on M&A activity consolidating component vendors into full-system portfolios, and strategic partnerships binding hardware manufacturers to cloud hyperscalers for analytics layers.
Among European-integrated industrial conglomerates, Siemens and Schneider Electric occupy positions exemplifying the platform-provider archetype, anchoring multi-jurisdiction utility modernization programs. Autodesk and Bentley Systems represent the engineering-software hybrid segment, with geographic naming indicating North American origins. These named entities illustrate how competitive positioning stratifies between hardware-dominant and software-dominant value capture models.
| Leading Market Players |
|---|
| Bentley Systems |
| Autodesk |
| Siemens |
| Hexagon AB |
| Johnson Controls |
| Honeywell International |
| Schneider Electric |
| Trimble Solutions |
| ABB |
| Others |
Cost & Logistics Intelligence
Captive semiconductor fabrication in East Asian foundries anchors supply positions for edge computing nodes while simultaneously constraining pricing flexibility for systems integrators facing extended lead times. This vertical integration choice concentrates cost pressure on vendors dependent on external chip sourcing, particularly those serving municipal procurement cycles compressed by budget constraints.
Pricing Analysis
Premium pricing for sub-100-millisecond latency systems with guaranteed delivery windows commands substantial markups over standard-configuration spot inventory. Project-based contracting dominates utility-scale deployments, with price differentiation resting on cybersecurity certification tier and geographic delivery complexity. Cost compression in government-facing tiers is intensifying because pre-integrated hardware-software bundles are displacing component-level procurement. Industrial campus buyers exhibit lowest price sensitivity due to net-zero compliance mandates, while residential deployments fragment across price-conscious consumer segments.
Supply Chain Analysis
Freight costs for redundant fiber backbones and licensed-spectrum equipment elevate total landed costs for municipal operators in Germany and Japan relative to coastal Chinese manufacturing clusters. Edge node semiconductor fabrication concentrates in Taiwan, South Korea, and China, with sensor assembly drawing from Chinese industrial zones and German precision component suppliers. Single-source vulnerability in advanced node chip fabrication exposes project timelines to geopolitical disruption. Distribution runs through systems integrators with end-to-end delivery capabilities rather than component specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated platform providers as EU AI Act compliance costs and cybersecurity certification fragmentation force smaller component vendors toward acquisition or exit. Municipal procurement consolidation amplifies this pressure by favoring single-contractor accountability.
For Market Incumbents: Cement platform dominance by acquiring edge AI specialists with EU AI Act conformity expertise, countering the threat from cloud hyperscalers expanding into infrastructure analytics. Deepen backward integration into semiconductor supply through strategic foundry partnerships or captive wafer capacity commitments, securing priority allocation during supply crunches. For New Entrants and Emerging Players: Municipal engineering consultants represent the most accessible channel partners for bypassing entrenched vendor relationships in German and Japanese transportation agencies. Target fire-safety integration with building automation as the most penetrable white space, where unified control platforms can displace siloed incumbent relationships. Pursue outcome-based contracting models to differentiate from capital-sale incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by industrial conglomerates seeking digital infrastructure capabilities. The five-to-ten year viability window favors engineering-software hybrids with digital twin platforms over pure hardware component vendors. Acquisition target archetypes include mid-tier systems integrators with proven brownfield SCADA integration expertise. Watch FERC interconnection standard revisions as the critical inflection signal for US utility procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Edge AI Specialist | EU AI Act compliance expertise accelerates control system upgrade cycles for German utilities. |
| Backward Integration into Semiconductor Supply | Captive wafer commitments secure priority allocation from Taiwan and South Korean foundries. |
| Outcome-Based Service Contracting | Performance-guaranteed arrangements align vendor incentives with utility uptime requirements. |
| Fire-Safety Platform Integration | Unified HVAC and lighting controls displace siloed vendor relationships in commercial real estate. |
| Digital Twin Simulation Partnership | Physics-based modeling capabilities compress design validation for German bridge and tunnel projects. |
Research Approach
Multi-period observation of municipal procurement cycles, FERC interconnection filings, and EU AI Act implementation timelines anchored the trend analysis, supplemented by interviews with utility planning officers, smart building facility managers, systems integration specialists, and cybersecurity certification auditors. Primary fieldwork combined with secondary validation against EIA grid investment data, German Federal Network Agency regulatory notices, METI infrastructure mandate publications, and hyperscaler edge computing capex disclosures. Bottom-up project pipeline tracking and top-down macroeconomic scenario modeling enabled cross-verification of market sizing.
Input-output matrices mapped technology layer adoption rates against application domain penetration and service model evolution across the projection horizon. Segmentation dimensions modeled include IoT connectivity substrate, AI analytics tier, deployment scale, and regional regulatory framework cluster. CAGRs derived from weighted average of historical deployment trajectories and policy-mandated replacement cycle assumptions. Forecast inputs incorporated renewable interconnection standard compliance deadlines and semiconductor supply lead time volatility.
Caveats apply where geopolitical disruption to East Asian foundry output or accelerated EU AI Act enforcement timelines could materially shift the outlook. Forecasts reflect assumptions about municipal budget recovery trajectories and fiber backbone deployment pace. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Infrastructure
Asia-Pacific Smart Building Market
Smart Infrastructure
Smart Airport Construction Market
Smart Infrastructure
US Smart Building Market
Smart Infrastructure
Smart Hydrants Market
Smart Infrastructure
Smart Pipeline Networks Market
Smart Infrastructure
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market
Smart Infrastructure
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market
Smart Infrastructure
Construction 4.0 Market
Smart Infrastructure
IoT in Commercial Construction Market
Smart Infrastructure
Big Data in Construction Market
Smart Infrastructure
Infrastructure Solution Integration Service Market
Smart Infrastructure
Smart Concrete Market
Smart Infrastructure
Global IoT in Construction Market