
 Global Biological Safety Testing Market | 2026-2036
Global Biological Safety Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biological Safety Testing Market Foresight
The gap between premium validated testing services and commodity screening is realigning contract laboratory economics. Thermo Fisher Scientific leverages its integrated analytical instrumentation portfolio to control high-margin endotoxin and sterility workflows. Charles River Laboratories anchors its position through captive biologics safety assessment capacity across North America and Europe. Eurofins Scientific competes by extending its geographic laboratory network into Asia-Pacific biotech clusters.
Biological safety testing encompasses the analytical verification that biological materials, pharmaceutical products, and medical devices are free from microbial contamination, viral adventitious agents, and pyrogenic substances through methods such as Limulus Amebocyte Lysate assays with sensitivity thresholds reaching 0.03 EU/mL. Its primary purpose is to ensure patient safety and regulatory compliance before product release across biopharmaceutical and medical device supply chains. Endotoxin testing and sterility testing command the largest revenue pools due to mandatory batch-release requirements for parenteral drugs and implantable devices. Polymerase Chain Reaction-based microbial identification represents the fastest-expanding technology segment as manufacturers replace slower culture-based methods for rapid contamination detection.
The FDA enforces current Good Manufacturing Practice regulations that mandate documented sterility assurance levels for all biologic products, while the EMA's Annex 1 revision imposes stricter environmental monitoring requirements for aseptic processing facilities. ISO 17025 accreditation has become a de facto market access threshold for contract testing laboratories serving multinational pharmaceutical clients. Stakeholders must monitor how evolving cell and gene therapy product specifications reshape testing protocol standards and laboratory capital deployment priorities.
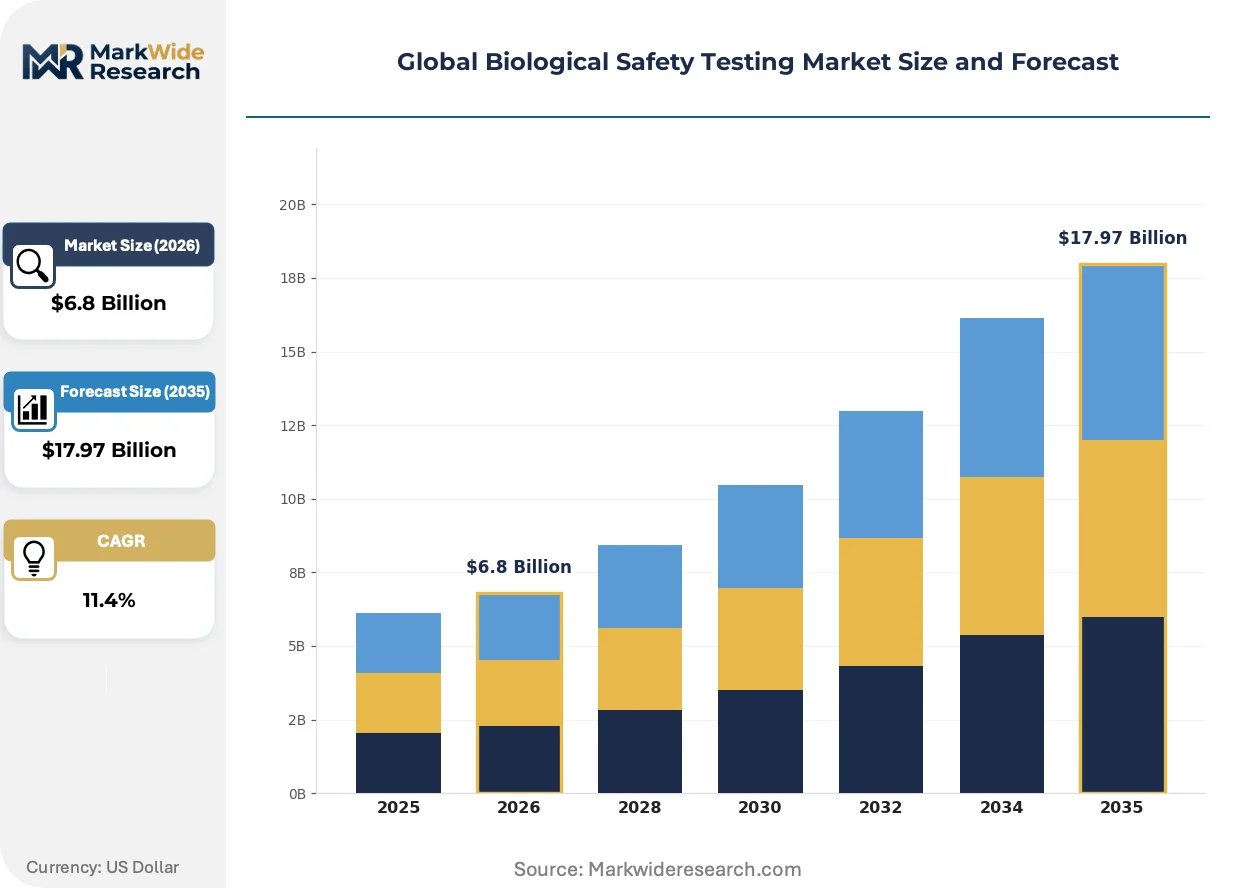
Market Dynamics
Cell therapy manufacturing scale-up is forcing biological safety testing providers to reconfigure laboratory workflows around closed-system automation and single-use technologies. The FDA's sterility assurance expectations for autologous products now exceed conventional biologics thresholds.
Growth Catalysts
- EMA Annex 1 Revision:The EMA's updated contamination control requirements for aseptic processing mandate expanded environmental monitoring programs. Contract laboratories in Germany and Switzerland report order backlog expansion for viable particle testing.
- Cell Therapy Manufacturing:CAR-T and stem cell production facilities require dedicated endotoxin and sterility suites. Each manufacturing site demands captive or contracted testing capacity that runs 24/7 to match perishable batch timelines.
- Rapid Microbial Methods:PCR-based detection systems cut contamination identification from days to hours. Biopharmaceutical quality control departments are retiring culture-based workflows for gene therapy release testing.
Market Restraints
- Reference Standard Supply Concentration:Control Standard Endotoxin production concentrates at a single US supplier. Any disruption to this sole-source material halts Limulus Amebocyte Lysate assay validation across the industry.
- Laboratory Capital Intensity:ISO 17025-accredited cleanroom suites require $15-25 million per facility. The capex barrier prevents mid-sized regional laboratories from entering gene therapy safety testing.
- Technical Substitution Limits:Recombinant Factor C assays remain incompatible with certain complex biologic matrices. Pharmaceutical sponsors cannot fully displace horseshoe crab-derived reagents despite conservation pressures.
Strategic Opportunities
- India Biologics Manufacturing:CDSCO's accelerated biologics approval pathway attracts multinational investment. Contract testing laboratories establishing presence in Hyderabad and Bangalore capture pre-market validation work.
- Gene Therapy Vector Testing:Adeno-associated virus and lentiviral vector safety assessment requires new adventitious agent detection panels. Laboratories developing next-generation sequencing-based viral screens secure long-term platform contracts.
- Continuous Manufacturing Integration:Real-time release testing architectures enable in-line endotoxin monitoring. Partnerships between instrument manufacturers and testing service providers create subscription-based revenue models.
Industry Challenges
- Qualified Analyst Scarcity:Aseptic technique certification and GMP documentation training programs produce insufficient graduates. Testing facilities compete for personnel capable of operating isolator-based sterility systems.
- Method Transfer Complexity:Client-specific validation protocols for PCR-based microbial identification create non-standard workflows. Each technology transfer consumes 12-18 weeks of laboratory capacity without revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biological Safety Testing Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Microbial Identification, Endotoxin Testing, Sterility Testing, Bioburden Testing, Pyrogen Testing Application: Pharmaceutical Manufacturing, Medical Device Validation, Vaccine Production, Food Safety, Cosmetic Safety Technology: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Flow Cytometry, Chromatography, Spectroscopy End User: Contract Testing Laboratories, Biotech Firms, Diagnostic Centers, Regulatory Authorities |
| Companies Covered | Thermo Fisher Scientific Inc., Charles River Laboratories, Merck KGaA, SGS Société Générale de Surveillance SA, Eurofins Scientific, Sartorius AG, Lonza, WuXi AppTec, BSL Bioservice, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biological Safety Testing Market Shifts & Advancements
Automation and artificial intelligence are compressing detection timelines while expanding the analytical scope of biological safety verification. These shifts are redrawing competitive boundaries between instrument manufacturers and service laboratories.
Next-generation sequencing-based adventitious agent detection is rewriting viral safety assessment protocols. Gene therapy sponsors in the United States and Germany now specify NGS panels for master cell bank characterization. The technology is compressing the timeline for unknown pathogen identification from weeks to days, forcing contract laboratories to retrain staff on bioinformatics interpretation.
The FDA's 2023 guidance on rapid microbial methods for pharmaceutical quality control has accelerated ATP-bioluminescence and flow cytometry adoption. Sterility testing workflows that previously required 14-day incubation periods now complete in 5-7 days. Parenteral drug manufacturers in Ireland and Singapore are retrofitting quality control laboratories to accommodate these accelerated release schedules.
Consolidated procurement of safety testing services is displacing transactional relationships between biopharmaceutical quality departments and regional laboratories. Large molecule sponsors in Massachusetts and Basel now mandate global master service agreements with single providers. This behavior concentrates volume with integrated testing networks that offer harmonized data formats and audit-ready documentation packages across multiple manufacturing sites.
Global Biological Safety Testing Market Segmentation
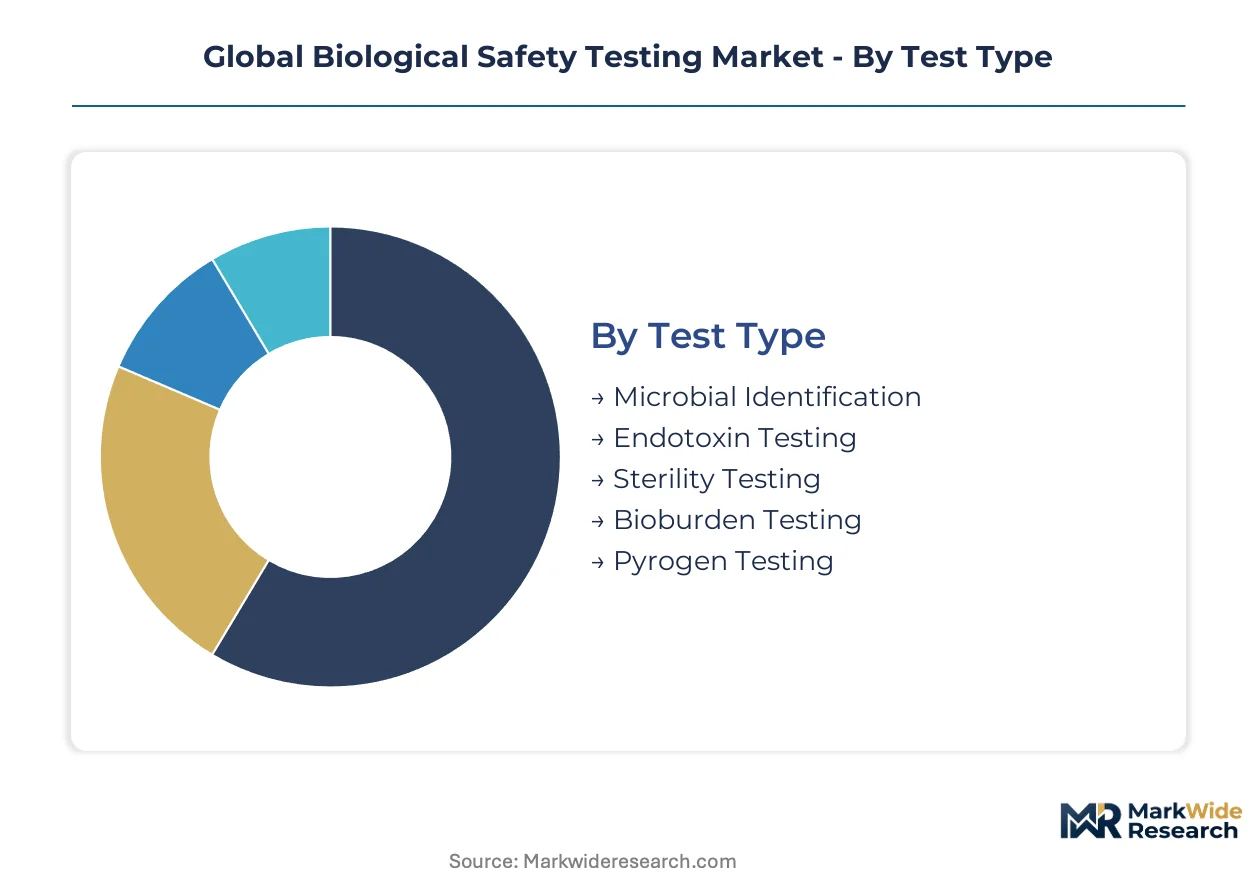
Biological safety testing markets fragment across four critical dimensions that determine laboratory capital deployment and service pricing. Test type and application categories drive regulatory compliance requirements, while technology and end-user segments shape procurement patterns and margin structures.
Test Type:
Standardization dominates high-volume release testing, while custom protocol development concentrates in emerging therapeutic categories.
- Endotoxin Testing:Limulus Amebocyte Lysate and recombinant Factor C assays detect lipopolysaccharide contamination with sensitivity thresholds reaching 0.03 EU/mL. Parenteral drug manufacturers in the United States and Germany mandate this testing for every batch release, with CAR-T production facilities driving 24/7 testing capacity expansion.
- Sterility Testing:Membrane filtration and direct inoculation methods verify absence of viable microorganisms in injectable products and implantable devices. The FDA's sterility assurance level requirements for autologous cell therapies now exceed conventional biologics thresholds, forcing laboratory reconfiguration around isolator-based systems.
- Microbial Identification:Culture-based and molecular methods classify contaminant species for root cause analysis.
- Bioburden Testing:Quantitative enumeration of viable microorganisms on raw materials and in-process samples.
- Pyrogen Testing:Rabbit pyrogen and monocyte activation assays detect fever-inducing substances beyond endotoxin.
Most installed capacity flows through Endotoxin Testing. Expansion is steepest in Microbial Identification.
Application:
Volume concentration in mature therapeutic areas subsidizes capability building for emerging product classes.
- Pharmaceutical Manufacturing:Biologics and small molecule parenteral production require comprehensive contamination control across raw materials, in-process samples, and finished product release. Massachusetts and Basel sponsors now mandate global master service agreements with single testing providers.
- Medical Device Validation:Implantable and contact devices undergo sterility and biocompatibility verification per ISO 10993 standards. The EMA's Annex 1 revision imposes stricter environmental monitoring requirements for device manufacturing facilities in Germany and Switzerland.
- Vaccine Production:Viral adventitious agent testing dominates cell substrate and bulk harvest safety assessment.
- Food Safety:Pathogen detection and spoilage organism monitoring for processed and packaged products.
- Cosmetic Safety:Microbial limit testing for preservative efficacy and product contamination.
Revenue concentration sits in Pharmaceutical Manufacturing. Capability investment is accelerating fastest in Vaccine Production.
Technology:
Speed premiums command pricing power against established but slower analytical methods.
- Polymerase Chain Reaction:Nucleic acid amplification enables species-specific microbial identification and viral adventitious agent detection in hours rather than days. Gene therapy sponsors in the United States and Germany now specify PCR-based methods for master cell bank characterization, displacing slower culture-based workflows.
- Flow Cytometry:Laser-based cell counting and viability assessment accelerates sterility testing from 14-day incubation to 5-7 days. Parenteral drug manufacturers in Ireland and Singapore are retrofitting quality control laboratories to accommodate these accelerated release schedules.
- Enzyme-Linked Immunosorbent Assay:Antibody-based detection for specific microbial antigens and endotoxin quantification.
- Chromatography:Separation-based analysis for pyrogen and contaminant characterization.
- Spectroscopy:Optical and mass spectrometry methods for molecular identification and quantification.
Adoption is broadest in Polymerase Chain Reaction. Deployment is climbing fastest in Flow Cytometry.
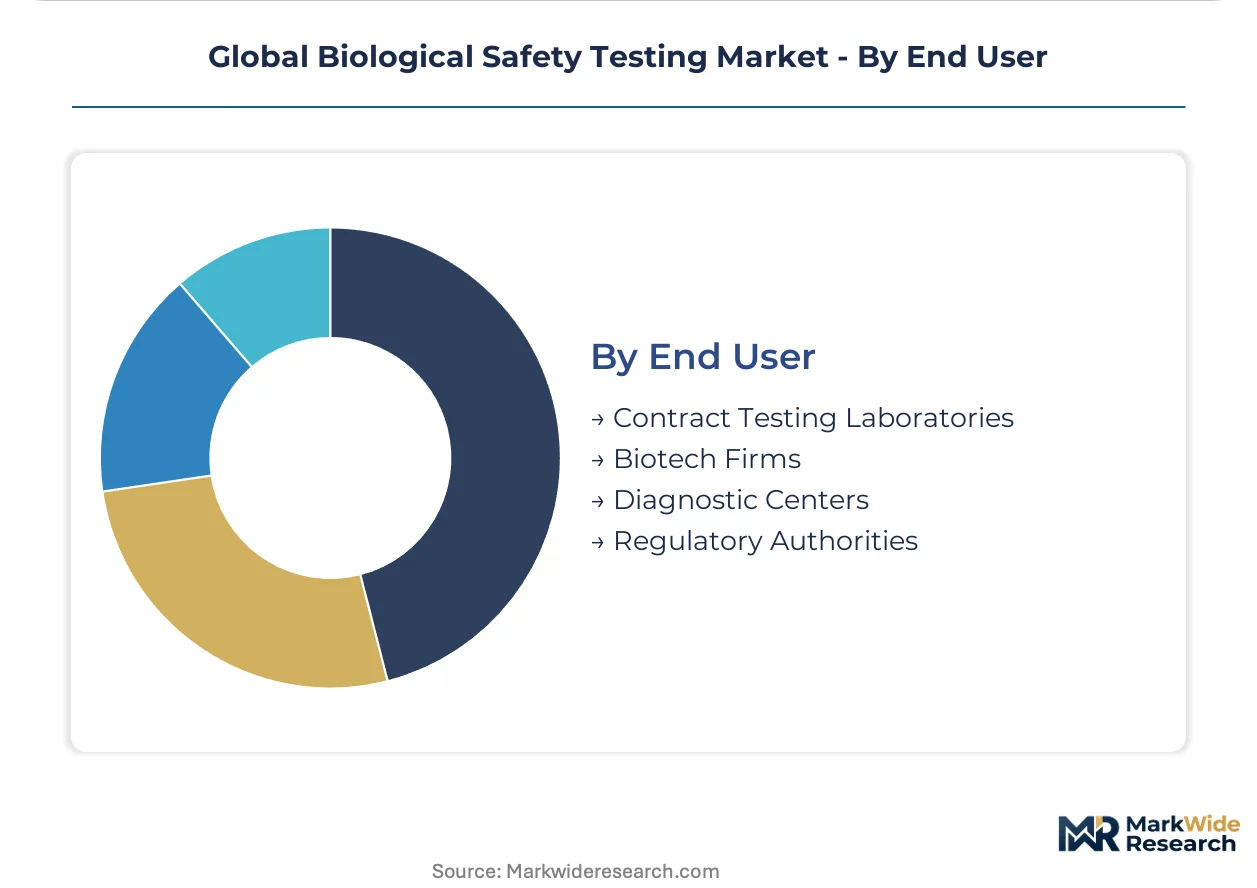
End User:
Outsourcing depth varies with manufacturing scale and regulatory submission complexity.
- Contract Testing Laboratories:ISO 17025-accredited service providers perform outsourced safety testing for sponsors lacking captive capacity. Thermo Fisher Scientific and Charles River Laboratories anchor market share through integrated instrumentation portfolios and captive biologics safety assessment capacity across North America and Europe.
- Biotech Firms:Early-stage companies with limited quality infrastructure rely heavily on contracted testing services.
- Diagnostic Centers:Clinical laboratories performing safety testing for point-of-care and companion diagnostic products.
- Regulatory Authorities:Government laboratories conducting confirmatory testing and reference standard calibration.
Testing volume concentrates in Contract Testing Laboratories. Facility expansion is most aggressive among Biotech Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled analytical chemists and GMP-certified technicians concentrate in established biopharma manufacturing corridors across the United States, Germany, China, Switzerland, and India. These workforce pools anchor the largest contract testing laboratory networks and drive regional specialization in endotoxin validation and sterility assurance.
United States
CAR-T manufacturing facilities in Massachusetts and California require 24/7 endotoxin and sterility testing capacity to match perishable autologous batch timelines. The FDA enforces sterility assurance levels for advanced therapy medicinal products that exceed conventional biologics thresholds. Greater Boston hosts the densest concentration of gene therapy sponsors now specifying next-generation sequencing for master cell bank characterization.
Germany
EMA Annex 1 revision mandates expanded environmental monitoring programs for aseptic processing facilities across Baden-Württemberg and Bavaria. Contract laboratories in Basel and Munich report order backlog expansion for viable particle testing and isolator-based sterility systems. The Rhine-Main biotech corridor anchors captive safety assessment capacity serving multinational pharmaceutical sponsors.
China
CDSCO-equivalent NMPA accelerated biologics approval pathways attract multinational manufacturing investment to Shanghai and Suzhou biotech clusters. Domestic contract testing laboratories in Hangzhou and Wuxi scale PCR-based microbial identification capacity to displace slower culture-based workflows. Yangtze River Delta facilities retrofit quality control laboratories for rapid release testing architectures.
Switzerland
Swissmedic maintains alignment with EMA contamination control guidelines while preserving distinct national pharmacopeia requirements for pyrogen testing. Basel anchors integrated biologics safety assessment capacity spanning endotoxin, sterility, and adventitious agent detection. Geneva-based laboratories specialize in reference standard calibration serving European contract testing networks.
India
CDSCO accelerated biologics approval pathway attracts multinational investment to Hyderabad and Bangalore manufacturing corridors. Contract testing laboratories establishing ISO 17025-accredited presence capture pre-market validation work for export-oriented biologics production. Karnataka and Telangana biotech parks drive facility expansion among regional service providers.
Global Biological Safety Testing Market Competitive Landscape
Top-tier vendors anchor integrated testing networks with harmonized data formats, while mid-sized regional laboratories compete on specialized turnaround times and local regulatory relationships. The market structure reflects consolidation pressure from consolidated procurement practices among large molecule sponsors. Three archetypes dominate: diversified analytical instrumentation conglomerates, captive biologics safety assessment specialists, and geographic network extenders. M&A activity concentrates testing volume with providers offering audit-ready documentation packages, while strategic partnerships between instrument manufacturers and service laboratories create subscription-based revenue models.
Within the diversified instrumentation tier, Thermo Fisher Scientific Inc. occupies a position exemplifying integrated analytical portfolio control over high-margin endotoxin and sterility workflows. Charles River Laboratories anchors the captive safety assessment archetype through North American and European laboratory density. Eurofins Scientific represents the geographic network extension model, with laboratory presence scaling into Asia-Pacific biotech clusters.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Charles River Laboratories |
| Merck KGaA |
| SGS Société Générale de Surveillance SA |
| Eurofins Scientific |
| Sartorius AG |
| Lonza |
| WuXi AppTec |
| BSL Bioservice |
| Others |
Supply & Pricing Matrix
Captive testing capacity integration across endotoxin and sterility workflows anchors pricing power for laboratories serving CAR-T manufacturers with 24/7 batch-release requirements. The FDA's sterility assurance mandates for autologous cell therapies exceed conventional biologics thresholds, forcing sponsors to pay premiums for ISO 17025-accredited facilities with isolator-based systems.
Pricing Analysis
Service bundling versus unbundling splits the market between integrated master service agreements and transactional per-test pricing. Three-tier pricing structure across premium validated, standard compliance, and economy screening levels reflects certification grade and turnaround urgency. Pricing pressure stems from consolidated procurement practices among Massachusetts and Basel sponsors demanding harmonized data formats. Early-stage biotech firms exhibit highest price sensitivity, while gene therapy sponsors prioritize speed over cost.
Supply Chain Analysis
Cold-chain logistics costs for perishable cell therapy samples concentrate supply relationships within 200-mile radii of manufacturing sites. Control Standard Endotoxin production centers on a single US supplier, while recombinant Factor C reagents source from Switzerland and Germany. Single-source vulnerability in reference standard supply creates industry-wide validation risk. Distribution runs through captive laboratory networks and contracted service providers with regional ISO 17025 accreditation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in biological safety testing rests on automation-driven cost compression in sterility workflows and premium-tier pricing for gene therapy vector testing. Laboratories capturing NGS-based adventitious agent detection contracts secure multi-year platform lock-in with sponsors.
For Market Incumbents: Anchor market position through captive biologics safety assessment capacity expansion in Basel and Greater Boston corridors. Defend against PCR-based rapid microbial method substitution by retrofitting isolator-based sterility systems. Prioritize ISO 17025 accreditation maintenance across all facilities to meet EMA Annex 1 revision requirements. For New Entrants and Emerging Players: Begin with specialized adventitious agent detection services for adeno-associated virus vector sponsors in Hyderabad and Bangalore biotech clusters. Target CDSCO pre-market validation work for export-oriented biologics manufacturers. Differentiate through 48-hour turnaround guarantees for endotoxin testing that incumbent networks cannot match. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-sized regional laboratories lack capital for $15-25 million cleanroom facility investments required for gene therapy safety testing. Long-term viability favors providers with integrated instrumentation portfolios and harmonized data formats across multiple manufacturing sites. Monitor FDA guidance on rapid microbial methods adoption as inflection indicator for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| NGS-Based Viral Screen Development | Laboratories deploying next-generation sequencing for master cell bank characterization secure platform contracts with US gene therapy sponsors. |
| Isolator-Based Sterility Suite Investment | Facilities retrofitting for closed-system automation meet FDA sterility assurance thresholds exceeding conventional biologics requirements. |
| Asia-Pacific Laboratory Network Expansion | Establishing ISO 17025-accredited presence in Hangzhou and Wuxi captures PCR-based microbial identification demand from NMPA-registered manufacturers. |
| Continuous Manufacturing Integration Partnership | Instrument manufacturer collaborations enable real-time endotoxin monitoring subscriptions replacing batch-release testing. |
| Qualified Analyst Training Program Scaling | GMP documentation and aseptic technique certification pipelines address personnel scarcity constraining isolator-based sterility system operations. |
Research Methodology
Multiple input streams — regulatory affairs directors at contract testing laboratories, quality control executives at CAR-T manufacturers, biologics safety assessment scientists, and procurement managers at gene therapy sponsors — were reconciled with secondary validation from FDA guidance documents, EMA Annex 1 revision texts, ISO 17025 accreditation databases, and pharmacopeial reference standard records. Bottom-up facility capacity estimates and top-down sponsor testing expenditure patterns were triangulated to derive market sizing.
Historical capacity utilization rates were cross-referenced against expert panel assessments of cell therapy manufacturing expansion timelines across the projection horizon. Segmentation modeling incorporated test type, application category, technology platform, and end-user archetype dimensions. CAGRs were derived from laboratory capital expenditure trajectories and sponsor outsourcing depth projections, with specific weighting for PCR-based rapid microbial method substitution velocity and NGS adoption curves in viral safety assessment.
Several conditions sit outside the modeled scope, including unforeseen disruptions to Control Standard Endotoxin supply, abrupt shifts in horseshoe crab conservation regulations affecting LAL reagent availability, and macroeconomic contractions delaying biologics manufacturing facility construction. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
Home DNA Testing Market
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
Global ADME Toxicology Testing Market
Testing Services
Over-The-Counter Tests Market
Testing Services
Global Medical Device Testing and Certification Market
Testing Services
Rapid Sterility Testing Market
Testing Services
Test Strips Market
Testing Services
Antibiotic Susceptibility Testing Market
Testing Services
Pneumonia Testing Market
Testing Services
Nicotine Testing Market
Testing Services
Middle East and Africa IVD Regulatory Affairs Outsourcing Market
Testing Services
Rapid Coagulation Testing Market
Testing Services
Esoteric Testing Market
Testing Services
Pneumococcal Testing Market
Testing Services
Vestibular Testing System Market