
 Global Antiseptic Products Market | 2026-2036
Global Antiseptic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antiseptic Products Market Foresight
Alcohol-free and persistent-acting polymer technologies is fragmenting traditional antiseptic formulation architectures across wound care and surgical scrub applications. Johnson & Johnson leverages its hospital direct sales network to sustain premium positioning in surgical preparation kits. Ecolab dominates institutional cleaning and infection control protocols with concentrated service-contract bundles. 3M differentiates through advanced film-forming antiseptic platforms that extend protection duration in operating theaters.
Antiseptic products encompass biocidal formulations containing active agents such as chlorhexidine gluconate, povidone-iodine, or benzalkonium chloride at specified concentrations, manufactured through controlled chemical synthesis or extraction processes, and designed to reduce microbial load on living tissue or medical surfaces without inducing tissue damage. The alcohol-based product category anchors volume demand in hand hygiene and preoperative skin preparation due to rapid kill kinetics and low cost per application. Chlorhexidine formulations command margin premiums in surgical scrub and catheter site care where persistent antimicrobial activity reduces healthcare-associated infection risk. Hospital end users concentrate procurement power through group purchasing organizations, squeezing distributor markups while favoring suppliers with validated sterile manufacturing capabilities.
The FDA's Tentative Final Monograph for Healthcare Antiseptics and the EU Medical Device Regulation reshape compliance burdens for topical antiseptic claims and sterile delivery formats. The EPA regulates hard-surface disinfectant-antiseptic hybrids in the US, while Health Canada and the EU EMA impose divergent clinical evidence standards for preoperative skin preparations. Stakeholders must monitor evolving monograph rulings and harmonization gaps between FDA, EMA, and national regulators to anticipate reformulation costs and market access barriers.
Market Dynamics
Polymer-based persistent-acting technologies are fragmenting traditional alcohol-dominant formulation architectures, forcing incumbents to rebuild R&D pipelines around extended-duration efficacy claims while FDA monograph revisions compress approval timelines.
Growth Catalysts
- Hospital Infection Control Mandates:India's Ministry of Health is expanding mandatory hand hygiene protocols in tertiary care facilities, driving institutional procurement of chlorhexidine-based surgical scrubs.
- EU Medical Device Regulation:MDR's sterility validation requirements for preoperative skin preparations are accelerating manufacturer investment in validated aseptic filling lines.
- Polymer Film-Forming Chemistry:Advanced film-forming antiseptic platforms are extending protection duration in operating theaters, creating premium positioning opportunities.
Market Restraints
- Active Ingredient Supply Concentration:Chlorhexidine gluconate API production concentrates in Chinese chemical manufacturing clusters, exposing formulators to input volatility and geopolitical supply risk.
- FDA Monograph Uncertainty:The Tentative Final Monograph for Healthcare Antiseptics creates reformulation cost ambiguity, freezing new product development budgets at mid-sized manufacturers.
- Alcohol Price Sensitivity:Ethanol and isopropanol cost fluctuations directly compress margins in high-volume hand hygiene segments where procurement tenders emphasize unit economics.
Strategic Opportunities
- Home Healthcare Expansion:Post-acute care settings in Germany and Japan are adopting catheter site antiseptics previously restricted to hospital formulary, opening new channel access.
- Green Chemistry Incentives:The EU Green Deal's biocidal product sustainability criteria are creating first-mover advantage for bio-based quaternary ammonium formulations.
- Direct-to-Institution Platforms:Digital procurement portals are disintermediating traditional distributor networks in Brazil's hospital sector, enabling margin capture by manufacturers with logistics infrastructure.
Industry Challenges
- Sterile Manufacturing Certification Backlogs:ISO 13485 and FDA QSR compliance timelines for aseptic filling facilities are extending 12-18 months, constraining capacity expansion.
- Cross-Functional Formulation Expertise Scarcity:The convergence of polymer chemistry, microbiology, and regulatory science required for next-generation persistent-acting products exceeds available talent pools in secondary manufacturing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antiseptic Products Market |
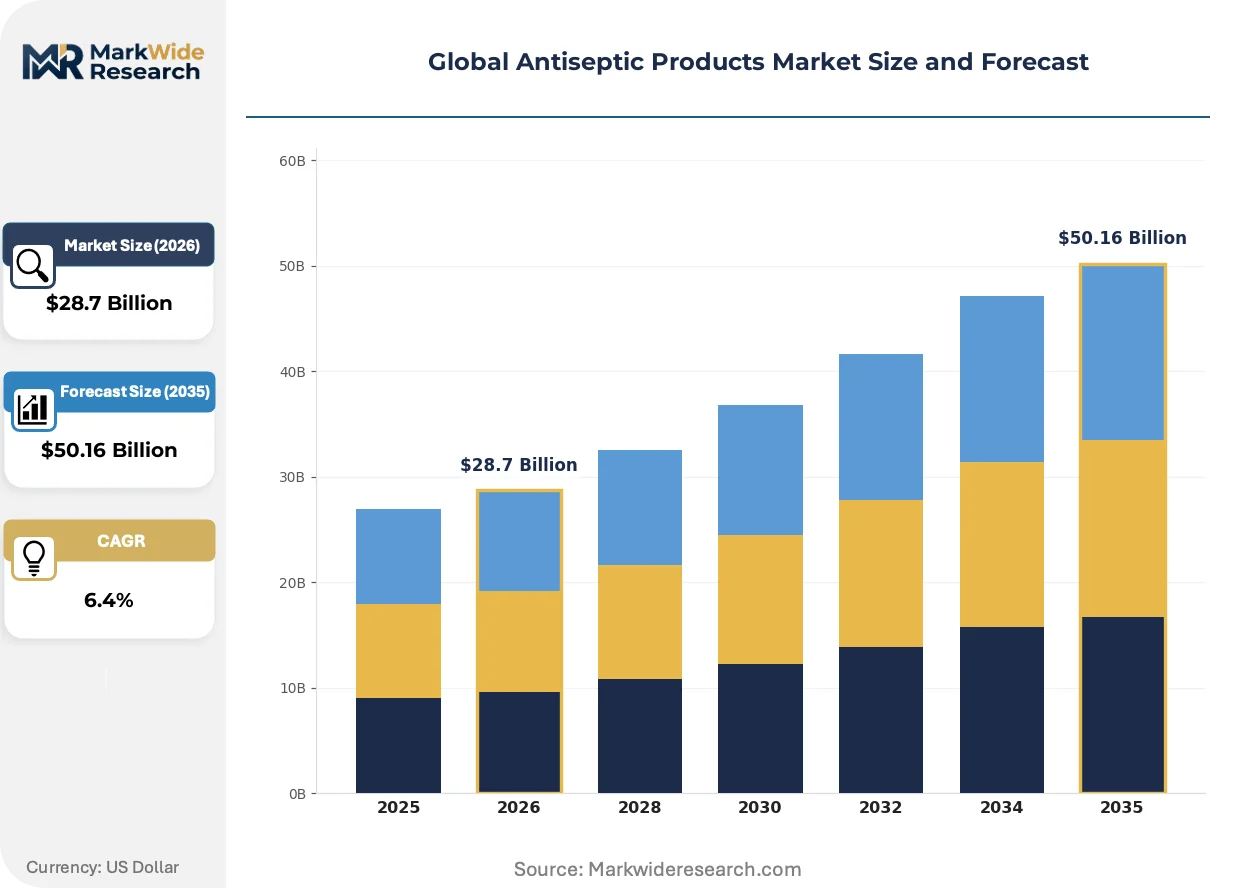
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
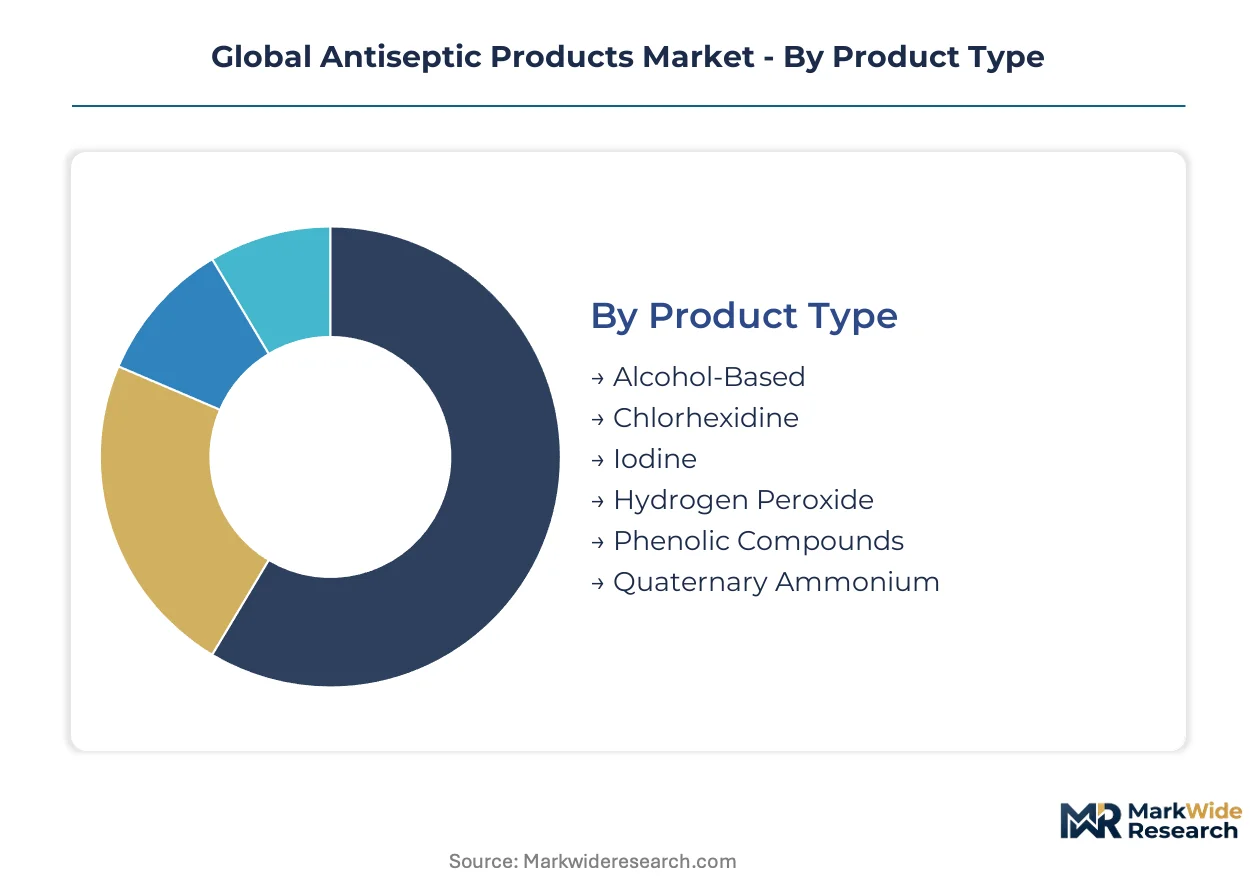
| Segmentation | Product Type: Alcohol-Based, Chlorhexidine, Iodine, Hydrogen Peroxide, Phenolic Compounds, Quaternary Ammonium Application: Wound Care, Surgical Scrub, Hand Hygiene, Oral Care, Skin Disinfection, Instrument Sterilization End User: Hospitals, Ambulatory Surgical Centers, Diagnostic Laboratories, Dental Clinics, Nursing Homes, Outpatient Facilities Distribution Channel: Pharmacies, Hospitals Direct Sales, Online Retail, Medical Supply Distributors, Supermarkets, Specialty Stores |
| Companies Covered | Johnson & Johnson, 3M, Reckitt Benckiser, Ecolab, STERIS, BD, Kimberly-Clark Corporation, Becton, Dickinson & Co., Procter & Gamble, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antiseptic Products Market Shifts & Advancements
Antiseptic formulation architectures are bifurcating between rapid-kill alcohol systems and persistent-acting polymer platforms, with regulatory evidence standards increasingly determining which chemistry classes secure formulary placement.
Film-forming polymer technologies incorporating chlorhexidine or octenidine are digitizing compliance tracking in surgical suites. Operating theater managers in German university hospitals are adopting these platforms to reduce re-application frequency during prolonged procedures. The technology is digitizing workflow optimization and documentation burden, compressing demand for conventional scrub protocols that require timed reapplication cycles.
REACH's biocidal product authorization timelines are extending market access barriers for novel active substances. European manufacturers are redirecting R&D toward existing approved actives with formulation modifications rather than new molecular entities. Preoperative skin preparation categories face the steepest compliance cost escalation, prompting consolidation among smaller EU-based specialty formulators.
Group purchasing organizations in the United States are unbundling infection control service contracts from product supply agreements. Hospital systems in Texas and California are separating Ecolab-style bundled offerings, instead awarding product tenders to lowest-qualified bidders while contracting service elements independently. This disaggregation is most visible in IDN-affiliated community hospitals seeking procurement transparency.
Global Antiseptic Products Market Segmentation
Antiseptic product segmentation reveals divergent margin profiles across formulation chemistries and procurement channels. Service intensity varies sharply between institutional direct sales requiring clinical training support versus retail pharmacy transactions with minimal after-sale engagement.
Product Type:
After-sales service intensity peaks with chlorhexidine formulations requiring sterile handling protocols and clinical education, while alcohol-based products demand minimal technical support beyond basic storage guidance.
- Alcohol-Based:Ethanol and isopropanol formulations dominate hand hygiene and preoperative skin preparation with rapid kill kinetics. Hospital procurement in India concentrates volume demand as infection control mandates expand in tertiary care facilities.
- Chlorhexidine:Persistent-acting gluconate formulations command premium positioning in surgical scrub and catheter site care. German university hospitals drive adoption of film-forming polymer variants that extend protection duration during prolonged procedures.
- Iodine:Povidone-iodine solutions retain formulary presence in wound irrigation and emergency department protocols.
- Hydrogen Peroxide:Oxidative biocide formulations serve niche applications in oral care and minor wound cleansing.
- Phenolic Compounds:Legacy antiseptic chemistry persists in veterinary and industrial hygiene segments with declining clinical use.
- Quaternary Ammonium:Benzalkonium chloride formulations are gaining traction in alcohol-free hand hygiene products targeting EU sustainability criteria.
By volume, alcohol-based leads. By growth pace, chlorhexidine polymer platforms are expanding most quickly.
Application:
Application segmentation tracks directly to reimbursement pathways and regulatory classification intensity, with surgical applications facing steepest compliance burdens under FDA and EMA frameworks.
- Surgical Scrub:Preoperative skin preparation formulations require sterile validation and persistent efficacy claims. EU MDR sterility requirements are accelerating manufacturer investment in validated aseptic filling lines.
- Hand Hygiene:High-frequency institutional use drives ethanol-based volume in hospital and outpatient settings. India's Ministry of Health mandates are expanding procurement of chlorhexidine alternatives in tertiary facilities.
- Wound Care:Antiseptic irrigation and dressing applications serve acute and chronic wound management protocols.
- Oral Care:Mouthwash and dental rinse formulations occupy consumer and professional channels with distinct regulatory pathways.
- Skin Disinfection:Pre-injection and minor procedure antisepsis bridges institutional and retail procurement.
- Instrument Sterilization:High-level disinfection applications compete with sterilization technologies in reprocessing workflows.
Surgical scrub captures the highest per-unit value. Hand hygiene dominates absolute volume throughput.
End User:
End user segmentation reflects procurement sophistication gradients, with hospitals exercising consolidated purchasing power through group purchasing organizations while dental clinics maintain fragmented individual ordering patterns.
- Hospitals:Tertiary care systems concentrate demand across all formulation categories with stringent sterile manufacturing requirements. Southeast Asian hospital expansion is driving procurement of surgical scrubs and hand hygiene formulations.
- Ambulatory Surgical Centers:Outpatient procedural volumes favor rapid-turnover antiseptic protocols with minimized reapplication cycles.
- Diagnostic Laboratories:Specimen handling and phlebotomy applications require skin disinfection and hand hygiene compliance.
- Dental Clinics:Oral antiseptic and instrument disinfection needs operate through distributor and direct sales channels.
- Nursing Homes:Long-term care settings in Germany and Japan are adopting catheter site antiseptics previously restricted to acute care formulary.
- Outpatient Facilities:Community-based care drives retail pharmacy and medical supply distributor volume.
Hospitals anchor absolute demand. Nursing homes are gaining share fastest as post-acute care protocols expand.
Distribution Channel:
Channel segmentation tracks disintermediation pressure, with digital procurement portals eroding traditional distributor margins in Brazil and other emerging markets.
- Hospitals Direct Sales:Manufacturer clinical service contracts and sterile logistics integration dominate institutional procurement. Ecolab-style bundled offerings are unbundling as Texas and California IDNs seek procurement transparency.
- Medical Supply Distributors:Traditional channel faces margin compression from group purchasing organization consolidation and digital platform competition.
- Pharmacies:Retail and hospital outpatient dispensing captures consumer and minor procedure antiseptic demand.
- Online Retail:E-commerce penetration is expanding in post-acute and home healthcare segments.
- Supermarkets:Mass-market hand hygiene and first-aid antiseptics serve consumer self-care applications.
- Specialty Stores:Veterinary and industrial hygiene channels serve niche professional segments.
Direct sales commands the highest service intensity. Online retail is climbing the fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese chlorhexidine gluconate API manufacturers supply formulators across Germany, India, and the United States, creating trade-flow dependencies that shape regional procurement strategies.
United States
Texas and California hospital systems are unbundling infection control service contracts from product supply agreements, seeking procurement transparency through independent tender processes. The FDA's Tentative Final Monograph for Healthcare Antiseptics is freezing new product development budgets at mid-sized manufacturers. Boston's medical device corridor houses sterile manufacturing facilities facing ISO 13485 compliance backlogs extending 12-18 months.
Germany
University hospitals in Bavaria and North Rhine-Westphalia are adopting film-forming polymer antiseptics to digitize surgical workflow optimization and reduce re-application frequency. The EU Medical Device Regulation's sterility validation requirements are accelerating manufacturer investment in validated aseptic filling lines. Frankfurt's chemical manufacturing base supplies polymer chemistry expertise for next-generation persistent-acting formulations.
India
The Ministry of Health is expanding mandatory hand hygiene protocols in tertiary care facilities across Maharashtra and Karnataka, driving institutional procurement of chlorhexidine-based surgical scrubs. CDSCO alignment with international standards is streamlining market access for imported sterile preparations. Mumbai's hospital procurement networks concentrate demand through consolidated purchasing arrangements.
Japan
Post-acute care settings in Kanto and Kansai regions are adopting catheter site antiseptics previously restricted to acute care formulary, opening new channel access for home healthcare applications. METI's sustainability incentives under the national green growth strategy are favoring bio-based formulation chemistry. Osaka's medical supply distribution hub is digitizing procurement portals for nursing home networks.
Brazil
Digital procurement portals are disintermediating traditional distributor networks in São Paulo and Rio de Janeiro hospital sectors, enabling margin capture by manufacturers with logistics infrastructure. ANVISA's convergence with FDA sterility standards is elevating compliance costs for imported preoperative preparations. The Southeast region's IDN-affiliated community hospitals are separating bundled service offerings from product tenders.
Global Antiseptic Products Market Competitive Landscape
Channel-controlling players compete with product-specialist players across institutional and retail procurement pathways. The market structure concentrates around diversified healthcare conglomerates with hospital direct sales networks and sterile manufacturing capabilities alongside focused infection control service providers. Three archetypes dominate: premium surgical preparation suppliers with validated aseptic facilities, institutional service-contract bundlers with logistics integration, and mass-market hygiene brands with retail pharmacy penetration. Competitive moves center on geographic expansion through distributor acquisition and portfolio diversification into persistent-acting polymer platforms.
Within the premium surgical preparation tier, Johnson & Johnson and 3M occupy positions anchored by hospital direct sales infrastructure and film-forming technology portfolios. Ecolab exemplifies the service-contract bundler archetype with concentrated institutional cleaning and infection control protocols. These three entities represent the dominant competitive anchors against which mid-sized formulators and regional distributors position alternative procurement economics.
| Leading Market Players |
|---|
| Johnson & Johnson |
| 3M |
| Reckitt Benckiser |
| Ecolab |
| STERIS |
| BD |
| Kimberly-Clark Corporation |
| Becton, Dickinson & Co. |
| Procter & Gamble |
| Others |
Supply & Pricing Matrix
Undercapacity in validated aseptic filling facilities across the United States and Germany is compressing supplier pricing power while amplifying premiums for sterile chlorhexidine formulations. Capacity utilization rates above 85% in ISO 13485-certified plants are forcing buyers into longer contract terms and accepting price escalation clauses for surgical scrub supply security.
Pricing Analysis
Next-generation film-forming polymer antiseptics command 40-60% premiums over conventional alcohol-based formulations, while legacy iodine solutions face sustained price erosion in emergency department procurement. Three-tier pricing structure across premium, standard, and economy levels separates validated sterile preparations from non-sterile hospital-grade products from retail consumer formats. Pricing pressure stems from group purchasing organization consolidation in Texas and California hospital systems unbundling service contracts. Ambulatory surgical centers exhibit highest price sensitivity due to procedure-volume volatility, while German university hospitals demonstrate lowest sensitivity given reimbursement protection for infection control protocols.
Supply Chain Analysis
Export-control scrutiny on advanced polymer chemistry IP is fragmenting technology transfer pathways between German formulators and Asian manufacturing partners. Chlorhexidine gluconate API production concentrates in Chinese chemical manufacturing clusters, with secondary sourcing from Indian pharmaceutical intermediates producers. Raw material dependencies span chlorhexidine base compounds, pharmaceutical-grade ethanol, and film-forming polymer resins from petrochemical feedstocks. Single-source vulnerability in Chinese API supply exposes formulators to geopolitical disruption and input cost volatility. Distribution runs through hospital direct sales networks for institutional procurement, medical supply distributors for mid-tier facilities, and digital procurement portals disintermediating traditional channels in Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through group purchasing organization consolidation across United States hospital systems and Southeast Asian tertiary care networks, fragmenting supplier margin capture and forcing unbundling of historically integrated service-product offerings.
For Market Incumbents: Entrench sterile manufacturing certification advantages by accelerating ISO 13485 capacity expansion in Germany and the United States before compliance backlogs extend further. Secure backward integration into chlorhexidine gluconate API through long-term offtake agreements with Chinese manufacturers or captive production in India, defending against supply concentration risk and input cost volatility threatening margin sustainability in high-volume hand hygiene segments. For New Entrants and Emerging Players: Pursue white-space opportunities in Japan's post-acute nursing home sector and Germany's home healthcare catheter site antiseptic applications, segments previously restricted to acute care formulary now opening to new channel access. Target Brazil's digitizing hospital procurement landscape through direct-to-institution platform investments, bypassing entrenched distributor networks and capturing margin through logistics infrastructure ownership rather than clinical service bundling. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because FDA monograph finalization and EU MDR sterility validation requirements are elevating barriers to entry and consolidating viable acquisition targets around certified manufacturing assets. Focus on mid-sized formulators with validated aseptic filling lines and existing hospital direct sales relationships in India or Southeast Asia. Watch FDA Tentative Final Monograph resolution timing as the critical inflection signal determining reformulation cost burdens and competitive repositioning requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Validated Aseptic Capacity Expansion | ISO 13485 certification backlogs extending 12-18 months constrain supply elasticity for surgical scrub demand. |
| Film-Forming Polymer R&D Investment | 3M's advanced platforms demonstrate premium positioning through extended protection duration claims in operating theaters. |
| Direct-to-Institution Digital Procurement | Brazil's hospital sector disintermediation enables margin capture bypassing traditional medical supply distributors. |
| Backward Integration into API Supply | Chlorhexidine gluconate concentration in Chinese manufacturing clusters creates geopolitical input volatility exposure. |
| EU Green Deal Biocidal Compliance | Bio-based quaternary ammonium formulations gain first-mover advantage under sustainability criteria incentives. |
Research Methodology
Desk research of FDA Tentative Final Monograph filings, EU MDR technical documentation, and hospital procurement contract databases preceded structured interviews with infection control officers, sterile manufacturing plant managers, group purchasing organization contract specialists, and antiseptic formulation R&D directors. Secondary validation drew from customs trade data on chlorhexidine gluconate API flows, SEC 10-K disclosures of listed healthcare conglomerates, and CDSCO regulatory alignment notifications. Bottom-up volume modeling across formulation chemistry tiers triangulated against top-down market sizing from institutional expenditure surveys.
Assumptions held fixed include FDA monograph finalization proceeding without substantive active ingredient exclusions, EU MDR sterility validation timelines stabilizing at current 12-18 month intervals, and Chinese API export licensing maintaining existing pharmaceutical-grade pathways. The analytical framework modeled demand across alcohol-based, chlorhexidine, iodine, and emerging polymer platform chemistries; surgical scrub, hand hygiene, wound care, and post-acute catheter site applications; and hospital, ambulatory surgical center, and nursing home end-user segments. CAGRs were derived from procedure volume growth in target geographies, infection control mandate expansion trajectories, and pricing elasticity estimates from tender database analysis.
Macroeconomic conditions sit as an overlay; deviation in ethanol commodity pricing, euro-dollar exchange rate volatility affecting German export competitiveness, or Indian rupee depreciation impacting import procurement budgets would shift the trajectory. Material shifts in FDA monograph rulings on chlorhexidine concentration limits, REACH biocidal authorization timelines for novel actives, or Chinese export control expansion into pharmaceutical intermediates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Green Floor Care Chemical Systems for Commercial Facilities Market
Cleaning Chemicals
Commercial Cleaning Products Market
Cleaning Chemicals
Adhesive Remover Market
Cleaning Chemicals
Optical Foaming Cleaning Solution Market
Cleaning Chemicals
Mask Reticle Cleaning Agent Market
Cleaning Chemicals
Chlorhexidine Gluconate (CHG) Cloth Market
Cleaning Chemicals
Europe Metal Cleaning Chemicals Market
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
Metal Polish Products Market
Cleaning Chemicals
Glass and Metal Cleaner Market
Cleaning Chemicals
Commercial Deodorizers Market
Cleaning Chemicals
Multifunctional Cleaner Market
Cleaning Chemicals
Korea Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Electrostatic Liquid Cleaner Market
Cleaning Chemicals
Europe Mastic Remover Market
Cleaning Chemicals
Dust and Emission Control Chemicals for Ore Handling Market