
 Mastic Remover Market | 2026-2036
Mastic Remover Market Size, Share, and Industry Trends Forecast 2026-2036
Mastic Remover Market Analysis
United States manufacturing capacity for bio-based chemical processing is reshaping supply availability for mastic remover producers. Franmar leverages soy-based chemistry expertise to dominate the biodegradable segment. 3M sustains broad channel control across industrial distribution networks. Dumond Chemicals specializes in heavy-duty solvent formulations for professional contractors.
Mastic remover denotes a chemical formulation engineered to dissolve or emulsify adhesive residues, typically comprising citrus terpenes, petroleum distillates, or aqueous alkaline compounds with flash points ranging from 100°F to 350°F depending on solvent class. Its primary industrial purpose centers on substrate preservation during flooring demolition and surface refinishing operations. Biodegradable formulations now lead product type expansion as contractors face disposal cost pressures and jobsite exposure limits. Citrus-based chemistries command premium positioning in specialty shops serving restoration contractors. Solvent-based products retain volume dominance in wholesale distribution serving commercial maintenance providers.
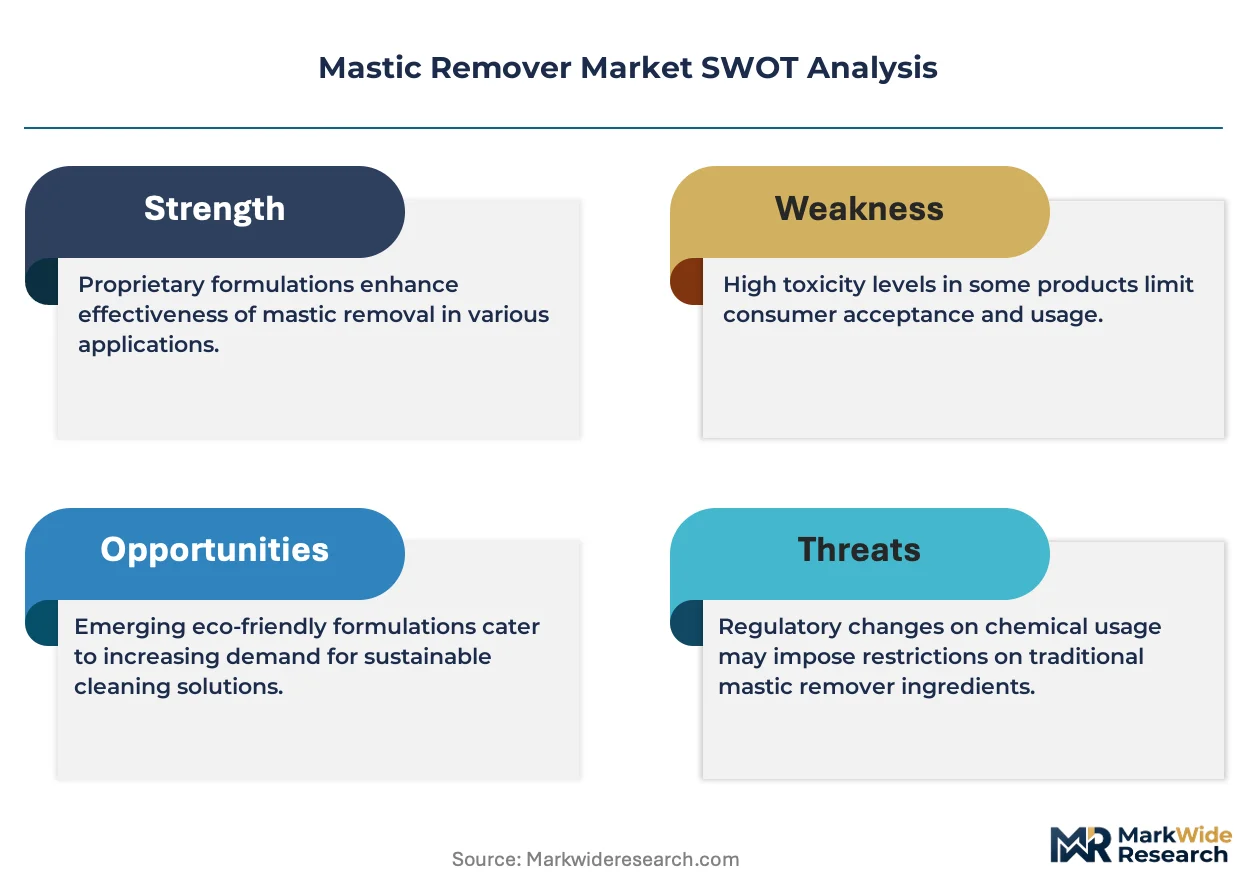
EPA NESHAP standards for hazardous air pollutants and OSHA permissible exposure limits for methylene chloride directly constrain solvent-based formulation options and push reformulation investments. California Air Resources Board SCM-2007 regulations impose the nation's strictest VOC limits on architectural coatings and related surface preparation products, effectively serving as a de facto national design standard. Stakeholders must monitor evolving state-level chemical restriction cascades to anticipate product portfolio obsolescence cycles.
Market Dynamics
State-level VOC restriction cascades are fragmenting formulation standards across jurisdictions, forcing producers to maintain parallel product portfolios. California Air Resources Board SCM-2007 regulations now serve as the de facto national design threshold for architectural coatings and surface preparation chemicals.
Growth Catalysts
- California Air Resources Board SCM-2007:The nation's strictest VOC limits on architectural coatings create regulatory pull for low-emission formulations. Manufacturers reformulate product lines to meet this threshold, capturing compliant demand across Sun Belt renovation markets.
- Commercial flooring demolition:Substrate preservation requirements in high-value restoration projects drive specification of specialized adhesive removers. Contractors prioritize chemistries that eliminate mechanical abrasion damage to concrete and wood substrates.
- Biodegradable chemistry:Soy-based and citrus terpene formulations reduce hazardous waste disposal costs. Jobsite exposure limits and liability concerns accelerate adoption among unionized contractor workforces.
Market Restraints
- Petroleum distillate feedstock volatility:Solvent-based formulations remain exposed to crude oil price swings. Margin compression during feedstock spikes limits pricing flexibility for wholesale distribution channels.
- Midwest chemical processing concentration:Bio-based feedstock refining capacity clusters in Iowa and Illinois. Supply disruption risks from localized weather events or logistics bottlenecks constrain national biodegradable product availability.
- Methylene chloride substitution timeline:OSHA permissible exposure limits constrain legacy solvent formulations. Reformulation R&D cycles extend 18-24 months, delaying compliant product launches.
Strategic Opportunities
- Texas Gulf Coast petrochemical corridor:Proximity to specialty chemical manufacturing infrastructure enables integrated production of next-generation aqueous alkaline compounds. Regional feedstock access supports cost-competitive biodegradable formulation scale-up.
- Restoration contractor certification programs:LEED AP and RRP-certified contractor networks create specification pull for low-toxicity products. Channel partnerships with training institutions lock in preferred product status.
- Online direct procurement:E-commerce platforms serving small commercial maintenance operators bypass traditional industrial distribution markups. Digital channel investment captures price-sensitive volume outside major metropolitan contractor networks.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in green chemistry transitions remains concentrated at land-grant universities. Recruitment competition from pharmaceutical and agricultural chemical sectors elevates compensation costs.
- State-by-state registration compliance:Each jurisdiction maintains independent chemical product notification requirements. Registration timeline variability extends market entry delays by 6-12 months for new formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mastic Remover Market |
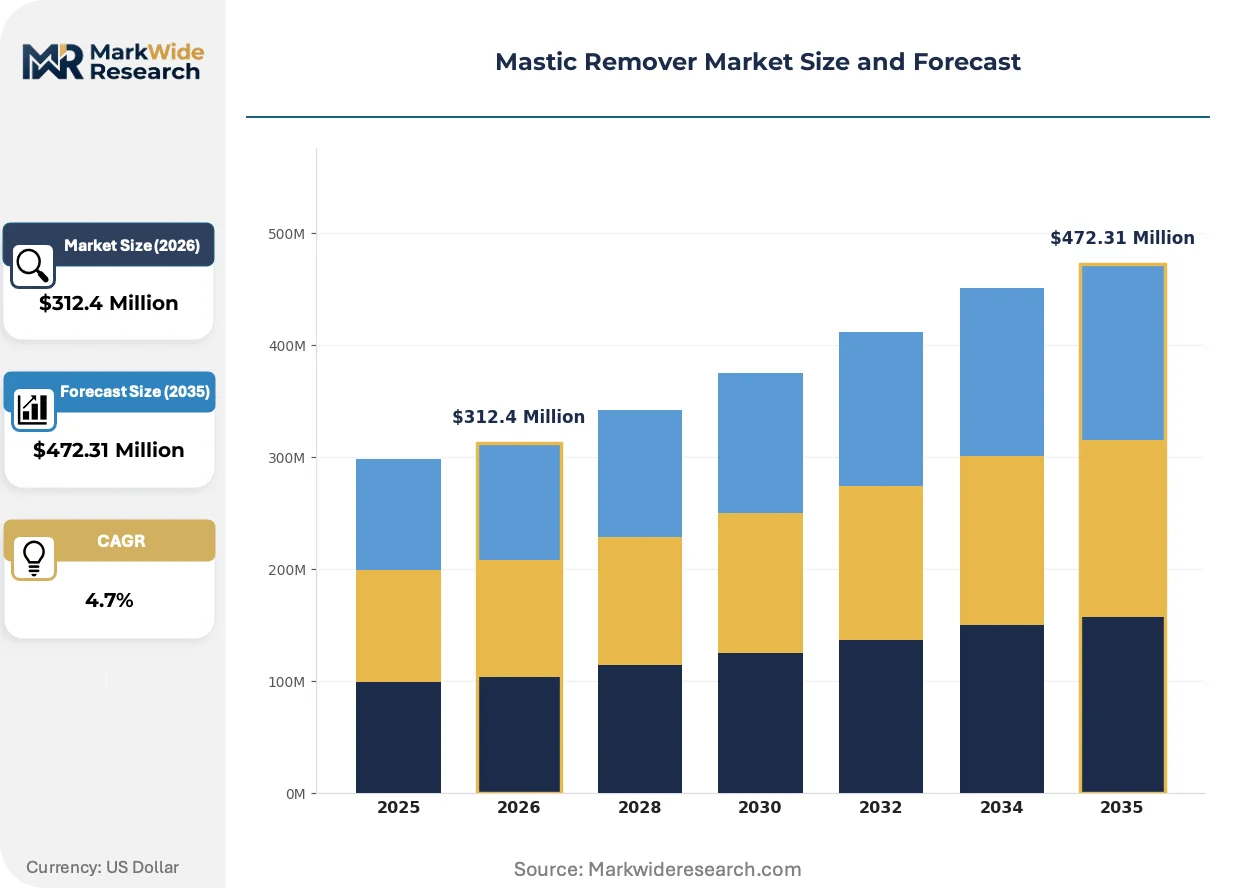
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Solvent, Solvent-Based, Biodegradable, Citrus-Based End User: Construction Industry, DIY Enthusiasts, Contractors, Maintenance Providers Application: Flooring Removal, Wallpaper Stripping, Adhesive Cleanup, Surface Preparation Distribution Channel: Online Retail, Home Improvement Stores, Wholesale Distributors, Specialty Shops |
| Companies Covered | Franmar, 3M, Dumond Chemicals, WM Barr & Company, Sunnyside Corporation, Abatement Technologies, Abatix Corp, American Building Restoration Products, Aramsco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mastic Remover Market Emerging Trajectories
Digital formulation tools and predictive chemistry software are compressing product development cycles. Regulatory monitoring systems now automate compliance tracking across fragmented state-level rulemaking.
Enzymatic biodegradation accelerants are virtualizing traditional solvent-based removal mechanisms. Restoration contractors in historic building projects specify these chemistries for delicate substrate preservation. The technology is virtualizing conventional mechanical stripping demand in premium renovation segments.
EPA NESHAP standards for hazardous air pollutants continue tightening methylene chloride emission thresholds. Industrial finishers and commercial maintenance operators face expanded reporting obligations. Solvent-based product lines in wholesale distribution are responding with accelerated aqueous formulation transitions.
Certification-driven contractor preferences now dominate specification decisions. LEED project requirements and RRP training penetration push procurement toward third-party validated low-toxicity products. This behavioral shift concentrates demand in specialty distribution channels serving certified professional networks across Florida, Arizona, and Nevada construction markets.
Mastic Remover Market Segmentation
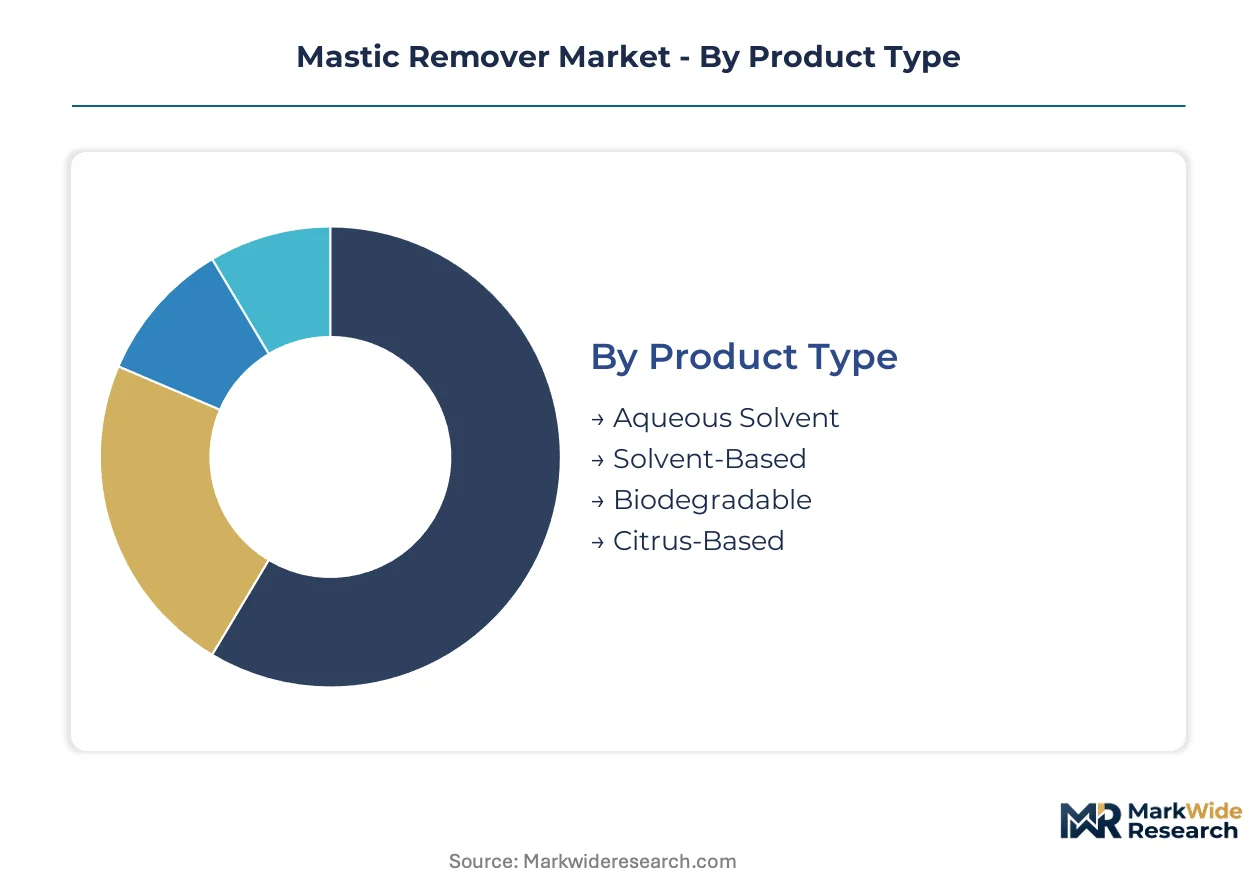
Formulation chemistry and contractor procurement patterns create distinct demand clusters across the mastic remover market. Each segment carries unique regulatory exposure and margin profiles that shape competitive positioning.
Product Type:
Mature solvent formulations coexist with emerging biodegradable alternatives as regulatory thresholds tighten across jurisdictions.
- Aqueous Solvent:Water-based alkaline formulations with flash points above 200°F serve high-temperature industrial stripping applications. Demand concentrates among unionized commercial contractors in California facing strict CARB SCM-2007 VOC limits.
- Solvent-Based:Petroleum distillate and methylene chloride formulations deliver aggressive adhesive dissolution for heavy-duty flooring demolition. Wholesale distribution channels in Texas and Florida retain volume dominance despite OSHA exposure limit pressures.
- Biodegradable:Soy-based enzymatic chemistries from Midwest bio-refining capacity reduce hazardous waste disposal liabilities.
- Citrus-Based:D-limonene terpene formulations target restoration contractors in historic building preservation segments.
Solvent-Based retains volume leadership; Biodegradable holds the steepest expansion curve.
End User:
Professional credentialing requirements separate certified contractor demand from price-sensitive maintenance procurement.
- Construction Industry:Large-scale commercial developers specify low-VOC formulations for LEED project compliance. Volume concentrates in Sun Belt states with active hospital and school renovation pipelines.
- Contractors:RRP-certified flooring specialists prioritize substrate-preserving chemistries for high-value restoration contracts. Unionized workforces in Nevada and Arizona drive specification of exposure-limit-compliant products.
- Maintenance Providers:Facility management operators in commercial real estate favor bulk aqueous formulations for recurring adhesive cleanup.
- DIY Enthusiasts:Home improvement retail channels serve small-scale wallpaper stripping and residential flooring projects.
Contractors capture the premium pricing tier; Maintenance Providers drive the highest purchase frequency.
Application:
Substrate value and demolition complexity determine formulation specification intensity across use cases.
- Flooring Removal:Concrete and wood substrate preservation in commercial renovation demands specialized adhesive removers. EPA NESHAP compliance requirements push aqueous formulation adoption in industrial facilities.
- Surface Preparation:Pre-coating adhesion optimization requires residue-free substrate conditioning. Demand clusters among automotive and aerospace finishing operations with strict contamination protocols.
- Adhesive Cleanup:Post-installation residue removal in manufacturing environments favors fast-evaporating solvent formulations.
- Wallpaper Stripping:Residential and light commercial renovation applications prioritize low-odor aqueous products.
Flooring Removal commands the highest formulation premium; Surface Preparation shows the most rapid specification upgrading.
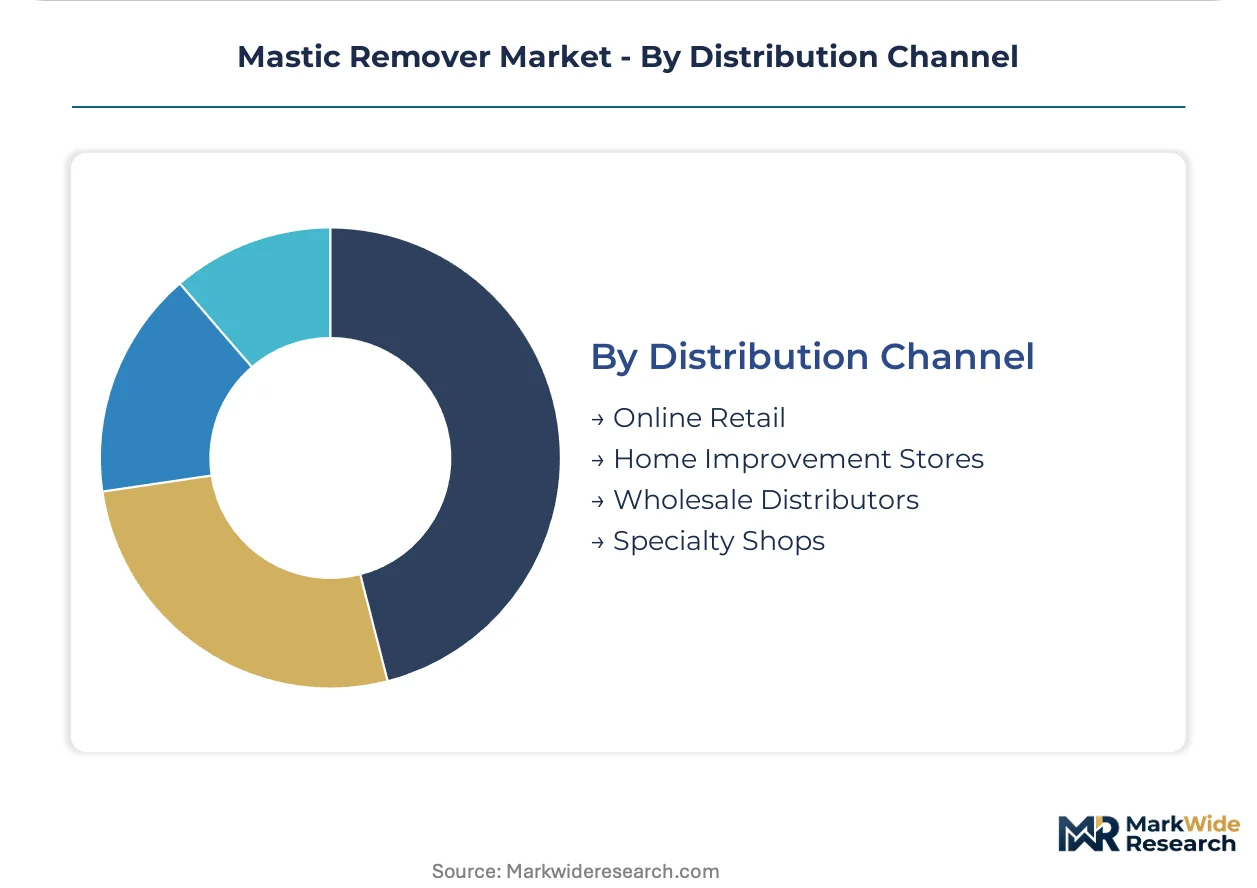
Distribution Channel:
Channel structure reflects contractor scale and procurement sophistication rather than geographic coverage alone.
- Wholesale Distributors:Industrial supply houses serving commercial maintenance networks carry solvent-based volume SKUs. Texas Gulf Coast petrochemical corridor proximity enables competitive pricing on petroleum-derived formulations.
- Specialty Shops:Restoration-focused retailers stock citrus-based and enzymatic premium products for historic building contractors. LEED AP certification programs create specification pull through training partnerships.
- Home Improvement Stores:Mass retail channels serve DIY volume with aqueous and low-VOC standard formulations.
- Online Retail:E-commerce platforms bypass traditional markups for small commercial operators outside major metropolitan contractor networks.
Wholesale Distributors maintain the deepest contractor relationships; Online Retail is climbing the fastest in transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel petrochemical corridor anchors North American specialty chemical production, with integrated refining infrastructure supporting mastic remover formulation scale-up across the Sun Belt renovation corridor.
United States
Commercial flooring demolition in Texas, Florida, and Arizona drives aqueous alkaline demand among unionized contractors. EPA NESHAP standards for hazardous air pollutants constrain methylene chloride formulations, accelerating aqueous transitions. The Houston Ship Channel corridor enables cost-competitive bio-based feedstock processing for next-generation enzymatic removers.
Canada
Historic building restoration in Quebec and Ontario concentrates citrus-terpene specification among RRP-certified contractors. Health Canada's PMRA maintains parallel VOC notification requirements with California thresholds. The Greater Toronto Area hosts specialty distribution networks serving cross-border certified contractor networks.
Germany
Industrial surface preparation for automotive finishing operations demands residue-free substrate conditioning chemistries. ECHA REACH registration requirements govern bio-based enzymatic formulation imports. The North Rhine-Westphalia chemical cluster supplies aqueous alkaline compounds to Central European flooring contractors.
China
Construction sector expansion in Yangtze River Delta and Pearl River Delta metro corridors absorbs bulk solvent-based formulations for commercial renovation. NMPA chemical notification procedures and provincial environmental bureau VOC limits tighten formulation standards. Shandong Peninsula petrochemical capacity feeds domestic mastic remover production for Southeast Asian export.
India
Hospital and school renovation pipelines in Maharashtra and Karnataka create specification pull for low-toxicity products among LEED-oriented developers. BIS standards for architectural coatings and surface preparation chemicals remain under development. The Gujarat chemical processing corridor enables import substitution for petroleum-derived solvent formulations.
Mastic Remover Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation chemistry and feedstock refining. The vendor base clusters around three functional tiers: petrochemical majors with integrated solvent supply, bio-refining specialists with Midwest soy-processing infrastructure, and regional formulators serving contractor certification networks. Strategic moves concentrate on geographic expansion into Sun Belt construction corridors and portfolio diversification toward enzymatic biodegradation technologies.
Within the bio-based formulation tier, Franmar exemplifies soy-chemistry specialization anchored to Iowa and Illinois feedstock refining capacity. 3M occupies a position spanning industrial distribution channel control across wholesale and specialty retail vectors. Dumond Chemicals represents the heavy-duty solvent archetype, with formulation positioning aligned to professional contractor demand for aggressive adhesive dissolution in commercial demolition applications.
| Leading Market Players |
|---|
| Franmar |
| 3M |
| Dumond Chemicals |
| WM Barr & Company |
| Sunnyside Corporation |
| Abatement Technologies |
| Abatix Corp |
| American Building Restoration Products |
| Aramsco |
| Others |
Supply Flow & Price Mechanics
The Houston Ship Channel petrochemical corridor concentrates specialty chemical manufacturing capacity, granting formulators with integrated refining access substantial leverage over pricing in downstream distribution. Soy-based feedstock processing clusters in Iowa and Illinois create a parallel bio-refining hub whose Midwest location introduces freight cost differentials that reshape regional pricing power.
Pricing Analysis
Volume-discount tiering separates certified contractor formulations from standard maintenance-grade products. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and hazardous waste disposal liability bundling. Cost compression in the solvent-based tier is intensifying because petroleum distillate feedstock volatility limits margin flexibility for wholesale distributors. Maintenance providers exhibit the highest price sensitivity, while LEED-certified contractors absorb premium positioning for substrate-preserving enzymatic chemistries.
Supply Chain Analysis
Tariff exposure between China and the United States constrains D-limonene terpene feedstock availability for citrus-based formulations. Manufacturing capacity draws from Texas, Iowa, and Illinois, with petroleum-derived solvents anchored in Gulf Coast petrochemical infrastructure and bio-based alternatives resting on Midwest soy-processing clusters. Single-source vulnerability concentrates in Shandong Peninsula specialty chemical imports for aqueous alkaline compounds. Distribution runs through industrial supply houses and restoration-focused specialty shops serving contractor certification networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mastic remover market sits in early-cycle expansion as EPA NESHAP compliance deadlines and state-level VOC cascades force aqueous formulation transitions across installed solvent-based product bases.
For Market Incumbents: Insulate market position by securing captive supply of Midwest bio-refining capacity and deepening channel control through RRP certification program partnerships. Methylene chloride substitution timelines compress reformulation windows; vertical integration into Iowa soy-processing infrastructure defends margin structure against feedstock volatility. For New Entrants and Emerging Players: Establish a beachhead in online direct procurement channels serving small commercial maintenance operators outside major metropolitan contractor networks. Underpenetrated demand for enzymatic biodegradation accelerants in historic building restoration segments offers specification entry through specialty shop partnerships with LEED AP training institutions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors bio-refining specialists with integrated formulation capabilities over pure-play petrochemical distributors. Five-to-ten year viability hinges on enzymatic chemistry R&D pipelines and state registration compliance infrastructure. Monitor California Air Resources Board rulemaking cascades as the inflection signal for portfolio obsolescence risk in legacy solvent formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Refining | Captive soy-processing capacity in Iowa secures feedstock cost advantage for enzymatic formulations. |
| Certification Program Partnerships | RRP and LEED AP training alliances lock in specification pull among unionized contractor workforces. |
| State Registration Compliance Infrastructure | Parallel product portfolios meet fragmented CARB SCM-2007 and EPA NESHAP thresholds across jurisdictions. |
| Enzymatic Formulation R&D Scale-Up | Next-generation biodegradation accelerants displace mechanical stripping in historic substrate preservation. |
| Online Direct Procurement Channel | E-commerce platforms bypass wholesale markups for price-sensitive maintenance operators in secondary markets. |
Methodological Framework
Desk research of customs trade data, EPA regulatory filings, and SEC 10-K disclosures preceded structured interviews with plant managers at bio-refining facilities, procurement leads at commercial flooring contractors, distribution channel partners in industrial supply houses, and technical R&D directors at specialty chemical formulators. Bottom-up volume estimates triangulated against top-down market sizing from petrochemical feedstock consumption patterns.
Assumptions around EPA NESHAP enforcement timelines and California VOC restriction diffusion patterns were held fixed across scenarios, while bio-based feedstock cost trajectories and contractor certification penetration rates were varied. The analytical framework segmented by formulation chemistry, end-user credentialing tier, application substrate value, and distribution channel structure. CAGRs derived from regression against construction spending indices and renovation permit flows in Sun Belt states.
Stress conditions across petroleum price volatility bands, Midwest logistics disruption scenarios, and state registration timeline variability were modeled; outcomes outside those bands fall beyond the analytical envelope. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Glass Cleaner Market
Cleaning Chemicals
Surface Cleaning Products Market
Cleaning Chemicals
Global Cleaner and Degreaser Aftermarket Market
Cleaning Chemicals
US Institutional Cleaning Detergents Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market
Cleaning Chemicals
Coating Removal System Market
Cleaning Chemicals
Home Care Chemicals Market
Cleaning Chemicals
Fabric Softener Market
Cleaning Chemicals
Home Insecticides Market
Cleaning Chemicals
Aviation Cabin Cleaning Chemical Market
Cleaning Chemicals
Cleaning Fluids Market
Cleaning Chemicals
Limestone Cleaner Market
Cleaning Chemicals
Fabric Conditioner Market
Cleaning Chemicals
Adhesive Remover Market
Cleaning Chemicals
Liquid Detergent Market
Cleaning Chemicals
Dust Control Systems and Suppression Chemicals Market