
 Indoor Bike Trainers Market | 2026-2036
Indoor Bike Trainers Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Bike Trainers Market Foresight
Buyer concentration among dedicated cyclists and triathletes is pivoting toward fragmented demand across home fitness enthusiasts and boutique studio operators. Garmin Tacx leverages its integration with cycling computers and GPS ecosystems to sustain loyalty among performance-oriented users. Wahoo Fitness anchors its position through proprietary KICKR ecosystem control over software-hardware pairing. Elite competes on manufacturing scale from its Italian base, supplying OEM trainers to multiple international brands.
An indoor bike trainer is a mechanical or electromechanical device that secures a bicycle's rear wheel or replaces the rear wheel entirely, using fluid, magnetic, or electromagnetic resistance to simulate road riding conditions with power measurement accuracy typically within one to two percent. Smart trainers incorporate integrated power meters, flywheels exceeding six kilograms, and automatic resistance control for immersive simulation. Direct drive trainers command the premium tier due to superior power accuracy and reduced tire wear, while wheel-on trainers retain volume leadership among entry-level home users. Interactive technology segments are expanding fastest as platforms demand real-time resistance synchronization, though standalone units still dominate club and commercial gym procurement.
FCC certification governs wireless transmission protocols for US-market smart trainers, while CE marking mandates electromagnetic compatibility and mechanical safety standards across European distribution channels. Japan's METI enforces electrical appliance safety benchmarks that constrain import pathways for uncertified equipment. Stakeholders must monitor evolving interoperability standards between hardware manufacturers and subscription-based training platforms as platform exclusivity agreements increasingly determine hardware purchase decisions.
Market Dynamics
The dominance of connected training ecosystems is compressing hardware margins while elevating software-hardware bundling as the primary competitive battleground. Direct drive electromagnetic trainers now anchor premium positioning, forcing wheel-on manufacturers toward price-driven volume plays.
Growth Catalysts
- Smart trainer protocol standardization:FCC certification for wireless transmission and ANT+ interoperability eliminates friction for US consumers integrating trainers with third-party cycling platforms.
- Home fitness infrastructure permanence:Dedicated training spaces in residential properties sustain replacement cycles for high-accuracy power measurement equipment among amateur cyclists.
- Fluid resistance refinement:Advanced thermal dissipation engineering in fluid trainers narrows the performance gap with electromagnetic systems at lower price points.
Market Restraints
- Rare earth magnet supply concentration:Neodymium procurement dependency on Chinese processing facilities exposes electromagnetic trainer manufacturers to input cost volatility and export control risk.
- CE marking complexity:Electromagnetic compatibility testing and mechanical safety validation for European distribution extends product launch timelines by four to six months.
- Stationary bike substitution:Integrated smart bikes from Peloton and NordicTrack capture consumers prioritizing convenience over wheel compatibility.
Strategic Opportunities
- Japan METI compliance pathway:Electrical appliance safety certification for the Japanese market remains underpenetrated by European manufacturers, creating first-mover advantage for compliant entrants.
- Boutique studio fleet procurement:Spin studio chains in Germany seek durable wheel-on trainers for high-rotation commercial environments with standardized maintenance protocols.
- Photovoltaic pairing:Off-grid training setups pairing human power generation with battery storage appeal to sustainability-focused cyclists in California and Colorado.
Industry Challenges
- Power calibration technician scarcity:Accurate strain gauge calibration and firmware debugging require specialized expertise concentrated among cycling industry veterans.
- Platform exclusivity integration:Zwift, TrainerRoad, and Wahoo Systm compete for hardware partnership locks, fragmenting development resources across incompatible API requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Bike Trainers Market |
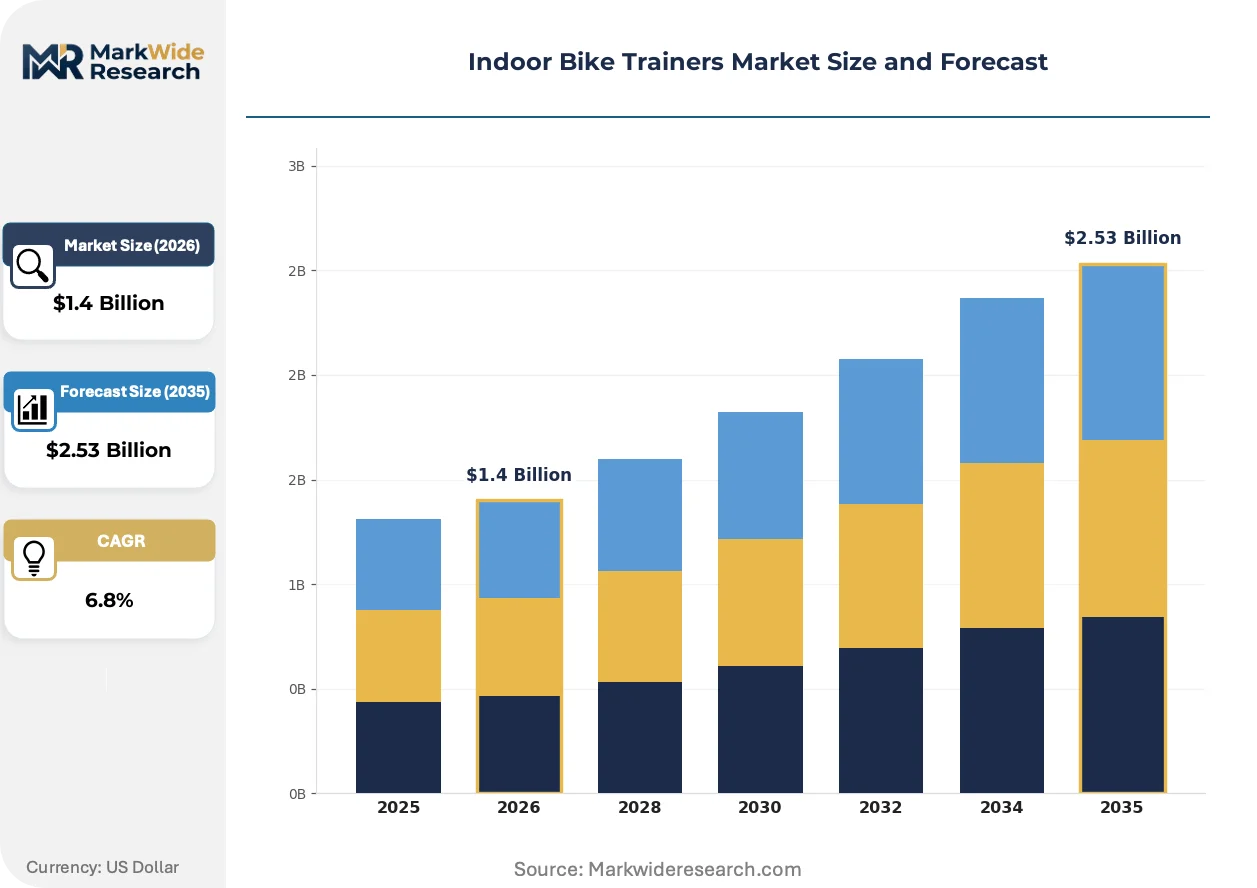
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Smart Trainers, Wheel-On Trainers, Direct Drive Trainers, Turbo Trainers Technology: Bluetooth, ANT+, Standalone, Interactive End User: Home Users, Gyms, Professional Athletes, Fitness Clubs Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Wahoo Fitness, Garmin Tacx, Saris, Elite, Kinetic by Kurt, JetBlack, Zwift, Minoura, Technogym, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Bike Trainers Market Shifts & Advancements
Resistance mechanism convergence with real-time environmental simulation is erasing the boundary between indoor training and outdoor ride replication. Hardware differentiation now hinges on software ecosystem depth rather than raw mechanical specifications.
Electromagnetic resistance with integrated power measurement is unifying the mid-premium trainer segment. Serious amateur cyclists and triathlon clubs adopt these systems for structured interval training. The technology is unifying hardware procurement decisions around platform subscription bundling, compressing standalone unit sales.
Japan's METI electrical appliance safety standards are tightening import documentation requirements for wireless-enabled trainers. Manufacturers must submit expanded electromagnetic emission testing to customs authorities before commercial distribution. Smart trainer imports face extended clearance timelines, advantaging domestic distributors with established compliance relationships.
Subscription bundling is displacing hardware-only transactions across direct-to-consumer channels. Boutique fitness studios and cycling clubs now procure trainers exclusively through platform-affiliated fleet programs. This shift concentrates most visibly in Germany and the United States, where Zwift and Wahoo control instructor certification networks.
Indoor Bike Trainers Market Segmentation
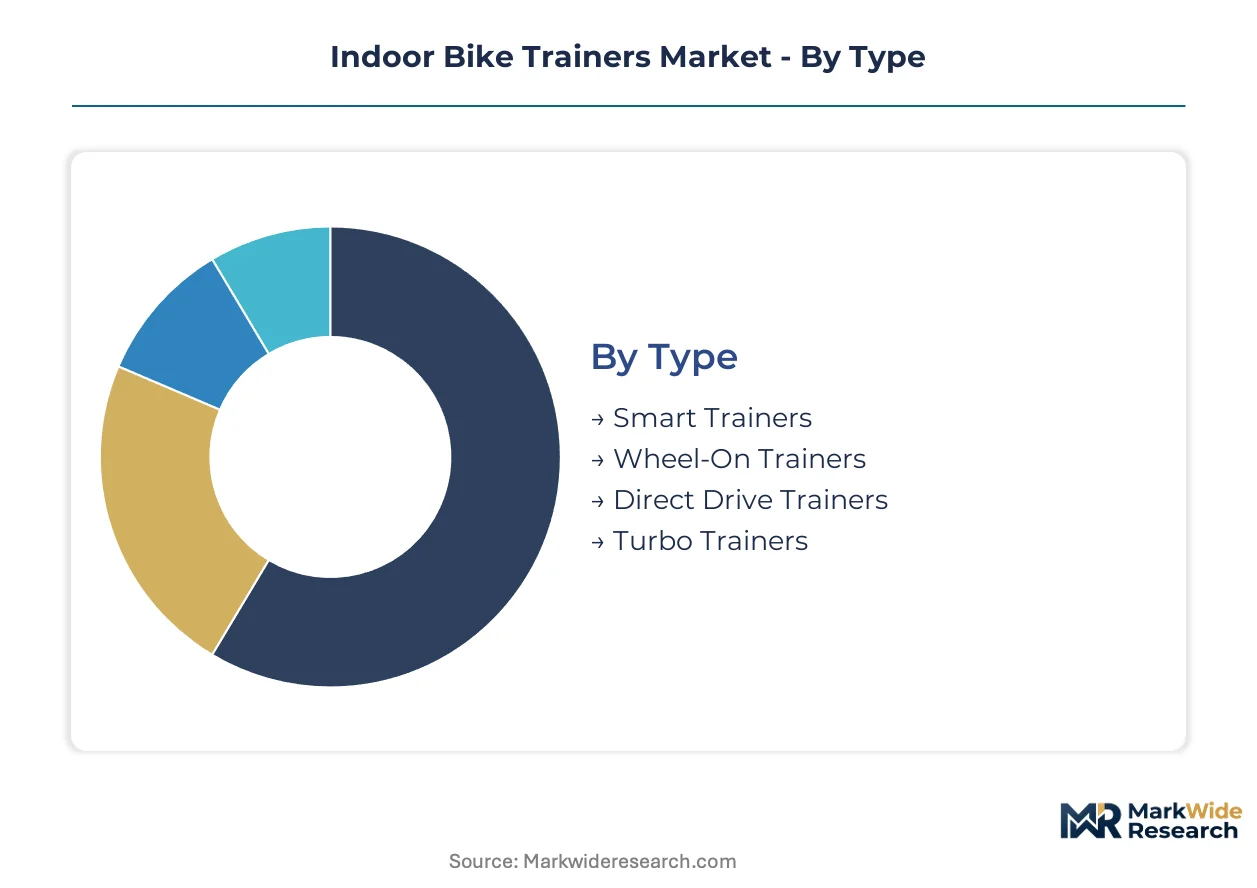
Segmentation in the indoor bike trainer market reveals how purchase decisions split between technical sophistication and accessibility requirements. Understanding these divides exposes where margin compression hits hardest and where ecosystem lock-in secures pricing power.
Type:
Buyers weigh accuracy demands against installation convenience when selecting trainer architecture.
- Smart Trainers:Integrated power meters, automatic resistance control, and real-time platform synchronization define this segment. Demand concentrates among competitive cyclists and triathletes in the United States and Germany where Zwift and TrainerRoad subscriptions drive hardware procurement decisions.
- Direct Drive Trainers:These units replace the rear wheel entirely, delivering power accuracy within one to two percent through electromagnetic resistance and flywheels exceeding six kilograms. Japanese buyers prioritize this architecture for its reduced tire wear and superior thermal stability during extended sessions.
- Wheel-On Trainers:Entry-level home users favor these units for their lower cost and minimal setup complexity, though tire slippage and calibration drift limit accuracy.
- Turbo Trainers:Basic fluid or magnetic resistance units without connectivity features retain presence in commercial gym fleets where standardization trumps simulation depth.
Wheel-on trainers lead on scale; smart trainers lead on momentum.
Technology:
Protocol compatibility now functions as a baseline hygiene factor rather than a differentiator.
- Interactive:Real-time resistance synchronization with virtual environments demands bidirectional communication between hardware and software platforms. German boutique studios and California home fitness enthusiasts drive procurement here, with subscription bundling displacing standalone transactions.
- Bluetooth:Universal smartphone compatibility makes this protocol essential for casual home users prioritizing plug-and-play simplicity over specialized cycling computer integration.
- ANT+:Dedicated cyclists and triathletes demand this protocol for seamless pairing with Garmin cycling computers and heart rate monitors.
- Standalone:Non-connected units persist in budget-conscious segments and commercial environments where platform subscriptions add operational complexity.
Standalone units retain volume leadership; interactive systems are climbing the fastest.
End User:
Procurement authority separates between individual buyers optimizing personal performance and institutional purchasers managing fleet durability.
- Home Users:Dedicated training spaces in residential properties sustain replacement cycles for high-accuracy equipment among amateur cyclists in the United States, Germany, and Japan.
- Professional Athletes:Power measurement precision within one percent and thermal stability during interval sessions drive specification requirements for this segment.
- Fitness Clubs:Standardized maintenance protocols and durability under high-rotation use prioritize wheel-on trainers with replaceable wear components.
- Gyms:Commercial procurement favors standalone units or basic smart trainers without subscription dependencies to minimize ongoing operational costs.
Home users dominate absolute unit volume; professional athletes command the steepest expansion trajectory.
Price Tier:
Cost positioning aligns directly with power accuracy specifications and ecosystem integration depth.
- Premium:Direct drive electromagnetic systems with integrated power meters and automatic resistance control target serious amateurs and triathlon clubs. German and Japanese buyers concentrate here, with platform subscription bundling compressing standalone hardware margins.
- Luxury:Limited-edition collaborations and museum-grade industrial design command prices detached from functional specifications, appealing to collectors and brand loyalists in California and Colorado.
- Mid-Range:Refined fluid resistance systems with basic connectivity satisfy price-conscious enthusiasts seeking acceptable accuracy without ecosystem lock-in.
- Budget:Basic magnetic or fluid trainers without power measurement serve entry-level cyclists testing indoor training commitment before upgrade investments.
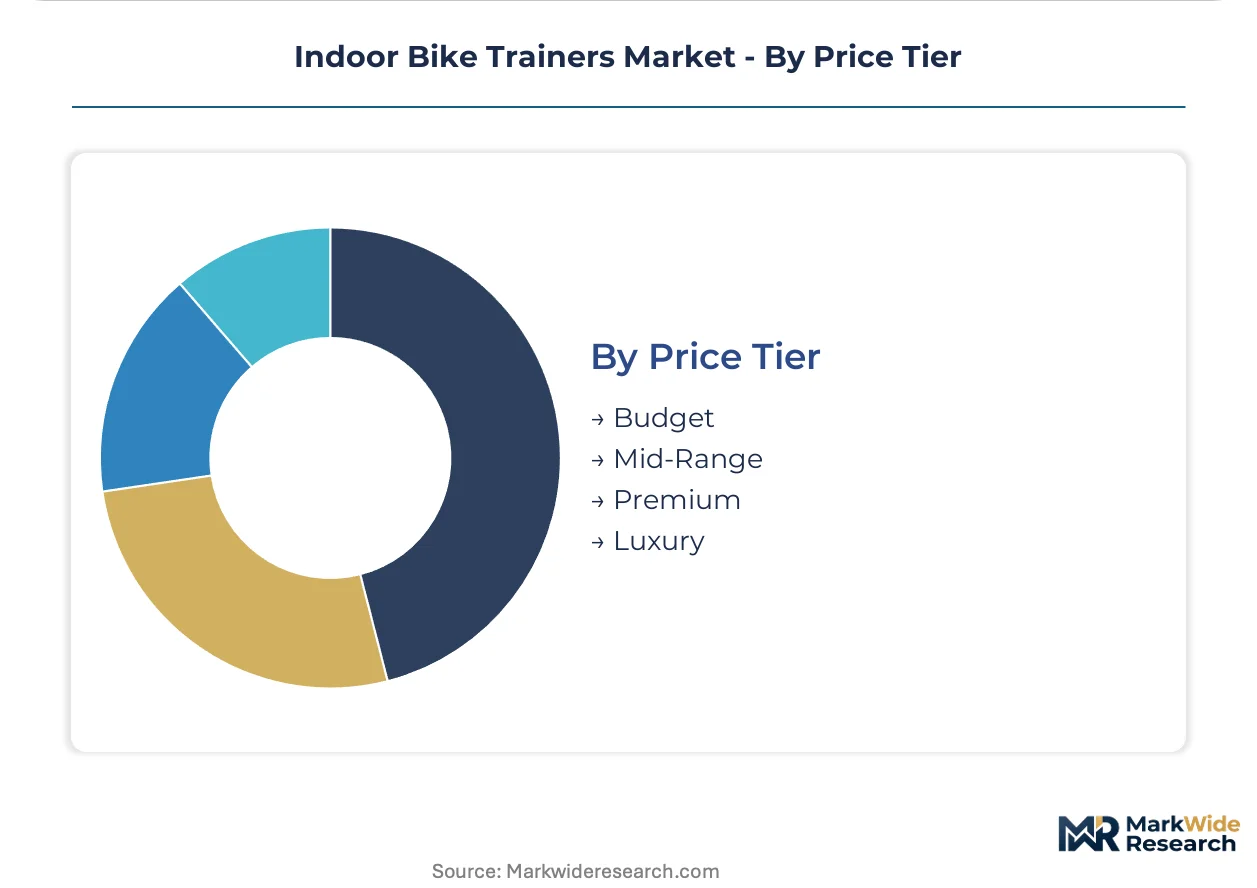
Budget and mid-range tiers capture unit volume; premium and luxury segments concentrate margin extraction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers prioritize ecosystem integration while German consumers emphasize power measurement precision, revealing divergent premium market logics across the Atlantic.
United States
Home fitness infrastructure permanence sustains replacement cycles for high-accuracy equipment among amateur cyclists and triathletes. FCC certification for wireless transmission protocols governs smart trainer market entry, eliminating friction for consumers integrating hardware with third-party cycling platforms. California and Colorado host concentrated demand clusters where sustainability-focused cyclists seek off-grid training setups pairing human power generation with battery storage.
Germany
Structured interval training adoption among triathlon clubs drives procurement of direct drive electromagnetic systems with integrated power meters. CE marking mandates electromagnetic compatibility testing and mechanical safety validation, extending product launch timelines by four to six months for European distribution. Boutique studio chains in Berlin and Munich seek durable wheel-on trainers for high-rotation commercial environments with standardized maintenance protocols.
Japan
Thermal stability during extended sessions and reduced tire wear priorities elevate direct drive trainer architecture above wheel-on alternatives. METI enforces electrical appliance safety benchmarks that constrain import pathways for uncertified equipment, advantaging domestic distributors with established compliance relationships. Tokyo and Osaka metropolitan areas concentrate demand among dedicated cyclists requiring power accuracy within one to two percent.
United Kingdom
Subscription bundling through platform-affiliated fleet programs displaces standalone hardware transactions across direct-to-consumer channels. Post-Brexit regulatory alignment with CE marking standards maintains electromagnetic compatibility requirements for European-origin imports. London and Southeast England host cycling club procurement networks where Zwift and Wahoo control instructor certification networks.
Italy
Manufacturing scale from domestic production bases supplies OEM trainers to multiple international brands, anchoring European supply capacity. REACH compliance for chemical substances in resistance fluids and electromagnetic components governs material selection for export-oriented producers. The Veneto region concentrates precision engineering capabilities serving mid-premium trainer segment assembly.
Indoor Bike Trainers Market Competitive Landscape
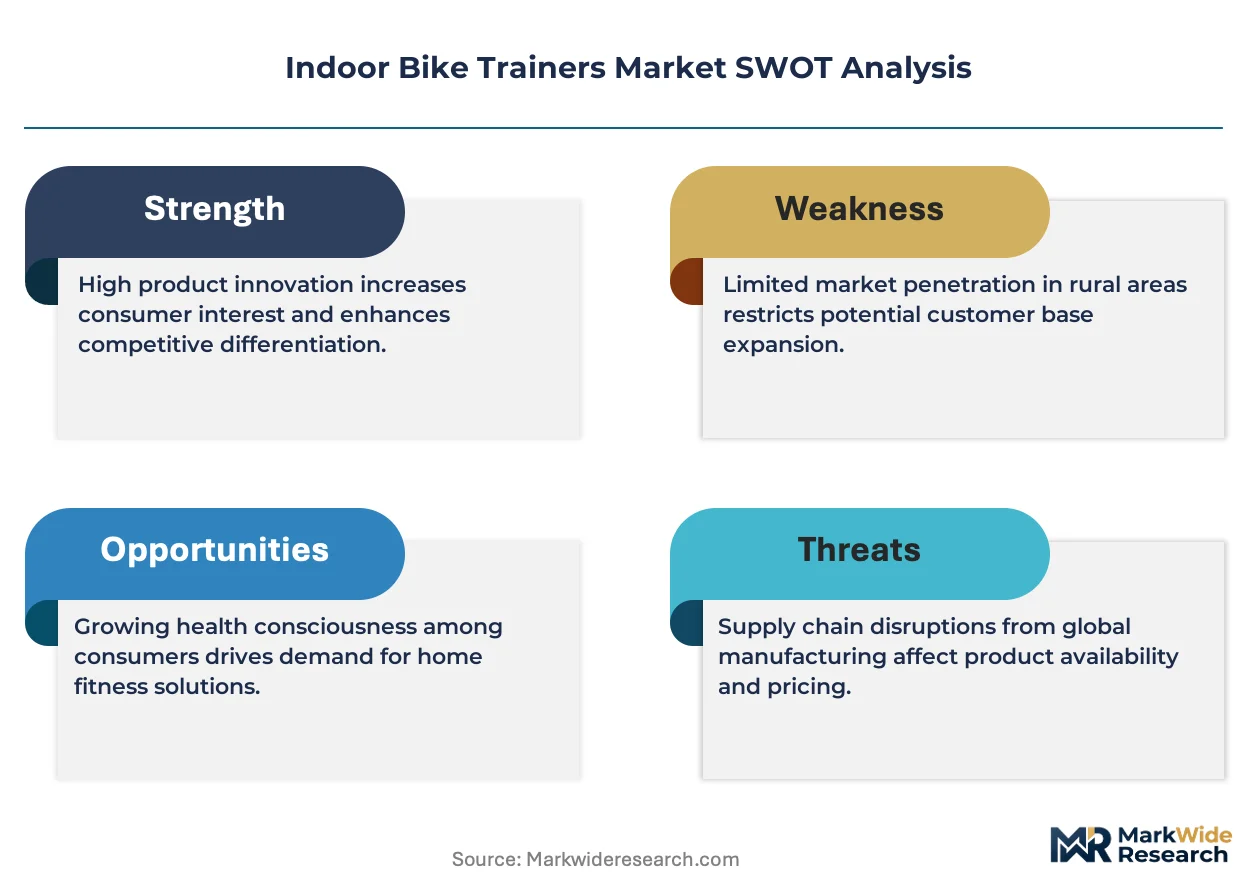
Italian producers anchor manufacturing scale tier; Dutch specialists hold ecosystem integration positions. The vendor base splits between consolidated platform-hardware bundlers and fragmented component suppliers. Three archetypes dominate: GPS ecosystem integrators, proprietary platform controllers, and OEM scale manufacturers. Competitive moves concentrate on software-hardware partnership locks and geographic compliance certification acquisition.
Among North American platform operators, Zwift occupies a position exemplifying subscription-first bundling strategy. Garmin Tacx and Wahoo Fitness represent the ecosystem control archetype, anchoring loyalty through cycling computer and GPS integration depth. These three companies sit within the premium tier where platform exclusivity agreements increasingly determine hardware purchase decisions.
| Leading Market Players |
|---|
| Wahoo Fitness |
| Garmin Tacx |
| Saris |
| Elite |
| Kinetic by Kurt |
| JetBlack |
| Zwift |
| Minoura |
| Technogym |
| Others |
Supply & Pricing Matrix
Japan's METI electrical appliance safety standards gate qualified supply for electromagnetic trainer imports, compressing premium-tier pricing access to domestic distributors with established compliance relationships while elevating cost structures for uncertified European entrants.
Pricing Analysis
Capacity additions in Italy are reshaping price floors for mid-range direct drive trainers as Elite scales OEM output for international brands. Three-tier pricing structure across premium, standard, and economy levels separates electromagnetic systems with sub-one-percent accuracy from fluid-based alternatives and basic magnetic units. Cost compression in the wheel-on segment is intensifying because Peloton and NordicTrack stationary bikes capture convenience-oriented buyers. Home fitness enthusiasts show highest price sensitivity, while triathlon clubs accept premium positioning for power precision.
Supply Chain Analysis
Single-source vulnerability sits with Chinese neodymium processing facilities that supply rare earth magnets for electromagnetic resistance systems. Manufacturing draws from Italy for precision assembly, Taiwan for electronic components, and China for magnet raw materials. Tariff exposure runs through trans-Pacific component flows for US-bound smart trainers. Distribution runs through direct-to-consumer channels for home users and platform-affiliated fleet programs for boutique studios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: European manufacturers face four-to-six-month CE marking delays while Japanese compliance gaps create first-mover premiums for prepared entrants.
For Market Incumbents: Deploy certification investments as defensive moats. Garmin Tacx and Wahoo Fitness should accelerate METI pathway completion ahead of European rivals to lock Tokyo and Osaka demand. Anchor ecosystem loyalty through cycling computer integration depth, resisting platform exclusivity fragmentation that drains development resources. For New Entrants and Emerging Players: Enter via photovoltaic pairing for off-grid training setups in California and Colorado sustainability clusters. Target boutique studio fleet procurement in Germany, where Berlin and Munich chains seek durable wheel-on trainers with standardized maintenance protocols. Pursue white-label OEM supply relationships with Italian engineering houses lacking brand presence. For Investors and Strategic Acquirers: Roll-up economics work for regional distributors with METI compliance relationships because import clearance timelines concentrate procurement authority. Five-to-ten-year viability hinges on software-hardware bundling depth rather than standalone hardware margins. Watch Zwift-TrainerRoad-Wahoo platform exclusivity negotiations as inflection signal for hardware procurement lock-in patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ANT+ and Bluetooth protocol standardization eliminates friction for Zwift and TrainerRoad subscribers. |
| Geographic Expansion | METI certification acquisition opens Tokyo metropolitan demand clusters to compliant European manufacturers. |
| Backward Integration | Captive neodymium magnet supply insulates electromagnetic trainer production from Chinese export controls. |
| Product Launch | Photovoltaic-compatible trainers capture California sustainability-focused cyclist segments. |
| Strategic Partnership | Boutique studio fleet programs in Germany concentrate procurement through Zwift-affiliated networks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions covered product managers at smart trainer OEMs, procurement leads at German boutique studio chains, cycling computer ecosystem engineers, and aftermarket service technicians specializing in strain gauge calibration. Secondary validation drew from FCC equipment authorization databases, METI electrical appliance safety filings, CE marking notification records, and customs trade data for trainer component flows. Bottom-up demand modeling and top-down supply capacity estimates were triangulated for cross-checking.
Segment-weighting applied trainer type, technology protocol, end-user category, and price tier dimensions across the analysis window. CAGRs were derived from installed base replacement cycles, subscription platform growth curves, and regional fitness spending elasticity coefficients. Resistance mechanism adoption curves and electromagnetic component cost trajectories fed specific forecast inputs.
Inputs from regulatory filing databases and platform subscriber disclosures were available through the study window; gaps in real-time inventory channel data introduce uncertainty bands around near-term volume estimates. Forecasts reflect documented assumptions about subscription bundling penetration and rare earth magnet supply stability. Platform exclusivity renegotiations or METI standard revisions could materially revise trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Europe Refurbished Fitness Equipment Market
Fitness Equipment
Treadmill Ergometer Market
Fitness Equipment
Pilates Equipment Market
Fitness Equipment
Middle East and Africa Fitness Equipment Market
Fitness Equipment
Military Fitness Training Equipment Market
Fitness Equipment
North America Home Fitness Equipment Market
Fitness Equipment
Muscle Oxygen Monitors Market
Fitness Equipment
Yoga Equipment Market
Fitness Equipment
Elliptical Trainers Market
Fitness Equipment
Hydrotherapy Treadmills Market
Fitness Equipment
Europe E-Commerce Home Fitness Products Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
Pilates Reformer Market
Fitness Equipment
Personal Exercise Mats Market
Fitness Equipment
Leg Exercise Equipment Market
Fitness Equipment
Gymnastic Springboard Market