
 Pilates Reformer Market | 2026-2036
Pilates Reformer Market Size, Share, and Industry Trends Forecast 2026-2036
Pilates Reformer Market Analytics
Modular reformer configurations that separate carriage systems from tower attachments is rebalancing how boutique studios allocate capital across equipment categories. Balanced Body Inc. leverages its vertically integrated manufacturing in Sacramento to control component quality across wood and aluminum frame lines. Merrithew International Inc. anchors its position through instructor education networks that lock in studio loyalty and recurring accessory purchases. Gratz Pilates sustains premium pricing by specializing in handcrafted steel-frame designs that dominate high-end rehabilitation clinics.
A Pilates reformer consists of a sliding carriage mounted on a rectangular frame, connected to adjustable spring resistance systems typically ranging from four to five tension levels, designed to facilitate controlled resistance training through full-range movement patterns. Studio reformers built with maple or rock maple frames dominate commercial installations where load capacity exceeds 400 pounds and daily use cycles surpass twenty sessions. Electric reformers incorporating motorized incline and resistance adjustment represent the fastest-expanding product category as physical therapy chains automate session protocols. Aluminum-frame compact reformers occupy the highest-margin tier among home-user segments where space constraints drive purchasing decisions over raw performance specifications.
The Consumer Product Safety Commission governs stability and pinch-point standards for reformers sold in the United States, while the EU Machinery Directive mandates third-party conformity assessment for electric reformer variants prior to CE marking placement. ISO 20957-1 fixed training equipment standards influence liability insurance underwriting for studio operators, effectively filtering non-compliant manufacturers from commercial procurement channels. Stakeholders must monitor how evolving accessibility regulations in multiple jurisdictions reshape platform height and transfer-assist design requirements before committing to next-generation product architectures.
Market Dynamics
Post-pandemic hybrid training models have permanently altered equipment procurement cycles, with boutique studios now prioritizing modular configurations that accommodate both in-person and remote instruction formats.
Growth Catalysts
- EU Machinery Directive compliance:Updated CE marking requirements for motorized exercise equipment are accelerating studio upgrades to certified electric reformer variants.
- Physical therapy chain automation:Large rehabilitation networks are standardizing on programmable resistance systems to reduce session-to-session variability.
- Germany studio density:Instructor certification rates exceeding other European markets create concentrated demand for commercial-grade maple-frame installations.
Market Restraints
- Rock maple supply volatility:North American hardwood pricing fluctuations directly compress margins on premium studio reformer lines.
- Third-party conformity assessment:EU Machinery Directive mandates for electric variants add 12-18 week lead times before market entry.
- Home fitness substitution:Connected stationary bikes and smart mirrors capture overlapping wellness budgets from residential buyers.
Strategic Opportunities
- Accessibility mandate alignment:Evolving platform height regulations in multiple jurisdictions reward early redesign of transfer-assist mechanisms.
- Aluminum-frame compact segment:Space-constrained urban apartments in dense metropolitan areas favor collapsible home-use configurations.
- Instructor education lock-in:Certification network expansion creates recurring accessory revenue streams and reduces competitive switching.
Industry Challenges
- ISO 20957-1 liability underwriting:Insurance carriers are tightening coverage requirements for non-compliant studio operators, filtering procurement channels.
- Spring calibration technician shortage:Specialized maintenance skills for tension system adjustment lag behind installed base growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pilates Reformer Market |
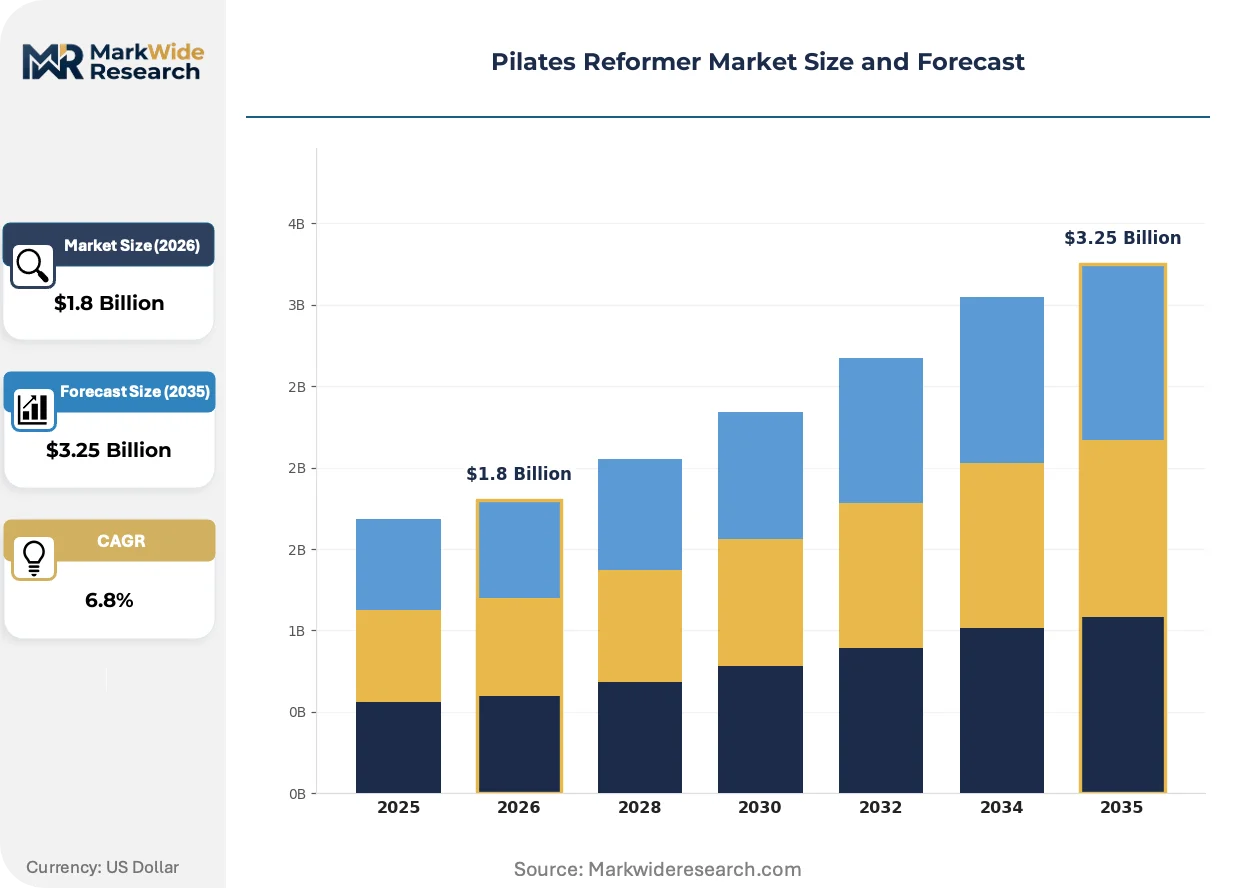
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Reformer, Electric Reformer, Compact Reformer, Studio Reformer Material: Wood, Aluminum, Steel, Plastic End User: Fitness Studios, Home Users, Rehabilitation Centers, Athletic Facilities Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesale |
| Companies Covered | Decathlon SA, BASI Systems, Balanced Body Inc., Peak Pilates, Align Pilates Equipment Ltd, Merrithew International Inc., Stamina Products Inc., Sivan Health and Fitness, Gratz Pilates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pilates Reformer Market Evolving Landscape
Motorized resistance systems are compressing traditional mechanical spring architectures, while regulatory accessibility mandates and procurement model fragmentation simultaneously reshape product development priorities.
Sensor-integrated carriage tracking is absorbing session data capture functions previously handled by separate wearable devices. Physical therapy chains are adopting these systems fastest, automating protocol documentation for reimbursement compliance. This convergence is absorbing adjacent digital health budgets into capital equipment decisions.
CE marking requirements under the EU Machinery Directive are elevating third-party assessment costs for electric reformer variants. Manufacturers serving European markets are consolidating compliance functions in-house. German studio operators face the steepest adjustment timelines due to early enforcement priority.
Leasing arrangements are displacing outright purchase for boutique studios managing cash flow across hybrid model transitions. Equipment financiers are inserting service bundling into contract structures. This shift concentrates most visibly in urban centers where studio opening costs have climbed fastest.
Pilates Reformer Market Segmentation
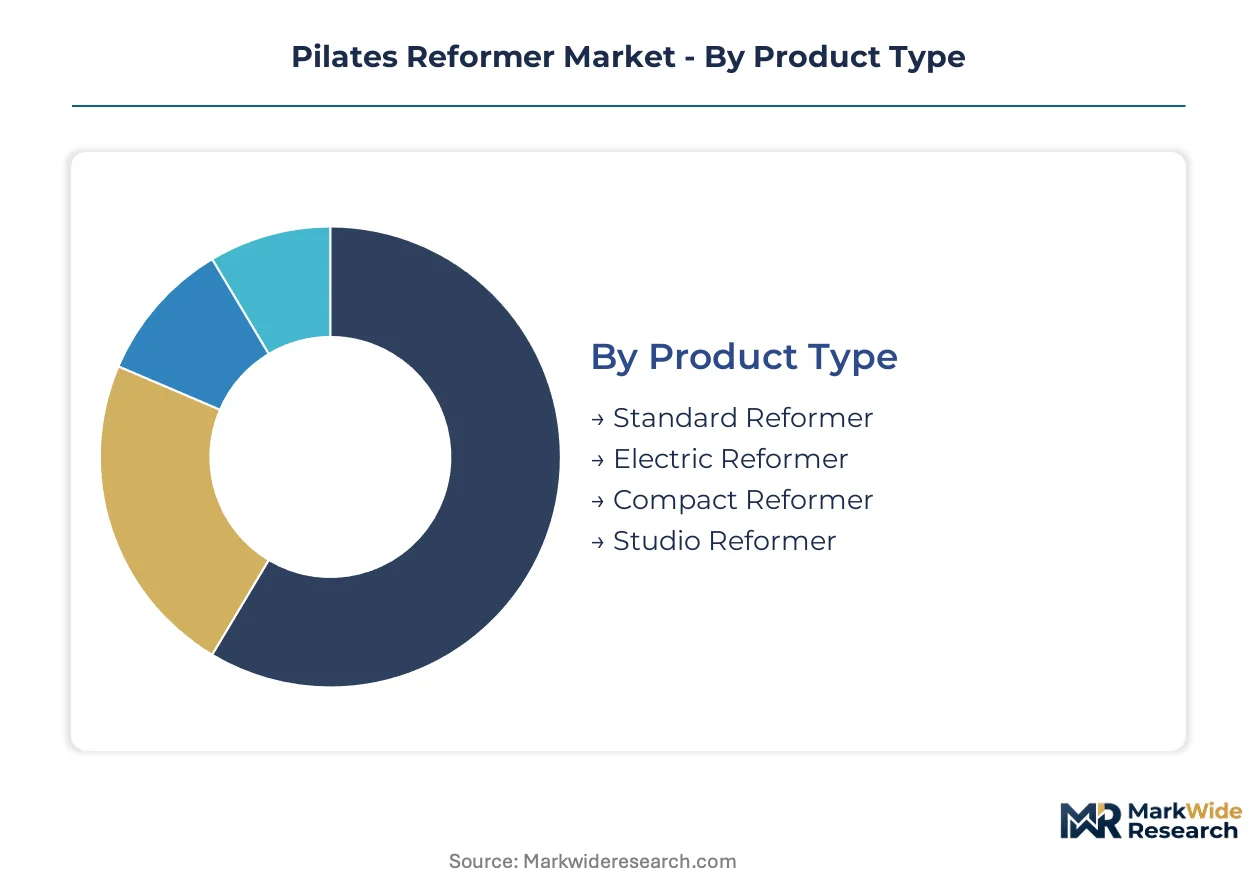
Segmentation in the Pilates reformer market determines compliance pathways, margin structures, and procurement channel access. Material composition and motorized features trigger distinct regulatory obligations across major markets.
Product Type:
Certification burdens vary sharply across this dimension, with electric variants requiring third-party conformity assessment under EU Machinery Directive while mechanical configurations face lighter oversight.
- Studio Reformer:Constructed with rock maple or aluminum frames rated for 400+ pound load capacity and twenty-plus daily use cycles. Demand concentrates in Germany, where instructor certification density and boutique studio expansion drive commercial-grade procurement despite rock maple supply volatility compressing manufacturer margins.
- Electric Reformer:Motorized incline and resistance adjustment systems enable programmable session protocols. Physical therapy chains in Germany and the United States standardize on these variants to automate documentation for reimbursement compliance, though CE marking mandates add 12-18 week lead times.
- Standard Reformer:Traditional spring-resistance mechanical systems serve cost-sensitive studio operators and home users without motorized complexity.
- Compact Reformer:Collapsible aluminum-frame configurations dominate space-constrained urban apartments where purchasing decisions prioritize footprint over raw performance specifications.
Studio Reformer sits at the top of the volume ranking, with Electric Reformer climbing the fastest.
Material:
Cost tier alignment separates premium hardwood offerings from mid-market aluminum and economy steel alternatives, with direct implications for warranty terms and resale value retention.
- Wood:Rock maple and maple frames anchor premium commercial installations. German boutique studios favor these for aesthetic consistency and durability certification, though North American hardwood pricing fluctuations directly compress margins.
- Aluminum:Lightweight corrosion-resistant frames enable compact collapsible designs. Home users in dense metropolitan areas prioritize these configurations, creating the highest-margin tier among residential segments.
- Steel:Handcrafted steel-frame designs sustain premium positioning in high-end rehabilitation clinics where load precision and longevity justify elevated capital outlay.
- Plastic:Injection-molded components reduce unit economics for entry-level home-use variants, though load rating limitations restrict commercial applicability.
Wood commands the largest revenue share, with Aluminum expanding most quickly in residential channels.
End User:
Application-specific requirements reshape product specifications, with rehabilitation centers demanding motorized precision while home users trade performance for spatial efficiency.
- Rehabilitation Centers:Clinical settings require ISO 20957-1 compliance for liability insurance coverage. Programmable electric reformers with sensor-integrated carriage tracking automate protocol documentation, absorbing adjacent digital health budgets into capital equipment decisions.
- Fitness Studios:Boutique operators prioritize modular configurations accommodating hybrid in-person and remote instruction formats. Leasing arrangements displace outright purchase as these businesses manage cash flow across model transitions.
- Home Users:Space constraints and wellness budget competition from connected stationary bikes and smart mirrors shape purchasing behavior.
- Athletic Facilities:Professional training environments demand rapid session turnover capability and multi-user durability specifications.
Fitness Studios generate the highest unit volume, with Rehabilitation Centers gaining share fastest among institutional buyers.
Distribution Channel:
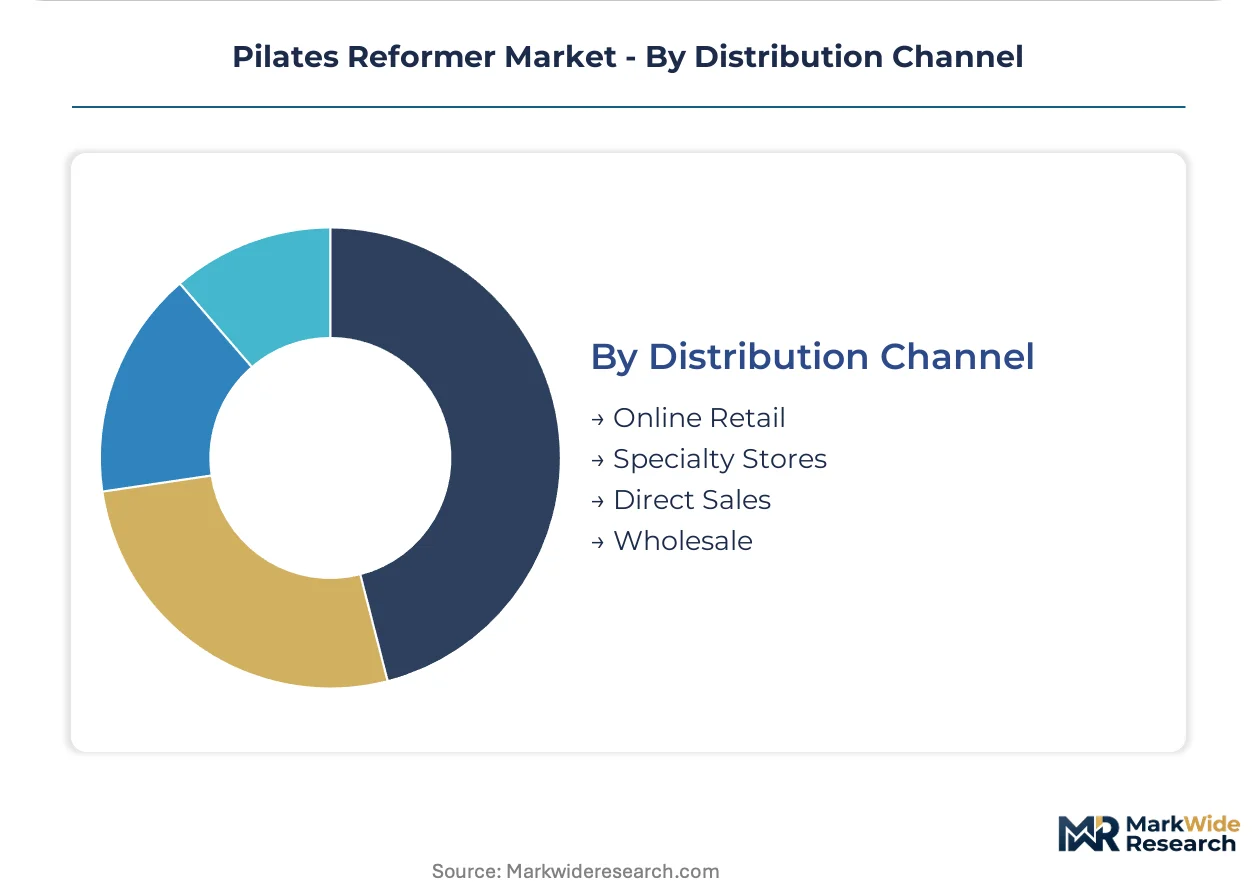
Customer type and geography dictate channel selection, with direct sales dominating institutional procurement while online retail captures residential convenience preferences.
- Direct Sales:Equipment financiers insert service bundling into contract structures for boutique studio leasing arrangements. This channel concentrates in urban centers where studio opening costs have climbed fastest.
- Online Retail:Aluminum-frame compact reformers move through this channel to space-constrained urban apartment dwellers prioritizing delivery convenience over tactile evaluation.
- Specialty Stores:Physical showrooms enable load testing and frame material comparison for discerning home users and small studio operators.
- Wholesale:Physical therapy chains and multi-location fitness brands leverage volume aggregation for standardized fleet deployment across facility networks.
Direct Sales leads channel revenue, with Online Retail climbing fastest in residential segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Joseph Pilates developed his method in New York during the 1920s, establishing the United States as the historical origin point for reformer equipment manufacturing and instructor training infrastructure. Studio density and certification networks now concentrate across multiple continents, with regulatory compliance costs reshaping procurement patterns in key markets.
United States
Boutique fitness chains and physical therapy networks drive commercial-grade equipment procurement, with sensor-integrated carriage tracking systems automating documentation for reimbursement compliance. The Consumer Product Safety Commission governs stability and pinch-point standards, filtering non-compliant manufacturers from institutional channels. California and New York host the densest studio clusters, where leasing arrangements displace outright purchase as operators manage cash flow across hybrid model transitions.
Germany
Instructor certification rates exceeding other European markets create concentrated demand for commercial-grade maple-frame installations, despite rock maple supply volatility compressing manufacturer margins. The EU Machinery Directive mandates third-party conformity assessment for electric reformer variants, adding 12-18 week lead times before CE marking placement. Berlin and Munich anchor the studio expansion wave, with equipment financiers inserting service bundling into contract structures for urban boutique operators.
United Kingdom
Specialty retail channels and direct-to-studio sales dominate distribution, with aluminum-frame compact configurations capturing space-constrained urban apartment dwellers in London and Manchester. ISO 20957-1 fixed training equipment standards influence liability insurance underwriting, effectively filtering procurement channels toward certified suppliers. The Southeast England corridor concentrates rehabilitation clinic demand for programmable electric systems.
Australia
Home-use segments expand fastest in Sydney and Melbourne, where wellness budget competition from connected fitness devices shapes purchasing behavior toward collapsible aluminum configurations. The Therapeutic Goods Administration (TGA) regulates clinical-grade equipment claims, while general consumer sales fall under Australian Consumer Law safety standards. Queensland and Western Australia show emerging studio density as instructor certification programs scale regionally.
Japan
Metropolitan Tokyo and Osaka anchor demand for premium handcrafted steel-frame designs in high-end rehabilitation clinics, where load precision and longevity justify elevated capital outlay. METI oversees industrial standards for motorized exercise equipment, with JIS certification requirements elevating compliance costs for electric variant imports. Compact configurations for residential use gain traction in space-constrained urban districts.
Pilates Reformer Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material-grade and certification-tier dimensions, with handcrafted hardwood and steel-frame offerings commanding price multiples over injection-molded entry-level alternatives. The vendor base organizes into three strategic archetypes: vertically integrated manufacturers controlling component quality across frame lines, education-network anchors locking in studio loyalty through instructor certification, and premium specialists serving rehabilitation clinics with bespoke steel constructions. Dominant competitive moves include backward integration into captive hardwood supply and geographic consolidation of compliance functions for CE marking efficiency.
Within the education-network tier, Merrithew International Inc. and BASI Systems exemplify certification-driven lock-in strategies that reduce competitive switching and generate recurring accessory revenue. Balanced Body Inc. anchors the vertically integrated archetype through Sacramento-based manufacturing control. Gratz Pilates occupies the premium-specialist position with handcrafted steel-frame designs. Among mass-market fabricators, Decathlon SA and Stamina Products Inc. represent scale-driven approaches to residential segments.
| Leading Market Players |
|---|
| Decathlon SA |
| BASI Systems |
| Balanced Body Inc. |
| Peak Pilates |
| Align Pilates Equipment Ltd |
| Merrithew International Inc. |
| Stamina Products Inc. |
| Sivan Health and Fitness |
| Gratz Pilates |
| Others |
Value Network & Pricing Analysis
Equipment financiers bundling service contracts into studio lease structures have concentrated procurement decision-making among a narrow tier of capital providers, tightening price discipline on manufacturers while rewarding suppliers with in-house compliance capabilities.
Pricing Analysis
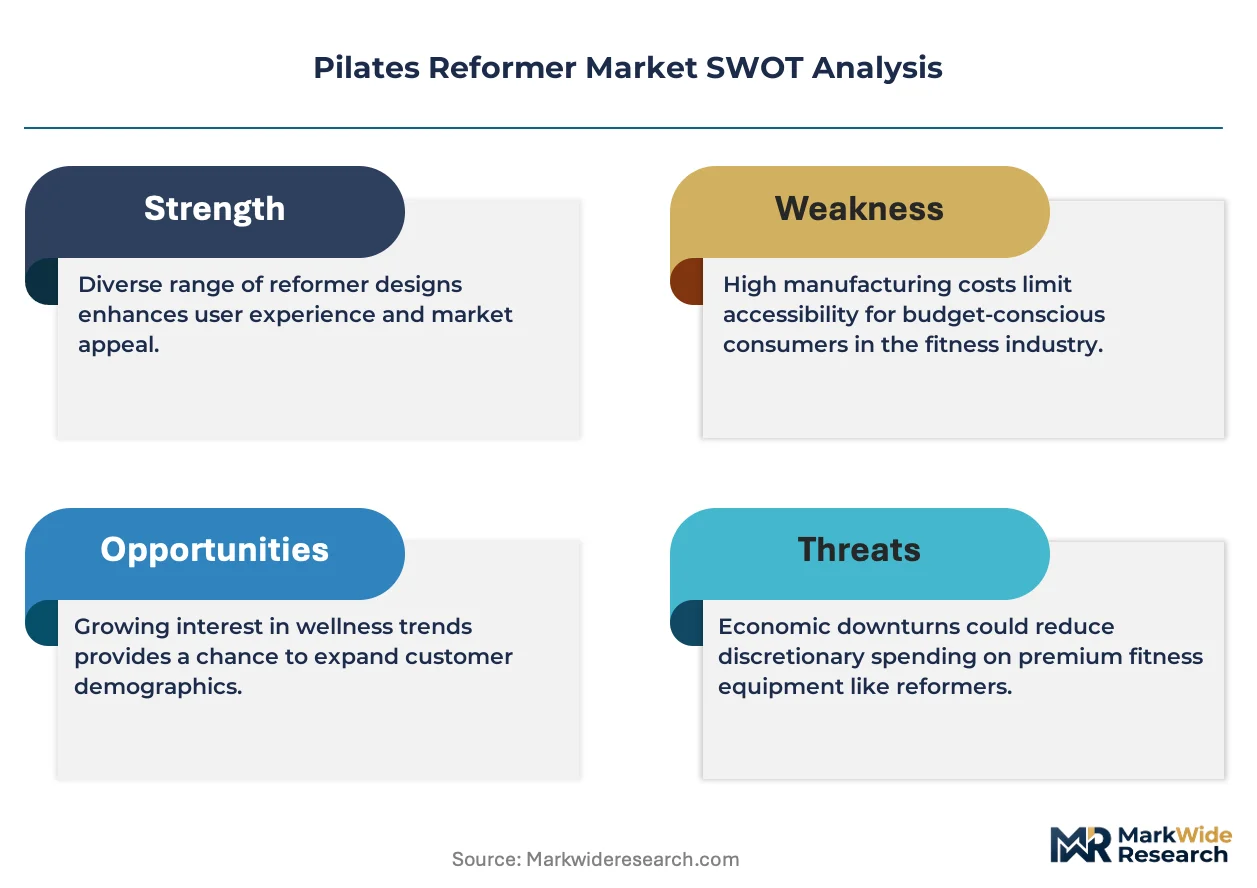
Three-tier pricing structure across handcrafted steel, premium maple, and aluminum compact tiers anchors the market, with ISO 20957-1 certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in entry-level residential segments is intensifying because connected fitness devices capture overlapping wellness budgets. Boutique studios show least price sensitivity due to lease-financed procurement, while home users in dense metropolitan areas prioritize footprint over performance specifications.
Supply Chain Analysis
CE marking and ISO 20957-1 certification gating filter supplier access to institutional channels, concentrating qualified production in the United States, Germany, and China. Rock maple hardwood draws from North American forests, aluminum extrusions from Chinese mills, and precision steel components from German fabricators. Single-source vulnerability in certified hardwood supply creates disruption exposure. Distribution runs through direct sales with embedded financing for studios, online retail for residential compact units, and wholesale for physical therapy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in electric reformer variants where programmable resistance commands premium positioning, and in aluminum-frame compact segments where space-constrained urban demand outstrips supply.
For Market Incumbents: Deepen backward integration into captive maple supply to defend against North American hardwood pricing volatility. Lock in instructor certification network exclusivity to reduce competitive switching and secure recurring accessory revenue streams. Prioritize in-house CE marking consolidation to compress compliance lead times for electric variants entering German markets. For New Entrants and Emerging Players: EU Machinery Directive compliance requirements in Germany open a window for specialist electric reformer manufacturers with third-party assessment capabilities already established. Target home-use aluminum compact segments in space-constrained Tokyo, London, and Sydney apartments where incumbent presence remains thin. Pursue direct-to-consumer online retail with delivery logistics partnerships to bypass specialty showroom gatekeepers. For Investors and Strategic Acquirers: Physical therapy chains are the most active acquirer in this space, consolidating equipment procurement through standardized fleet deployment. Five-to-ten year viability hinges on regulatory accessibility mandate alignment across multiple jurisdictions. Watch for platform height regulation enforcement timelines as inflection indicator for transfer-assist redesign investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Integrated Carriage Development | Physical therapy chains automate protocol documentation for reimbursement compliance, absorbing digital health budgets. |
| CE Marking Consolidation | German manufacturers compress third-party assessment lead times to capture electric reformer upgrade cycles. |
| Instructor Certification Network Expansion | Education-platform anchors lock in studio loyalty and generate recurring accessory revenue streams. |
| Aluminum-Frame Compact Line Launch | Space-constrained urban apartments in Tokyo, London, and Sydney drive highest-margin residential tier. |
| Leasing Arrangement Structuring | Equipment financiers insert service bundling to capture boutique studio cash flow management needs. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with studio operators, physical therapy procurement managers, equipment financiers, and certification program directors alongside secondary validation from FDA device listings, EU Machinery Directive conformity databases, and customs trade records. Bottom-up equipment shipment triangulation against top-down wellness expenditure allocation informs volume estimates.
Rate-of-change decomposition across the analysis window segments growth by product type, material grade, end-user application, and distribution channel. CAGRs derive from installed base replacement cycles, studio expansion rates, and motorized equipment penetration curves. Forecast inputs incorporate EU Machinery Directive enforcement timelines, North American hardwood supply volatility patterns, and urban apartment density projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated accessibility regulation enforcement or sustained connected fitness substitution. Model outputs reflect assumptions around hybrid training model permanence and certification network stickiness. A model refresh is warranted upon material change in EU Machinery Directive implementation timelines or physical therapy reimbursement protocol automation adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
PVC Stretch Yoga Mats Market
Fitness Equipment
Gymnastics Equipment Market
Fitness Equipment
Saudi Arabia Outdoor Fitness Equipment Market
Fitness Equipment
Exercise Band Market
Fitness Equipment
Treadmill Ergometer Market
Fitness Equipment
Europe Fitness Rings Market
Fitness Equipment
Lateral Fitness Equipment Market
Fitness Equipment
South Africa Gym Accessories Market
Fitness Equipment
Treadmill Motors Market
Fitness Equipment
Military Fitness Training Equipment Market
Fitness Equipment
Europe E-Commerce Home Fitness Products Market
Fitness Equipment
Belt Trainers Market
Fitness Equipment
Pilates Equipment and Gears Market
Fitness Equipment
Indoor Bike Trainers Market
Fitness Equipment
Mexico Outdoor Fitness Equipment Market
Fitness Equipment
Fitness Rings Market