
 Yoga Equipment Market | 2026-2036
Yoga Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Yoga Equipment Market Analytics
Buyer concentration across the yoga equipment channel is restructuring as boutique studio chains and corporate wellness aggregators displace individual consumers as the primary volume purchasers. Lululemon Athletica Inc controls premium retail positioning through owned-store networks and instructor ambassador programs. Manduka LLC anchors professional-grade supply relationships with certified yoga teacher training programs worldwide. Alo Yoga differentiates through lifestyle crossover appeal that extends beyond dedicated practice into athleisure adjacencies.
Yoga equipment encompasses purpose-designed apparatus—mats engineered to specific density and grip coefficients, blocks carved to dimensional tolerances for alignment support, straps with tensile-rated hardware, and absorbent textiles—manufactured to sustain repetitive biomechanical loading during asana practice. Natural rubber and TPE formulations now dominate material innovation as PVC faces substitution pressure from studios pursuing sustainability credentials. The end-user dimension reveals studios and gyms commanding bulk procurement volumes with customized branding requirements, while individual purchasers concentrate in premium and mid-range tiers where mat longevity and warranty terms determine repeat purchase cycles.
REACH in Europe and EPA chemical standards in the United States govern phthalate content and volatile organic compound emissions in mat manufacturing, directly elevating compliance costs for PVC-dependent producers. ISO 9001 quality management and OEKO-TEX textile certifications increasingly function as baseline market access requirements rather than premium differentiators. Stakeholders must monitor how evolving chemical disclosure mandates across multiple jurisdictions reshape material selection timelines and supplier qualification protocols.
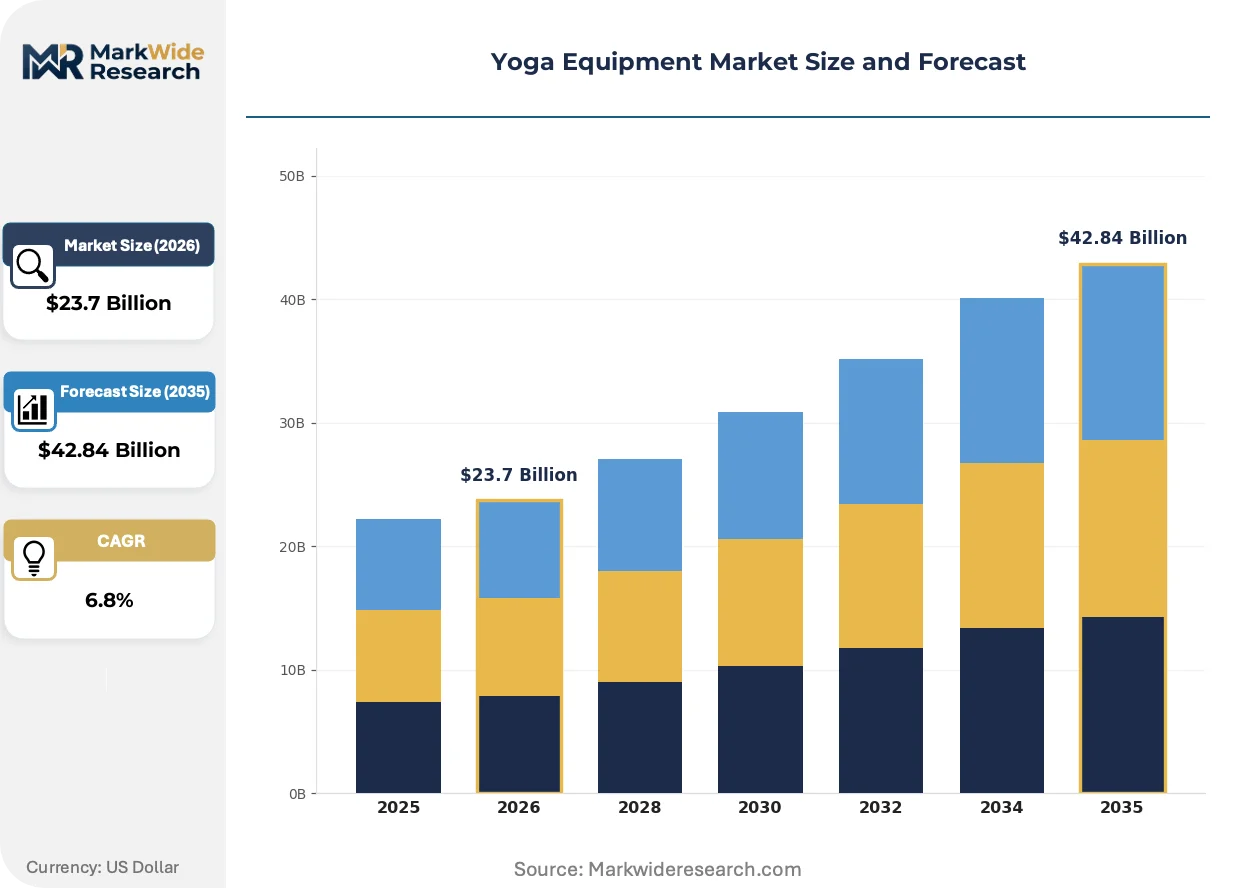
Market Dynamics
Corporate wellness aggregators and boutique studio chains are consolidating procurement volumes, compressing supplier margins while elevating sustainability and customization requirements as non-negotiable contract terms.
Growth Catalysts
- REACH compliance mandates:European chemical disclosure requirements for phthalate content and VOC emissions are accelerating PVC substitution toward natural rubber and TPE formulations, creating material innovation premiums.
- India manufacturing expansion:Domestic production capacity growth combined with traditional practice culture is concentrating supply-side investment in Gujarat and Tamil Nadu clusters.
- Corporate wellness programs:Employer-funded fitness benefits are displacing individual retail as the primary volume channel, with customized branding requirements driving contract manufacturing specialization.
Market Restraints
- Natural rubber price volatility:Hevea brasiliensis latex supply sensitivity to climate patterns in Southeast Asia creates input cost instability for premium mat producers.
- EPA chemical standard evolution:Shifting American emissions thresholds force repeated reformulation cycles, extending product development timelines and compliance expenditure.
- Certified instructor supply concentration:Yoga Alliance-registered teacher training programs represent a narrow certification bottleneck limiting studio expansion velocity.
Strategic Opportunities
- India domestic market depth:Underpenetrated tier-2 and tier-3 cities offer white-space expansion as urban wellness culture diffuses beyond metropolitan centers.
- Athleisure crossover positioning:Equipment brands extending into lifestyle apparel capture higher-margin adjacent revenue streams from non-practicing consumers.
- Bulk customization technology:Digital printing and modular manufacturing enable cost-efficient private-label production for mid-sized studio chains previously excluded from branded programs.
Industry Challenges
- OEKO-TEX certification timelines:Textile testing protocols for absorbent towel and apparel lines extend supplier qualification periods, delaying new product introductions.
- Biomechanical engineering talent scarcity:Specialized expertise in density coefficient optimization and grip surface engineering concentrates among a limited pool of materials scientists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yoga Equipment Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mats, Blocks, Straps, Towels End User: Individuals, Studios, Gyms, Schools Material: Natural Rubber, PVC, TPE, Cotton Price Tier: Premium, Mid-Range, Budget, Discounted |
| Companies Covered | Jade Yoga, Adidas AG, Manduka LLC, Liforme Ltd, Decathlon SA, Lululemon Athletica Inc, Alo Yoga, Nike Inc, Gaiam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yoga Equipment Market Evolving Landscape
Material science breakthroughs and procurement model restructuring are compressing traditional product lifecycles while elevating performance specifications as baseline market entry requirements rather than premium differentiators.
Closed-loop manufacturing systems are unifying waste rubber reclamation with virgin material production, enabling mat producers to market carbon-negative product lines. Boutique studio chains in California and New York are piloting take-back programs at scale. This technology is unifying sustainability credentials with cost structure optimization through reduced raw material procurement.
ECHA REACH authorization procedures are tightening scrutiny on plasticizer additives used in PVC mat production, forcing reformulation investments across European supply chains. Manufacturers serving Germany and France face accelerated substitution timelines. Professional-grade suppliers with established TPE supply relationships are capturing shelf space from legacy PVC-dependent competitors.
Subscription-based equipment refresh models are displacing one-time retail purchases among high-frequency practitioners in urban markets. Studio chains bundle mat replacement into membership fees, compressing individual replacement cycles. This pattern is most visible in London and Sydney where wellness-as-a-service platforms dominate customer acquisition.
Yoga Equipment Market Segmentation
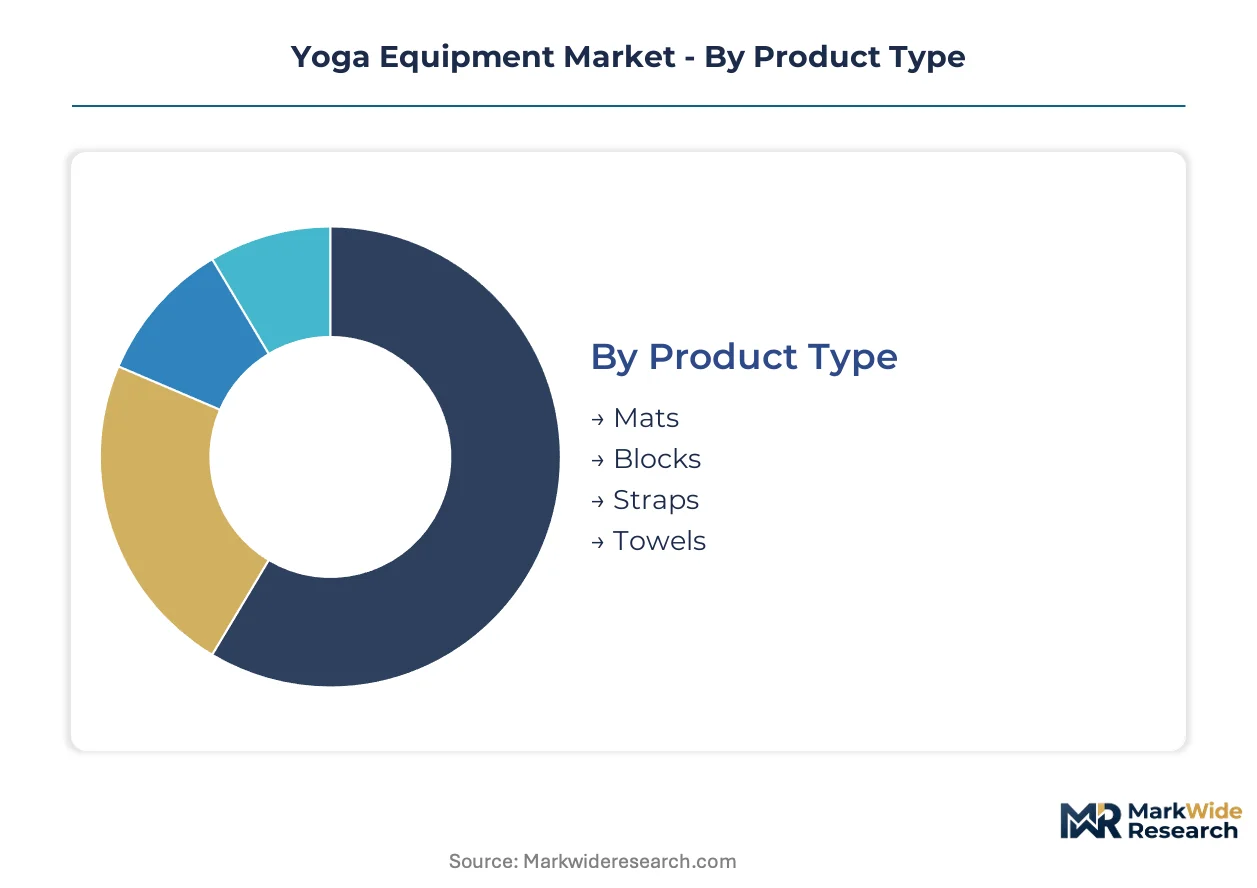
Segmentation in yoga equipment reveals how procurement scale and practice setting reshape product specifications. Studio buyers demand biomechanical durability and bulk customization, while individual purchasers prioritize portability and aesthetic differentiation.
Product Type:
Integration depth varies sharply: mats function as standalone purchase decisions with extended replacement cycles, while blocks and straps typically embed within studio starter kits or teacher training bundles.
- Mats:Engineered to precise density coefficients and grip surface specifications for repetitive loading during asana practice. Demand concentrates in California and New York boutique studio chains where ECHA REACH compliance mandates accelerate natural rubber and TPE adoption away from PVC formulations.
- Blocks:Carved to dimensional tolerances supporting alignment correction across varying practitioner heights. Volume procurement from Yoga Alliance-registered teacher training programs in India and Germany drives standardized sizing requirements and private-label branding.
- Straps:Tensile-rated hardware with D-ring or buckle configurations for flexibility assistance. Corporate wellness aggregators specify institutional durability grades.
- Towels:Absorbent microfiber or cotton textiles with silicone grip backing for hot yoga applications. OEKO-TEX certification timelines delay supplier qualification for new entrants.
Volume placements concentrate in Mats; the faster expansion belongs to Towels as hot yoga studio penetration deepens.
End User:
Customer type determines contract structure and margin profile, with institutional buyers extracting customization concessions unavailable to retail channels.
- Individuals:Direct-to-consumer purchasers selecting on warranty terms, portability weight, and instructor endorsement. Premium and mid-range tiers dominate where mat longevity drives repeat purchase timing.
- Studios:Boutique fitness chains and independent operators commanding bulk volumes with logo embossing and color-matched inventory. REACH-compliant material specifications function as non-negotiable contract terms across European procurement.
- Gyms:Multi-purpose fitness facilities integrating yoga programming into broader membership offerings. Equipment durability specifications exceed studio grades due to higher user turnover.
- Schools:Physical education departments and university wellness programs with institutional purchasing protocols. Budget constraints favor mid-range specifications over premium professional grades.
Procurement scale peaks with Studios; Schools are gaining share fastest as wellness curriculum mandates expand.
Material:
Raw material selection now tracks regulatory trajectory rather than cost optimization alone, with compliance investments restructuring supplier competitive position.
- Natural Rubber:Hevea brasiliensis latex formulations offering biodegradability and superior grip coefficient. Climate volatility in Southeast Asian growing regions creates input cost instability for premium producers.
- PVC:Legacy polyvinyl chloride construction facing substitution pressure from EPA chemical standard evolution and ECHA authorization procedures. Reformulation investments compress margins for dependent manufacturers.
- TPE:Thermoplastic elastomer blends capturing share from PVC-dependent competitors with closed-loop manufacturing compatibility. Professional-grade suppliers with established TPE supply relationships secure shelf space in German and French markets.
- Cotton:Organic and conventional textile grades for strap and towel applications. BIS certification requirements govern Indian domestic market access.
Supply concentration sits with Natural Rubber; TPE is climbing the fastest as REACH deadlines accelerate.
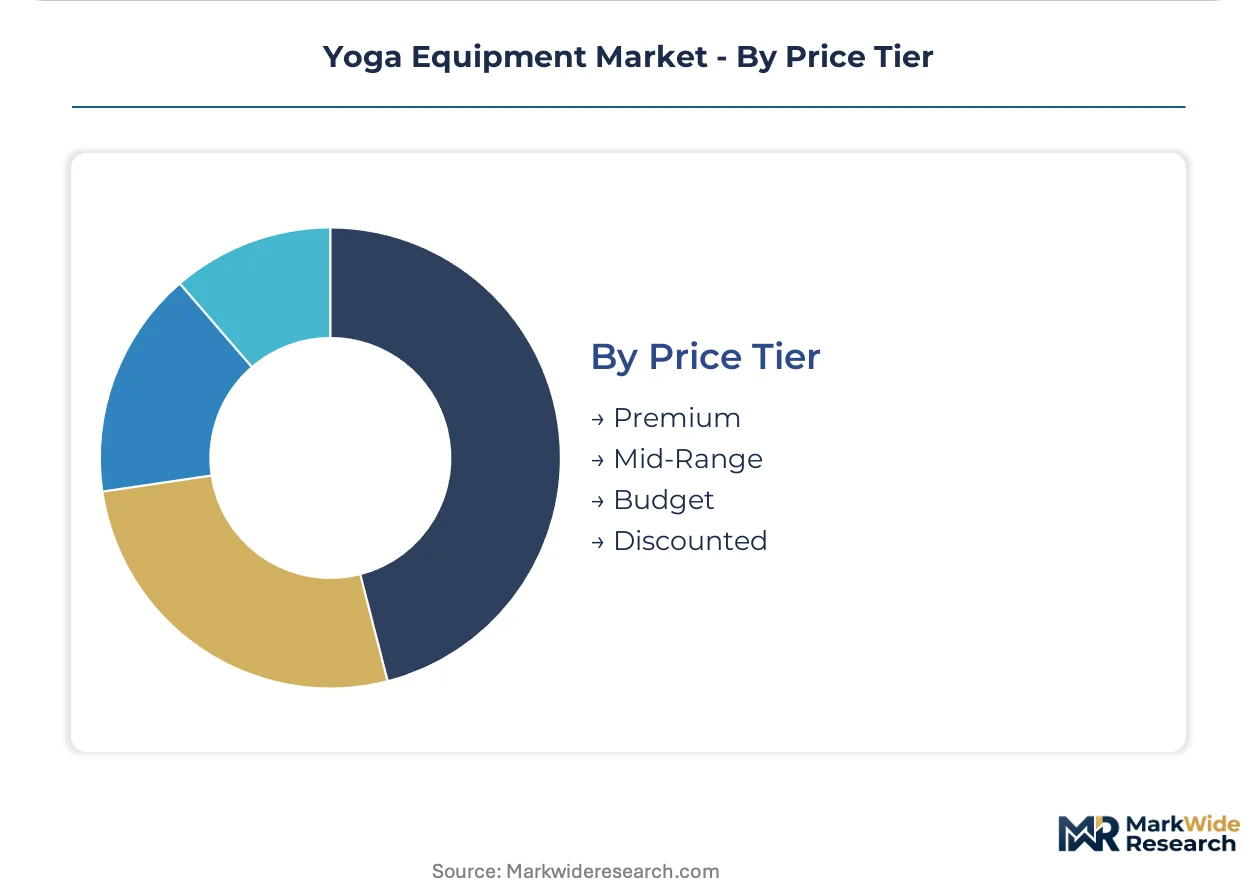
Price Tier:
Three-tier pricing structure separates warranty-backed professional grades from commodity alternatives, with subscription refresh models compressing replacement cycles in urban markets.
- Premium:Lifetime warranty coverage, closed-loop manufacturing credentials, and instructor ambassador program distribution. Lululemon Athletica and Manduka LLC anchor positioning through owned-store networks.
- Mid-Range:Two-to-five year durability guarantees with OEKO-TEX or comparable certification baseline. Alo Yoga captures lifestyle crossover demand extending beyond dedicated practice.
- Budget:Functional specifications without extended warranty or sustainability credentials. Price-sensitive individual purchasers and underfunded school programs dominate.
- Discounted:Closeout inventory and private-label overruns through off-price retail channels. Quality consistency varies significantly.
Revenue contribution peaks in Premium; subscription bundling is expanding fastest in Mid-Range urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for yoga equipment concentrates in India, the United States, and Germany, where studio expansion, corporate wellness adoption, and regulatory compliance investments reshape procurement patterns. Each geography presents distinct material specification pressures and channel consolidation trajectories.
United States
Boutique studio chains in California and New York drive bulk procurement volumes with customized branding requirements. EPA chemical standard evolution forces repeated reformulation cycles for mat producers, extending product development timelines. Los Angeles and Manhattan clusters anchor professional-grade supply relationships with certified teacher training programs.
India
Domestic manufacturing capacity in Gujarat and Tamil Nadu intersects with traditional practice culture to concentrate supply-side investment. BIS certification requirements govern market access for cotton-based strap and towel lines. Tier-2 cities like Pune and Ahmedabad offer white-space expansion as urban wellness culture diffuses beyond metropolitan centers.
Germany
ECHA REACH authorization procedures tighten scrutiny on plasticizer additives, accelerating PVC substitution toward TPE formulations. Professional-grade suppliers with established TPE supply relationships capture shelf space from legacy competitors. Berlin and Munich studio chains pilot closed-loop manufacturing take-back programs at scale.
United Kingdom
Subscription-based equipment refresh models displace one-time retail purchases among high-frequency practitioners in London and Sydney-influenced wellness-as-a-service platforms. Corporate wellness aggregators specify institutional durability grades for strap procurement. Manchester and Birmingham clusters concentrate mid-sized studio chain expansion.
Australia
Wellness-as-a-service platforms dominate customer acquisition in Sydney and Melbourne, compressing individual replacement cycles through bundled mat refresh programs. TGA-equivalent product safety expectations elevate baseline quality management requirements. Brisbane studio networks expand fastest among tier-2 metropolitan markets.
Yoga Equipment Market Competitive Landscape
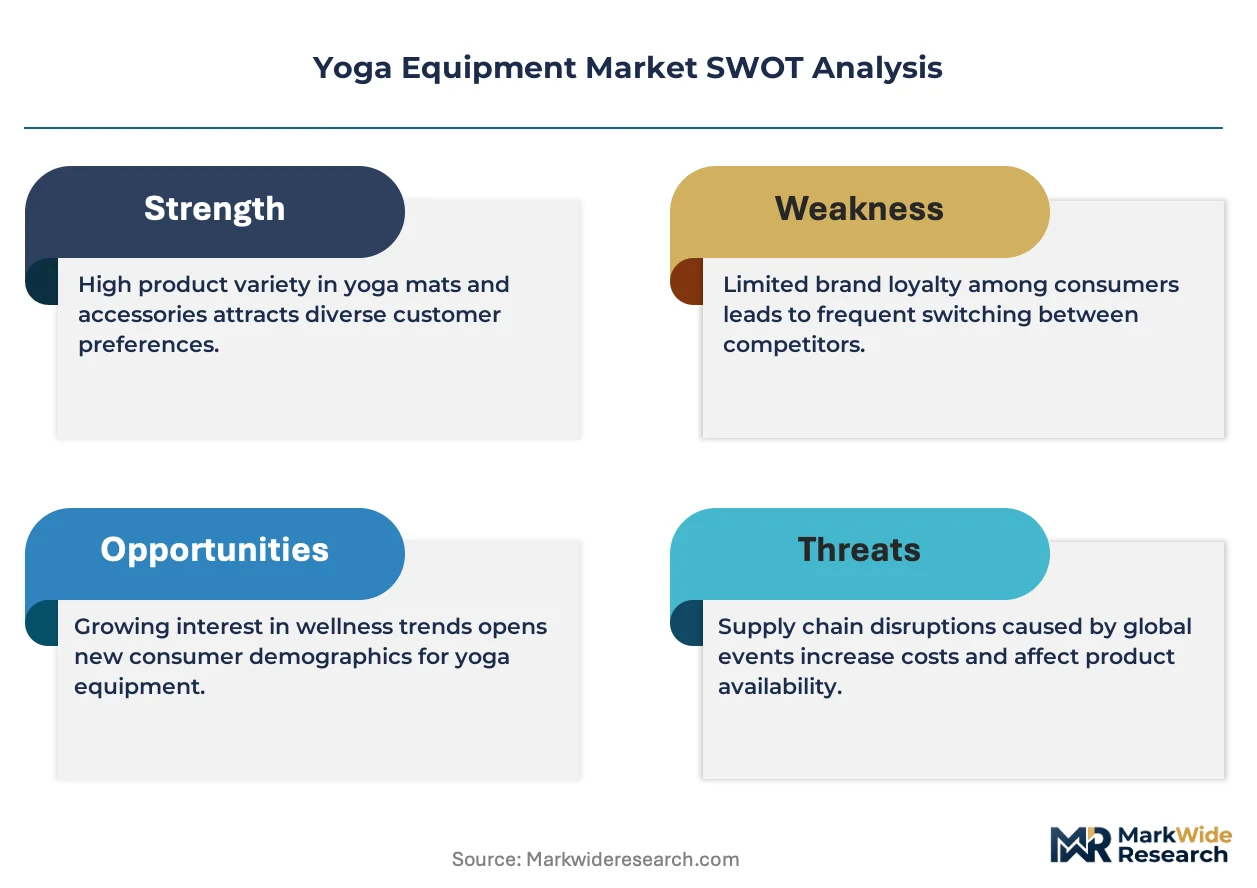
Established producers occupy the standard tier; emerging entrants pursue athleisure crossover positioning and closed-loop sustainability credentials. The vendor base separates into three tiers: premium professional-grade suppliers, lifestyle-integrated brands, and volume-oriented contract manufacturers. Strategic archetypes include biomechanical engineering specialists, sustainability-certification leaders, and corporate wellness channel aggregators. Competitive moves concentrate on M&A for material science capabilities and strategic partnerships with certified instructor training programs.
Within the premium professional-grade tier, Manduka LLC and Liforme Ltd represent biomechanical engineering specialization through density coefficient optimization and grip surface innovation. Lululemon Athletica Inc occupies the lifestyle-integrated position, extending equipment credibility into athleisure adjacencies. Alo Yoga exemplifies the crossover archetype, capturing non-practicing consumers through aesthetic differentiation beyond dedicated yoga practice.
| Leading Market Players |
|---|
| Jade Yoga |
| Adidas AG |
| Manduka LLC |
| Liforme Ltd |
| Decathlon SA |
| Lululemon Athletica Inc |
| Alo Yoga |
| Nike Inc |
| Gaiam |
| Others |
Value Network & Pricing Analysis
Specialized materials scientists with biomechanical engineering expertise concentrate in California and Germany, creating labor-cost differentials that widen spreads between premium professional-grade mats and economy-tier alternatives. This workforce concentration enables Lululemon Athletica and Manduka LLC to command certification-backed pricing power while PVC-dependent manufacturers absorb margin compression from repeated EPA reformulation cycles.
Pricing Analysis
Volume procurement by boutique studio chains extracts customization concessions at compressed margins, while individual retail transactions sustain higher per-unit economics through warranty-backed premium tiers. Three-tier pricing structure across premium, standard, and economy levels separates lifetime-guaranteed professional grades from OEKO-TEX-certified mid-range alternatives and functional budget specifications. Pricing pressure stems from natural rubber price volatility in Southeast Asian growing regions, which destabilizes input costs for biodegradable mat producers. Corporate wellness aggregators exhibit lowest price sensitivity due to employer-funded procurement protocols, while underfunded school physical education departments dominate budget-tier demand with rigid cost ceilings.
Supply Chain Analysis
Ocean freight cost fluctuations between Southeast Asian latex processing hubs and European distribution centers directly impact landed costs for natural rubber mat producers serving German and French markets. Manufacturing concentrates in India, China, and Vietnam, with Gujarat and Tamil Nadu clusters anchoring domestic capacity expansion for cotton-based strap and towel lines. Raw material dependencies center on Hevea brasiliensis latex, TPE polymer blends, and organic cotton textiles. Single-source vulnerability concentrates in Southeast Asian climate-sensitive growing regions. Distribution runs through certified yoga teacher training programs, boutique studio chains, and direct-to-consumer platforms with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The yoga equipment sector sits in a material-transition phase as TPE and natural rubber formulations displace legacy PVC construction under tightening ECHA REACH and EPA chemical mandates. This technology shift restructures supplier competitive position and procurement qualification timelines.
For Market Incumbents: Deepen closed-loop manufacturing capabilities to unify waste rubber reclamation with virgin material production, capturing carbon-negative product positioning. Manduka LLC and Liforme Ltd should anchor TPE supply relationships in Germany and France before REACH deadlines accelerate PVC substitution. Incumbents must defend against emerging lifestyle-crossover entrants by tightening instructor ambassador program exclusivity.
For New Entrants and Emerging Players: Launch via subscription-based equipment refresh models in London and Sydney wellness-as-a-service platforms, compressing individual replacement cycles through bundled membership structures. White-space expansion targets tier-2 Indian cities like Pune and Ahmedabad where domestic manufacturing capacity intersects with underpenetrated urban wellness culture. Athleisure crossover positioning captures higher-margin adjacent revenue from non-practicing consumers.
For Investors and Strategic Acquirers: Re-rating potential sits with TPE-specialized contract manufacturers given REACH compliance acceleration and studio chain consolidation. Long-term viability over the next decade favors suppliers with established closed-loop systems and bulk customization technology. Monitor ECHA authorization procedure timelines as the inflection signal for PVC-dependent competitor distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Manufacturing Scale-Up | Enables carbon-negative product lines through waste rubber reclamation integration with virgin TPE production. |
| Bulk Customization Technology Deployment | Digital printing and modular systems unlock private-label production for mid-sized studio chains previously excluded. |
| TPE Supply Relationship Anchoring | Professional-grade suppliers secure shelf space in German markets as ECHA REACH deadlines accelerate PVC displacement. |
| Instructor Ambassador Program Expansion | Yoga Alliance-registered teacher training certification bottlenecks limit studio expansion velocity for uncredentialed competitors. |
| Tier-2 India Market Entry | Pune and Ahmedabad clusters offer white-space penetration as urban wellness culture diffuses beyond metropolitan centers. |
Research Methodology
Trade publications, customs databases, and regulatory filings formed the secondary backbone, supplemented by primary interviews with procurement directors at boutique studio chains, materials scientists specializing in density coefficient optimization, certified yoga instructor training program administrators, and corporate wellness benefit managers. Bottom-up and top-down triangulation validated volume estimates across product type, end user, material, and price tier segmentation dimensions.
Bottom-up unit economics modeled mat, block, strap, and towel demand by practice setting and replacement cycle frequency, while top-down macro trends anchored expansion assumptions across the analysis window. Segmentation dimensions included product type, end user category, raw material formulation, and price tier positioning. CAGRs derived from regression analysis against historical procurement volumes and regulatory compliance investment trajectories. Forecast inputs incorporated REACH authorization timelines and India domestic manufacturing capacity expansion.
Natural rubber price volatility, ECHA regulatory acceleration, and certified instructor supply concentration are the dominant revision risks that could compress or extend modeled growth trajectories. Forecasts reflect documented assumptions about material substitution rates and studio chain consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Elliptical Market
Fitness Equipment
Yoga Mat Market
Fitness Equipment
Indoor Bike Trainers Market
Fitness Equipment
Fitness Equipment Market
Fitness Equipment
Fitness Ball Market
Fitness Equipment
Europe Refurbished Fitness Equipment Market
Fitness Equipment
Hydrotherapy Treadmills Market
Fitness Equipment
Gymnastics Equipment Market
Fitness Equipment
Mexico Outdoor Fitness Equipment Market
Fitness Equipment
Treadmill Motors Market
Fitness Equipment
Lung Exercise Machine Market
Fitness Equipment
Europe Home Fitness Equipment Market
Fitness Equipment
Yoga and Exercise Mats Market
Fitness Equipment
Asia-Pacific Fitness Equipment Market
Fitness Equipment
North America Home Fitness Equipment Market
Fitness Equipment
China Outdoor Fitness Equipment Market