
 Hydrotherapy Treadmills Market | 2026-2036
Hydrotherapy Treadmills Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrotherapy Treadmills Market Foresight
Preventive maintenance contracts and software-enabled session tracking is expanding the recurring revenue base for hydrotherapy treadmill vendors. HydroWorx International Inc. leverages its installed base across NCAA athletic programs to sustain aftermarket service margins. SwimEx Inc. anchors its competitive position through fiberglass tank manufacturing integrated with proprietary paddlewheel propulsion systems. BTL Corporate differentiates via digital physiotherapy platforms that interface with aquatic treadmill telemetry.
Hydrotherapy treadmills are motorized walking platforms submerged in temperature-controlled water tanks, typically operating at belt speeds from 0.1 to 8.0 miles per hour with water depths adjustable between 24 and 60 inches to modulate buoyancy and joint loading. These systems enable gait retraining, cardiovascular conditioning, and pain-modulated exercise for patients with orthopedic, neurological, or metabolic conditions. Fixed installations dominate the product type landscape due to structural integration requirements in clinical facilities, while portable units represent the fastest-expanding category as mobile rehabilitation services proliferate. Rehabilitation centers command the largest end-user segment share, though sports clinics exhibit the steepest adoption trajectory driven by athlete return-to-play protocols.
The FDA's 510(k) clearance pathway for Class II medical devices governs hydrotherapy treadmill commercialization in the United States, while ISO 13485 quality management certification shapes supplier qualification for institutional procurement in Europe. The EU Medical Device Regulation's clinical evidence requirements are extending product development timelines for manufacturers seeking CE marking access. Stakeholders must monitor reimbursement code evolution for aquatic therapy across Medicare and private payers, as coding density directly influences capital equipment purchasing cycles in outpatient settings.
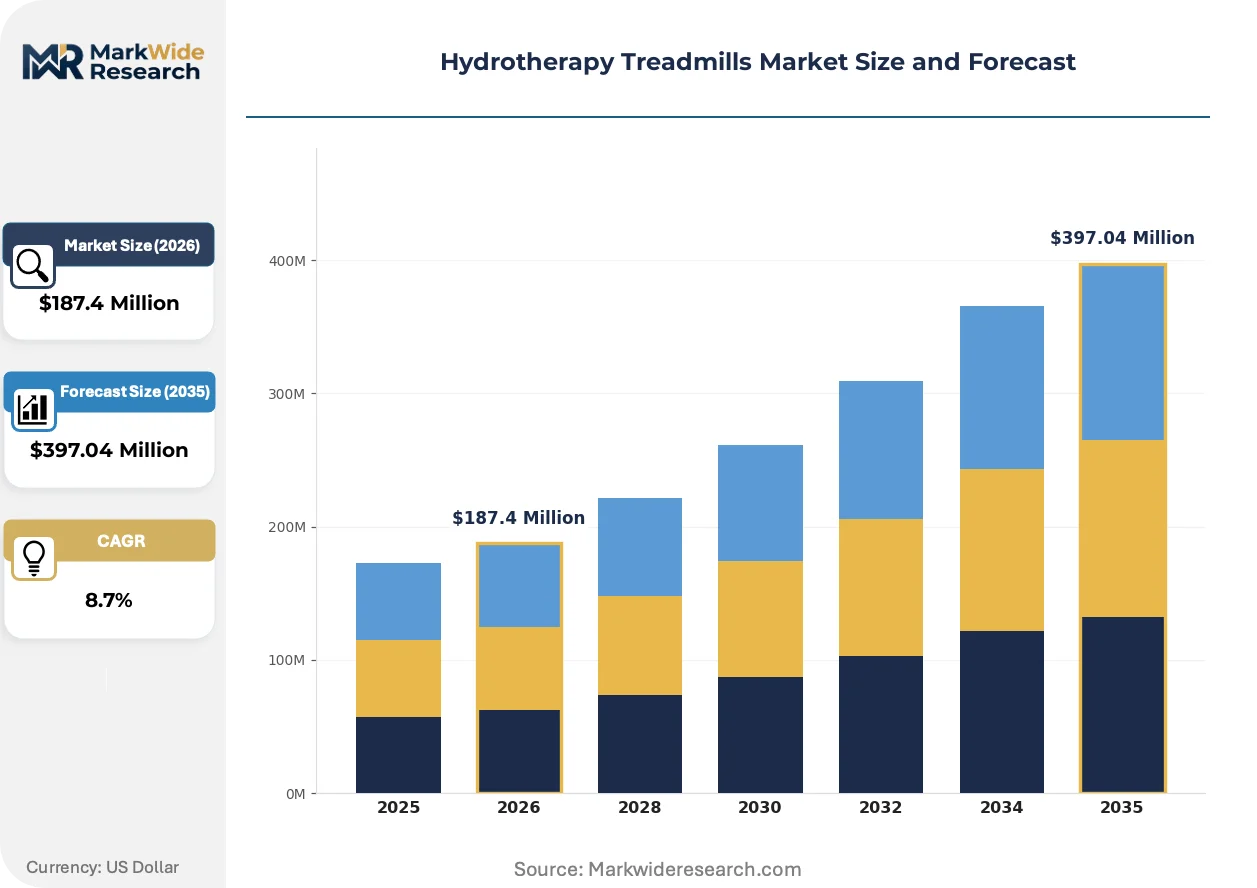
Market Dynamics
Post-surgical rehabilitation protocols are accelerating equipment replacement cycles as aquatic therapy gains traction in orthopedic recovery pathways. The FDA's 510(k) clearance framework for Class II medical devices shapes competitive entry barriers and capital allocation decisions across the vendor landscape.
Growth Catalysts
- CMS reimbursement expansion:Medicare coding density for aquatic therapy CPT codes directly influences outpatient clinic purchasing decisions across the United States.
- NCAA athletic infrastructure:Collegiate sports medicine programs are standardizing hydrotherapy treadmill protocols for athlete return-to-play rehabilitation.
- Fiberglass tank manufacturing:Integrated production of corrosion-resistant vessel systems reduces lead times for fixed installation deployments.
Market Restraints
- Stainless steel input volatility:Fluctuations in medical-grade 316L stainless steel pricing compress margin structures for tank component suppliers.
- EU MDR clinical evidence requirements:Extended CE marking timelines delay product launches in European institutional procurement channels.
- Land-based anti-gravity treadmills:AlterG and competing unweighting systems capture budget share in sports medicine settings with lower facility requirements.
Strategic Opportunities
- Mobile rehabilitation services:Portable hydrotherapy treadmill units enable home-based therapy delivery through regional home health networks.
- Digital physiotherapy convergence:Integration of aquatic treadmill telemetry with remote patient monitoring platforms opens subscription revenue streams.
- Veterans Affairs procurement channels:Federal healthcare systems prioritize aquatic therapy for service-connected orthopedic and neurological conditions.
Industry Challenges
- Aquatic therapy technician certification:Shortage of ATAC-credentialed specialists limits facility utilization rates and session throughput.
- Legacy EMR integration complexity:Proprietary data formats from paddlewheel propulsion systems require custom API development for hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrotherapy Treadmills Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable, Fixed, Portable, Custom-Built End User: Rehabilitation Centers, Fitness Gyms, Sports Clinics, Home Users Technology: Digital Interface, Water Resistance, Adjustable Speed, Temperature Control Application: Physical Therapy, Sports Training, Weight Loss, Pain Management |
| Companies Covered | SwimEx Inc., BTL Corporate, HydroWorx International Inc., EWAC Medical, Hudson Aquatic Systems, Prime Pacific Health Innovations Corporation, Endless Pools Inc., Narang Medical Limited, Hydro Physio Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrotherapy Treadmills Market Shifts & Advancements
Software-enabled session tracking is compressing service contract pricing while expanding telemetry data monetization pathways. Vendors are repositioning around predictive maintenance algorithms and outcome measurement integration.
Variable-speed underwater camera systems paired with AI gait analysis is decentralizing biomechanical assessment capabilities previously concentrated in research hospitals. Sports medicine clinics in Texas and Florida are adopting these systems for real-time kinematic feedback during athlete rehabilitation. The technology is decentralizing specialist referrals by enabling community-based facilities to deliver previously centralized diagnostic services.
The EU Medical Device Regulation's post-market surveillance requirements are extending clinical follow-up obligations for hydrotherapy treadmill manufacturers seeking CE marking renewal. European notified bodies are demanding real-world performance data across diverse patient populations. Rehabilitation centers in Germany and the Netherlands are prioritizing vendors with established MDR technical documentation to minimize procurement risk.
After-sales service unbundling is fragmenting traditional capital-plus-maintenance contract structures. Outpatient physical therapy chains in California and New York are negotiating à la carte software subscriptions separate from hardware warranties. Independent service organizations are capturing calibration and preventive maintenance work previously performed by original equipment manufacturers.
Hydrotherapy Treadmills Market Segmentation
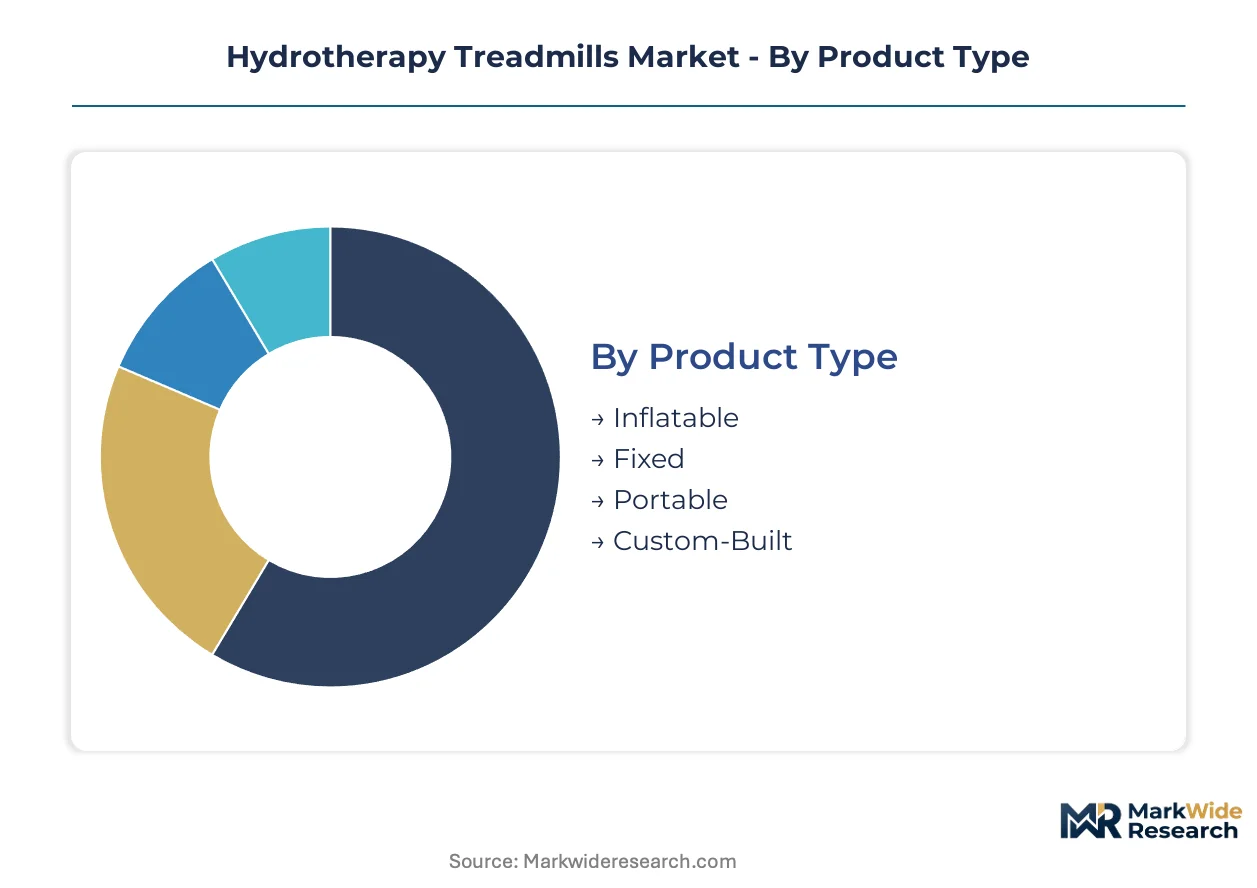
Hydrotherapy treadmill segmentation reveals divergent buyer priorities across clinical, athletic, and consumer channels. Equipment specifications, facility infrastructure, and reimbursement pathways create distinct procurement profiles that vendors must address through differentiated product architectures.
Product Type:
Facility capital budgets and installation permanence separate buyers across this dimension.
- Fixed:Steel-framed installations with integrated fiberglass tanks anchor rehabilitation centers requiring continuous patient throughput. Clinical facilities in the United States prioritize these systems for orthopedic post-surgical protocols, though structural retrofit costs limit replacement frequency.
- Portable:Modular units with detachable tanks and wheeled bases enable mobile therapy delivery through home health networks. Sports medicine programs in Texas and Florida are deploying these for satellite training facilities where permanent construction is impractical.
- Inflatable:Collapsible polymer vessels reduce shipping costs for international institutional procurement.
- Custom-Built:Specified dimensions accommodate unique facility footprints or specialized patient populations.
Fixed installations dominate revenue today; portable configurations are gaining share fastest.
End User:
Reimbursement density and session economics determine equipment selection across buyer categories.
- Rehabilitation Centers:Medicare-certified outpatient clinics with aquatic therapy CPT coding drive capital allocation toward high-duty-cycle systems. These facilities prioritize FDA 510(k) clearance and predictive maintenance contracts to maximize equipment uptime.
- Sports Clinics:NCAA-affiliated programs and professional team medical staff demand telemetry integration with athlete management systems. Return-to-play protocols in collegiate athletic departments are standardizing underwater gait analysis requirements.
- Fitness Gyms:Wellness-oriented installations target member retention through differentiated amenity offerings.
- Home Users:Direct-to-consumer sales remain limited by space requirements and technical support needs.
Rehabilitation centers anchor current volumes; sports clinics show the steepest expansion trajectory.
Technology:
Software-hardware integration depth separates premium from standard-tier offerings.
- Digital Interface:Touchscreen controls with session logging and outcome tracking command pricing premiums in institutional procurement. Integration with hospital EMR systems requires API development for proprietary paddlewheel telemetry formats.
- Adjustable Speed:Belt motors spanning 0.1 to 8.0 miles per hour enable gait retraining progression protocols.
- Temperature Control:Precision heating systems maintain therapeutic water temperatures for pain modulation.
- Water Resistance:Corrosion-resistant component specifications extend service intervals in high-chlorine environments.
Digital interface capabilities command the widest price premiums; adjustable speed is becoming table stakes.
Application:
Clinical outcomes documentation requirements shape feature prioritization across use cases.
- Physical Therapy:Post-surgical rehabilitation protocols for joint replacement and spinal procedures represent the core installed base. Medicare reimbursement density directly influences equipment purchasing cycles in outpatient settings.
- Sports Training:Load-managed conditioning for athlete return-to-play drives adoption in collegiate and professional programs. Underwater camera systems with AI gait analysis are decentralizing biomechanical assessment capabilities.
- Pain Management:Buoyancy-modulated exercise for metabolic and neurological conditions expands addressable patient populations.
- Weight Loss:Reduced joint loading enables exercise initiation for bariatric patient cohorts.
Physical therapy anchors current utilization; sports training applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as CE marking delays under EU MDR push production capacity toward jurisdictions with streamlined medical device pathways. Vendors are reallocating technical documentation resources to maintain market access across divergent approval timelines.
United States
FDA 510(k) clearance density and Medicare reimbursement expansion for aquatic therapy CPT codes drive institutional procurement in outpatient rehabilitation settings. The agency's Class II medical device framework shapes competitive entry barriers for tank system manufacturers. Texas and Florida sports medicine clusters are deploying portable units for satellite athletic training facilities.
Germany
EU MDR clinical evidence requirements and post-market surveillance obligations extend product development timelines for CE marking renewal. German rehabilitation centers in Bavaria and North Rhine-Westphalia prioritize vendors with established technical documentation to minimize procurement risk. Notified bodies are demanding real-world performance data across diverse patient populations.
United Kingdom
NHS procurement frameworks for musculoskeletal rehabilitation equipment concentrate demand in England's integrated care systems. The Medicines and Healthcare products Regulatory Agency's post-Brexit device registration requirements create parallel compliance pathways. London and Southeast England rehabilitation networks are standardizing hydrotherapy protocols for orthopedic post-surgical recovery.
Japan
PMDA medical device approval timelines and JIS standards for therapeutic exercise equipment shape supplier qualification for institutional procurement. Aging demographics in Kanto and Kansai regions drive replacement cycles in geriatric rehabilitation facilities. METI's healthcare technology assessment programs influence capital allocation decisions for aquatic therapy infrastructure.
Australia
TGA medical device inclusion requirements and private health insurance rebate structures determine equipment purchasing cycles in physiotherapy practices. New South Wales and Victoria rehabilitation networks are integrating aquatic treadmill protocols for sports injury management. The country's national disability insurance scheme expands addressable patient populations for water-based exercise interventions.
Hydrotherapy Treadmills Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system vendors commanding premium positioning in fixed installations while component suppliers capture modular portable opportunities. The vendor landscape exhibits moderate concentration around established fiberglass tank fabricators and digital physiotherapy platform developers. Three archetypes dominate: full-system integrators with captive manufacturing, telemetry-software specialists licensing hardware partnerships, and regional fabricators serving price-sensitive procurement channels. Competitive moves center on predictive maintenance algorithm development and unbundled service contract structures that separate software subscriptions from hardware warranties.
Within the full-system integrator tier, HydroWorx International Inc. and SwimEx Inc. exemplify divergent manufacturing philosophies, with the former leveraging installed base scale across NCAA athletic programs and the latter anchoring position through proprietary paddlewheel propulsion integration. BTL Corporate occupies a position at the digital convergence frontier, representing the telemetry-platform archetype that interfaces aquatic treadmill data streams with remote physiotherapy monitoring systems. These three entities collectively illustrate the strategic tension between hardware-centric and software-enabled competitive positioning in clinical rehabilitation equipment.
| Leading Market Players |
|---|
| SwimEx Inc. |
| BTL Corporate |
| HydroWorx International Inc. |
| EWAC Medical |
| Hudson Aquatic Systems |
| Prime Pacific Health Innovations Corporation |
| Endless Pools Inc. |
| Narang Medical Limited |
| Hydro Physio Ltd. |
| Others |
Supply & Pricing Matrix
Medical-grade 316L stainless steel price volatility cascades through hydrotherapy treadmill manufacturing into three distinct procurement tiers, compressing margins for tank component suppliers while fiberglass-integrated system vendors defend pricing power through captive vessel production.
Pricing Analysis
Distributor markup layers separate direct-to-institutional contracts from retail-equipment channels, with pricing stratifying across FDA 510(k)-cleared premium systems, ISO 13485-certified standard platforms, and uncertified economy imports. Cost compression in the stainless steel-dependent component tier is intensifying because spot-market metal pricing feeds directly into tank fabrication quotes. Sports clinics exhibit the lowest price sensitivity due to telemetry integration requirements, while independent physical therapy practices negotiate aggressively on capital equipment.
Supply Chain Analysis
Container freight rates from Asian manufacturing hubs to North American rehabilitation networks determine landed cost structures for tank assemblies and electronic control modules. Supply concentrates in the United States for fiberglass vessel fabrication, Germany for precision drive systems, and China for pump and heating components. The chain draws from medical-grade polymers, corrosion-resistant alloys, and embedded sensor arrays. Single-source vulnerability in paddlewheel propulsion motors poses structural risk. Distribution runs through GPO contracts, direct institutional sales, and regional medical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in hydrotherapy treadmills rests on software-enabled service unbundling and predictive maintenance algorithm monetization, shifting revenue mix from capital hardware toward recurring telemetry subscriptions.
For Market Incumbents: Deepen aftermarket service penetration by disaggregating software subscriptions from hardware warranties, mirroring the à la carte contracting patterns emerging in California and New York outpatient chains. Prioritize API development for EMR integration to lock in hospital system switching costs against telemetry-platform specialists licensing third-party hardware.
For New Entrants and Emerging Players: Telehealth platform partnerships offer the lowest-friction channel for portable unit distribution through regional home health networks. Target mobile rehabilitation services in Texas and Florida satellite athletic facilities where permanent construction is impractical. Pursue Veterans Affairs procurement channels with federal healthcare system credentialing.
For Investors and Strategic Acquirers: Asymmetric upside sits with telemetry-software specialists possessing established hospital information system integrations and recurring revenue bases. Five-to-ten-year viability favors vendors with FDA 510(k) clearance density and installed base scale across NCAA athletic programs. Monitor Medicare CPT code expansion for aquatic therapy as the inflection signal for outpatient clinic capital allocation cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Predictive maintenance algorithms expand recurring revenue beyond hardware warranties in institutional contracts. |
| Reimbursement Strategy | Medicare aquatic therapy CPT code density directly influences capital equipment purchasing cycles across outpatient settings. |
| Hospital System Partnership | EMR integration via custom APIs locks in switching costs and secures multi-year service contracts. |
| CE Marking Pathway | EU MDR technical documentation completion minimizes procurement risk for German and Dutch rehabilitation centers. |
| Backward Integration | Captive fiberglass tank manufacturing reduces lead times and defends margin structures against stainless steel volatility. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with rehabilitation center clinical directors, hospital biomedical engineers, GPO contracts managers, and aquatic therapy equipment distributors alongside secondary validation through FDA 510(k) filings, CMS reimbursement databases, EU MDR notified body documentation, and hospital procurement records. Bottom-up equipment shipment data and top-down healthcare capital expenditure estimates were triangulated.
Granularity-level modeling disaggregated volume and value across fixed, portable, inflatable, and custom-built product types; rehabilitation center, sports clinic, fitness gym, and home user end-use categories; and digital interface, adjustable speed, temperature control, and water resistance technology tiers. CAGRs were derived from regression analysis of historical replacement cycles and projected Medicare reimbursement expansion. Forecast inputs incorporated NCAA athletic program infrastructure investment patterns and EU MDR approval timeline assumptions.
Stainless steel commodity volatility, EU MDR clinical evidence requirement extensions, and land-based anti-gravity treadmill competitive displacement are the dominant revision risks to installed base and revenue projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Lung Exercise Machine Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
Europe Fitness Rings Market
Fitness Equipment
Pilates Reformer Market
Fitness Equipment
Home Fitness Market
Fitness Equipment
Resistance Bands Market
Fitness Equipment
PVC Stretch Yoga Mats Market
Fitness Equipment
Treadmill Desks Market
Fitness Equipment
North America Home Fitness Equipment Market
Fitness Equipment
Pilates Equipment and Gears Market
Fitness Equipment
Asia-Pacific Fitness Rings Market
Fitness Equipment
Latin America Fitness Ring Market
Fitness Equipment
Fitness Rings Market
Fitness Equipment
BMI Machine Market
Fitness Equipment
Treadmill Ergometer Market
Fitness Equipment
Weight Training Market