
 Military Fitness Training Equipment Market | 2026-2036
Military Fitness Training Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Military Fitness Training Equipment Market Outlook
MIL-STD-810H environmental qualification is bifurcating the competitive landscape into defense-certified suppliers and commercial fitness crossover entrants. Rogue Fitness leverages its forged-in-America manufacturing base to sustain domestic military contracts. Technogym S.p.A. competes through European defense procurement frameworks with precision-calibrated cardio platforms. BeaverFit anchors its position via portable containerized gym systems purpose-built for expeditionary force deployments.
Military fitness training equipment encompasses strength, endurance, and mobility apparatus engineered to withstand sand, salt fog, and temperature extremes from -51°C to 71°C while supporting load-carriage conditioning for combat readiness. Treadmills and battle ropes dominate current procurement volumes across permanent base installations. Smart gym equipment and biometric monitoring systems represent the fastest-expanding technology segment as armed forces digitize individual performance tracking. Mobile units command premium pricing due to rapid deployment requirements for special operations and forward operating elements.
The U.S. Department of Defense enforces MIL-STD-810H and ASTM F2276 equipment safety standards, while the EU Green Deal and REACH chemical compliance rules shape European procurement specifications for materials and coatings. Stakeholders must monitor evolving biometric data governance from GDPR-derived military personnel privacy frameworks and decide whether to develop captive sensor technology or partner with cleared defense contractors.
Market Dynamics
MIL-STD-810H certification requirements are bifurcating vendor eligibility, forcing equipment manufacturers to restructure R&D budgets toward environmental testing infrastructure or exit defense procurement channels entirely.
Growth Catalysts
- Special operations procurement:NATO special forces units are expanding load-bearing conditioning system acquisitions for expeditionary readiness. Portable gym systems now constitute priority procurement categories across rapid-deployment commands.
- EU Green Deal compliance:REACH chemical regulations and sustainable materials mandates are accelerating coating and polymer substitutions in European defense contracts. Manufacturers adapting supply chains capture preferential Bundeswehr tender access.
- Biometric integration:Smart gym equipment with embedded performance tracking is displacing analog systems in permanent base modernizations. Sensor-enabled platforms enable command-level fitness data aggregation.
Market Restraints
- Aluminum and steel price volatility:Raw material cost swings compress margin structures for forged load-bearing equipment. Domestic foundry capacity constraints in North America extend lead times for structural components.
- Testing infrastructure concentration:MIL-STD-810H certified environmental chambers cluster in Germany and the United States. Vendors without proximate testing partnerships face six-to-nine-month certification delays.
- Commercial fitness substitution:Uncertified commercial-grade equipment penetrates non-deployable training facilities. Budget-constrained reserve units occasionally bypass defense-specified procurement channels.
Strategic Opportunities
- Expeditionary containerization:Modular gym systems deployable within standard shipping containers address unmet special operations demand. Rapid-setup configurations command pricing premiums in forward operating base tenders.
- GDPR-derived military privacy frameworks:Evolving biometric data governance creates captive sensor development opportunities. Cleared defense contractors with established security protocols gain preferential partnership status.
- Smart-endurance convergence:Integration of wearable performance monitors with fixed equipment enables real-time load-adjustment algorithms. Early movers in cardio platform digitization secure multi-year platform contracts.
Industry Challenges
- Environmental testing talent scarcity:Qualified technicians capable of executing MIL-STD-810H protocols command premium compensation. Recruitment competition with aerospace and automotive sectors strains specialist availability.
- Legacy infrastructure integration:Smart equipment deployment requires fiber and power upgrades at aging base facilities. Installation timelines frequently exceed equipment delivery schedules.
- Cross-border certification reciprocity:Divergent national interpretations of NATO standardization agreements create duplicate testing requirements. Vendors face redundant validation expenses for multi-country contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Fitness Training Equipment Market |
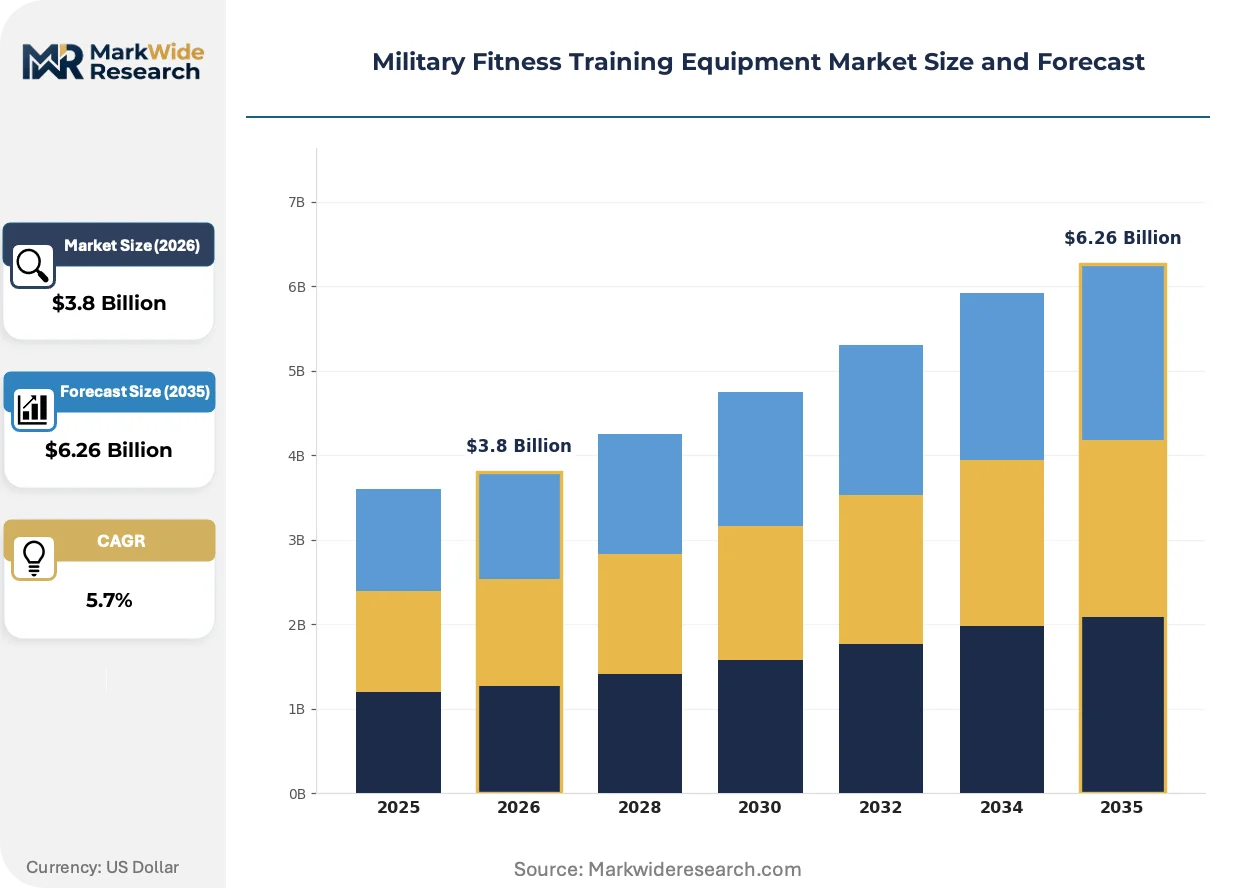
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
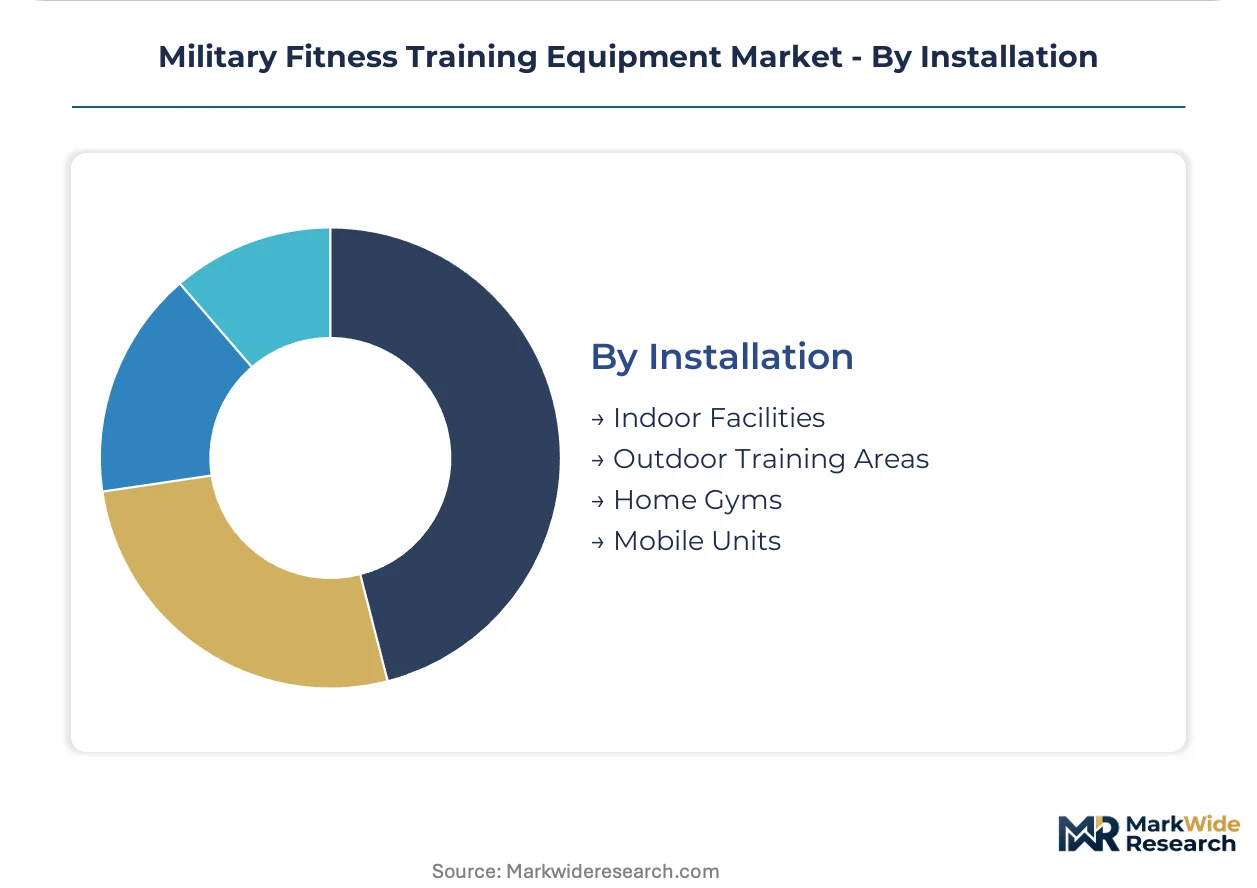
| Segmentation | Product Type: Treadmills, Battle Ropes, Weight Plates, Resistance Bands End User: Armed Forces, Fitness Trainers, Military Academies, Personal Trainers Technology: Smart Gym Equipment, Biometric Monitoring Systems, Wearable Sensors, Interactive Platforms Installation: Indoor Facilities, Outdoor Training Areas, Home Gyms, Mobile Units |
| Companies Covered | Life Fitness, Technogym S.p.A., TriActive USA, MoveStrong, Rally Fitness LLC, BeaverFit, Rogue Fitness, Keiser Corporation, Greenfields Outdoor Fitness, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Fitness Training Equipment Market Strategic Shifts
Digital performance tracking and expeditionary modularity are compressing traditional equipment categories. Vendors now compete on deployment velocity and data interoperability rather than mechanical durability alone.
Embedded biometric sensors are decomposing the boundary between fixed gym equipment and wearable performance monitors. Special operations commands in Germany and the United States are field-testing integrated platforms that stream load-carriage metrics directly to unit commanders. This convergence is collapsing the procurement distinction between cardio machines and individual soldier monitoring systems.
REACH chemical compliance and the EU Green Deal are mandating coating substitutions across European defense contracts. Chromium plating and solvent-based finishes face phased elimination from Bundeswehr and French Armed Forces specifications. Equipment suppliers reformulating surface treatments capture preferential access to continental tender processes.
Unit-level purchasing autonomy is fragmenting traditional centralized defense procurement patterns. Base commanders in expeditionary roles now issue direct equipment requisitions through digital defense marketplaces. This behavioral shift is most visible in United States special operations and British Army rapid response formations, where deployment timelines override legacy contract vehicle preferences.
Military Fitness Training Equipment Market Segmentation
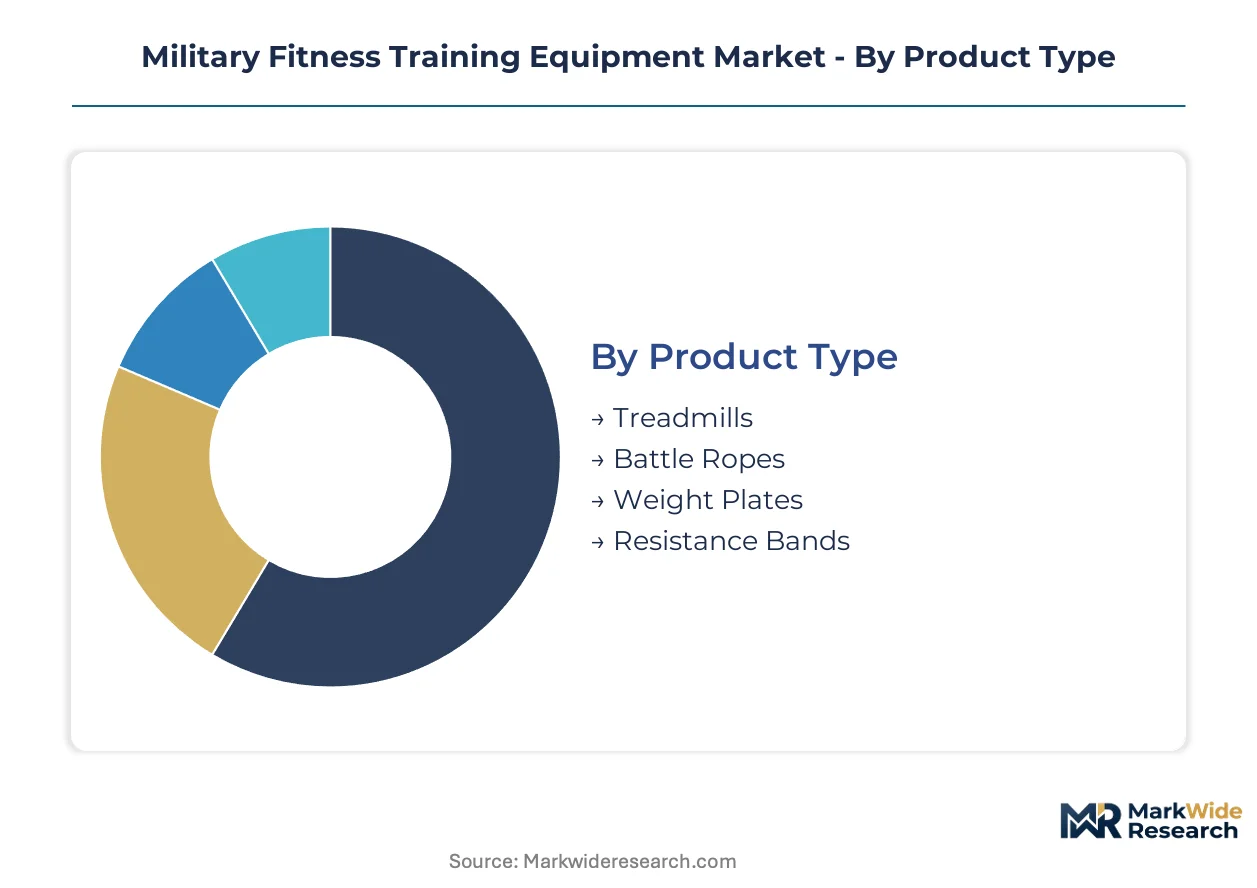
Defense procurement channels bifurcate sharply between MIL-STD-810H certified equipment and commercial-grade alternatives. Segmentation reveals how certification requirements, deployment velocity, and data governance reshape vendor eligibility across NATO militaries.
Product Type:
MIL-STD-810H environmental testing protocols differentiate forged load-bearing equipment from commercial fitness crossover products in defense tenders.
- Treadmills:Precision-calibrated cardio platforms with embedded shock absorption systems withstand temperature extremes from -51°C to 71°C. Bundeswehr base modernization programs in Germany prioritize these for permanent installations, though fiber and power upgrades at aging facilities frequently delay deployment timelines.
- Battle Ropes:Heavy-duty synthetic fiber construction resists salt fog and sand abrasion for expeditionary conditioning. NATO special operations units across rapid-deployment commands drive priority procurement, with portable configurations commanding premium pricing in forward operating base tenders.
- Weight Plates:Cast iron and rubber-coated variants engineered for load-carriage conditioning protocols.
- Resistance Bands:Latex and fabric alternatives for mobility training in constrained deployment environments.
Established volume favors Treadmills; emerging adoption favors Battle Ropes.
End User:
Customer type determines procurement autonomy and certification stringency across defense hierarchies.
- Armed Forces:Formal military branches enforce strict MIL-STD-810H and ASTM F2276 compliance for all equipment acquisitions. The U.S. Department of Defense mandates environmental qualification, while EU Green Deal and REACH regulations shape European material specifications for Bundeswehr and French Armed Forces contracts.
- Military Academies:Institutional training facilities balance durability requirements with educational technology integration. These installations in Germany and the United States are expanding biometric-enabled platforms for cadet performance tracking, though legacy infrastructure constraints slow smart equipment deployment.
- Fitness Trainers:Contracted specialists operating within defense facilities.
- Personal Trainers:Individual operators serving reserve and non-deployable units.
Procurement concentration sits with Armed Forces; technology upgrade cycles favor Military Academies.
Technology:
Data governance frameworks from GDPR-derived military privacy regulations reshape sensor development partnerships.
- Smart Gym Equipment:Embedded performance tracking platforms enable command-level fitness data aggregation. These systems are displacing analog equipment in permanent base modernizations, with early movers in cardio platform digitization securing multi-year contracts across NATO installations.
- Biometric Monitoring Systems:Fixed installations capturing load-carriage metrics and physiological thresholds. Special operations commands in Germany and the United States field-test integrated platforms streaming data directly to unit commanders, collapsing procurement distinctions between cardio machines and individual soldier monitoring.
- Wearable Sensors:Individual soldier devices for real-time performance tracking.
- Interactive Platforms:Software layers enabling equipment-to-equipment data interoperability.
Platform consolidation favors Smart Gym Equipment; convergence momentum favors Biometric Monitoring Systems.
Installation:
Deployment velocity requirements fragment traditional centralized procurement patterns toward unit-level purchasing autonomy.
- Mobile Units:Containerized gym systems deployable within standard shipping containers address unmet special operations demand. Rapid-setup configurations command pricing premiums in forward operating base tenders across United States special operations and British Army rapid response formations.
- Indoor Facilities:Permanent base installations requiring fiber and power infrastructure upgrades. These dominate current procurement volumes but face installation timelines exceeding equipment delivery schedules at aging facilities in Germany and the United States.
- Outdoor Training Areas:Weather-hardened equipment for expeditionary conditioning.
- Home Gyms:Individual equipment allocations for remote personnel.
Revenue scale favors Indoor Facilities; expansion trajectory favors Mobile Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement officers in expeditionary commands and base modernization programs concentrate demand across NATO member states. Special operations units in rapid-deployment formations drive premium equipment acquisitions. National military regulations and environmental certification standards reshape vendor eligibility by geography.
United States
Special operations commands and Marine Corps expeditionary units drive portable gym system demand through rapid-deployment tenders. The Department of Defense enforces MIL-STD-810H environmental testing protocols for all load-bearing equipment acquisitions. San Diego and Norfolk host the densest clusters of defense contractors adapting commercial fitness platforms for military specifications.
Germany
Bundeswehr base modernization programs prioritize integrated smart training systems for permanent installations. EU Green Deal REACH chemical compliance rules mandate coating substitutions in surface treatments for defense contracts. Bavaria and North Rhine-Westphalia concentrate equipment testing infrastructure serving continental procurement frameworks.
United Kingdom
British Army rapid response formations exercise unit-level purchasing autonomy through digital defense marketplaces. Ministry of Defence procurement guidelines align with NATO standardization agreements for interoperability. Salisbury Plain and Aldershot Garrison anchor field-testing programs for expeditionary conditioning systems.
France
French Armed Forces specifications phase out chromium plating and solvent-based finishes under EU environmental mandates. Direction Générale de l'Armement oversees certification reciprocity for multi-country NATO tenders. Toulouse and Paris-Saclay clusters integrate aerospace testing expertise into military fitness equipment validation.
Australia
Australian Defence Force special operations command prioritizes containerized gym systems for Indo-Pacific expeditionary deployments. Department of Defence procurement aligns with TGA-adjacent equipment safety frameworks for extreme climate performance. Brisbane and Perth base complexes drive regional demand for temperature-extreme conditioning apparatus.
Military Fitness Training Equipment Market Competitive Environment
Player mix skews toward defense-certified specialists and commercial fitness crossover entrants bifurcated by MIL-STD-810H qualification status. The competitive structure concentrates around three archetypes: forged-manufacturing domestic contractors, precision-calibrated European platform suppliers, and portable containerization specialists. Dominant competitive moves include strategic partnerships with cleared defense contractors for biometric sensor integration and supply chain restructuring for REACH-compliant material substitutions.
Among defense-certified fabricators, Rogue Fitness and BeaverFit exemplify contrasting strategic positions within the vendor base. Rogue Fitness represents the forged-in-America manufacturing archetype sustaining domestic military contracts through environmental qualification investments. BeaverFit occupies the expeditionary containerization specialist tier, anchoring demand from special operations commands requiring rapid-deployment configurations. Technogym S.p.A. sits within the European precision-platform segment, competing through defense procurement frameworks with calibrated cardio systems. These three players collectively illustrate how certification access, geographic origin, and deployment velocity specialization segment competitive eligibility across NATO tenders.
| Leading Market Players |
|---|
| Life Fitness |
| Technogym S.p.A. |
| TriActive USA |
| MoveStrong |
| Rally Fitness LLC |
| BeaverFit |
| Rogue Fitness |
| Keiser Corporation |
| Greenfields Outdoor Fitness |
| Others |
Value Chain & Pricing Dynamics
Six-to-nine-month MIL-STD-810H certification delays concentrate pricing power among defense-certified suppliers with proximate testing partnerships in Germany and the United States, while commercial-grade crossover entrants compete on shorter lead times at compressed margins.
Pricing Analysis
Cost-plus contracts with aluminum and steel indexation dominate procurement for forged load-bearing equipment, with price differentiation resting on MIL-STD-810H certification tier and expeditionary deployment velocity. Three-tier pricing structure across expeditionary-containerized, permanent-installation smart, and commercial-grade analog systems separates premium rapid-setup configurations from standard base modernization offerings. Pricing pressure stems from raw material cost volatility in North American foundry supply, compressing margin structures for structural components. Reserve units exhibit highest price sensitivity, bypassing defense-specified channels for uncertified commercial alternatives, while special operations commands demonstrate lowest sensitivity due to mission-critical deployment timelines.
Supply Chain Analysis
Ninety-day inventory cycles for structural steel components expose vendors to aluminum and steel price volatility, with geographic supply concentration anchoring in Germany, the United States, and Italy for precision-calibrated cardio platforms and forged manufacturing. Raw material dependencies center on domestic foundry capacity for cast iron weight plates, synthetic fiber imports for battle rope construction, and sensor component sourcing for biometric-enabled systems. Single-source vulnerability concentrates in MIL-STD-810H certified environmental testing infrastructure clustered in Bavaria and Virginia. Distribution runs through defense procurement frameworks and emerging digital defense marketplaces enabling unit-level purchasing autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as biometric integration and expeditionary containerization displace analog systems across NATO base modernization programs.
For Market Incumbents: Secure MIL-STD-810H testing partnerships in Germany and the United States to defend certification-eligible positioning against commercial fitness crossover entrants. Deepen backward integration into REACH-compliant coating supply chains to capture preferential Bundeswehr tender access as EU Green Deal mandates accelerate. For New Entrants and Emerging Players: Lead with portable containerized gym systems for special operations rapid-deployment commands, the most penetrable segment where unit-level purchasing autonomy overrides legacy contract vehicles. Target biometric sensor development partnerships with cleared defense contractors to navigate GDPR-derived military privacy frameworks. For Investors and Strategic Acquirers: Long-term, this sits as a defense-contractor consolidation play because certification barriers and testing infrastructure scarcity concentrate durable margins among qualified vendors. Watch special operations procurement velocity as the signal indicating acceleration or deceleration in expeditionary equipment adoption.| Strategic Initiative | Industry Significance |
|---|---|
| MIL-STD-810H Certification Investment | Environmental testing infrastructure unlocks eligibility for U.S. Department of Defense load-bearing equipment tenders. |
| REACH-Compliant Coating Reformulation | Surface treatment substitutions capture preferential access to Bundeswehr and French Armed Forces procurement frameworks. |
| Biometric Sensor Partnership | Cleared defense contractor alliances navigate GDPR-derived military personnel privacy regulations for smart platform deployment. |
| Expeditionary Containerization Scale-Up | Modular shipping-container configurations command pricing premiums in special operations forward operating base tenders. |
| Digital Defense Marketplace Integration | Platform connectivity enables unit-level purchasing autonomy in United States and British Army rapid-response formations. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with defense procurement officers, base facility engineers, special operations logistics coordinators, and commercial fitness equipment manufacturers transitioning into military contracts. Secondary validation drew from U.S. Department of Defense contract award databases, EU tender documentation for Bundeswehr modernization programs, ASTM and MIL-STD specification registries, and NATO standardization agreement archives. Bottom-up equipment shipment estimates and top-down defense budget allocation analysis were triangulated to establish market sizing.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by product type, end-user hierarchy, technology tier, and installation mobility class. CAGRs were derived from equipment procurement pipeline visibility, base modernization program schedules, and special operations force structure expansion plans. Inputs included defense budget trajectory assumptions, REACH chemical compliance phase-out timelines, and biometric data governance evolution across NATO member states.
The analysis sits within stated boundaries; outcomes outside sustained special operations procurement growth or accelerated EU environmental mandate enforcement would require recalibration. Forecasts reflect documented assumptions regarding certification reciprocity progress and testing infrastructure expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Exercise Bike Market
Fitness Equipment
Lung Exercise Machine Market
Fitness Equipment
Asia-Pacific Fitness Rings Market
Fitness Equipment
India Fitness Ring Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
South Africa Gym Accessories Market
Fitness Equipment
Japan Fitness Ring Market
Fitness Equipment
Functional Fitness Equipment Market
Fitness Equipment
Leg Exercise Equipment Market
Fitness Equipment
Fitness Equipment Market
Fitness Equipment
US Fitness Rings Market
Fitness Equipment
Personal Exercise Mats Market
Fitness Equipment
Belt Trainers Market
Fitness Equipment
North America Home Fitness Equipment Market
Fitness Equipment
Yoga Mat Market
Fitness Equipment
Asia-Pacific Fitness Equipment Market