
 Gymnastic Springboard Market | 2026-2036
Gymnastic Springboard Market Size, Share, and Industry Trends Forecast 2026-2036
Gymnastic Springboard Market Analytics
Single-source supply for springboard components is decoupling from traditional European foundries as manufacturers diversify forging partnerships across Asia. Janssen-Fritsen leverages its Benelux manufacturing base to sustain premium positioning in Olympic-specification equipment. Shenzhen LDK Industrial anchors volume production through integrated plywood lamination and steel spring fabrication in Guangdong. Mizuno competes in East Asian markets with specialized competition-grade platforms certified by Japan's national sports federation.
A gymnastic springboard is a resilient takeoff platform engineered with laminated hardwood decks, tempered steel coil springs, and non-slip surfacing to convert athlete approach velocity into vertical lift for vault and floor exercise routines. Competition-grade units typically achieve rebound coefficients between 0.75 and 0.85 while withstanding cyclic loads exceeding 1,500 Newtons. Standard springboard configurations retain the largest installed base among training facilities, though adjustable springboard variants capture expanding share as clubs seek multi-age-group program flexibility. Composite material construction represents the fastest-growing material segment as fiberglass-epoxy laminates displace solid wood cores in humidity-intensive environments.
China's SAMR enforces GB standards for sports equipment structural integrity, while Japan's METI coordinates JIS certification for institutional procurement eligibility. The EU AI Act and CE marking requirements under the MDR framework govern springboard exports to European training centers and competitive venues. Stakeholders must monitor evolving rebound-performance test protocols as national gymnastics federations recalibrate equipment specifications ahead of major championship cycles.
Market Dynamics
Certification-driven procurement tightening in China is fragmenting supplier bases as provincial training centers demand GB-compliant rebound-performance documentation before purchase authorization. This structural shift favors domestic manufacturers with integrated testing laboratories over import-reliant distributors.
Growth Catalysts
- GB Standards Enforcement:China's SAMR mandates structural integrity testing for all institutional springboard purchases, creating compliance-driven replacement cycles in Guangdong and Jiangsu training facilities.
- Fiberglass-Epoxy Adoption:Humidity-resistant composite cores are penetrating tropical and subtropical markets where solid wood degradation previously shortened equipment lifecycles.
- Multi-Age Program Expansion:Adjustable springboard configurations enable clubs to serve junior developmental pipelines through elite competitive tracks within single facility footprints.
Market Restraints
- Tempered Steel Input Volatility:Coil spring fabrication depends on specialized alloy steel grades subject to foundry capacity constraints in Asian forging centers.
- European Supply Decoupling:Traditional Benelux foundry partnerships are narrowing as manufacturers diversify forging relationships across Southeast Asian metalworking clusters.
- Rebound Coefficient Ceiling:Physics limitations in spring mechanics constrain competition-grade unit performance to 0.75-0.85 coefficient ranges regardless of material investment.
Strategic Opportunities
- India Institutional Buildout:National sports infrastructure programs are creating first-mover advantages for suppliers establishing BIS-certified manufacturing or assembly operations.
- Modular Surfacing Systems:Replaceable deck surface technologies extend core springboard lifecycles while generating recurring aftermarket revenue streams.
- AI-Assisted Performance Analytics:Sensor-integrated springboards capturing approach velocity and takeoff angle data are opening subscription-based coaching tool markets.
Industry Challenges
- Certification Timeline Compression:National federation specification updates ahead of championship cycles force accelerated retesting protocols that strain manufacturer R&D bandwidth.
- Legacy Equipment Integration:Training facilities with amortized standard-configuration inventories face capital inefficiencies when upgrading to adjustable or smart-enabled platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gymnastic Springboard Market |
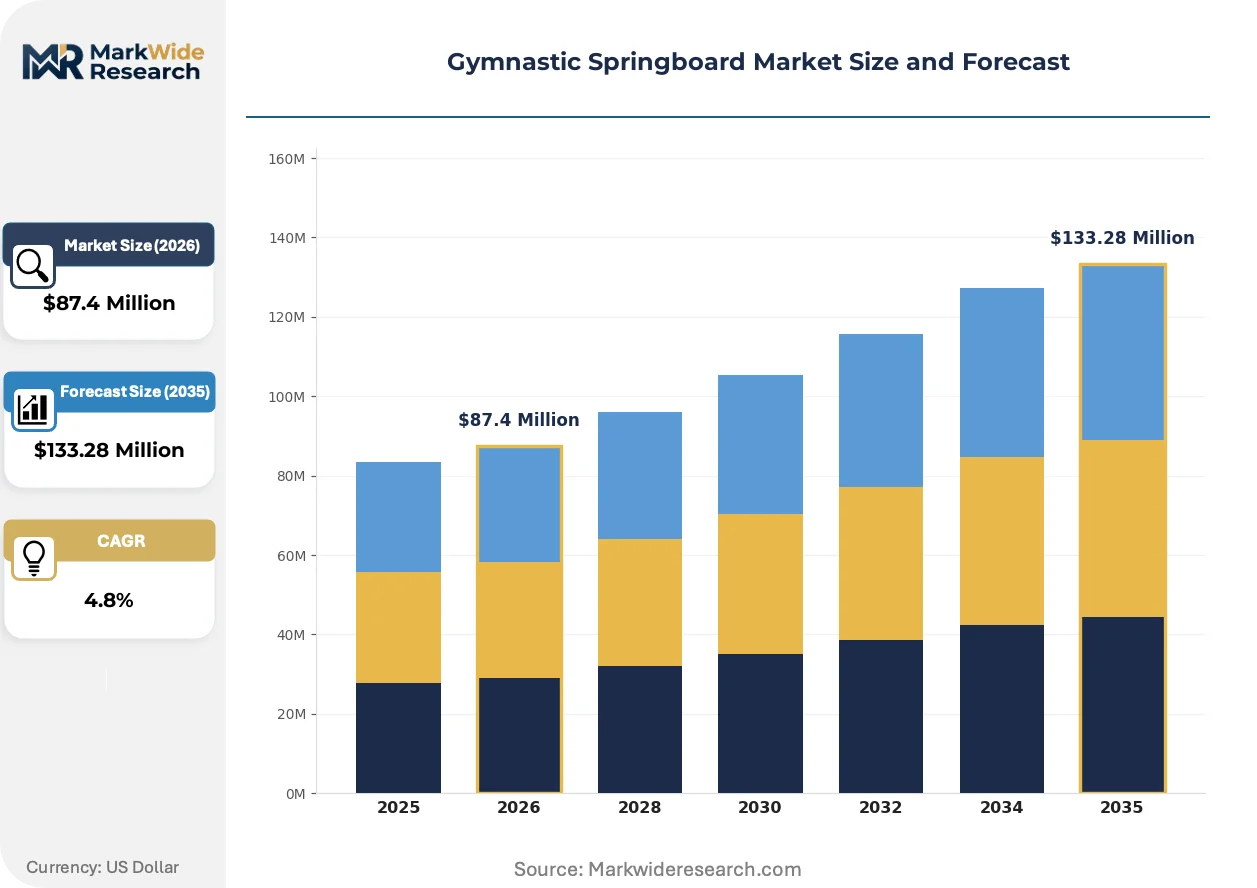
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $133.28 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Springboard, Adjustable Springboard, Portable Springboard, Competition Springboard Material: Wood, Foam, Composite, Rubber End User: Gymnastic Clubs, Schools, Training Centers, Professional Athletes Weight Capacity: Junior, Senior, Elite, Heavy-Duty |
| Companies Covered | Janssen-Fritsen, Adec Sports, Spieth America, Mizuno, Shenzhen LDK Industrial, ABEO, AVAI Gymnastic Equipment, Norberts Athletic Products, Gymnova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gymnastic Springboard Market Evolving Landscape
Material science advances and procurement digitization are restructuring how training centers evaluate and acquire springboard equipment. Three developments are altering competitive positioning and buyer decision frameworks.
Fiberglass-epoxy laminate construction is overtaking solid hardwood cores in humidity-intensive environments. Southeast Asian and coastal Chinese training centers are specifying composite decks to eliminate warping and delamination failures. This material transition is compressing maintenance cost differentials between premium and mid-tier product categories.
Japan's METI-coordinated JIS certification revisions are tightening rebound-performance measurement protocols for institutional eligibility. Equipment suppliers must now submit third-party laboratory documentation across temperature and humidity ranges. Competitive-grade platform manufacturers serving East Asian markets are restructuring quality assurance departments to manage expanded documentation requirements.
Direct manufacturer procurement through digital specification platforms is displacing traditional equipment distributor relationships in mid-market club segments. Chinese provincial sports bureaus are piloting centralized purchasing portals that standardize GB compliance verification before vendor consideration. This channel shift is visible in Shandong and Jiangsu where municipal training center networks aggregate demand through regional procurement consortia.
Gymnastic Springboard Market Segmentation
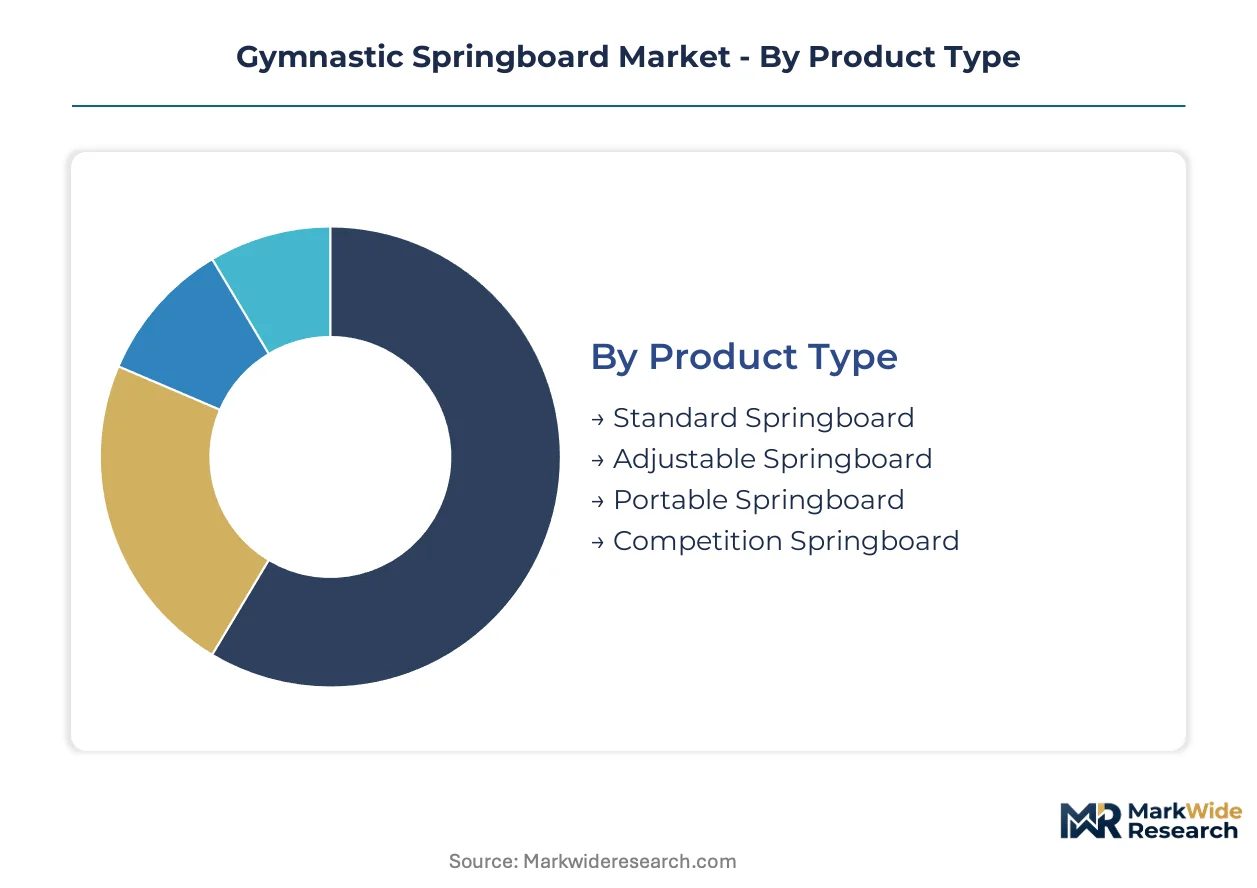
Springboard procurement decisions split across performance certification tiers, material durability requirements, and facility upgrade cycles. Each segmentation dimension carries distinct capital allocation implications for institutional buyers and commercial suppliers.
Product Type:
Capital intensity varies sharply across product categories, with competition-grade units demanding precision spring calibration and third-party rebound certification.
- Standard Springboard:Fixed-coil configurations with laminated hardwood decks dominate training facility inventories. Guangdong and Jiangsu provincial centers specify these units for foundational skill development programs where rebound consistency outweighs adjustability requirements.
- Adjustable Springboard:Modular spring tension systems enable rapid reconfiguration between junior and elite athlete protocols. Clubs in Shandong are consolidating equipment purchases around these platforms to compress capital expenditure across multi-age programming.
- Portable Springboard:Lightweight aluminum-frame designs with detachable components serve exhibition circuits and temporary training installations.
- Competition Springboard:Olympic-specification platforms with documented rebound coefficients undergo federation-mandated calibration cycles.
Standard configurations absorb the bulk of installed capacity; adjustable variants are expanding most quickly.
Material:
Raw material selection determines lifecycle economics, with humidity exposure and maintenance staffing driving specification divergence between coastal and inland facilities.
- Composite:Fiberglass-epoxy laminates eliminate moisture absorption failures in tropical training environments. Southeast Asian clubs are mandating composite cores to extend replacement intervals beyond solid hardwood degradation timelines.
- Wood:Traditional laminated maple and beech constructions retain cost advantages in climate-controlled facilities with dedicated maintenance programs.
- Foam:Polyurethane core systems reduce unit weight for portable and junior-specific applications.
- Rubber:Vulcanized elastomer surfacing layers provide non-slip interfaces over structural substrates.
Wood retains the deepest installed base; composite materials are climbing the fastest as humidity-resistant specifications spread.
End User:
Procurement authority and certification requirements fragment the buyer landscape across institutional, educational, and individual athlete segments.
- Training Centers:Provincial and municipal facilities in China account for the largest volume procurement, with SAMR GB compliance documentation mandatory before purchase authorization.
- Gymnastic Clubs:Private competitive programs balance equipment performance against membership retention economics, driving interest in adjustable configurations.
- Schools:Physical education departments prioritize durability and liability protection over competitive rebound specifications.
- Professional Athletes:Individual elite competitors maintain personal equipment for training camp portability and personalized spring calibration.
Training centers command the greatest procurement volume; gymnastic clubs are gaining share fastest as competitive program privatization accelerates.
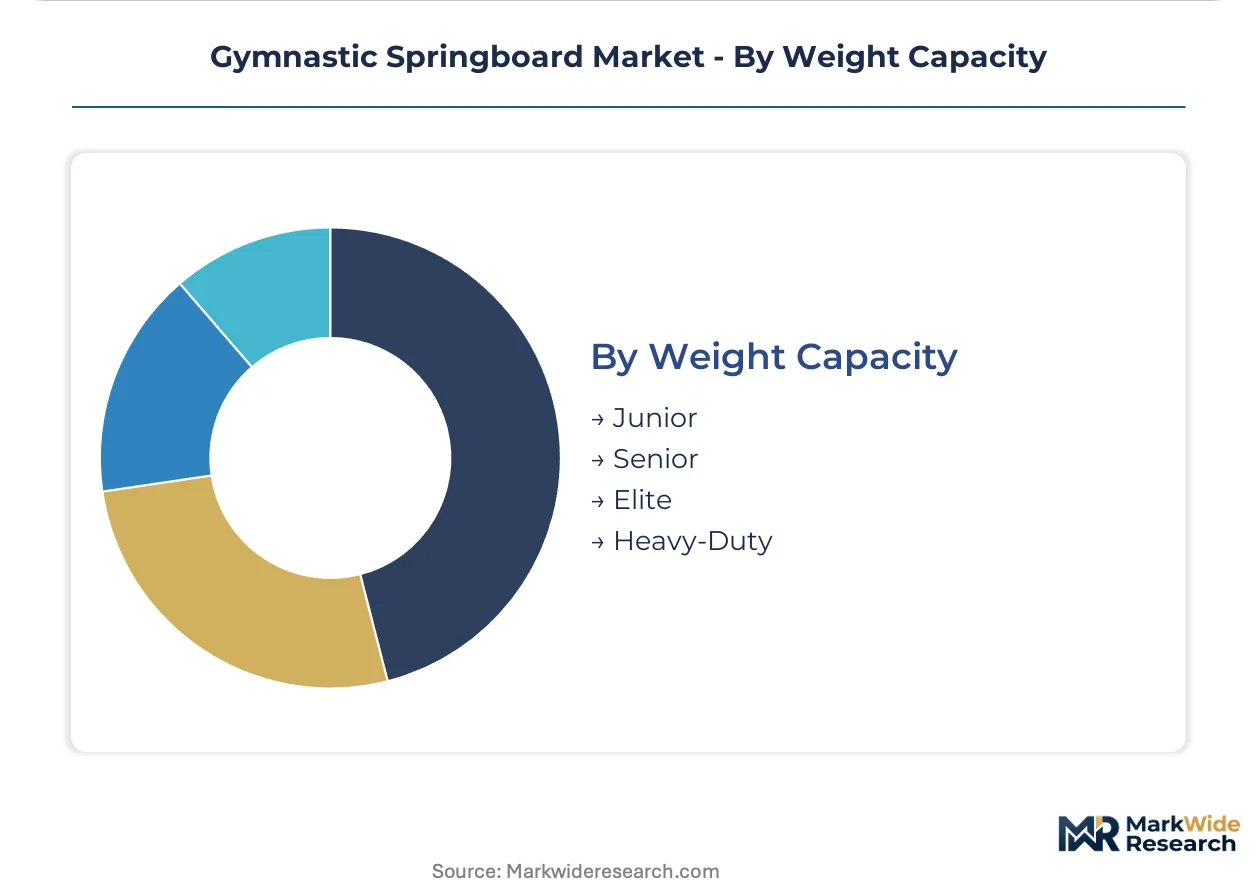
Weight Capacity:
Load rating specifications align with athlete development pathways, with certification bodies mandating distinct structural testing protocols across junior through elite tiers.
- Elite:Competition-grade platforms withstand cyclic loads exceeding 1,500 Newtons with documented rebound coefficients between 0.75 and 0.85. National federation procurement specifications restrict institutional purchases to elite-rated units for championship preparation facilities.
- Senior:Intermediate load ratings serve adolescent competitive pipelines where athlete mass distribution overlaps junior and elite classifications.
- Junior:Reduced spring tension and deck surface area accommodate younger athlete biomechanics and safety protocols.
- Heavy-Duty:Reinforced frame construction supports adaptive gymnastics and therapeutic training applications with elevated load requirements.
Elite-rated platforms dominate replacement expenditure; senior-tier specifications are expanding most quickly as developmental program enrollment rises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates institutional procurement volume through provincial training center networks in Guangdong, Jiangsu, and Shandong. Japan and South Korea maintain federation-driven certification requirements that structure equipment eligibility. European markets decouple from traditional Benelux supply chains as manufacturers diversify forging partnerships.
China
Provincial training centers in Guangdong and Jiangsu drive replacement cycles as SAMR tightens GB standards compliance for structural integrity documentation. Municipal sports bureaus pilot centralized procurement portals that aggregate demand through regional consortia. Shenzhen LDK Industrial anchors volume production through integrated plywood lamination and steel spring fabrication in the Pearl River Delta.
Japan
METI-coordinated JIS certification revisions mandate third-party rebound-performance documentation across temperature and humidity ranges for institutional eligibility. National gymnastics federation specification updates ahead of championship cycles force accelerated retesting protocols. Tokyo and Osaka metropolitan training facilities represent the primary demand concentration for competition-grade platforms.
Germany
CE marking requirements under the MDR framework govern springboard exports to European training centers and competitive venues. The EU AI Act introduces compliance considerations for sensor-integrated equipment entering institutional procurement channels. Industrial clusters in Bavaria and North Rhine-Westphalia host distributors serving Central European club networks.
United States
Private gymnastic clubs balance equipment performance against membership retention economics in competitive program expansion. NCAA institutional procurement follows federation-mandated specifications for championship preparation facilities. California and Texas metropolitan areas concentrate club density driving adjustable springboard demand for multi-age programming.
India
National sports infrastructure programs create first-mover advantages for suppliers establishing BIS-certified manufacturing or assembly operations. State-level training center buildouts in Maharashtra and Karnataka generate institutional procurement volume. Humidity-resistant composite specifications penetrate tropical training environments where solid wood degradation previously shortened equipment lifecycles.
Gymnastic Springboard Market Competitive Landscape
Certification-driven portfolio diversification dominates the current landscape as manufacturers restructure quality assurance departments to manage expanded documentation requirements. The vendor base separates into three tiers: Olympic-specification specialists with federation calibration contracts, mid-market integrated producers serving provincial procurement networks, and regional fabricators competing on price for club-level replacement cycles. Strategic archetypes include Benelux-based premium positioning, Guangdong-anchored volume manufacturing, and East Asian federation-certified specialization. Competitive moves concentrate on geographic expansion into BIS-eligible Indian operations and backward integration into captive steel spring production.
Within the premium-tier vector, Janssen-Fritsen represents Benelux-based Olympic-specification positioning. Shenzhen LDK Industrial exemplifies Guangdong-integrated volume manufacturing with combined plywood lamination and steel fabrication capabilities. Mizuno occupies a federation-certified specialization position serving East Asian institutional eligibility requirements.
| Leading Market Players |
|---|
| Janssen-Fritsen |
| Adec Sports |
| Spieth America |
| Mizuno |
| Shenzhen LDK Industrial |
| ABEO |
| AVAI Gymnastic Equipment |
| Norberts Athletic Products |
| Gymnova |
| Others |
Value Network & Pricing Analysis
Fiberglass-epoxy laminate adoption is compressing maintenance cost differentials between coastal and inland training facilities while simultaneously shifting procurement power toward composite-integrated manufacturers in Guangdong and Southeast Asian metalworking clusters. This material transition rewards suppliers with captive lamination capabilities and penalizes distributors dependent on European hardwood sourcing.
Pricing Analysis
Warranty and calibration service bundling separates Olympic-specification suppliers from unbundled club-grade competitors, with federation-mandated rebound certification cycles generating recurring revenue streams. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service inclusion, with provincial training centers in Jiangsu and Shandong exhibiting highest price sensitivity due to centralized procurement consortia. Cost compression in mid-tier wood-core configurations is intensifying because humidity-resistant composite alternatives are collapsing lifecycle cost premiums.
Supply Chain Analysis
Tempered steel coil supply rests on specialized alloy foundry capacity concentrated in China, South Korea, and Japan, with Guangdong metalworking clusters feeding integrated manufacturers like Shenzhen LDK Industrial. Laminated hardwood decking draws from Baltic birch and maple suppliers in Eastern Europe, while fiberglass-epoxy composite feeds from petrochemical processors in Singapore and South Korea. Single-source vulnerability in specialty spring steel grades exposes manufacturers to foundry queue delays. Distribution runs through regional sports equipment consortia in Chinese provinces and federation-authorized distributors in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certification timeline compression is forcing accelerated R&D retesting that smaller fabricators cannot fund, consolidating procurement authority around integrated manufacturers with captive testing laboratories.
For Market Incumbents: Deepen backward integration into tempered steel spring production to insulate margin structures from foundry queue volatility. Janssen-Fritsen's Benelux manufacturing base demonstrates how federation calibration contracts defend against price erosion from Guangdong volume competitors. Captive rebound-performance testing laboratories accelerate certification cycles ahead of championship-driven specification updates. For New Entrants and Emerging Players: Direct-to-club digital specification platforms offer lower-friction entry than federation-authorized distributor networks. India's BIS certification pathway remains underpenetrated by established players, creating first-mover advantages for suppliers establishing Maharashtra or Karnataka assembly operations. Modular surfacing replacement technologies generate recurring aftermarket revenue without requiring full springboard manufacturing scale. For Investors and Strategic Acquirers: Exit pathways concentrate in federation-authorized specialists with calibration contract lock-in. Long-term viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Watch for SAMR GB standard enforcement intensity as inflection indicator for replacement cycle velocity in Guangdong and Jiangsu provincial networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spring Steel Production | Captive foundry capacity insulates margins from Asian alloy supply queue volatility. |
| Federation Calibration Contract Acquisition | Janssen-Fritsen's Olympic-specification positioning demonstrates recurring revenue lock-in. |
| Composite Lamination Capability Buildout | Fiberglass-epoxy integration captures humidity-resistant specifications spreading through Southeast Asia. |
| BIS-Certified India Assembly Operations | Maharashtra and Karnataka state buildouts create first-mover procurement advantages. |
| Sensor-Integrated Smart Platform Development | AI-assisted performance analytics open subscription-based coaching tool markets. |
Research Methodology
Independent corroboration across equipment procurement directors at provincial training centers, quality assurance leads at federation-certified manufacturers, and sports infrastructure planners at municipal bureaus underwrites the qualitative findings. Secondary validation drew from SAMR GB standard documentation, JIS certification revision records, and customs trade data on steel alloy imports. Bottom-up facility inventory estimates triangulated against top-down federation procurement disclosures.
Comparable-period anchoring to historical replacement cycles in Guangdong and Jiangsu provinces structured the projection horizon. Segmentation dimensions modeled include product type tier, material composition, end-user institutional category, and weight capacity rating. CAGRs were derived from elasticity-adjusted demand curves incorporating provincial sports infrastructure budget trajectories and certification-driven compliance deadlines.
The model holds under steady GB enforcement intensity and stable steel alloy supply; deviation in SAMR audit frequency or foundry capacity constraints would shift replacement cycle timing. Forecasts reflect documented assumptions about federation specification update cadence. A small set of named triggers warrants ongoing watch: SAMR structural integrity audit intensity, JIS rebound-protocol revision scope, and Southeast Asian composite feedstock price volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Lateral Fitness Equipment Market
Fitness Equipment
BMI Machine Market
Fitness Equipment
Hydrotherapy Treadmills Market
Fitness Equipment
Saudi Arabia Outdoor Fitness Equipment Market
Fitness Equipment
Treadmill Desks Market
Fitness Equipment
Gym Ball Market
Fitness Equipment
Europe Fitness Equipment Market
Fitness Equipment
Recumbent Stationary Bikes Market
Fitness Equipment
Pilates Equipment and Gears Market
Fitness Equipment
Strength Training Equipment Market
Fitness Equipment
Lung Exercise Machine Market
Fitness Equipment
Smart Scales Market
Fitness Equipment
Exercise Resistance Bands Market
Fitness Equipment
China Outdoor Fitness Equipment Market
Fitness Equipment
PVC Stretch Yoga Mats Market
Fitness Equipment
Europe E-Commerce Home Fitness Products Market