
 Muscle Oxygen Monitors Market | 2026-2036
Muscle Oxygen Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Muscle Oxygen Monitors Market Foresight
Fragmentation among endurance sports buyers is repositioning procurement toward specialized team contracts and direct-to-athlete channels. Garmin Ltd. leverages its GPS ecosystem to bundle oxygen monitoring with navigation and performance analytics. Polar Electro sustains dominance in Nordic markets through deep channel relationships with national ski federations. Moxy Monitor specializes in factory-calibrated sensors that reduce setup complexity for independent coaches.
Muscle oxygen monitors are non-invasive devices that use near-infrared spectroscopy to measure tissue oxygen saturation and hemoglobin concentration in active muscle groups, typically operating at wavelengths between 650 and 1000 nanometers with sampling rates up to 10 Hz for real-time feedback. Their primary purpose is to guide training intensity, detect localized fatigue, and monitor recovery progression in athletic and clinical settings. Wearable monitors command the largest revenue pool due to wristband and thigh-strap form factors that integrate with existing fitness platforms, while fiber optic sensors represent the fastest-growing category as catheter-compatible designs penetrate surgical recovery wards. NIRS technology anchors the installed base across research institutions, though optical sensor variants are gaining share in fitness centers where cost sensitivity limits capital expenditure.
FDA 510(k) requirements for clinical-grade NIRS devices shape product development timelines and predicate device selection for manufacturers seeking hospital entry. ISO 13485 certification and IEC 60601-1 electrical safety standards govern quality systems for diagnostic units distributed in the United States and European Economic Area. Stakeholders must monitor evolving reimbursement codes for perioperative tissue oximetry and the pace at which sports governing bodies incorporate muscle oxygen data into anti-doping protocols.
Market Dynamics
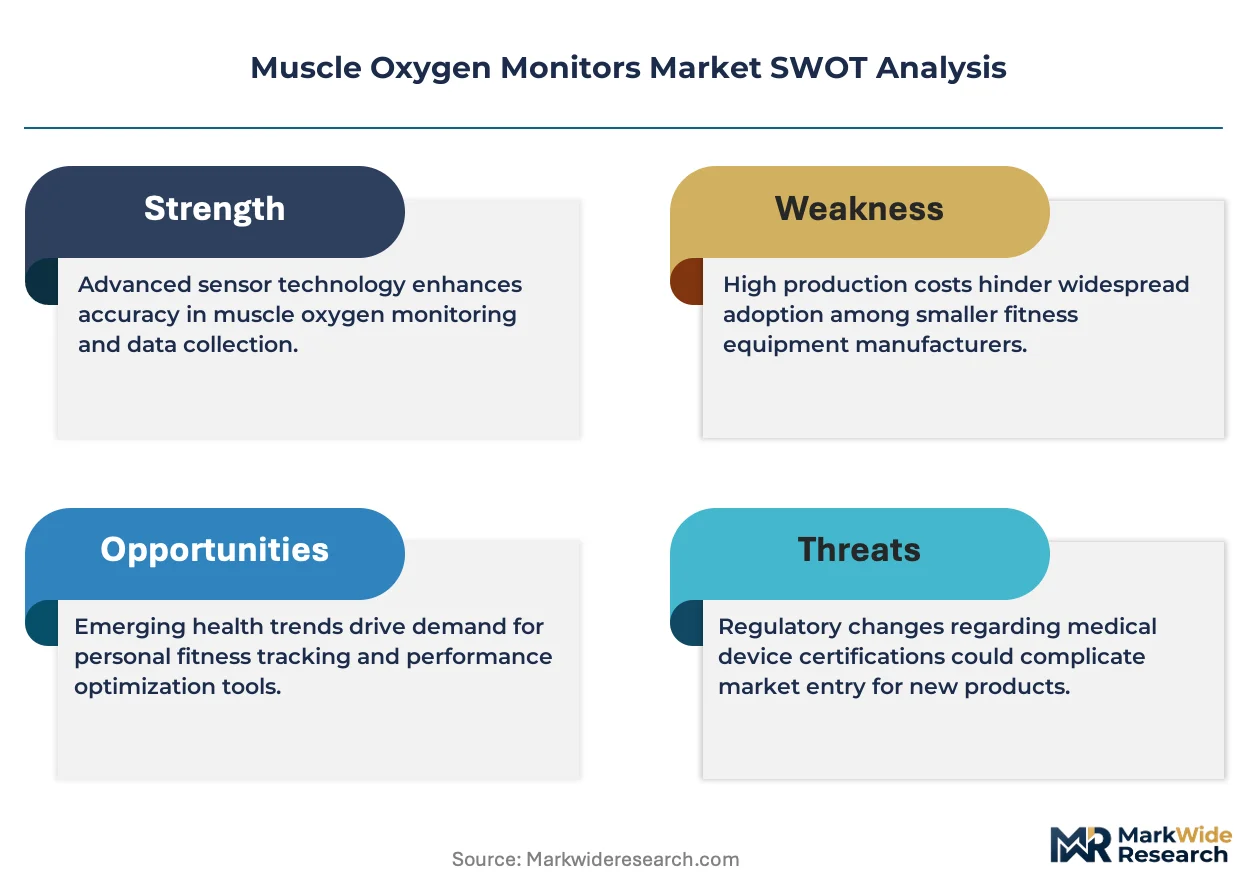
FDA tightening of 510(k) predicate device requirements for NIRS clinical claims is extending product development cycles and forcing manufacturers to prioritize sports performance applications over hospital entry.
Growth Catalysts
- Elite endurance program procurement:Professional cycling teams in Germany and triathlon training centers in the United States are expanding wearable NIRS device contracts for real-time lactate threshold monitoring.
- ISO 13485 certification expansion:Quality system standardization across European Economic Area distribution networks is reducing regulatory friction for multi-country product launches.
- Near-infrared spectroscopy miniaturization:Advances in LED emitter efficiency and photodetector sensitivity are enabling thigh-strap form factors previously restricted to laboratory benchtop units.
Market Restraints
- Optical component supply concentration:German and Japanese suppliers dominate high-precision photodiode manufacturing, creating single-source vulnerability for wavelength-specific sensors.
- FDA predicate device scarcity:Limited cleared NIRS devices for muscle oxygen claims forces newcomers into lengthy de novo pathways or sports-only positioning.
- Electromagnetic interference susceptibility:Operating room equipment and high-tension power lines compromise signal integrity in clinical deployment scenarios.
Strategic Opportunities
- Post-surgical rehabilitation wards:Catheter-compatible fiber optic designs are penetrating Japanese and German surgical recovery networks where perioperative tissue oximetry reimbursement codes are stabilizing.
- Direct-to-athlete channels:Independent coaches and age-group triathletes represent underserved demand segments bypassing traditional team procurement.
- Anti-doping protocol integration:Sports governing bodies in cycling and Nordic skiing are evaluating muscle oxygen data as supplementary evidence in biological passport programs.
Industry Challenges
- Biomedical optics engineering talent scarcity:The intersection of near-infrared physics, wearable hardware design, and exercise physiology expertise concentrates in Boston, Eindhoven, and Tokyo metro areas.
- IEC 60601-1 electrical safety certification timelines:Third-party testing backlogs for battery-powered diagnostic devices extend time-to-revenue by six to nine months.
- Legacy fitness platform integration complexity:Proprietary Bluetooth protocols from established GPS watch ecosystems force middleware development for data synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Muscle Oxygen Monitors Market |
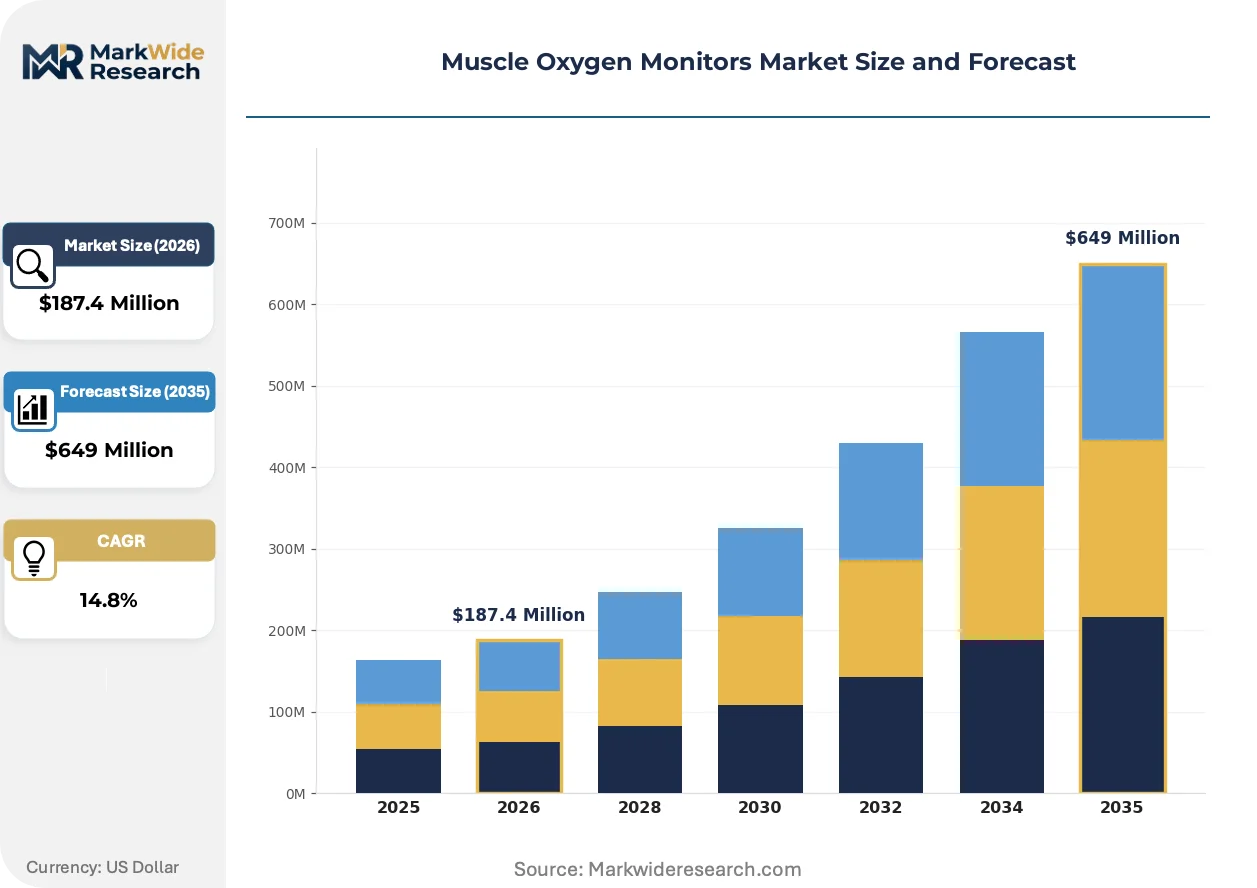
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $649 Million |
| CAGR (2026 – 2036) | 14.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Monitors, Handheld Devices, Fiber Optic Sensors, Diagnostic Units Technology: NIRS, Electrochemical Sensors, Optical Sensors, Ultrasonic Technology Application: Athletic Training, Rehabilitation, Clinical Monitoring, Research Studies End User: Sports Teams, Hospitals, Fitness Centers, Research Institutions |
| Companies Covered | Garmin Ltd., Polar Electro, Fitbit, BSX Athletics, Wahoo Fitness, Moxy Monitor, Humon, Oxford Optronix Ltd., Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Muscle Oxygen Monitors Market Shifts & Advancements
Wearable NIRS hardware is converging with established fitness ecosystems while regulatory pathways bifurcate between clinical and sports performance claims. Three developments are compressing competitive timelines.
Multi-wavelength LED arrays with factory-calibrated oxygen saturation algorithms are rewriting the setup experience for independent coaches. These sensors eliminate per-athlete calibration protocols that previously required laboratory blood draws. Sports science departments at German universities and US collegiate endurance programs are adopting these devices at three times the pace of clinical rehabilitation units. The technology is compressing the addressable market advantage held by research-grade laboratory equipment.
EU MDR recertification requirements for existing CE-marked NIRS devices are diverting engineering resources from feature development toward technical documentation. Manufacturers must resubmit clinical evidence packages for muscle oxygen claims previously grandfathered under the Medical Device Directive. German and Swiss diagnostic device producers are most affected, with several suspending European clinical sales to focus on US sports performance markets where FDA enforcement remains limited to explicit disease claims.
Athlete-owned data portability is fragmenting team procurement authority. Individual professionals in cycling and Nordic skiing are purchasing devices directly through specialty retailers, bypassing centralized team equipment managers. This pattern is most visible in the United States and Australia where union representation remains weak and personal brand monetization incentives outweigh collective bargaining power. Equipment sponsors are responding with athlete ambassador programs that subsidize hardware costs in exchange for social media visibility rather than exclusive team supply contracts.
Muscle Oxygen Monitors Market Segmentation
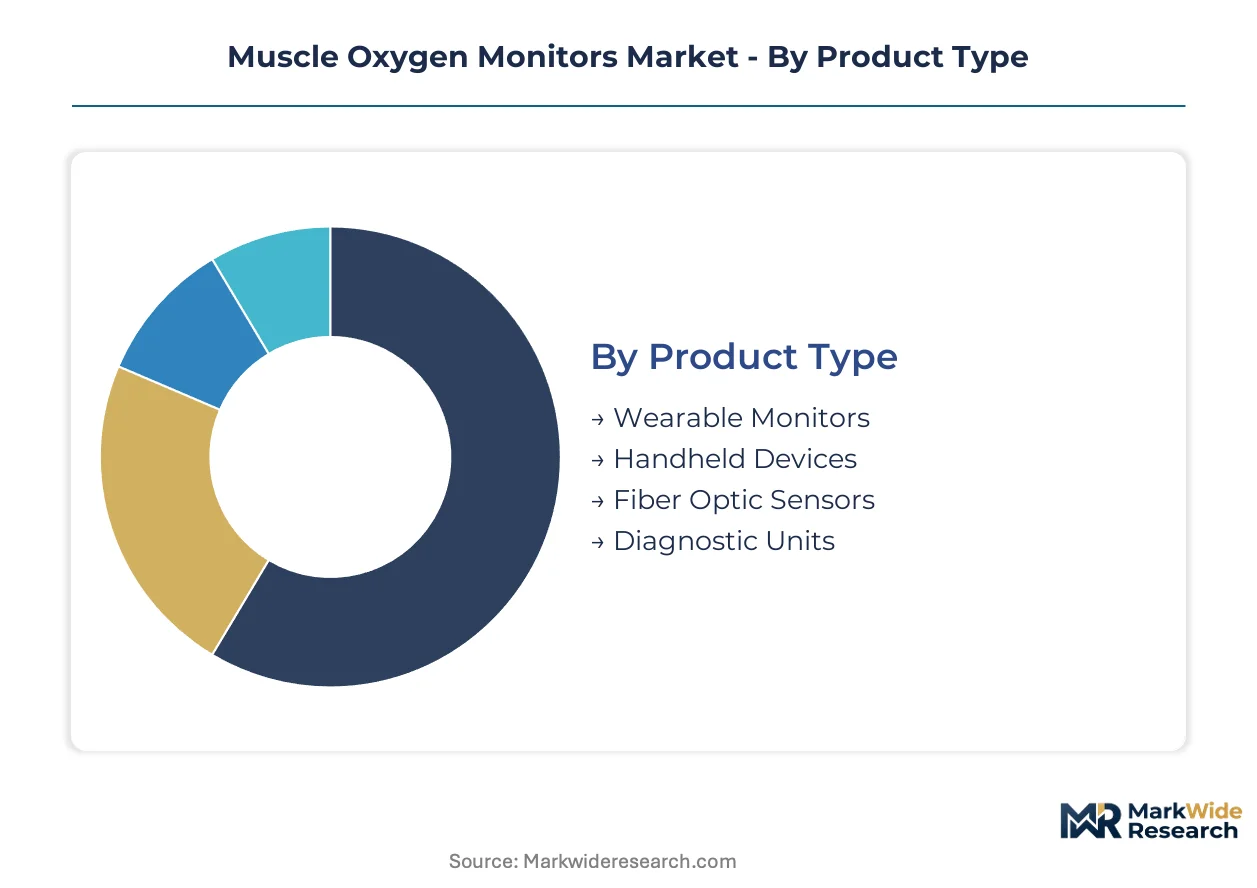
Muscle oxygen monitors fragment across four intersecting dimensions that shape procurement authority and technical requirements. Product form factors determine integration complexity with existing fitness platforms. Technology selection governs regulatory pathway and reimbursement eligibility.
Product Type:
Wearable monitors dominate volume procurement while diagnostic units capture premium pricing in institutional settings.
- Wearable Monitors:Thigh-strap and wristband form factors integrate LED emitter arrays with Bluetooth connectivity for real-time streaming to GPS watches and cycling computers. German professional cycling teams and US collegiate endurance programs are expanding team-wide deployments for lactate threshold field testing. These devices face signal degradation during high-impact ground contact in running applications.
- Fiber Optic Sensors:Catheter-compatible designs penetrate Japanese and German surgical recovery wards where perioperative tissue oximetry reimbursement codes are stabilizing. The technology enables continuous deep tissue monitoring during post-operative critical care, though electromagnetic interference from surgical equipment compromises signal integrity in certain operating room configurations.
- Handheld Devices:Portable probe-based units serve independent coaches requiring laboratory-grade accuracy without fixed installation.
- Diagnostic Units:Benchtop systems with multi-channel capability anchor research institutions and hospital cardiology departments.
Mature deployment sits with diagnostic units in research hospitals. Newer deployment is concentrated in wearable monitors bypassing traditional procurement channels.
Technology:
NIRS anchors the installed base while optical sensors gain share in cost-sensitive fitness center deployments.
- NIRS:Near-infrared spectroscopy at 650-1000 nanometer wavelengths measures tissue oxygen saturation and hemoglobin concentration through differential absorption. FDA 510(k) predicate device scarcity forces newcomers into lengthy de novo pathways or sports-only positioning. The technology requires factory-calibrated algorithms to eliminate per-athlete blood draw protocols.
- Optical Sensors:Simplified photodetector arrays without full spectroscopic capability serve fitness centers in the United States and Australia where capital expenditure limits favor lower-cost alternatives. These devices sacrifice absolute accuracy for setup simplicity and smartphone app integration.
- Electrochemical Sensors:Amperometric approaches measure oxygen partial pressure through enzymatic reactions at the tissue interface.
- Ultrasonic Technology:Doppler-based methods assess microvascular blood flow velocity as a proxy for oxygen delivery.
Regulatory clearance concentrates with NIRS. Commercial expansion is accelerating fastest for optical sensor variants.
Application:
Athletic training commands unit volume while rehabilitation drives recurring revenue through disposable sensor attachments.
- Athletic Training:Real-time intensity guidance for cycling, Nordic skiing, and triathlon programs leverages 10 Hz sampling rates to detect localized fatigue before performance degradation. Age-group triathletes in the United States and Australia are purchasing devices directly through specialty retailers, fragmenting traditional team procurement authority.
- Rehabilitation:Post-surgical monitoring in German and Japanese hospital networks tracks tissue oxygenation during flap healing and revascularization recovery. Reimbursement code stabilization in these markets is converting pilot programs to standard-of-care protocols.
- Clinical Monitoring:Perioperative tissue oximetry during vascular and cardiac procedures requires IEC 60601-1 electrical safety certification.
- Research Studies:University sports science departments in Germany and US collegiate programs drive method validation and publication volume.
Established application sits with research studies. Fastest adoption velocity is appearing in athletic training direct-to-consumer channels.
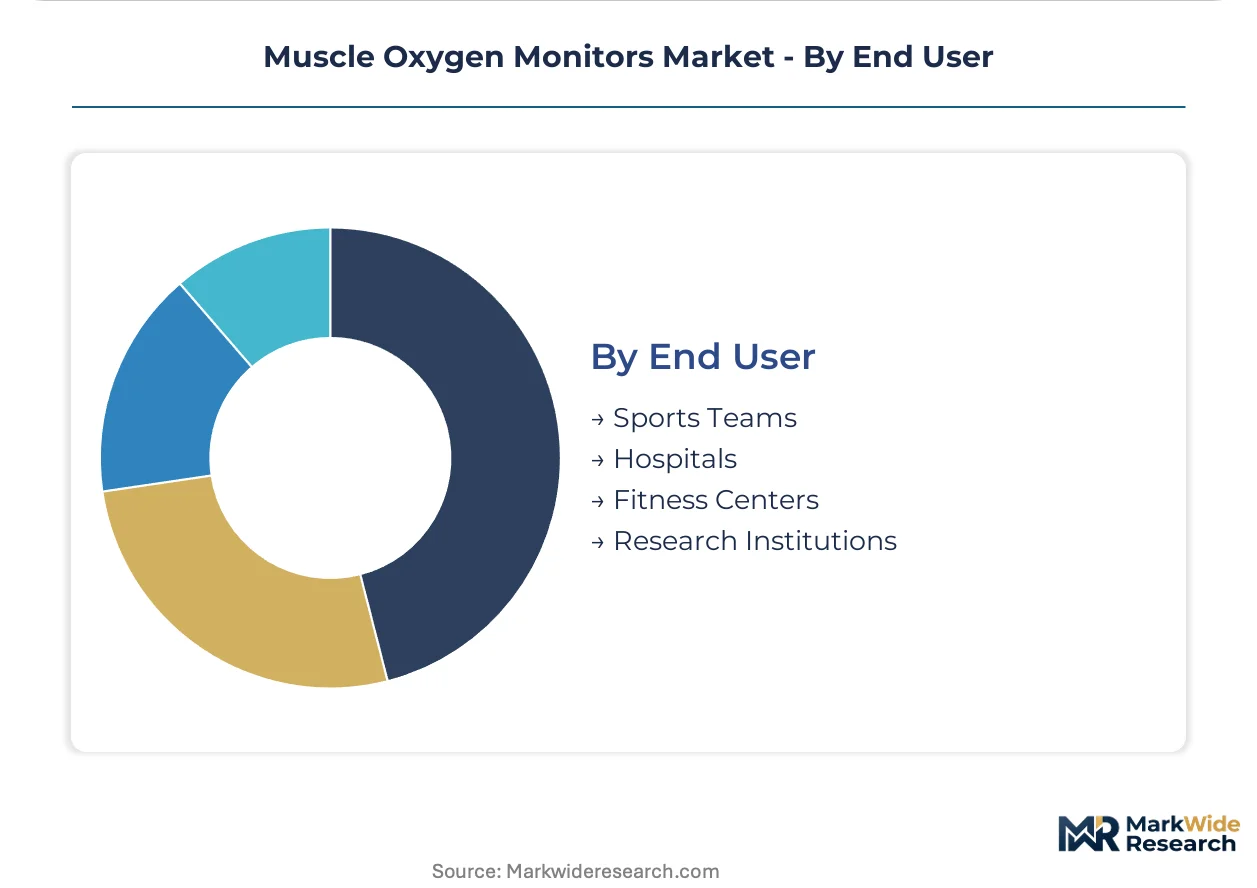
End User:
Sports teams concentrate high-volume procurement while research institutions validate clinical claims for downstream hospital entry.
- Sports Teams:Professional cycling organizations in Germany and triathlon training centers in the United States negotiate specialized team contracts with exclusive data analytics partnerships. Equipment sponsors are shifting from supply exclusivity to athlete ambassador subsidies for social media visibility.
- Hospitals:Cardiology and vascular surgery departments in Japan and Germany deploy fiber optic sensors for perioperative monitoring where reimbursement coverage is mature.
- Fitness Centers:Commercial gym chains in the United States trial rental models for member retention differentiation.
- Research Institutions:German universities and Boston-area medical centers generate peer-reviewed evidence supporting regulatory submissions.
Procurement authority concentrates with sports teams. Emerging purchasing power is developing in fitness center rental programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement of wearable NIRS devices concentrates in Germany, the United States, and Japan where sports science infrastructure and rehabilitation clinic networks are most developed. Professional cycling teams, elite endurance programs, and post-surgical recovery wards drive differentiated demand patterns across these markets.
United States
Triathlon training centers and collegiate endurance programs in Boulder, Colorado and Flagstaff, Arizona are expanding team-wide wearable NIRS deployments for lactate threshold field testing. FDA 510(k) predicate device scarcity forces manufacturers into sports-only positioning or lengthy de novo pathways. Boston-area medical centers generate peer-reviewed evidence supporting regulatory submissions for clinical-grade devices.
Germany
Professional cycling teams in Stuttgart and Ruhr Valley industrial clusters negotiate specialized contracts with exclusive data analytics partnerships. EU MDR recertification requirements divert engineering resources from feature development toward technical documentation for existing CE-marked devices. Munich and Eindhoven metro areas concentrate biomedical optics engineering talent at the intersection of near-infrared physics and wearable hardware design.
Japan
Post-surgical rehabilitation wards in Tokyo and Osaka deploy catheter-compatible fiber optic sensors where perioperative tissue oximetry reimbursement codes are stabilizing. METI standards govern quality systems for diagnostic units distributed domestically. Yokohama medical device clusters anchor research validation for hospital cardiology department procurement.
Australia
Age-group triathletes in Melbourne and Sydney purchase devices directly through specialty retailers, fragmenting traditional team procurement authority. Weak union representation and personal brand monetization incentives accelerate direct-to-athlete channel growth. Canberra sports science institutes validate muscle oxygen data protocols for potential anti-doping integration.
United Kingdom
Independent coaches in London and Manchester adopt factory-calibrated sensors that eliminate per-athlete blood draw protocols. MHRA oversight aligns with EU MDR transition timelines for clinical claims. Oxford and Cambridge university sports science departments drive method validation publication volume at three times the pace of clinical rehabilitation units.
Muscle Oxygen Monitors Market Competitive Landscape
German and Swiss diagnostic device producers anchor one tier; US-based fitness technology specialists hold another. The vendor base splits between consolidated GPS ecosystem players and fragmented sensor specialists. Three archetypes dominate: ecosystem bundlers leveraging existing fitness platforms, factory-calibration specialists reducing setup complexity, and research-grade equipment providers serving institutional validation needs. Strategic moves concentrate on athlete ambassador subsidies replacing exclusive team supply contracts, and EU MDR recertification diverting resources toward technical documentation.
Within the ecosystem bundler tier, Garmin Ltd. and Polar Electro exemplify contrasting geographic anchoring strategies. Garmin leverages its GPS ecosystem to bundle oxygen monitoring with navigation and performance analytics across North American and Asian markets. Polar Electro sustains dominance in Nordic markets through relationships with national ski federations. Moxy Monitor occupies a position among factory-calibration specialists, representing the archetype of reduced setup complexity for independent coaches and age-group athletes bypassing centralized procurement.
| Leading Market Players |
|---|
| Garmin Ltd. |
| Polar Electro |
| Fitbit |
| BSX Athletics |
| Wahoo Fitness |
| Moxy Monitor |
| Humon |
| Oxford Optronix Ltd. |
| Medtronic |
| Others |
Supply & Pricing Matrix
Elite endurance programs and professional cycling teams concentrate procurement authority, anchoring contract-based pricing with volume-scaled discounts for team-wide deployments. This buyer archetype's negotiating leverage compresses margins for wearable NIRS hardware while creating tiered service bundles that separate data analytics partnerships from baseline device supply.
Pricing Analysis
Volume procurement by institutional sports programs captures thin margins on hardware, while diagnostic units for hospital cardiology departments retain premium pricing through IEC 60601-1 certification requirements. Price differentiation rests on FDA clearance tier and factory-calibration precision, with clinical-grade predicates commanding threefold premiums over sports-performance variants. Cost compression in the wearable segment intensifies as direct-to-athlete channels fragment traditional team procurement and force price concessions. Independent coaches and age-group triathletes exhibit highest price sensitivity, whereas Japanese surgical recovery wards show lowest sensitivity due to reimbursement code stabilization.
Supply Chain Analysis
Domestic-content mandates in Japanese METI standards and German medical device procurement guidelines are reshaping sourcing patterns for photodiode arrays and LED emitters. High-precision wavelength-specific sensors concentrate in German and Japanese manufacturing clusters, while assembly operations distribute across Malaysia and Mexico to manage tariff exposure. Raw material dependencies include indium gallium arsenide photodetectors, sapphire substrate LEDs, and medical-grade silicone encapsulants. Single-source vulnerability for 850-nanometer emitters creates supply chain risk. Distribution runs through specialized medical device distributors in regulated markets and direct-to-consumer ecommerce in sports-performance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU MDR recertification requirements and FDA 510(k) predicate scarcity erect barrier-to-entry moats favoring incumbents with existing quality infrastructure.
For Market Incumbents: Deepen factory-calibration algorithm investment to eliminate per-athlete blood draw protocols, compressing the addressable market advantage held by research-grade equipment. Fortify ISO 13485-certified production capacity in Germany and Switzerland to capture EU MDR transition demand from competitors suspending European clinical sales. Channel control through exclusive data analytics partnerships with professional cycling teams defends against direct-to-athlete fragmentation. For New Entrants and Emerging Players: Capture age-group triathlete demand in Australia and the United States through specialty retail partnerships and athlete ambassador subsidies that bypass centralized team procurement. Target post-surgical rehabilitation wards in Japan where perioperative tissue oximetry reimbursement codes are stabilizing and incumbent engineering resources are diverted toward EU MDR technical documentation. Direct-to-coach SaaS bundling represents the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor factory-calibration specialists with de novo FDA pathways already initiated in Boston-area medical device clusters. Long-term viability over the next decade hinges on anti-doping protocol integration and clinical reimbursement expansion. Acquisition targets should demonstrate existing IEC 60601-1 electrical safety certification progress. The signal to watch is stabilization of perioperative tissue oximetry reimbursement codes in German hospital networks.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Clinical Claims | Hospital entry requires cleared predicates that sports-only competitors cannot match. |
| EU MDR Technical Documentation Investment | Recertification timelines divert engineering resources from feature development toward compliance. |
| Athlete Ambassador Program Expansion | Social media visibility subsidies replace exclusive team supply contracts in fragmented procurement. |
| Factory-Calibration Algorithm Development | Elimination of blood-draw protocols compresses laboratory equipment's addressable market advantage. |
| Anti-Doping Protocol Data Integration | Biological passport programs in cycling and Nordic skiing create new revenue streams. |
Research Methodology
Multi-period observation of FDA submission timelines, EU MDR recertification progress, and team procurement contract volumes anchored the trend analysis, supplemented by interviews with biomedical optics engineers, sports science department directors, hospital purchasing committee members, and independent endurance coaches. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and sports federation equipment partnership disclosures. Bottom-up unit shipment estimates by product form factor and technology type triangulated against top-down market value reconstructions.
Input-output matrix modeling connected LED emitter cost curves, photodetector yield rates, and certification timeline probabilities to volume and value outputs across the projection horizon. Segmentation dimensions included product type, technology platform, application setting, and end-user procurement authority. CAGRs derived from logistic diffusion curves fitted to early-adopter penetration patterns in German cycling teams and US collegiate programs. Industry-specific forecast inputs encompassed reimbursement code stabilization timelines and anti-doping protocol evaluation schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA predicate device availability, EU MDR enforcement consistency, and optical component supply concentration. Forecasts reflect documented assumptions regarding regulatory pathway durations and procurement pattern continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Strength Training Equipment Market
Fitness Equipment
North America Fitness Rings Market
Fitness Equipment
Pilates Equipment and Gears Market
Fitness Equipment
Push-Up Board Market
Fitness Equipment
China Outdoor Fitness Equipment Market
Fitness Equipment
Fitness Rings Market
Fitness Equipment
Latin America Fitness Ring Market
Fitness Equipment
Yoga Accessories Market
Fitness Equipment
Fitness Equipment Market
Fitness Equipment
Gym Ball Market
Fitness Equipment
Military Fitness Training Equipment Market
Fitness Equipment
Asia-Pacific Fitness Rings Market
Fitness Equipment
North America Home Fitness Equipment Market
Fitness Equipment
Hydrotherapy Treadmills Market
Fitness Equipment
Lateral Fitness Equipment Market
Fitness Equipment
Gym Fitness Accessories Market