
 Treadmill Ergometer Market | 2026-2036
Treadmill Ergometer Market Size, Share, and Industry Trends Forecast 2026-2036
Treadmill Ergometer Market Outlook
Buyer concentration among commercial gyms is pivoting toward fragmentation as boutique fitness studios and corporate wellness programs multiply procurement channels. Technogym S.p.A. leverages its Italian manufacturing base to dominate premium commercial installations across European health clubs. Johnson Health Tech anchors its position through vertical control of assembly lines in Asia, sustaining cost advantages in mid-tier motorized units. ICON Health & Fitness competes through direct-to-consumer channel density, occupying a distinct price-position in folding treadmill ergometers for home users.
A treadmill ergometer is an instrumented running platform that measures physiological workload through integrated force plates, gas-analysis ports, and variable resistance systems calibrated to metabolic equivalents. These systems serve clinical diagnostics, athletic performance laboratories, and commercial fitness environments requiring quantified training prescriptions. Motorized units with electrical resistance technology lead installed base volumes, while magnetic resistance configurations capture margin pools in rehabilitation settings demanding silent operation and precise torque control. Folding designs remain a mature home-user category, whereas non-folding platforms dominate commercial gym and sports institute deployments where structural rigidity outweighs space constraints.
The FDA enforces 21 CFR 870 classification for diagnostic exercise stress systems, compelling software validation and electromagnetic compatibility testing that elevates engineering costs for US market entry. ISO 20957-6 governs stationary training equipment safety, while the EU Medical Device Regulation demands notified body oversight for ergometers claiming clinical measurement accuracy. Stakeholders must monitor how evolving cybersecurity standards for connected fitness devices reshape product development roadmaps and regional certification timelines.
Market Dynamics
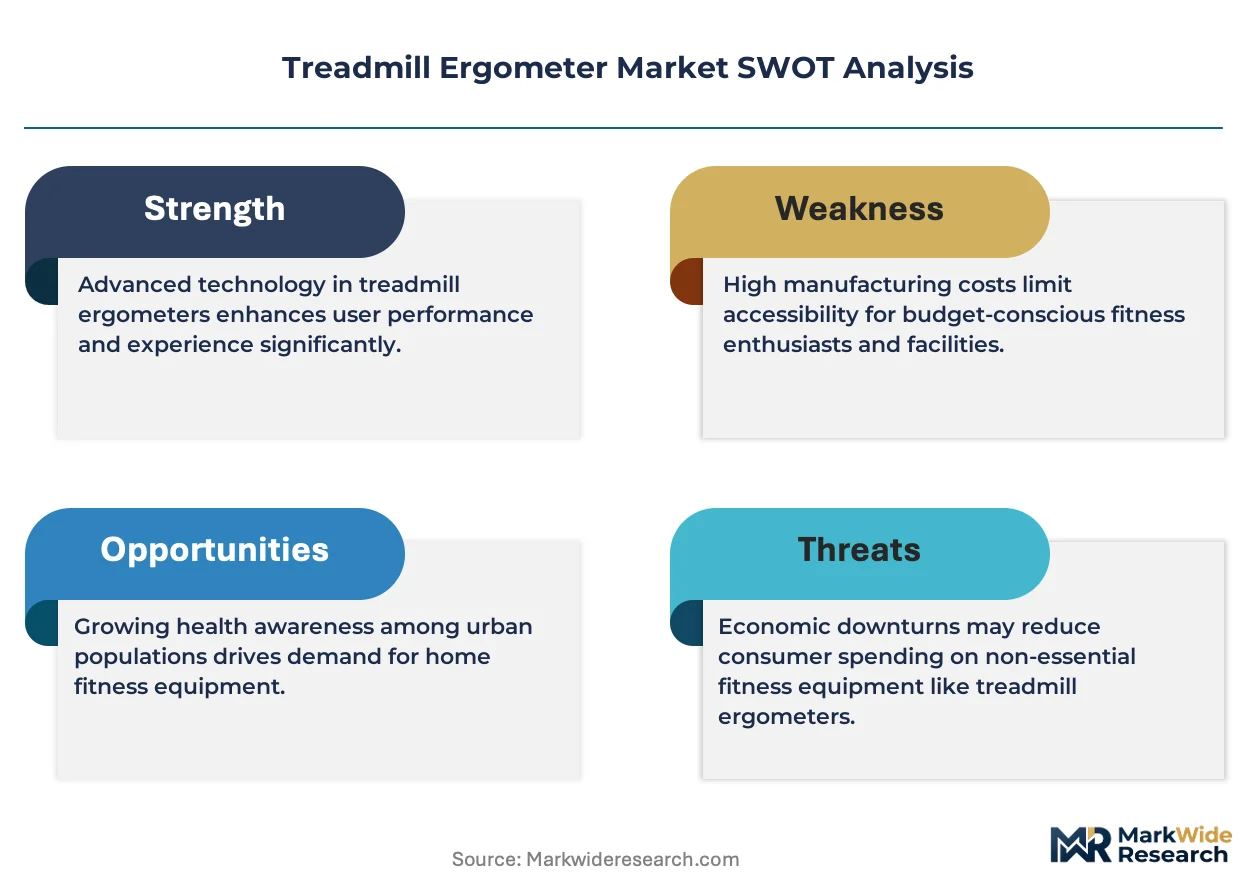
The treadmill ergometer market is experiencing structural pressure from the FDA's tightening 21 CFR 870 software validation requirements, which are elevating engineering costs and compressing margins for diagnostic-grade equipment manufacturers seeking US market access.
Growth Catalysts
- EU Medical Device Regulation (MDR):Notified body oversight for clinical measurement accuracy claims is accelerating product differentiation, pushing manufacturers toward higher-margin rehabilitation configurations.
- Precision gait-analysis systems:Rehabilitation centers in Germany are expanding procurement of instrumented platforms with integrated force plates and variable resistance systems for quantified therapeutic protocols.
- Gas-analysis port integration:Athletic performance laboratories are demanding metabolic equivalent calibration capabilities, creating pull for motorized units with electrical resistance technology.
Market Restraints
- Electromagnetic compatibility testing costs:FDA-mandated EMC validation for diagnostic exercise stress systems adds substantial fixed costs to US market entry, disadvantaging smaller manufacturers.
- Magnetic resistance component concentration:Silent-operation torque control systems rely on specialized permanent magnet supply chains concentrated in East Asian manufacturing clusters.
- ISO 20957-6 compliance burden:Stationary training equipment safety certification requires extensive third-party testing, extending product development timelines by 8-14 months.
Strategic Opportunities
- Corporate wellness programs:Boutique fitness studios and employer-sponsored health initiatives are fragmenting procurement channels beyond traditional commercial gym concentration.
- Cybersecurity standards for connected fitness:Evolving IEC 62443 frameworks for industrial automation security are creating first-mover advantages for manufacturers with embedded cryptographic hardware.
- Folding treadmill ergometers:Direct-to-consumer channel density for home users remains underdeveloped relative to institutional sales, presenting white-space for digitally native distribution models.
Industry Challenges
- Software validation talent scarcity:FDA 21 CFR Part 820 quality system compliance requires specialized regulatory affairs expertise that commands premium compensation in medical device labor markets.
- Legacy platform integration complexity:Sports institutes with installed bases of non-folding platforms face capital-intensive retrofit decisions when adopting networked diagnostic capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Treadmill Ergometer Market |
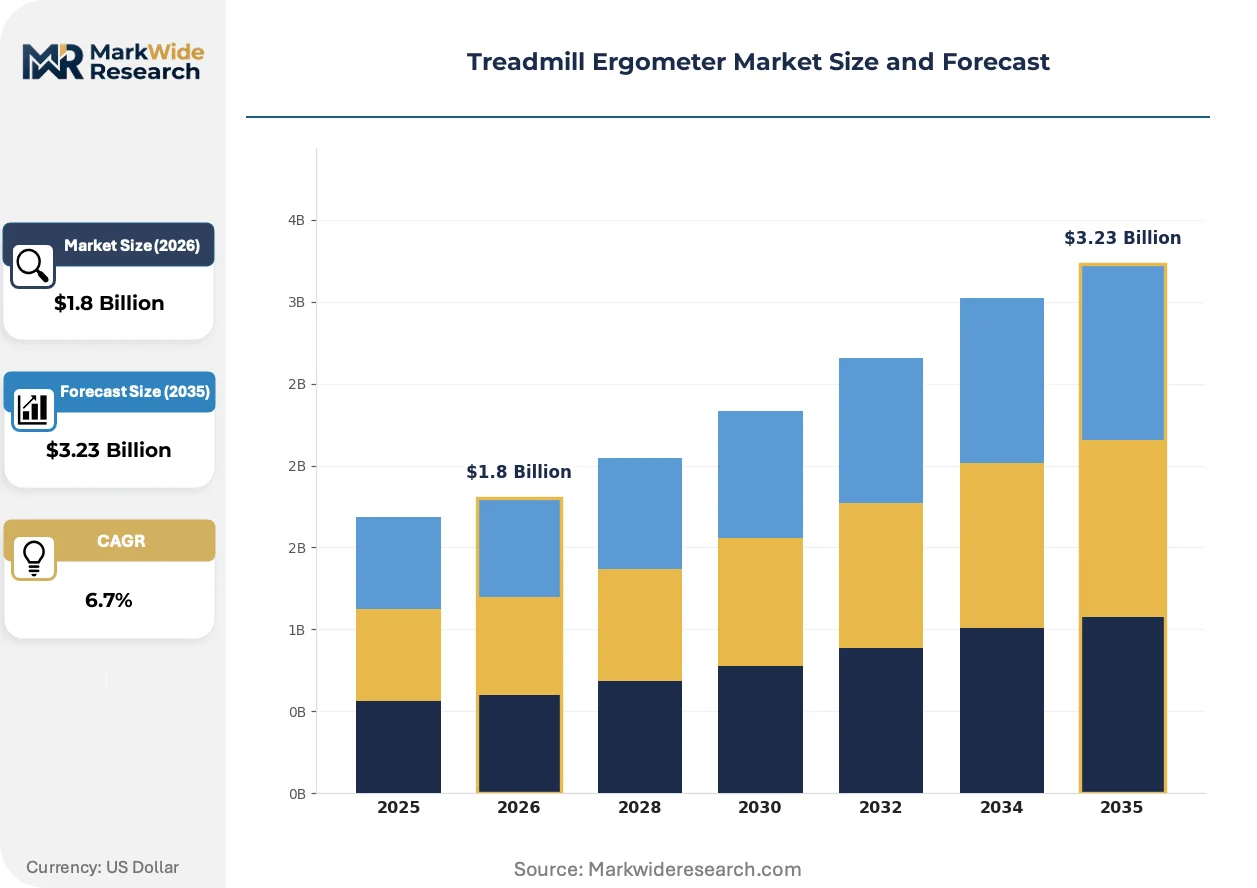
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Motorized, Folding, Non-Folding End User: Commercial Gyms, Home Users, Rehabilitation Centers, Sports Institutes Technology: Magnetic Resistance, Electrical Resistance, Air Resistance, Hydraulic Resistance Service Type: Maintenance, Repair, Installation, Warranty |
| Companies Covered | Amer Sports, Life Fitness, Technogym S.p.A, ICON Health & Fitness, Ergoline GmbH, Bodycraft, Johnson Health Tech, Cybex International, h/p/cosmos sports & medical gmbh, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Treadmill Ergometer Market Strategic Shifts
Digital instrumentation is reshaping how physiological workload measurement systems interface with clinical decision-making, compressing the gap between raw biomechanical data and actionable training prescriptions across rehabilitation and performance environments.
Force plate arrays with six-axis load cell configurations are integrating pressure distribution mapping and real-time center-of-mass tracking into treadmill decks. Rehabilitation centers in Germany are adopting these systems at accelerated pace for stroke and orthopedic recovery protocols. The technology is integrating previously separate gait-lab equipment into single-platform diagnostics, compressing capital expenditure requirements for hospital physiotherapy departments.
The EU AI Act's risk classification framework for medical device software is forcing manufacturers to document algorithmic decision pathways for metabolic equivalent calculations. This regulatory consequence is extending notified body review timelines and elevating documentation burdens. Rehabilitation settings claiming clinical measurement accuracy face the most severe compliance adjustments, with several German university hospitals demanding supplier transparency on training data provenance.
Service unbundling is disrupting traditional capital-equipment sales models in commercial fitness. Health clubs are separating hardware procurement from preventive maintenance contracts, compressing vendor margins on aftermarket revenue. This behavioral shift is most visible in Italian and Spanish markets, where facility operators are negotiating multi-year performance guarantees rather than standard warranty terms.
Treadmill Ergometer Market Segmentation
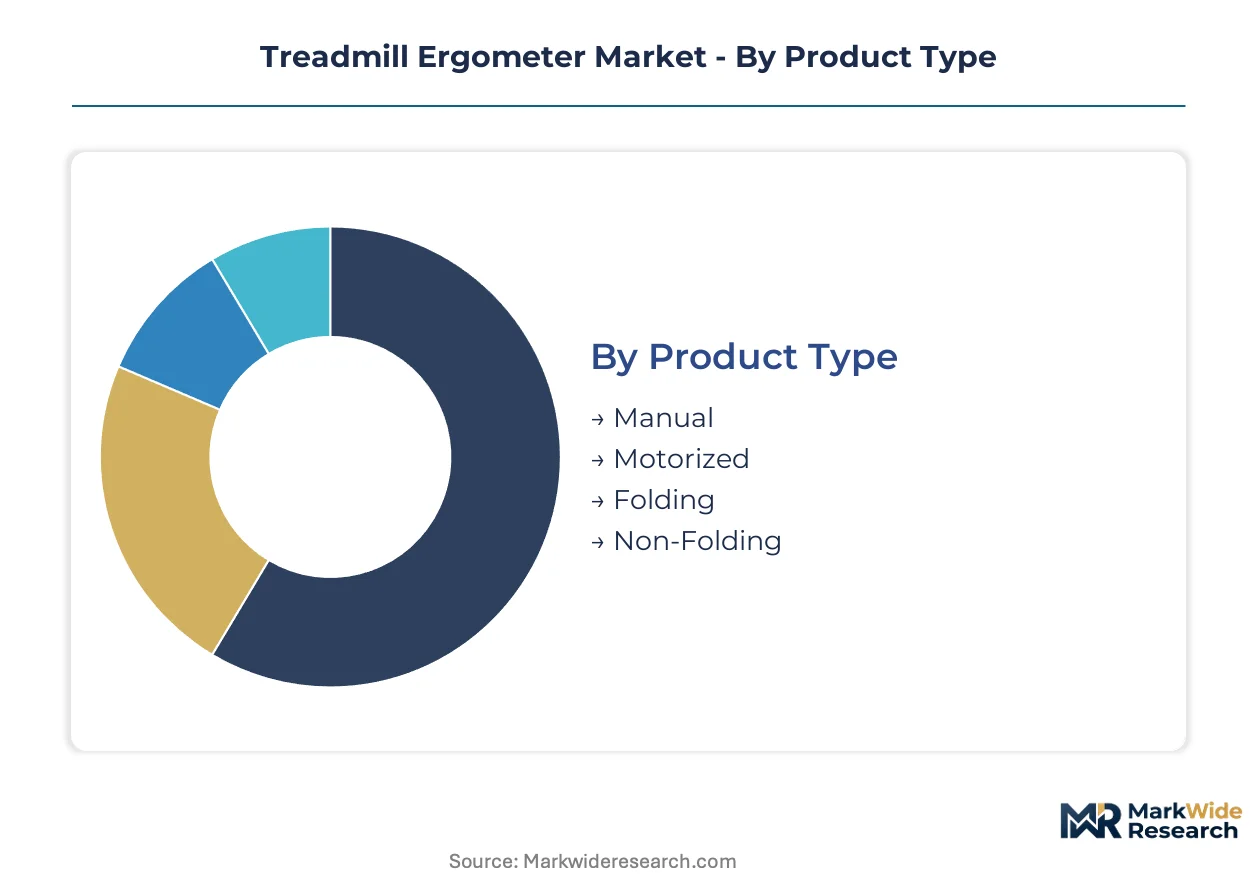
Treadmill ergometer procurement patterns diverge sharply across institutional versus consumer contexts, with clinical measurement requirements, space constraints, and resistance technology preferences fragmenting demand into distinct technical specifications and service expectations.
Product Type:
Customization intensity varies from standardized folding mechanisms to bespoke non-folding platforms engineered for specific gait-lab protocols.
- Motorized:Electrical resistance technology dominates installed base volumes through integrated force plates and gas-analysis ports calibrated to metabolic equivalents. Demand concentrates in German university hospitals pursuing clinical research partnerships with precision gait-analysis requirements.
- Non-Folding:Structural rigidity from welded steel frames supports six-axis load cell configurations and real-time center-of-mass tracking for stroke recovery protocols. Sports institutes prioritize these platforms despite capital-intensive retrofit decisions when adopting networked diagnostic capabilities.
- Manual:Belt-driven systems without motorized assistance serve cost-sensitive home users and basic conditioning environments.
- Folding:Space-saving hinge mechanisms dominate residential installations where storage constraints outweigh measurement precision needs.
Leading the category by volume: Motorized. Growing fastest: Non-Folding.
End User:
Procurement authority concentrates in institutions with clinical measurement accuracy claims versus dispersed consumer decision-making.
- Rehabilitation Centers:Instrumented platforms with variable resistance systems support quantified therapeutic protocols for orthopedic and neurological recovery. German facilities are expanding adoption of force plate arrays with pressure distribution mapping capabilities.
- Commercial Gyms:Fragmenting buyer concentration as boutique studios and corporate wellness programs multiply procurement channels beyond traditional health club networks. Italian and Spanish facility operators increasingly negotiate multi-year performance guarantees.
- Home Users:Folding designs with direct-to-consumer distribution occupy price-sensitive segments where digitally native sales models remain underdeveloped relative to institutional channels.
- Sports Institutes:Non-folding platforms with legacy installed bases face complex integration decisions when upgrading to networked diagnostic capabilities.
Highest margin concentration: Rehabilitation Centers. Steepest expansion trajectory: Corporate wellness programs within Commercial Gyms.
Technology:
Supply chain configuration for resistance systems determines acoustic profile, torque precision, and regulatory compliance burden.
- Magnetic Resistance:Permanent magnet arrays deliver silent operation and precise torque control critical for rehabilitation settings. East Asian manufacturing clusters concentrate specialized magnet supply chains, creating sourcing vulnerabilities.
- Electrical Resistance:Motorized units with programmable load profiles integrate metabolic equivalent calibration demanded by athletic performance laboratories. FDA 21 CFR 870 software validation requirements elevate engineering costs for diagnostic-grade configurations.
- Air Resistance:Fan-based systems generate resistance proportional to belt speed, serving high-intensity interval training environments with minimal electronic complexity.
- Hydraulic Resistance:Piston-based damping systems offer compact form factors for space-constrained installations with moderate precision requirements.
Widest installed base: Electrical Resistance. Gaining share fastest: Magnetic Resistance.
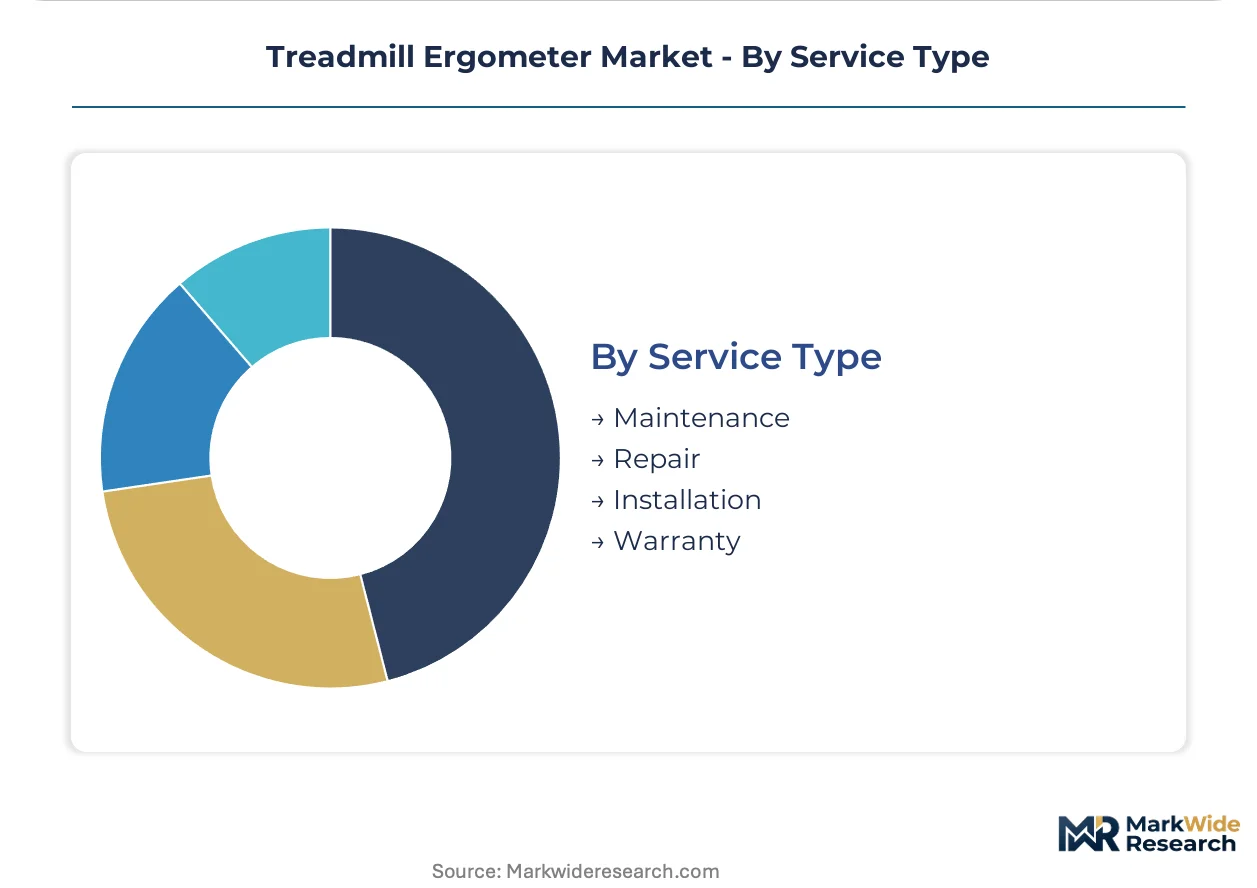
Service Type:
Revenue model unbundling is compressing traditional aftermarket margins as facility operators separate hardware procurement from ongoing support obligations.
- Maintenance:Preventive service contracts face margin pressure as health clubs negotiate multi-year performance guarantees rather than standard warranty terms. Italian and Spanish markets exhibit the most aggressive unbundling behavior.
- Installation:Precision calibration for force plate arrays and gas-analysis port alignment demands specialized technical labor, particularly for German rehabilitation centers with clinical accuracy claims.
- Repair:Component replacement for motorized drive systems and load cell arrays requires OEM-certified technicians to preserve measurement validity.
- Warranty:Standard coverage periods compress as manufacturers transfer risk through performance-based service level agreements.
Largest revenue pool: Maintenance. Most rapid structural change: Installation complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany where rehabilitation centers anchor clinical research partnerships, while the United States and Japan follow with distinct regulatory-driven procurement patterns for diagnostic-grade equipment.
United States
FDA 21 CFR 870 enforcement elevates software validation costs for diagnostic exercise stress systems, compressing margins for manufacturers seeking market entry. Electromagnetic compatibility testing requirements add substantial fixed costs that disadvantage smaller competitors. Research hospitals in Boston and Stanford clusters drive adoption of instrumented platforms with integrated gas-analysis capabilities for cardiac stress testing protocols.
Germany
University hospitals in Berlin and Munich expand procurement of precision gait-analysis systems for stroke and orthopedic recovery. EU Medical Device Regulation notified body oversight extends review timelines for clinical measurement accuracy claims. The Baden-Württemberg industrial corridor hosts h/p/cosmos sports & medical gmbh, anchoring partnerships between equipment manufacturers and rehabilitation research institutes.
Japan
METI standards for connected fitness devices accelerate cybersecurity certification requirements for networked diagnostic platforms. Aging demographics expand rehabilitation center procurement of silent-operation magnetic resistance systems for elderly gait retraining. The Kansai region around Osaka concentrates manufacturing partnerships for force plate array components used in therapeutic protocols.
Italy
Commercial gym operators in Milan and Rome negotiate unbundled service contracts separating hardware procurement from preventive maintenance. Technogym S.p.A leverages its domestic manufacturing base to dominate premium health club installations. Italian facility managers increasingly demand multi-year performance guarantees rather than standard warranty coverage, compressing vendor aftermarket margins.
China
MIIT certification for medical device software creates compliance barriers for imported diagnostic-grade equipment. Domestic rehabilitation center construction in Shanghai and Guangzhou drives demand for motorized units with electrical resistance technology. Yangtze River Delta manufacturing clusters supply permanent magnet components for magnetic resistance configurations, though specialized torque control systems remain import-dependent.
Treadmill Ergometer Market Competitive Environment
Italian producers anchor the premium commercial tier; Taiwanese and Chinese specialists hold mid-tier motorized segments through cost-optimized assembly. The vendor base fragments across three strategic tiers: European precision-engineering houses, Asian scale manufacturers, and North American direct-to-consumer distributors. Consolidation pressure operates through vertical control of magnet supply chains and captive service networks. M&A activity targets rehabilitation technology specialists, while capacity expansion concentrates in East Asian electrical component clusters.
Within the European precision tier, Technogym S.p.A and Ergoline GmbH exemplify engineering-intensive positioning for clinical and commercial installations. Johnson Health Tech and ICON Health & Fitness occupy scale-driven segments, with the former representing Asian manufacturing integration and the latter exemplifying direct-to-consumer channel density. h/p/cosmos sports & medical gmbh anchors specialized rehabilitation configurations, reflecting how German engineering heritage supports university hospital partnerships requiring gait-lab precision.
| Leading Market Players |
|---|
| Amer Sports |
| Life Fitness |
| Technogym S.p.A |
| ICON Health & Fitness |
| Ergoline GmbH |
| Bodycraft |
| Johnson Health Tech |
| Cybex International |
| h/p/cosmos sports & medical gmbh |
| Others |
Value Chain & Pricing Dynamics
Permanent magnet arrays for magnetic resistance systems anchor cost structures from East Asian mining operations through German rehabilitation center installations, with specialized torque control components commanding premium positioning against commodity electrical resistance alternatives.
Pricing Analysis
Volume concentrates in mid-tier motorized units with electrical resistance technology, while margin pools accrue to magnetic resistance configurations for clinical settings. Pricing stratifies across premium instrumented platforms with force plate arrays, standard commercial gym installations, and economy folding designs for home users. Cost compression in the premium tier stems from FDA software validation requirements elevating engineering overhead. Rehabilitation centers exhibit lowest price sensitivity due to clinical accuracy claims, while corporate wellness programs drive hardest bargain negotiations.
Supply Chain Analysis
Specialized permanent magnet supply chains rest on East Asian manufacturing clusters in China and Taiwan, with precision machining of torque control systems concentrated in Japan and Germany. Raw material dependencies span neodymium magnet alloys, six-axis load cell arrays, and gas-analysis sensor modules. Single-source vulnerability concentrates in rare-earth magnet processing capabilities. Distribution runs through medical device distributors for institutional sales and direct-to-consumer platforms for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized magnet supply constraints prop pricing power for manufacturers with captive sourcing arrangements, while FDA validation bottlenecks limit competitor entry velocity.
For Market Incumbents: Lock in exclusive supply agreements with Yangtze River Delta magnet processors before capacity constraints tighten. Deepen backward integration into force plate array manufacturing to defend margin position against Asian scale competitors. Prioritize ISO 20957-6 pre-certification investments to compress notified body review timelines for EU MDR compliance. For New Entrants and Emerging Players: EU AI Act risk classification framework in Germany opens a window for algorithmic transparency specialists to capture rehabilitation center procurement. Target corporate wellness programs within commercial gyms as the most penetrable segment with unbundled service contract offerings. Pursue digitally native distribution models for folding treadmill ergometers in underdeveloped home user channels. For Investors and Strategic Acquirers: Notified body queue extensions for clinical measurement accuracy claims are the leading indicator that rehabilitation technology specialists will command acquisition premiums. Position for five-to-ten year horizon consolidation around vertical control of magnet supply chains and captive service networks. Watch German university hospital partnership announcements as the inflection signal for platform technology viability.| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Supply Captive Integration | Backward control over neodymium processing insulates margin from East Asian export constraints. |
| FDA 21 CFR 870 Pre-Submission Pathway | Early software validation engagement compresses electromagnetic compatibility testing timelines for US entry. |
| University Hospital Research Partnership | Clinical data co-generation with German facilities accelerates EU MDR notified body approval. |
| Corporate Wellness Channel Development | Direct employer relationships bypass fragmented health club procurement concentration. |
| Cybersecurity Hardware Embedding | IEC 62443-compliant cryptographic modules create first-mover advantage in connected diagnostic platforms. |
Study Parameters
Multi-period observation of rehabilitation center procurement volumes, regulatory submission timelines, and magnet supply chain capacity anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and aftermarket service heads. Secondary validation drew from FDA 510(k) filings, EU MDR notified body databases, ISO certification registries, and customs trade data for permanent magnet imports. Bottom-up equipment shipment tracking triangulated against top-down healthcare capital expenditure surveys.
Input-output matrix framing connected resistance technology segmentation, end-user institutional categories, and regional regulatory clusters across the projection horizon. CAGRs derived from fitted growth curves on historical installation base data, adjusted for compliance burden elasticity and supply constraint scenarios. Forecast inputs incorporated rehabilitation center construction pipelines, university hospital research grant allocations, and corporate wellness program adoption curves.
Caveats apply where FDA software validation rule revisions or rare-earth export restrictions could materially shift the outlook. Forecasts embed assumptions on notified body capacity and magnet supply continuity that warrant sensitivity testing. A small set of named triggers—EU AI Act enforcement timing, East Asian magnet processor consolidation, and rehabilitation center reimbursement policy—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
BMI Machine Market
Fitness Equipment
Hydrotherapy Treadmills Market
Fitness Equipment
Global Commercial Fitness Equipment Market
Fitness Equipment
Indoor Bike Trainers Market
Fitness Equipment
Gym Ball Market
Fitness Equipment
China Outdoor Fitness Equipment Market
Fitness Equipment
Weight Training Market
Fitness Equipment
Lateral Fitness Equipment Market
Fitness Equipment
Push-Up Board Market
Fitness Equipment
PVC Stretch Yoga Mats Market
Fitness Equipment
Yoga Equipment Market
Fitness Equipment
Latin America Fitness Ring Market
Fitness Equipment
Muscle Oxygen Monitors Market
Fitness Equipment
Leg Exercise Equipment Market
Fitness Equipment
Europe Home Fitness Equipment Market
Fitness Equipment
Fitness Equipment Market