
 Yoga Accessories Market | 2026-2036
Yoga Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Yoga Accessories Market Outlook
Corporate wellness programs are repositioning the buyer base away from purely individual consumers toward institutional procurement contracts. Lululemon Athletica Inc. leverages its retail footprint and brand equity to dominate premium studio partnerships. Manduka LLC anchors its position through in-house production of natural rubber mats with closed-loop manufacturing. JadeYoga differentiates via tree-planting commitments tied to every unit sold, deepening channel control in eco-conscious segments.
Yoga accessories comprise purpose-built equipment—mats engineered to specific density measurements, blocks carved from cork or foam at standardized dimensions, straps with metal D-rings rated for tensile load, and microfiber towels with grip-optimized weave patterns—designed to stabilize alignment, extend range of motion, and maintain hygiene during asana practice. Mats fabricated from natural rubber command margin concentration due to biodegradability premiums and odor-resistance performance, while TPE formulations gain volume in price-sensitive studio bulk orders. Distribution through specialty stores sustains higher attachment rates for blocks and straps, whereas online retail captures replacement-cycle purchases for worn mats.
California's Proposition 65 chemical warning requirements and the EU REACH framework restrict phthalate and heavy-metal content in PVC-based products, compelling reformulation across supply chains. The US Consumer Product Safety Commission monitors flammability standards for foam accessories, while ISO 9001 certification increasingly gates B2B contracts with multinational fitness chains. Stakeholders must track evolving bioplastic certifications and regional extended-producer-responsibility mandates to secure long-term material sourcing.
Market Dynamics
Corporate wellness mandates are converting individual yoga practitioners into institutional procurement accounts, compressing sales cycles while demanding ISO 9001 certification and volume pricing structures that favor manufacturers with captive natural rubber supply chains.
Growth Catalysts
- REACH Regulation Compliance:EU ECHA enforcement of phthalate restrictions in PVC-based mats is accelerating reformulation toward TPE and natural rubber alternatives, opening premium positioning for biodegradable material suppliers.
- Bioplastic Certification Standards:Emerging third-party biodegradability protocols are creating definitional moats around closed-loop manufacturing claims, rewarding early adopters with B2B contract eligibility.
- Metropolitan Wellness Corridors:Dense urban clusters in the United States concentrate studio openings and corporate headquarters, generating localized demand spikes for studio-grade equipment bundles.
Market Restraints
- Natural Rubber Price Volatility:Hevea brasiliensis harvest sensitivity to monsoon patterns in Southeast Asian growing regions creates input cost instability for biodegradable mat producers.
- California Proposition 65 Liability:Chemical warning requirements for heavy-metal content impose litigation exposure and labeling costs that disproportionately burden small-batch domestic manufacturers.
- Foam Block Substitution:Cork harvesting from Quercus suber in Portugal and Spain faces multi-decade tree maturation cycles, limiting supply elasticity against surging studio demand.
Strategic Opportunities
- Extended Producer Responsibility Mandates:EU member state implementation of mat take-back programs creates first-mover advantage for brands with established recycling infrastructure and material traceability systems.
- Corporate Wellness Procurement:Fortune 500 on-site fitness facility buildouts represent underpenetrated B2B accounts with multi-year equipment replacement schedules and standardized vendor qualification requirements.
- Smart Textile Integration:Pressure-sensing weave technologies from athletic performance apparel are converging with microfiber towel production, enabling real-time alignment feedback accessories for premium consumer segments.
Industry Challenges
- ISO 9001 Certification Timeline:Multinational fitness chains now gate vendor approval on quality management system documentation, requiring 12-18 month implementation periods that delay contract eligibility for mid-tier manufacturers.
- Closed-Loop Manufacturing Capex:In-house natural rubber processing and solvent recovery systems demand seven-figure capital deployment, concentrating production scale among well-capitalized incumbents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yoga Accessories Market |
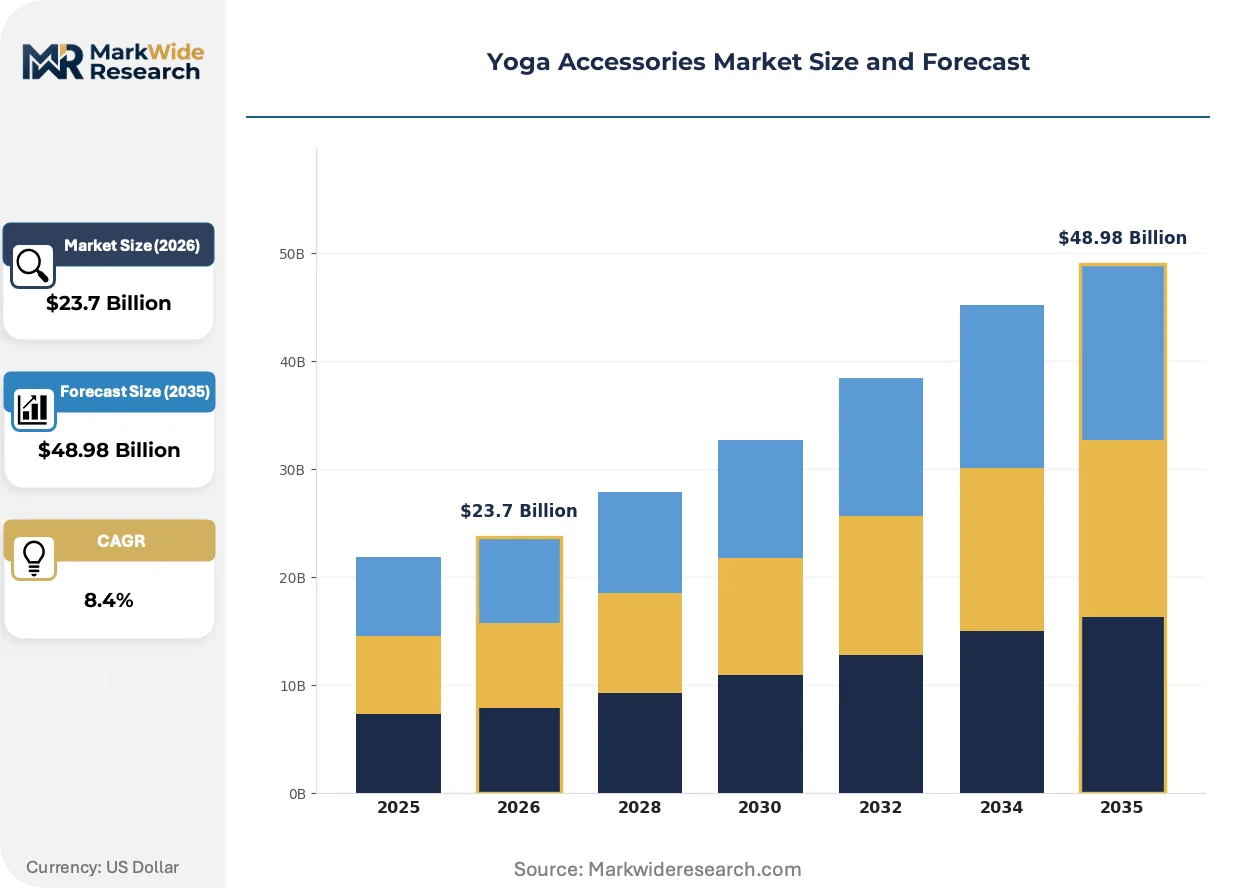
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yoga Mats, Blocks, Straps, Towels Material: Natural Rubber, PVC, TPE, Cotton End User: Individuals, Studios, Fitness Centers, Corporate Wellness Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Hugger Mugger Yoga Products, Decathlon SA, Lululemon Athletica Inc., Barefoot Yoga Co., Liforme Ltd, Manduka LLC, JadeYoga, prAna Living LLC, Adidas AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yoga Accessories Market Strategic Shifts
Material science breakthroughs and procurement digitization are restructuring how yoga accessories reach end users, compressing traditional channel hierarchies while elevating performance specifications as primary purchase determinants.
Thermoplastic elastomer (TPE) formulations are expanding into studio bulk procurement segments previously dominated by PVC, offering closed-cell density without off-gassing concerns. National fitness chains in the United States are specifying TPE for new location fit-outs, accepting 15-20% unit cost premiums to preempt Proposition 65 disclosure requirements and simplify vendor compliance documentation. This material migration is expanding into direct-to-consumer replacement cycles as odor-sensitive practitioners seek alternatives to synthetic rubber off-gassing.
EU REACH Annex XVII restrictions on phthalate plasticizers are forcing reformulation across Asian contract manufacturers supplying European distributors. The industrial consequence is a supply chain bifurcation: REACH-compliant production lines command 8-12 week lead time premiums, while non-compliant inventory diverts to Middle Eastern and African markets with less stringent chemical disclosure frameworks. German and French distributors are responding by consolidating supplier relationships with vertically integrated manufacturers possessing in-house polymer compounding capabilities.
Corporate wellness departments are consolidating individual reimbursement programs into centralized procurement portals managed by facilities teams. This behavioral shift displaces traditional specialty retail discovery with RFP-driven vendor selection, prioritizing volume pricing, customization branding, and consolidated invoicing over in-store tactile evaluation. The transformation is most visible in the United States, where technology sector headquarters in Austin, Seattle, and San Francisco have established preferred vendor lists with 24-36 month contract terms.
Yoga Accessories Market Segmentation
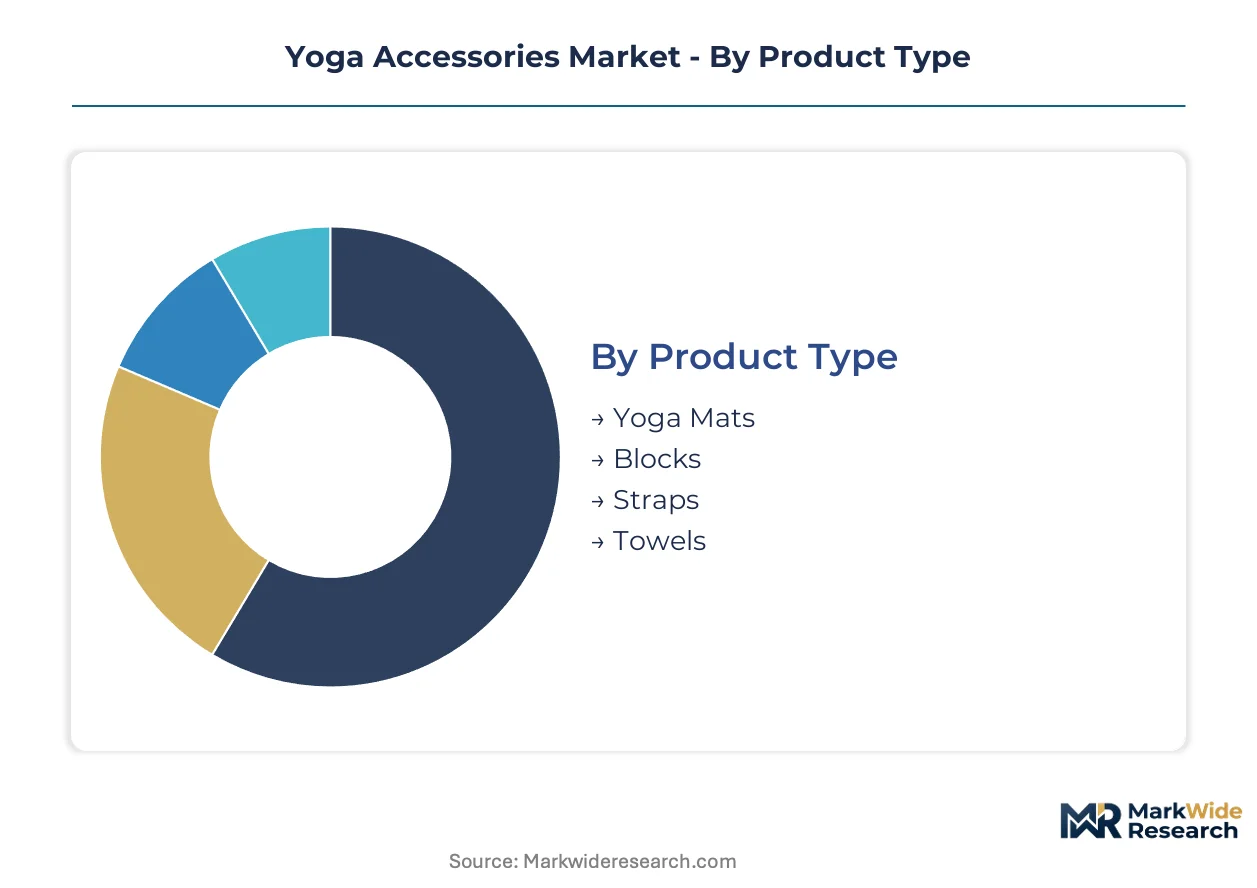
Segmentation in yoga accessories reveals how procurement patterns diverge between institutional buyers and individual practitioners. Material composition and distribution channel selection directly determine margin capture and contract eligibility across buyer types.
Product Type:
Customization intensity varies sharply across this category, with some products demanding precise density specifications while others tolerate commoditized production.
- Yoga Mats:Engineered to specific density measurements with closed-cell or open-cell construction determining grip performance and moisture absorption. Demand concentrates in corporate wellness procurement bundles across United States metropolitan corridors, where ISO 9001 certification gates vendor approval. Natural rubber formulations command premium positioning due to REACH compliance advantages.
- Blocks:Carved from cork or foam at standardized dimensions to stabilize alignment during asana practice. Studio bulk orders in dense urban clusters favor cork for biodegradability credentials, though foam maintains volume share in price-sensitive fitness center fit-outs.
- Straps:Cotton or synthetic webbing with metal D-rings rated for tensile load, extending range of motion in seated and standing poses.
- Towels:Microfiber construction with grip-optimized weave patterns for hot yoga hygiene maintenance.
Most installed capacity flows through Yoga Mats. Expansion is steepest in Blocks as studio openings accelerate cork adoption.
Material:
Cost tier stratification in this category aligns with regulatory compliance burden and biodegradability certification availability.
- Natural Rubber:Harvested from Hevea brasiliensis with closed-loop manufacturing enabling solvent recovery and odor-resistance performance. Southeast Asian supply chains face monsoon-driven price volatility, compressing margins for producers without captive plantation access.
- PVC:Phthalate-plasticized formulations facing REACH Annex XVII restrictions and California Proposition 65 disclosure requirements. Reformulation costs are diverting production to Middle Eastern and African markets with less stringent chemical frameworks.
- TPE:Thermoplastic elastomer alternatives gaining studio procurement share through closed-cell density without off-gassing concerns.
- Cotton:Organic certification pathways creating definitional moats in eco-conscious consumer segments.
Volume leadership sits with PVC. The steepest climb belongs to TPE as national fitness chains specify REACH-compliant alternatives.
End User:
Customer type in this category determines contract structure, with institutional accounts consolidating previously fragmented individual purchases.
- Individuals:Replacement-cycle purchases driven by mat wear and odor sensitivity, increasingly migrating from specialty retail discovery to online convenience.
- Studios:Bundle procurement of mats, blocks, and straps with customization branding requirements and 24-36 month replacement schedules.
- Fitness Centers:Volume pricing negotiations prioritizing TPE formulations to preempt regulatory exposure.
- Corporate Wellness:Fortune 500 facilities teams managing centralized procurement portals with consolidated invoicing and vendor qualification documentation.
Transaction volume concentrates in Individuals. Corporate Wellness is gaining share fastest as technology sector headquarters expand on-site fitness buildouts.
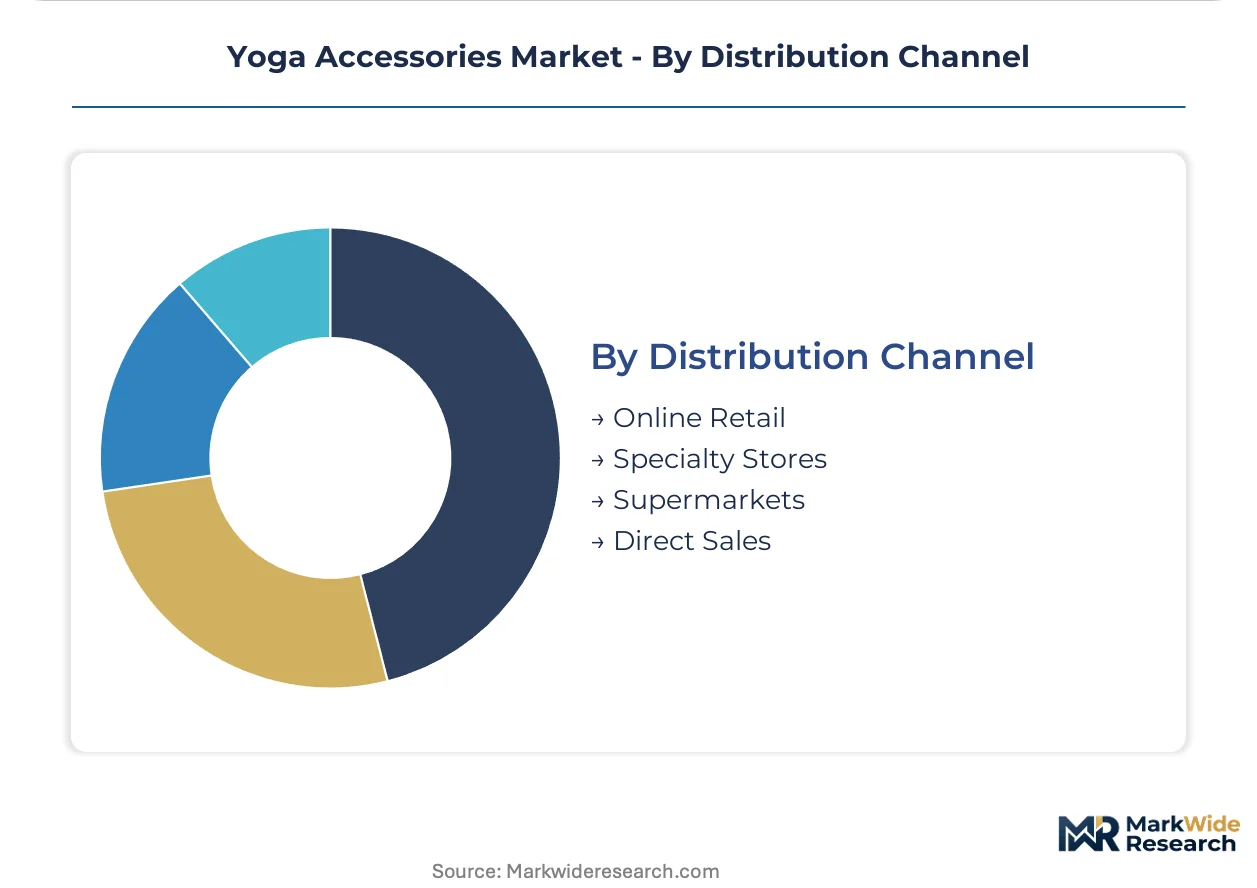
Distribution Channel:
Supply concentration in this category reflects the tension between tactile evaluation needs and procurement digitization efficiency.
- Online Retail:Captures replacement-cycle mat purchases with subscription models emerging for consumable accessories.
- Specialty Stores:Sustain higher attachment rates for blocks and straps through in-person instruction and community programming.
- Supermarkets:Entry-level price points for occasional practitioners with limited SKU depth.
- Direct Sales:B2B contracts with multinational fitness chains and corporate wellness departments bypassing traditional retail markup.
Most unit volume moves through Online Retail. Direct Sales is climbing fastest as institutional procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan wellness corridors in the United States concentrate studio-grade equipment demand, while regulatory divergence across jurisdictions reshapes material sourcing and distribution strategies for yoga accessories manufacturers.
United States
Corporate headquarters in Austin, Seattle, and San Francisco drive institutional procurement through centralized wellness portals. California's Proposition 65 imposes chemical warning requirements for heavy-metal content in PVC-based mats. New York and Los Angeles studio clusters favor cork blocks from Portuguese suppliers despite longer lead times.
Germany
REACH Annex XVII enforcement by ECHA accelerates reformulation toward TPE and natural rubber alternatives among distributors. Berlin and Munich wellness studio openings generate localized demand for ISO 9001-certified equipment bundles. Frankfurt-based fitness chains consolidate vendor relationships with vertically integrated manufacturers.
China
Domestic yoga participation expands in Shanghai and Beijing, though export-oriented production dominates Hebei and Zhejiang manufacturing zones. GB standards for consumer product safety govern domestic sales, while REACH compliance diverts non-compliant inventory to Middle Eastern markets. Yangtze River Delta factories invest in closed-loop solvent recovery systems.
United Kingdom
London's premium studio segment imports natural rubber mats from Southeast Asian suppliers, absorbing currency-driven cost volatility. The UKCA marking transition post-Brexit creates documentation friction for EU-sourced accessories. Manchester and Birmingham corporate wellness programs adopt centralized procurement models mirroring US technology sector practices.
India
Bangalore and Mumbai studio openings drive demand for price-sensitive TPE formulations over natural rubber. The Bureau of Indian Standards (BIS) certification requirements for imported fitness equipment create entry barriers for unbranded Chinese suppliers. Domestic cotton strap production concentrates in Tamil Nadu textile clusters.
Yoga Accessories Market Competitive Environment
Strategic partnerships dominate the current landscape as manufacturers seek REACH-compliant material sourcing and corporate wellness contract eligibility. The vendor base separates into three tiers: premium brands with retail footprint dominance, mid-tier specialists in biodegradable materials, and contract manufacturers serving private-label distributors. Two strategic archetypes have emerged—vertically integrated natural rubber processors and digitally native direct-to-consumer brands. Competitive intensity centers on ISO 9001 certification acquisition and closed-loop manufacturing infrastructure deployment.
Within the premium brand archetype, Lululemon Athletica Inc. and Manduka LLC occupy positions defined by studio partnership depth and material traceability systems. JadeYoga exemplifies the sustainability-focused specialist tier through its tree-planting commitment structure. Among European mass-market distributors, Decathlon SA leverages scale advantages in TPE sourcing. These three company types—premium incumbent, biodegradable specialist, and mass-market retailer—collectively represent the competitive vectors reshaping procurement relationships with corporate wellness departments and multinational fitness chains.
| Leading Market Players |
|---|
| Hugger Mugger Yoga Products |
| Decathlon SA |
| Lululemon Athletica Inc. |
| Barefoot Yoga Co. |
| Liforme Ltd |
| Manduka LLC |
| JadeYoga |
| prAna Living LLC |
| Adidas AG |
| Others |
Value Chain & Pricing Dynamics
Captive natural rubber processing in Southeast Asian plantation networks anchors both supply security and premium-tier pricing power for biodegradable mat producers, insulating them from commodity volatility that erodes margins among PVC-dependent contract manufacturers serving price-sensitive studio bulk orders.
Pricing Analysis
Input-cost pass-through from Hevea brasiliensis harvest volatility in Thailand and Indonesia flows directly to natural rubber mat pricing, with monsoon-driven supply squeezes compressing margins for producers lacking upstream plantation control. Three-tier pricing structure across premium, standard, and economy levels separates ISO 9001-certified studio bundles from direct-to-consumer replacement cycles and entry-level supermarket SKUs. Pricing pressure stems from TPE formulation competition in national fitness chain procurement, where REACH compliance premiums face resistance from facilities managers optimizing capital expenditure budgets. Corporate wellness departments exhibit lowest price sensitivity due to consolidated vendor qualification requirements, while individual practitioners migrating online demonstrate highest elasticity to unit cost differentials.
Supply Chain Analysis
Direct-to-fitness-chain channels handle hyperscale institutional demand through centralized procurement portals, displacing traditional distributor markups with volume-negotiated contracts and consolidated invoicing structures. Manufacturing concentrates in China, Vietnam, and Thailand, with Hebei and Zhejiang provinces hosting PVC and TPE compounding capacity while Thai and Indonesian facilities control natural rubber sheet production. Raw material dependencies center on petroleum-derived polymer feedstocks, cork bark from Portuguese Quercus suber stands, and cotton webbing from Tamil Nadu textile clusters. Single-source vulnerability runs through Southeast Asian latex processing infrastructure concentrated in monsoon-exposed regions. Distribution runs through hybrid models blending direct B2B contracting for Fortune 500 wellness programs with online retail capture of individual replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion trajectories favor producers commanding certification premiums and captive material sourcing, as input cost volatility and regulatory compliance burdens concentrate margin capture among integrated incumbents while fragmenting price-taker competitors.
For Market Incumbents: Lock in studio partnership exclusivity through multi-year equipment replacement schedules bundled with ISO 9001 certification documentation, preempting TPE-based challengers from penetrating corporate wellness vendor lists. Deepen backward integration into Hevea brasiliensis plantation networks or solvent recovery systems to insulate margin structures from natural rubber price volatility and REACH reformulation costs.
For New Entrants and Emerging Players: The premium-economy price-point gap in cork block procurement creates white-space opportunity for Portuguese-sourced alternatives positioned between mass-market foam and boutique studio grades. Target underpenetrated metropolitan wellness corridors in Austin and Seattle with direct-to-studio sales models bypassing distributor markups, leveraging customization branding as the primary go-to-market wedge against established retail footprints.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier biodegradable specialists because ISO 9001 certification timelines and closed-loop manufacturing capex requirements create structural barriers that prevent organic scaling by sub-scale competitors. Acquisition target archetypes include TPE compounders with existing REACH-compliant production lines and regional distributors consolidating fragmented studio relationships. Watch corporate wellness procurement portal adoption rates as the inflection signal indicating acceleration in institutional contract consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 9001 Certification Investment | Unlocks B2B eligibility with multinational fitness chains and Fortune 500 wellness departments. |
| Backward Integration into Natural Rubber | Captures margin compression from Southeast Asian harvest volatility and REACH compliance premiums. |
| Corporate Wellness Portal Integration | Positions suppliers for centralized procurement consolidation displacing specialty retail discovery. |
| TPE Formulation Scale-Up | Captures studio bulk orders migrating from PVC due to Proposition 65 and REACH Annex XVII exposure. |
| Extended Producer Responsibility Infrastructure | Creates first-mover advantage as EU member states implement mat take-back program mandates. |
Study Parameters
Multiple input streams — executive interviews with yoga studio owners and corporate facilities managers, trade data from customs records and specialty retail audit databases, and regulatory filings with ECHA and California OEHHA — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement decision-making across institutional and individual buyer archetypes, while secondary validation drew from SEC 10-K disclosures of listed fitness equipment distributors, ISO certification registries, and biodegradability certification databases maintained by third-party standards bodies.
Historical volume trajectories were cross-referenced against panel-derived growth assumptions across the projection horizon, with segmentation modeling incorporating product type, material composition, end-user category, and distribution channel dimensions. CAGRs were derived from curve-fitting approaches applied to replacement cycle frequencies, studio opening rates in metropolitan wellness corridors, and corporate wellness program adoption patterns. Industry-specific forecast inputs included natural rubber futures price volatility indices and REACH enforcement trend data from ECHA regulatory bulletins.
Caveats apply where ECHA enforcement intensity, monsoon disruption severity in Southeast Asia, or corporate wellness budget freezes could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Pilates Reformer Market
Fitness Equipment
Pilates Equipment Market
Fitness Equipment
Fitness Ball Market
Fitness Equipment
Weight Training Benches Market
Fitness Equipment
Exercise Band Market
Fitness Equipment
GCC Fitness Ring Market
Fitness Equipment
Weight Training Market
Fitness Equipment
Europe Fitness Rings Market
Fitness Equipment
Belt Trainers Market
Fitness Equipment
Asia-Pacific Fitness Rings Market
Fitness Equipment
Fitness Rings Market
Fitness Equipment
Yoga and Pilates Mats Market
Fitness Equipment
Global Commercial Fitness Equipment Market
Fitness Equipment
Gym Ball Market
Fitness Equipment
Leg Exercise Equipment Market
Fitness Equipment
Gym Fitness Accessories Market