
 Middle East and Africa Fitness Equipment Market | 2026-2036
Middle East and Africa Fitness Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Fitness Equipment Market Foresight
South Africa's manufacturing base for steel-frame cardio equipment is tilting toward export readiness. Technogym S.P.A leverages its Italian engineering heritage to dominate premium commercial installations across Gulf states. Johnson Health Tech Co. Ltd anchors its regional position through cost-competitive treadmill assembly serving mid-market gym chains. Icon Health & Fitness Inc competes via direct-to-home digital channels targeting remote fitness users in Nigeria and Kenya.
Middle East and Africa fitness equipment encompasses motorized and non-motorized apparatus designed for cardiovascular conditioning, resistance training, and physical rehabilitation, typically constructed from powder-coated steel frames, polyurethane cushioning systems, and brushless DC motors rated for continuous duty cycles. Treadmills and exercise bikes occupy the largest product volume pools due to universal gym adoption, while smart equipment integrating biometric sensors commands premium pricing from corporate fitness buyers. Manual equipment sustains dominant share among price-sensitive home users and rehabilitation centers where capital constraints limit technology deployment.
Saudi Arabia's Quality of Life Program and the UAE's national fitness certification standards shape product compliance requirements for imported equipment. South Africa's National Regulator for Compulsory Specifications enforces safety standards on motorized fitness machines, creating market access barriers for uncertified suppliers. Stakeholders must monitor how Gulf state localization incentives reshape procurement rules for government-funded sports infrastructure.
Market Dynamics
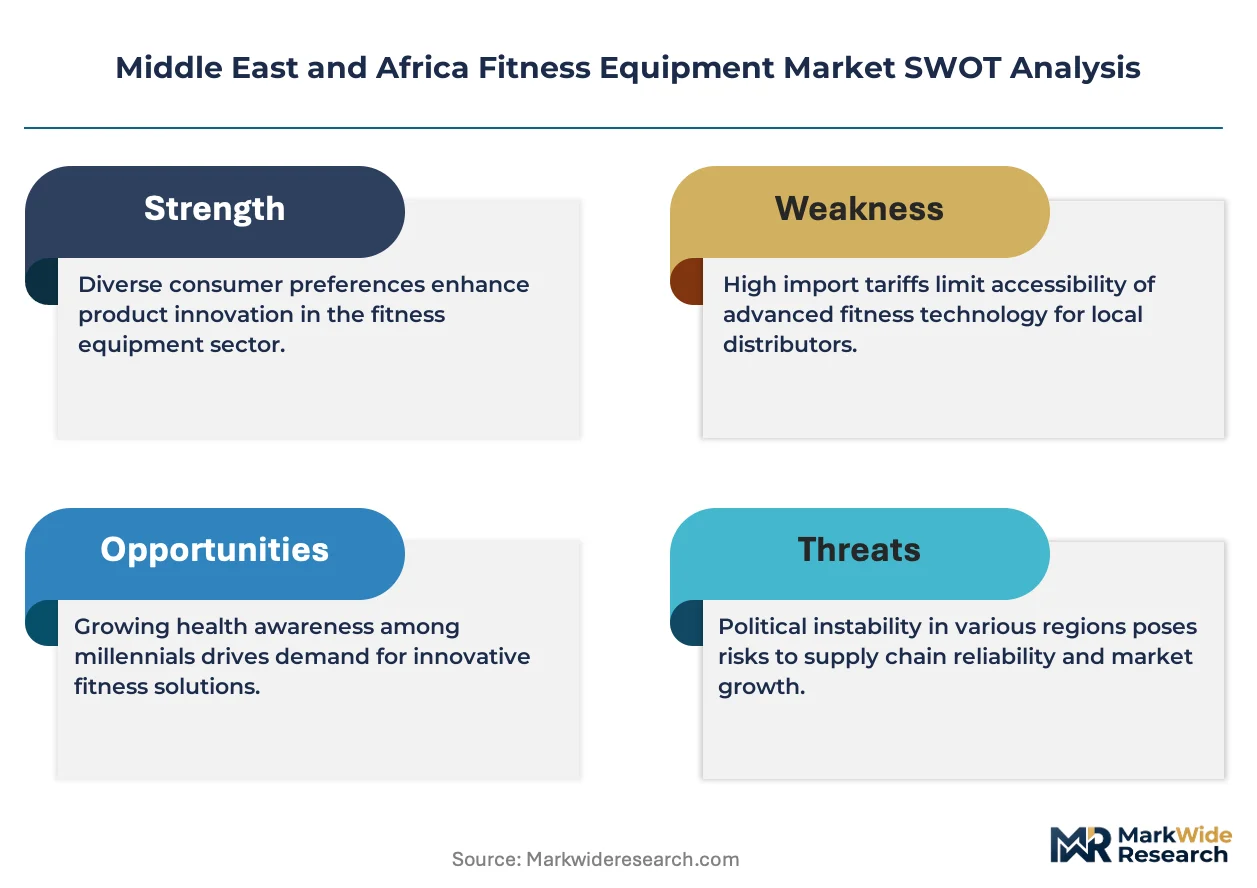
Saudi Arabia's Quality of Life Program mandates are compressing procurement timelines for commercial fitness infrastructure, forcing suppliers to accelerate certification workflows and localize assembly capacity to meet government-funded installation deadlines.
Growth Catalysts
- Quality of Life Program mandates:Saudi government regulations require fitness facilities in all new residential developments, creating guaranteed demand pools for cardio and strength equipment across Riyadh and Jeddah.
- Smart equipment integration:Biometric sensor systems embedded in treadmills and bikes enable usage tracking for corporate wellness contracts, differentiating premium suppliers serving Dubai's commercial gym chains.
- South Africa's health consciousness pivot:Private hospital groups are expanding rehabilitation centers, driving orders for manual resistance equipment and motorized treadmills with medical-grade safety certifications.
Market Restraints
- Steel and aluminum input volatility:Powder-coated frame manufacturers face margin compression when commodity prices spike, particularly affecting mid-market treadmill producers serving Nigerian gym chains.
- Brushless DC motor supply concentration:Continuous-duty motor sourcing clusters in East Asian production hubs, exposing regional assemblers to shipping disruptions and extended lead times.
- MOHAP certification friction:UAE medical device classification for rehabilitation equipment creates documentation burdens that delay market entry for European suppliers lacking prior Gulf regulatory experience.
Strategic Opportunities
- Kenya's underpenetrated home fitness segment:Rising middle-class disposable income in Nairobi creates first-mover potential for compact non-motorized equipment distributed through mobile commerce channels.
- Corporate wellness mandate expansion:Saudi labor regulations incentivizing employee health programs generate demand for on-site gym installations at industrial facilities and government offices.
- AI-powered form correction convergence:Computer vision algorithms paired with resistance equipment enable remote personal training subscriptions, opening software-recurring revenue streams for hardware suppliers.
Industry Challenges
- Biomedical engineer talent scarcity:Rehabilitation equipment calibration and maintenance requires specialized technicians, with training programs lagging equipment deployment rates in Egypt and Morocco.
- Multi-jurisdiction certification complexity:Suppliers must navigate parallel approval processes through South Africa's National Regulator for Compulsory Specifications and Gulf state standardization bodies, extending product launch timelines.
- Legacy equipment integration friction:Smart-enabled machines face interoperability barriers with existing gym management software platforms, complicating retrofit sales to established fitness chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Fitness Equipment Market |
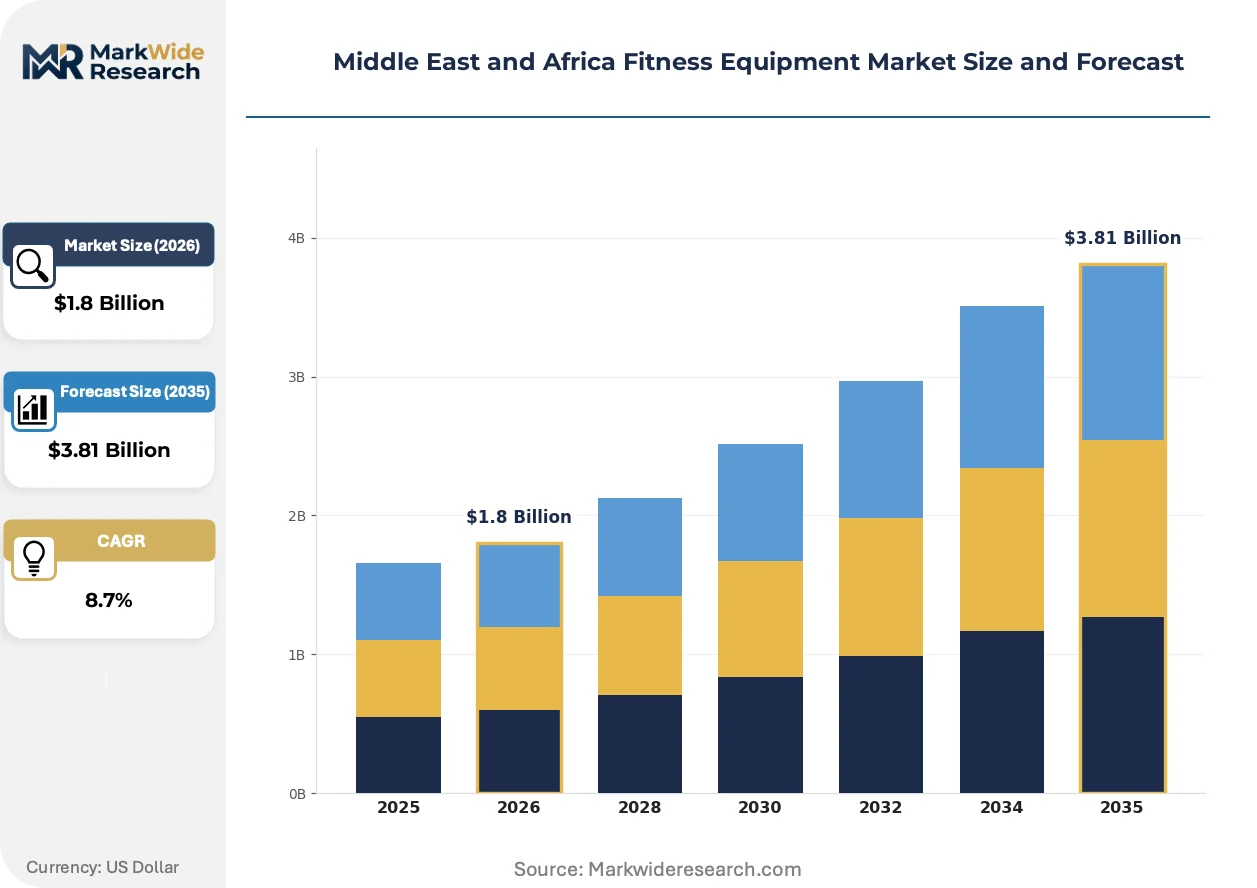
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Treadmills, Exercise Bikes, Weight Machines, Ellipticals End User: Gyms, Home Users, Rehabilitation Centers, Corporate Fitness Technology: Smart Equipment, Manual Equipment, Wearable Devices, Fitness Apps Distribution Channel: Online Retail, Offline Stores, Distributors, Direct Sales |
| Companies Covered | Icon Health & Fitness Inc, SportsArt Fitness, Inc., Technogym S.P.A, Dubai Sports LLC, Core Health & Fitness LLC, Life Fitness, Precor Incorporated, Acme Fitness, Johnson Health Tech Co. Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Fitness Equipment Market Shifts & Advancements
Connected fitness ecosystems are collapsing the traditional boundary between hardware sales and ongoing service revenue, embedding subscription mechanics into equipment procurement decisions across commercial and home segments.
Brushless DC motor efficiency gains are collapsing energy consumption benchmarks for continuous-duty treadmills, enabling 24-hour gym operators in Dubai and Riyadh to reduce utility overhead while maintaining peak-hour machine availability. Commercial buyers are specifying these motors in procurement contracts, compressing demand for older induction motor designs. The shift is forcing component suppliers to retool production lines or exit the regional supply base entirely.
Saudi Arabia's Quality of Life Program regulations are mandating fitness infrastructure quotas in new real estate developments, compelling property developers to pre-install gym equipment before occupancy permits issue. Equipment suppliers must secure SFDA conformity assessments and localize assembly to qualify for government-linked procurement pools. The policy is accelerating demand for standardized product configurations that simplify bulk purchasing decisions.
Corporate wellness buyers are unbundling after-sales service from equipment purchase contracts, negotiating separate maintenance agreements with third-party technical service providers. This procurement pattern disrupts traditional supplier-captive service revenue models, particularly affecting European manufacturers serving UAE premium gym chains. The behavior is most visible in Dubai, where facility management companies are consolidating multi-brand maintenance contracts to reduce vendor complexity.
Middle East and Africa Fitness Equipment Market Segmentation
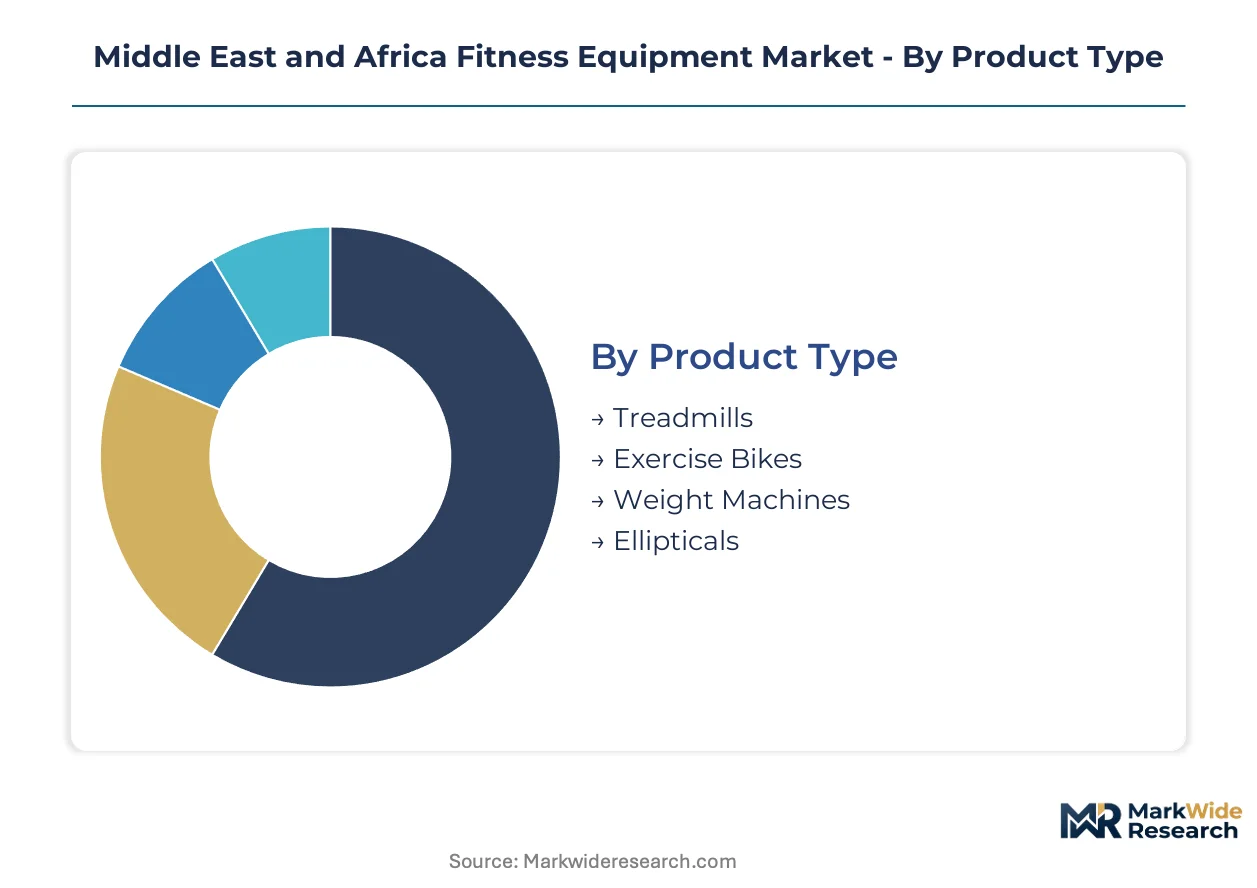
Segmentation in the Middle East and Africa fitness equipment market reveals how procurement patterns diverge between Gulf state commercial installations and African home-use adoption. Understanding these splits enables suppliers to align certification investments and distribution strategies with actual demand concentration.
Product Type:
Mature motorized categories dominate commercial procurement while emerging manual alternatives sustain price-sensitive segments.
- Treadmills:Continuous-duty brushless DC motors power these units, with powder-coated steel frames rated for 24-hour gym operation. Dubai's premium fitness chains specify energy-efficient models to reduce utility overhead during peak summer cooling loads.
- Exercise Bikes:Upright and recumbent configurations utilize polyurethane cushioning systems and magnetic resistance mechanisms. Saudi Arabia's Quality of Life Program mandates are compressing procurement timelines for residential development installations across Riyadh and Jeddah.
- Weight Machines:Plate-loaded and selectorized systems serve strength training floors in South African commercial gyms.
- Ellipticals:Low-impact cardio units with articulated foot pedals address rehabilitation center demand in private hospital groups.
Treadmills handle the majority of throughput; exercise bikes are expanding most quickly on share.
End User:
Customer type determines specification intensity, with institutional buyers demanding biometric integration absent from residential purchases.
- Gyms:Commercial facilities specify smart-enabled equipment with usage tracking and preventive maintenance alerts. UAE facility management companies are consolidating multi-brand maintenance contracts to reduce vendor complexity.
- Home Users:Compact non-motorized equipment dominates price-sensitive segments in Nigeria and Kenya. Nairobi's rising middle-class disposable income creates first-mover potential for mobile commerce distribution of folding treadmills and resistance bands.
- Rehabilitation Centers:Medical-grade safety certifications from South Africa's National Regulator for Compulsory Specifications govern motorized treadmill procurement for private hospital groups.
- Corporate Fitness:On-site installations at Saudi industrial facilities and government offices respond to labor regulation incentives for employee health programs.
Gyms command the largest equipment volume; corporate fitness is climbing the fastest as Saudi mandates expand.
Technology:
Hardware-software integration intensity separates premium commercial offerings from basic residential units.
- Smart Equipment:Biometric sensor systems embedded in cardio machines enable real-time performance tracking and remote diagnostics. Dubai's corporate wellness contracts specify these capabilities for usage-based billing models.
- Manual Equipment:Non-motorized resistance apparatus with mechanical adjustment systems serves capital-constrained rehabilitation centers and home users. Egyptian and Moroccan facilities face biomedical engineer talent scarcity for calibration and maintenance.
- Wearable Devices:Heart rate monitors and activity trackers complement gym equipment ecosystems in South African health consciousness pivots.
- Fitness Apps:Subscription-based training platforms pair with hardware for remote personal training revenue streams.
Smart equipment captures premium pricing; manual equipment sustains dominant volume share.
Distribution Channel:
Channel selection reflects buyer sophistication and installation complexity requirements.
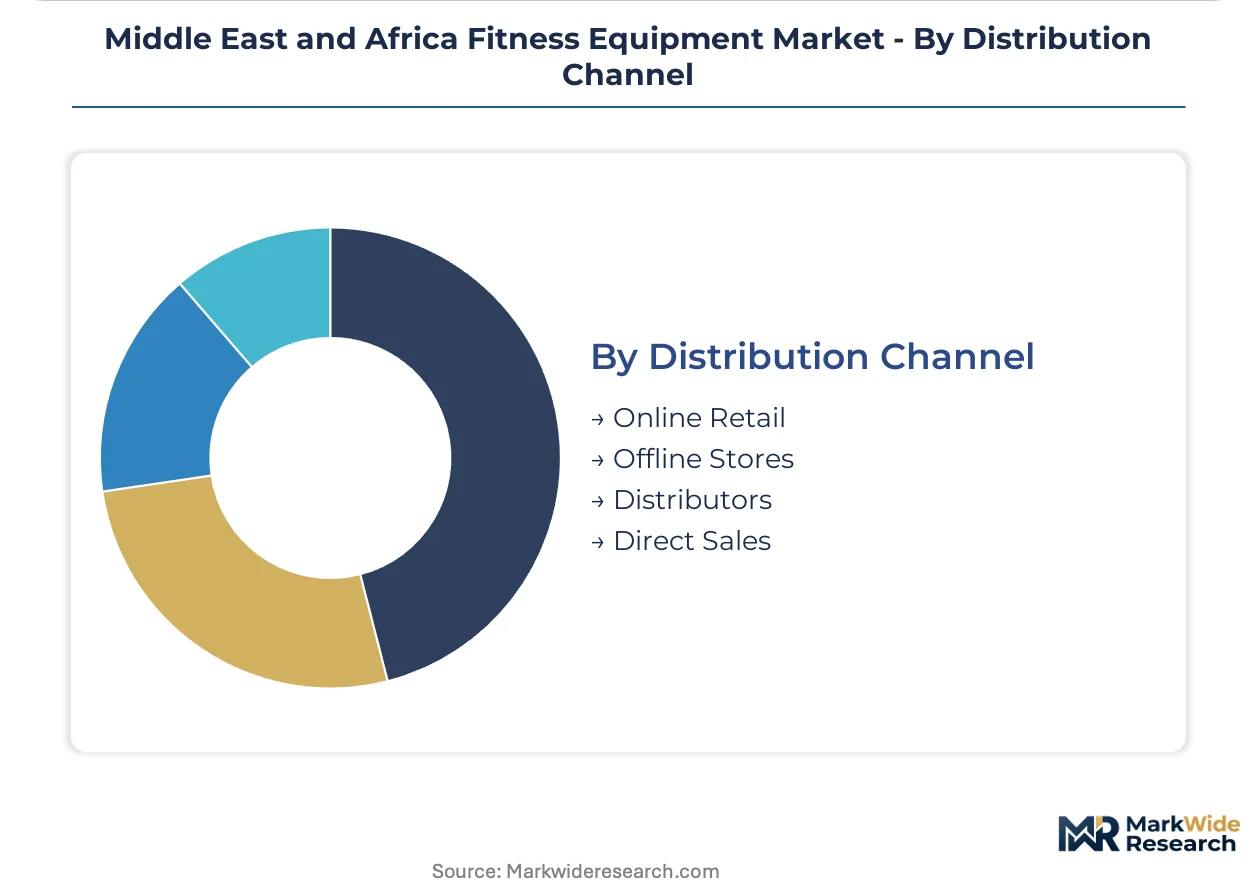
- Online Retail:Direct-to-home digital channels target remote fitness users in Nigeria and Kenya with compact equipment. Mobile commerce penetration in Nairobi accelerates first-time buyer acquisition for non-motorized categories.
- Offline Stores:Showroom-based sales with physical testing dominate high-treadmill purchases in UAE and Saudi Arabia.
- Distributors:Multi-brand wholesalers serve mid-market gym chains across South Africa with cost-competitive assembly options.
- Direct Sales:Manufacturer-led procurement addresses government-funded sports infrastructure in Gulf states with localization requirements.
Offline stores transact the highest-value orders; online retail is gaining share fastest in African markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali port complex underwrites the UAE's role as the regional equipment import gateway, handling containerized fitness machinery from East Asian manufacturing hubs before redistribution across Gulf Cooperation Council states and East African markets.
United Arab Emirates
Dubai's premium fitness club density drives high-end equipment specification intensity, with MOHAP medical device classification shaping rehabilitation equipment compliance requirements. Abu Dhabi's government-funded sports infrastructure programs are accelerating procurement timelines for smart-enabled cardio installations at municipal wellness centers.
Saudi Arabia
The Quality of Life Program mandates fitness facilities in all new residential developments, creating guaranteed demand pools for motorized treadmills and selectorized strength systems across Riyadh and Jeddah. SFDA conformity assessments govern import clearance, compelling suppliers to localize assembly capacity for government-linked procurement pools.
South Africa
Private hospital groups are expanding rehabilitation center networks, driving orders for medical-grade motorized equipment with National Regulator for Compulsory Specifications safety certifications. Cape Town's manufacturing base for steel-frame cardio equipment is tilting toward export readiness for sub-Saharan African markets.
Nigeria
Lagos's rising health consciousness among affluent urban demographics is compressing procurement cycles for commercial gym chains seeking cost-competitive treadmill assemblies. Mobile commerce penetration is accelerating first-time buyer acquisition for compact non-motorized home fitness equipment.
Kenya
Nairobi's underpenetrated home fitness segment presents first-mover potential for folding treadmills and resistance bands distributed through mobile commerce channels. Rising middle-class disposable income is shifting equipment procurement from institutional buyers toward individual residential purchasers.
Middle East and Africa Fitness Equipment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying brushless DC motors and polyurethane cushioning systems to regional assemblers. The vendor base clusters around three strategic tiers: Italian-engineered premium brands, East Asian cost-competitive manufacturers, and Gulf-based distributors with localization capabilities. Two dominant competitive moves are reshaping positioning: direct-to-home digital channel expansion targeting African residential markets, and third-party technical service unbundling that disrupts traditional captive maintenance revenue models.
Within the premium commercial tier, Technogym S.P.A and Johnson Health Tech Co. Ltd exemplify divergent sourcing strategies—one leveraging European engineering heritage for Gulf state installations, the other anchoring regional position through cost-competitive assembly serving mid-market gym chains. Icon Health & Fitness Inc occupies a position on the direct-to-consumer vector, targeting remote fitness users in Nigeria and Kenya through digital distribution channels.
| Leading Market Players |
|---|
| Icon Health & Fitness Inc |
| SportsArt Fitness, Inc. |
| Technogym S.P.A |
| Dubai Sports LLC |
| Core Health & Fitness LLC |
| Life Fitness |
| Precor Incorporated |
| Acme Fitness |
| Johnson Health Tech Co. Ltd |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese brushless DC motor production is compressing component costs for regional assemblers while simultaneously eroding pricing power for mid-market treadmill suppliers serving Nigerian gym chains. This utilization dynamic rewards buyers with procurement leverage in bulk negotiations but squeezes margins for manufacturers lacking premium brand positioning or localized assembly capabilities in Gulf states.
Pricing Analysis
Saudi Arabia's Quality of Life Program dictates the pricing tier structure for government-linked procurement pools, with SFDA conformity assessments creating a certification premium that separates localized assemblers from import-dependent competitors. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling, with corporate wellness buyers in Dubai unbundling maintenance contracts to drive cost compression in the standard tier. Pricing pressure stems from steel and aluminum input volatility, which disproportionately affects economy-tier suppliers serving price-sensitive home users in Kenya and Nigeria.
Supply Chain Analysis
Powder-coated steel feedstock draws from South Africa's manufacturing base and East Asian rolling mills, while brushless DC motor sourcing rests on production clusters in China, Taiwan, and South Korea. Polyurethane cushioning systems and continuous-duty motor controllers hinge on specialized component suppliers concentrated in Guangdong and Zhejiang provinces. Single-source vulnerability in East Asian motor production exposes regional assemblers to shipping disruptions through the Jebel Ali port complex. Distribution runs through multi-brand wholesalers serving mid-market gym chains and direct sales channels for government-funded sports infrastructure mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa fitness equipment market sits in early-cycle expansion, with Saudi residential development mandates and Kenya's mobile commerce penetration representing dual tailwinds accelerating equipment adoption beyond traditional gym channels.
For Market Incumbents: Harden certification workflows to compress SFDA and MOHAP approval timelines, defending against emerging entrants with prior Gulf regulatory experience. Deepen backward integration into brushless DC motor assembly within Saudi Arabia's localization incentive zones, securing preferential access to Quality of Life Program procurement pools while margin pressure intensifies on import-dependent competitors. For New Entrants and Emerging Players: Nairobi's underpenetrated home fitness segment represents the most penetrable entry point, with folding treadmills and resistance bands distributed through mobile commerce channels capturing first-mover advantage among rising middle-class residential purchasers. Compact non-motorized equipment for Egyptian rehabilitation centers facing biomedical engineer talent scarcity offers a secondary white-space target, with remote calibration support services as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart equipment manufacturing, as biometric sensor integration and AI-powered form correction capabilities require sustained R&D commitment that separates viable long-term players from component assemblers. Acquisition targets should screen for Gulf state localization capabilities and existing SFDA conformity infrastructure, with certification backlog duration serving as the critical inflection signal for competitive positioning durability over the coming decade.| Strategic Initiative | Industry Significance |
|---|---|
| Localization Assembly Partnership | SFDA conformity assessments qualify suppliers for Saudi government-linked procurement pools. |
| Smart Equipment Platform Integration | Biometric sensor ecosystems enable usage-based billing for Dubai corporate wellness contracts. |
| Mobile Commerce Channel Expansion | Nairobi's rising middle-class disposable income shifts procurement toward residential purchasers. |
| Third-Party Service Unbundling | Independent maintenance agreements disrupt traditional supplier-captive revenue models in UAE. |
| Energy-Efficient Motor Transition | Brushless DC specifications reduce utility overhead for 24-hour gym operators in Riyadh. |
Research Methodology
A standing panel of commercial gym procurement directors, biomedical engineers at private hospital groups, SFDA regulatory consultants, and mobile commerce platform operators provided ongoing calibration throughout the study. Primary interviews with equipment distributors across Dubai and Riyadh combined with secondary validation against UAE customs records, South Africa's National Regulator for Compulsory Specifications filings, and Saudi real estate development permit databases. Bottom-up equipment shipment tracking and top-down fitness facility investment flow analysis enabled triangulation across demand estimation approaches.
Scenario-bracketing framed the analytical framework across the projection horizon, with segmentation modeling across product type, end user, technology integration intensity, and distribution channel. CAGRs derived from equipment procurement pipeline analysis and facility installation timelines, with brushless DC motor efficiency benchmarks and biometric sensor adoption curves serving as industry-specific forecast inputs alongside real estate development permit velocity in Riyadh and Jeddah.
Practitioners should monitor steel and aluminum commodity price volatility, East Asian shipping route disruptions, and Gulf state localization incentive recalibrations for early signals requiring forecast revision. Cross-checking against UAE Ministry of Economy import statistics and Saudi General Authority for Statistics construction activity indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Resistance Bands Market
Fitness Equipment
Exercise Resistance Bands Market
Fitness Equipment
Yoga Mat Market
Fitness Equipment
Yoga Equipment Market
Fitness Equipment
Gym Ball Market
Fitness Equipment
Home Fitness Equipment Market
Fitness Equipment
Asia-Pacific Fitness Rings Market
Fitness Equipment
Saudi Arabia Outdoor Fitness Equipment Market
Fitness Equipment
Exercise Band Market
Fitness Equipment
Lateral Fitness Equipment Market
Fitness Equipment
Personal Exercise Mats Market
Fitness Equipment
US Fitness Rings Market
Fitness Equipment
Belt Trainers Market
Fitness Equipment
Global Jumping Rope Market
Fitness Equipment
Europe Fitness Equipment Market
Fitness Equipment
Elliptical Trainers Market