
 Personal Exercise Mats Market | 2026-2036
Personal Exercise Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Exercise Mats Market Analytics
Fitness enthusiasts transitioning from casual home workouts to structured studio memberships is unwinding the historical dominance of price-sensitive beginner buyers. Manduka LLC leverages its premium natural rubber supply chain to anchor the professional yoga segment with certified sustainable sourcing. Nike Inc. competes across multiple thickness grades while extending its athletic apparel distribution into mat accessories. Decathlon S.A. dominates mass-market positioning through controlled vertical retail networks spanning Europe and Asia.
Personal exercise mats are flat, resilient platforms engineered from polymer foams or tree-derived elastomers, typically spanning 173 cm by 61 cm with surface textures calibrated for grip coefficient under humid conditions. Their primary commercial purpose is to cushion kinetic impact, stabilize joint alignment, and define spatial boundaries during floor-based movement protocols. Natural rubber and TPE formulations lead material type demand as studios phase out PVC under chemical scrutiny, while 6 mm thickness occupies the volume core for travel portability and 10 mm variants capture margin pools in rehabilitation settings. Target user segmentation shows fitness enthusiasts outpacing beginners in replacement frequency, with professional athletes driving specification intensity for density and dimensional tolerance.
The EPA oversees volatile organic compound thresholds in foam manufacturing, while REACH restricts phthalate plasticizers across European import channels, and California's Proposition 65 mandates warning labels on PVC-containing products sold in that state. These frameworks collectively shift procurement criteria toward certified low-emission materials and documented supply chain transparency. Stakeholders must monitor evolving chemical restriction lists and decide whether to absorb compliance costs or accelerate material transitions ahead of regulatory expansion.
Market Dynamics
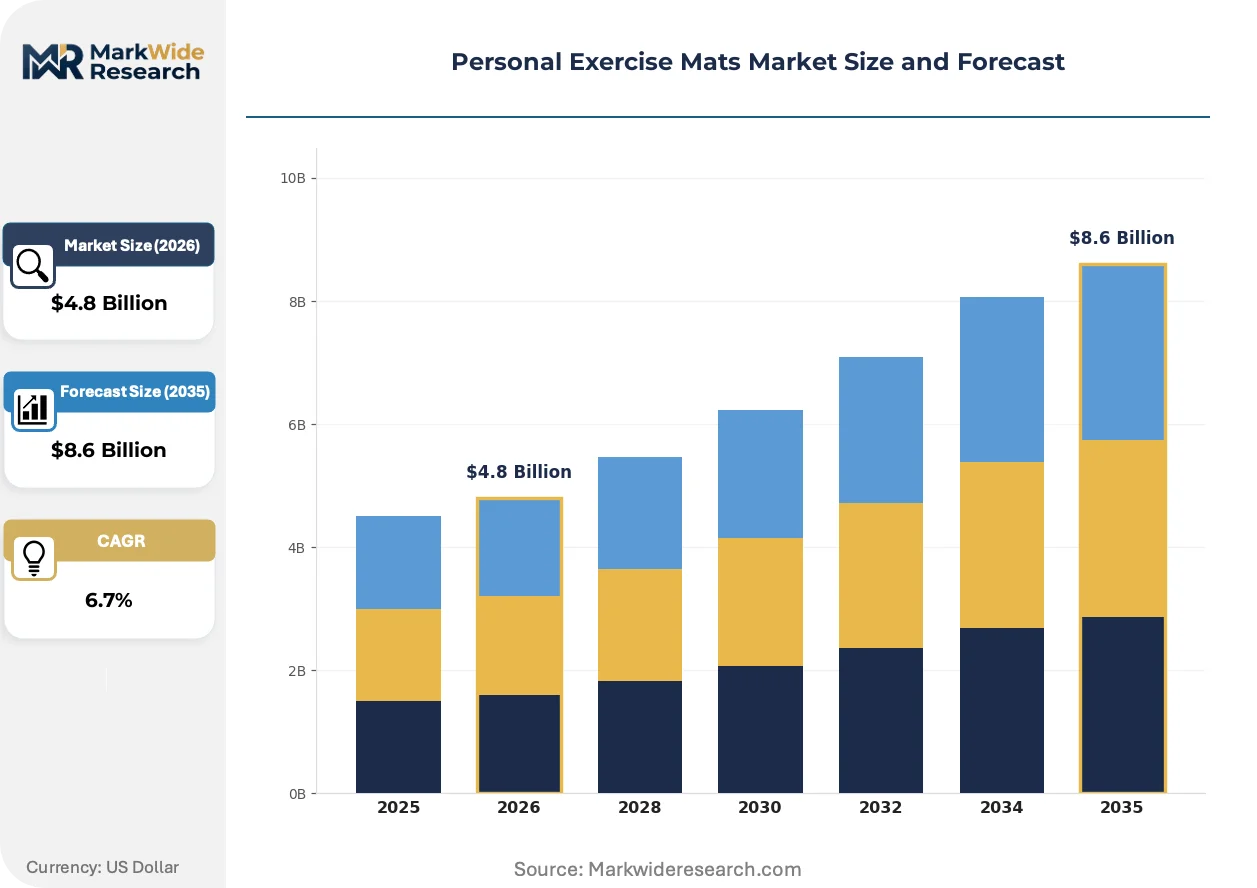
EU REACH phthalate restrictions and California's Proposition 65 warning mandates are accelerating material transitions away from PVC-dominant formulations, compressing margins for legacy suppliers while rewarding certified natural rubber and TPE producers with studio procurement contracts.
Growth Catalysts
- Boutique studio densification:Specialized fitness operators in the United States and Germany now mandate eco-certified mats for instructor-led classes, creating institutional procurement pipelines that bypass retail markups.
- REACH chemical compliance:European restrictions on phthalate plasticizers force PVC-dependent manufacturers to reformulate, opening shelf space for compliant natural rubber alternatives in specialty channels.
- Home practitioner equipment upgrades:Former casual exercisers investing in dedicated practice spaces drive replacement cycles for higher-density mats with documented grip performance under humid conditions.
Market Restraints
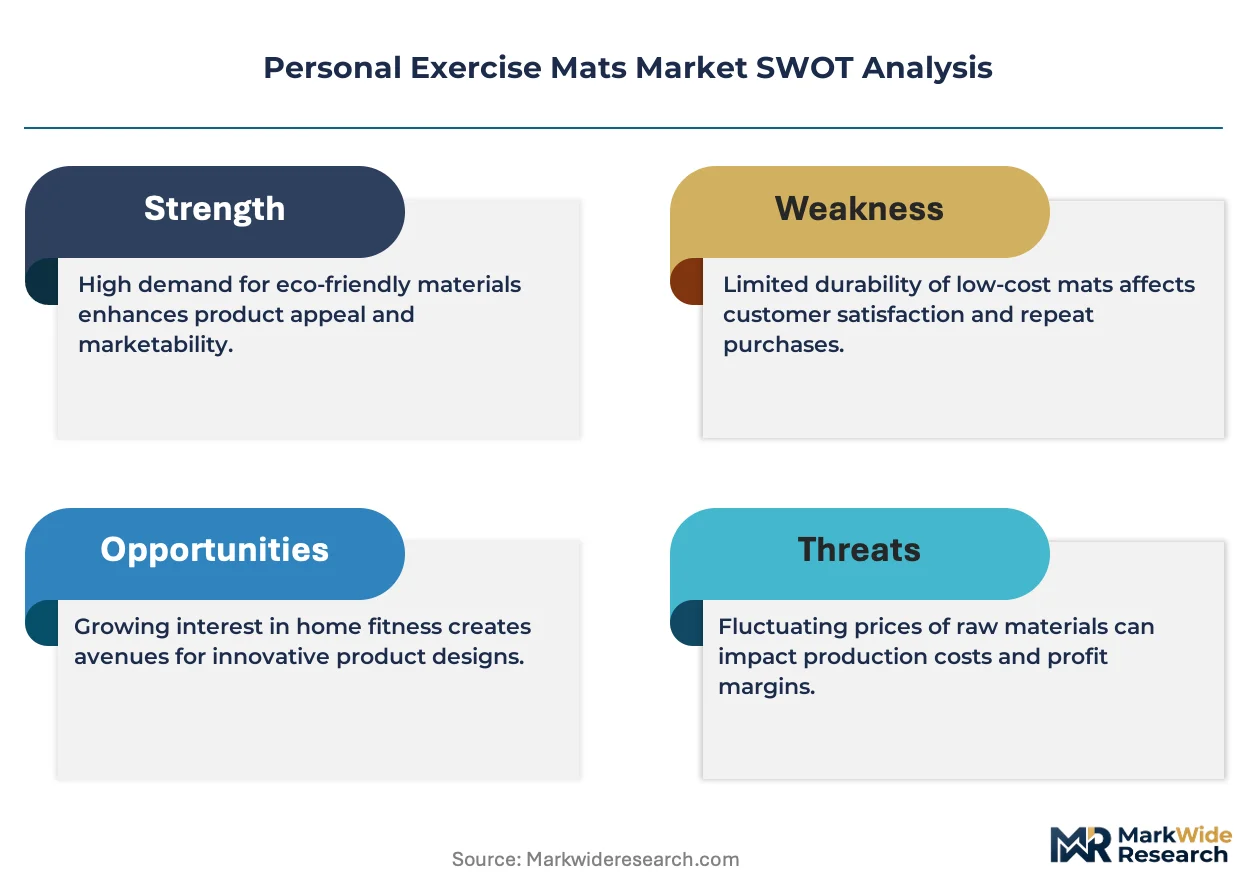
- Natural rubber price volatility:Latex supply concentrates in Southeast Asian plantations, exposing TPE and rubber-formulation producers to input cost swings that compress working capital buffers.
- California Proposition 65 litigation exposure:PVC-containing products sold in-state require warning labels, creating legal liability for distributors and deterring mass-market retailers from stocking non-compliant inventory.
- Thickness-performance tradeoffs:Travel-oriented 6 mm mats sacrifice joint cushioning that rehabilitation practitioners demand, fragmenting demand across incompatible specification tiers.
Strategic Opportunities
- Rehabilitation clinic vertical:Physical therapy practices in Japan and Australia specify 10 mm density mats for patient protocols, commanding price premiums through medical-channel procurement.
- Direct-to-consumer subscription bundling:Mat-plus-content packages bypass wholesale intermediaries, capturing recurring revenue from home practitioners seeking structured programming.
- EU Green Deal circularity incentives:Closed-loop recycling mandates for polymer products create certification pathways for take-back programs that differentiate premium positioning.
Industry Challenges
- Supply chain reconfiguration friction:Shifting from PVC to TPE or natural rubber requires new molding equipment and qualified resin suppliers, extending qualification timelines for contract manufacturers.
- Certification documentation gaps:Studios demanding OEKO-TEX or GOTS traceability encounter incomplete supplier records, delaying procurement approvals and freezing vendor switches mid-cycle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Exercise Mats Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PVC, TPE, Natural Rubber, NBR Thickness: 6 mm, 8 mm, 10 mm, 12 mm Target User: Beginner, Professional, Fitness Enthusiast, Rehabilitation Usage: Yoga, Pilates, Stretching, Aerobics |
| Companies Covered | Lululemon Athletica Inc., Manduka LLC, Gaiam, Jade Yoga, Adidas AG, Liforme Ltd., Nike Inc., Decathlon S.A., ProsourceFit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Exercise Mats Market Evolving Landscape
Material science advances and regulatory chemical restrictions are converging to redefine performance benchmarks and procurement criteria across professional and consumer channels simultaneously.
Thermoplastic elastomer (TPE) closed-cell foam is supplanting PVC in studio procurement specifications due to its closed-loop recyclability and absence of plasticizer off-gassing. Boutique operators in Germany and the Netherlands now require TPE documentation for instructor mat pools, compressing PVC volumes in B2B channels while elevating price floors for certified alternatives.
California's Proposition 65 enforcement against PVC-containing consumer goods has triggered warning-label mandates that deter mass-market retail stocking. Distributors serving the United States now segregate inventory by chemical composition, with compliant SKUs receiving preferential placement in specialty fitness channels and PVC variants relegated to discount liquidation.
Practitioners transitioning from casual home exercise to structured studio membership now prioritize mat longevity and warranty terms over initial purchase price. This specification intensity concentrates replacement demand among fitness enthusiasts rather than beginners, with United States specialty retailers capturing margin through durability guarantees and trade-in programs that lock repeat purchases.
Personal Exercise Mats Market Segmentation
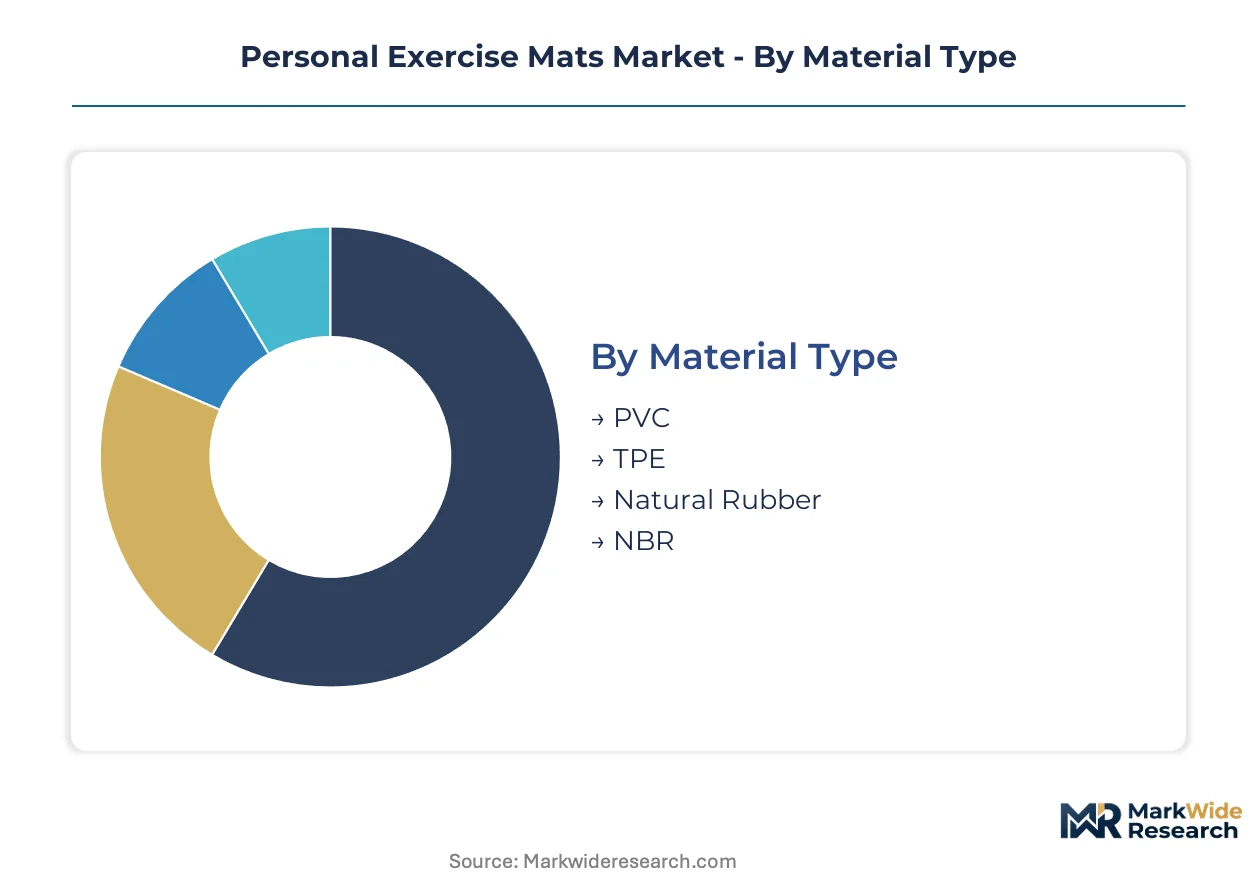
Material specifications and user sophistication levels determine margin capture in the personal exercise mats market, with certified formulations commanding premium positioning against commodity alternatives. Studio procurement contracts and home practitioner upgrade cycles create divergent demand profiles across each segmentation axis.
Material Type:
Margin pools concentrate in certified low-emission formulations as regulatory scrutiny elevates compliance costs for legacy suppliers.
- Natural Rubber:Tree-derived elastomer with closed-cell construction delivers superior grip coefficient under humid conditions. Boutique studios in Germany and the United States now mandate FSC-certified sourcing for instructor pools, locking in multi-year procurement contracts.
- TPE:Thermoplastic elastomer foam enables closed-loop recyclability without plasticizer off-gassing. REACH compliance documentation positions TPE variants for shelf space expansion across European specialty retailers phasing out PVC inventory.
- PVC:Polyvinyl chloride formulations face California Proposition 65 warning mandates and ECHA phthalate restrictions that compress margins through reformulation costs and retail access limitations.
- NBR:Nitrile butadiene rubber offers oil resistance and durability for high-intensity protocols, capturing specification in commercial gym chains prioritizing equipment longevity over eco-certification.
The dominant share belongs to PVC, while natural rubber is closing the gap fastest.
Thickness:
Specification intensity varies sharply by end-use, with medical-channel density commanding price premiums against travel-oriented portability.
- 6 mm:Standard travel format balances rollability with baseline joint protection. Fitness enthusiasts in Japan and Australia prioritize this specification for home practice spaces requiring storage efficiency.
- 10 mm:Rehabilitation-grade density cushions kinetic impact for patient protocols. Physical therapy practices specify this thickness for clinical settings, bypassing retail markups through institutional procurement.
- 8 mm:Intermediate specification serves hybrid practitioners transitioning between studio and home environments.
- 12 mm:Maximum cushioning targets senior fitness and injury recovery segments with limited volume but elevated per-unit economics.
Volume concentrates at 6 mm, though 10 mm claims the steepest expansion trajectory through medical vertical penetration.
Target User:
Replacement frequency and specification intensity separate high-value segments from price-sensitive entry buyers.
- Fitness Enthusiast:Practitioners with structured practice schedules drive replacement cycles every 18-24 months, prioritizing durability guarantees and trade-in programs over initial purchase price.
- Professional:Instructors and competitive athletes demand dimensional tolerance and density consistency for daily intensive use, creating specification intensity that filters out mid-tier suppliers.
- Beginner:Price-sensitive entry buyers show high churn and low replacement frequency, concentrating volume in mass-market channels with compressed margins.
- Rehabilitation:Clinical practitioners specify medical-grade density and hygiene protocols, commanding price premiums through channel-specific procurement.
Fitness enthusiasts anchor volume share, while rehabilitation is expanding most quickly through physical therapy vertical integration.
Usage:
Movement protocol requirements dictate surface texture and grip coefficient specifications across end-use applications.
- Yoga:Downward-facing dog and balancing postures require textured surfaces with calibrated friction coefficients. Hot yoga practitioners in the United States drive demand for moisture-wicking top layers.
- Pilates:Controlled movement patterns prioritize joint cushioning over grip intensity, aligning specification with 8-10 mm density preferences.
- Stretching:Static hold protocols tolerate thinner profiles, concentrating demand in 6 mm travel formats for pre-workout mobility routines.
- Aerobics:High-impact plyometric sequences demand maximum cushioning and slip resistance, favoring NBR formulations in commercial gym deployments.
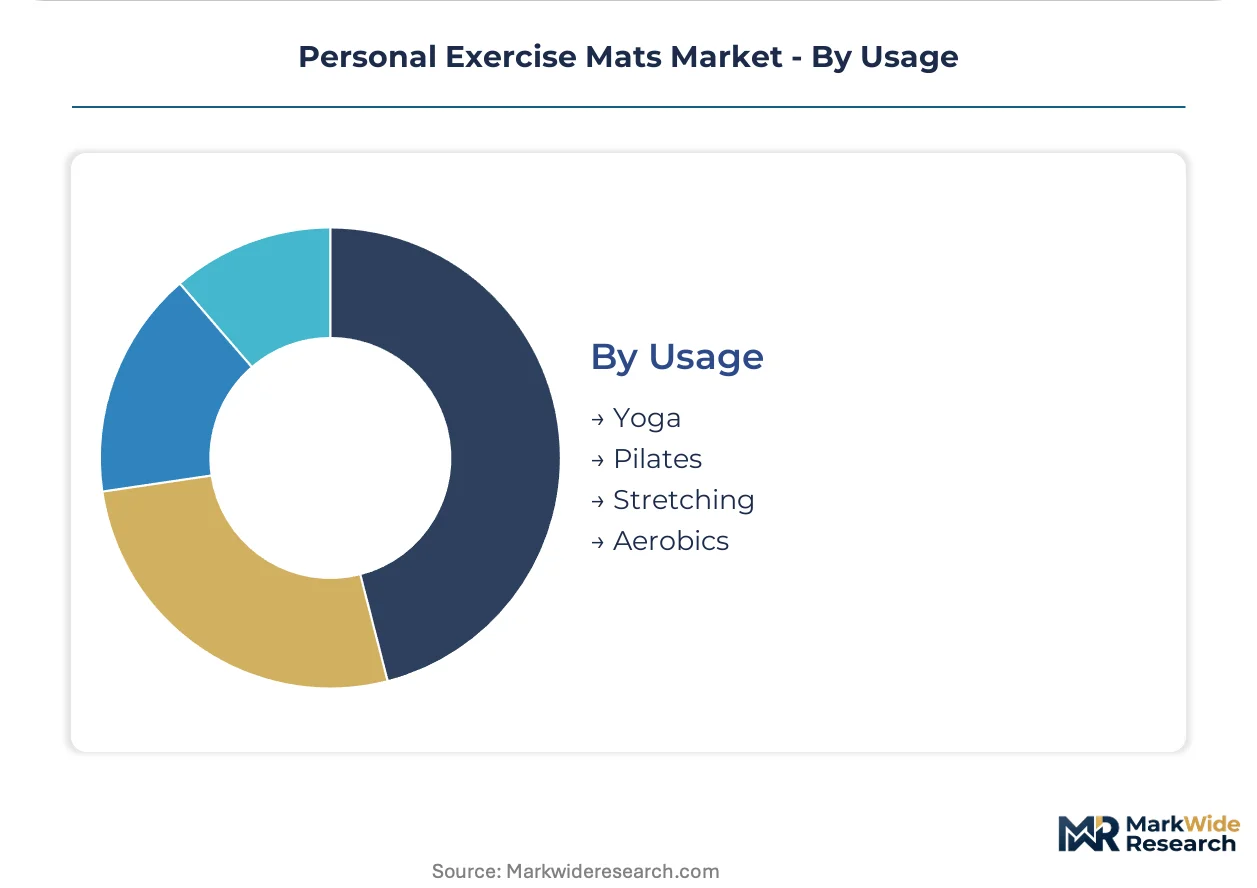
Yoga retains the dominant share, while Pilates is gaining share fastest through studio densification in Germany and the Netherlands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness enthusiasts in the United States and Germany drive premium procurement volumes, while studio densification in the Netherlands and Australia accelerates eco-certified mat adoption. Boutique operators in Japan and the United Kingdom now mandate documented supply chain transparency for instructor equipment pools.
United States
Boutique fitness studios in Los Angeles and New York City mandate FSC-certified natural rubber mats for instructor pools. California's Proposition 65 requires warning labels on PVC-containing products, compressing retail shelf space for legacy formulations. Specialty retailers in Austin and Denver capture margin through durability guarantees and trade-in programs.
Germany
Boutique operators in Berlin and Hamburg require TPE documentation for instructor mat pools under REACH phthalate compliance protocols. The EU Green Deal circularity incentives reward closed-loop recycling programs for polymer products. Manufacturing clusters in Bavaria specialize in certified low-emission foam formulations for export channels.
Netherlands
Studio densification in Amsterdam and Rotterdam drives institutional procurement contracts that bypass retail markups. ECHA restrictions on chemical substances elevate compliance costs for PVC-dominant suppliers. Distribution hubs in Utrecht consolidate certified natural rubber inventory for re-export across Northern Europe.
Japan
Physical therapy practices in Tokyo and Osaka specify 10 mm density mats for patient rehabilitation protocols. METI oversees voluntary standards for chemical emissions in consumer products. Manufacturing facilities in Nagoya produce medical-grade density formulations for clinical channel procurement.
Australia
Home practitioners in Sydney and Melbourne drive replacement cycles for higher-density mats with documented grip performance. The TGA regulates therapeutic goods claims for rehabilitation equipment. Specialty retailers in Brisbane capture premium positioning through certified sustainable sourcing documentation.
Personal Exercise Mats Market Competitive Landscape
Player mix skews toward vertically integrated specialty brands and mass-market athletic apparel distributors. Manduka LLC anchors the professional yoga segment through certified sustainable supply chains, while Decathlon S.A. dominates mass-market positioning across controlled retail networks. Nike Inc. and Adidas AG leverage athletic apparel distribution infrastructure to extend into mat accessories. Strategic moves concentrate on material transitions ahead of regulatory expansion and direct-to-consumer subscription bundling that bypasses wholesale intermediaries.
Within the specialty-brand tier, Manduka LLC and Liforme Ltd. occupy positions defined by certified natural rubber sourcing and studio procurement relationships. Lululemon Athletica Inc. represents the athletic-lifestyle crossover archetype, bridging apparel loyalty into equipment categories. Among mass-market distributors, Decathlon S.A. exemplifies scale-driven vertical retail control spanning Europe and Asia. These three anchors illustrate how competitive positioning separates premium certified suppliers from volume-oriented channels.
| Leading Market Players |
|---|
| Lululemon Athletica Inc. |
| Manduka LLC |
| Gaiam |
| Jade Yoga |
| Adidas AG |
| Liforme Ltd. |
| Nike Inc. |
| Decathlon S.A. |
| ProsourceFit |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Southeast Asian latex processors and European mat manufacturers lock in supply access and price visibility across volatile commodity cycles. These agreements insulate certified natural rubber producers from spot market swings while anchoring cost-plus pricing for REACH-compliant formulations sold through German and Dutch studio procurement channels.
Pricing Analysis
Cost-plus contracts with latex indexation dominate procurement between Southeast Asian suppliers and European manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified natural rubber from TPE alternatives and legacy PVC stock. Pricing pressure stems from California Proposition 65 compliance costs that compress margins on non-certified inventory. Beginners exhibit highest price sensitivity, while rehabilitation clinics accept premium positioning for medical-grade density specifications.
Supply Chain Analysis
Malacca Strait transit underwrites raw material flows between Indonesian and Malaysian latex plantations and processing facilities in Thailand and Vietnam. Natural rubber feedstock draws from Hevea brasiliensis estates concentrated across Southeast Asia, while TPE resin sources from petrochemical complexes in South Korea and Japan. Single-source vulnerability concentrates in latex processing capacity, with distribution running through specialty fitness retailers and direct-to-consumer subscription channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH and Proposition 65 compliance requirements create switching costs that protect certified suppliers from commodity PVC competitors.
For Market Incumbents: Secure multi-year studio procurement contracts with documented OEKO-TEX traceability before TPE capacity expansion accelerates. Invest in captive latex processing partnerships in Thailand or Vietnam to offset natural rubber price volatility. Manduka LLC and Liforme Ltd. have demonstrated that certification investment locks out mid-tier challengers. For New Entrants and Emerging Players: EU Green Deal fast-track certification for closed-loop TPE recyclability opens shelf space in Amsterdam and Rotterdam studio densification. Target physical therapy verticals in Japan and Australia with 10 mm medical-grade density specifications. Direct-to-consumer subscription bundling bypasses wholesale markups and captures recurring revenue from home practitioners. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialty brands with captive Southeast Asian latex supply and established studio procurement relationships. Watch for inflection signals in California Proposition 65 enforcement expansion that would accelerate PVC inventory liquidation and compress legacy supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | FSC and OEKO-TEX documentation secures studio procurement contracts in Germany and the United States. |
| Backward Integration | Captive latex processing in Thailand insulates margins from commodity price swings. |
| Direct-to-Consumer Launch | Mat-plus-content subscriptions bypass wholesale intermediaries and capture recurring revenue. |
| Medical Channel Expansion | 10 mm density specifications for Japanese and Australian physical therapy practices command price premiums. |
| Sustainability Repositioning | Closed-loop TPE recyclability aligns with EU Green Deal circularity incentives. |
Research Methodology
A standing panel of boutique studio owners, procurement managers at fitness chains, latex plantation operations directors, and specialty retail buyers provided ongoing calibration across the analysis window. Primary interviews combined with secondary validation from customs trade records, ECHA chemical restriction updates, and studio equipment procurement databases. Bottom-up volume triangulation against top-down value estimates anchored segmentation outputs.
Consistency checks validated outputs against external benchmarks including REACH compliance cost disclosures and California Proposition 65 enforcement patterns. The analytical framework modeled material type, thickness specification, target user sophistication, and usage protocol across the projection horizon. CAGRs derived from replacement cycle analysis and studio densification rates in tracked metropolitan clusters.
Decision-makers should treat outputs as directional under stable regulatory enforcement assumptions; material deviation in ECHA phthalate restriction expansion would warrant model refresh. Practitioners should keep alternative scenarios live as EU Green Deal circularity mandates and Southeast Asian climate volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Indoor Bike Trainers Market
Fitness Equipment
Push-Up Board Market
Fitness Equipment
Fitness Ball Market
Fitness Equipment
Resistance Bands Market
Fitness Equipment
Global Jumping Rope Market
Fitness Equipment
Leg Exercise Equipment Market
Fitness Equipment
Europe Fitness Equipment Market
Fitness Equipment
Elliptical Trainers Market
Fitness Equipment
Lateral Fitness Equipment Market
Fitness Equipment
Middle East and Africa Fitness Equipment Market
Fitness Equipment
Japan Fitness Ring Market
Fitness Equipment
Exercise Band Market
Fitness Equipment
Hydrotherapy Treadmills Market
Fitness Equipment
Treadmill Ergometer Market
Fitness Equipment
China Outdoor Fitness Equipment Market
Fitness Equipment
South Africa Gym Accessories Market