
 Elliptical Trainers Market | 2026-2036
Elliptical Trainers Market Size, Share, and Industry Trends Forecast 2026-2036
Elliptical Trainers Market Analysis
Connected sensor technology is reconfiguring how elliptical trainers collect biomechanical data and sync with third-party fitness ecosystems. NordicTrack leverages its iFit streaming platform to anchor recurring subscription revenue alongside hardware sales. Technogym S.p.A sustains premium positioning through integrated digital wellness infrastructure for commercial clients. Precor, Inc. dominates institutional procurement channels with durable frame engineering and extended service contracts.
An elliptical trainer is a stationary exercise machine that simulates stair climbing, walking, and running through linked pedal and handlebar motion, typically featuring adjustable stride lengths from 18 to 22 inches and flywheel masses between 15 and 30 pounds for smooth kinetic momentum. The apparatus serves commercial fitness operators and residential users seeking low-impact cardiovascular conditioning with reduced joint stress compared to treadmills. Magnetic resistance systems command the largest installed base due to silent operation and minimal maintenance requirements, while smart trainers with embedded touchscreens and Wi-Fi connectivity represent the fastest-expanding margin pool as operators bundle hardware with software subscriptions. Online retail channels are gaining shelf share from specialty stores as direct-to-consumer brands simplify assembly logistics and virtual setup assistance.
Regulators in the United States enforce FCC certification for wireless-enabled trainers and CPSC safety standards for mechanical stability and pinch-point guarding. European operators must comply with CE marking under the Machinery Directive and REACH substance restrictions on handlebar coatings and plastics. Stakeholders should monitor how emerging energy-efficiency labeling requirements and right-to-repair mandates reshape product design priorities and aftermarket service economics.
Market Dynamics
Connected sensor technology is reconfiguring competitive boundaries by merging hardware durability with recurring software revenue streams. Manufacturers now compete on ecosystem lock-in rather than flywheel specifications alone.
Growth Catalysts
- FCC certification pathways:Wireless-enabled trainers gain faster market entry through streamlined electromagnetic compliance testing in the United States, accelerating product refresh cycles.
- Corporate wellness procurement:Employer-sponsored fitness stipends are expanding institutional purchase volumes for commercial-grade ellipticals with usage tracking capabilities.
- Magnetic resistance engineering:Silent-drive systems are penetrating residential segments where noise constraints previously limited adoption in multi-unit dwellings.
Market Restraints
- Steel and aluminum input volatility:Frame material costs fluctuate with commodity indexes, compressing margin stability for manufacturers without long-term supply agreements.
- REACH substance compliance:European coating and plastic restrictions add formulation complexity and testing overhead for handlebar grips and console housings.
- Treadmill substitution elasticity:Running machines retain preference among high-impact training protocols, capping elliptical ceiling in performance-oriented commercial facilities.
Strategic Opportunities
- India BIS certification alignment:Standardized safety testing infrastructure creates pathway for premium import brands to access expanding metro fitness infrastructure.
- Rehabilitation clinic integration:Physical therapy protocols are incorporating low-impact cardiovascular equipment for joint-prescription exercise regimens.
- Direct-to-consumer assembly logistics:Virtual setup assistance and modular shipping formats are opening geographic markets previously unserved by specialty retail footprints.
Industry Challenges
- Embedded software talent scarcity:Firmware development for touchscreen interfaces and cloud synchronization outpaces qualified hiring pools in traditional fitness equipment manufacturing centers.
- CE marking timeline compression:Machinery Directive conformity assessments for smart trainers with electrical components extend certification cycles versus mechanical-only predecessors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elliptical Trainers Market |
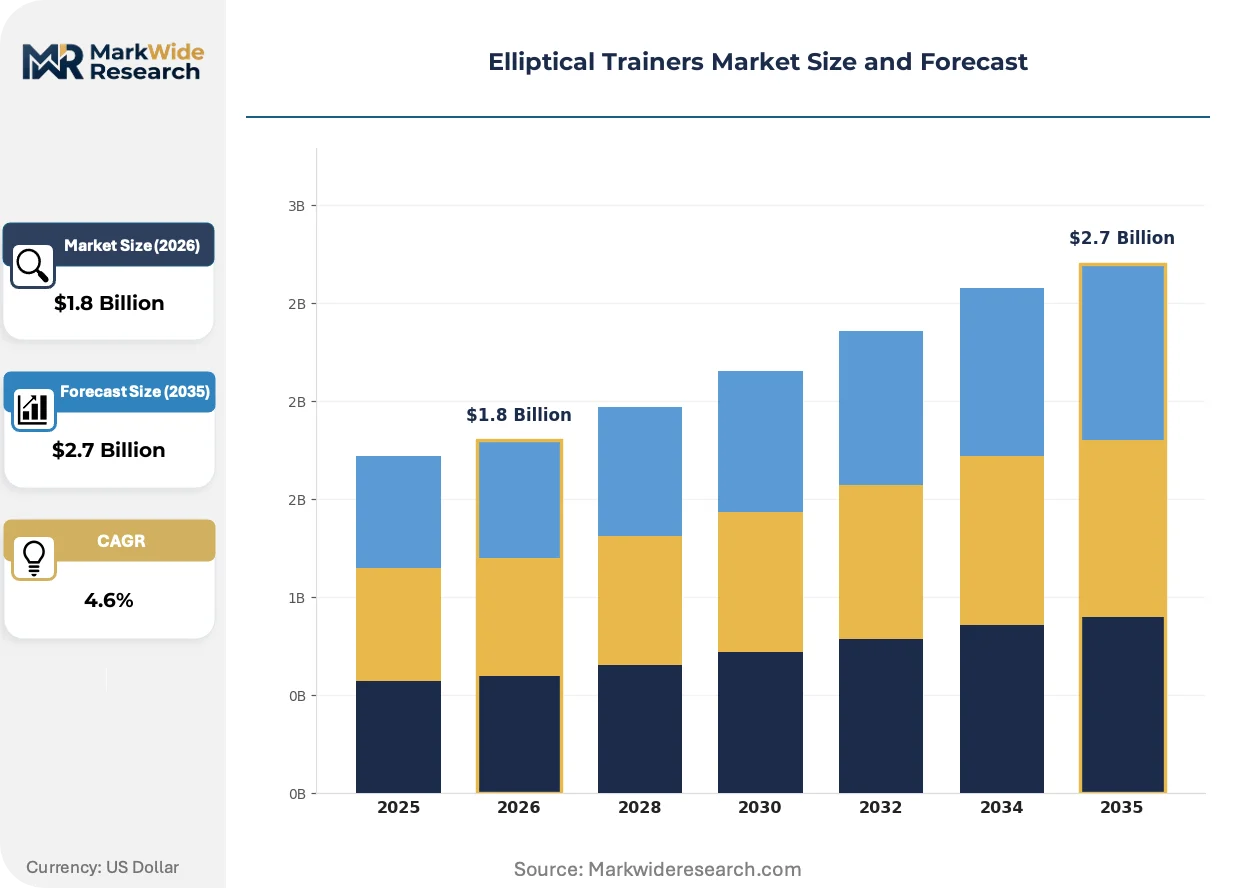
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Magnetic, Electronic, Hybrid End User: Residential, Commercial Gyms, Fitness Centers, Rehabilitation Facilities Technology: Smart Trainers, Conventional Trainers, Battery-Powered, Plug-in Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Precor, Inc., Life Fitness, NordicTrack, Core Health & Fitness, LLC, Technogym S.p.A, Sole Fitness, Schwinn, Body-Solid Inc., FreeMotion Fitness, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elliptical Trainers Market Emerging Trajectories
Software-defined functionality is overtaking mechanical differentiation as the primary value driver in trainer procurement decisions. Buyers now prioritize ecosystem compatibility and data portability over stride mechanics.
Adaptive resistance algorithms calibrated to heart-rate variability and power output are rendering obsolete fixed-program consoles that offer static hill profiles without biometric feedback. Boutique fitness studios in the United States are retrofitting fleets with these systems to support personalized interval coaching. The shift is compressing replacement cycles for equipment purchased between 2015 and 2020 that lacks API connectivity.
EU energy-efficiency labeling requirements for networked appliances are extending to cardiovascular equipment with standby power draw above threshold limits. Manufacturers serving European commercial operators must redesign power management circuits to meet standby consumption targets. German fitness chains are prioritizing compliant models in procurement specifications to preempt operational cost penalties.
Subscription bundling is restructuring ownership economics as operators shift from capital expenditure to operational expenditure models. Full-service leasing with bundled maintenance and software access is displacing outright purchase in mid-market gym chains. This pattern concentrates in the United Kingdom where property lease terms favor equipment financing aligned with facility contracts.
Elliptical Trainers Market Segmentation
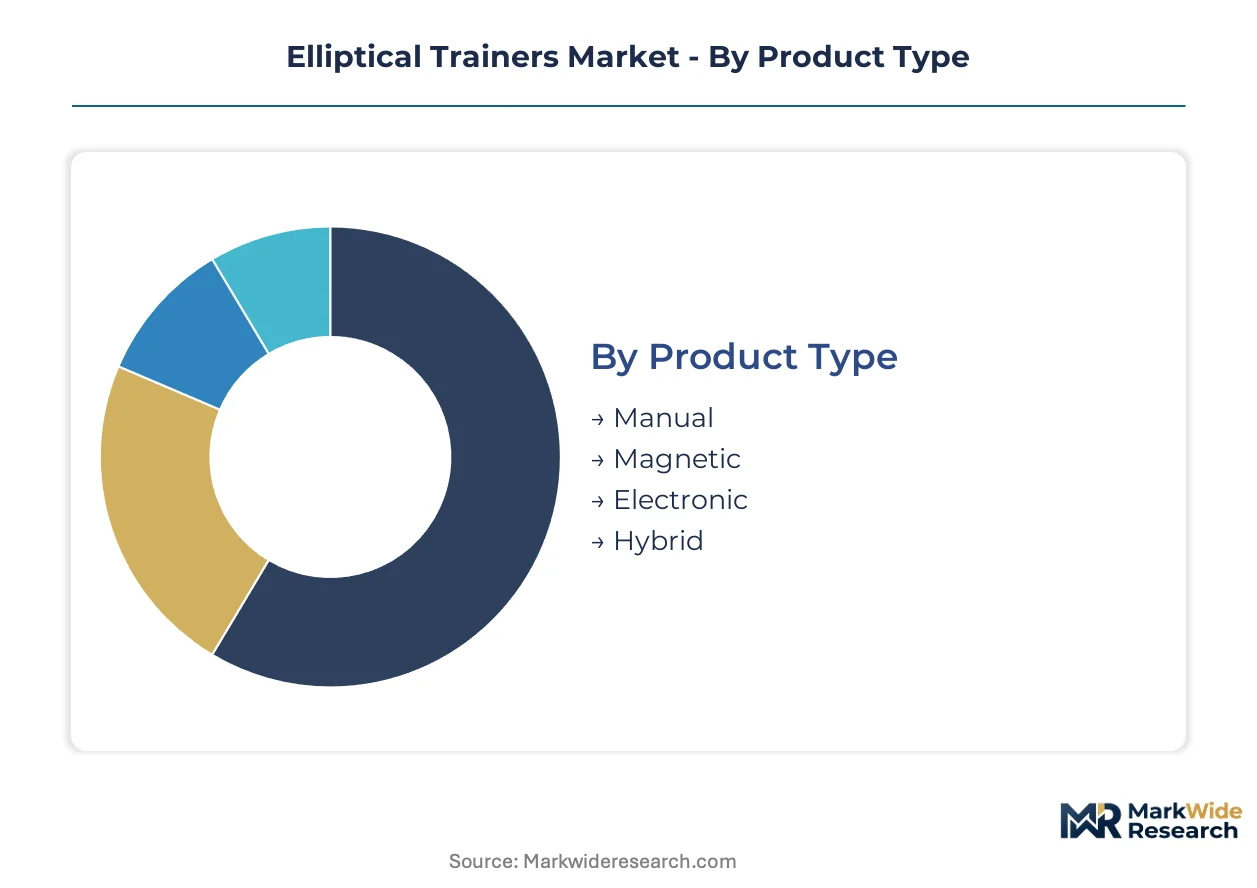
Elliptical trainer procurement patterns diverge sharply across use environments and technical specifications. Product differentiation now centers on connectivity infrastructure rather than mechanical performance alone.
Product Type:
Mature resistance technologies dominate installed capacity while emerging electronic variants capture premium replacement cycles.
- Magnetic:Silent-drive friction systems utilize eddy current braking with 15-30 pound flywheel masses for kinetic stability. Demand concentrates in United States multi-unit residential developments where noise ordinances constrain treadmill alternatives, with commercial gym chains prioritizing these units for 24-hour facility operations.
- Electronic:Motorized resistance modulation enables programmatic incline and adaptive workload algorithms through console-integrated firmware. Boutique fitness studios in California and New York are retrofitting fleets with these systems to support heart-rate-variability coaching protocols.
- Manual:Friction-brake systems with mechanical tension dials serve budget residential segments and institutional procurement with limited electrical infrastructure.
- Hybrid:Combined magnetic and air-resistance architectures support high-intensity interval training protocols for performance-oriented commercial facilities.
Magnetic trainers retain volume leadership; Electronic variants hold the steepest expansion curve.
End User:
Customer type determines durability specifications and service contract structures across procurement channels.
- Commercial Gyms:Heavy-gauge steel frame construction with 5-7 year service life ratings supports high-frequency usage patterns. United States franchise operators are standardizing on connected equipment with API compatibility for member usage tracking.
- Residential:Folding frame designs with transport wheels address space constraints in urban apartments. Direct-to-consumer brands are capturing share through virtual assembly assistance and modular shipping formats.
- Fitness Centers:Corporate wellness programs and university recreation facilities drive institutional procurement with centralized fleet management requirements.
- Rehabilitation Facilities:Low-impact cardiovascular protocols for joint-prescription exercise regimens are expanding clinical adoption with bidirectional stride capability and zero-impact start mechanisms.
Commercial Gyms dominate absolute unit demand; Rehabilitation Facilities are expanding most quickly.
Technology:
Power architecture and connectivity infrastructure segment pricing tiers and margin structures.
- Smart Trainers:Embedded touchscreen consoles with Wi-Fi connectivity and Bluetooth sensor pairing enable third-party app synchronization and subscription revenue bundling. FCC certification requirements for wireless-enabled devices shape United States market entry timelines.
- Conventional Trainers:LCD display units with fixed programming and no external connectivity serve price-sensitive institutional procurement and basic residential needs.
- Battery-Powered:Self-contained electrical systems eliminate outlet dependency for facility flexibility and outdoor deployment scenarios.
- Plug-in:AC-powered consoles with continuous electrical supply support motorized resistance and high-brightness display requirements for commercial environments.
Conventional Trainers retain installed base dominance; Smart Trainers are gaining share fastest.
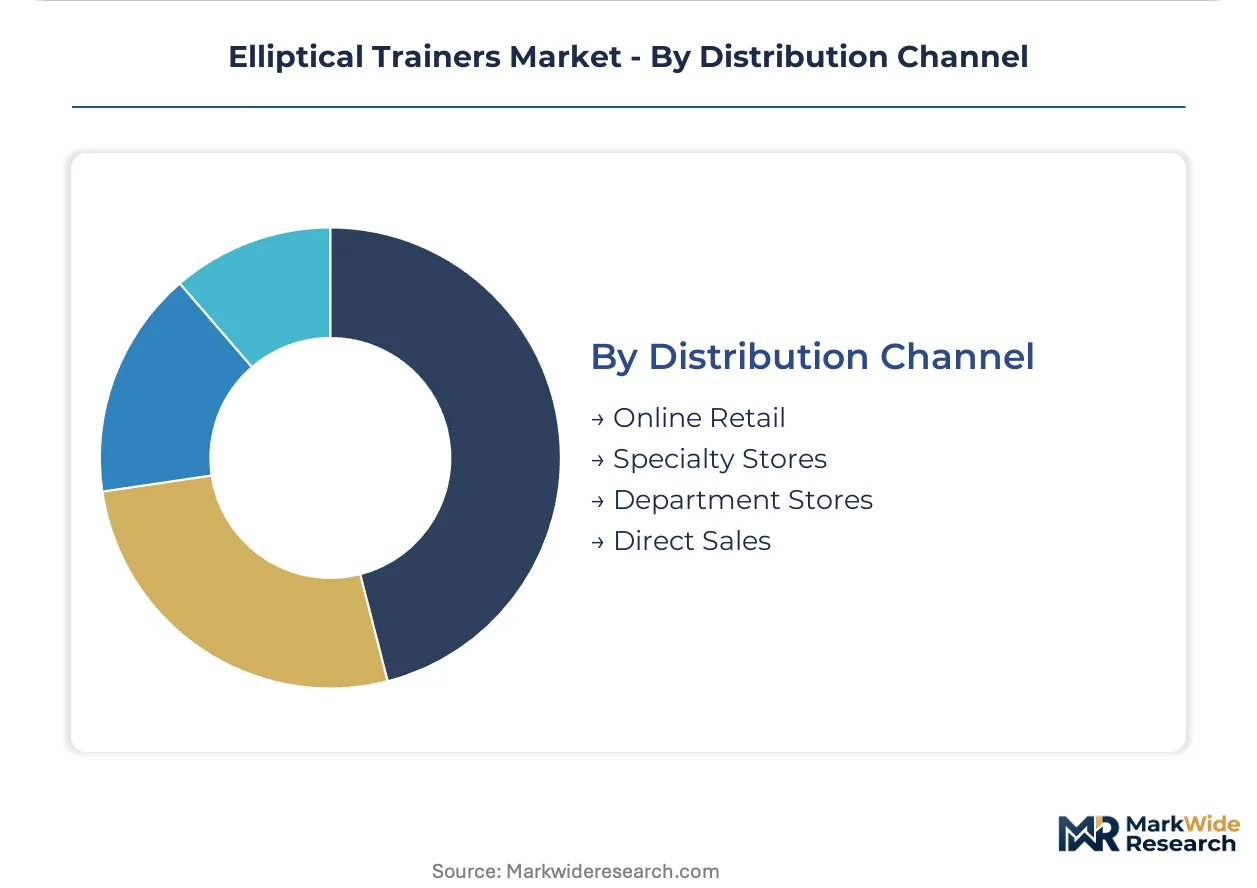
Distribution Channel:
Channel economics determine assembly support requirements and warranty servicing structures.
- Online Retail:E-commerce platforms with virtual setup assistance and return logistics are displacing specialty store foot traffic for residential purchases. Amazon and direct-to-consumer brand sites are capturing United States metro market growth.
- Specialty Stores:Physical showrooms with test-ride facilities and white-glove delivery services sustain premium positioning for high-end magnetic and electronic models.
- Department Stores:Mass-market retail placement serves entry-level manual and basic magnetic units with limited service bundling.
- Direct Sales:Manufacturer-owned channels with captive installation crews support commercial gym and fitness center fleet procurement with extended service contracts.
Online Retail is climbing the fastest; Direct Sales retains commercial contract concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports elliptical trainer components and finished units to North American and European buyers, establishing the dominant trade-flow corridor for this equipment category. Manufacturing clusters in coastal provinces supply frame assemblies and electronic resistance systems to brand owners abroad.
United States
Boutique fitness studios in California and New York drive premium equipment procurement with heart-rate-variability coaching requirements. FCC certification mandates for wireless-enabled trainers shape market entry timelines for connected models. Corporate wellness programs in Texas and Illinois expand institutional purchase volumes for commercial-grade units with usage tracking capabilities.
Germany
Commercial gym chains prioritize energy-efficient models to preempt operational cost penalties under standby power regulations. CE marking under the Machinery Directive and REACH substance restrictions on handlebar coatings add formulation complexity for imported equipment. Fitness infrastructure in Bavaria and North Rhine-Westphalia leads procurement of compliant smart trainer fleets.
China
Domestic metro fitness expansion in Shanghai and Shenzhen absorbs production from coastal manufacturing zones. MIIT standards for networked appliances and GB safety requirements frame product design for home-market distribution. Yangtze River Delta factories supply magnetic resistance systems and touchscreen consoles to global brand owners.
United Kingdom
Mid-market gym chains favor full-service leasing with bundled maintenance and software access aligned with property lease terms. Energy-efficiency labeling requirements for networked appliances extend to cardiovascular equipment with standby power draw above threshold limits. London and Southeast England concentrate fleet retrofit demand for API-compatible connected units.
India
Metro fitness infrastructure expansion in Mumbai and Delhi drives premium import brand penetration. BIS certification alignment creates standardized safety testing pathways for foreign manufacturers. Rehabilitation clinics in Karnataka and Maharashtra incorporate low-impact cardiovascular equipment for joint-prescription exercise regimens.
Elliptical Trainers Market Vendor Landscape
On the supply side, the industry is tiered between integrated wellness platform operators, specialized fitness equipment fabricators, and mass-market consumer brands. The upper tier commands pricing power through software subscription bundling and ecosystem lock-in. The middle tier competes on frame durability and service contract structures for institutional procurement. Dominant competitive moves include strategic partnerships with streaming content providers and backward integration into resistance system manufacturing.
Within the integrated platform tier, NordicTrack exemplifies the hardware-plus-subscription archetype through its captive streaming ecosystem. Technogym S.p.A occupies a position representing premium commercial positioning with integrated digital wellness infrastructure. Precor, Inc. anchors the institutional durability segment with extended service contract offerings for franchise operators. These three entities collectively illustrate how competitive boundaries now merge physical engineering with recurring software revenue streams.
| Leading Market Players |
|---|
| Precor, Inc. |
| Life Fitness |
| NordicTrack |
| Core Health & Fitness, LLC |
| Technogym S.p.A |
| Sole Fitness |
| Schwinn |
| Body-Solid Inc. |
| FreeMotion Fitness |
| Others |
Supply Flow & Price Mechanics
Undercapacity in Yangtze River Delta touchscreen console production is compressing supplier margins while amplifying pricing leverage for integrated platform operators who control captive component sourcing. This utilization asymmetry rewards manufacturers with backward integration into resistance system fabrication and penalizes pure-play assemblers exposed to spot-market electronics procurement.
Pricing Analysis
Current-generation smart trainers with embedded Wi-Fi connectivity and subscription bundling command substantial premiums over prior-generation LCD-console units and next-generation adaptive-resistance prototypes still in beta deployment. Three-tier pricing structure across premium, standard, and economy levels separates ecosystem-locked operators from durability-focused institutional vendors and mass-market consumer brands. Price differentiation hinges on FCC certification tier for wireless-enabled models and after-sales service bundling for commercial contracts. Pricing pressure stems from steel and aluminum commodity volatility squeezing frame fabrication margins. Budget residential segments exhibit highest price sensitivity; boutique fitness studios demonstrate lowest sensitivity due to member-experience differentiation priorities.
Supply Chain Analysis
Contract manufacturing concentration sits with Yangtze River Delta electronics assemblers and Taiwan-based touchscreen foundries holding capacity for console production. Geographic supply concentration centers on China for magnetic resistance systems and frame assemblies, Taiwan for display modules, and Vietnam for lower-complexity mechanical components. Raw material dependencies draw from Chinese steel mills for frame tubing, Malaysian rubber processors for belt drives, and South Korean battery cell suppliers for self-powered units. Tariff exposure on Chinese-imported electronics creates structural risk for US-bound finished goods. Distribution runs through direct-to-consumer e-commerce platforms capturing residential volume and manufacturer-direct sales forces serving commercial gym fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through mid-market gym chain consolidation in the United Kingdom and United States, where procurement committees now negotiate enterprise-wide equipment standards rather than facility-by-facility purchases. This aggregation pressures vendors to accept operational-expenditure leasing models and API-standardization demands.
For Market Incumbents: Entrench ecosystem lock-in through exclusive iFit-equivalent streaming content partnerships and proprietary sensor calibration protocols that raise switching costs for commercial operators. Deepen backward integration into magnetic resistance system manufacturing to offset steel input volatility and defend margin position against emerging direct-to-consumer brands with modular assembly logistics. Prioritize FCC pre-certification investment to accelerate product refresh cycles versus compliance-lagged competitors.
For New Entrants and Emerging Players: Pursue rehabilitation clinic integration in India and Germany where low-impact cardiovascular protocols are expanding clinical adoption with limited incumbent penetration. Target corporate wellness procurement channels in Texas and Illinois where employer-sponsored fitness stipends are expanding institutional volumes without entrenched supplier relationships. Deploy virtual setup assistance and modular shipping formats as primary go-to-market angle to bypass specialty retail footprint requirements.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart trainer sub-segments as firmware development and cloud infrastructure requirements displace pure mechanical engineering competencies. Long-term viability over the next decade favors platform operators with recurring subscription revenue anchoring hardware economics rather than transactional equipment vendors. Monitor API standardization adoption rates across United States franchise operators as inflection indicator for ecosystem winner-take-most dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Streaming Platform Integration | NordicTrack's iFit bundling demonstrates recurring revenue anchoring hardware margin compression. |
| Magnetic Resistance Backward Integration | In-house eddy current system production insulates Precor from commodity steel volatility. |
| Rehabilitation Channel Partnership | Technogym's clinical protocol integration in German physical therapy clinics expands addressable market. |
| Direct-to-Consumer Logistics Investment | Virtual assembly assistance and modular shipping formats open geographic markets beyond specialty retail. |
| Energy-Efficiency Certification Preemption | Early CE marking alignment for standby power compliance secures German gym chain procurement preference. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with commercial gym procurement directors, fitness equipment maintenance engineers, rehabilitation clinic program managers, and direct-to-consumer brand operations executives; and secondary validation through SEC 10-K filings of listed equipment manufacturers, FCC equipment authorization databases, EU CE marking registries under the Machinery Directive, and trade flow data from Chinese customs authorities. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Forecast inputs considered resistance technology generation transitions, connectivity infrastructure adoption curves, and regional certification timeline differentials across the projection horizon. Segmentation dimensions modeled include product type, end-user environment, power architecture, and distribution channel, with additional granularity on smart trainer versus conventional trainer technology splits. CAGRs derived from logistic diffusion curves fitted to historical replacement cycle data and projected subscription bundling penetration. Industry-specific inputs incorporated steel commodity index trajectories and REACH substance restriction compliance cost escalations.
Macroeconomic conditions sit as an overlay; deviation in commercial real estate construction cycles and employer wellness benefit allocation would shift the trajectory. Forecasts reflect documented assumptions on replacement cycle compression rates and wireless certification pathway streamlining. Quarterly review of FCC equipment authorization backlogs and German fitness chain procurement specifications is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Gymnastic Springboard Market
Fitness Equipment
Ergometer Market
Fitness Equipment
Elliptical Market
Fitness Equipment
Treadmill Desks Market
Fitness Equipment
BMI Machine Market
Fitness Equipment
Europe Refurbished Fitness Equipment Market
Fitness Equipment
Home Fitness Equipment Market
Fitness Equipment
Weight Training Benches Market
Fitness Equipment
Fitness Ball Market
Fitness Equipment
Smart Scales Market
Fitness Equipment
Home Fitness Market
Fitness Equipment
Push-Up Board Market
Fitness Equipment
North America Fitness Rings Market
Fitness Equipment
Lateral Fitness Equipment Market
Fitness Equipment
Strength Training Equipment Market
Fitness Equipment
Belt Trainers Market