
 Indonesia Payments Infrastructure Market | 2026-2036
Indonesia Payments Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Payments Infrastructure Market Foresight
Digital tokenization is rebalancing economics across Indonesia's payment stack as card-present infrastructure yields to software-centric acceptance. Xendit leverages API-first architecture to embed payments into MSME workflows across the archipelago. Bank Negara Indonesia anchors wholesale settlement capacity through its participation in BI-FAST and national clearing systems. GoPay competes by controlling rider and driver liquidity loops within Gojek's super-app ecosystem.
Indonesia payments infrastructure encompasses the hardware, software, protocols, and settlement systems enabling monetary exchange between consumers, merchants, and financial institutions, with specifications including ISO 20022 messaging compatibility, PCI-DSS Level 1 certification thresholds, and sub-three-second transaction latency for real-time gross settlement. The primary commercial purpose is reducing friction in a cash-dominant economy where over seventy percent of adults remain underbanked or thin-filed. Mobile wallets and QR code payments command structural momentum as Bank Indonesia's QRIS mandate collapses fragmented proprietary codes into a single interoperable standard, while online payment gateways capture margin pools from cross-border e-commerce settlement complexity. POS systems retain relevance in physical retail but face compression as smartphone-based acceptance displaces dedicated terminal deployments.
Bank Indonesia governs payment system oversight through QRIS standardization, BI-FAST real-time infrastructure mandates, and electronic money licensing frameworks that dictate capital reserves and interoperability obligations. The Financial Services Authority (OJK) shapes non-bank payment institution governance through fit-and-proper testing and consumer protection rules, while the Ministry of Communication and Informatics enforces data localization requirements under its electronic system operator regulations. Stakeholders must monitor how BI-FAST volume thresholds and QRIS merchant tiering will redistribute profitability between banks and fintech aggregators as the infrastructure layer commoditizes.
Market Dynamics
Bank Indonesia's QRIS standardization mandate is compressing fragmented payment rails into a single interoperable layer, redistributing margin pools from proprietary wallet ecosystems toward infrastructure-agnostic aggregators.
Growth Catalysts
- BI-FAST real-time settlement rails:Bank Indonesia's sub-three-second gross settlement infrastructure eliminates interbank friction. MSMEs access instant fund availability without correspondent banking delays.
- Java corridor merchant density:Greater Jakarta's transaction velocity concentrates infrastructure investment. Payment aggregators deploy QR acceptance at unit economics impossible in outer island provinces.
- Tokenization protocols:Software-centric card-present alternatives reduce hardware dependency. Cloud-native acceptance layers embed directly into merchant accounting workflows.
Market Restraints
- Last-mile connectivity gaps:Eastern Indonesia's fiber and 4G penetration deficits limit real-time payment reliability. Transaction timeouts degrade merchant trust outside Java-Sumatra corridors.
- Data localization mandates:Ministry of Communication and Informatics regulations require domestic server placement. Cross-border payment gateways face compliance cost escalation.
- Cash handling cost structures:Informal sector liquidity cycles resist digitization. Micro-merchant working capital requirements favor physical rupiah settlement.
Strategic Opportunities
- Eastern Indonesia archipelago penetration:Sulawesi, Maluku, and Papua provinces show sub-15% QRIS merchant coverage. First-mover aggregators capture unbanked consumer-to-business flows.
- Cross-border remittance corridor integration:ASEAN payment connectivity initiatives enable Indonesian worker remittance capture. Real-time settlement with Malaysia and Singapore reduces correspondent banking friction.
- Embedded finance convergence:API-native payment rails merge with inventory management and lending workflows. MSMEs access working capital tied directly to transaction history.
Industry Challenges
- ISO 20022 migration complexity:Financial institutions restructure legacy messaging stacks. Mid-tier banks face talent scarcity in structured data format implementation.
- PCI-DSS Level 1 certification timelines:Payment aggregators endure 12-18 month audit cycles. Compliance bottlenecks delay product launches and geographic expansion.
- Interoperability testing overhead:QRIS certification requires validation across 15+ wallet issuers. Integration costs burden smaller fintech entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Payments Infrastructure Market |
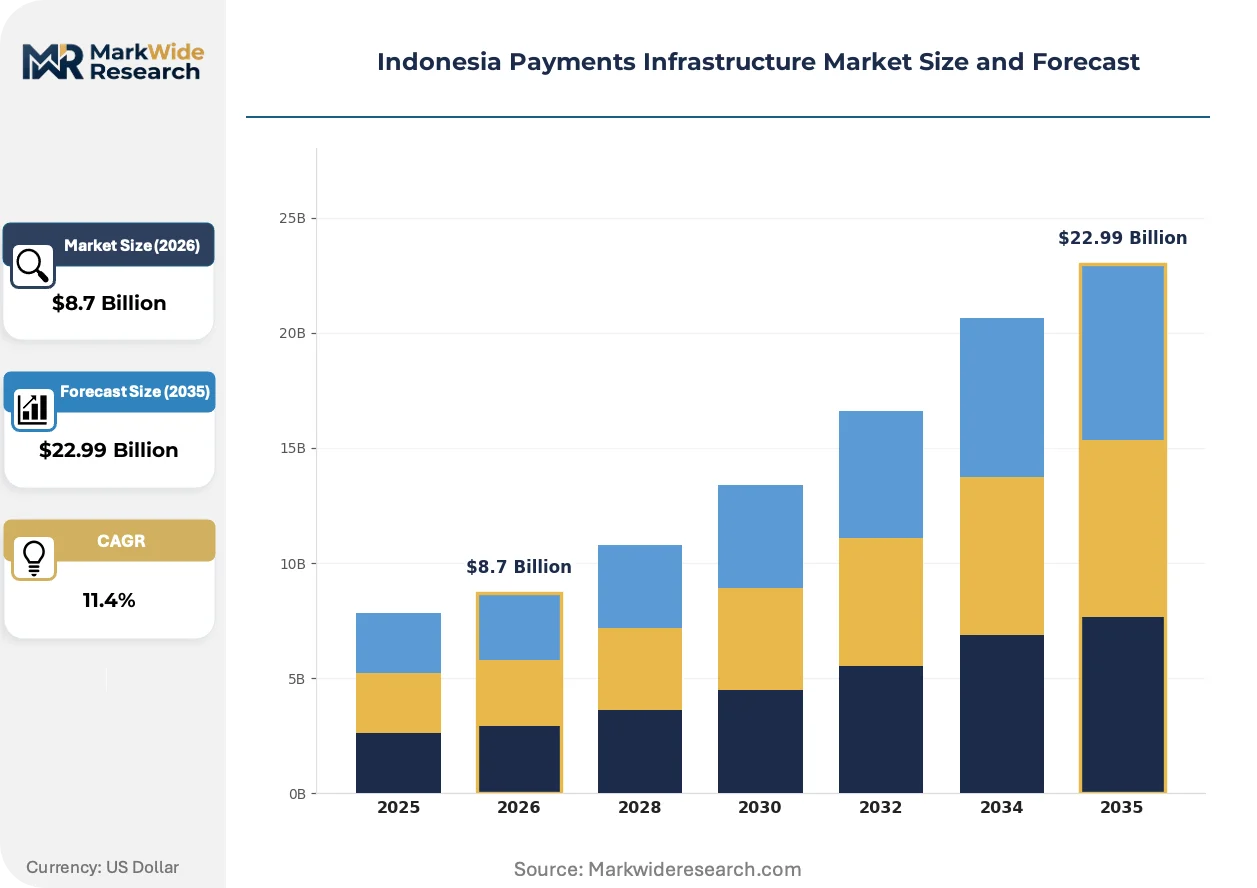
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Cards, Debit Cards, Mobile Wallets, Bank Transfers End User: Retail Sector, E-Commerce Platforms, Financial Institutions, Service Providers Technology: Contactless Payments, QR Code Payments, POS Systems, Online Payment Gateways Service Type: Payment Processing, Fraud Detection, Merchant Services, Compliance Solutions |
| Companies Covered | Xendit, Bank Negara Indonesia (BNI), GoPay (Gojek), PT Artajasa Pembayaran Elektronis, PT Finnet Indonesia, OVO, Bank Central Asia (BCA), Moka POS (GoTo Financial), DANA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Payments Infrastructure Market Shifts & Advancements
Software-defined payment acceptance is displacing dedicated terminal hardware across Indonesian commerce. Three converging developments are restructuring competitive positioning.
API-first payment orchestration is decentralizing infrastructure ownership away from banks toward embedded-finance platforms. MSMEs in Yogyakarta and Surabaya adopt smartphone-based acceptance faster than terminal deployment permits. Merchant acquirers compress hardware capital requirements while capturing transaction economics previously reserved for tier-one banks.
Bank Indonesia's QRIS merchant tiering framework stratifies compliance obligations by transaction volume. Small merchants face simplified know-your-customer thresholds. Large retailers absorb enhanced reporting requirements while gaining access to BI-FAST priority settlement windows.
Super-app ecosystems now bundle payment acceptance with logistics and inventory services. Gojek and Grab driver networks double as merchant onboarding agents. Rural penetration accelerates through gig-economy liquidity loops rather than traditional bank branch expansion.
Indonesia Payments Infrastructure Market Segmentation
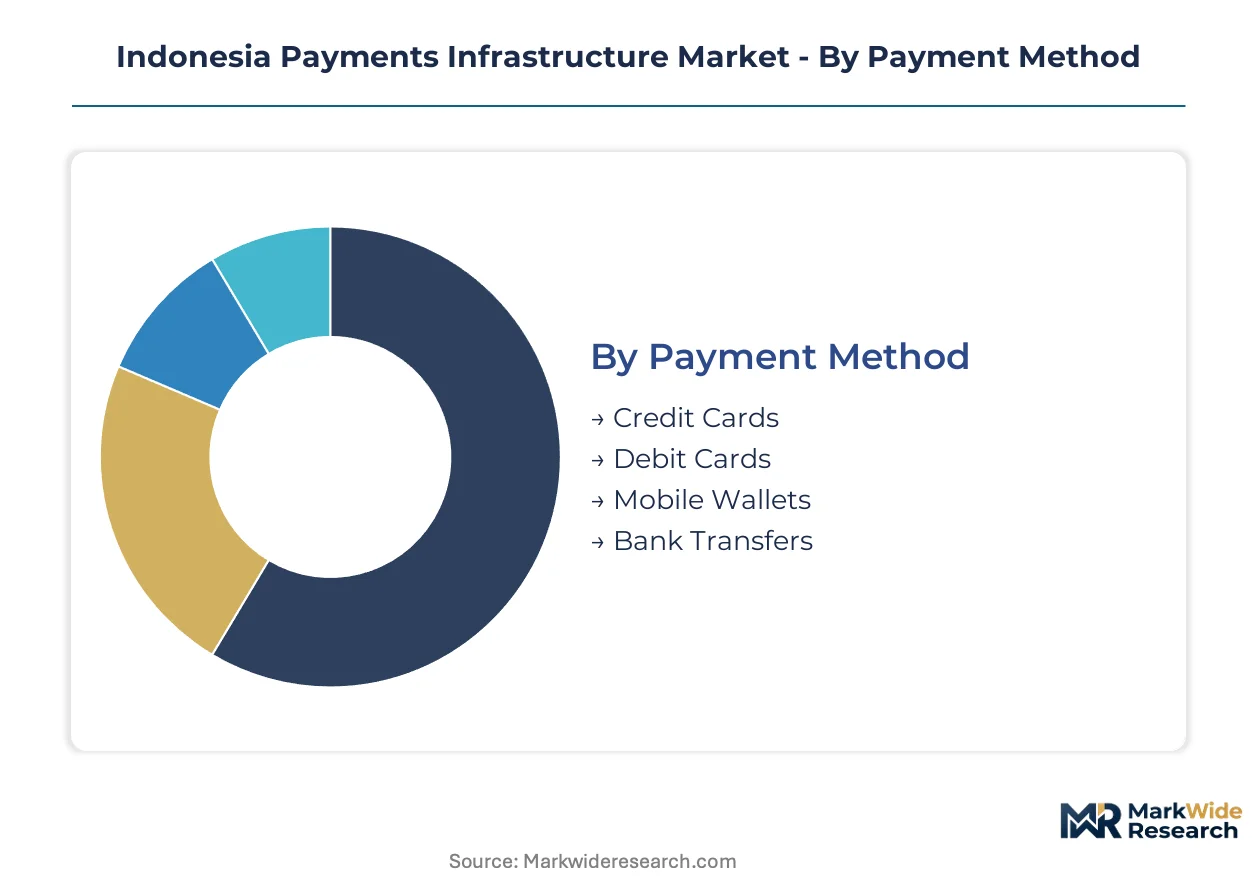
Payment infrastructure segmentation in Indonesia reveals how QRIS standardization and BI-FAST rails are redistributing transaction economics across method, user, and technology layers. Distinct deployment patterns emerge between Java's merchant-dense corridors and outer island provinces where cash still dominates settlement cycles.
Payment Method:
Volume concentration favors low-friction, low-acquisition-cost instruments, while premium economics attach to instruments with embedded credit or cross-border capability.
- Credit Cards:Revolving credit instruments with PCI-DSS Level 1 certification thresholds and 3D Secure authentication protocols. Demand clusters with large retailers in Greater Jakarta seeking installment financing and loyalty program integration. Bank Indonesia's interchange caps compress issuer margins while preserving acceptance infrastructure investment.
- Mobile Wallets:Stored-value accounts linked to phone numbers and QRIS interoperability standards. Penetration accelerates among MSMEs in Surabaya and Bandung where smartphone acceptance displaces terminal hardware. GoPay and OVO compete through super-app ecosystem lock-in rather than standalone wallet features.
- Debit Cards:Direct-linked bank account instruments with EMV chip compliance and domestic-only settlement rails. Rural bank branches in Central Java push debit adoption as first formal payment instrument for agricultural value chains.
- Bank Transfers:Account-to-account settlement through BI-FAST real-time gross settlement or legacy batch clearing. Corporate treasury operations in Jakarta favor instant confirmation for supplier payments above QRIS transaction limits.
Mature deployment sits with credit cards at tier-one merchants with established acquiring relationships. Newer deployment is concentrated in mobile wallets penetrating micro-merchant segments previously excluded from formal acceptance infrastructure.
End User:
Merchant scale and transaction velocity dictate infrastructure requirements, with tiered service levels separating high-frequency from occasional acceptance needs.
- Retail Sector:Physical merchant locations spanning modern trade hypermarkets to traditional market stalls. Modern retail in Jakarta's mall corridors demands multi-acquirer redundancy and sub-second authorization latency. Wet market vendors in Yogyakarta adopt QRIS through agent-assisted onboarding rather than direct bank relationships.
- E-Commerce Platforms:Digital-native merchants requiring payment gateway integration, escrow services, and cross-border settlement rails. Marketplace operators in Tangerang and Bekasi embed payment orchestration APIs directly into seller dashboards.
- Financial Institutions:Banks and non-bank payment institutions requiring wholesale settlement access, liquidity management tools, and regulatory reporting infrastructure. Regional banks outside Java prioritize BI-FAST connectivity over proprietary payment system development.
- Service Providers:Utility companies, telecommunications operators, and government agencies collecting recurring payments. State electricity utility PLN's bill payment volume drives infrastructure investment into automated debit and mobile collection channels.
Transaction density peaks with e-commerce platforms processing millions of daily events. Physical retail expansion is climbing the fastest as QRIS merchant tiering reduces onboarding friction for sub-scale operators.
Technology:
Hardware dependency versus software flexibility defines competitive positioning, with cloud-native layers capturing margin from legacy terminal deployments.
- QR Code Payments:Static and dynamic barcode standards under Bank Indonesia's QRIS interoperability mandate. Merchant acquisition costs collapse to near-zero as smartphones replace dedicated terminals. Street vendors in Surabaya's food corridors convert cash customers through zero-hardware acceptance.
- Contactless Payments:NFC-enabled card and device taps with sub-500 millisecond transaction completion. Transit operators in Jakarta's MRT and commuter rail networks drive tap-to-pay habit formation for daily mobility spending.
- POS Systems:Dedicated terminal hardware with integrated receipt printing, cash drawer control, and inventory management. Modern trade retailers in Bali and Lombok retain terminal preference for multi-payment-method consolidation and chargeback documentation.
- Online Payment Gateways:API-hosted checkout layers handling tokenization, 3D Secure routing, and multi-acquirer failover. SaaS merchants in Bandung's creative economy cluster demand gateway flexibility across domestic and ASEAN cross-border settlement.
Terminal-heavy POS systems anchor established retail footprints. QR code infrastructure is expanding most quickly through smartphone-native merchant segments.
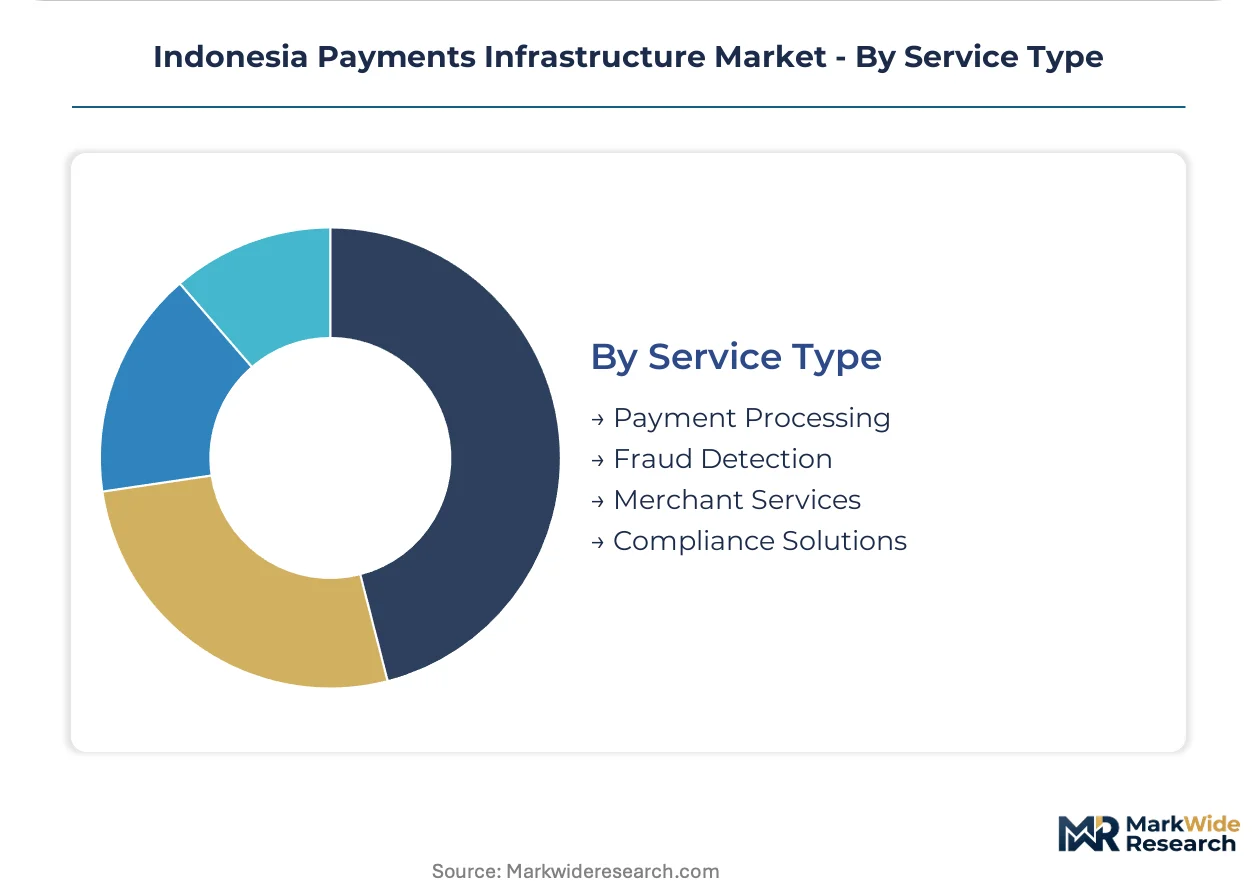
Service Type:
Value-added services attach to transaction flow economics, with compliance and security layers commanding premium pricing relative to commodity processing.
- Payment Processing:Core authorization, clearing, and settlement orchestration across multiple payment rails. Aggregators like Xendit compete on API latency and developer experience rather than processing margins alone.
- Fraud Detection:Real-time transaction scoring, device fingerprinting, and behavioral biometrics. E-commerce platforms face chargeback liability pressure driving investment into machine learning-based risk engines.
- Merchant Services:Onboarding, settlement reconciliation, and working capital advances tied to transaction history. MSME lending in East Java leverages payment data as credit scoring input for thin-file merchants.
- Compliance Solutions:KYC automation, AML transaction monitoring, and regulatory reporting infrastructure. OJK's fit-and-proper requirements for payment institutions create sustained demand for outsourced compliance technology.
Commodity processing dominates transaction volume. Fraud detection services are gaining share fastest as real-time payment rails eliminate chargeback recovery windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kawasan Ekonomi Khusus (KEK) incentives in Batam and Bintan anchor payment infrastructure investment outside Java. These zones compress hardware import duties and accelerate cross-border settlement licensing. Merchant acquirers deploy QRIS terminals through tax-advantaged distribution hubs serving Sumatra and Kalimantan corridors.
Java
Greater Jakarta's transaction velocity concentrates BI-FAST server capacity and QRIS merchant tiering implementation. Bank Indonesia's real-time settlement mandates prioritize fiber redundancy across the Jakarta-Bandung-Surabaya corridor. Fintech aggregators embed payment APIs into MSME accounting workflows in Yogyakarta's creative economy cluster.
Sumatra
Medan's cross-border trade with Malaysia and Singapore drives demand for multi-currency payment gateways. Bank Indonesia's ASEAN payment connectivity initiatives reduce correspondent banking friction for palm oil exporters. QRIS penetration accelerates through agent networks in Palembang's manufacturing zones.
Sulawesi
Makassar's port logistics and nickel processing corridors require instant settlement for supplier chains. Last-mile 4G deficits in Central Sulawesi limit real-time payment reliability outside urban cores. Payment aggregators partner with telecommunications operators to compress connectivity gaps in Gorontalo's fisheries value chains.
Kalimantan
East Kalimantan's new capital zone (IKN) construction triggers demand for corporate treasury and bulk payment infrastructure. Bank Indonesia's BI-FAST expansion targets sub-three-second settlement for government contractor payments. Samarinda's coal logistics hubs adopt QRIS for driver wage disbursement and fuel station networks.
Papua
Jayapura's isolation from fiber backbones forces satellite-dependent payment routing with elevated latency. Central government social program disbursements drive mobile wallet adoption in Merauke's agricultural settlements. Payment infrastructure investment concentrates on BI-FAST connectivity to Timika's mining operations.
Indonesia Payments Infrastructure Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with API-native platforms capturing margin from legacy terminal deployers. The market structures around three tiers: bank-owned payment rails with BI-FAST connectivity, fintech aggregators with developer-centric orchestration layers, and super-app ecosystems controlling closed-loop liquidity. Strategic moves concentrate on QRIS certification velocity and embedded finance API partnerships.
Among Indonesia-based payment infrastructure providers, Xendit, Bank Negara Indonesia, and GoPay occupy distinct archetype positions. Xendit exemplifies the API-first aggregator model embedding acceptance into software workflows. Bank Negara Indonesia anchors wholesale settlement capacity through central bank infrastructure participation. GoPay represents super-app ecosystem lock-in, leveraging driver and merchant networks for rural penetration.
| Leading Market Players |
|---|
| Xendit |
| Bank Negara Indonesia (BNI) |
| GoPay (Gojek) |
| PT Artajasa Pembayaran Elektronis |
| PT Finnet Indonesia |
| OVO |
| Bank Central Asia (BCA) |
| Moka POS (GoTo Financial) |
| DANA |
| Others |
Supply & Pricing Matrix
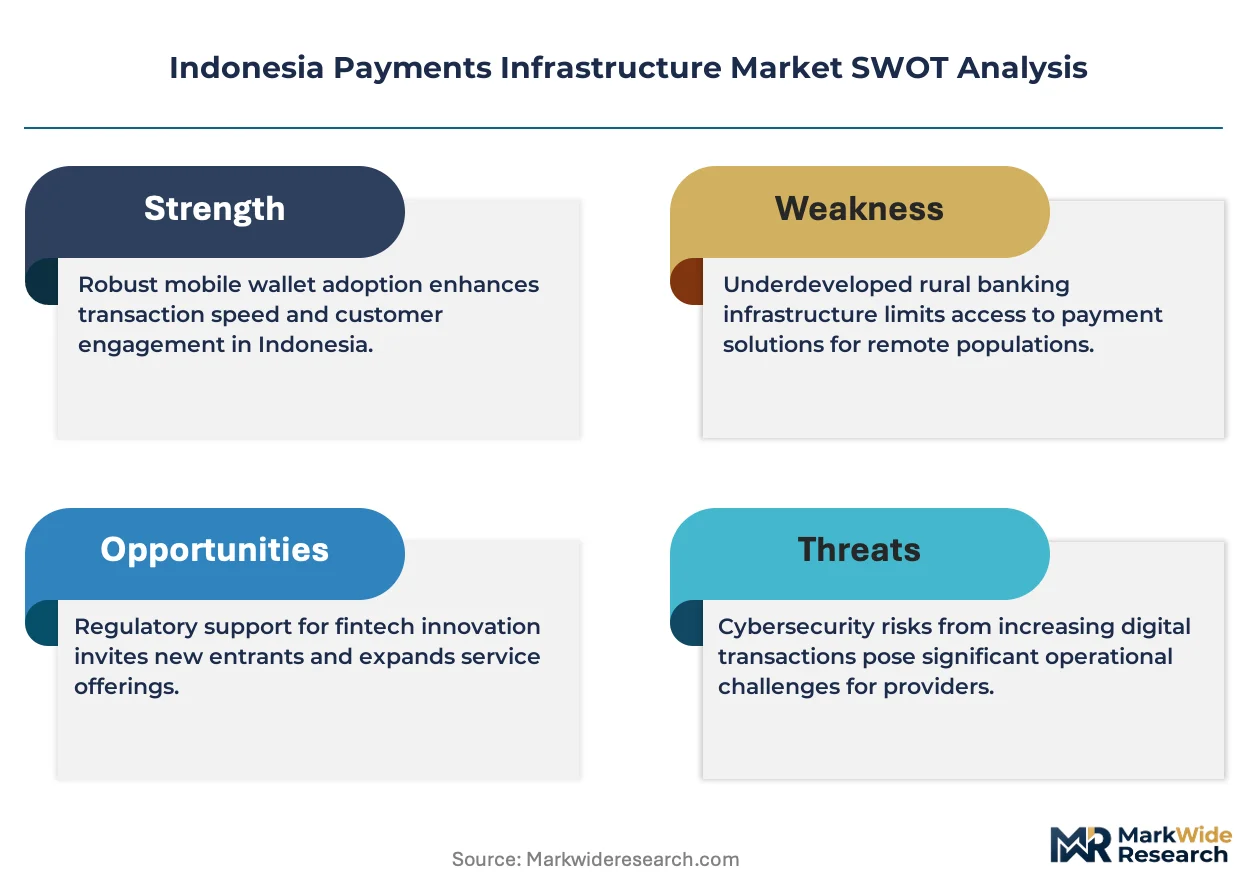
Bank Indonesia's data localization mandate gates qualified supply access and premium-tier pricing eligibility for cross-border payment gateways. Compliance cost escalation separates domestic server-deployed operators from margin-compressed entrants facing licensing delays.
Pricing Analysis
Short lead-time certification for QRIS interoperability commands premium pricing from aggregators serving Jakarta's high-velocity merchant corridors. Three-tier pricing structure across premium, standard, and economy levels stratifies by transaction volume thresholds and settlement speed guarantees. Price differentiation hinges on PCI-DSS certification grade and BI-FAST priority window access. Margins are tightening in the standard tier due to aggregator saturation in Java, while micro-merchant segments show highest price sensitivity to hardware-free onboarding costs.
Supply Chain Analysis
Workforce availability constraints in Shenzhen, Taipei, and Singapore shape terminal hardware and semiconductor sourcing timelines for Indonesian payment deployers. Cloud infrastructure draws from AWS Singapore, Google Cloud Jakarta, and Alibaba Cloud availability zones. Supply chain risk centers on single-source vulnerability for EMV chip modules and NFC antenna components. Distribution runs through Batam's KEK tax-advantaged logistics hubs before final-mile agent networks in Sumatra and Sulawesi.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a consolidation play. BI-FAST volume thresholds and QRIS certification complexity are forcing sub-scale aggregators toward exit or acquisition.
For Market Incumbents: Extend API-native orchestration layers into embedded finance workflows across Yogyakarta and Surabaya MSME clusters. Deepen vertical integration through captive BI-FAST settlement capacity to defend against fintech challengers. Prioritize PCI-DSS Level 1 certification investment as a competitive moat against mid-tier bank entrants. For New Entrants and Emerging Players: Launch via super-app ecosystem partnerships targeting Gorontalo fisheries and Merauke agricultural corridors where agent-assisted onboarding outperforms direct bank relationships. White-space concentration sits with Sulawesi and Papua provinces showing sub-15% QRIS merchant coverage. Go-to-market leverage rests on telecommunications operator co-deployment for 4G-dependent real-time settlement. For Investors and Strategic Acquirers: OJK fit-and-proper enforcement waves are the leading indicator that compliance-technology bundled aggregators will command acquisition premiums. Long-term viability favors API-first platforms with ISO 20022 migration capability and regional bank BI-FAST connectivity partnerships. Target acquisition archetype: mid-tier aggregators with QRIS certification velocity and East Java merchant density.| Strategic Initiative | Industry Significance |
|---|---|
| BI-FAST Connectivity Expansion | Real-time settlement access anchors wholesale payment rail participation for regional banks. |
| QRIS Certification Acceleration | Interoperability validation across 15+ wallet issuers compresses merchant onboarding friction. |
| Embedded Finance API Integration | Payment-data-driven working capital advances deepen MSME wallet share in Surabaya clusters. |
| Data Localization Compliance | Domestic server placement satisfies Ministry of Communication and Informatics mandates for cross-border gateways. |
| Eastern Indonesia Agent Network Buildout | Telecommunications partnerships bridge 4G gaps in Sulawesi and Papua merchant corridors. |
Research Methodology
Bank Indonesia regulatory filings, OJK payment institution licensing databases, and BI-FAST transaction volume disclosures formed the secondary backbone. Primary interviews with payment infrastructure CTOs, merchant acquirer business development heads, and regional bank digital transformation officers combined with bottom-up and top-down triangulation. Trade data from Indonesia's Ministry of Communication and Informatics and ASEAN payment connectivity initiative reports provided cross-border settlement context.
Bottom-up modeling aggregated merchant tier transaction volumes and QRIS penetration rates by province. Top-down validation cross-checked against Bank Indonesia electronic money licensing trends and BI-FAST infrastructure deployment timelines. Segmentation dimensions spanned payment method, end-user vertical, technology layer, and service type. CAGRs derived from volume trajectory analysis across Java corridor density and outer island expansion phases. Forecast inputs incorporated QRIS merchant tiering adoption curves and real-time settlement rail saturation thresholds.
Regulatory enforcement intensity shifts, BI-FAST technical outage frequency, and QRIS interoperability revision cycles are the dominant revision risks. Forecasts reflect assumptions around infrastructure deployment timelines and merchant onboarding velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Argentina Mobile Wallet Market
Payments
Proximity Payment Market
Payments
Telecom Cloud Billing Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Sweden Payments Market
Payments
Australia Buy Now Pay Later Services Market
Payments
South Africa Real Time Payments Market
Payments
North America Mobile Payments Market
Payments
Global Telecom Billing Market
Payments
China Payment Gateway Market
Payments
United States Payments Market
Payments
Latin America Mobile Payment Market
Payments
UAE POS Terminal Market
Payments
North America Payments Market
Payments
Transit Cards Market
Payments
Contactless Payment Market