
 Asia Pacific Video Streaming Market | 2026-2036
Asia Pacific Video Streaming Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Video Streaming Market Insights
India's BIS streaming quality standards is decoupling low-latency infrastructure from premium content tiers. Tencent Holdings Limited anchors its competitive edge through captive cloud infrastructure across Greater China. Netflix Inc. navigates fragmented licensing regimes by producing original regional content. Amazon.com Inc. leverages Prime bundling to sustain subscriber retention in price-sensitive South Asian markets.
Asia Pacific video streaming denotes the digital distribution of audiovisual content via internet protocol networks, typically encoded through adaptive bitrate protocols such as H.264 or HEVC to maintain playback continuity across variable bandwidth conditions. The technology serves both consumer entertainment consumption and enterprise communications, with latency tolerance ranging from sub-three seconds for live sports to thirty-plus seconds for on-demand catalog viewing. Subscription-based platforms dominate revenue pools, while ad-supported models capture the fastest user growth among price-sensitive demographics in Indonesia and Vietnam. Smartphone viewing leads device-level engagement, though smart TV installations accelerate in South Korean and Australian households where fixed broadband penetration supports 4K throughput.
Japan's MIC enforces content localization quotas that shape catalog composition for foreign entrants, while Australia's ACMA applies media concentration rules to streaming mergers. China's SAMR and NRTA jointly regulate cross-border content licensing, creating compliance barriers for platforms without domestic partnerships. Stakeholders must weigh regulatory fragmentation against platform scale economics when prioritizing market entry sequences across the region.
Market Dynamics
India's BIS streaming quality standards are forcing infrastructure reinvestment across Southeast Asian markets, decoupling low-latency delivery from premium subscription tiers and compressing margin structures for platforms serving price-sensitive demographics.
Growth Catalysts
- Mobile-first consumption:Smartphone viewing dominates engagement in Indonesia and Vietnam, where fixed broadband penetration remains limited. Platforms optimize adaptive bitrate protocols for variable cellular bandwidth.
- TRAI's net neutrality framework:India's telecom regulator prevents throttling of video traffic, preserving quality-of-service guarantees for streaming providers without tiered access fees.
- Cloud infrastructure localization:Captive data center buildouts in Singapore and Mumbai reduce transit costs and improve edge delivery performance for live sports broadcasts.
Market Restraints
- Content licensing fragmentation:China's SAMR and NRTA jointly regulate cross-border licensing, creating compliance barriers for platforms without domestic partnerships.
- Input cost volatility:CDN transit fees fluctuate with submarine cable capacity constraints across the Pacific, squeezing margin for independent platforms without scale.
- Technical limitation:HEVC codec licensing costs deter adoption in budget smartphone segments, locking lower-tier markets into H.264 efficiency ceilings.
Strategic Opportunities
- Enterprise communications:Indian ed-tech platforms drive B2B adoption of streaming infrastructure for remote training and corporate communications.
- Regulatory tailwind:Australia's ACMA media concentration rules create acquisition opportunities for mid-tier platforms seeking scale through merger clearance.
- Technology convergence:Edge computing integration with 5G networks in South Korea enables sub-second latency for interactive live commerce broadcasts.
Industry Challenges
- Localization talent scarcity:Japan's MIC content quotas require native-language dubbing and subtitling at scale, straining regional production capacity.
- Legacy system integration:Established broadcasters migrating to IP-based delivery face friction reconciling SDI workflows with cloud-native architectures.
- Certification timelines:BIS equipment approval processes delay smart TV and set-top box launches, compressing hardware refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Video Streaming Market |
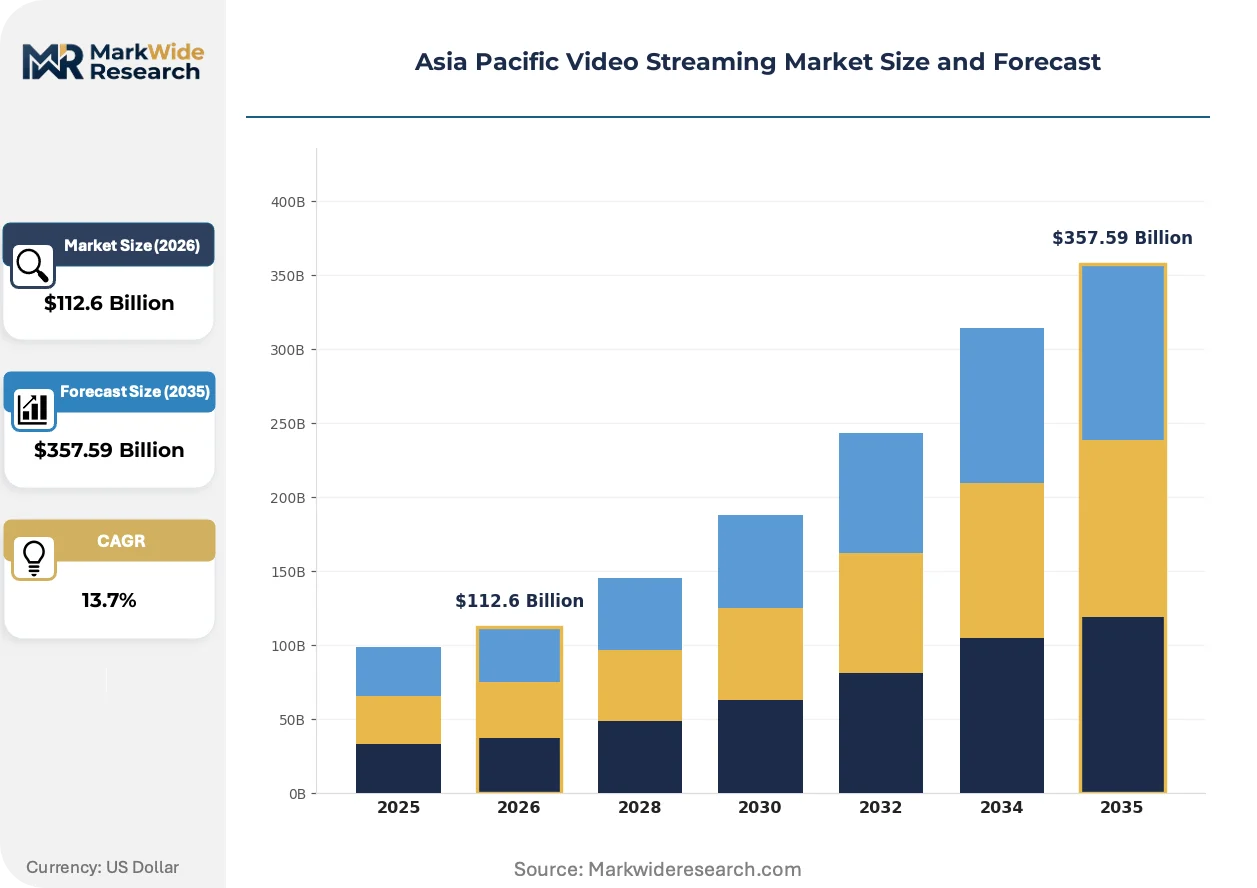
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $357.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Subscription-Based, Ad-Supported, Transactional Video On Demand, Hybrid Content Genre: Drama, Comedy, Documentary, Sports Device Type: Smartphones, Smart TVs, Tablets, Laptops End User Segment: Millennials, Generation Z, Families, Seniors |
| Companies Covered | Baidu Inc., Akamai Technologies, Amazon.com Inc., Kaltura Inc., Brightcove Inc., Google LLC, Netflix Inc., U-Next, Tencent Holdings Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Video Streaming Market Trends and Innovations
Compression of latency tolerance thresholds is redrawing competitive boundaries across the Asia Pacific video streaming landscape, with live sports and interactive formats demanding infrastructure investments that on-demand catalog businesses can defer.
AV1 codec deployment is absorbing capital from HEVC migration roadmaps as patent royalty uncertainty deters licensing commitments. Mid-tier platforms in Thailand and Malaysia are adopting AV1 for mobile-optimized streams to avoid per-device fees. This shift is absorbing engineering resources that would otherwise target 4K bitrate efficiency gains.
Japan's MIC localization quotas are reshaping content acquisition strategies for foreign entrants, mandating minimum ratios of dubbed or subtitled domestic programming. Studios in Tokyo and Osaka are expanding capacity to meet platform procurement volumes. Korean and Australian platforms are responding by pre-commissioning regional productions to satisfy quota requirements without catalog gaps.
Subscription fatigue among urban millennials is fragmenting wallet share across multiple niche services rather than consolidating on flagship platforms. Ad-supported tiers in Indonesia and the Philippines are capturing churned subscribers who reject recurring fees. This rotation is most visible in Jakarta and Manila, where free-to-view models now account for the majority of new user acquisitions.
Asia Pacific Video Streaming Market Segmentation
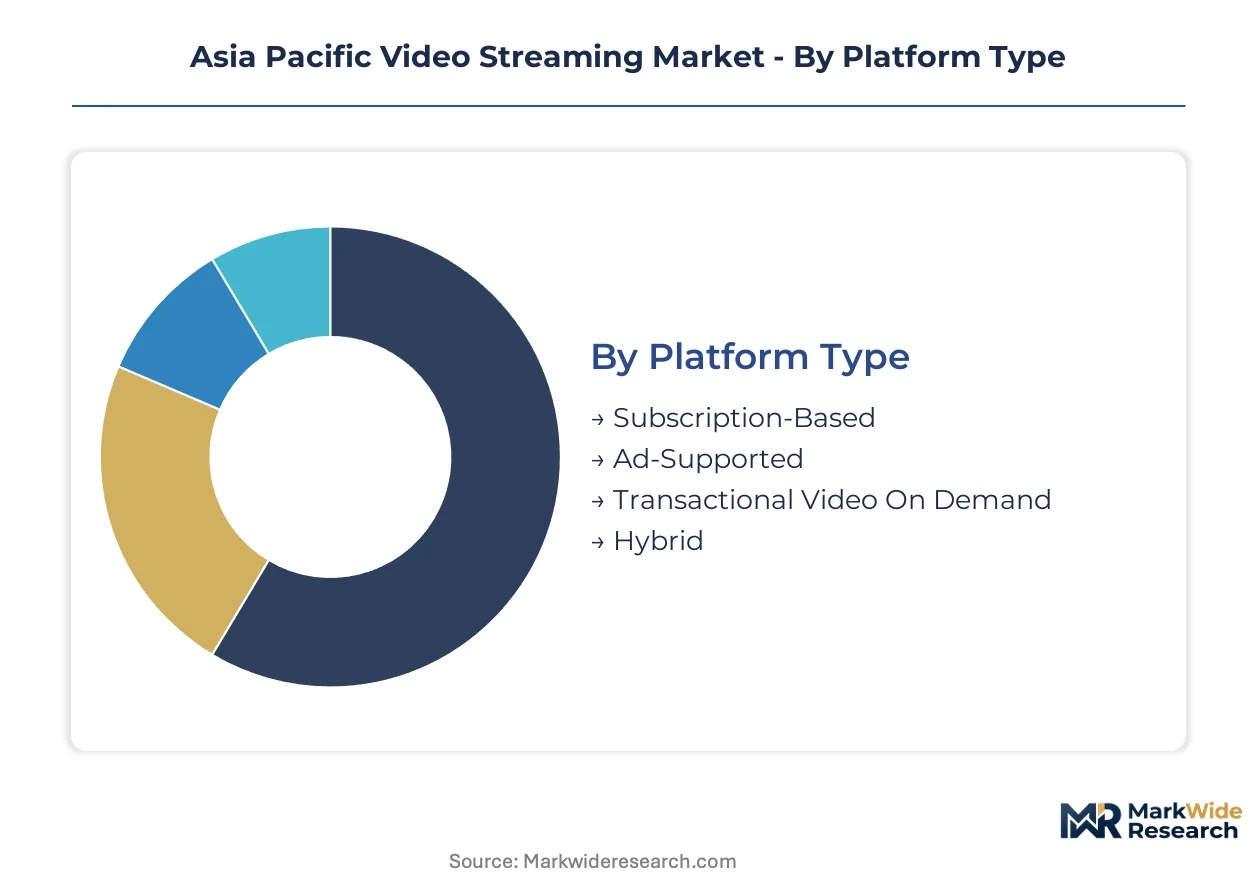
Platform architecture and viewing modality choices determine infrastructure capex requirements and monetization elasticity across Asia Pacific's heterogeneous connectivity landscape. Content genre concentration shapes localization spend and regulatory exposure. Device and demographic targeting calibrates codec selection, bitrate ladders, and subscription pricing architecture.
Platform Type:
Supply concentration in cloud infrastructure favors platforms with captive data center capacity or long-term CDN commitments, locking independent entrants into higher unit economics.
- Subscription-Based:Recurring revenue models dominate in Australia, South Korea, and Japan where credit card penetration supports auto-renewal mechanics. TRAI's net neutrality framework in India prevents throttling of subscription traffic, preserving quality-of-service guarantees without tiered access fees. Today's leader: Subscription-Based. Tomorrow's challenger: Hybrid.
- Ad-Supported:Free-to-view tiers capture churned subscribers in Jakarta and Manila where recurring fee rejection is highest. Inventory monetization depends on local advertiser density and programmatic infrastructure maturity. Advertiser demand concentrates in Indonesian and Philippine metropolitan zones with retail and FMCG concentration.
- Transactional Video On Demand:Event-based purchases align with live sports and day-and-date film releases in markets with limited theatrical infrastructure. Revenue spikes correlate with cricket broadcasts in India and K-pop concerts in South Korea.
- Hybrid:Tiered access combining subscription base with ad-supported downgrade paths and transactional upsells. Flexibility attracts price-sensitive households in Vietnam and Thailand undergoing subscription fatigue rotation.
Revenue gravity centers on subscription mechanics, yet user acquisition velocity belongs to ad-supported entry points.
Content Genre:
Localization cost structures vary dramatically by genre, with scripted drama requiring dubbing and subtitling investment that sports and documentary formats avoid.
- Drama:Scripted series drive subscriber retention through serialized engagement. Japan's MIC localization quotas mandate minimum dubbed or subtitled domestic programming ratios, expanding Tokyo and Osaka studio capacity to meet procurement volumes. Korean and Australian platforms pre-commission regional productions to satisfy quota requirements without catalog gaps.
- Comedy:Cultural translation barriers limit cross-border portability, favoring locally produced sketch and sitcom formats. Indonesian and Philippine creators dominate Southeast Asian laugh tracks with vernacular humor.
- Documentary:Lower production cost base and minimal localization requirements suit educational and brand-funded distribution models. Indian ed-tech platforms integrate documentary streaming into corporate training modules.
- Sports:Live broadcasts demand sub-three-second latency infrastructure and command premium subscription tiers. Cricket rights in India and football in Southeast Asia concentrate viewership during seasonal tournaments.
Production investment tilts toward drama for retention, yet sports rights extract the highest per-subscriber willingness-to-pay.
Device Type:
Hardware refresh cycles and codec compatibility fragment addressable audiences across price-tiered device ecosystems.
- Smartphones:Dominant engagement channel in Indonesia and Vietnam where fixed broadband penetration remains constrained. Adaptive bitrate protocols optimize for variable cellular bandwidth and H.264 efficiency ceilings in budget handset segments.
- Smart TVs:4K throughput requirements concentrate adoption in South Korean and Australian households with fiber broadband penetration. BIS equipment approval processes in India delay set-top box launches, compressing hardware refresh timelines.
- Tablets:Commuter and co-viewing use cases sustain niche demand in Japanese and Singaporean urban transit corridors.
- Laptops:Enterprise training and educational deployments in Indian ed-tech and corporate communications segments sustain institutional demand.
Smartphone supremacy defines volume, while smart TV penetration unlocks premium tier conversion.
End User Segment:
Willingness-to-pay gradients and content preference divergence shape platform portfolio strategy and marketing spend allocation.
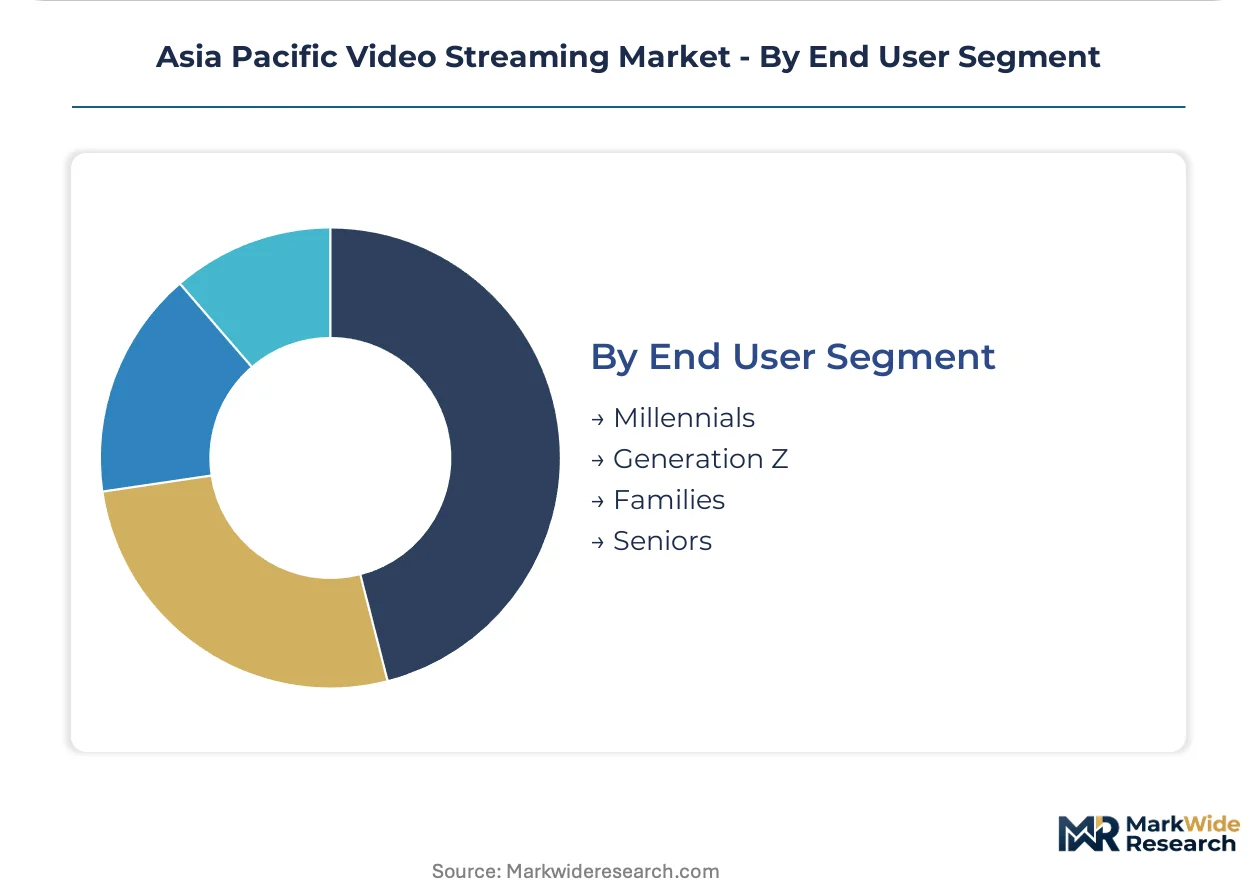
- Millennials:Subscription fatigue among urban cohorts fragments wallet share across multiple niche services rather than flagship consolidation. Rotation toward ad-supported tiers is most visible in Jakarta and Manila.
- Generation Z:Mobile-native consumption patterns and interactive format preference drive short-form and live commerce integration. South Korean 5G edge computing enables sub-second latency for interactive broadcasts.
- Families:Multi-profile subscription economics and parental control requirements influence platform selection. Shared household accounts in Australia and Japan sustain higher average revenue per user.
- Seniors:Accessibility features and simplified interfaces determine platform accessibility. Japan's aging demographic sustains dedicated senior-oriented catalog curation.
Millennial wallet fragmentation challenges retention, while Generation Z engagement models are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Bengaluru and Singapore anchor cloud infrastructure buildouts across the region. Platform operators recruit aggressively from Indian Institutes of Technology and National University of Singapore programs. Regional data center construction concentrates in Mumbai, Jakarta, and Sydney to reduce latency for live broadcasts.
China
Domestic cloud hyperscalers dominate infrastructure supply for streaming platforms serving the mainland market. SAMR and NRTA jointly regulate cross-border content licensing, requiring foreign platforms to form domestic partnerships for compliance. Shanghai and Beijing host the primary engineering clusters developing proprietary codec optimization and edge delivery systems.
India
Ed-tech platforms and cricket broadcasters drive enterprise and consumer streaming demand simultaneously. TRAI's net neutrality framework prevents throttling of video traffic, preserving quality-of-service guarantees without tiered access fees. Mumbai and Bengaluru concentrate cloud infrastructure investment, with Hyderabad emerging as a secondary hub for Telugu-language content production.
Japan
High smart TV penetration and aging demographics shape platform feature development toward accessibility and simplified interfaces. MIC enforces content localization quotas that mandate minimum ratios of dubbed or subtitled domestic programming. Tokyo and Osaka studios expand dubbing capacity to meet procurement volumes from foreign entrants.
South Korea
5G network maturity enables sub-second latency experiments for interactive live commerce broadcasts. K-pop concert streaming and esports tournaments command premium subscription tiers from Generation Z consumers. Seoul anchors edge computing integration with mobile network infrastructure, while Busan hosts secondary content production facilities.
Australia
Fiber broadband penetration supports 4K throughput adoption in smart TV households across metropolitan zones. ACMA applies media concentration rules to streaming mergers, creating acquisition pathways for mid-tier platforms seeking scale. Sydney and Melbourne concentrate both platform headquarters and post-production services for regional content.
Asia Pacific Video Streaming Market Competitive Landscape
Capital-heavy infrastructure operators compete with asset-light content aggregators for margin capture across the value chain. The market structure consolidates around three to five dominant platforms in each national market, with long-tail specialists occupying niche genre or demographic segments. Strategic archetypes separate captive cloud builders from CDN-dependent licensors and hybrid retail-media bundlers. Competitive moves concentrate on exclusive sports rights acquisition and original production commissioning to differentiate catalog depth.
Among China-based technology conglomerates, Tencent Holdings Limited and Baidu Inc. occupy positions anchored by captive cloud infrastructure and search-integrated distribution. Netflix Inc. and Amazon.com Inc. represent the multinational subscription archetype, navigating fragmented licensing regimes through regional production investment. Google LLC exemplifies the advertising-supported model with platform-agnostic reach across device ecosystems. These named entities illustrate how geographic origin and capital structure determine strategic optionality without prescribing specific competitive actions.
| Leading Market Players |
|---|
| Baidu Inc. |
| Akamai Technologies |
| Amazon.com Inc. |
| Kaltura Inc. |
| Brightcove Inc. |
| Google LLC |
| Netflix Inc. |
| U-Next |
| Tencent Holdings Limited |
| Others |
Pricing and Supply Chain Analysis
AV1 codec migration is compressing content delivery costs while redistributing infrastructure investment toward edge computing deployments across Southeast Asian markets. This technology transition simultaneously lowers per-stream licensing burdens and concentrates supply relationships among hyperscale cloud operators with captive data center footprints.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Asia Pacific video streaming, with subscription tiers calibrated to smart TV penetration in South Korea and Australia versus mobile-only access in Indonesia and Vietnam. Price differentiation rests on latency guarantees and 4K throughput capabilities, with live sports commanding the highest premiums. Cost compression in ad-supported tiers is intensifying because BIS streaming quality standards mandate infrastructure upgrades without corresponding revenue uplift. Enterprise training segments in Indian ed-tech show the lowest price sensitivity, while churned millennials in Jakarta and Manila reject recurring fees entirely.
Supply Chain Analysis
Single-source vulnerability sits with submarine cable capacity across the Pacific, exposing platforms to transit fee volatility during maintenance windows. Geographic supply concentration centers on Singapore, Mumbai, and Sydney for regional data center buildouts, with engineering talent clusters anchored in Bengaluru and Seoul. Raw material dependencies span H.264 and HEVC codec licensing, CDN transit agreements, and 5G edge computing hardware. Tariff exposure on networking equipment imports into India compresses hardware refresh timelines. Distribution runs through hyperscale cloud partnerships and long-term CDN commitments that lock independent platforms into unfavorable unit economics.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific video streaming has entered a late-cycle quality phase where subscriber retention hinges on sub-three-second latency infrastructure and original regional content depth. Demand is shifting decisively toward premium live sports and interactive formats that require capital-intensive edge deployments.
For Market Incumbents: Lock in exclusive sports rights for cricket in India and K-pop concerts in South Korea to defend against ad-supported challengers capturing price-sensitive churn. Deepen backward integration into captive cloud infrastructure across Mumbai and Singapore to reduce CDN dependency and preserve margin compression tolerance. Pre-commission regional drama productions to satisfy Japan's MIC localization quotas without catalog gaps.
For New Entrants and Emerging Players: Rural Indian households with limited fixed broadband penetration represent the most penetrable buyer archetype for mobile-optimized, low-bitrate streaming tiers. White-space targets include Indonesian SME corporate training segments and Philippine free-to-view models with programmatic advertising integration. A direct-to-educator go-to-market angle through Indian ed-tech platform partnerships bypasses consumer acquisition costs entirely.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier platforms with regional content libraries but subscale infrastructure. Long-term viability over a five-to-ten year window favors assets with demonstrated compliance navigation across China's SAMR-NRTA joint licensing regime. The inflection signal to watch is 5G edge computing deployment velocity in South Korea spreading to Southeast Asian markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Sports Rights Acquisition | Cricket and K-pop streaming rights in India and South Korea lock in premium subscriber tiers. |
| Captive Cloud Infrastructure Buildout | Mumbai and Singapore data centers reduce transit costs for live broadcasts under TRAI net neutrality. |
| Regional Original Content Commissioning | Pre-production in Tokyo and Osaka satisfies Japan's MIC localization quotas for foreign entrants. |
| AV1 Codec Deployment | Thailand and Malaysia platforms avoid HEVC per-device fees while optimizing mobile streams. |
| Enterprise B2B Partnership Expansion | Indian ed-tech integrations monetize streaming infrastructure for remote corporate training modules. |
Research Methodology
Direct dialogue with platform engineering directors, CDN procurement leads, content licensing executives, and Indian ed-tech integration specialists grounded the qualitative foundation. Secondary validation drew from TRAI regulatory filings, BIS equipment approval databases, SEC 10-K hyperscaler capex disclosures, and App Annie mobile engagement metrics. Bottom-up segmentation modeling triangulated against top-down market sizing across subscription, ad-supported, transactional, and hybrid platform architectures.
Revenue and user projections across the analysis window reflect econometric modeling of platform type, content genre, device category, and end-user demographic interactions. CAGRs derive from regression analysis of historical subscription growth, smartphone penetration curves, and broadband infrastructure deployment timelines. Industry-specific forecast inputs include India's BIS streaming quality compliance costs and South Korea's 5G edge computing rollout velocity.
Underlying measurement precision varies by segment; subscription-based platforms in Australia and Japan carry tighter precision than emerging ad-supported models in Indonesia and Vietnam. Forecasts reflect documented assumptions regarding regulatory stability, codec licensing cost trajectories, and submarine cable capacity expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Video on Demand Market
Video Streaming (OTT) Services
Game Streaming Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
OTT Content Market
Video Streaming (OTT) Services
Latin America OTT Platform Market
Video Streaming (OTT) Services
Streaming Media Services Market
Video Streaming (OTT) Services
Mexico OTT TV and Video Market
Video Streaming (OTT) Services
Advertising-Based Video on Demand Market
Video Streaming (OTT) Services
Video-On-Demand [Vod] Market
Video Streaming (OTT) Services
India Smart TV and OTT Market
Video Streaming (OTT) Services
Global Over-The-Top Content Market
Video Streaming (OTT) Services
Online Video Platform Market
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
Sports Streaming Platform Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
E-Sports and Games Streaming Market