
 Belgium Payments Market | 2026-2036
Belgium Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Payments Market Outlook
Multi-source infrastructure partnerships between legacy banks and fintech platforms is repositioning how payment rails deploy across Belgian commerce. Worldline leverages its European processing scale to anchor transaction clearing for major Belgian merchants. Bancontact Payconiq Company dominates domestic QR-code and app-based payment interfaces. Mastercard Inc. competes by extending its tokenization services into Belgian e-commerce channels.
Belgium payments encompass electronic fund transfer systems, card networks, and digital settlement infrastructure operating through SEPA-compliant protocols with real-time clearing capabilities. These systems facilitate commercial transactions, salary disbursements, and cross-border remittances within the eurozone monetary framework. Mobile payment methods are gaining transaction volume as Belgian consumers shift from physical card swipes to smartphone-authenticated purchases. Bank transfer mechanisms sustain dominance in B2B settlements due to SEPA Instant Credit Transfer availability. Traditional banks retain the largest margin pools in corporate treasury services, though fintech companies are capturing consumer-facing payment gateway fees.
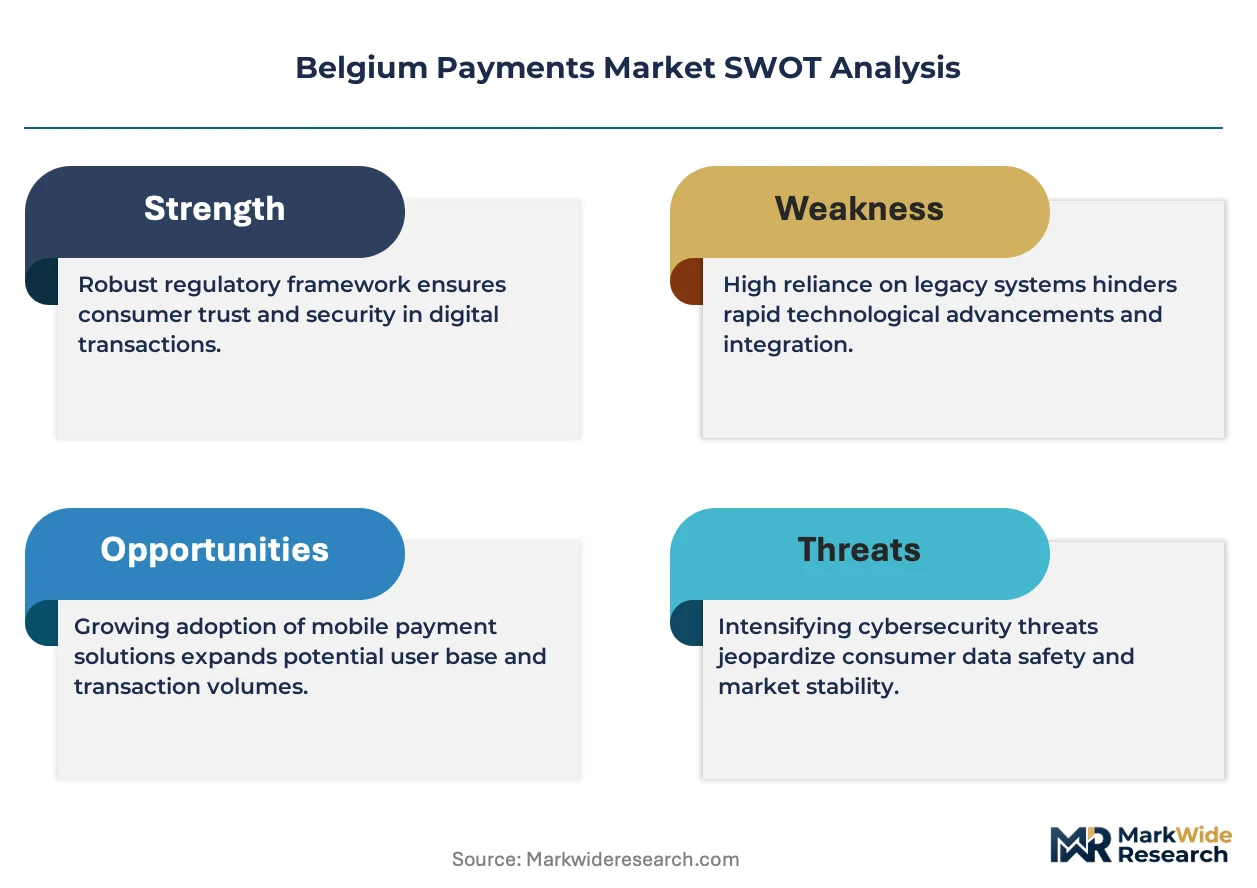
National Bank of Belgium oversight intersects with EBA PSD2 technical standards and EU GDPR data protection requirements to mandate strong customer authentication and limit merchant data retention. These frameworks shape product development timelines and determine which service providers qualify for open banking API access. Stakeholders must monitor how forthcoming EU digital euro consultations could redistribute clearing authority between central infrastructure and private payment gateways.
Market Dynamics
PSD2 open banking mandates from the European Banking Authority are forcing legacy Belgian banks to expose payment initiation APIs to third-party fintech providers, fragmenting traditional deposit-based revenue models while accelerating infrastructure modernization timelines.
Growth Catalysts
- SEPA Instant Credit Transfer:Real-time euro settlement capabilities eliminate interbank float for Belgian merchants, compressing working capital cycles in retail and logistics verticals.
- Contactless POS terminal mandates:Belgian retailers face consumer preference shifts toward tap-to-pay authentication, driving hardware refresh cycles across Brussels and Antwerp commerce corridors.
- QR-code payment standardization:Bancontact Payconiq's unified interface reduces merchant fragmentation, consolidating consumer wallet adoption under interoperable domestic rails.
Market Restraints
- Core banking system replacement costs:Belgian institutions face eight-figure euro expenditures to retrofit legacy mainframes for API compliance under PSD2 technical standards.
- Concentrated clearing infrastructure:Worldline's dominance in Belgian transaction processing creates single-point-of-failure exposure for merchant settlement continuity.
- Strong Customer Authentication friction:EBA-mandated two-factor verification adds checkout steps, elevating cart abandonment rates in Belgian e-commerce channels.
Strategic Opportunities
- Flanders logistics payment hubs:Port of Antwerp-Bruges cargo settlement volumes remain underserved by specialized B2B payment workflows, creating white space for trade finance digitization.
- Request-to-Pay messaging convergence:Integration of SEPA R2P with ERP systems enables Belgian corporates to automate invoice reconciliation against inbound customer payments.
- Digital euro consultation participation:National Bank of Belgium stakeholder input processes allow domestic providers to shape central bank digital currency interface specifications before issuance.
Industry Challenges
- API talent scarcity:Belgian fintechs compete with Frankfurt and Amsterdam hubs for developers fluent in Berlin Group NextGenPSD2 standards, inflating compensation benchmarks.
- Legacy stack integration complexity:Cobol-based core systems at established Belgian banks resist real-time data streaming requirements, extending PSD2 compliance project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Payments Market |
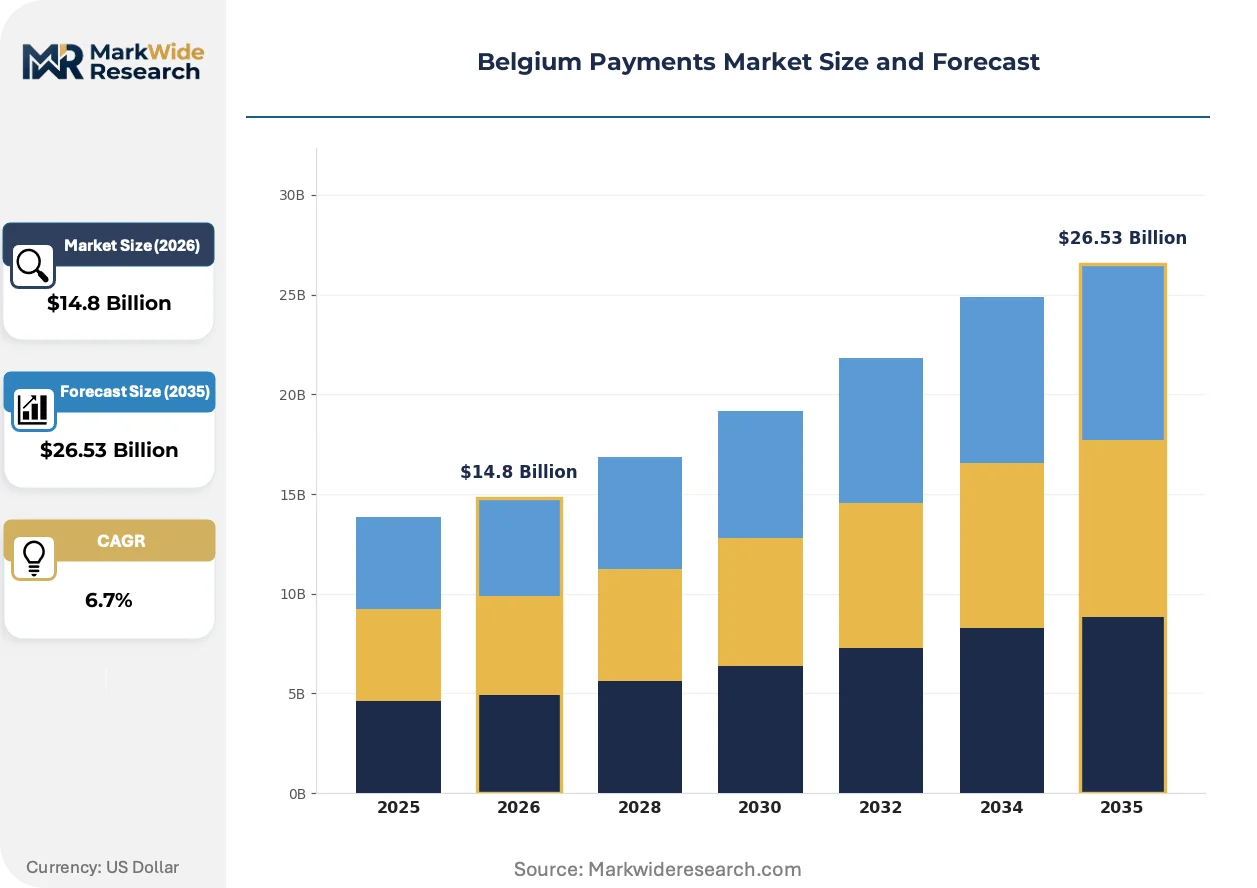
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Bank Transfer, Mobile Payment Transaction Type: Online Payment, In-Store Payment, Peer-to-Peer Transfer, Recurring Payment Customer Type: Consumer, Small Business, Enterprise, Non-Profit Service Provider: Traditional Banks, Fintech Companies, Payment Gateways, Digital Wallets |
| Companies Covered | Bancontact Payconiq Company, Visa Inc., Mastercard Inc., American Express Company, PayPal Payments Private Limited, Sofort GmbH, KBC Group, Belfius, Worldline, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Payments Market Strategic Shifts
Belgian payment infrastructure is pivoting from batch-processed settlement toward real-time, API-orchestrated transaction flows. This shift compresses clearing windows and repositions merchant acquiring economics around data services rather than float capture.
Biometric authentication is integrating into Belgian mobile banking applications, replacing static PIN entry with facial recognition and fingerprint validation. Retail banking apps from domestic institutions now deploy these modalities for transaction authorization above Strong Customer Authentication thresholds. The technology is compressing checkout duration metrics while elevating fraud detection precision through behavioral biometrics layered beneath presentation authentication.
GDPR data retention limitations intersect with PSD2 transaction history requirements to create compliance tension for Belgian payment service providers. The European Data Protection Board's narrow interpretation of legitimate interest grounds restricts merchant data analytics pipelines. Belgian acquirers are responding by anonymizing transaction streams earlier in processing workflows, sacrificing personalization depth for regulatory defensibility.
Belgian consumers are consolidating payment method selection within super-app environments, displacing standalone banking applications. Messaging platforms and retail loyalty ecosystems now embed payment initiation without redirecting to bank interfaces. This pattern concentrates most visibly among Brussels metropolitan users under age thirty-five, where single-interface financial management has become default behavior.
Belgium Payments Market Segmentation
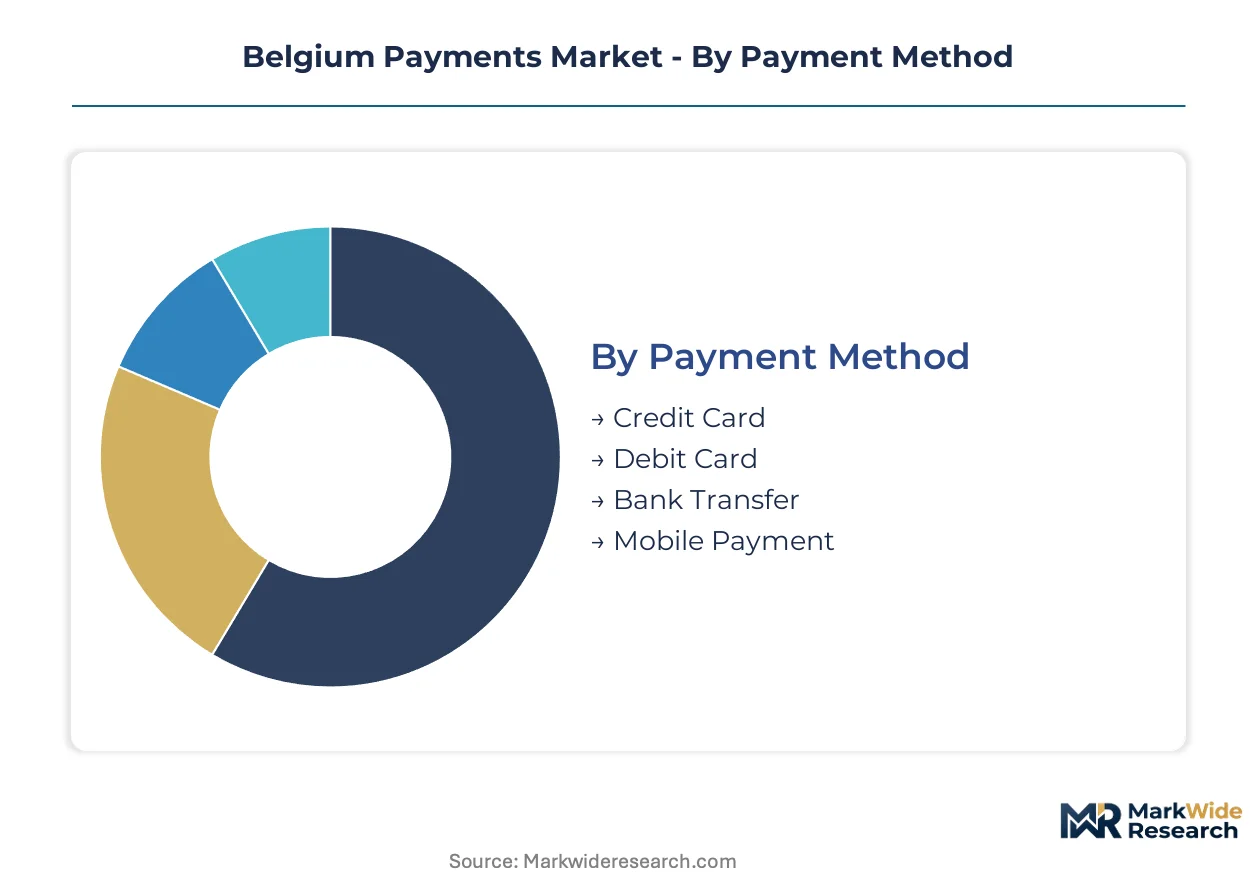
Belgian payment infrastructure exhibits divergent margin structures across transaction rails and customer tiers. Segmentation reveals where SEPA compliance costs concentrate versus where open banking APIs unlock new revenue pools.
Payment Method:
Supply concentration in Belgium's payment rails tilts toward card networks and bank-operated systems with established clearing relationships.
- Credit Card:Visa and Mastercard networks dominate cross-border e-commerce authentication through tokenized credentials. Brussels-based luxury retailers and Antwerp diamond traders drive premium transaction volumes requiring chargeback protection.
- Debit Card:Bancontact-branded debit rails process the majority of domestic point-of-sale volume through chip-and-PIN and contactless modalities. Flemish supermarket chains and fuel stations anchor infrastructure deployment decisions for terminal acceptance.
- Bank Transfer:SEPA Instant Credit Transfer protocols enable real-time euro settlement between Belgian IBAN accounts without card network interchange fees. B2B procurement workflows and property transactions rely on this rail for large-value transfers.
- Mobile Payment:Smartphone-authenticated transactions integrate biometric verification with QR-code interfaces from domestic wallet providers. Younger demographics in Brussels metropolitan area displace physical card usage through super-app consolidation.
Debit card infrastructure absorbs the bulk of installed capacity; mobile payment is expanding most quickly.
Transaction Type:
Cost tier differentiation separates high-friction authentication requirements from low-touch recurring flows.
- Online Payment:E-commerce checkouts require 3D Secure 2.0 compliance and PSD2 Strong Customer Authentication, elevating gateway fees. Belgian fashion retailers and digital service marketplaces absorb these friction costs for cross-border customer acquisition.
- In-Store Payment:Physical terminal acceptance concentrates in Antwerp's commercial corridors and Brussels shopping districts. Contactless tap limits and PIN thresholds vary by merchant category code, shaping hardware configuration decisions.
- Peer-to-Peer Transfer:Mobile number-linked IBAN transfers through domestic banking apps displace cash settlement for informal transactions. Student populations and gig economy workers in university cities drive adoption velocity.
- Recurring Payment:SEPA Direct Debit mandates enable utility billing and subscription services with pre-authorized collection rights. Belgian energy providers and telecom operators optimize for low-failure, high-retention payment schedules.
In-store payment absorbs the bulk of installed capacity; peer-to-peer transfer is climbing the fastest.
Customer Type:
Application-specific requirements drive divergent service level agreements and pricing structures.
- Consumer:Individual account holders access basic payment initiation through mobile banking interfaces with standardized PSD2 functionality. Mass-market fee sensitivity limits revenue per user for domestic institutions.
- Small Business:Merchant acquirers target sole proprietors and family enterprises with bundled POS terminal and accounting software packages. Flemish construction trades and Walloon hospitality operators represent underserved verticals.
- Enterprise:Corporate treasury departments demand multi-bank connectivity, automated reconciliation, and FX hedging integration. Port of Antwerp-Bruges logistics conglomerates and Brussels-headquartered multinationals anchor high-value relationships.
- Non-Profit:Charitable organizations prioritize low-cost donation collection through SEPA Direct Debit and card-not-present channels. Belgian cultural institutions and humanitarian NGOs negotiate reduced interchange rates.
Consumer payment volumes absorb the bulk of installed capacity; small business is gaining share fastest.
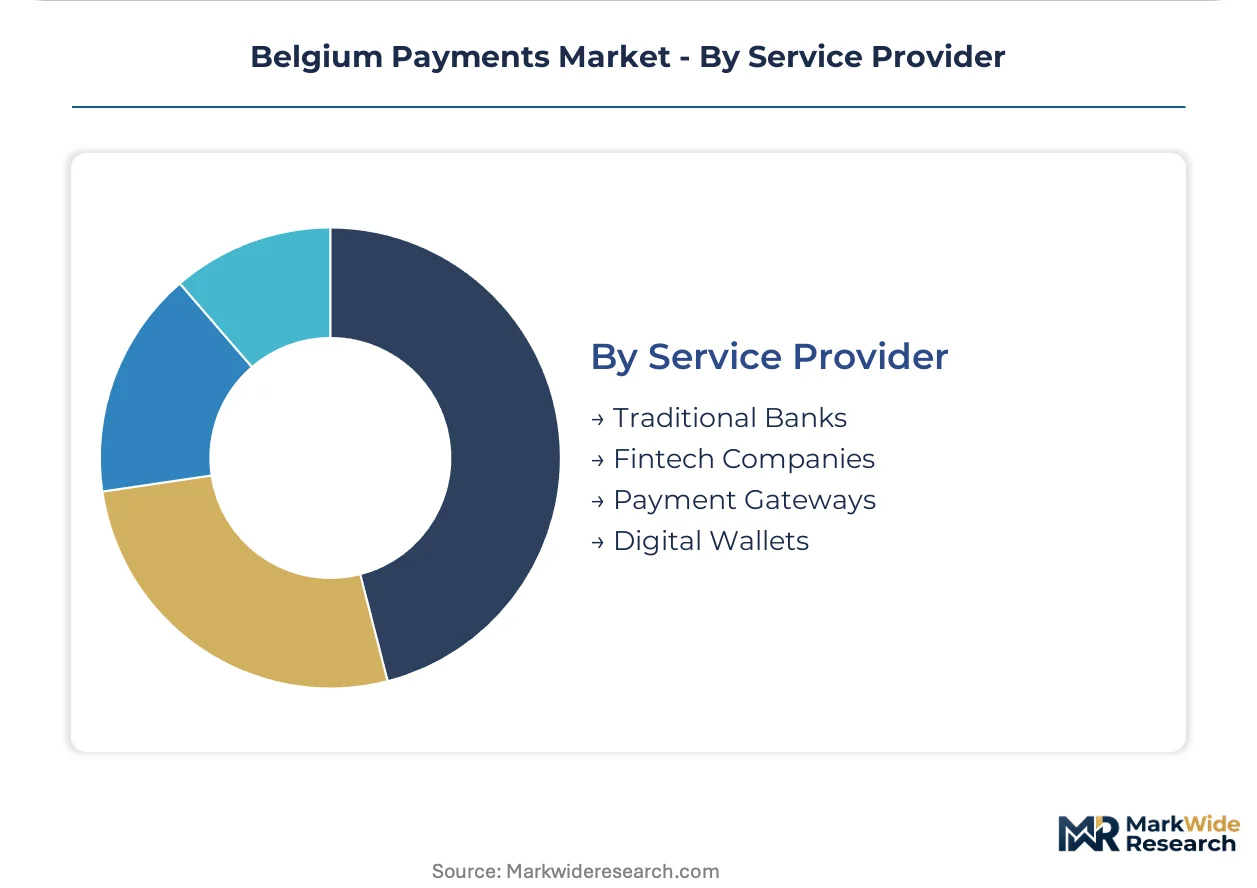
Service Provider:
Margin structure varies dramatically between regulated deposit-taking institutions and API-native technology platforms.
- Traditional Banks:BNP Paribas Fortis, KBC, and ING Belgium operate core banking infrastructure with direct access to National Bank of Belgium settlement systems. Legacy mainframe constraints slow API deployment timelines despite regulatory pressure.
- Fintech Companies:Licensed payment institutions and electronic money issuers compete on user experience without branch network overhead. Belgian neobanks target unmet demand among expatriate professionals and cross-border workers.
- Payment Gateways:Technical intermediaries aggregate merchant acceptance across multiple acquirers and alternative payment methods. E-commerce platforms in Belgium's Dutch-language and French-language markets require localized checkout optimization.
- Digital Wallets:Closed-loop and open-loop wallet providers compete for consumer primary account status through loyalty integration. Retail banking apps face displacement from messaging platform embedded finance in Brussels urban corridors.
Traditional bank infrastructure absorbs the bulk of installed capacity; fintech companies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgian payment demand concentrates in Brussels' fintech corridor and Flanders' logistics hubs, with infrastructure deployment decisions driven by merchant density and SEPA compliance requirements.
Brussels-Capital Region
EU institutional presence and international banking headquarters generate high-value cross-border transaction volumes. National Bank of Belgium oversight intersects with ECB settlement protocols here. The European Quarter anchors correspondent banking relationships and fintech API development clusters.
Flanders
Port of Antwerp-Bruges cargo flows and manufacturing supply chains sustain specialized B2B payment workflows. EBA PSD2 technical standards enforcement shapes corporate treasury service offerings. Ghent and Leuven host embedded finance startups targeting logistics verticals.
Wallonia
Steel and aerospace manufacturing supply chains require trade finance digitization for international procurement. Belgian federal regional development incentives support payment infrastructure modernization. Liège logistics platforms process cross-border e-commerce settlement volumes.
Antwerp Metropolitan Area
Diamond trading and luxury retail segments drive premium authentication requirements and chargeback-sensitive transaction processing. Contactless POS terminal penetration rates exceed national averages in central commercial corridors. Merchant acquirers compete on same-day settlement guarantees.
Belgium Payments Market Competitive Environment
Strategic partnerships dominate the current landscape as legacy banks and fintech platforms negotiate API access agreements. The market exhibits tiered concentration: domestic clearing infrastructure operators, international card networks, and licensed payment institutions each occupy distinct margin pools. Three archetypes define positioning: SEPA-compliant infrastructure anchors, open banking API aggregators, and merchant-facing gateway specialists. M&A activity and technology licensing arrangements represent the primary competitive vectors reshaping market share distribution.
Within the domestic infrastructure tier, Bancontact Payconiq Company and Worldline exemplify divergent scale strategies. Among international network operators, Visa Inc. and Mastercard Inc. occupy positions as tokenization and cross-border authentication standards setters. KBC Group represents the traditional banking archetype confronting API compliance pressures.
| Leading Market Players |
|---|
| Bancontact Payconiq Company |
| Visa Inc. |
| Mastercard Inc. |
| American Express Company |
| PayPal Payments Private Limited |
| Sofort GmbH |
| KBC Group |
| Belfius |
| Worldline |
| Others |
Value Chain & Pricing Dynamics
Belgian merchant demand for real-time settlement APIs is forcing payment service providers to absorb infrastructure modernization costs without proportional fee recovery, compressing margins across transaction processing tiers while accelerating consolidation among acquirers.
Pricing Analysis
High-volume domestic debit transactions absorb infrastructure capacity while cross-border e-commerce authentication commands premium gateway fees. Three-tier pricing structure across premium, standard, and economy levels separates enterprise treasury services with multi-bank connectivity from basic merchant acquiring and mass-market consumer apps. Cost compression in standard-tier merchant acquiring is intensifying because Bancontact Payconiq's unified QR standard reduces switching friction. Small business merchants show highest price sensitivity; diamond traders and luxury retailers in Antwerp demonstrate lowest sensitivity due to chargeback protection requirements.
Supply Chain Analysis
API developer talent scarcity in Belgian fintech hubs is forcing payment institutions to source technical capabilities from Amsterdam, Frankfurt, and Dublin talent markets at inflated compensation benchmarks. Core banking infrastructure draws from legacy mainframe maintenance pools concentrated in Belgium, France, and Germany while cloud-native processing layers source from distributed European development centers. Single-source vulnerability concentrates in Worldline's clearing infrastructure dominance for Belgian merchant settlement. Distribution runs through licensed payment institution networks with direct National Bank of Belgium settlement access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over API development talent and direct merchant acquiring relationships to defend margin pools against platform commoditization.
For Market Incumbents: Cement clearing infrastructure relationships with National Bank of Belgium settlement systems while acquiring specialized fintech development teams to accelerate PSD2 API deployment timelines against emerging neobank threats. Prioritize backward integration into merchant-facing software to capture gateway fees currently leaking to payment aggregators. For New Entrants and Emerging Players: Embedded finance routes through messaging platforms and retail loyalty apps offer the most penetrable path into Brussels metropolitan consumer segments under age thirty-five. Target Flanders logistics payment hubs with trade finance digitization workflows for Port of Antwerp-Bruges cargo settlements. Pursue white-label API partnerships with established acquirers rather than direct licensing overhead. For Investors and Strategic Acquirers: Re-rating potential sits with licensed payment institutions possessing direct central bank settlement access given forthcoming digital euro interface specification decisions. Long-term viability favors acquirers with enterprise treasury service depth and multi-bank connectivity capabilities. Monitor National Bank of Belgium stakeholder consultation participation as inflection signal for central bank digital currency clearing authority redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| API Infrastructure Modernization | PSD2 compliance mandates from EBA force legacy mainframe replacement to enable real-time transaction streaming. |
| Merchant Acquiring Consolidation | Scale economies in terminal deployment and settlement processing defend margin pools against gateway disintermediation. |
| Embedded Finance Partnership | Super-app integration captures Brussels consumer payment initiation without standalone banking app dependency. |
| Biometric Authentication Deployment | Facial recognition and fingerprint validation compress checkout duration while satisfying Strong Customer Authentication thresholds. |
| Digital Euro Consultation Participation | National Bank of Belgium stakeholder input shapes central bank digital currency interface specifications before issuance. |
Study Parameters
Independent corroboration across payment processor executives, regulatory compliance officers, merchant acquiring specialists, and fintech platform architects underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation against National Bank of Belgium regulatory filings, EBA PSD2 technical standards documentation, SEPA scheme rulebooks, and European Banking Authority implementation reports. Bottom-up transaction volume modeling triangulated against top-down market sizing from banking sector disclosures.
Historical reference periods anchored the forecast window to pre-PSD2 implementation baselines and post-open banking adoption trajectories. The analytical framework segments by payment method, transaction type, customer tier, and service provider category across the projection horizon. CAGRs derived from regression analysis against SEPA Instant Credit Transfer penetration curves, contactless terminal deployment rates, and mobile wallet adoption velocity in comparable European markets.
The model holds under stable EBA regulatory interpretation and continued eurozone monetary integration; deviation in digital euro issuance timelines or PSD3 mandate scope would shift infrastructure investment assumptions. Forecasts reflect stated assumptions regarding merchant API adoption rates and fintech licensing velocity. Material deviation in central bank digital currency consultation outcomes or core banking replacement cost trajectories warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Direct Carrier Billing Market
Payments
Saudi Arabia Payment Gateway Market
Payments
Retail POS Terminals Market
Payments
Asia Pacific Mobile Wallet Market
Payments
Philippines Remittance Market
Payments
United States Real Time Payments Market
Payments
Voice-Based Payments Market
Payments
South Korea Mobile Payment Market
Payments
Wireless POS Terminals Market
Payments
Global Bitcoin Payments Ecosystem Market
Payments
Electronic Cash Register Market
Payments
Fuel and Convenience Store POS Market
Payments
Germany POS Terminal Market
Payments
Saudi Arabia Payments Market
Payments
India Forex Cards Market
Payments
United States POS Terminals Market