
 GCC Furniture Market | 2026-2036
GCC Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Furniture Market Analysis
Saudi Arabia is tilting toward domestic manufacturing capacity as Vision 2030 industrialization targets draw furniture production closer to major project sites. Royal Furniture leverages its Riyadh-centric manufacturing base to sustain rapid fulfillment timelines for government and hospitality contracts. IKEA competes through flat-pack logistics and localized sourcing partnerships that reduce landed costs across Gulf markets. Danube Home differentiates via vertically integrated showrooms and warehousing networks spanning the UAE, Saudi Arabia, and Qatar.
Furniture encompasses movable objects engineered for human support, storage, and spatial organization, typically fabricated from engineered wood substrates, solid timber, metal framing, upholstery foams, and textile or leather coverings through processes including CNC routing, veneer pressing, powder coating, and foam molding. The primary commercial purpose spans residential living environments, corporate workplaces, hospitality venues, and retail spaces where ergonomics, durability, and aesthetic compliance with interior specifications determine procurement decisions. Wood material categories anchor the GCC market due to cultural preferences for carved and veneered finishes in premium residential and hospitality segments, while metal frames gain share in commercial office fit-outs demanding modular reconfigurability. The hospitality end-user segment represents the fastest-growing demand pool as hotel pipeline expansions in Riyadh, Jeddah, and Dubai drive bulk procurement of custom seating and case goods.
SASO technical regulations, UAE's Emirates Authority for Standardization and Metrology (ESMA) product conformity schemes, and Gulf Standardization Organization (GSO) harmonized furniture safety standards collectively shape import clearance protocols and manufacturing compliance costs across member states. These frameworks mandate flame-retardant upholstery certifications, formaldehyde limits on particleboard and MDF substrates, and stability testing for storage units, effectively filtering non-compliant suppliers from public-sector and branded hospitality procurement channels. Stakeholders must monitor evolving SASO and ESMA enforcement timelines and pre-position testing partnerships to avoid customs delays as local content requirements tighten.
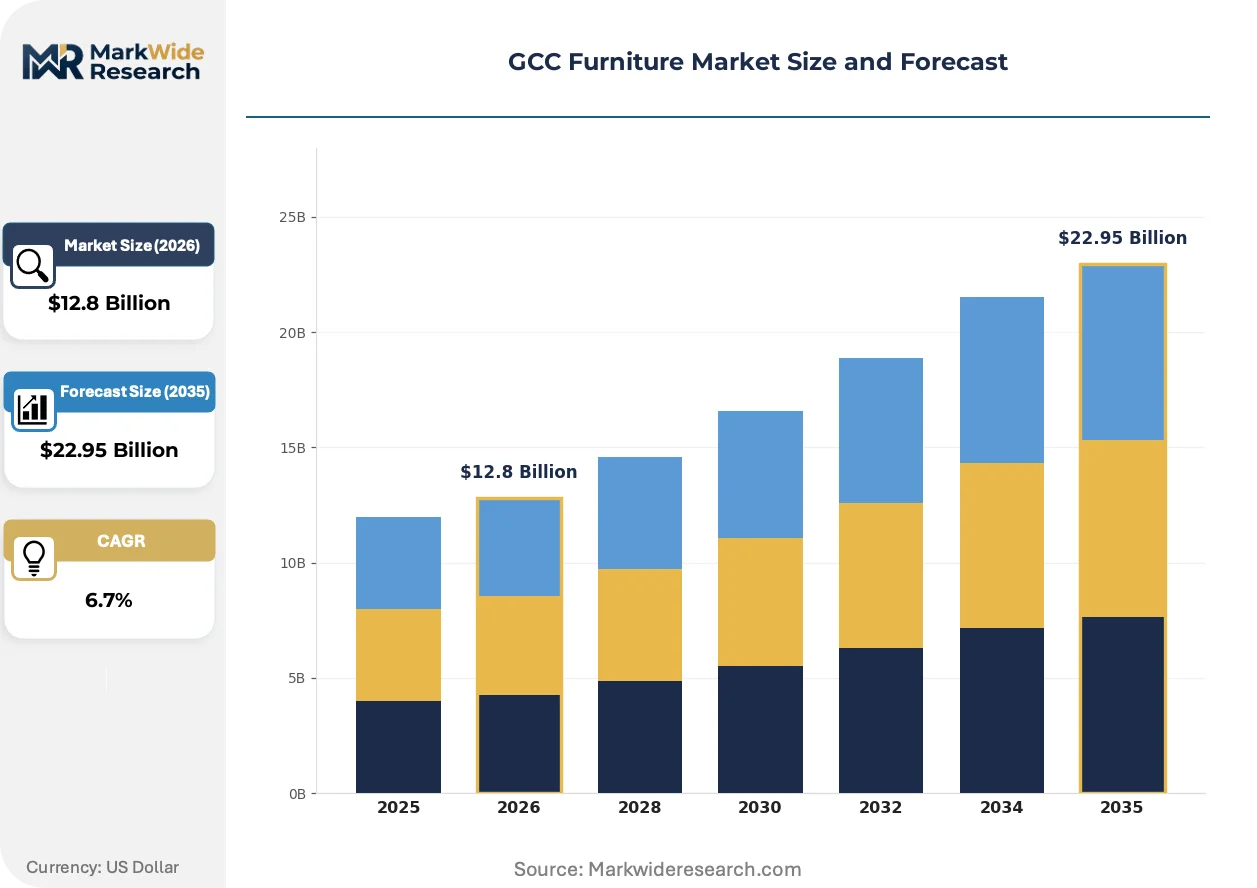
Market Dynamics
Hospitality fit-outs in luxury hotels and resorts are accelerating procurement of premium furnishings across Saudi Arabia and the UAE, while SASO flammability and formaldehyde emission standards are compelling manufacturers to reformulate finishes and substrates ahead of enforcement timelines.
Growth Catalysts
- Vision 2030 industrialization:Saudi Arabia's domestic manufacturing targets draw furniture production closer to major project sites in Riyadh and Jeddah, shortening fulfillment cycles for government contracts.
- Hospitality pipeline expansion:Hotel developments in Dubai and Riyadh drive bulk procurement of custom seating and case goods, with fit-out contractors pre-qualifying suppliers against ESMA conformity schemes.
- Modular metal framing:Commercial office fit-outs across Doha and Kuwait City demand reconfigurable workstations, displacing fixed wood partitions in corporate environments.
Market Restraints
- Particleboard cost volatility:Formaldehyde-compliant engineered wood substrates face price pressure from petrochemical resin feedstock fluctuations, squeezing margin structures for mid-market case goods.
- Import concentration risk:Non-compliant suppliers from Southeast Asia face systematic exclusion as SASO and GSO harmonized standards tighten customs clearance protocols across member states.
- Upholstery certification lag:Flame-retardant textile testing capacity bottlenecks in the Gulf delay product launches by 8-14 weeks for seating manufacturers.
Strategic Opportunities
- Qatar hospitality undersupply:FIFA legacy tourism infrastructure and new luxury hotel developments in Doha create unmet demand for premium furnishings with expedited delivery terms.
- Flat-pack distribution innovation:Last-mile assembly partnerships with regional logistics networks reduce landed costs and damage rates for e-commerce furniture channels serving secondary Saudi cities.
- Local content incentives:Saudi Industrial Development Fund financing preferences for domestic manufacturing facilities reward backward integration into veneer pressing and powder coating operations.
Industry Challenges
- CNC programming talent scarcity:Shortages of operators capable of complex veneer routing and 5-axis milling constrain production scaling for custom hospitality millwork.
- Multi-jurisdiction certification complexity:Divergent SASO, ESMA, and GSO enforcement timelines force suppliers to maintain parallel testing partnerships, elevating compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Furniture Market |
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Cabinets Material: Wood, Metal, Fabric, Leather End User: Residential, Commercial, Hospitality, Office Distribution Channel: Online, Offline, Showrooms, Warehouses |
| Companies Covered | Home Center, Royal Furniture, IKEA, Saudi Modern Factory Co, Midas Furniture, Pan Emirates, Danube Home, Herman Miller, Al Huzaifa, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Furniture Market Emerging Trajectories
Digital fabrication and regulatory harmonization are compressing product development cycles while reshaping how specifications flow from architect to manufacturer across Gulf project pipelines.
Parametric design-to-fabrication software is collapsing the traditional gap between interior design visualization and CNC production files. Hospitality designers in Dubai and Riyadh now transmit directly executable cutting paths to manufacturing partners, eliminating translation errors and accelerating custom furniture prototyping from weeks to days. This compression is collapsing the competitive advantage of traditional sample-based bidding processes.
SASO technical regulations on formaldehyde emissions and upholstery flammability are forcing reformulation of particleboard substrates and foam compositions across imported and locally manufactured product lines. Manufacturers serving Saudi government and branded hospitality procurement channels must pre-position testing partnerships with SASO-notified bodies to avoid customs delays. The regulations most severely affect seating and storage units entering Riyadh and Jeddah project sites.
Architects and procurement teams in luxury hospitality are consolidating vendor relationships around full-service fit-out partners capable of delivering coordinated furniture, fixture, and equipment packages under single-contract accountability. This bundling displaces fragmented sourcing of discrete case goods, upholstery, and metalwork from separate suppliers. The shift is most visible in Dubai and Riyadh mega-projects where developer risk allocation favors turnkey interior execution.
GCC Furniture Market Segmentation
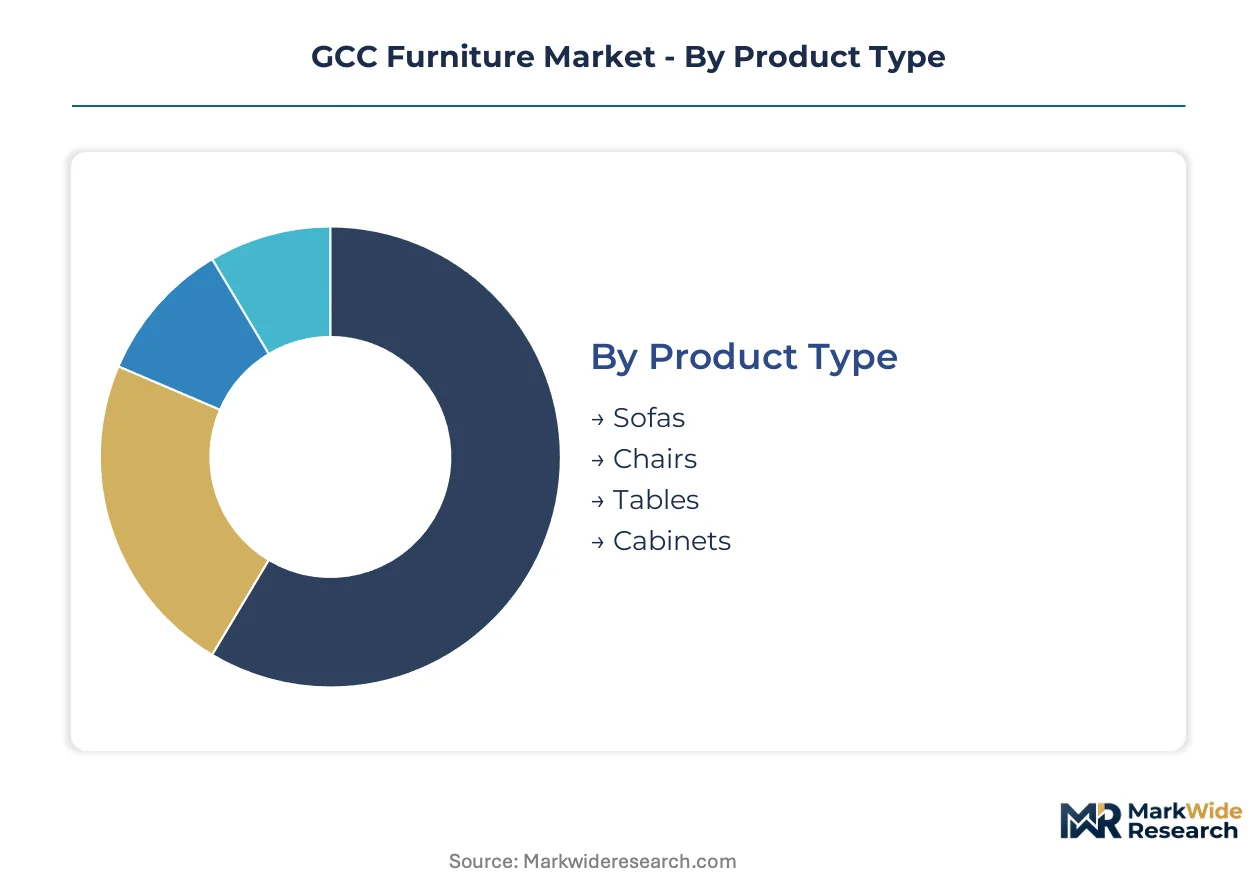
Segmentation in the GCC furniture market reveals how procurement priorities diverge across project types and compliance environments. Each dimension carries distinct margin structures, certification burdens, and fulfillment timelines that determine supplier competitiveness.
Product Type:
Mature categories dominate residential procurement volumes, while emerging segments capture hospitality-driven premiumization.
- Sofas:Multi-seat upholstered units combining engineered wood frames, high-density foam cushioning, and flame-retardant fabric or leather coverings. Hospitality fit-outs in Riyadh and Dubai drive demand for custom sectional configurations, though upholstery certification lag stretches lead times.
- Chairs:Ergonomic seating solutions span dining, accent, and task categories with metal or wood frame substrates. Commercial office fit-outs across Doha and Kuwait City prioritize reconfigurable task seating with modular metal framing.
- Tables:Surface structures fabricated from solid timber, engineered substrates, or metal framing support dining, work, and display functions.
- Cabinets:Storage units with particleboard or MDF carcasses and veneer or laminate facings face SASO formaldehyde emission testing requirements.
Sofas handle the majority of throughput; chairs are expanding most quickly on share.
Material:
Cost tiers separate premium specifications from mass-market procurement, with compliance-grade substrates commanding price premiums.
- Wood:Solid timber and engineered substrates including particleboard, MDF, and plywood form the cultural preference base for carved and veneered finishes. Saudi Arabia's domestic manufacturing incentives are drawing veneer pressing operations closer to Riyadh project sites.
- Metal:Steel and aluminum framing enables modular reconfigurability in commercial environments. Powder coating capacity constraints in the Gulf elevate lead times for custom color specifications.
- Fabric:Textile upholstery materials require flame-retardant certification under ESMA and SASO schemes.
- Leather:Natural and synthetic hide coverings serve premium residential and hospitality segments with durability specifications.
Wood commands the dominant volume position; metal is climbing the fastest as office modularization accelerates.
End User:
Application context determines specification intensity, with contract-grade requirements filtering supplier participation.
- Residential:Individual household procurement spanning living, dining, and bedroom categories. Riyadh and Dubai population growth is reshaping interior specifications across apartment and villa developments.
- Commercial:Retail, healthcare, and institutional fit-outs demanding durability and code compliance.
- Hospitality:Hotel, resort, and serviced apartment furnishings requiring custom millwork and coordinated FF&E packages. Branded developments in Jeddah and Doha are consolidating vendor relationships around turnkey execution.
- Office:Corporate workplace systems emphasizing ergonomics and spatial reconfigurability.
Residential absorbs the largest procurement volume; hospitality shows the steepest expansion trajectory.
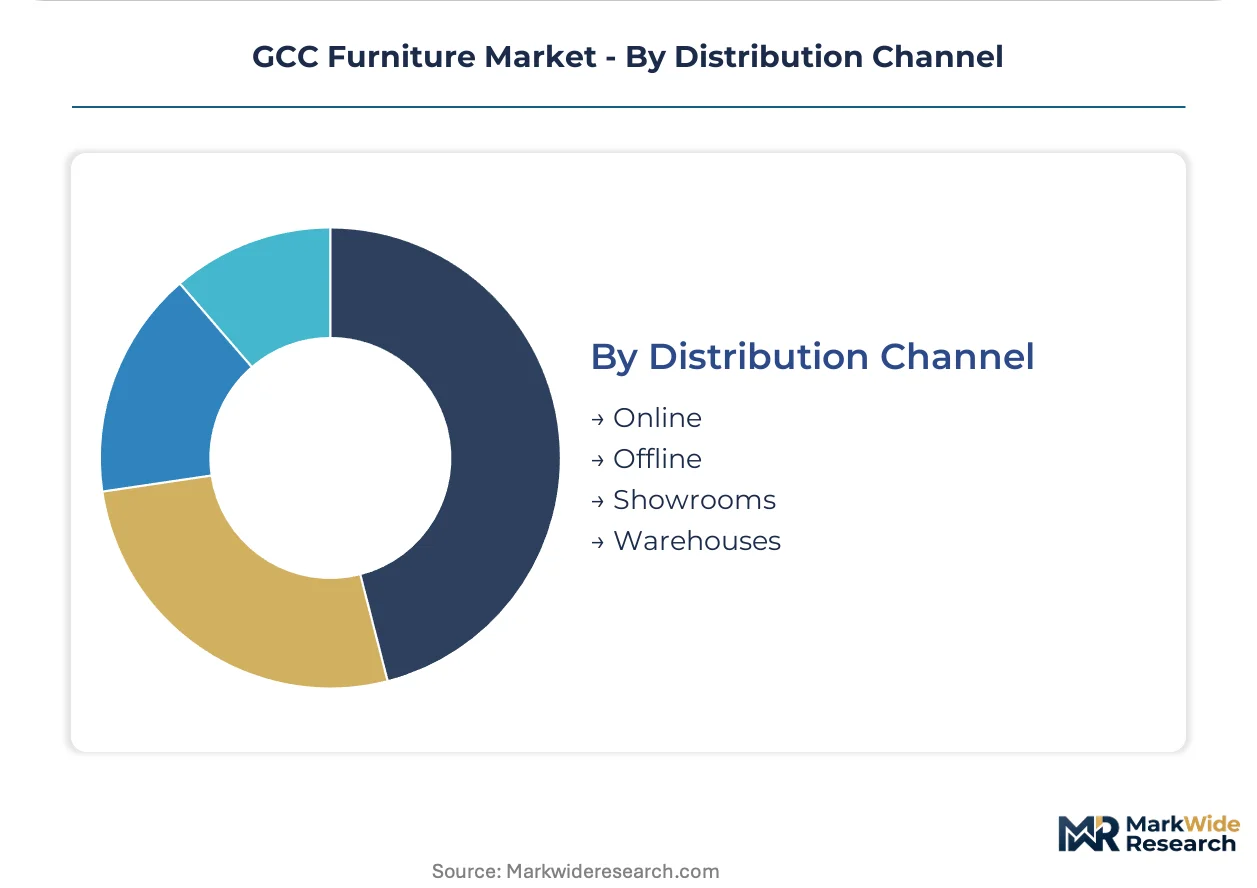
Distribution Channel:
Customer type separates project-scale contract fulfillment from individual purchase behaviors.
- Online:E-commerce platforms with last-mile assembly partnerships reducing damage rates for flat-pack delivery to secondary Saudi cities.
- Offline:Traditional retail networks including department store furniture departments and independent dealers.
- Showrooms:Experience-centric display environments with vertically integrated design consultation and fulfillment. Danube Home's UAE-Saudi-Qatar network exemplifies this model.
- Warehouses:Bulk storage and direct-to-contractor distribution serving project-scale procurement with rapid fulfillment timelines.
Offline channels maintain the dominant throughput position; online is gaining share fastest through logistics innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Furniture manufacturing capacity clusters near Riyadh and Dubai where mega-project pipelines concentrate procurement demand. Domestic production incentives in Saudi Arabia are reshaping supply geography as import-dependent markets tighten conformity enforcement.
Saudi Arabia
Vision 2030 industrialization targets are accelerating domestic furniture manufacturing investment around Riyadh and Jeddah. SASO technical regulations on formaldehyde emissions and upholstery flammability now filter import clearance protocols, compelling suppliers to pre-position testing partnerships with notified bodies. The Riyadh-centric manufacturing base shortens fulfillment cycles for government and hospitality contracts.
United Arab Emirates
Dubai's hospitality pipeline expansion drives bulk procurement of custom seating and case goods for luxury hotel fit-outs. ESMA product conformity schemes mandate flame-retardant certifications and stability testing for storage units entering the market. Vertically integrated showroom networks span Dubai and Abu Dhabi, combining design consultation with rapid fulfillment timelines.
Qatar
FIFA legacy tourism infrastructure and new luxury hotel developments in Doha create concentrated demand for premium furnishings with expedited delivery terms. The country's national standardization body enforces Gulf Standardization Organization harmonized furniture safety standards alongside import conformity requirements. Doha-based fit-out contractors are consolidating vendor relationships around full-service FF&E packages.
Kuwait
Commercial office fit-outs across Kuwait City prioritize reconfigurable workstations with modular metal framing over fixed wood partitions. Central Bank financing preferences support corporate real estate development, indirectly stimulating furniture procurement for workplace environments. Kuwait City serves as the primary demand concentration point for contract-grade office systems.
GCC Furniture Market Vendor Landscape
Flat-pack logistics specialists and vertically integrated showroom operators split the market across distinct fulfillment models. Domestic Saudi manufacturers leverage proximity to Riyadh project sites for government contract capture, while regional retailers optimize last-mile assembly networks. The competitive terrain rewards scale-driven procurement leverage and design-to-fabrication speed. M&A activity targets showroom footprint expansion and captive veneer pressing capacity.
Among regional specialists, Royal Furniture exemplifies the domestic manufacturing archetype with Riyadh-centric production positioning. Danube Home anchors the vertically integrated retail tier through showroom and warehousing networks spanning multiple Gulf states. IKEA occupies the flat-pack distribution position, optimizing landed costs through localized sourcing partnerships across member markets.
| Leading Market Players |
|---|
| Home Center |
| Royal Furniture |
| IKEA |
| Saudi Modern Factory Co |
| Midas Furniture |
| Pan Emirates |
| Danube Home |
| Herman Miller |
| Al Huzaifa |
| Others |
Supply Flow & Price Mechanics
Jebel Ali port freight corridors from Southeast Asia feed supply concentration into Dubai warehousing clusters, compressing landed costs for mass-market particleboard while elevating price premiums on SASO-certified substrates that clear Riyadh customs without detention.
Pricing Analysis
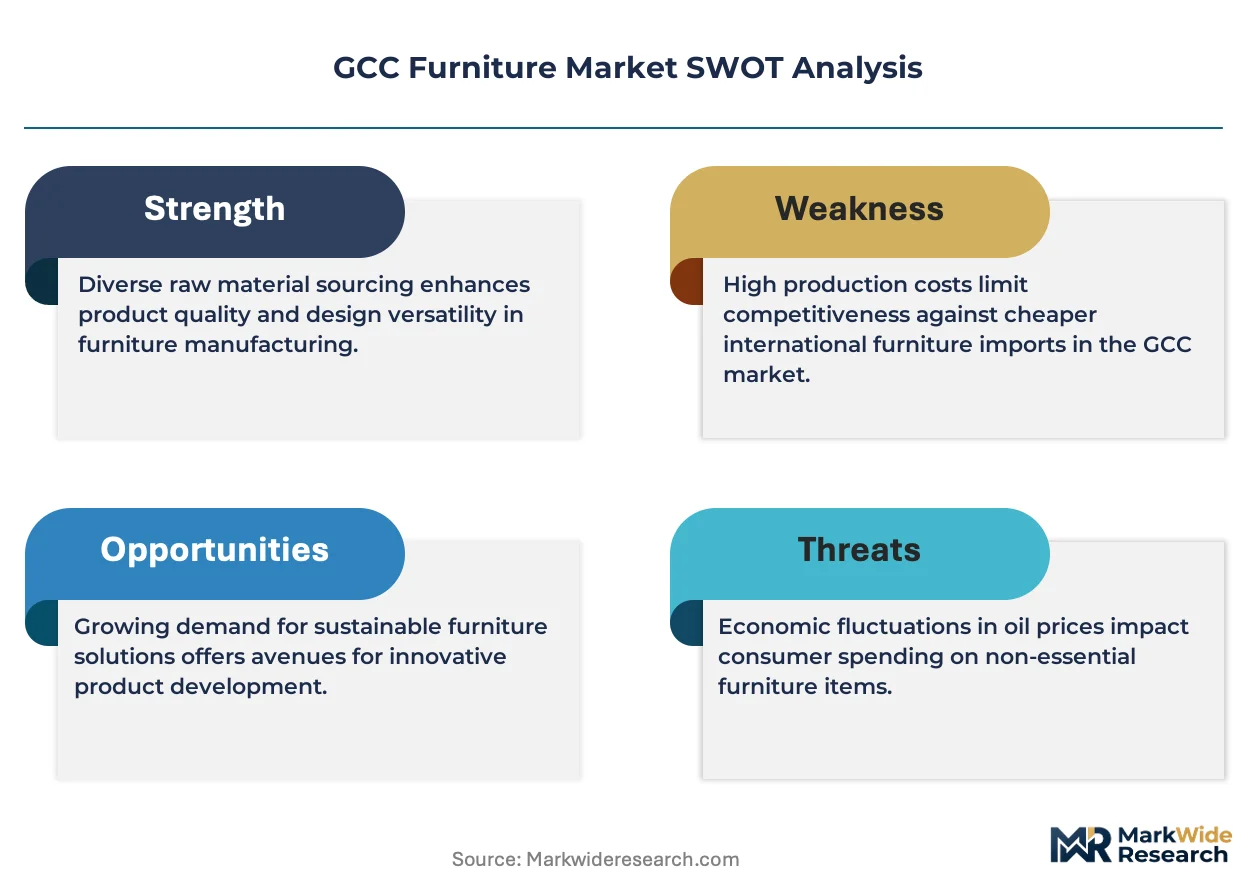
SASO technical regulations dictate the pricing tier structure across the GCC furniture market. Certification-grade substrates command three-tier pricing structure across premium, standard, and economy levels, with formaldehyde-compliant engineered wood carrying material premiums over uncertified imports. Pricing pressure stems from petrochemical resin feedstock volatility squeezing mid-market case goods margins. Government and branded hospitality procurement channels exhibit lowest price sensitivity, while residential e-commerce segments in secondary Saudi cities drive aggressive cost competition.
Supply Chain Analysis
Export-control restrictions on advanced CNC routing software from European Union member states limit technology transfer to Gulf manufacturing facilities, constraining domestic production scaling for complex hospitality millwork. Supply concentrates in China for engineered wood substrates, Italy for high-end veneer pressing equipment, and Vietnam for upholstered component assembly. Raw material dependencies span Malaysian rubberwood logs, German adhesive formulations, and Korean textile flame-retardant treatments. Single-source vulnerability runs through petrochemical resin supply chains tethered to Gulf refinery output. Distribution runs through vertically integrated showroom networks with captive warehousing in Riyadh, Dubai, and Doha.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC furniture market is accelerating through a regulatory inflection as SASO and ESMA harmonization collapses legacy import pathways, forcing rapid compliance infrastructure investment that separates viable suppliers from excluded competitors.
For Market Incumbents: Pre-empt compliance-driven margin erosion by securing captive veneer pressing capacity in Riyadh industrial zones before Saudi Industrial Development Fund financing preferences fully phase in. Anchor backward integration into powder coating operations to control custom color specification lead times that currently constrain hospitality contract capture. Defend against flat-pack logistics specialists by tightening last-mile assembly partnerships in secondary Saudi cities where IKEA's network penetration remains shallow. For New Entrants and Emerging Players: Establish a beachhead in Qatar's hospitality fit-out segment where FIFA legacy infrastructure and new luxury hotel developments in Doha have created acute undersupply for premium furnishings with expedited delivery terms. Target white-space in modular metal framing for Kuwait City commercial office fit-outs, displacing fixed wood partitions with reconfigurable workstation systems. Deploy direct-to-contractor distribution bypassing traditional showroom overhead to capture price-sensitive corporate procurement committees. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned Saudi manufacturing groups lacking succession planning and SASO certification infrastructure required for government contract eligibility. Five-to-ten year viability favors facilities with Riyadh-proximate real estate and existing ESMA testing partnerships that transfer across ownership. Monitor enforcement timeline acceleration at Saudi customs as the inflection signal separating compliant from stranded asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Veneer Pressing | Saudi Industrial Development Fund financing preferences reward Riyadh-proximate captive substrate production. |
| SASO Certification Pre-Positioning | Early testing partnerships with notified bodies eliminate customs detention risk for hospitality seating imports. |
| Flat-Pack Logistics Partnership | Last-mile assembly networks reduce damage rates for e-commerce channels serving secondary Saudi cities. |
| Parametric Design-to-Fabrication Adoption | Direct CNC file transmission from Dubai architects collapses custom furniture prototyping from weeks to days. |
| Turnkey FF&E Bundling | Single-contract accountability displaces fragmented sourcing in Riyadh and Dubai mega-project pipelines. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs import records, SASO technical regulation filings, and hospitality project procurement databases. Primary interviews engaged furniture manufacturing plant managers, hospitality fit-out contractors, procurement leads at branded hotel developers, and ESMA conformity assessment body representatives. Secondary validation drew from Gulf Standardization Organization harmonized standards documentation, Saudi Industrial Development Fund financing disclosure records, and UAE trade statistics. Bottom-up demand modeling triangulated against top-down macroeconomic projections across the analysis window.
Forecast inputs span product type segmentation across sofas, chairs, tables, and cabinets; material categories including wood, metal, fabric, and leather; end-user applications across residential, commercial, hospitality, and office; and distribution channels spanning online, offline, showroom, and warehouse. CAGRs derived from regression analysis against construction sector output indices, hospitality pipeline tracking, and population growth trajectories. Industry-specific inputs incorporate SASO enforcement timeline scenarios and domestic manufacturing incentive uptake rates.
Sensitivities concentrate around SASO formaldehyde emission standard acceleration, petrochemical resin price volatility, and hospitality project delay cascades from construction financing constraints. Forecasts reflect documented assumptions on regulatory harmonization pace and industrial zone infrastructure completion. Material shifts in Saudi customs enforcement intensity or Gulf refinery output disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Study Carrels Market
Furniture
Middle East and Africa Wood Based Panel Market
Furniture
Ergonomic Chair Market
Furniture
Massive Wood Slabs Market
Furniture
Cabinet Market
Furniture
United Kingdom Furniture Market
Furniture
Italy Furniture Retail Market
Furniture
Ready-To-Assemble (RTA) Furniture Market
Furniture
Metal Furniture Market
Furniture
Laminated Door Market
Furniture
Piano Stools Market
Furniture
Japan Furniture Market
Furniture
Wooden Furniture Market
Furniture
Italy Home Furniture Market
Furniture
Furniture Laminate Market
Furniture
Europe Outdoor Furniture Market