
 Indonesia E-Commerce Market | 2026-2036
Indonesia E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia E-Commerce Market Outlook
Micro-entrepreneurs and individual resellers is collapsing the traditional wholesale-distributor channel for consumer goods. Shopee dominates transaction volume through its integrated logistics and payment ecosystem. Tokopedia anchors merchant onboarding in second-tier cities with hyperlocal fulfillment infrastructure. Lazada competes through cross-border inventory flows from its regional warehousing network in Singapore and Malaysia.
Indonesia e-commerce denotes digitally mediated retail transactions conducted through internet-connected interfaces, typically requiring mobile-optimized front ends, API-integrated payment gateways, and last-mile distribution nodes capable of archipelagic coverage across more than 17,000 islands. Fashion and electronics categories within product type segmentation generate the highest gross merchandise value, though beauty is recording the fastest order frequency growth among repeat purchasers. E-wallet penetration within payment method segmentation is displacing cash on delivery as the default settlement mode, particularly among mobile app users in Java and Sumatra.
Indonesia's Ministry of Communication and Informatics enforces content moderation and platform licensing under the Electronic Information and Transactions Law, while Bank Indonesia regulates e-money issuers and digital payment interoperability standards. The Personal Data Protection Law imposes data localization and consent management obligations that elevate compliance costs for cross-border marketplace operators. Stakeholders must monitor enforcement consistency between Jakarta's central regulators and emerging provincial digital economy offices as transaction volumes shift outside Java.
Market Dynamics
Mobile wallet infrastructure is compressing settlement cycles and collapsing the cash-on-delivery dependency that historically dominated archipelagic logistics. This payment digitization is forcing marketplace operators to rebuild trust architectures around escrow and buyer protection rather than physical inspection.
Growth Catalysts
- Personal Data Protection Law:Indonesia's data localization mandates are accelerating domestic cloud infrastructure investment, reducing latency for transaction processing across the archipelago.
- Hyperlocal fulfillment nodes:Tier-two cities like Surabaya and Bandung are deploying micro-warehousing that cuts last-mile delivery times from days to hours.
- QRIS interoperability standards:Bank Indonesia's unified QR code protocol is consolidating previously fragmented e-wallet acceptance at merchant endpoints.
Market Restraints
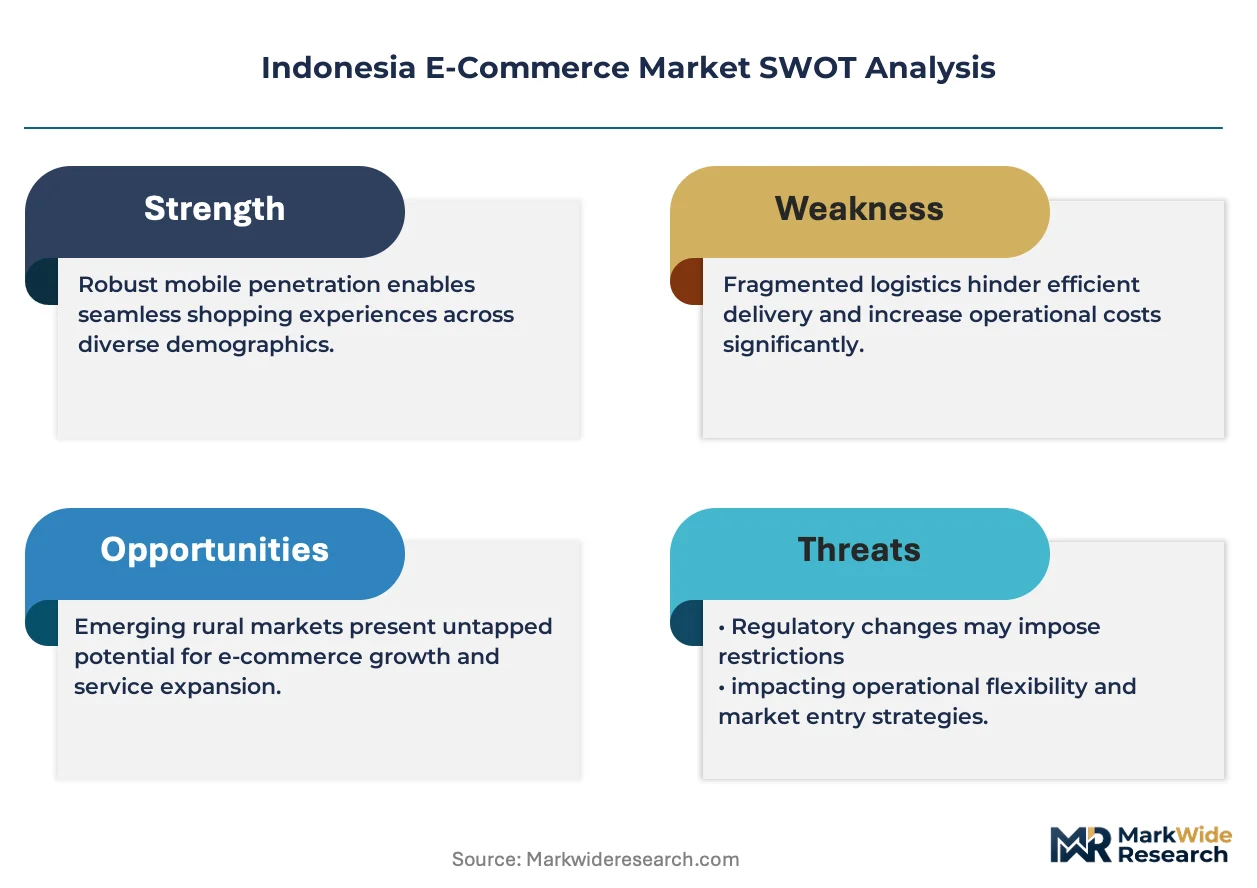
- Archipelagic logistics costs:Sea freight rates between Java and outer islands remain structurally elevated due to port congestion and fuel price volatility.
- Merchant onboarding friction:KYC verification requirements under anti-money laundering rules extend seller activation timelines beyond operational patience thresholds.
- Cross-border data routing:Data localization obligations block cost-efficient use of Singapore-based cloud regions for transaction processing.
Strategic Opportunities
- Live commerce integration:Video streaming platforms are converging with checkout flows, creating impulse purchase channels in beauty and fashion verticals.
- East Indonesia penetration:Sulawesi and Papua merchant bases remain underdeveloped relative to Java-Sumatra transaction density.
- Embedded finance products:Working capital advances tied to seller transaction history are displacing traditional micro-lending for inventory financing.
Industry Challenges
- Logistics workforce scalability:Same-day delivery promises are outstripping trained driver and warehouse operator availability in secondary cities.
- Platform-to-merchant API integration:Legacy inventory management systems in family-owned retail require costly middleware development for real-time stock synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia E-Commerce Market |
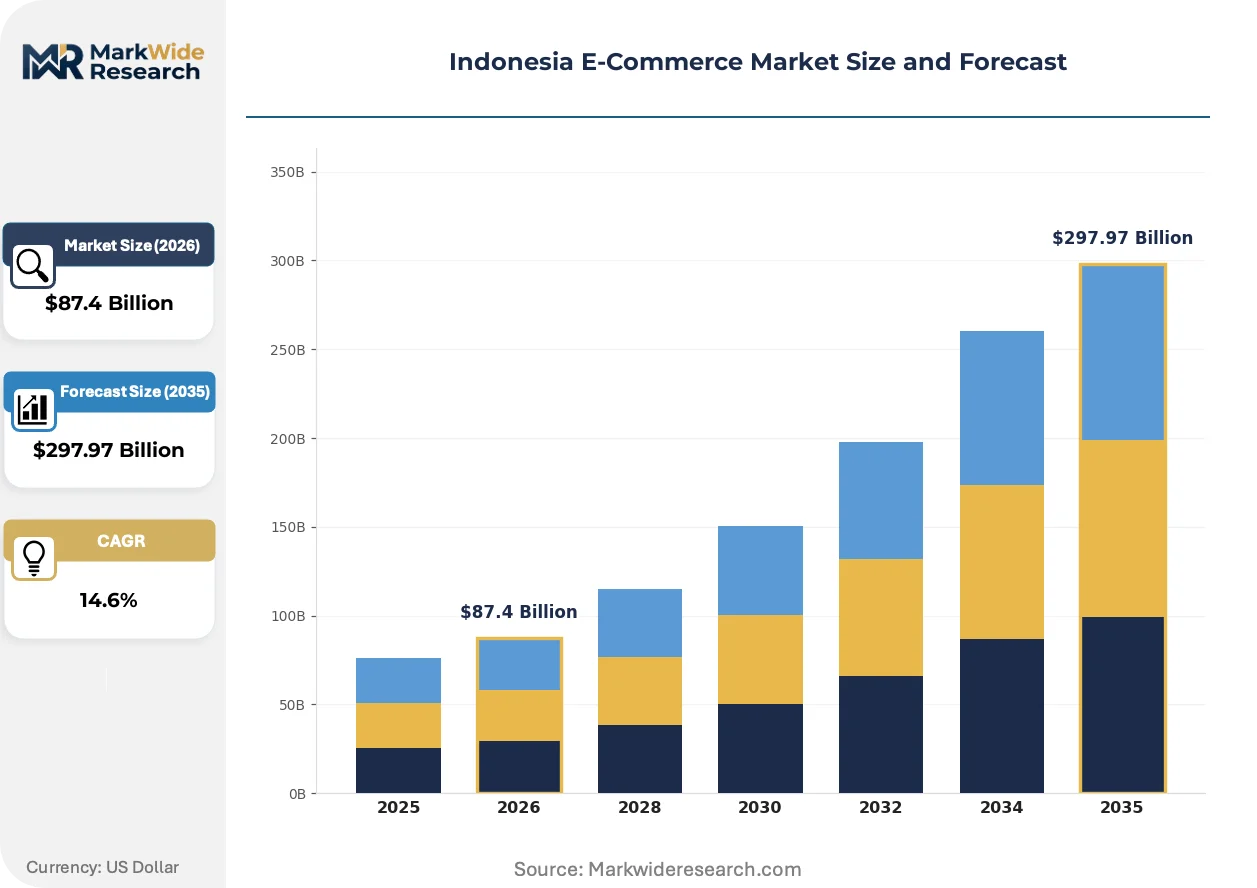
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $297.97 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Fashion, Beauty, Home Goods Platform Type: Mobile Apps, Websites, Marketplaces, Social Media Payment Method: Credit Card, E-Wallet, Bank Transfer, Cash on Delivery Customer Type: Individuals, Businesses, Resellers, Wholesale Buyers |
| Companies Covered | Shopee, Tokopedia, Lazada, Blibli, Bukalapak, TikTok Shop, Akulaku, Orami, Ralali, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia E-Commerce Market Strategic Shifts
Social commerce interfaces are dissolving the boundary between content consumption and transaction completion. This convergence is redefining customer acquisition economics and forcing infrastructure investment in streaming-capable mobile architectures.
AI-powered product recommendation engines are fragmenting search-based discovery into personalized feed curation. Micro-entrepreneurs in fashion resale are adopting these tools to surface inventory without keyword optimization expertise. The technology is fragmenting merchant marketing capabilities, separating algorithm-fluent sellers from those dependent on platform advertising spend.
Indonesia's Personal Data Protection Law is imposing consent management and breach notification obligations on marketplace operators. Compliance costs are elevating for cross-border platforms that previously routed data through regional hubs. Domestic marketplace incumbents are responding by building captive data centers in Batam and Jakarta to satisfy localization requirements.
Community-based buying patterns are rotating demand toward group purchase models that aggregate orders for bulk pricing. Neighborhood WhatsApp administrators are displacing individual storefront browsing as the primary discovery channel in residential clusters. This behavior is most visible in grocery and household consumables across dense urban kampungs in Jakarta and Surabaya.
Indonesia E-Commerce Market Segmentation
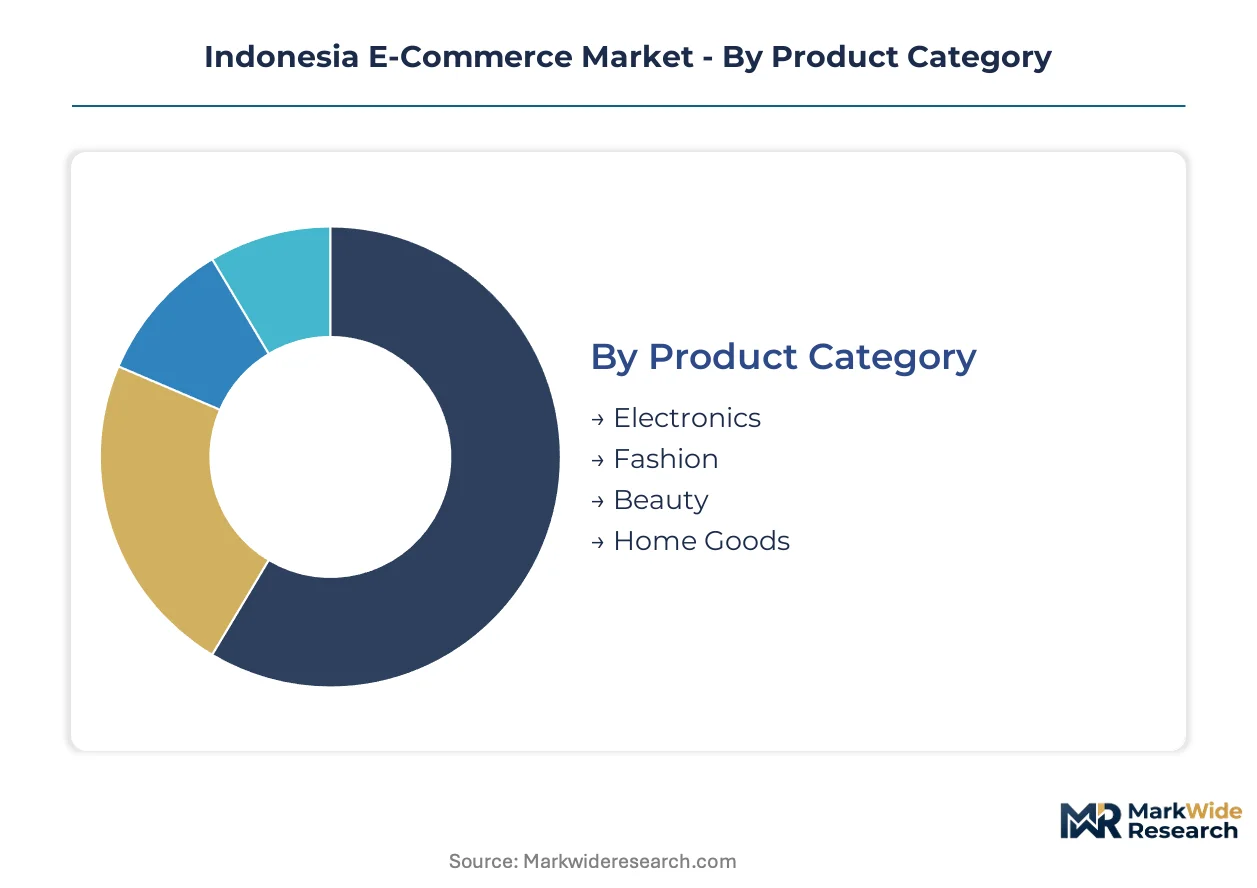
Segmentation in Indonesia's e-commerce landscape reveals how transaction flows concentrate across distinct channel and payment preferences. Understanding these divisions exposes where infrastructure investments yield the highest conversion returns.
Product Category:
Margin pools concentrate in high-velocity discretionary categories where repeat purchase frequency compounds customer lifetime value.
- Electronics:Smartphones, laptops, and consumer appliances dominate gross merchandise value through high average order values. Demand clusters in Jakarta and Surabaya where device upgrade cycles accelerate through installment financing partnerships with local banks.
- Fashion:Apparel and accessories generate the highest order frequency among repeat purchasers, particularly through mobile-optimized discovery feeds. Micro-entrepreneurs in Bandung and Yogyakarta supply this segment through direct-to-consumer resale channels.
- Beauty:Skincare and cosmetics command premium pricing through influencer-driven discovery on video platforms.
- Home Goods:Furniture and household consumables anchor basket size expansion during promotional periods.
The dominant share belongs to Electronics, while Beauty is closing the gap fastest.
Platform Type:
Customer acquisition costs vary dramatically by interface, with native mobile experiences capturing the stickiest session durations.
- Mobile Apps:Native iOS and Android applications deliver push-notification re-engagement and biometric checkout acceleration. Java-based users exhibit 40% higher session frequency than website visitors, driving platform investment into app-exclusive flash sales.
- Marketplaces:Aggregator platforms with integrated logistics and payment escrow dominate merchant onboarding in tier-two cities. Surabaya and Bandung sellers cluster here for access to nationwide fulfillment networks without capital expenditure.
- Websites:Desktop and mobile web interfaces retain relevance for high-consideration purchases requiring comparison browsing.
- Social Media:Live-streaming commerce through video platforms collapses discovery and checkout into single-session transactions.
Marketplaces command the largest merchant base, though Social Media interfaces are expanding most quickly.
Payment Method:
Settlement infrastructure determines conversion rates at checkout, with digital wallets eliminating friction in archipelagic logistics.
- E-Wallet:Mobile wallet settlement through providers like GoPay and OVO compresses transaction completion to under ten seconds. QRIS interoperability standards mandated by Bank Indonesia are consolidating acceptance across street-level merchants in Sumatra and Java.
- Cash on Delivery:Physical cash settlement at delivery retains importance in outer islands with limited banking penetration. Sulawesi and Papua transactions still favor this method, though its share is eroding as smartphone penetration deepens.
- Credit Card:Card-not-present transactions concentrate among affluent urban demographics in Jakarta seeking reward point accumulation.
- Bank Transfer:Virtual account settlement persists for high-value purchases requiring manual invoice reconciliation.
E-Wallet settlement holds the dominant position, while Credit Card usage is climbing the fastest among premium customer segments.
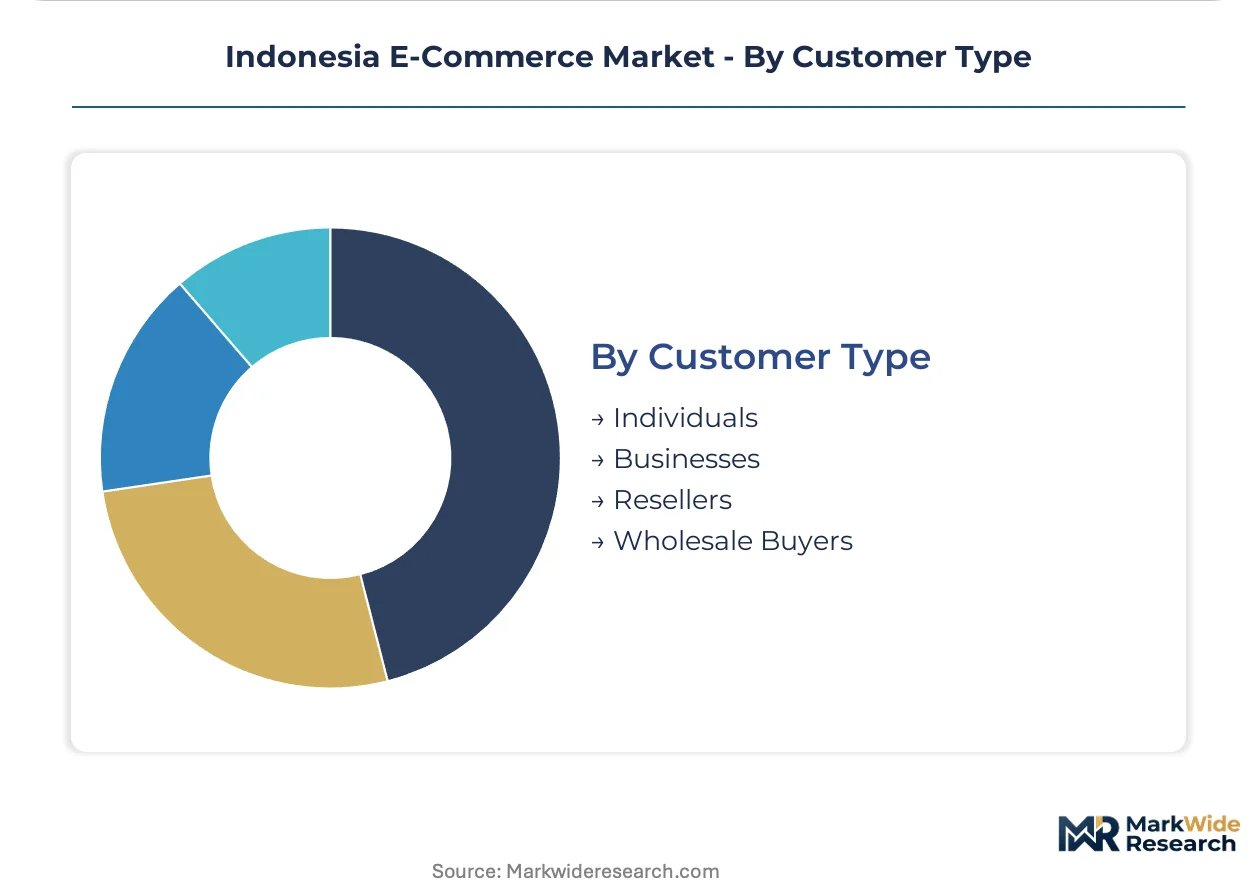
Customer Type:
Order patterns diverge sharply between consumption-driven individuals and inventory-accumulating commercial buyers.
- Individuals:End-consumers purchasing for personal use generate the highest order frequency in fashion and beauty verticals. Their behavior concentrates in dense urban kampungs where community-based buying aggregates demand for bulk pricing.
- Resellers:Micro-entrepreneurs sourcing inventory for offline redistribution collapse traditional wholesale-distributor channels. These operators in Surabaya and Medan leverage platform analytics to identify trending SKUs before physical market restocking.
- Businesses:Corporate procurement accounts for electronics and office supply bulk orders with negotiated payment terms.
- Wholesale Buyers:Volume purchasers aggregate demand for cross-border inventory flows from regional warehousing hubs.
Individuals account for the largest transaction volume, though Resellers are gaining share fastest as social commerce dissolves formal retail boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform infrastructure concentrates in Java's urban corridor, where fulfillment networks achieve density economies unavailable across the archipelago. Transaction volumes fragment sharply between established western markets and emerging eastern zones.
Java
Jakarta and Surabaya generate the highest gross merchandise value through dense smartphone penetration and same-day delivery coverage. Bank Indonesia's QRIS interoperability standards mandate unified payment acceptance across street-level merchants. Bandung's garment manufacturing clusters feed direct-to-consumer fashion resale through marketplace APIs.
Sumatra
Medan anchors northern transaction flows with cross-border logistics links to Penang and Singapore. The Ministry of Communication and Informatics enforces platform licensing under Electronic Information and Transactions Law provisions. Palembang's emerging merchant base leverages micro-warehousing to compress delivery windows for electronics purchases.
Sulawesi
Makassar's port infrastructure enables sea-borne inventory consolidation from Java-based distribution centers. Data localization requirements under the Personal Data Protection Law elevate compliance costs for operators routing transactions through Singapore cloud regions. Local merchant onboarding accelerates as hyperlocal fulfillment nodes deploy in secondary cities.
Kalimantan
Balikpapan and Samarinda concentrate demand from mining and energy sector payrolls with elevated disposable income. Provincial digital economy offices are emerging as regulatory interpreters between Jakarta's central mandates and local enforcement. Last-mile logistics remain constrained by riverine geography and limited inter-city road connectivity.
Papua
Jayapura represents the frontier of mobile wallet penetration where cash-on-delivery still dominates settlement preference. The central government's Palapa Ring fiber optic backbone extends connectivity to previously isolated transaction nodes. Merchant density remains sparse relative to other regions, creating first-mover opportunities for platform operators willing to absorb elevated logistics costs.
Indonesia E-Commerce Market Competitive Environment
Concentration sits with integrated marketplace operators possessing captive logistics and payment infrastructure. Three distinct competitive tiers have crystallized: pan-Asian platforms with regional warehousing networks, domestic incumbents with hyperlocal fulfillment density, and social commerce interfaces converging content with checkout. Strategic moves center on merchant onboarding acceleration through simplified KYC workflows and live-streaming commerce integration.
Within the integrated marketplace tier, Shopee and Tokopedia exemplify divergent fulfillment philosophies. Shopee anchors transaction volume through logistics control and payment ecosystem integration. Tokopedia occupies a position emphasizing merchant tools and second-city penetration. Lazada represents the cross-border inventory archetype with regional hub dependency.
| Leading Market Players |
|---|
| Shopee |
| Tokopedia |
| Lazada |
| Blibli |
| Bukalapak |
| TikTok Shop |
| Akulaku |
| Orami |
| Ralali |
| Others |
Value Chain & Pricing Dynamics
Mobile wallet penetration replacing cash-on-delivery settlement is compressing transaction costs and redrawing fulfillment geography across the archipelago. This substitution simultaneously collapses the price premium historically attached to outer-island delivery and forces marketplace operators to absorb escrow infrastructure investments.
Pricing Analysis
Bank Indonesia's QRIS interoperability standards dictate the pricing tier structure across merchant settlement flows. Three-tier pricing structure across premium, standard, and economy levels segments by delivery speed and payment method, with same-day fulfillment commanding premiums in Jakarta and Surabaya. Cost compression in economy tiers is intensifying because micro-warehouse density is reducing per-unit last-mile costs. Individual consumers in tier-two cities exhibit the highest price sensitivity, while corporate procurement accounts show minimal elasticity on electronics purchases.
Supply Chain Analysis
Sunda Strait maritime chokepoints between Java and Sumatra constrain inventory velocity during monsoon disruptions. Fulfillment infrastructure draws from China, Singapore, and Malaysia for cross-border electronics and fashion inventory. Last-mile distribution rests on domestic road networks, inter-island sea freight, and hyperlocal micro-warehousing nodes. Single-source vulnerability concentrates in Jakarta-centric cloud data centers subject to Personal Data Protection Law localization mandates. Distribution runs through marketplace-integrated logistics networks rather than independent courier aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's e-commerce market sits at a platform-economics inflection where QRIS standardization and live-streaming commerce convergence are rewriting merchant acquisition economics and infrastructure investment priorities.
For Market Incumbents: Shield merchant relationships through embedded working capital products tied to transaction history, displacing traditional micro-lending channels. Deepen hyperlocal fulfillment density in Surabaya and Bandung before TikTok Shop captures reseller communities. Prioritize captive data center construction in Batam to satisfy Personal Data Protection Law mandates without Singapore routing dependencies.
For New Entrants and Emerging Players: Lead with live commerce infrastructure targeting beauty and fashion verticals where video discovery converts at premium rates. Sulawesi and Papua merchant bases remain the most penetrable geography given sparse incumbent fulfillment coverage. Anchor go-to-market through neighborhood WhatsApp administrator networks rather than direct consumer advertising.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed logistics operators possessing archipelagic warehouse networks but lacking payment ecosystem integration. Long-term viability hinges on 5-10 year data localization compliance cost trajectories and outer-island smartphone penetration curves. Watch merchant onboarding friction metrics as the inflection signal — KYC workflow simplification will separate scalable platforms from capital-constrained competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Live Commerce Platform Integration | Video streaming checkout convergence captures impulse purchase behavior in beauty verticals. |
| Hyperlocal Fulfillment Expansion | Micro-warehouse deployment in tier-two cities compresses delivery windows below same-day thresholds. |
| Embedded Finance Product Launch | Working capital advances tied to seller history displace traditional inventory financing channels. |
| Data Center Localization | Captive Batam and Jakarta facilities satisfy Personal Data Protection Law routing requirements. |
| QRIS-First Merchant Onboarding | Unified payment acceptance accelerates seller activation in street-level retail segments. |
Study Parameters
Operator-level perspectives from marketplace logistics directors, e-wallet product managers, merchant onboarding specialists, and provincial digital economy officers anchored the qualitative base. These interviews combined with Bank Indonesia regulatory filings, Ministry of Communication and Informatics licensing databases, customs trade flow records, and platform transaction disclosures. Bottom-up merchant density estimates and top-down gross merchandise value projections underwent iterative triangulation.
Sensitivity analysis tested forecast robustness across alternative smartphone penetration curves and logistics cost scenarios. The analytical framework modeled product category, platform type, payment method, and customer type dimensions across the projection horizon. CAGRs derived from segment-level adoption curves, archipelagic fulfillment cost trajectories, and regulatory implementation timelines. QRIS transaction volume growth and outer-island merchant onboarding velocity served as primary forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained mobile wallet penetration acceleration or stable fuel price environments would require recalibration. Forecasts reflect documented assumptions regarding Personal Data Protection Law enforcement consistency and central-provincial regulatory alignment. Practitioners should keep alternative scenarios live as data localization compliance costs and live commerce adoption rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Europe FMCG B2B E-Commerce Market
E-Commerce Solutions
Retail E-Commerce Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
Lithuania E-Commerce Market
E-Commerce Solutions
E-Commerce App Market
E-Commerce Solutions
Bedding E-Commerce Platform Market
E-Commerce Solutions
Netherlands E-Commerce Market
E-Commerce Solutions
Nigeria E-Commerce Market
E-Commerce Solutions
US Pharma E-Commerce Market
E-Commerce Solutions
Asia-Pacific FMCG B2B E-Commerce Market
E-Commerce Solutions
Russia Alcohol E-Commerce Market
E-Commerce Solutions
Middle East and Africa E-Commerce Market
E-Commerce Solutions
E-Commerce Buy Now Pay Later Market
E-Commerce Solutions
E-Tailing Market
E-Commerce Solutions
Multi-Channel E-Commerce Software Market
E-Commerce Solutions
Global Online Book Services Market