
 E-Tailing Market | 2026-2036
E-Tailing Market Size, Share, and Industry Trends Forecast 2026-2036
E-Tailing Market Analysis
Buyer concentration in the e-tailing sector is pivoting as millions of small merchants fragment what was once a landscape dominated by large retail chains. Amazon.com Inc. leverages its fulfillment infrastructure to anchor third-party seller ecosystems across multiple continents. Alibaba Group Holding Limited sustains dominance through captive payment systems and integrated logistics networks. JD.com Inc. differentiates via in-house warehousing and rapid delivery guarantees that tighten inventory control.
E-tailing denotes the commercial distribution of goods and services through internet-connected platforms, relying on encrypted payment gateways, real-time inventory APIs, and algorithmic recommendation engines to match supply with demand. The product category dimension shows electronics and cosmetics commanding margin pools due to repeat purchase frequency and premium positioning, while the sales channel dimension reveals mobile apps capturing the fastest growth trajectory as smartphone penetration deepens. Customer type segmentation indicates D2C models expanding fastest as brands bypass intermediaries, though B2C marketplaces still occupy the largest volume share.
The EU Digital Services Act and GDPR impose transparency obligations and data handling standards that reshape platform architecture across Europe, while the FTC in the United States scrutinizes marketplace fee structures and seller treatment practices. China's SAMR enforces antitrust measures that constrain exclusive merchant arrangements on domestic platforms. Stakeholders must monitor how divergent regulatory philosophies across these jurisdictions fragment compliance requirements and alter competitive dynamics.
Market Dynamics
Mobile-first purchasing behavior in India's tier-two cities is fragmenting buyer concentration as millions of small merchants gain platform access through simplified onboarding tools and localized payment interfaces.
Growth Catalysts
- EU Digital Services Act:Marketplace accountability mandates across Europe are forcing platform architecture upgrades that improve seller transparency and consumer trust mechanisms.
- Logistics API Integration:Real-time inventory synchronization and automated fulfillment routing compress delivery windows and reduce working capital requirements for third-party sellers.
- India's Tier-Two Urban Clusters:Mobile penetration and vernacular-language interfaces unlock first-time e-commerce adoption among previously underserved consumer bases.
Market Restraints
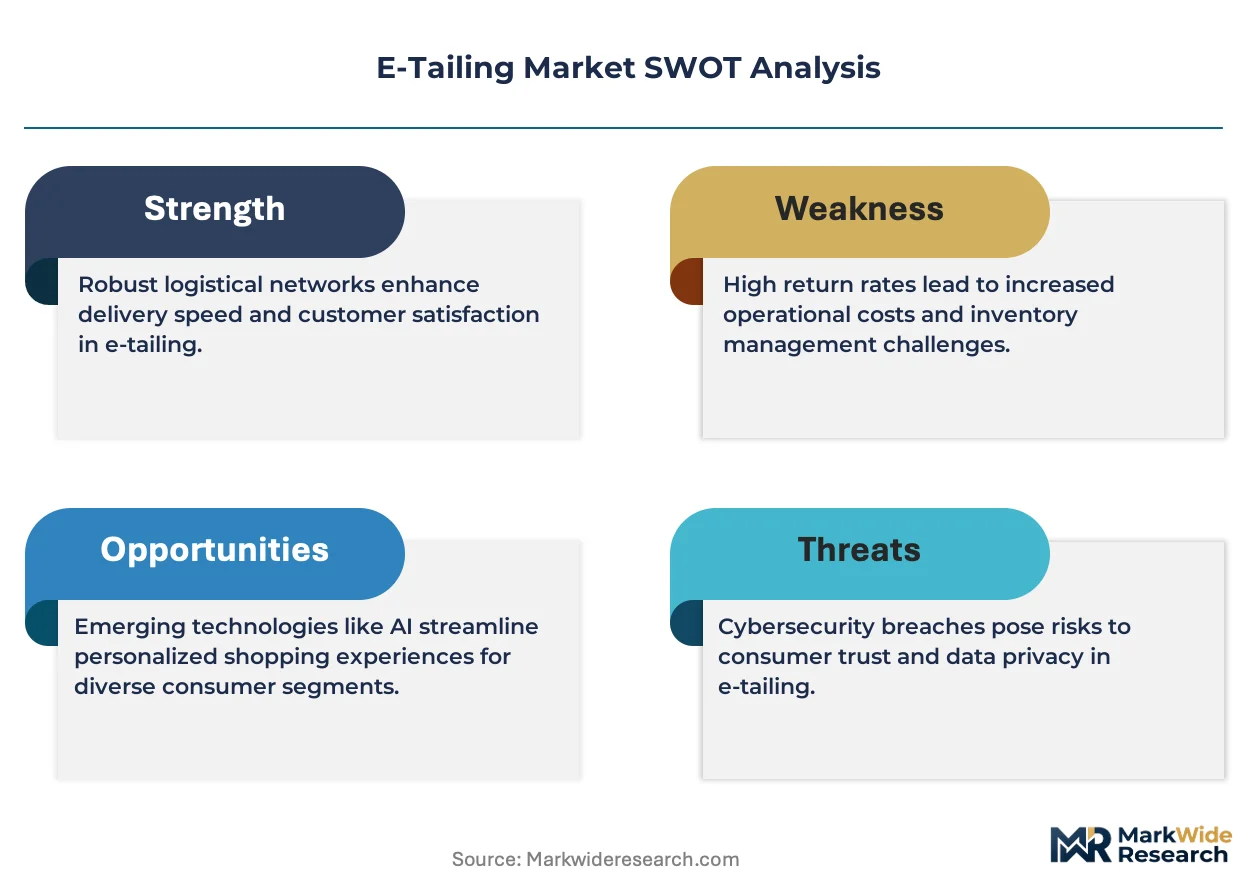
- Last-Mile Delivery Cost Volatility:Fuel price fluctuations and labor scarcity in dense urban corridors erode margin structures for rapid delivery guarantees.
- Cross-Border Customs Friction:Divergent de minimis thresholds and documentation requirements between the United States, European Union, and China fragment international seller expansion.
- Data Localization Mandates:Russia's data sovereignty laws and China's cybersecurity regulations force redundant infrastructure investments that duplicate operational overhead.
Strategic Opportunities
- Embedded Finance Convergence:Integration of buy-now-pay-later instruments with checkout flows captures incremental transaction volume from credit-constrained buyer segments.
- Recommerce Platform Expansion:Certified pre-owned electronics and apparel marketplaces address sustainability-conscious consumers while extending product lifecycle monetization.
- India's Open Network for Digital Commerce:Government-mandated interoperability protocols break platform lock-in and enable decentralized seller discovery across competing marketplaces.
Industry Challenges
- Warehouse Automation Talent Scarcity:Shortages of robotics technicians and inventory optimization specialists constrain fulfillment network scaling.
- GDPR Compliance Architecture:Consent management and data portability requirements demand continuous engineering investment that diverts resources from core platform development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Tailing Market |
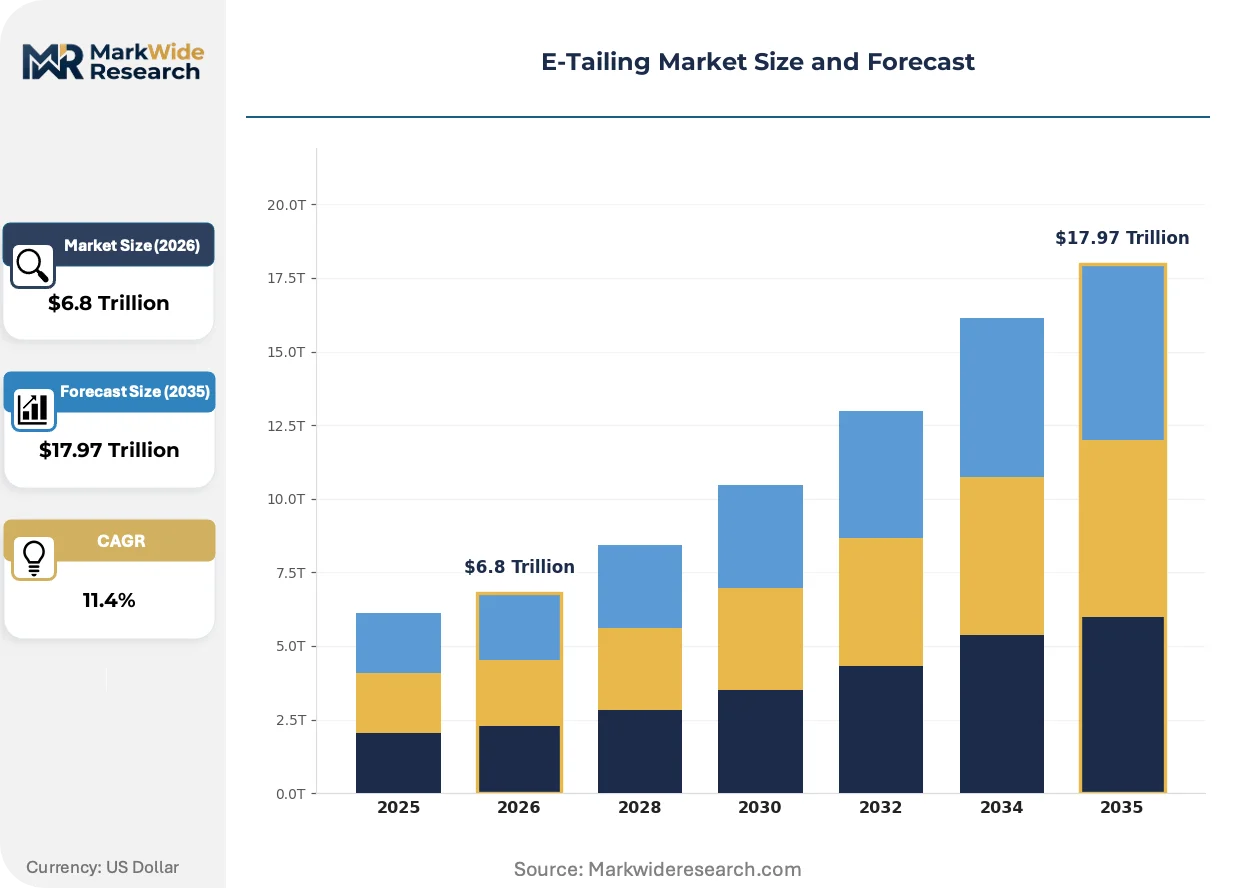
| Market Size in 2026 | $6.8 Trillion |
| Market Size in 2035 | $17.97 Trillion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Category: Electronics, Apparel, Home Goods, Cosmetics Sales Channel: Direct Online, Marketplace, Social Media, Mobile Apps Customer Type: B2C, B2B, C2C, D2C Delivery Model: Same-Day Delivery, Standard Shipping, Click & Collect, Drop Shipping |
| Companies Covered | Amazon.com Inc., Alibaba Group Holding Limited, Walmart Inc., JD.com Inc., eBay Inc., Shopify Inc., Rakuten Group Inc., MercadoLibre Inc., Zalando SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Tailing Market Emerging Trajectories
Algorithmic personalization engines and embedded payment infrastructures are compressing the path from product discovery to transaction completion across every major e-tailing corridor.
Live-stream commerce interfaces are overtaking static product catalogs as the dominant engagement format in Asian markets. Individual sellers and brand accounts on platforms like Douyin and Taobao deploy real-time video demonstrations with integrated checkout buttons. This format collapses the consideration phase and is overtaking traditional search-based purchasing in cosmetics and fashion verticals.
GDPR enforcement actions by European data protection authorities are mandating granular consent architectures and algorithmic explainability. Platforms must now disclose how recommendation engines rank products and provide opt-out mechanisms for profiling-based suggestions. Fashion and electronics retailers with complex personalization stacks face the steepest compliance retrofit costs and are accelerating investment in privacy-preserving collaborative filtering techniques.
Direct-to-consumer brands are bypassing marketplace intermediaries through proprietary mobile applications and subscription models. Beauty and wellness verticals lead this shift, capturing first-party data and repeat purchase commitments that third-party seller fees previously eroded. This pattern concentrates in North American and Western European markets where consumer willingness to manage multiple brand-specific apps remains highest.
E-Tailing Market Segmentation
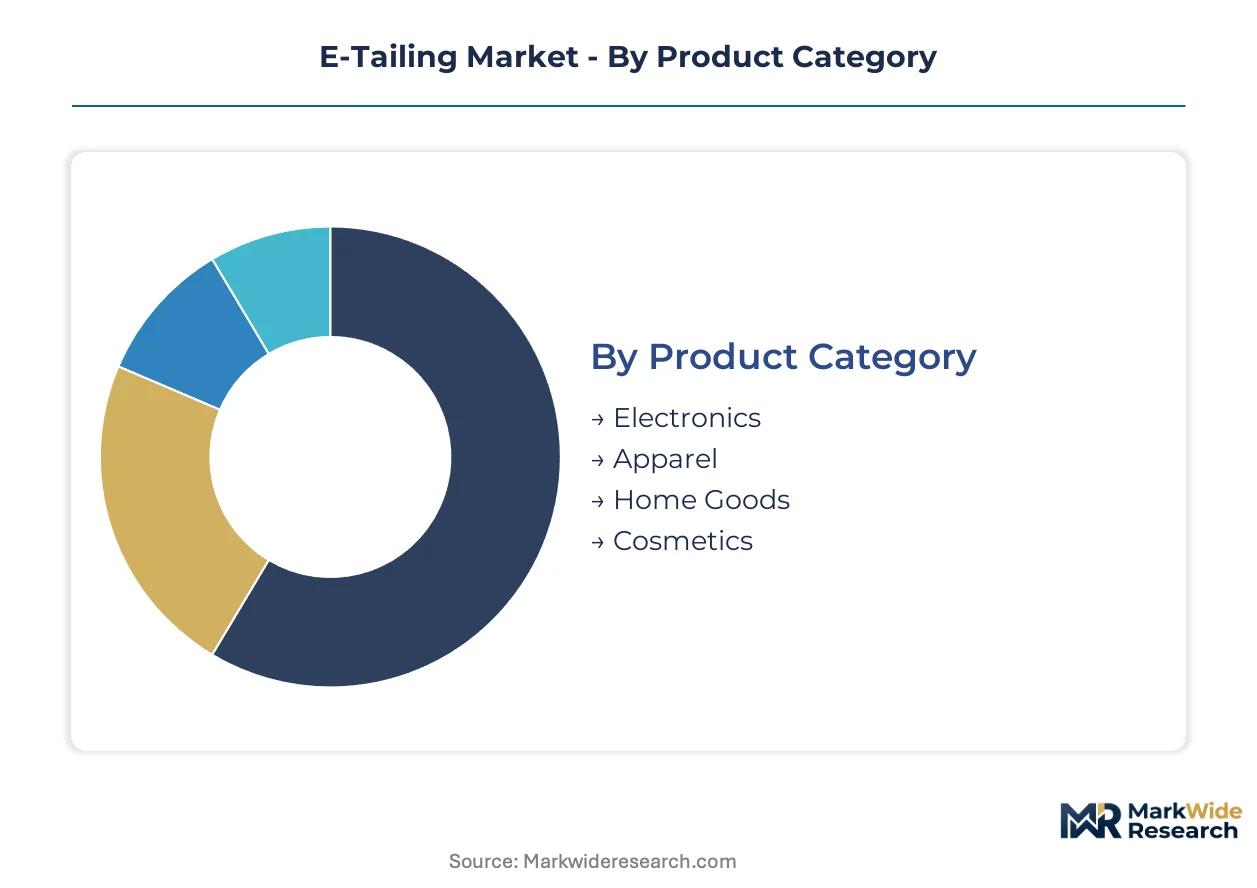
E-tailing segmentation reveals how purchase frequency, margin structure, and logistics requirements fragment platform strategies across distinct commercial corridors. Upgrade cycles in electronics and cosmetics compress repurchase windows, while delivery speed expectations diverge sharply between urban and suburban geographies.
Product Category:
Replacement cycles and technology refresh rates determine inventory velocity and working capital intensity across merchandise verticals.
- Electronics:Smartphone and laptop refresh cycles average 24-36 months, concentrating demand in India's tier-two cities where mobile-first purchasing accelerates fastest. Warranty complexity and return rates demand specialized reverse logistics infrastructure that elevates platform operational costs.
- Cosmetics:Repeat purchase intervals of 6-10 weeks sustain subscription-model viability and first-party data accumulation for D2C brands. Premium positioning in this vertical captures margin pools that offset high customer acquisition expenditures across Asian and European markets.
- Apparel:Seasonal trend volatility requires predictive demand forecasting and flexible supplier relationships.
- Home Goods:Bulky fulfillment constraints favor marketplace models with distributed warehousing networks.
Volume placements concentrate in Electronics; the faster expansion belongs to Cosmetics.
Sales Channel:
Channel economics hinge on customer acquisition cost differentials and checkout friction reduction.
- Mobile Apps:Native applications compress path-to-purchase through biometric authentication and one-tap payment storage, climbing the fastest in India's tier-two urban clusters. Push notification re-engagement sustains session frequency that mobile web interfaces fail to replicate.
- Marketplace:Aggregated seller ecosystems reduce inventory risk for platform operators while capturing transaction fees from third-party merchants. Amazon and Alibaba anchor this channel through fulfillment infrastructure investments across multiple continents.
- Direct Online:Proprietary websites capture first-party data but demand standalone marketing expenditure.
- Social Media:Live-stream interfaces collapse consideration phases in cosmetics and fashion verticals.
Marketplace channels absorb the largest transaction volume; mobile apps gain share fastest among first-time e-commerce adopters.
Customer Type:
Procurement patterns and decision-unit size differentiate commercial requirements across buyer archetypes.
- B2C:Individual purchasing decisions favor algorithmic personalization and rapid fulfillment guarantees that tighten inventory control requirements. This segment retains the largest volume share across North American and Western European corridors.
- D2C:Brand-owned channels bypass intermediary fees while capturing subscription commitments and repeat purchase data. Beauty and wellness verticals lead this shift through proprietary mobile applications.
- B2B:Bulk procurement and negotiated terms demand specialized account management infrastructure.
- C2C:Peer-to-peer transactions concentrate in recommerce platforms for certified pre-owned electronics.
B2C retains dominant volume position; D2C models expand most quickly as brands bypass marketplace intermediaries.
Delivery Model:
Speed-tier differentiation aligns capital deployment with customer willingness-to-pay gradients.
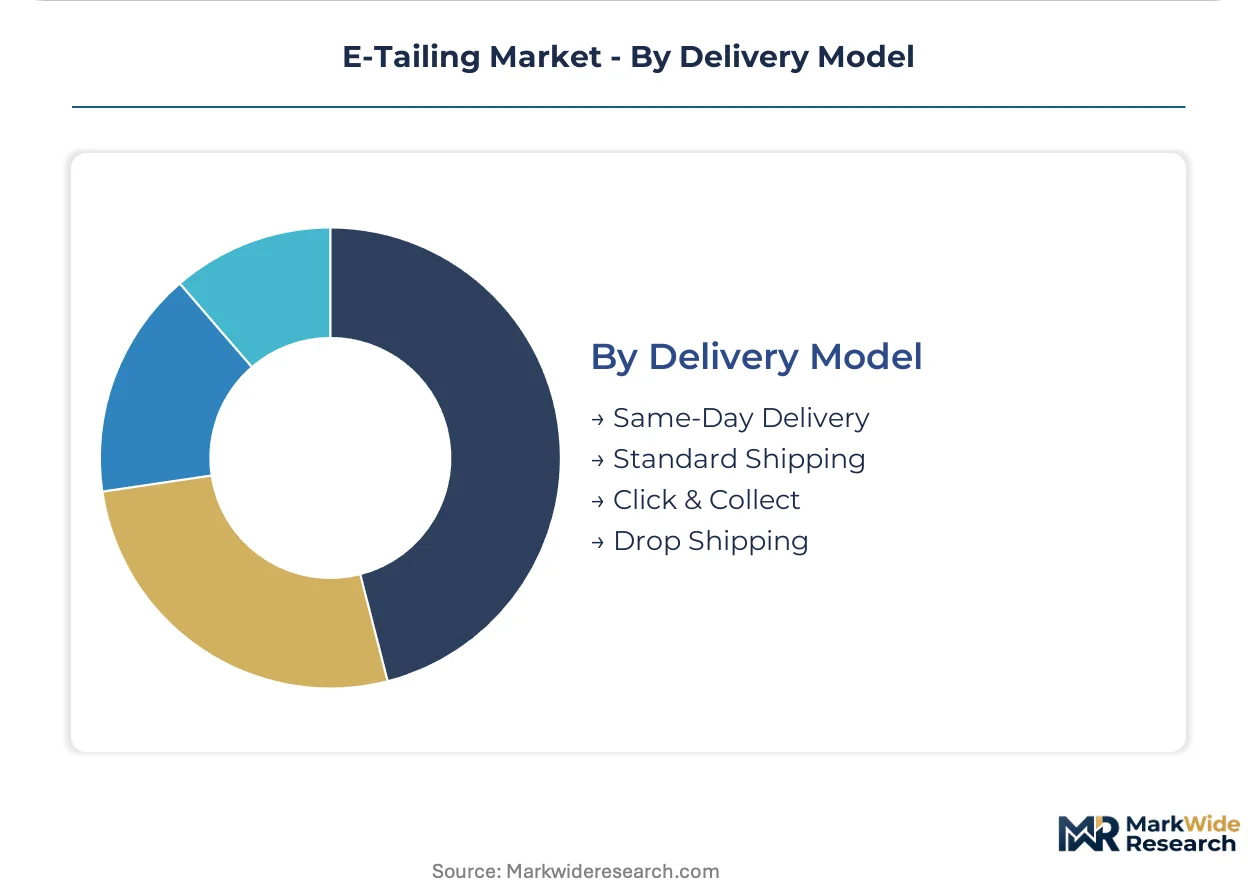
- Same-Day Delivery:Urban density and micro-fulfillment center networks enable rapid delivery guarantees that erode margin structures through labor scarcity and fuel price volatility. JD.com anchors this model through in-house warehousing across Chinese metropolitan corridors.
- Click & Collect:Store-integrated fulfillment reduces last-mile costs while driving foot traffic to physical retail locations. This model gains traction in European markets where GDPR-constrained data environments favor hybrid online-offline customer relationships.
- Standard Shipping:Cost-optimized routing sustains rural and suburban penetration where speed premiums fail to justify expenditure.
- Drop Shipping:Inventory-free fulfillment minimizes working capital for small merchants but fragments quality control.
Standard shipping retains volume concentration; same-day delivery climbs fastest in dense urban corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the largest transaction volume through integrated payment-logistics ecosystems, while India and Southeast Asian corridors exhibit the fastest adoption velocity among first-time digital buyers.
United States
Mobile app penetration and same-day delivery infrastructure sustain transaction density in metropolitan corridors. The FTC scrutinizes marketplace fee structures and seller treatment practices through ongoing enforcement actions. California's Silicon Valley and Seattle anchor fulfillment technology development and cloud infrastructure deployment for platform operators.
China
Live-stream commerce interfaces and super-app ecosystems compress purchase paths in cosmetics and fashion verticals. SAMR enforces antitrust measures that constrain exclusive merchant arrangements on domestic platforms. The Yangtze River Delta and Pearl River Delta concentrate warehousing automation and last-mile robotics manufacturing.
India
Mobile-first purchasing behavior in tier-two cities fragments buyer concentration as vernacular-language interfaces expand access. The Open Network for Digital Commerce mandates interoperability protocols that break platform lock-in. Bangalore and Hyderabad anchor logistics technology development and seller onboarding tool innovation.
Germany
GDPR compliance architecture and click-and-collect fulfillment sustain hybrid online-offline customer relationships. The EU Digital Services Act imposes transparency obligations that reshape platform accountability across the bloc. Berlin and Munich concentrate D2C brand headquarters and sustainable packaging innovation clusters.
Brazil
Installment payment integration and marketplace seller expansion address credit-constrained buyer segments in urban corridors. ANVISA regulates cosmetics and electronics import standards that affect cross-border seller compliance. São Paulo anchors MercadoLibre's fulfillment network scaling and fintech-payment convergence development.
E-Tailing Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue embedded finance and recommerce specialization. The vendor base stratifies across three maturity tiers: integrated ecosystem operators with captive logistics, modular platform providers enabling third-party seller independence, and vertical specialists dominating single-category niches. Dominant competitive moves include fulfillment infrastructure expansion into tier-two urban clusters and strategic API partnerships with logistics providers.
Within the integrated ecosystem tier, Amazon.com Inc. and Alibaba Group Holding Limited exemplify archetypes that anchor third-party seller networks through proprietary fulfillment infrastructure. JD.com Inc. occupies a position representing in-house warehousing and rapid delivery guarantee differentiation. Among modular platform specialists, Shopify Inc. sits within the merchant independence archetype, enabling direct-to-consumer brand proliferation without marketplace fee structures.
| Leading Market Players |
|---|
| Amazon.com Inc. |
| Alibaba Group Holding Limited |
| Walmart Inc. |
| JD.com Inc. |
| eBay Inc. |
| Shopify Inc. |
| Rakuten Group Inc. |
| MercadoLibre Inc. |
| Zalando SE |
| Others |
Supply Flow & Price Mechanics
Small and medium enterprise merchants concentrate transaction volume in the e-tailing sector, anchoring a per-unit transactional pricing model where marketplace fees and fulfillment costs dominate margin structures. Platform operators extract value through commission tiers and logistics markups that scale with seller volume rather than subscription commitments.
Pricing Analysis
Volume placements concentrate in standard-tier fulfillment with compressed margins, while premium same-day delivery and subscription-based loyalty programs capture margin pools. Price differentiation rests on delivery speed guarantees and inventory proximity to urban demand clusters. Cost compression in rapid delivery tiers is intensifying because fuel volatility and labor scarcity erode service-level economics. Small merchants in India's tier-two cities exhibit highest price sensitivity, whereas D2C beauty brands in North American corridors demonstrate lowest elasticity due to first-party data capture.
Supply Chain Analysis
Robotics technician scarcity in China's Yangtze River Delta and Pearl River Delta manufacturing corridors constrains warehouse automation deployment timelines. Fulfillment infrastructure draws from China, the United States, and Germany for automated sorting systems, last-mile vehicle fleets, and cloud orchestration platforms. Single-source vulnerability concentrates in micro-fulfillment center robotics sourced from Chinese OEMs. Distribution runs through platform-operated fulfillment networks with third-party seller API integration for inventory synchronization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The e-tailing sector occupies a technology-transition phase where live-stream commerce interfaces displace static product catalogs as the dominant engagement format across Asian corridors.
For Market Incumbents: Hedge against live-stream commerce disintermediation by acquiring proprietary video infrastructure and influencer network management capabilities. Fortify fulfillment density in India's tier-two urban clusters before ONDC interoperability protocols fragment platform lock-in. Vertical integration into last-mile robotics manufacturing reduces exposure to automation talent scarcity.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in embedded finance instruments offers white-space penetration for credit-constrained buyer segments in Brazil and Southeast Asia. Target recommerce platform certification services where sustainability-conscious consumers in European corridors demand authenticated pre-owned electronics. Deploy API-first logistics partnerships rather than capital-intensive warehouse buildouts.
For Investors and Strategic Acquirers: The window for entry favors modular platform providers enabling merchant independence without marketplace fee structures. Long-term viability hinges on first-party data accumulation capabilities that survive GDPR consent architecture evolution. Monitor India's ONDC adoption velocity as the inflection signal for platform interoperability tipping points.
| Strategic Initiative | Industry Significance |
|---|---|
| Live-Stream Commerce Infrastructure | Video-native checkout interfaces compress consideration phases in cosmetics and fashion verticals on Douyin and Taobao. |
| Fulfillment Network Expansion | Micro-fulfillment center deployment in India's tier-two cities captures mobile-first purchasing acceleration. |
| Embedded Finance Integration | Buy-now-pay-later instruments at checkout capture incremental volume from credit-constrained Brazilian buyer segments. |
| Recommerce Platform Certification | Authenticated pre-owned electronics marketplaces address GDPR-constrained sustainability demand in German corridors. |
| Logistics API Partnership | Real-time inventory synchronization reduces working capital requirements for third-party sellers on Shopify-enabled stores. |
Methodological Framework
SEC 10-K filings, customs and trade databases, and App Annie mobile commerce metrics formed the secondary backbone for this analysis. Primary interviews with marketplace seller operations directors, logistics API product managers, and D2C brand technology officers validated demand-side assumptions. Bottom-up transaction volume modeling and top-down GDP-correlation approaches triangulated market sizing across the projection horizon.
Historical trendline analysis of e-tailing penetration rates by product category established baseline growth trajectories. The analytical framework modeled segmentation dimensions including sales channel, delivery model, customer type, and regional regulatory cluster throughout the forecast period. CAGRs were derived from logistic diffusion curves fitted to mobile penetration and vernacular interface adoption patterns in emerging corridors.
Inputs from platform operator disclosures and logistics provider filings were available through the study window; gaps in privately held D2C brand financials introduce uncertainty bands around subscription revenue projections. Forecasts reflect assumptions regarding ONDC interoperability enforcement and GDPR consent architecture evolution. Material deviation in live-stream commerce adoption velocity or warehouse automation talent availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
E-Commerce Search Software Market
E-Commerce Solutions
Cyprus E-Commerce Market
E-Commerce Solutions
Hyperlocal Delivery App Market
E-Commerce Solutions
Czech Republic E-Commerce Market
E-Commerce Solutions
Spain E-Commerce Logistics Market
E-Commerce Solutions
IT Consumer Electronics E-Commerce Market
E-Commerce Solutions
E-Commerce App Market
E-Commerce Solutions
Slovak Republic E-Commerce Market
E-Commerce Solutions
E-Commerce Fulfillment Services Market
E-Commerce Solutions
Online to Offline Commerce Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
Albania E-Commerce Market
E-Commerce Solutions
India D2C E-Commerce Market
E-Commerce Solutions
Ireland E-Commerce Market
E-Commerce Solutions
Bedding E-Commerce Platform Market
E-Commerce Solutions
E-Commerce Buy Now Pay Later Market