
 Asia-Pacific FMCG B2B E-Commerce Market | 2026-2036
Asia-Pacific FMCG B2B E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific FMCG B2B E-Commerce Market Insights
Subscription-based replenishment software is restructuring procurement relationships between manufacturers and recurring buyers in the Asia-Pacific FMCG B2B E-Commerce Market. Alibaba Group Holding Ltd anchors its position through integrated logistics and payment ecosystems across China and Southeast Asia. JD.com leverages its proprietary warehouse automation to sustain same-day fulfillment guarantees for restaurant and retail chain clients. IndiaMART InterMESH Ltd dominates India's fragmented supplier base by connecting regional FMCG producers with institutional buyers through verifiable catalog systems.
Asia-Pacific FMCG B2B E-Commerce constitutes digital wholesale transactions for fast-moving consumer goods between businesses, operating through cloud-native platforms that integrate inventory APIs, dynamic pricing algorithms, and last-mile logistics orchestration to replace traditional distributor networks. The primary commercial purpose centers on reducing working capital cycles for buyers while expanding geographic reach for suppliers without physical branch infrastructure. Groceries and beverages occupy the largest transaction volume pools due to perishable inventory velocity and recurring purchase patterns among restaurant and eatery end users. Online marketplace distribution channels capture accelerating share as multi-vendor platforms aggregate fragmented supplier bases across Indonesia, Vietnam, and the Philippines. Subscription pricing models concentrate margin retention among platforms that lock in recurring procurement commitments from retail chain clients.
India's BIS digital marketplace standards, China's SAMR e-commerce compliance frameworks, and Indonesia's trade ministry logistics regulations collectively shape platform architecture, data localization requirements, and cross-border payment interoperability across the region. Japan's METI guidelines on SME digitization further channel subsidy flows toward B2B onboarding tools and inventory management integrations. Stakeholders must monitor evolving data sovereignty mandates and customs digitization timelines as these determine which platforms can operate across multiple national jurisdictions without operational fragmentation.
Market Dynamics
Subscription-based replenishment software is restructuring procurement relationships between manufacturers and recurring buyers across the Asia-Pacific region. Platform operators now compete on lock-in duration and inventory API integration depth rather than transaction fees alone.
Growth Catalysts
- India's PLI scheme:The production-linked incentive for digital infrastructure and logistics modernization compresses delivery timelines for tier-two city distributors. Warehouse automation subsidies accelerate platform onboarding.
- Small-format retail chains:Southeast Asian convenience store networks are accelerating platform adoption to consolidate fragmented supplier relationships. These buyers prioritize consolidated invoicing over price arbitrage.
- Cloud-native inventory APIs:Real-time stock synchronization between manufacturer ERPs and buyer procurement portals eliminates manual reorder cycles. Restaurant chains leverage this for perishable goods velocity.
Market Restraints
- Last-mile logistics fragmentation:Indonesia's archipelago geography forces platforms to maintain heterogeneous delivery partnerships. Cost per shipment varies by island cluster.
- Data localization mandates:China's SAMR e-commerce compliance frameworks and India's BIS digital marketplace standards impose server location requirements. Cross-border platform architecture faces operational fragmentation.
- Cash conversion cycle pressure:Traditional distributor networks extend supplier payment terms beyond platform-standard escrow periods. Manufacturer switching costs include working capital restructuring.
Strategic Opportunities
- Vietnam's urban corridors:Ho Chi Minh City and Hanoi present underpenetrated demand for restaurant procurement platforms. Local supplier digitization lags behind buyer readiness.
- Dynamic pricing algorithms:Convergence of demand forecasting models and real-time logistics cost indexing enables surge-adjusted wholesale rates. Volume commitments lock in margin retention.
- Japan's METI SME digitization guidelines:Subsidy flows toward B2B onboarding tools and inventory management integrations reduce platform customer acquisition costs for mid-size manufacturers.
Industry Challenges
- Legacy distributor relationship management:Platforms must disintermediate entrenched credit-based supplier networks without triggering supply boycotts. Transition pricing bridges create margin compression.
- Multi-jurisdiction compliance engineering:Engineering teams must architect separate data pipelines for China's SAMR, India's BIS, and Indonesia's trade ministry logistics regulations. Feature parity across instances delays rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific FMCG B2B E-Commerce Market |
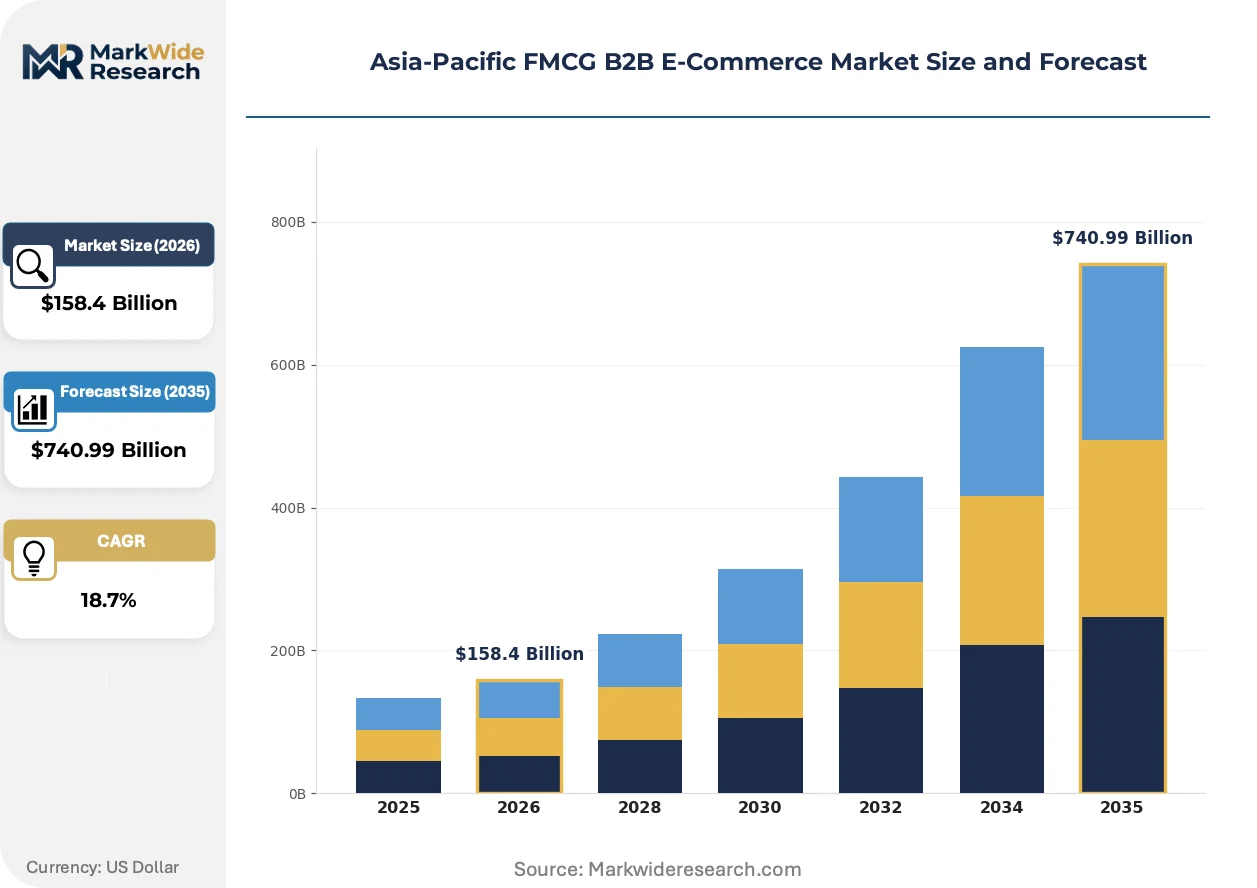
| Market Size in 2026 | $158.4 Billion |
| Market Size in 2035 | $740.99 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Groceries, Beverages, Personal Care, Household Products End User: Wholesalers, Retail Chains, Restaurants, Eateries Distribution Channel: Direct Sales, Online Marketplace, Auction, Third-Party Logistics Pricing Model: Subscription, Volume-Based, Dynamic Pricing, Fixed Pricing |
| Companies Covered | Alibaba Group Holding Ltd, JD.com, IndiaMART InterMESH Ltd, Flipkart Online Services Pvt. Ltd., Rakuten Group, Inc., Lazada Group, Shopee, Tokopedia, Udaan, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific FMCG B2B E-Commerce Market Trends and Innovations
Platform operators are racing to embed financial services and predictive analytics into core procurement workflows. The competitive frontier has shifted from catalog breadth to working capital optimization tools.
Blockchain-based provenance tracking is rewriting trust architectures between dispersed suppliers and institutional buyers. Restaurant chains in Singapore and Sydney now mandate lot-level traceability for high-value beverage imports. This technology is compressing dispute resolution cycles from weeks to automated smart-contract settlements.
Indonesia's trade ministry logistics regulations now mandate real-time shipment visibility for cross-island freight. Platforms must integrate with government tracking APIs or face route licensing restrictions. Cold-chain beverage distributors are most affected, restructuring fleet partnerships to comply.
Buyer committees at retail chains now specify API-first procurement as a vendor qualification threshold. Static catalog browsing loses share to automated reorder systems triggered by POS depletion signals. This pattern concentrates most visibly in India's tier-two cities where labor cost arbitrage no longer offsets stockout penalties.
Asia-Pacific FMCG B2B E-Commerce Market Segmentation
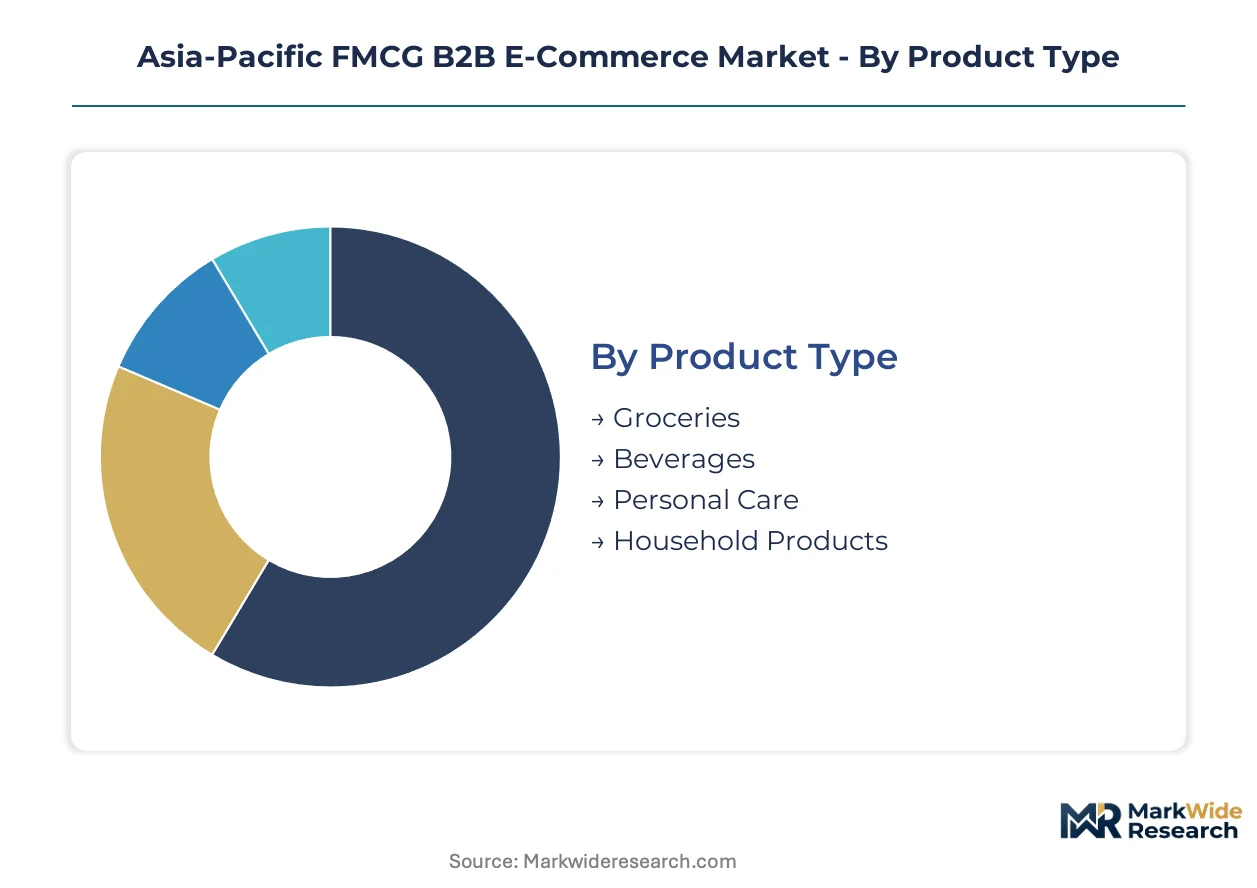
Segmentation in the Asia-Pacific FMCG B2B E-Commerce Market reveals how procurement workflows differ across buyer types and product velocity requirements. Platform operators configure inventory APIs, payment terms, and logistics orchestration differently for each segment combination.
Product Type:
Upgrade cycles in this category track perishability windows and SKU turnover rates, with faster-moving categories demanding tighter platform integration.
- Groceries:Fresh produce, packaged foods, and dairy products require temperature-controlled logistics APIs and expiration-date synchronization. Restaurant chains in Ho Chi Minh City and Jakarta drive demand for daily replenishment workflows with 4-hour delivery windows.
- Beverages:Alcoholic and non-alcoholic drinks carry higher margin retention but heavier freight costs. Cold-chain distributors in Indonesia's trade corridor face route licensing mandates from the trade ministry's tracking API requirements.
- Personal Care:Skincare, haircare, and hygiene products exhibit lower replenishment frequency with higher SKU diversity. Retail chains consolidate these into monthly procurement batches.
- Household Products:Cleaning supplies and paper goods occupy stable demand curves with predictable seasonality. Warehouse automation subsidies under India's PLI scheme accelerate platform onboarding for these bulk categories.
Groceries sits at the top of the volume ranking, with Beverages climbing the fastest.
End User:
Cost tier differentiation separates enterprise-grade procurement portals from self-serve interfaces, with integration depth scaling to buyer sophistication.
- Wholesalers:Traditional distributors transitioning to digital platforms require credit-term bridging and multi-supplier consolidation tools. India's tier-two city distributors face working capital restructuring to match platform escrow periods.
- Retail Chains:Convenience store networks across Southeast Asia prioritize consolidated invoicing and automated reorder triggers from POS depletion signals. These buyers specify API-first procurement as a vendor qualification threshold.
- Restaurants:Full-service establishments demand lot-level traceability for beverage imports and perishable velocity management. Singapore and Sydney operators now mandate blockchain-based provenance tracking.
- Eateries:Small-format food service outlets concentrate demand in India's urban corridors and Vietnam's Hanoi district, where labor cost arbitrage no longer offsets stockout penalties.
Retail Chains commands the largest procurement volume, with Eateries expanding most quickly.
Distribution Channel:
Application context determines whether buyers prioritize price transparency, speed guarantees, or supplier verification depth.
- Direct Sales:Manufacturer-to-buyer platforms bypass intermediary margins but require dedicated sales engineering. Japan's METI SME digitization subsidies reduce customer acquisition costs for these deployments.
- Online Marketplace:Multi-vendor platforms aggregate fragmented supplier bases across Indonesia, Vietnam, and the Philippines. These channels capture accelerating share through dynamic pricing algorithms and real-time inventory synchronization.
- Auction:Spot-buying mechanisms serve surplus inventory clearance and seasonal demand spikes. Usage concentrates in beverages and household products with flexible delivery windows.
- Third-Party Logistics:Outsourced fulfillment partnerships address Indonesia's archipelago geography through heterogeneous delivery networks. Cost per shipment varies by island cluster under trade ministry visibility mandates.
Online Marketplace leads channel volume, with Third-Party Logistics gaining share fastest.
Pricing Model:
Margin structure and customer lifetime value calculations favor recurring commitment mechanisms over transactional fee extraction.
- Subscription:Lock-in pricing for recurring replenishment compresses working capital cycles and deepens platform integration. Restaurant chains leverage these models for perishable goods velocity.
- Volume-Based:Tiered discounts scale to procurement batch size, rewarding consolidated purchasing across SKU categories. Wholesale buyers in India's fragmented supplier base favor this structure.
- Dynamic Pricing:Surge-adjusted rates respond to real-time logistics cost indexing and demand forecasting models. These algorithms enable margin retention through volume commitment locks.
- Fixed Pricing:Stable rate cards suit household products and personal care with predictable demand curves. Traditional distributors extend these terms to maintain legacy relationships.
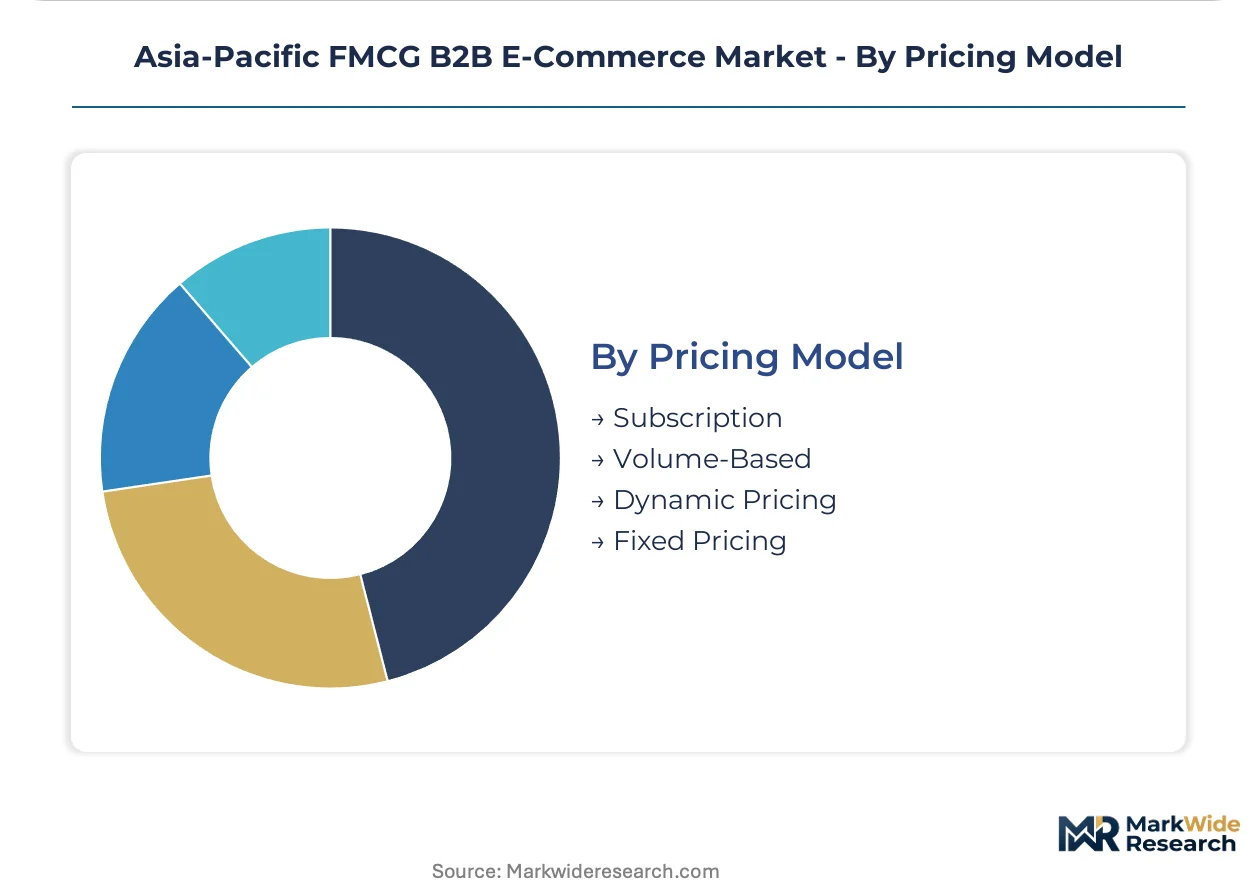
Subscription holds the highest margin retention, with Dynamic Pricing showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting platform investment toward jurisdictions with harmonized data frameworks and subsidized logistics modernization. India's PLI scheme and Japan's METI guidelines create compliance-cost gaps that attract cross-border operator entry.
India
Tier-two city distributors and small-format retail chains are compressing procurement cycles through cloud-native inventory APIs. The BIS digital marketplace standards impose server localization requirements that fragment platform architecture. Warehouse automation subsidies under the PLI scheme accelerate onboarding in Maharashtra's Mumbai-Pune corridor.
China
Restaurant chains and convenience store networks demand same-day fulfillment guarantees through integrated logistics ecosystems. SAMR e-commerce compliance frameworks mandate data sovereignty protocols that increase operational overhead. Yangtze River Delta manufacturers leverage proprietary warehouse automation to sustain velocity commitments.
Indonesia
Cross-island beverage distributors face route licensing mandates from the trade ministry's real-time tracking API requirements. The archipelago geography forces heterogeneous delivery partnerships with cost variance by island cluster. Cold-chain operators in Jakarta-Bandung corridor restructure fleet partnerships to comply.
Japan
SME manufacturers access subsidy flows toward B2B onboarding tools and inventory management integrations under METI digitization guidelines. Mid-size producers in Kanto region reduce platform customer acquisition costs through subsidized ERP integrations. Restaurant procurement platforms mandate lot-level traceability for high-value imports.
Vietnam
Ho Chi Minh City and Hanoi present underpenetrated demand for restaurant procurement platforms with buyer readiness outpacing supplier digitization. Local distributors lag in cloud-native API adoption versus regional chain requirements. Dynamic pricing algorithms gain traction among urban corridor wholesalers consolidating fragmented supplier relationships.
Asia-Pacific FMCG B2B E-Commerce Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated logistics operators commanding premium positioning in fulfillment-guaranteed tiers. The vendor base concentrates around three strategic archetypes: ecosystem-anchored platforms with captive payment and logistics infrastructure, vertical specialists optimizing perishable velocity workflows, and marketplace aggregators connecting fragmented regional supplier bases. Dominant competitive moves include M&A to acquire last-mile logistics networks and strategic partnerships to embed financial services into procurement workflows.
Among China-based ecosystem operators, Alibaba Group Holding Ltd and JD.com exemplify the integrated infrastructure archetype through captive logistics and payment systems. IndiaMART InterMESH Ltd occupies a position within the marketplace aggregation tier, connecting regional FMCG producers with institutional buyers through verifiable catalog systems. These three companies represent divergent strategic bets on whether procurement relationships consolidate around fulfillment guarantees, supplier verification depth, or working capital optimization tools.
| Leading Market Players |
|---|
| Alibaba Group Holding Ltd |
| JD.com |
| IndiaMART InterMESH Ltd |
| Flipkart Online Services Pvt. Ltd. |
| Rakuten Group, Inc. |
| Lazada Group |
| Shopee |
| Tokopedia |
| Udaan |
| Others |
Pricing and Supply Chain Analysis
Retail chain procurement committees across Southeast Asia concentrate demand around subscription-based replenishment contracts, locking in pricing structures that reward inventory API integration depth over transactional fee competition. This buyer archetype's preference for consolidated invoicing and automated reorder triggers compresses margin retention into platforms that can guarantee perishable velocity.
Pricing Analysis
Capacity additions in India's tier-two logistics corridors are reshaping price floors for same-day fulfillment guarantees. Subscription pricing dominates margin retention among platforms securing recurring procurement commitments from restaurant and retail chain clients. Price differentiation separates cold-chain beverage distributors with route licensing compliance from standard freight operators facing surge-adjusted wholesale rates. Cost compression in Indonesia's archipelago logistics is intensifying because heterogeneous delivery partnerships carry island-cluster cost variance. Small-format eateries in Vietnam's urban corridors exhibit highest price sensitivity, while Singapore restaurant chains mandating blockchain-based provenance tracking show least sensitivity.
Supply Chain Analysis
India's PLI scheme domestic-content mandates for warehouse automation equipment are reshaping sourcing patterns for platform operators. Supply concentration centers on China for cloud-native inventory API infrastructure, India for regional supplier aggregation platforms, and Indonesia for cross-island last-mile logistics networks. Raw material dependencies include server hardware for data localization compliance, cold-chain fleet assets for beverage distribution, and ERP integration modules for manufacturer onboarding. Single-source vulnerability sits with China's SAMR data sovereignty protocols fragmenting cross-border platform architecture. Distribution runs through online marketplace channels capturing accelerating share across Indonesia, Vietnam, and the Philippines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
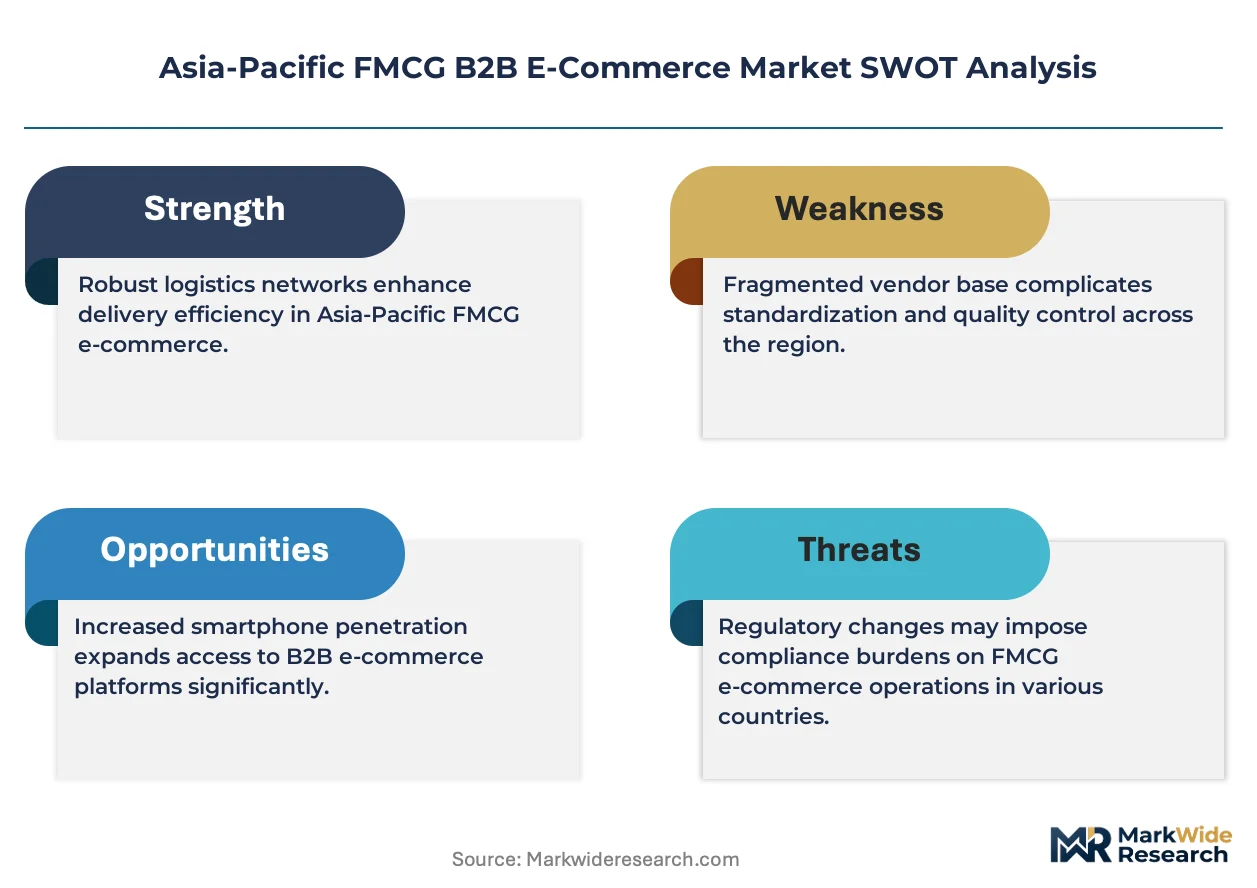
India's BIS digital marketplace standards impose server localization costs that China's SAMR-compliant operators avoid, creating a geographic-arbitrage window for capital deployment toward jurisdictions with harmonized data frameworks.
For Market Incumbents: Deepen vertical integration into captive logistics networks to defend against marketplace aggregators disintermediating traditional distributor relationships. Lock in retail chain clients through working capital optimization tools that compress cash conversion cycles beyond what legacy credit-based networks can match. Prioritize API-first procurement certification to maintain vendor qualification thresholds as buyer committees harden technical requirements. For New Entrants and Emerging Players: Japan's METI SME digitization guidelines open a window for B2B onboarding tool specialization targeting mid-size manufacturers in the Kanto region. Vietnam's Ho Chi Minh City and Hanoi restaurant procurement corridors present underpenetrated demand where buyer readiness outpaces local supplier digitization. Lead with dynamic pricing algorithm deployment to capture wholesalers consolidating fragmented supplier relationships. For Investors and Strategic Acquirers: Integrated logistics operators with captive payment ecosystems are the most active acquirer in this space, consolidating last-mile networks to sustain fulfillment guarantees. Long-term viability favors platforms embedding financial services into procurement workflows rather than pure marketplace aggregation. Watch for BIS-SAMR regulatory convergence signals as inflection indicators for cross-border operational scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Last-Mile Logistics Acquisition | Captive delivery networks in Indonesia's archipelago defray route licensing mandates from trade ministry tracking APIs. |
| Inventory API Integration | Real-time ERP synchronization eliminates manual reorder cycles for restaurant chains managing perishable velocity. |
| Blockchain Provenance Deployment | Lot-level traceability satisfies Singapore and Sydney restaurant mandates for high-value beverage import verification. |
| Dynamic Pricing Algorithm Launch | Surge-adjusted wholesale rates lock in margin retention through volume commitments from tier-two city distributors. |
| Working Capital Tool Embedding | Financial services integration compresses buyer cash conversion cycles beyond traditional distributor escrow periods. |
Research Methodology
Bottom-up restaurant and retail chain procurement modeling reconciled against top-down logistics infrastructure tracking forms the analytical core of this study. Primary interviews with platform operators, warehouse automation vendors, trade ministry compliance officers, and FMCG manufacturer supply chain directors combined with secondary validation from India's BIS regulatory filings, Indonesia's trade ministry logistics regulations, Japan's METI subsidy disbursement records, and customs data on cross-border digital service flows. Top-down macroeconomic indicators and bottom-up segment transaction velocity were triangulated to anchor market sizing.
Input-output matrices mapped platform adoption rates against logistics modernization subsidy flows across the analysis window. Segmentation dimensions modeled include product type velocity requirements, end-user integration sophistication, distribution channel API readiness, and pricing model commitment structures. CAGRs were derived from convergence of demand forecasting models and real-time logistics cost indexing. Forecast inputs incorporated PLI scheme warehouse automation deployment timelines and METI SME digitization subsidy absorption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under data sovereignty mandate fragmentation and cross-border payment interoperability delays. Analytical boundaries exclude C2C transactions and non-digital wholesale relationships. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
E-Commerce Lockers Market
E-Commerce Solutions
E-Commerce Technology Market
E-Commerce Solutions
E-Commerce Buy Now Pay Later Market
E-Commerce Solutions
Canada E-Commerce Market
E-Commerce Solutions
Shopping Application Market
E-Commerce Solutions
Southeast Asia Cross-Border E-Commerce Market
E-Commerce Solutions
Cyprus E-Commerce Market
E-Commerce Solutions
Qatar E-Commerce Market
E-Commerce Solutions
E-Tailing Solutions Market
E-Commerce Solutions
Online Apparel Retailing Market
E-Commerce Solutions
Slovenia E-Commerce Market
E-Commerce Solutions
C2C E-Commerce Market
E-Commerce Solutions
Retail E-Commerce Market
E-Commerce Solutions
China Ecommerce Logistics Market
E-Commerce Solutions
Asia Pacific B2B E-Commerce Market
E-Commerce Solutions
3D Interactive Ticketing Solutions Market