
 Bedding E-Commerce Platform Market | 2026-2036
Bedding E-Commerce Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Bedding E-Commerce Platform Market Insights
First-time millennial and Gen Z homebuyers is reorganizing the bedding e-commerce landscape, shifting volume from traditional retail toward digital-native brands with trial-friendly return policies. Casper differentiates through its sleep-tech positioning and extended home-trial periods that reduce purchase friction. Wayfair leverages its vast third-party marketplace to offer breadth across price points and material grades. Purple anchors its competitive stance with proprietary hyper-elastic polymer technology that commands premium positioning in the direct-to-consumer channel.
A bedding e-commerce platform is a digital commerce infrastructure purpose-built for selling sleep products online, integrating augmented reality visualization tools, compressed-roll logistics protocols, and dynamic firmness-matching algorithms to overcome the tactile barrier of remote mattress selection. Mattresses and bed linens command the largest revenue pools within product type segments, though subscription-based pillow replacement cycles are capturing recurring-revenue models that improve lifetime value metrics. Online marketplaces currently dominate sales channel flows by aggregating fragmented supplier bases, yet direct sales channels are deepening margin capture as brands invest in captive logistics networks and post-purchase sleep coaching services.
The US Consumer Product Safety Commission and California Bureau of Electronic and Appliance Repair impose flammability labeling and chemical disclosure mandates that shape product design and cross-state fulfillment compliance for domestic platforms. China's SAMR enforces live-streaming commerce disclosure rules that affect how bedding influencers present material claims and promotional pricing on Alibaba and JD.com interfaces. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple geographies that could impose end-of-life mattress recovery obligations onto platform operators rather than manufacturers alone.
Market Dynamics
Compressed-roll logistics protocols and augmented reality visualization tools are dismantling the tactile barrier that once protected brick-and-mortar mattress retail, while California's updated flammability standards force cross-border sellers into costly compliance recalibration.
Growth Catalysts
- Same-day delivery infrastructure:JD.com and Alibaba have built dedicated fulfillment networks for bulky home goods in China's tier-one cities, compressing delivery windows from weeks to hours.
- Extended producer responsibility frameworks:Emerging regulations across multiple geographies are shifting end-of-life mattress recovery obligations toward platform operators, creating captive recycling revenue streams.
- Hyper-elastic polymer technology:Proprietary material innovations are commanding premium positioning in direct-to-consumer channels by solving heat retention problems that plagued memory foam predecessors.
Market Restraints
- Polyol and petroleum-based foam input volatility:Raw material cost swings compress margin predictability for manufacturers operating on 90-day inventory cycles.
- Cross-border compliance friction:California Bureau of Electronic and Appliance Repair flammability labeling mandates create fulfillment complexity for domestic platforms shipping interstate.
- Physical trial substitution limitations:Body-weight distribution and sleep-position matching algorithms remain imperfect proxies for in-store firmness testing, elevating return-processing costs.
Strategic Opportunities
- Subscription-based pillow replacement cycles:Recurring-revenue models are capturing lifetime value improvements through automated replenishment of compressed-fill products.
- Live-streaming commerce disclosure rules:China's SAMR enforcement creates structured transparency requirements that premium brands can leverage for trust differentiation against unverified sellers.
- Post-purchase sleep coaching services:Digital-native brands are deepening margin capture by unbundling advisory content previously bundled into retail markups.
Industry Challenges
- Compressed-roll packaging engineering talent scarcity:Specialized mechanical design expertise for vacuum-compression durability testing remains concentrated among legacy foam manufacturers.
- Augmented reality asset production capex:Photorealistic 3D mattress visualization requires sustained investment in scanning infrastructure and WebGL rendering pipelines.
- Multi-jurisdiction chemical disclosure synchronization:Platforms must reconcile divergent state-level flammability documentation with federal CPSC baseline requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bedding E-Commerce Platform Market |
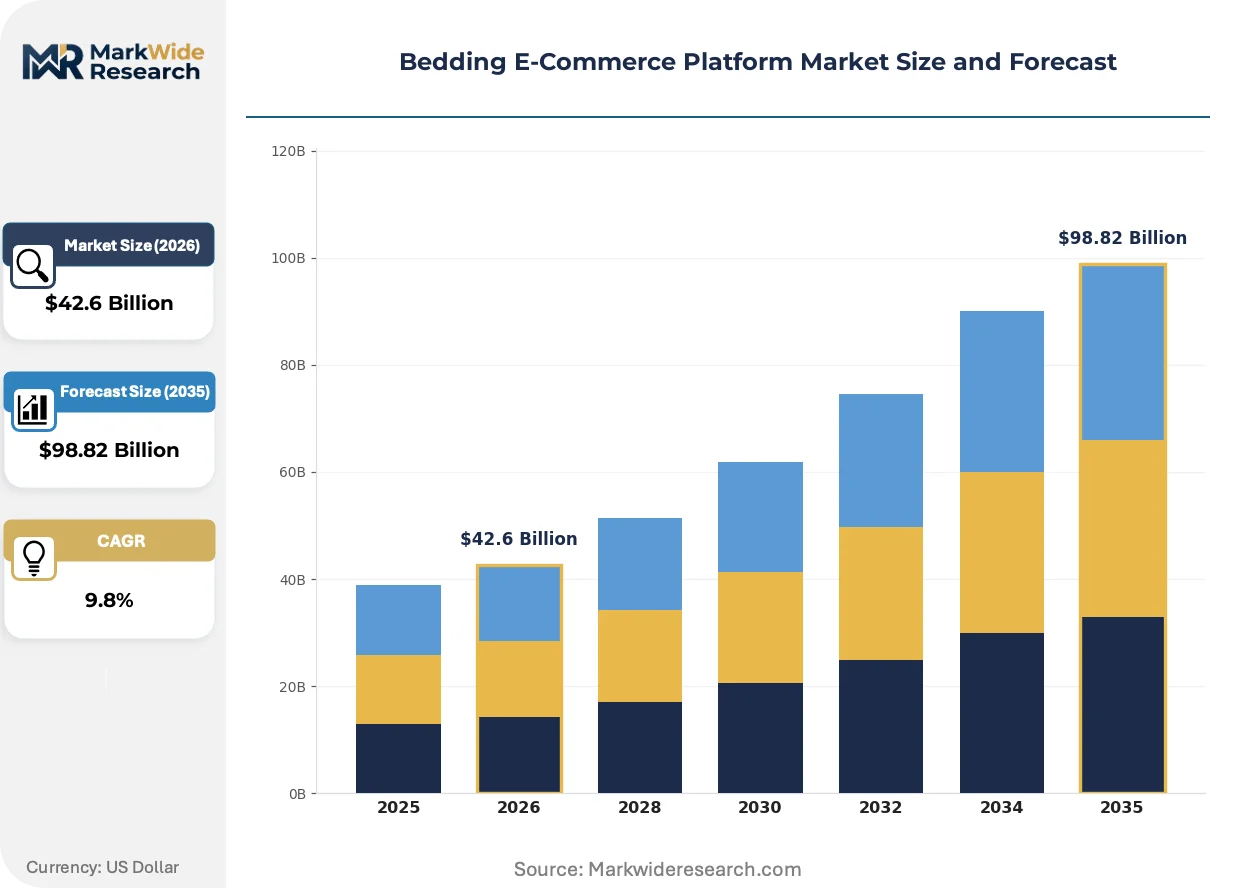
| Market Size in 2026 | $42.6 Billion |
| Market Size in 2035 | $98.82 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bedding Sets, Mattresses, Bed Linens, Pillows Customer Type: Residential, Hospitality, Institutional, Online Retailers Sales Channel: Direct Sales, Online Marketplaces, Retail Stores, Subscription Services Material: Cotton, Polyester, Linen, Memory Foam |
| Companies Covered | Amazon, Wayfair, Alibaba, Casper, Saatva, Purple, Tuft & Needle, Overstock.com, JD.com, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bedding E-Commerce Platform Market Trends and Innovations
Augmented reality visualization and AI-driven firmness-matching algorithms are compressing the information asymmetry that historically favored in-store mattress selection, while regulatory pressure on chemical transparency accelerates material innovation cycles.
Machine-learning sleep-profile matching is displacing static firmness categories in direct-to-consumer channels. First-time millennial and Gen Z homebuyers adopt these tools at twice the rate of repeat purchasers. This technology is displacing traditional sales associate roles while elevating return-policy generosity as the primary purchase-friction reducer.
REACH chemical disclosure expansions in Europe are mandating granular polyurethane foam component transparency across supply tiers. Manufacturers must now map additive provenance through three supplier layers. Bedding platforms serving EU markets are responding by consolidating supplier bases to reduce documentation complexity and audit exposure.
Buyer concentration around trial-friendly return policies is compressing traditional retail channel share. Online marketplaces that aggregate fragmented supplier bases are losing ground to captive direct-sales channels with in-house logistics networks. This rotation is most visible in China's tier-one cities where same-day delivery infrastructure has normalized immediate gratification expectations for bulky home goods.
Bedding E-Commerce Platform Market Segmentation
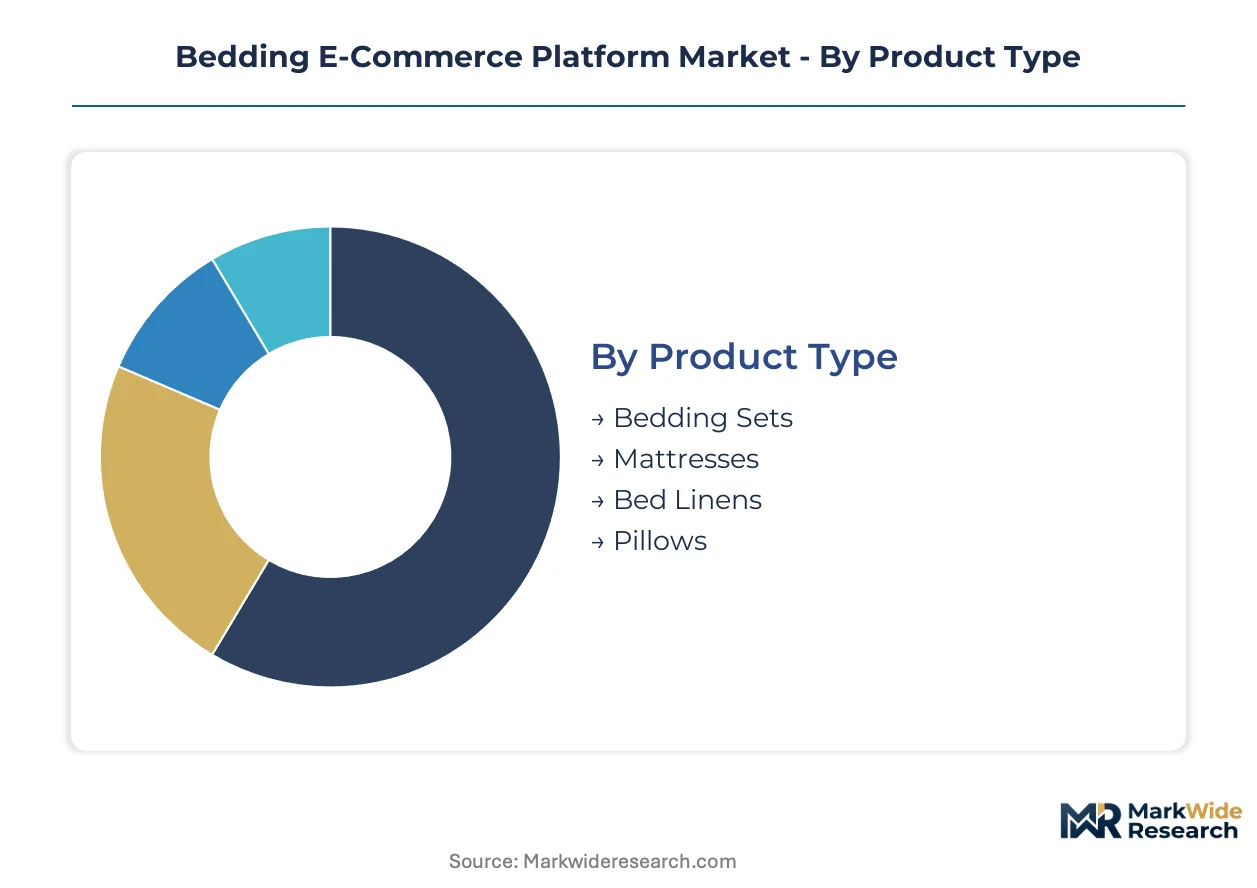
Bedding e-commerce platforms route distinct product categories through channel-specific fulfillment protocols. Channel-mix decisions determine margin capture, return-processing complexity, and customer acquisition economics across each segment.
Product Type:
Mattresses flow primarily through direct sales channels with compressed-roll logistics, while bed linens and pillows concentrate in online marketplaces that aggregate fragmented supplier bases.
- Mattresses:Vacuum-compressed foam and hybrid coil constructions enable parcel-network shipping that bypasses traditional white-glove delivery. Demand clusters among first-time millennial and Gen Z homebuyers in China's tier-one cities where same-day delivery infrastructure has normalized immediate gratification expectations for bulky home goods.
- Bed Linens:Thread-count differentiation and material certification drive purchase decisions in the absence of tactile evaluation. European REACH chemical disclosure expansions are mandating granular polyurethane foam component transparency that bedding platforms must surface through supplier consolidation.
- Bedding Sets:Coordinated color and texture matching reduces return rates compared to à la carte purchases.
- Pillows:Compressed-fill logistics support subscription-based replacement cycles that improve lifetime value metrics for direct-to-consumer brands.
Mattresses dominate installed base. Pillows represent the fastest-growing trajectory through recurring-revenue models.
Customer Type:
Cost tier stratification separates residential purchasers seeking trial-friendly return policies from hospitality buyers negotiating volume-based procurement contracts.
- Residential:Individual consumers prioritize augmented reality visualization and AI-driven firmness-matching algorithms that compress information asymmetry. California Bureau of Electronic and Appliance Repair flammability labeling mandates create fulfillment complexity for platforms shipping interstate to this segment.
- Hospitality:Hotel chains and short-term rental operators source through dedicated B2B portals with standardized durability specifications and bulk-compressed logistics. Procurement teams negotiate multi-property contracts that lock in three-year replacement cycles.
- Institutional:Healthcare and educational facilities require fire-retardant certification documentation that exceeds residential-grade compliance thresholds.
- Online Retailers:Third-party marketplace sellers arbitrage supplier fragmentation without captive logistics investment.
Residential captures the highest per-unit margins. Hospitality is where volume expansion concentrates.
Sales Channel:
Volume concentration varies by fulfillment infrastructure ownership, with captive logistics networks deepening margin capture against aggregator-dependent marketplace models.
- Direct Sales:Brand-operated storefronts integrate post-purchase sleep coaching services and extended home-trial periods. China's SAMR live-streaming commerce disclosure rules create structured transparency requirements that premium brands leverage for trust differentiation.
- Online Marketplaces:JD.com and Alibaba aggregate fragmented supplier bases across price points and material grades. These platforms rely on third-party compressed-roll logistics providers that limit delivery-window control.
- Retail Stores:Brick-and-mortar showrooms retain tactile trial advantages for high-consideration mattress purchases.
- Subscription Services:Automated replenishment of compressed-fill pillows and protective covers generates predictable recurring revenue with lower customer acquisition costs.
Online marketplaces dominate transaction volume. Direct sales is where margin expansion concentrates.
Material:
Supply concentration and input cost volatility separate petroleum-dependent synthetics from agricultural fiber networks with more stable pricing dynamics.
- Memory Foam:Viscoelastic polyurethane formulations enable vacuum-compression durability that underpins direct-to-consumer shipping economics. Polyol and petroleum-based foam input volatility compresses margin predictability for manufacturers operating on 90-day inventory cycles.
- Cotton:Natural fiber sourcing faces water-usage scrutiny that platforms must document for EU Green Deal compliance.
- Polyester:Recycled PET feedstocks respond to extended producer responsibility frameworks shifting end-of-life recovery obligations toward platform operators.
- Linen:Flax cultivation concentration in specific European regions creates supply vulnerability during climate-disrupted harvests.
Memory foam dominates technology-enabled channels. Cotton is where sustainability-driven substitution concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers ship compressed-roll mattresses through Alibaba and JD.com channels into North American and European residential markets, while US-based direct-to-consumer brands export proprietary polymer technologies into Asian tier-one cities.
United States
First-time millennial homebuyers in Austin and Denver metro areas drive demand for trial-friendly return policies. The CPSC enforces flammability labeling mandates that shape cross-state fulfillment protocols. California's Bureau of Electronic and Appliance Repair imposes the strictest chemical disclosure requirements, forcing platforms to maintain dual inventory SKUs for West Coast shipments.
China
JD.com and Alibaba have built same-day delivery infrastructure for bulky home goods in Shanghai, Beijing, and Shenzhen. SAMR enforces live-streaming commerce disclosure rules that affect how bedding influencers present material claims. The Yangtze River Delta concentrates vacuum-compression manufacturing capacity serving both domestic and export channels.
Germany
REACH chemical disclosure expansions mandate granular polyurethane foam component transparency across supply tiers. ECHA enforcement is accelerating supplier consolidation among platforms serving EU markets. The North Rhine-Westphalia industrial corridor hosts specialized logistics providers for compressed-roll cross-border fulfillment.
United Kingdom
London and Southeast England concentrate demand for subscription-based pillow replacement cycles among urban renters. The UK's national consumer protection regulator enforces distance-selling regulations that govern extended home-trial periods. Midlands-based fulfillment centers process returns for direct-to-consumer brands operating across Northern Europe.
India
Maharashtra and Karnataka see rising adoption of AI-driven firmness-matching algorithms among tech-sector employees. BIS certification requirements for upholstered furniture create compliance checkpoints for imported foam products. Mumbai and Bengaluru host the largest warehousing clusters for third-party marketplace sellers aggregating fragmented domestic supplier bases.
Bedding E-Commerce Platform Market Competitive Landscape
Listed leaders compete with private specialists across capital access and operational agility, creating a tiered structure where scale-driven aggregators face pressure from technology-differentiated direct-to-consumer brands. The vendor base fragments across three strategic archetypes: marketplace aggregators with third-party logistics dependence, captive-logistics direct brands, and hybrid retailers operating owned digital storefronts alongside wholesale distribution. Dominant competitive moves include backward integration into compressed-roll manufacturing and geographic expansion through localized fulfillment partnerships.
Among US-based operators, Casper and Purple exemplify the technology-differentiated direct-to-consumer archetype, while Wayfair occupies a position bridging marketplace aggregation with proprietary logistics investment. Chinese e-commerce infrastructure is anchored by Alibaba and JD.com, which represent the scale-driven fulfillment-network model that domestic platforms struggle to replicate.
| Leading Market Players |
|---|
| Amazon |
| Wayfair |
| Alibaba |
| Casper |
| Saatva |
| Purple |
| Tuft & Needle |
| Overstock.com |
| JD.com |
| Others |
Pricing and Supply Chain Analysis
Hyper-elastic polymer substitution for petroleum-based memory foam is redrawing raw material sourcing maps from Gulf Coast petrochemical corridors toward specialized polymer research clusters in North Carolina and Belgium, compressing input cost volatility while elevating premium-tier pricing power for technology-differentiated brands.
Pricing Analysis
Next-generation hyper-elastic polymer mattresses command 40-60% premiums over incumbent memory foam tiers, while legacy petroleum-based products face margin compression from polyol cost swings. Three-tier pricing structure across premium polymer, standard hybrid, and economy all-foam levels separates brands by heat-dissipation performance and trial-period length. Cost compression in the economy tier is intensifying because JD.com and Alibaba same-day delivery infrastructure has normalized free-shipping expectations. Hospitality procurement teams show lowest price sensitivity due to multi-property volume contracts, while individual first-time homebuyers in China's tier-one cities exhibit highest elasticity.
Supply Chain Analysis
Ninety-day inventory cycles for petroleum-based foam manufacturers create working capital strain during polyol price spikes, forcing just-in-time compression logistics adoption. Manufacturing concentrates in China's Yangtze River Delta, US Southeast foam corridors, and Belgian polymer research clusters. Raw material flows draw from Saudi Arabian petrochemical feedstocks, Appalachian coal-to-chemical complexes, and European flax cultivation networks. Single-source vulnerability sits with vacuum-compression machinery suppliers concentrated among legacy German equipment manufacturers. Distribution runs through captive direct-to-consumer parcel networks, JD.com/Alibaba marketplace aggregators, and third-party white-glove regional carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bedding e-commerce market is recovering from post-pandemic demand normalization, with millennial household formation rates serving as the cyclical anchor for volume recovery across direct-to-consumer channels.
For Market Incumbents: Shield margin structure by securing captive compressed-roll manufacturing capacity in the Yangtze River Delta before equipment lead times extend further. Backward integration into polymer formulation R&D creates defensible positioning against commodity foam competitors facing REACH disclosure compliance costs. Prioritize California Bureau of Electronic and Appliance Repair dual-SKU fulfillment infrastructure to preempt West Coast market share erosion. For New Entrants and Emerging Players: Differentiate on AI-driven firmness-matching algorithm accuracy to capture residential purchasers dissatisfied with static category recommendations. Target subscription-based pillow replacement cycles in UK urban rental corridors where compressed-fill logistics infrastructure remains underdeveloped. Launch through live-streaming commerce channels under China's SAMR disclosure framework to build trust differentiation against unverified marketplace sellers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors technology-differentiated direct-to-consumer brands with proprietary polymer IP over aggregator-dependent marketplace models. Acquisition targets should demonstrate captive logistics networks and post-purchase sleep coaching service attach rates above category norms. Monitor extended producer responsibility framework adoption across EU member states as the inflection signal for recycling infrastructure valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Manufacturing | Captive hyper-elastic polymer production insulates margin from petroleum feedstock volatility and REACH audit exposure. |
| Same-Day Delivery Infrastructure Partnership | JD.com and Alibaba logistics integration captures millennial homebuyers in Shanghai and Shenzhen with immediate gratification expectations. |
| AI-Driven Firmness Matching Platform Launch | Machine-learning sleep profiles displace static categories and reduce return-processing costs for direct-to-consumer brands. |
| Subscription Service Expansion | Automated pillow replacement cycles generate predictable recurring revenue with lower customer acquisition costs than mattress sales. |
| Extended Producer Responsibility Compliance | End-of-life mattress recovery infrastructure positions platform operators for regulatory advantage under emerging EU frameworks. |
Research Methodology
Cross-validation between executive interviews at compressed-roll logistics providers and customs trade data anchors the qualitative findings on supply chain concentration. Primary discussions with direct-to-consumer brand CEOs, JD.com category managers, vacuum-compression equipment engineers, and California compliance attorneys combined with secondary validation from CPSC flammability filings, SAMR live-streaming disclosure records, ECHA REACH substance databases, and SEC 10-K supply chain disclosures. Bottom-up SKU-level demand modeling and top-down macroeconomic triangulation produced convergent volume estimates.
Sensitivity analysis around polyol price volatility, same-day delivery penetration rates, and extended producer responsibility adoption timelines shaped the analytical framework. Segmentation dimensions modeled include product type, customer archetype, sales channel ownership, and material technology generation across the projection horizon. CAGRs were derived from logistic diffusion curves fitted to historical channel-shift patterns, with forecast inputs incorporating millennial household formation projections and compressed-roll logistics capacity buildout schedules.
Material uncertainties — abrupt California flammability standard revisions, Yangtze River Delta manufacturing disruptions, or EU mattress recovery mandate acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about trial-period standardization and AI matching algorithm adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Panama E-Commerce Market
E-Commerce Solutions
B2C E-Commerce Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
North America E-Commerce Watch Market
E-Commerce Solutions
E-Commerce in Luxembourg Market
E-Commerce Solutions
Second-Hand E-Commerce Market
E-Commerce Solutions
South Korea E-Commerce Market
E-Commerce Solutions
Global Live E-Commerce Market
E-Commerce Solutions
Mexico E-Commerce Market
E-Commerce Solutions
Asia-Pacific Automotive E-Commerce Market
E-Commerce Solutions
Estonia E-Commerce Market
E-Commerce Solutions
Africa E-Commerce Market
E-Commerce Solutions
Asia Pacific E-Commerce Market
E-Commerce Solutions
Indonesia Ecommerce Logistics Market
E-Commerce Solutions
Cross Border Ecommerce Market
E-Commerce Solutions
Digital Coupons Market