
 E-Commerce App Market | 2026-2036
E-Commerce App Market Size, Share, and Industry Trends Forecast 2026-2036
E-Commerce App Market Foresight
Subscription-based loyalty programs is recalibrating what e-commerce apps monetize beyond transaction fees. Amazon leverages Prime membership bundling to sustain recurring revenue streams across its app ecosystem. Alibaba Group Holding Limited anchors its competitive position through integrated financial services within its super-app architecture. Shopify differentiates by enabling merchant-owned subscription tools rather than marketplace dependency.
An e-commerce app constitutes a software application enabling online commercial transactions through digital storefronts, typically requiring SSL encryption, payment gateway APIs, and real-time inventory synchronization across cloud infrastructure. These platforms serve the primary commercial purpose of facilitating direct seller-buyer exchange without physical retail intermediation. Marketplace apps currently occupy the largest revenue pool by product type, while mobile deployment channels capture the fastest user growth trajectory due to smartphone-first purchasing behavior in emerging economies. Digital wallets within payment method segmentation are displacing traditional card-based flows, creating new margin concentration for fintech-integrated platforms.
The US Federal Trade Commission scrutinizes data collection practices that underpin targeted advertising within e-commerce apps, directly influencing platform architecture decisions. Europe's General Data Protection Regulation and Digital Services Act jointly constrain cross-border data flows and algorithmic product ranking transparency, elevating compliance costs for international operators. India's central bank guidelines on digital payment aggregation affect how apps structure wallet and UPI integrations. Stakeholders must monitor evolving antitrust interpretations of in-app marketplace control versus merchant independence.
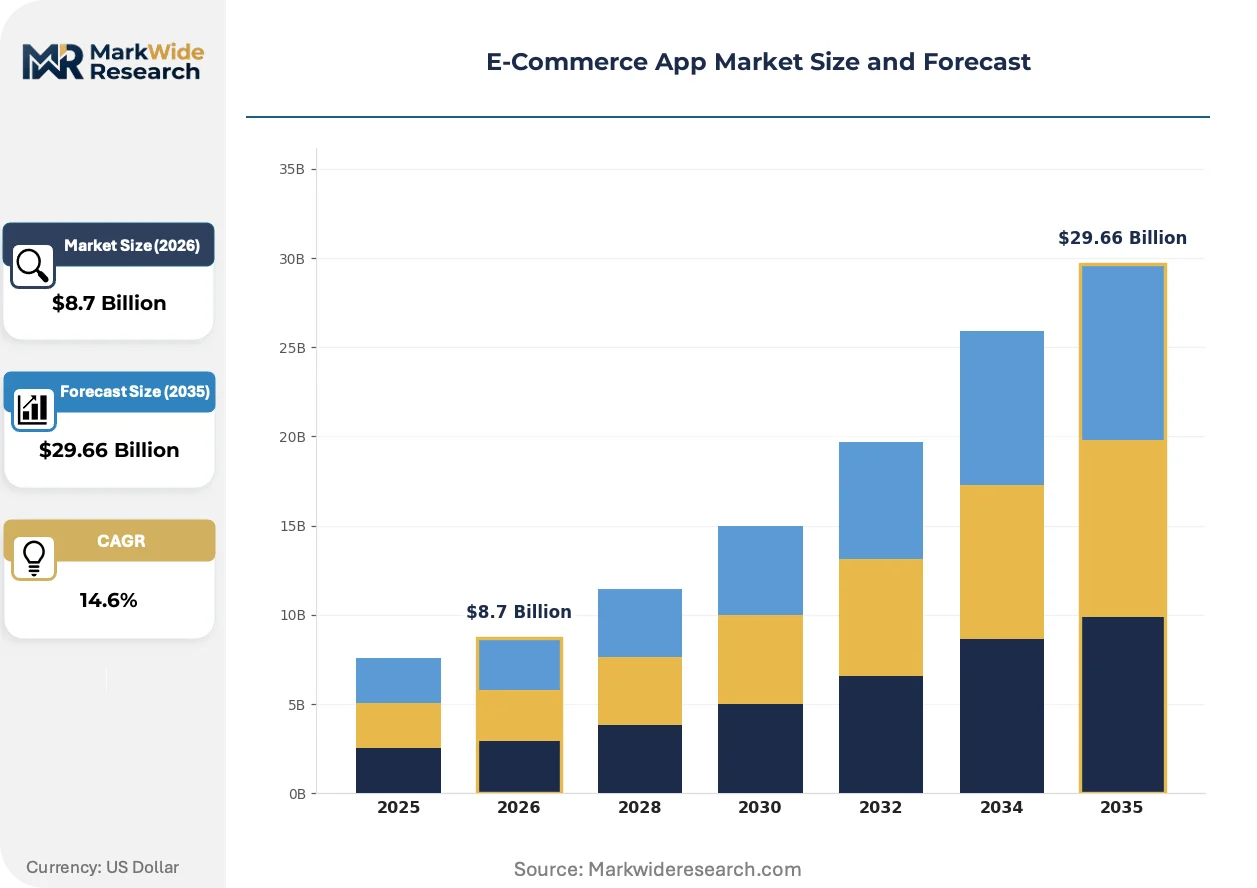
Market Dynamics
Mobile-first purchasing behavior is compressing the traditional desktop-to-app migration timeline, while India's UPI infrastructure and Europe's Digital Services Act simultaneously reshape payment flows and platform accountability requirements.
Growth Catalysts
- Real-time payment infrastructure:India's Unified Payments Interface enables instant settlement across e-commerce apps, reducing cart abandonment and merchant working capital requirements.
- Fashion and apparel verticalization:Category-specific apps capture mobile-native consumers through visual search and AR try-on capabilities, driving higher engagement metrics than generalist marketplaces.
- Quick-commerce logistics networks:Urban dark store density in metropolitan India enables sub-30-minute delivery promises that convert impulse purchases into habitual app usage.
Market Restraints
- Data localization mandates:India's RBI guidelines and Europe's GDPR constrain cross-border server architecture, elevating compliance infrastructure costs for multi-territory operators.
- Payment aggregator licensing:India's central bank requires separate authorization for wallet and UPI integration, creating regulatory friction for fintech-embedded commerce platforms.
- Smartphone penetration ceilings:Rural India and secondary European markets exhibit hardware limitations that cap addressable user bases for feature-heavy app experiences.
Strategic Opportunities
- Vernacular interface expansion:India's 22 scheduled languages represent underpenetrated segments where localized voice commerce can capture non-English proficient users.
- Subscription loyalty bundling:Prime-style membership programs create recurring revenue streams that decouple platform economics from pure transaction volume dependency.
- Embedded finance convergence:Integration of credit underwriting and insurance distribution within checkout flows captures margin pools traditionally held by standalone fintech providers.
Industry Challenges
- Algorithmic transparency compliance:Europe's Digital Services Act mandates explainable product ranking systems, requiring engineering resources to document recommendation logic.
- Legacy ERP synchronization:Merchant inventory systems often lack real-time API connectivity, forcing manual intervention or expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Commerce App Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Marketplace Apps, Retail Apps, Auction Apps, Discount Apps Deployment: Web-Based, Mobile, Desktop, Hybrid Customer Type: Consumers, Small Businesses, Enterprises, Corporations Payment Method: Credit Card, Digital Wallets, Bank Transfer, Cash on Delivery |
| Companies Covered | Amazon, Alibaba Group Holding Limited, Walmart, eBay, Shopify, JD.com, Shein, AliExpress, Flipkart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Commerce App Market Shifts & Advancements
Distributed ledger architectures and verifiable credential systems are recalibrating trust mechanisms in peer-to-peer commerce, while regulatory pressure on data practices accelerates privacy-preserving analytics adoption.
Blockchain-based provenance tracking is decentralizing authentication workflows for luxury and secondhand goods marketplaces. High-value category sellers in Europe and North America are adopting immutable ownership records to combat counterfeiting. This shift is decentralizing trust verification away from platform-mediated guarantees toward cryptographic seller credentials.
Europe's Digital Services Act imposes algorithmic accountability requirements on product ranking and recommendation systems. Platforms must now maintain audit trails for automated decision-making processes affecting merchant visibility. Fashion and electronics verticals face the steepest compliance burdens due to high seller density and dynamic inventory turnover.
Social commerce integration is collapsing the discovery-to-purchase funnel into single-session transactions. Live-streaming hosts and influencer storefronts are displacing traditional search-based procurement in Southeast Asian and Indian markets. Beauty and personal care categories exhibit the highest conversion rates through this channel, particularly among Gen-Z demographics in metropolitan India.
E-Commerce App Market Segmentation
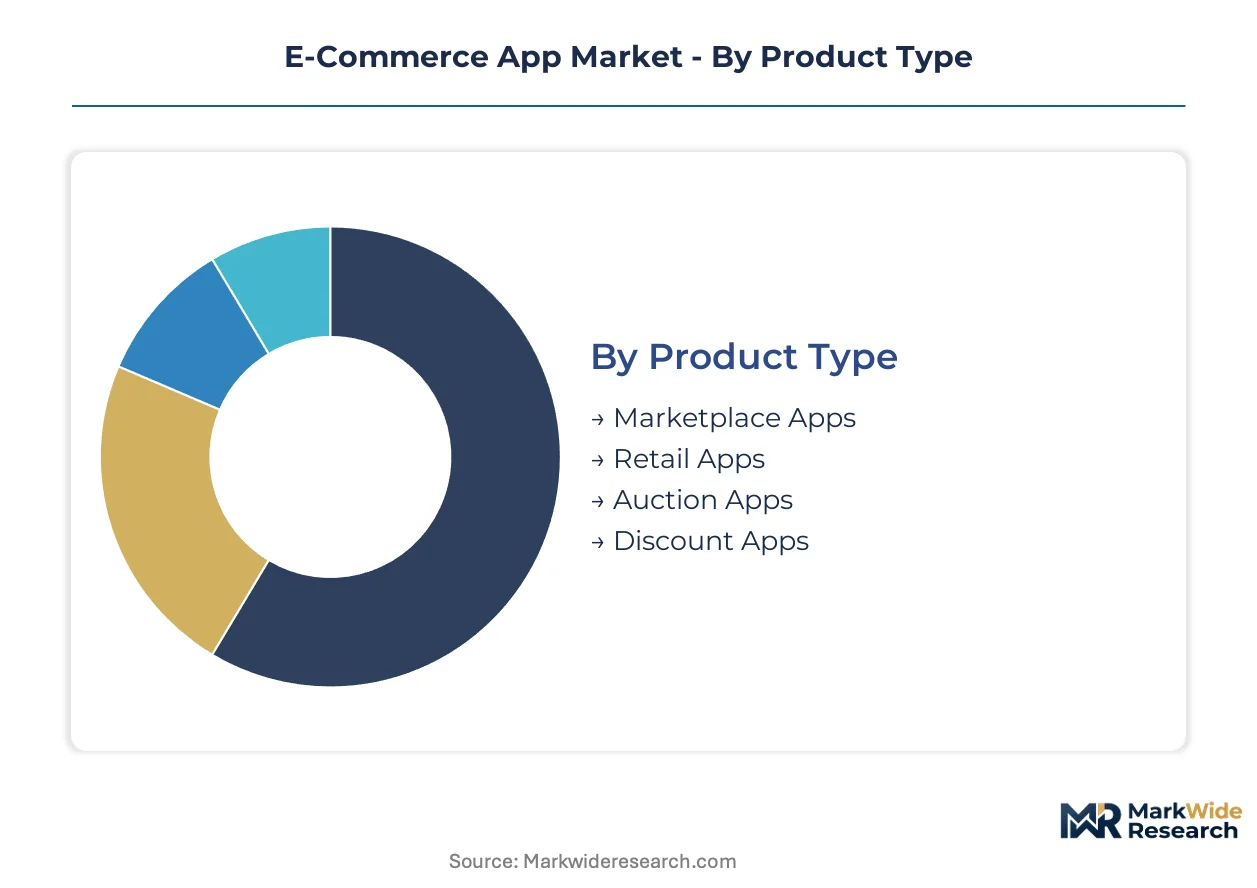
E-commerce app segmentation reveals divergent monetization models and infrastructure requirements across product architectures. Deployment channels and payment method preferences are compressing development roadmaps as smartphone-first purchasing behavior accelerates platform specialization.
Product Type:
Standardized marketplace infrastructure competes against vertically customized retail experiences across this spectrum, with each architecture demanding distinct seller onboarding protocols and revenue recognition models.
- Marketplace Apps:Multi-tenant platforms aggregate third-party inventory through unified search and checkout layers, requiring sophisticated dispute resolution mechanisms. India's Flipkart and quick-commerce networks concentrate demand here, driven by urban millennial preference for consolidated discovery. Most installed capacity flows through Marketplace Apps. Expansion is steepest in Retail Apps.
- Retail Apps:Single-brand storefronts with captive inventory management and direct fulfillment control enable tighter margin capture. Fashion and apparel verticals in Europe and India are migrating toward dedicated retail apps to escape marketplace fee structures and own customer data relationships. These apps prioritize AR visualization and personalized recommendation engines over discovery breadth.
- Auction Apps:Dynamic pricing mechanisms with time-bound bidding workflows serve collectibles and secondhand luxury segments. These platforms require real-time bid synchronization and escrow infrastructure.
- Discount Apps:Flash sale architectures with limited inventory windows create artificial scarcity engines. These apps concentrate in price-sensitive emerging economies with high deal-seeking consumer density.
Merchant acquisition economics favor marketplace entry, while margin sustainability drives retail app migration at scale.
Deployment:
Cost-to-serve variations across deployment modes are reshaping platform engineering investments, with mobile-native architectures commanding premium development resources.
- Web-Based:Browser-rendered storefronts minimize friction for first-time users and reduce app store dependency. India's UPI infrastructure enables lightweight web checkout without native app installation, capturing price-sensitive users with storage-constrained devices.
- Mobile:Native iOS and Android applications with push notification capabilities and biometric authentication dominate habitual purchasing behavior. Mobile deployment channels are climbing the fastest as smartphone penetration saturates urban India and secondary European markets. These apps require continuous OS compatibility maintenance and app store compliance overhead.
- Desktop:Full-featured browser applications with spreadsheet bulk ordering and procurement workflow integration serve enterprise purchasing departments. These platforms retain relevance in B2B segments with complex approval hierarchies.
- Hybrid:Cross-platform frameworks balancing development efficiency against native performance characteristics. These architectures appeal to mid-market retailers with constrained engineering resources.
Consumer-facing volume concentrates in mobile deployment. Enterprise procurement retains desktop dependency.
Customer Type:
Application-specific feature depth varies dramatically across customer sophistication tiers, from impulse purchasing simplicity to procurement system integration.
- Consumers:Individual purchasers requiring streamlined discovery, one-tap checkout, and flexible return workflows. India's Gen-Z demographics and European urban millennials drive feature prioritization toward social commerce integration and visual search.
- Small Businesses:Merchant-procurement hybrids with inventory forecasting needs and bulk pricing negotiations. These users demand simplified ERP connectivity and invoice management.
- Enterprises:Mid-sized organizations with departmental purchasing controls and spend analytics requirements. These customers require role-based access and approval workflow customization.
- Corporations:Large entities with vendor management systems, contract pricing, and compliance documentation needs. These deployments involve procurement software integration and dedicated account management.
Platform economics optimize for consumer scale. Corporate contracts deliver margin concentration.
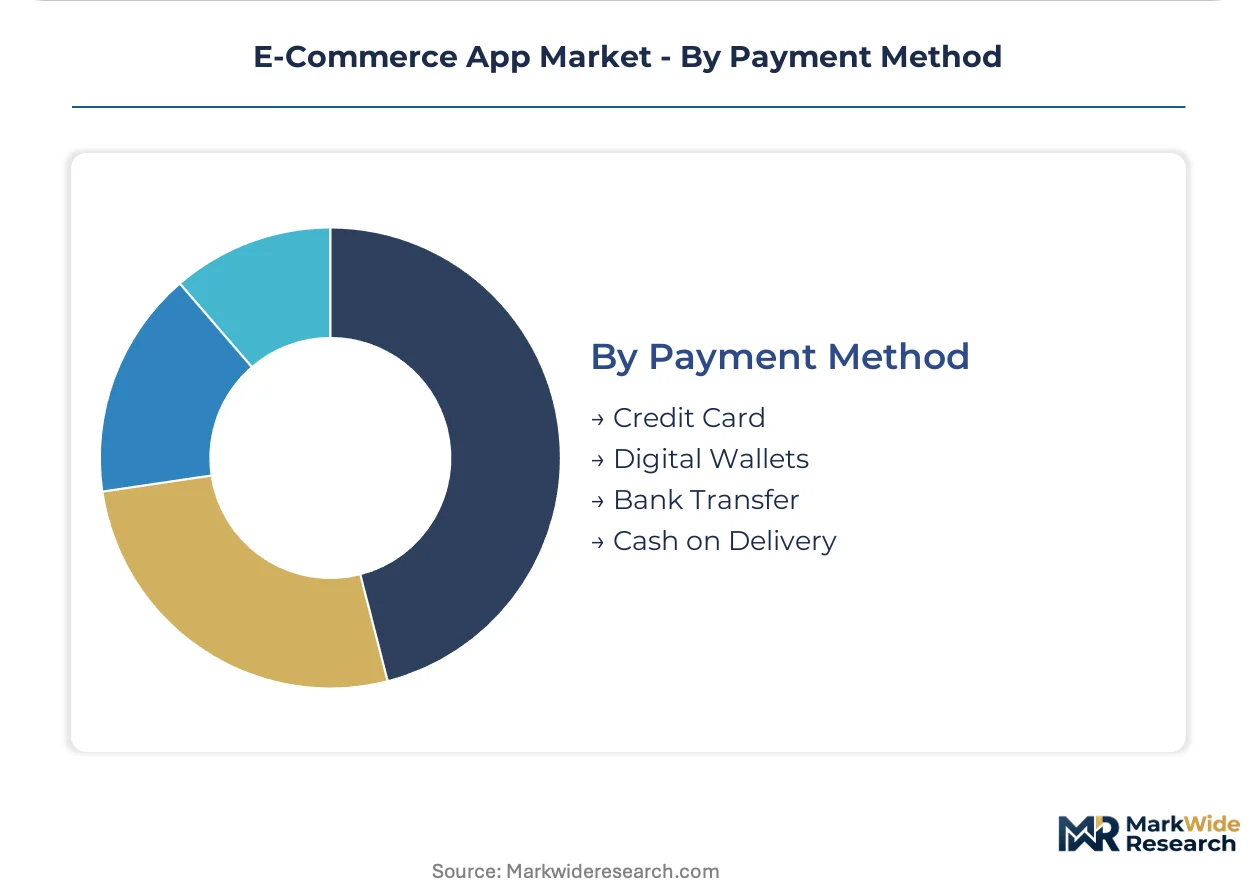
Payment Method:
Margin pool distribution and regulatory compliance burden diverge sharply across payment architectures, with fintech integration becoming a competitive differentiator.
- Credit Card:Traditional card network processing with chargeback protection and rewards program integration. Europe's PSD2 strong customer authentication requirements and India's RBI guidelines on data localization constrain cross-border card flow architecture.
- Digital Wallets:Stored-value and tokenized payment credentials with one-tap checkout optimization. Digital wallets are gaining share fastest as India's UPI infrastructure and Europe's open banking frameworks displace card-present habits. These methods reduce cart abandonment and enable subscription continuity.
- Bank Transfer:Direct account debiting with lower interchange costs but higher friction. These methods concentrate in B2B procurement and high-value transactions.
- Cash on Delivery:Physical settlement at delivery point with return risk concentration. This method retains significance in India's tier-2 cities with trust deficits in digital payment systems.
Wallet integration commands development priority. Cash on delivery retains geographic necessity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's UPI-enabled quick-commerce networks attract urban millennial density that contrasts with Europe's regulatory-heavy platform accountability frameworks. Divergent infrastructure maturity and compliance architectures shape deployment strategies across these territories.
United States
Mobile-first purchasing behavior concentrates in metropolitan coastal corridors with Prime-style subscription bundling driving habitual app engagement. The FTC scrutinizes data collection architectures underpinning targeted advertising, forcing platform engineering toward privacy-preserving analytics. Seattle and San Francisco Bay Area clusters host engineering centers optimizing push notification algorithms and biometric checkout flows.
India
UPI infrastructure enables instant settlement that reduces cart abandonment across quick-commerce and fashion verticals, capturing Gen-Z smartphone penetration. RBI guidelines on payment aggregator licensing and data localization constrain cross-border server architecture for multi-territory operators. Mumbai, Bangalore, and Delhi-NCR dark store networks sustain sub-30-minute delivery promises that convert impulse purchases into habitual usage.
Germany
GDPR and the Digital Services Act jointly elevate compliance costs for algorithmic transparency and cross-border data flows affecting marketplace ranking systems. Fashion and electronics verticals face steep documentation burdens for automated decision-making audit trails. Berlin and Munich engineering hubs concentrate resources on explainable recommendation engines and merchant dispute resolution mechanisms.
United Kingdom
Open banking frameworks accelerate digital wallet displacement of card-present habits, reducing friction in subscription continuity and one-tap checkout optimization. Competition and Markets Authority scrutiny of in-app marketplace control versus merchant independence shapes platform architecture decisions. London fintech-embedded commerce clusters drive margin capture through integrated credit underwriting at checkout.
China
Super-app architectures with integrated financial services anchor competitive positioning through captive payment ecosystems and social commerce discovery. SAMR antitrust interpretations of merchant data ownership and algorithmic pricing transparency constrain platform expansion modalities. Shenzhen and Hangzhou technology corridors optimize live-streaming commerce infrastructure and influencer storefront conversion funnels.
E-Commerce App Market Competitive Landscape
Top-tier vendors anchor super-app and marketplace ecosystems, while mid-tier specialists occupy verticalized retail and SaaS enablement layers. The vendor base stratifies across three tiers: integrated ecosystem operators, vertical retail app developers, and merchant-facing infrastructure providers. Two strategic archetypes dominate—ecosystem bundlers leveraging subscription loyalty programs, and independence enablers offering merchant-owned customer data relationships. Competitive moves concentrate on M&A for logistics network density and strategic partnerships for embedded finance convergence.
Within the ecosystem bundler tier, Amazon and Alibaba Group Holding Limited exemplify platform operators leveraging integrated financial services and Prime-style membership architectures to sustain recurring revenue streams independent of pure transaction volume. Shopify occupies a position within the independence enabler archetype, representing merchant-owned subscription tools and escape from marketplace fee structures through direct fulfillment control and customer data ownership.
| Leading Market Players |
|---|
| Amazon |
| Alibaba Group Holding Limited |
| Walmart |
| eBay |
| Shopify |
| JD.com |
| Shein |
| AliExpress |
| Flipkart |
| Others |
Supply & Pricing Matrix
Mobile app developer talent pools in Bangalore and Shenzhen compress labor-cost differentials, widening pricing-tier spreads between premium native applications and economy hybrid deployments as platform operators arbitrage engineering wages across offshore development centers.
Pricing Analysis
Capacity additions in Vietnam and Poland are reshaping price floors for mid-market e-commerce app development, forcing downward pressure on standard-tier SaaS subscriptions. Pricing stratifies across premium native builds with biometric integration, standard cross-platform frameworks, and economy white-label templates. Price differentiation hinges on customization depth and PCI-DSS certification tier. Margins are tightening in the standard tier due to low-code platform proliferation. Enterprise procurement departments exhibit lowest price sensitivity; small merchants in tier-2 Indian cities show highest.
Supply Chain Analysis
Regional distribution centers in Netherlands, Singapore, and UAE anchor hub-and-spoke fulfillment networks serving last-mile dark store density. Cloud infrastructure draws from hyperscaler regions in Virginia, Frankfurt, and Mumbai. Payment gateway APIs rest on banking partnerships in India, UK, and Brazil. Single-source vulnerability concentrates in UPI switch providers and biometric authentication SDKs. Distribution runs through app store ecosystems with 15-30% revenue share extraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's UPI infrastructure cost advantages versus Europe's GDPR compliance burdens create divergent platform economics for identical feature sets.
For Market Incumbents: Anchor super-app ecosystems through captive payment wallet retention and quick-commerce logistics density in Mumbai and Delhi-NCR. Counter threat from merchant-owned retail apps by subsidizing fulfillment infrastructure. Prioritize backward integration into dark store real estate as defensive moat. For New Entrants and Emerging Players: Logistics aggregators represent the most underexploited channel partner type for white-label e-commerce enablement. Target vernacular voice commerce in India's non-English proficient segments. Pursue embedded finance convergence through RBI-licensed payment aggregator partnerships as primary go-to-market wedge. For Investors and Strategic Acquirers: Quick-commerce specialists with dark store networks are the most active acquirer in this space, consolidating urban delivery density. Long-term viability favors platforms with subscription loyalty bundling over pure transaction-dependent models. Monitor RBI payment aggregator license grant velocity as inflection signal for fintech-embedded commerce scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Quick-Commerce Logistics Expansion | Dark store density in Indian metros converts impulse purchases into habitual app usage patterns. |
| Vernacular Interface Localization | Voice commerce in India's 22 scheduled languages captures non-English proficient user segments. |
| Embedded Finance Integration | Credit underwriting at checkout captures margin pools from standalone fintech providers. |
| Algorithmic Transparency Compliance | EU Digital Services Act audit trails require engineering investment in explainable recommendation systems. |
| Subscription Loyalty Bundling | Prime-style membership programs decouple platform economics from pure transaction volume dependency. |
Research Methodology
Direct dialogue with platform engineering leads, merchant acquisition heads, payment gateway architects, and dark store operations managers grounded qualitative findings. Secondary validation drew from SEC 10-K filings, RBI circulars on payment aggregation, EU Digital Services Act implementation guidance, and app store revenue disclosure statements. Bottom-up merchant onboarding cost models and top-down addressable smartphone user projections were triangulated against observed deployment patterns.
Segmentation outputs across product type, deployment channel, customer tier, and payment method were generated through the projection horizon. CAGRs were derived from installed base growth curves and average revenue per user trajectories. Model inputs incorporated UPI transaction volume trajectories, GDPR compliance cost benchmarks, and quick-commerce delivery promise fulfillment rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to RBI licensing velocity, smartphone penetration ceilings in rural India, and antitrust reinterpretations of in-app marketplace control. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Bulgaria E-Commerce Market
E-Commerce Solutions
South Korea Ecommerce Logistics Market
E-Commerce Solutions
Greece E-Commerce Market
E-Commerce Solutions
Poland E-Commerce Market
E-Commerce Solutions
C2C E-Commerce Market
E-Commerce Solutions
E-Commerce Household Appliances Market
E-Commerce Solutions
Cross-Border E-Commerce Logistics Market
E-Commerce Solutions
Albania E-Commerce Market
E-Commerce Solutions
India Quick Commerce Market
E-Commerce Solutions
Saudi Arabia E-Commerce Logistics Market
E-Commerce Solutions
Shopping Application Market
E-Commerce Solutions
Metaverse in E-Commerce Market
E-Commerce Solutions
Argentina Alcohol E-Commerce Market
E-Commerce Solutions
Nigeria E-Commerce Market
E-Commerce Solutions
Indonesia Ecommerce Logistics Market
E-Commerce Solutions
United States Same-Day Delivery Market