
 US Pharma E-Commerce Market | 2026-2036
US Pharma E-Commerce Market Size, Share, and Industry Trends Forecast 2026-2036
US Pharma E-Commerce Market Insights
US pharmacy distribution infrastructure is recalibrating around direct-to-consumer fulfillment models. CVS Health anchors its position through dense last-mile networks tied to existing retail footprints. Amazon.com, Inc. leverages logistics automation to compete on speed for recurring medication shipments. Walgreens Boots Alliance differentiates through specialty pharmacy integration with its digital platform.
US pharma e-commerce encompasses the online sale and fulfillment of pharmaceutical products through licensed digital channels, requiring cold-chain integrity for biologics and temperature-sensitive compounds alongside HIPAA-compliant data architecture. Its primary purpose is to reduce patient friction in medication access while enabling payers to enforce formulary compliance through real-time benefit integration. Prescription drugs command the dominant value share given reimbursement complexity and recurring refill economics, while same-day delivery represents the fastest-expanding delivery mode as urban density supports courier network efficiency. Individual consumers generate the highest transaction volume, though hospitals and healthcare providers concentrate bulk purchasing power that shapes contract pricing dynamics.
FDA oversight of online pharmacy legitimacy through its BeSafeRx program combines with CMS telehealth reimbursement policies and state-level board of pharmacy regulations to create a fragmented compliance landscape that elevates platform verification costs. HIPAA requirements for protected health information govern patient data flows across ordering, payment, and clinical consultation interfaces. Stakeholders must monitor evolving state pharmacist prescriptive authority expansions and FDA track-and-trace mandates as these rules determine which platforms can legally dispense controlled substances and specialty therapies.
Market Dynamics
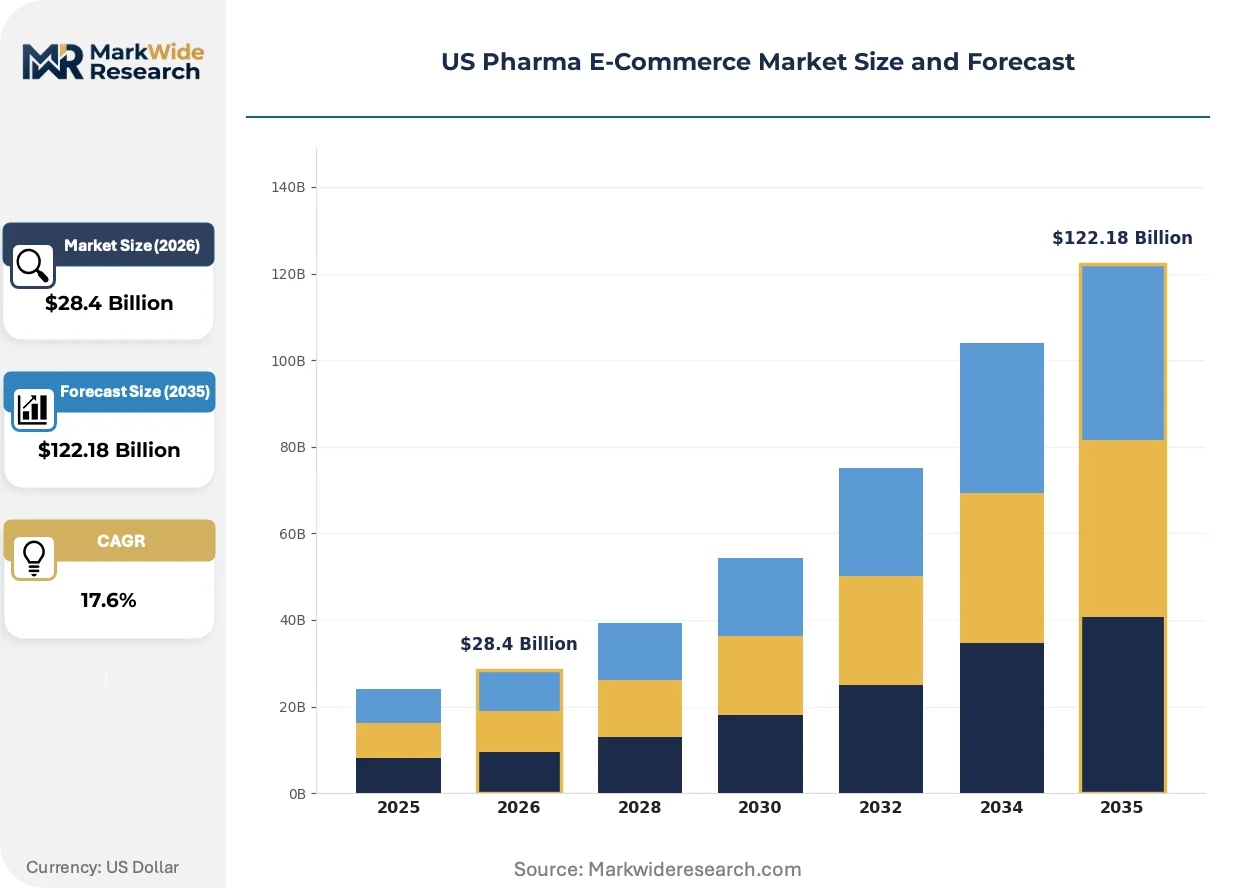
CMS telehealth reimbursement expansion is rewiring prescription fulfillment economics, pulling chronic disease patients toward digital refill channels and forcing pharmacy networks to restructure around direct-to-patient logistics rather than retail foot traffic.
Growth Catalysts
- HIPAA-compliant data architectures:Federally mandated patient privacy frameworks enable secure health information exchange across ordering, payment, and clinical consultation interfaces.
- State pharmacist scope-of-practice expansion:California and Florida now permit broader prescriptive authority, concentrating telehealth-integrated prescription flows in these jurisdictions.
- Cold-chain logistics automation:Temperature-controlled fulfillment networks now support biologics and specialty therapies through automated warehouse robotics and real-time monitoring systems.
Market Restraints
- FDA BeSafeRx verification costs:Platform legitimacy screening and ongoing compliance monitoring create persistent overhead for digital pharmacy operators.
- State board of pharmacy fragmentation:Fifty distinct regulatory regimes generate legal complexity that limits national scale for controlled substance dispensing.
- Specialty pharmacy credentialing timelines:URAC and ACHC accreditation processes stretch 12-18 months, gating entry for new market entrants.
Strategic Opportunities
- Medicare Advantage chronic disease management:Plan sponsors seek digital-first refill programs to improve medication adherence metrics and star ratings.
- Same-day urban courier networks:Dense metropolitan delivery infrastructure enables competitive differentiation through speed guarantees for recurring shipments.
- FDA track-and-trace mandate compliance:Serialized drug verification requirements create demand for integrated supply chain visibility platforms.
Industry Challenges
- Controlled substance dispensing restrictions:Ryan Haight Act limitations on remote prescribing of Schedule II-V drugs constrain revenue mix for pure-play digital pharmacies.
- Legacy pharmacy management system integration:Enterprise resource planning and inventory systems require costly API development to connect with patient-facing digital storefronts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pharma E-Commerce Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $122.18 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter Products, Dietary Supplements, Personal Care Products Delivery Mode: Home Delivery, Curbside Pickup, In-Store Pickup, Same-Day Delivery Customer Type: Hospitals, Retail Pharmacies, Individual Consumers, Healthcare Providers Payment Method: Credit Card, Insurance Billing, Digital Wallets, Bank Transfer |
| Companies Covered | Amazon.com, Inc., CVS Health, Walgreens Boots Alliance, Walmart Inc., Express Scripts, OptumRx, Inc., Rite Aid Corp., The Kroger Co., GoodRx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pharma E-Commerce Market Trends and Innovations
Prescription fulfillment is fragmenting across specialized digital channels, with automation, regulatory adaptation, and patient behavioral shifts converging to compress traditional retail pharmacy relevance.
Real-time benefit integration technology is rewriting how patients encounter medication costs at the point of prescribing. Pharmacy benefit managers embed formulary and copay data directly into prescriber workflows and patient portals. Medicare Advantage plans and employer-sponsored programs now demand this transparency to reduce prescription abandonment rates.
CMS telehealth reimbursement parity policies are expanding the eligible provider set for remote prescribing. State Medicaid programs and commercial payers follow federal precedent, loosening geographic and site-of-service restrictions. California and Florida regulators process the bulk of these waivers, creating regulatory gravity for platform licensing decisions.
Patient refill behavior is consolidating around subscription-style medication management. Chronic disease patients in diabetes, hypertension, and hyperlipidemia therapeutic classes expect automated shipment scheduling and proactive adherence outreach. Urban corridors with courier network density see highest conversion from retail pickup to home delivery models.
US Pharma E-Commerce Market Segmentation
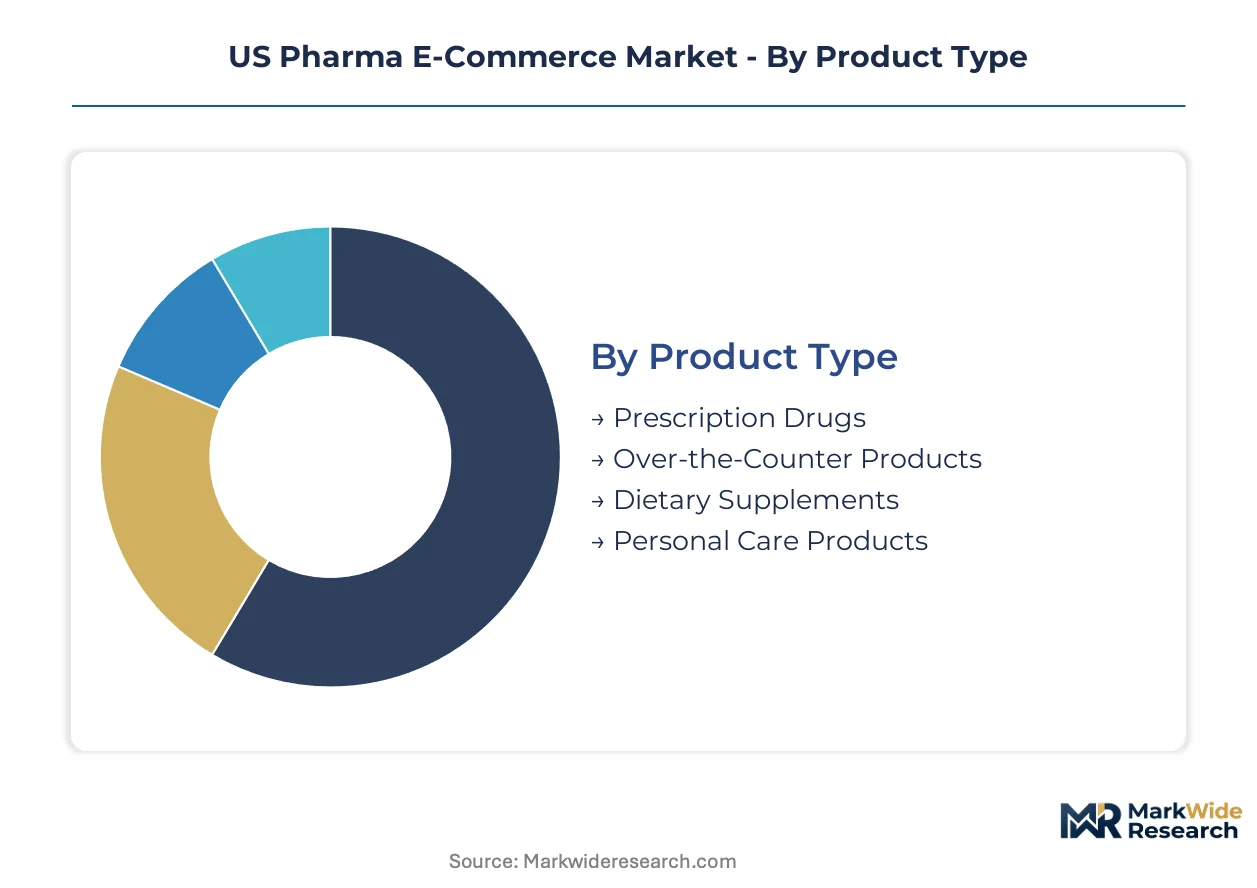
Segmentation in US pharma e-commerce reveals how reimbursement complexity, logistics infrastructure, and prescriptive authority shape platform economics. Each dimension exposes distinct margin structures and regulatory barriers that determine competitive viability.
Product Type:
Replacement cycles vary sharply across therapeutic categories, with chronic medications driving recurring revenue while acute prescriptions demand different fulfillment velocity.
- Prescription Drugs:These require temperature-controlled handling for biologics and real-time benefit verification at checkout. Demand concentrates among Medicare Advantage enrollees in California and Florida where pharmacist scope-of-practice laws support telehealth-integrated dispensing. CMS reimbursement parity pulls chronic disease patients toward automated refill channels.
- Over-the-Counter Products:Self-directed purchases bypass prescription verification, enabling faster checkout flows and broader SKU expansion. Volume clusters in urban corridors with same-day courier density where convenience premiums override retail price competition.
- Dietary Supplements:FDA regulates these as food products, exempting platforms from pharmacy licensing requirements that constrain prescription fulfillment.
- Personal Care Products:Adjacent health and wellness SKUs extend customer lifetime value through cross-sell algorithms tied to medication purchase history.
Prescription Drugs sits at the top of the volume ranking, with Same-Day Delivery climbing the fastest.
Delivery Mode:
Cost tiers separate premium speed guarantees from economy scheduled shipments, with infrastructure investment requirements scaling non-linearly across the spectrum.
- Home Delivery:Standard ground shipping dominates rural and suburban markets where courier density cannot support accelerated service. Cold-chain packaging adds per-unit cost that platforms absorb or pass through based on competitive positioning.
- Same-Day Delivery:Urban courier networks enable competitive differentiation through speed guarantees for recurring medication shipments. California and Florida metropolitan areas see highest conversion rates as telehealth prescribing concentrates in these jurisdictions.
- Curbside Pickup:Bridges digital ordering with existing retail pharmacy footprints, reducing last-mile cost while preserving patient-pharmacist interaction.
- In-Store Pickup:Lowest fulfillment cost option, retaining foot traffic for ancillary purchases while satisfying immediate medication needs.
Home Delivery captures the largest volume share, while Same-Day Delivery gains share fastest in metropolitan markets.
Customer Type:
Application context determines order size, formulary complexity, and integration requirements with existing health IT infrastructure.
- Individual Consumers:Direct-to-patient transactions generate highest transaction volume but smallest average order values. Medicare Advantage plan sponsors target this segment with digital-first refill programs to improve medication adherence metrics and star ratings.
- Hospitals:Bulk purchasing power shapes contract pricing dynamics for specialty therapies and controlled substances. URAC and ACHC accreditation requirements gate platform participation in hospital procurement networks.
- Retail Pharmacies:Competing fulfillment channels that must integrate with enterprise pharmacy management systems through costly API development.
- Healthcare Providers:Prescribing workflows demand real-time formulary integration to reduce prescription abandonment rates at the point of care.
Individual Consumers dominate transaction count, with Hospitals expanding most quickly through specialty pharmacy credentialing.
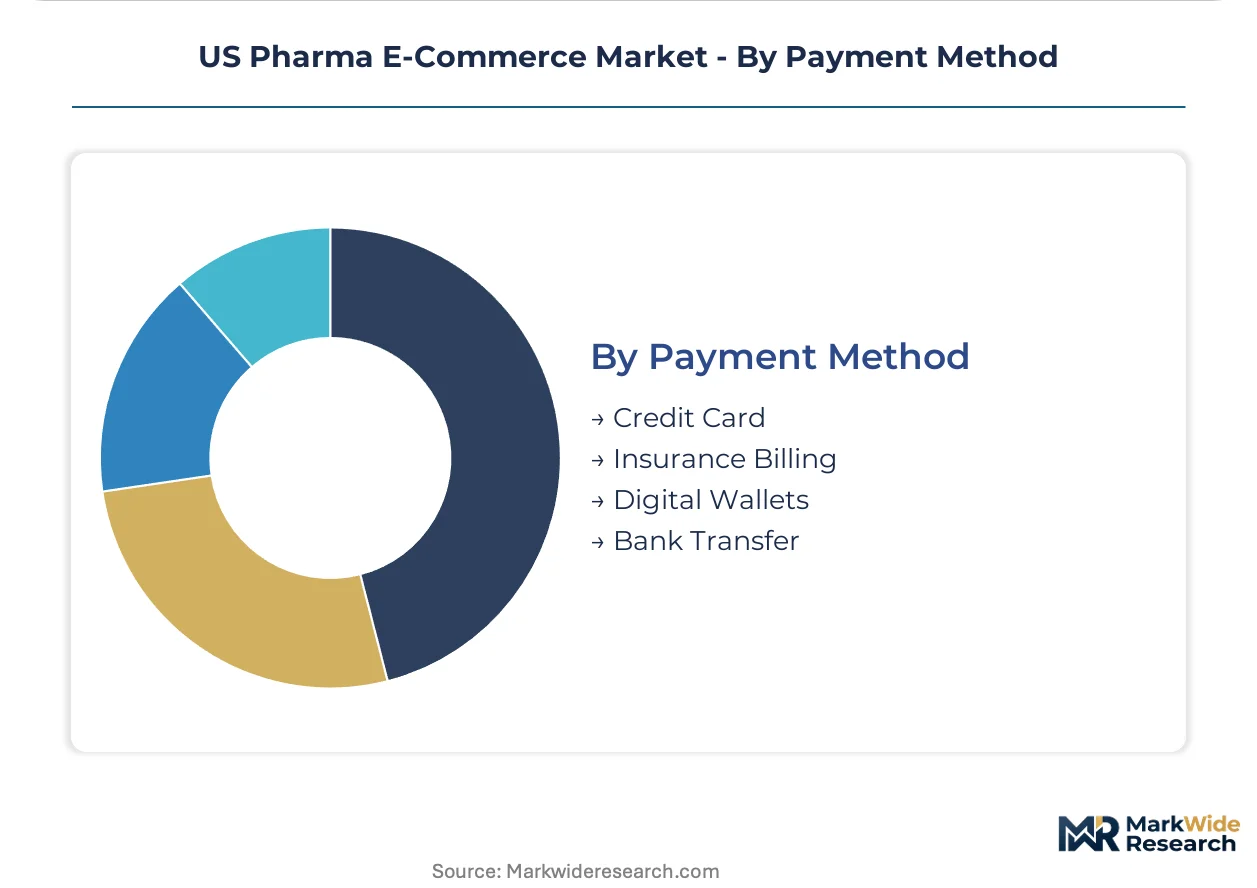
Payment Method:
Margin profiles diverge based on transaction processing costs, reimbursement timing, and fraud exposure across payment rails.
- Insurance Billing:Real-time benefit integration embeds formulary and copay data directly into patient portals. Medicare Advantage and employer-sponsored programs mandate this transparency to reduce abandonment.
- Digital Wallets:Accelerated checkout reduces friction for over-the-counter and supplement purchases where prescription verification is absent.
- Credit Card:Standard payment rail for uninsured or out-of-network transactions, carrying higher processing fees than insurance adjudication.
- Bank Transfer:Lowest processing cost option, typically reserved for high-value specialty medication orders with extended payment terms.
Insurance Billing leads by transaction value, with Digital Wallets showing steepest expansion trajectory among younger demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California and Florida concentrate telehealth-integrated prescription flows, while Texas and New York Metro develop competing logistics infrastructure for direct-to-patient fulfillment.
California
Pharmacist scope-of-practice expansion permits broader prescriptive authority, attracting platform licensing decisions from national operators. FDA BeSafeRx verification requirements apply alongside state board of pharmacy regulations governing controlled substance dispensing. The San Francisco Bay Area and Los Angeles corridor host dense courier networks enabling same-day delivery conversion for chronic disease patients.
Florida
Medicare Advantage enrollment density drives demand for digital-first refill programs targeting medication adherence metrics. State Medicaid programs follow federal CMS telehealth reimbursement parity precedent, loosening geographic restrictions on remote prescribing. The Miami-Fort Lauderdale and Tampa metropolitan areas see concentrated platform investment in temperature-controlled fulfillment infrastructure.
Texas
Urban population growth supports courier network economics for recurring medication shipments in Dallas-Fort Worth and Houston. State pharmacy regulations maintain stricter controlled substance dispensing protocols than California or Florida, limiting pure-play digital pharmacy market entry. The Austin corridor attracts specialty pharmacy credentialing operations serving hospital procurement networks.
New York Metro
Employer-sponsored health plan density creates demand for real-time benefit integration at the point of prescribing. State insurance regulations mandate formulary transparency to reduce prescription abandonment rates. The New York City and northern New Jersey logistics cluster supports cold-chain distribution for biologics and temperature-sensitive compounds.
Illinois
Midwest distribution hub positioning enables ground shipping coverage of secondary markets with lower courier density than coastal metros. State board of pharmacy maintains controlled substance dispensing restrictions that constrain telehealth prescribing volume. The Chicago metropolitan area anchors regional fulfillment networks serving Medicare Advantage plans across surrounding states.
US Pharma E-Commerce Market Competitive Landscape
California and Florida operators anchor one tier; Texas and Midwest specialists hold regional fulfillment positions. Market structure consolidates around vertically integrated retail pharmacy networks, pure-play logistics platforms, and specialty pharmacy credentialing organizations. Three archetypes dominate: dense last-mile retailers, automation-driven direct shippers, and URAC-accredited specialty providers. Competitive moves center on courier network density expansion and API integration with legacy pharmacy management systems.
Within the retail-digital hybrid tier, CVS Health and Walgreens Boots Alliance exemplify archetypes combining physical footprint with platform investment. Amazon.com, Inc. occupies a position representing logistics-automation competitive pressure on speed metrics. These three entities sit within a landscape where platform verification costs and state regulatory fragmentation determine viable scaling paths.
| Leading Market Players |
|---|
| Amazon.com, Inc. |
| CVS Health |
| Walgreens Boots Alliance |
| Walmart Inc. |
| Express Scripts |
| OptumRx, Inc. |
| Rite Aid Corp. |
| The Kroger Co. |
| GoodRx |
| Others |
Pricing and Supply Chain Analysis
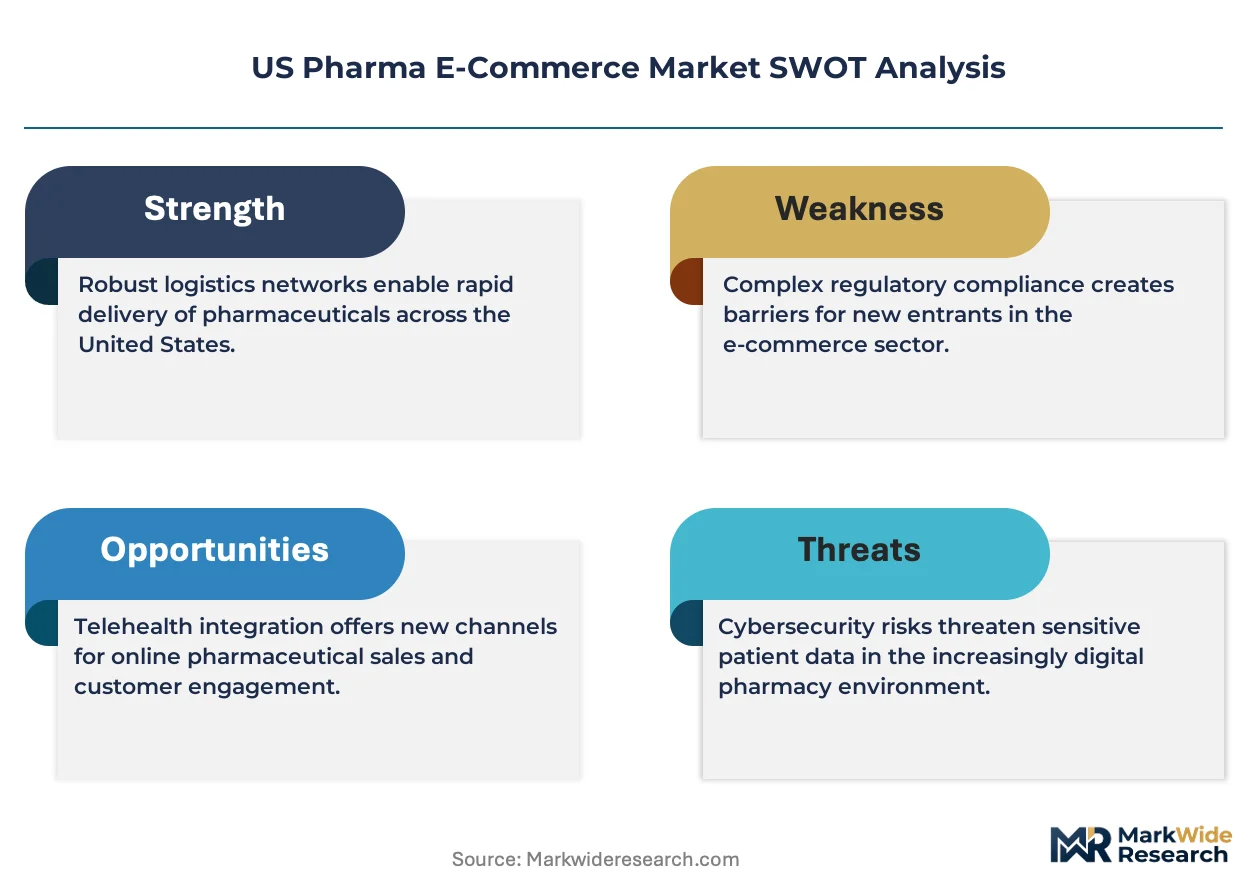
FDA track-and-trace serialization mandates gate qualified supply access for premium-tier pricing, as platforms bearing DSCSA-compliant infrastructure command formulary inclusion while non-compliant operators absorb exclusion penalties from payers.
Pricing Analysis
Capacity additions in Texas and Arizona are reshaping price floors for standard ground shipments, compressing margins for regional fulfillment networks lacking cold-chain certification. Three-tier pricing structure across specialty-courier, standard-home, and economy-mail tiers separates URAC-accredited platforms from retail-digital hybrids from pure-play logistics entrants. Cost compression in the economy tier is intensifying because Amazon automation investments reset patient delivery expectations. Medicare Advantage plan sponsors show lowest price sensitivity due to star-rating adherence incentives, while uninsured cash-pay patients drive fierce price competition.
Supply Chain Analysis
URAC and ACHC accreditation requirements gate supplier qualification, limiting viable API sourcing to FDA-registered facilities in India, Ireland, and Puerto Rico. Temperature-controlled biologics draw from specialized cold-chain packaging inputs, real-time monitoring sensors, and validated thermal shippers. Single-source vulnerability concentrates in Indian API manufacturers subject to FDA import alerts. Distribution runs through hub-and-spoke pharmacy fulfillment centers with last-mile courier injection in metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US pharma e-commerce rests on cold-chain automation cost-down curves and specialty pharmacy premium-tier migration away from commoditized retail dispensing.
For Market Incumbents: Extend courier network density through micro-fulfillment site expansion in California and Florida metropolitan corridors. Consolidate position by acquiring URAC-accredited specialty pharmacies to capture high-margin biologics dispensing threatened by Amazon logistics automation. For New Entrants and Emerging Players: Enter via white-space same-day delivery corridors in secondary metros—Phoenix, Atlanta, and Denver—where incumbent courier saturation remains incomplete. Target Medicare Advantage plan sponsor contracts with adherence-monitoring bundled pricing as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional specialty pharmacy platforms because state pharmacist scope-of-practice fragmentation prevents national scale, creating local monopoly value. Five-to-ten-year viability hinges on telehealth prescribing volume trajectories. Watch CMS reimbursement parity expansion signals as the inflection indicator for platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Investment | Enables biologics dispensing compliance with FDA temperature excursion protocols. |
| Real-Time Benefit Integration | Reduces prescription abandonment through CMS-mandated formulary transparency at checkout. |
| Specialty Pharmacy Accreditation | Unlocks hospital procurement networks and high-margin oncology therapy fulfillment. |
| Courier Network Density Expansion | Supports same-day delivery guarantees that differentiate against retail pharmacy pickup. |
| API Sourcing Diversification | Mitigates FDA import alert exposure concentrated in Indian manufacturing clusters. |
Research Methodology
Bottom-up patient-volume modeling reconciled against top-down pharmacy dispensing tracking forms the analytical core of this study. Primary interviews with formulary directors, telehealth platform operators, state board of pharmacy regulators, and cold-chain logistics providers combined with secondary validation against FDA BeSafeRx enforcement actions, CMS Medicare Advantage enrollment data, and URAC accreditation directories. Triangulation across these sources anchored segmentation-level volume estimates.
Input-output matrices mapped prescription flows across product type, delivery mode, customer archetype, and state regulatory cluster throughout the forecast period. CAGRs derived from trend-line extrapolation of telehealth prescribing volume, courier network expansion rates, and Medicare Advantage plan sponsor digital-first program adoption. Industry-specific forecast inputs included pharmacist scope-of-practice legislative tracking and FDA DSCSA implementation timelines.
Inputs from CMS reimbursement filings and state board of pharmacy rulemaking dockets were available through the study window; gaps in controlled substance dispensing waiver data introduce uncertainty bands around Schedule II-V volume projections. Forecasts reflect documented assumptions regarding telehealth parity policy durability and cold-chain packaging cost curves. A model refresh is warranted upon material change in CMS site-of-service restrictions or FDA import alert patterns affecting API supply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
LAMEA Dropshipping Market
E-Commerce Solutions
Express and Parcel Market
E-Commerce Solutions
Canada E-Commerce Market
E-Commerce Solutions
Dropshipping Market
E-Commerce Solutions
United Kingdom Same Day Delivery Market
E-Commerce Solutions
India E-Commerce Market
E-Commerce Solutions
North America B2B E-Commerce Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
Germany E-Commerce Market
E-Commerce Solutions
Global Omnichannel Retail Commerce Platform Market
E-Commerce Solutions
United States E-Invoicing Market
E-Commerce Solutions
Digital Gift Cards (Egift Cards) Market
E-Commerce Solutions
Nigeria Alcohol E-Commerce Market
E-Commerce Solutions
Indonesia Ecommerce Logistics Market
E-Commerce Solutions
Japan E-Commerce Market
E-Commerce Solutions
UAE Ecommerce Market