
 Multi-Channel E-Commerce Software Market | 2026-2036
Multi-Channel E-Commerce Software Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Channel E-Commerce Software Market Insights
Capital intensity divergence between cloud-native platforms and legacy on-premises providers is bifurcating competitive dynamics across the sector. Shopify Plus leverages its integrated payments ecosystem to sustain merchant retention at scale, while BigCommerce anchors its position through open-API architecture that appeals to enterprise developers. Adobe Commerce differentiates via deep creative suite integration, occupying a niche among content-heavy retailers that prioritize design flexibility over speed-to-market.
Multi-channel e-commerce software encompasses integrated platforms that synchronize product listings, inventory levels, order routing, and customer data across disparate sales channels through API-based middleware and real-time database replication. These systems typically process transaction volumes exceeding ten thousand orders per hour while maintaining sub-second latency for inventory updates across marketplaces, proprietary storefronts, and social commerce endpoints. Cloud-based deployment leads absolute revenue contribution as vendors shift from perpetual licenses to recurring SaaS models, though hybrid configurations capture expanding margin pools among enterprises with legacy ERP dependencies. Payment processing represents the fastest-growing product type segment as embedded finance capabilities deepen merchant stickiness and generate incremental transaction-based revenue streams.
FCC guidelines on digital advertising transparency and the EU AI Act's algorithmic accountability provisions are elevating compliance module requirements within vendor product roadmaps, particularly for automated pricing and recommendation engines. GDPR data localization mandates and emerging state-level privacy statutes in California and Virginia are fragmenting cloud infrastructure strategies, forcing providers to maintain region-specific data residency architectures. Stakeholders must monitor regulatory divergence between jurisdictions as compliance tooling becomes a primary vendor selection criterion rather than a secondary feature.
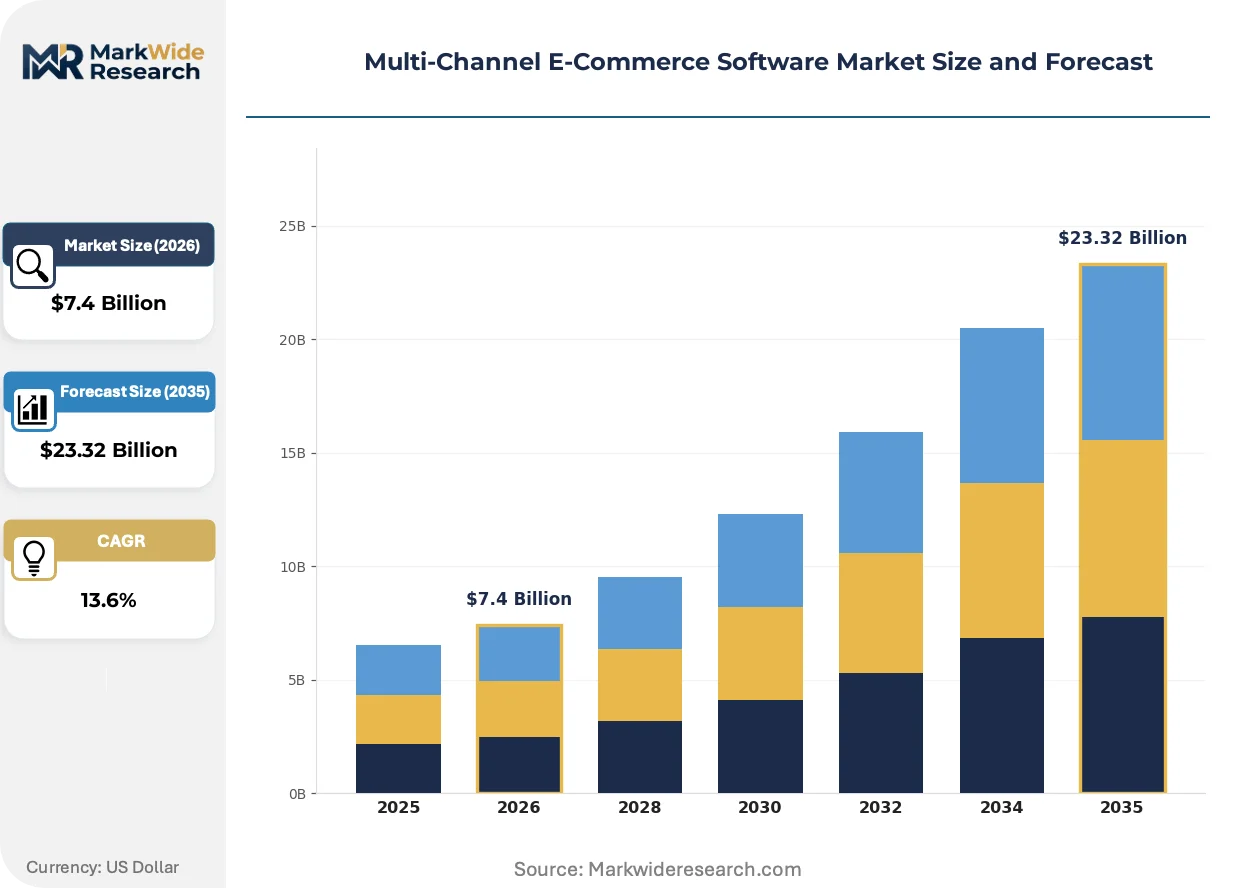
Market Dynamics
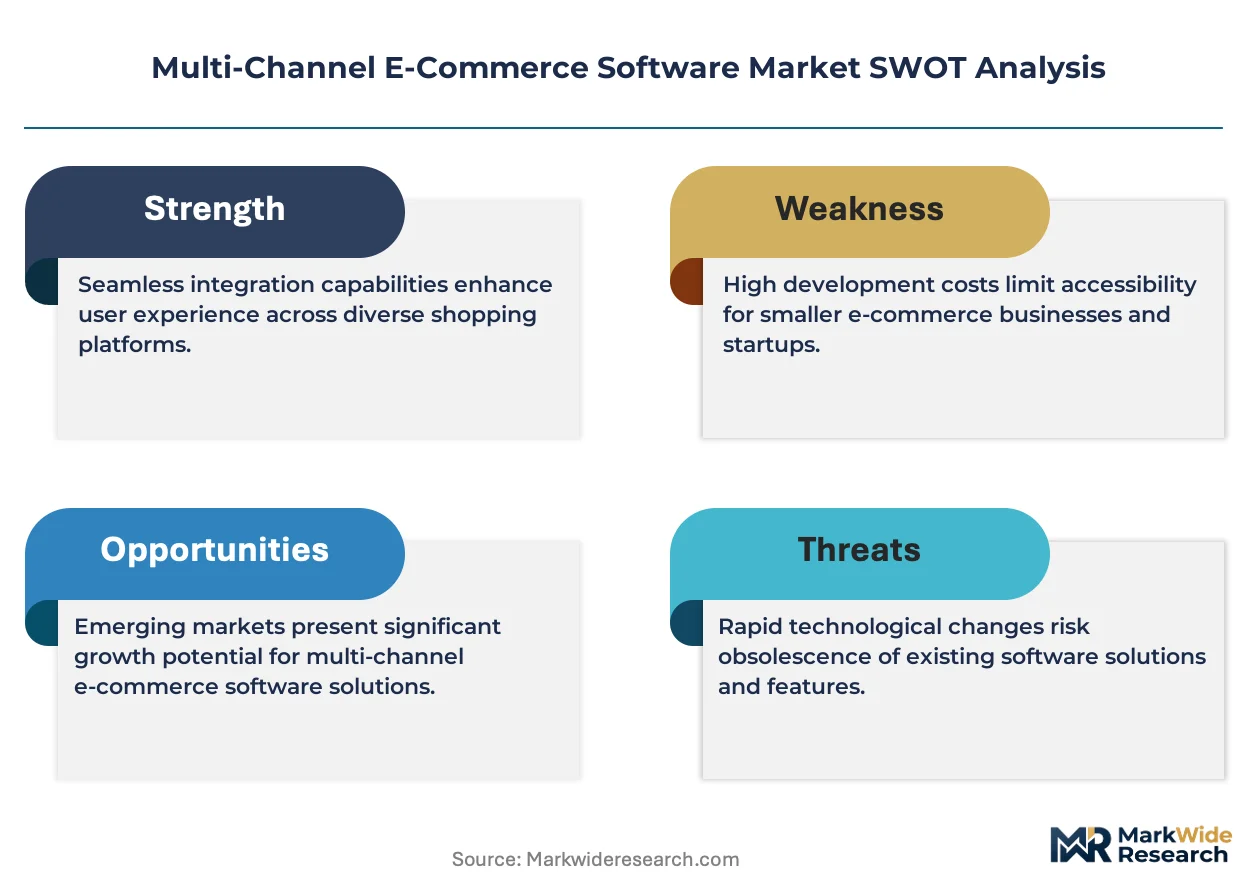
Cloud-native SaaS architectures are compressing the total cost of ownership gap between enterprise-grade and mid-market solutions, forcing legacy on-premises vendors to accelerate platform modernization or cede share to API-first competitors.
Growth Catalysts
- EU Digital Services Act:Marketplace transparency mandates are compelling retailers to adopt unified order-tracking systems that integrate across Amazon, eBay, and proprietary storefronts.
- Headless commerce architecture:Decoupled frontend-backend systems enable brands to deploy channel-specific experiences without rebuilding core transaction engines.
- Social commerce endpoints:TikTok Shop and Instagram Checkout integrations are driving demand for real-time inventory synchronization across entertainment and retail platforms.
Market Restraints
- API rate limiting:Amazon Marketplace and Walmart Seller Center impose throttling thresholds that constrain high-volume merchants during peak transaction periods.
- Data residency fragmentation:GDPR localization requirements force vendors to maintain separate cloud instances for EU, UK, and Swiss customer datasets.
- Legacy ERP dependencies:SAP and Oracle on-premises installations create middleware complexity that extends implementation timelines by 8-14 months.
Strategic Opportunities
- Embedded finance convergence:Buy-now-pay-later and merchant cash advance integrations transform software vendors into revenue-generating financial intermediaries.
- B2B marketplace underpenetration:Industrial distributors in Germany and France lag consumer retail in multi-channel adoption, presenting first-mover expansion potential.
- AI-driven dynamic pricing:Algorithmic repricing engines that respond to competitor movements in under 30 seconds are attracting high-velocity sellers.
Industry Challenges
- Integration talent scarcity:Full-stack developers with simultaneous expertise in Shopify Liquid, Magento PHP, and marketplace API protocols command premium compensation.
- Cross-border tax automation:VAT OSS and IOSS compliance for EU distance selling requires real-time jurisdictional rule updates that strain engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Channel E-Commerce Software Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $23.32 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shopping Cart, Inventory Management, Customer Relationship Management, Payment Processing Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Small Businesses, Medium Enterprises, Large Corporations, Online Marketplaces Service Type: Consulting, Integration, Support, Training |
| Companies Covered | Shopify Plus, BigCommerce, Descartes Sellercloud, Rithum, ChannelEngine, Channable, Zentail, Linnworks, Adobe Commerce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Channel E-Commerce Software Market Trends and Innovations
Real-time data synchronization protocols are displacing batch-processing architectures as the default expectation for inventory and order management across distributed commerce environments.
Composable commerce stacks built on microservices are supplanting monolithic platforms among mid-market retailers seeking to swap individual components without full replatforming. Merchants with $10-50 million annual GMV are migrating fastest, typically replacing legacy suites with best-of-breed cart, OMS, and PIM combinations. This modularity is compressing vendor lock-in duration from multi-year contracts to annual or even month-to-month arrangements.
The EU AI Act's risk-based classification system is mandating algorithmic audit trails for automated pricing and recommendation engines deployed in European markets. Vendors must now document training data provenance and decision logic for high-risk AI applications. Enterprise retailers with cross-border operations are consolidating vendor selection around providers with pre-certified compliance modules.
Merchant procurement patterns are shifting from perpetual licenses to consumption-based pricing tied to order volume or GMV tiers. This unbundles software costs from fixed capex budgets and aligns vendor revenue with merchant success metrics. The model is gaining traction fastest among direct-to-consumer brands in California and New York seeking to preserve cash during scaling phases.
Multi-Channel E-Commerce Software Market Segmentation
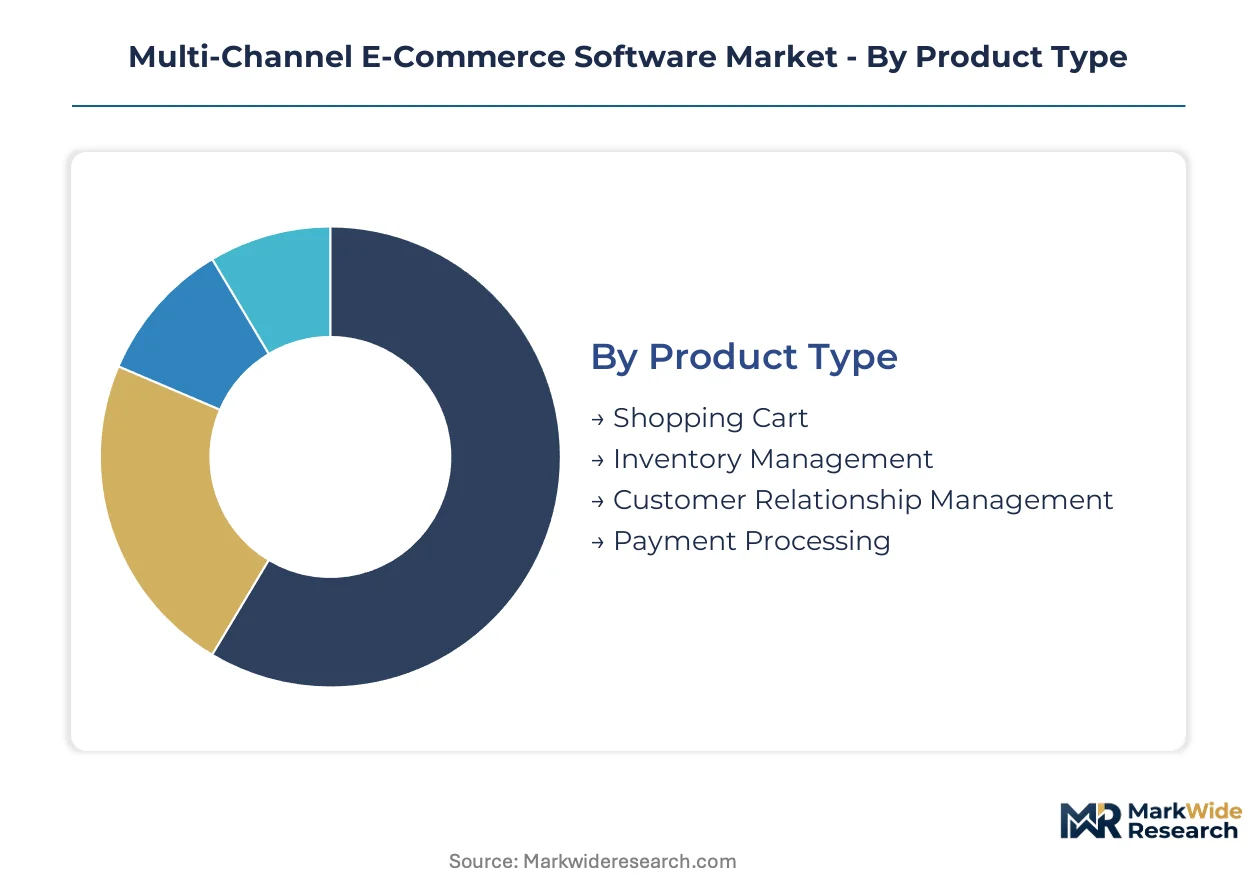
Multi-channel e-commerce software segmentation reflects divergent compliance burdens across deployment modes and the capital efficiency pressures reshaping buyer procurement patterns. Vendors align product architecture with specific regulatory thresholds rather than pursuing universal platform designs.
Product Type:
GDPR's data localization mandates and the EU AI Act's algorithmic accountability requirements create divergent feature roadmaps across product categories, with payment modules facing the strictest audit obligations.
- Payment Processing:Embedded finance infrastructure handling transaction authorization, settlement, and merchant cash advance distribution. Demand concentrates among high-velocity sellers in California and New York seeking to monetize transaction flows beyond software subscriptions. FCC digital advertising transparency guidelines elevate compliance module requirements for payment-adjacent data handling.
- Inventory Management:Real-time synchronization engines maintaining sub-second latency across distributed warehouse networks and marketplace endpoints. German and French industrial distributors drive emerging adoption as B2B marketplace penetration lags consumer retail. API rate limiting from Amazon Marketplace and Walmart Seller Center constrains peak-period performance.
- Shopping Cart:Transaction orchestration layers managing checkout flows, tax calculation, and cross-border compliance.
- Customer Relationship Management:Unified profile systems aggregating purchase history, support interactions, and marketing touchpoints across channels.
Established volume favors Inventory Management; emerging adoption favors Payment Processing.
Deployment:
Cost tier differentiation separates enterprise-grade infrastructure investments from mid-market SaaS consumption patterns.
- Cloud-Based:Multi-tenant architectures with region-specific data residency instances. Small and medium enterprises in the United States represent the fastest-expanding customer base as reduced upfront capital requirements accelerate procurement cycles. GDPR localization forces maintenance of separate EU, UK, and Swiss cloud instances.
- SaaS:Consumption-based pricing models tying vendor revenue to order volume or GMV tiers. Direct-to-consumer brands in California and New York favor this structure to preserve cash during scaling phases. The model compresses vendor lock-in duration from multi-year contracts to annual or month-to-month arrangements.
- Hybrid:Configurations bridging legacy ERP dependencies with cloud-native middleware.
- On-Premises:Perpetual license installations retaining data sovereignty within corporate firewalls.
Legacy infrastructure concentration favors On-Premises; cloud migration momentum favors Cloud-Based.
End User:
Application complexity scales with organizational transaction volume and cross-border operational scope.
- Medium Enterprises:Organizations with $10-50 million annual GMV migrating fastest to composable commerce stacks. These buyers replace legacy suites with best-of-breed cart, OMS, and PIM combinations to swap individual components without full replatforming. Procurement patterns favor consumption-based pricing over fixed capex commitments.
- Small Businesses:Merchant cohorts prioritizing speed-to-market over customization depth. Cloud-based deployment eliminates upfront capital barriers that previously constrained multi-channel adoption. VAT OSS and IOSS compliance automation represents a critical selection criterion for EU market access.
- Large Corporations:Enterprise retailers with cross-border operations consolidating vendor selection around pre-certified compliance modules.
- Online Marketplaces:Platform operators requiring API-based middleware for third-party seller integration.
Implementation simplicity favors Small Businesses; integration sophistication favors Large Corporations.
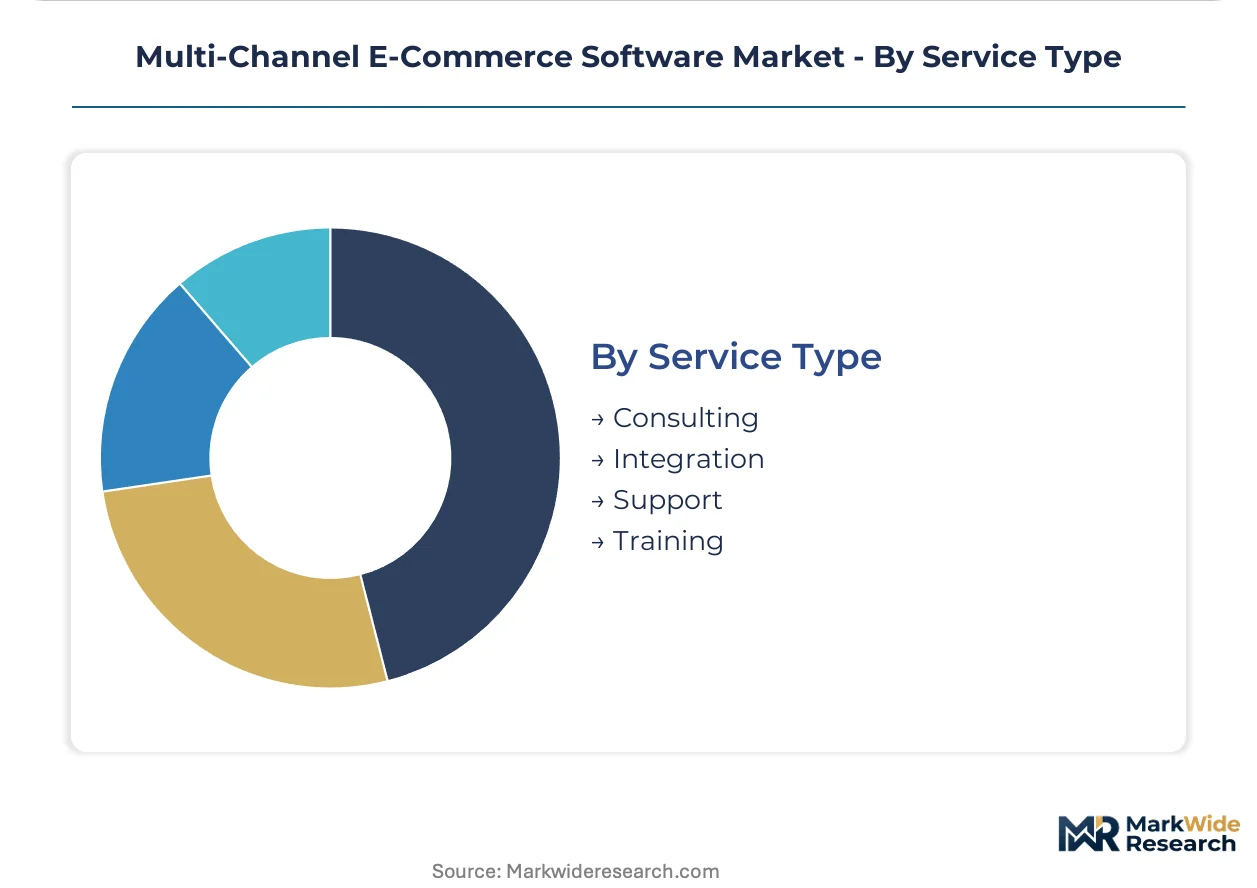
Service Type:
Margin concentration follows implementation complexity and ongoing operational dependency.
- Integration:Middleware development connecting proprietary storefronts with marketplace APIs and legacy ERP systems. Full-stack developers with simultaneous expertise in Shopify Liquid, Magento PHP, and marketplace protocols command premium compensation, constraining vendor scaling capacity. SAP and Oracle on-premises dependencies extend implementation timelines by 8-14 months.
- Consulting:Strategic advisory for channel selection, pricing architecture, and compliance roadmap development.
- Support:Technical assistance for platform maintenance, security patching, and incident response.
- Training:Knowledge transfer programs enabling merchant self-sufficiency in platform administration.
Recurring revenue stability favors Support; project-based margin peaks favor Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies, with United States buyers prioritizing speed-to-market over cost optimization while German purchasers emphasize compliance-certified architectures regardless of price premium.
United States
Established retail infrastructure and marketplace density create favorable conditions for multi-channel adoption, with California and New York direct-to-consumer brands driving consumption-based pricing adoption. FCC guidelines on digital advertising transparency elevate compliance module requirements for automated pricing engines. Los Angeles and New York City clusters concentrate merchant cohorts seeking embedded finance integrations to monetize transaction flows.
Germany
Industrial distributors in Baden-Württemberg and Bavaria lag consumer retail in multi-channel adoption, presenting first-mover expansion potential for B2B marketplace solutions. GDPR data localization mandates force vendors to maintain separate EU cloud instances, fragmenting infrastructure strategies. Berlin and Munich technology clusters anchor vendor development centers focused on algorithmic audit trail certification under the EU AI Act.
United Kingdom
Mid-market retailers with £10-50 million annual GMV migrate fastest to composable commerce stacks, replacing legacy suites with best-of-breed combinations. Post-Brexit VAT OSS and IOSS compliance requirements strain cross-border tax automation capabilities. London fintech corridor concentrates demand for embedded finance convergence including buy-now-pay-later integrations.
France
Content-heavy retailers in Île-de-France prioritize design flexibility over speed-to-market, creating niche demand for creative suite-integrated platforms. CNIL enforcement of GDPR provisions elevates data residency as a primary vendor selection criterion. Lyon and Marseille industrial distribution hubs present underpenetrated B2B marketplace opportunities relative to consumer retail saturation.
India
Small and medium enterprises represent the fastest-expanding customer base as cloud-based deployment eliminates upfront capital barriers previously constraining adoption. TRAI data governance frameworks and emerging digital commerce regulations reshape vendor feature roadmaps. Bangalore and Mumbai technology clusters concentrate full-stack developer talent commanding premium compensation for marketplace API protocol expertise.
Multi-Channel E-Commerce Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding merchant retention through embedded payment ecosystems and the latter gaining traction via open-API architectures that appeal to enterprise developers. Cloud-native SaaS platforms compress total cost of ownership gaps between enterprise-grade and mid-market solutions, forcing legacy on-premises vendors toward accelerated modernization. Two strategic archetypes dominate: integrated commerce suites with native payment processing and modular API-first platforms enabling composable stack assembly. Competitive moves concentrate on M&A for compliance module capabilities and strategic partnerships for marketplace API access.
Within the integrated suite tier, Shopify Plus and Adobe Commerce occupy positions anchored by distinct ecosystem strategies, while BigCommerce exemplifies the API-first archetype appealing to developer-centric procurement. Descartes Sellercloud and ChannelEngine sit within the specialist tier focused on multi-channel inventory orchestration. These company names illustrate the competitive spectrum from full-stack commerce platforms to point solutions for marketplace connectivity.
| Leading Market Players |
|---|
| Shopify Plus |
| BigCommerce |
| Descartes Sellercloud |
| Rithum |
| ChannelEngine |
| Channable |
| Zentail |
| Linnworks |
| Adobe Commerce |
| Others |
Pricing and Supply Chain Analysis
GDPR data localization mandates and EU AI Act algorithmic certification requirements simultaneously gate vendor qualification and stratify pricing tiers across the multi-channel e-commerce software market. Compliance-certified architectures command substantial premiums over uncertified alternatives while disqualifying vendors lacking region-specific cloud infrastructure from European procurement shortlists.
Pricing Analysis
Embedded finance revenue streams including merchant cash advances and buy-now-pay-later integrations drive lifetime value beyond base subscription tiers. Consumption-based pricing tied to GMV or order volume dominates as direct-to-consumer brands favor cash-preservation models over fixed capex commitments. Price differentiation hinges on compliance module depth and API throughput capacity, with high-velocity sellers showing lowest price sensitivity. Cost compression in mid-market SaaS tiers intensifies as cloud-native platforms compress total cost of ownership gaps.
Supply Chain Analysis
Real-time inventory synchronization demands are compressing lead-time tolerance thresholds to sub-second latency requirements across distributed warehouse networks. Engineering talent concentrates in the United States, India, and Germany, with full-stack developers commanding premium compensation for marketplace API protocol expertise. Raw material dependencies span cloud compute capacity, payment processor partnerships, and legacy ERP middleware licenses. Single-source vulnerability in specialized integration talent strains vendor scaling capacity. Distribution runs through direct sales teams for enterprise accounts and self-serve onboarding for small business segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multi-channel e-commerce software market exhibits cyclical recovery characteristics as enterprise retailers deferred replatforming investments during cost-optimization phases and now accelerate procurement amid compliance deadline pressures.
For Market Incumbents: Secure embedded payment ecosystem lock-in through merchant cash advance distribution capabilities that deepen switching costs. Fortify API rate-limiting negotiation leverage with Amazon Marketplace and Walmart Seller Center to preserve high-volume merchant retention. Capacity addition in Berlin and Munich development centers accelerates EU AI Act certification timelines ahead of smaller competitors.
For New Entrants and Emerging Players: GDPR fast-track certification programs enable rapid European market entry without multi-year compliance roadmaps. B2B industrial distributors in Baden-Württemberg and Bavaria present underpenetrated white-space relative to saturated consumer retail segments. Channel-specific social commerce integration for TikTok Shop and Instagram Checkout offers differentiated go-to-market positioning against established full-stack platforms.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native SaaS deployment as multi-tenant architectures reduce incremental customer delivery costs. Target acquisition archetypes include specialist inventory orchestration vendors with pre-built marketplace API connectors and compliance-certified algorithmic pricing engines. The signal to watch is vendor consolidation around pre-certified EU AI Act modules as enterprise procurement shifts toward compliance-guaranteed architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Certification | EU AI Act pre-certification opens enterprise procurement pipelines across German and French retail headquarters. |
| Embedded Finance Integration | Merchant cash advance capabilities transform SaaS vendors into revenue-generating financial intermediaries with superior retention. |
| Social Commerce Endpoint Expansion | TikTok Shop and Instagram Checkout APIs capture demand from entertainment-retail convergence in California and New York. |
| Legacy ERP Middleware Development | SAP and Oracle connector ecosystems extend implementation timelines but capture sticky enterprise accounts with 8-14 month dependencies. |
| Regional Cloud Infrastructure Expansion | Separate EU, UK, and Swiss data residency instances satisfy GDPR localization mandates and disqualify non-compliant competitors. |
Research Methodology
Desk research of SEC filings, hyperscaler capex disclosures, and marketplace API documentation preceded structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists. Primary fieldwork with e-commerce software vendors and enterprise retail technology leaders combined with secondary validation against customs records and cloud infrastructure spending reports. Bottom-up merchant adoption modeling triangulated against top-down market sizing from SaaS revenue disclosures.
Variance decomposition across deployment mode, organization size, vertical specialization, integration complexity, and regional regulatory cluster shaped the analytical framework. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion trajectories. Forecast inputs incorporated API rate-limiting constraints, compliance deadline schedules, and embedded finance adoption curves without year-specific event assumptions.
Decision-makers should treat outputs as directional under sustained cloud migration momentum and stable regulatory enforcement intensity; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
E-Commerce Solutions
Agricultural E-Commerce Market
E-Commerce Solutions
T-Commerce Market
E-Commerce Solutions
Hungary E-Commerce Market
E-Commerce Solutions
India Quick Commerce Market
E-Commerce Solutions
Cyprus E-Commerce Market
E-Commerce Solutions
Quiet Commerce Market
E-Commerce Solutions
Express and Parcel Market
E-Commerce Solutions
Malaysia E-Commerce Market
E-Commerce Solutions
Asia-Pacific E-Commerce Logistics Market
E-Commerce Solutions
Japan Same Day Delivery Market
E-Commerce Solutions
Asia-Pacific FMCG B2B E-Commerce Market
E-Commerce Solutions
India Alcohol E-Commerce Market
E-Commerce Solutions
United States E-Invoicing Market
E-Commerce Solutions
Dropshipping Market
E-Commerce Solutions
Portugal E-Commerce Market
E-Commerce Solutions
France E-Commerce Market