
 Asia-Pacific Microwave Oven Market | 2026-2036
Asia-Pacific Microwave Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Microwave Oven Market Insights
Inverter-based power delivery is narrowing the performance gap between entry-level and premium microwave units across the Asia-Pacific region. Panasonic Corporation leverages its semiconductor subsidiary to control inverter component costs and sustain margin advantages in built-in segments. Samsung Electronics anchors its position through captive magnetron production and integrated supply chains spanning Vietnam and India. Midea Group competes aggressively on manufacturing scale, operating some of the largest microwave oven production facilities globally from its Guangdong base.
A microwave oven is an electric kitchen appliance that generates electromagnetic radiation at frequencies near 2.45 GHz to excite water molecules in food, producing thermal energy through dielectric heating for cooking, reheating, or defrosting applications. The Asia-Pacific market spans countertop, built-in, over-the-range, and commercial product types, with countertop units dominating unit volumes while built-in configurations command higher margin pools in premium residential projects. Convection and grill features are gaining traction fastest among urban households seeking multi-function appliances, though standard models still occupy the largest addressable base across price-sensitive rural markets in India and Indonesia.
China's SAMR enforces GB standards for electromagnetic compatibility and energy efficiency, while India's BIS mandates compulsory registration for microwave ovens under its electronics certification scheme. Japan's METI oversees Top Runner program requirements that push manufacturers toward lower standby power consumption. Stakeholders must monitor how diverging national efficiency benchmarks reshape regional product portfolios and determine whether localized certification investments outweigh standardization savings.
Market Dynamics
Inverter-based power delivery is compressing performance gaps between entry-level and premium microwave units across Southeast Asia, while India's BIS energy-efficiency mandates and China's GB standards for electromagnetic compatibility force portfolio reconfiguration.
Growth Catalysts
- Urban household expansion:Compact kitchen appliances gain priority among Southeast Asia's rising middle class, with first-time appliance ownership climbing in India's tier-two cities and China's interior provinces.
- BIS labeling mandates:India's compulsory energy-efficiency registration creates pull for certified inverter models, accelerating replacement cycles in price-sensitive segments previously dominated by unbranded imports.
- Convection-grill convergence:Multi-function appliances address space constraints in dense urban housing, with grill features penetrating fastest among Jakarta, Bangkok, and Ho Chi Minh City apartment dwellers.
Market Restraints
- Magnetron supply concentration:Captive production networks in Vietnam and India create dependency on integrated manufacturers, limiting component sourcing flexibility for independent assemblers.
- GB standard compliance costs:China's SAMR electromagnetic compatibility testing requirements impose fixed certification burdens that disproportionately squeeze regional exporters with limited China revenue.
- Induction cooktop substitution:Built-in induction hobs with warming functions capture premium kitchen renovation budgets in Japan and South Korea, constraining built-in microwave attachment rates.
Strategic Opportunities
- Indonesia's underpenetrated tier-three cities:First-time ownership rates in Surabaya, Bandung, and Medan lag national averages by 40-60 points, creating whitespace for basic countertop units with localized voltage tolerance.
- Commercial foodservice digitization:Cloud kitchens and ghost kitchen operators in Singapore and Sydney seek programmable cooking profiles, opening specification channels bypassing traditional retail.
- METI Top Runner alignment:Japan's standby power consumption targets reward manufacturers achieving sub-one-watt idle draw, creating premium positioning for semiconductor-controlled inverter architectures.
Industry Challenges
- RF engineer scarcity:Electromagnetic compatibility design expertise concentrates in Japan and South Korea, forcing Southeast Asian manufacturers to outsource critical testing phases.
- Multi-jurisdiction certification timelines:Simultaneous BIS, GB, and JIS compliance cycles extend product launch windows by 8-14 months for pan-Asia portfolio strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Microwave Oven Market |
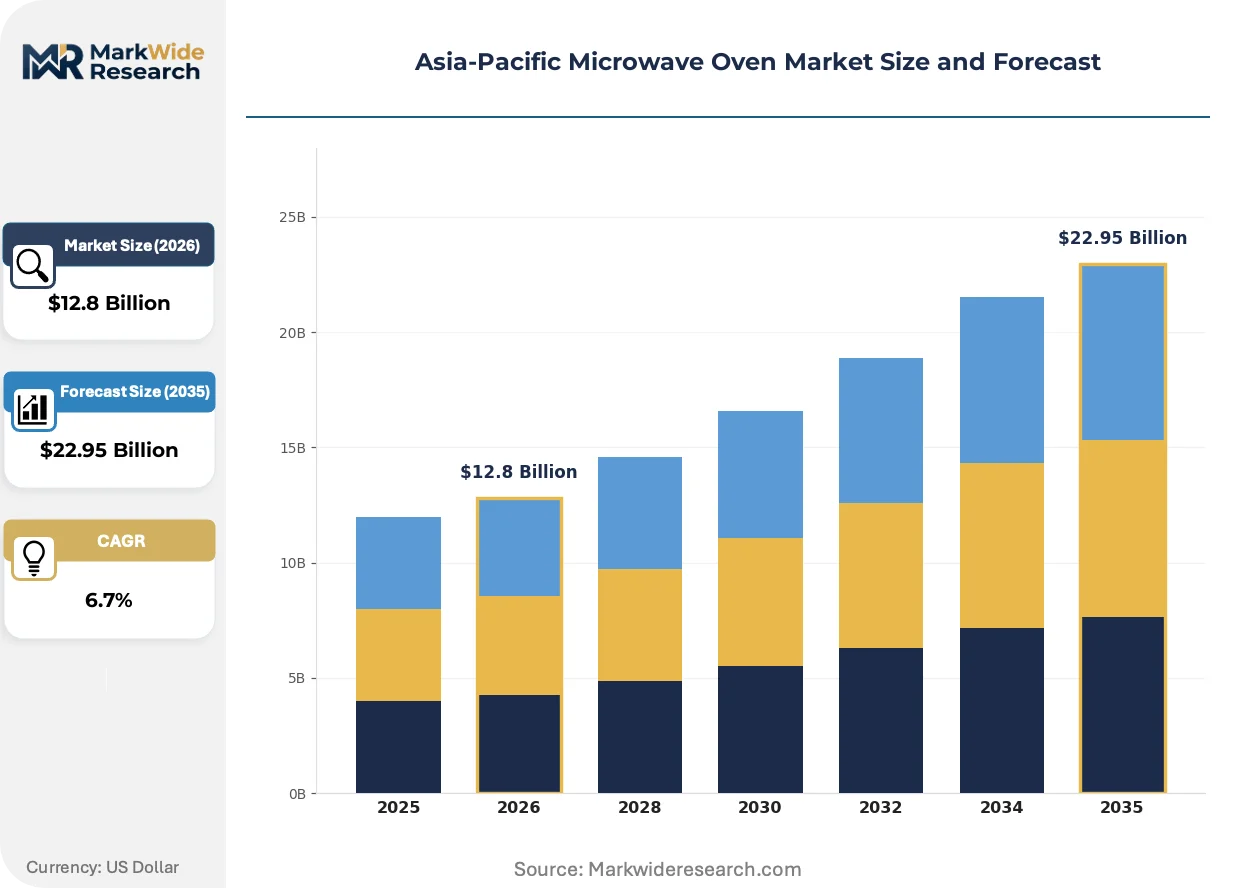
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Built-in, Over-the-Range, Commercial Feature: Convection, Grill, Sensor Cooking, Standard End User: Household, Restaurants, Cafes, Food Service Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Panasonic Corporation, Samsung Electronics, LG Electronics, Sharp Corporation, Midea Group, Robert Bosch GmbH, Haier Smart Home, IFB Industries Ltd, Galanz Enterprises, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Microwave Oven Market Trends and Innovations
Smart connectivity and sensor-based cooking automation are redefining user interfaces across the Asia-Pacific microwave oven landscape, compressing the traditional feature-ladder timeline.
Inverter power modules with silicon-based semiconductor control are digitizing thermal delivery precision previously achievable only through mechanical power cycling. Urban households in Seoul, Tokyo, and Shanghai are adopting sensor-equipped models at replacement rates twice those of basic units. This digitization is collapsing the historical three-tier quality hierarchy into two distinct performance bands.
India's BIS compulsory registration scheme for microwave ovens is tightening energy-efficiency thresholds on a three-year revision cycle. Domestic manufacturers must now submit third-party test reports for standby power and cooking efficiency metrics before market entry. The scheme most affects countertop imports from unbranded Chinese assemblers previously exempt from formal compliance.
Apartment-dweller preference for multi-function appliances is compressing single-purpose device ownership in Southeast Asian cities. Buyers in Bangkok and Jakarta increasingly reject standalone grills and toaster ovens in favor of convection-microwave combinations. This consolidation is most visible among 25-40 year-old first-home purchasers in buildings under 60 square meters.
Asia-Pacific Microwave Oven Market Segmentation
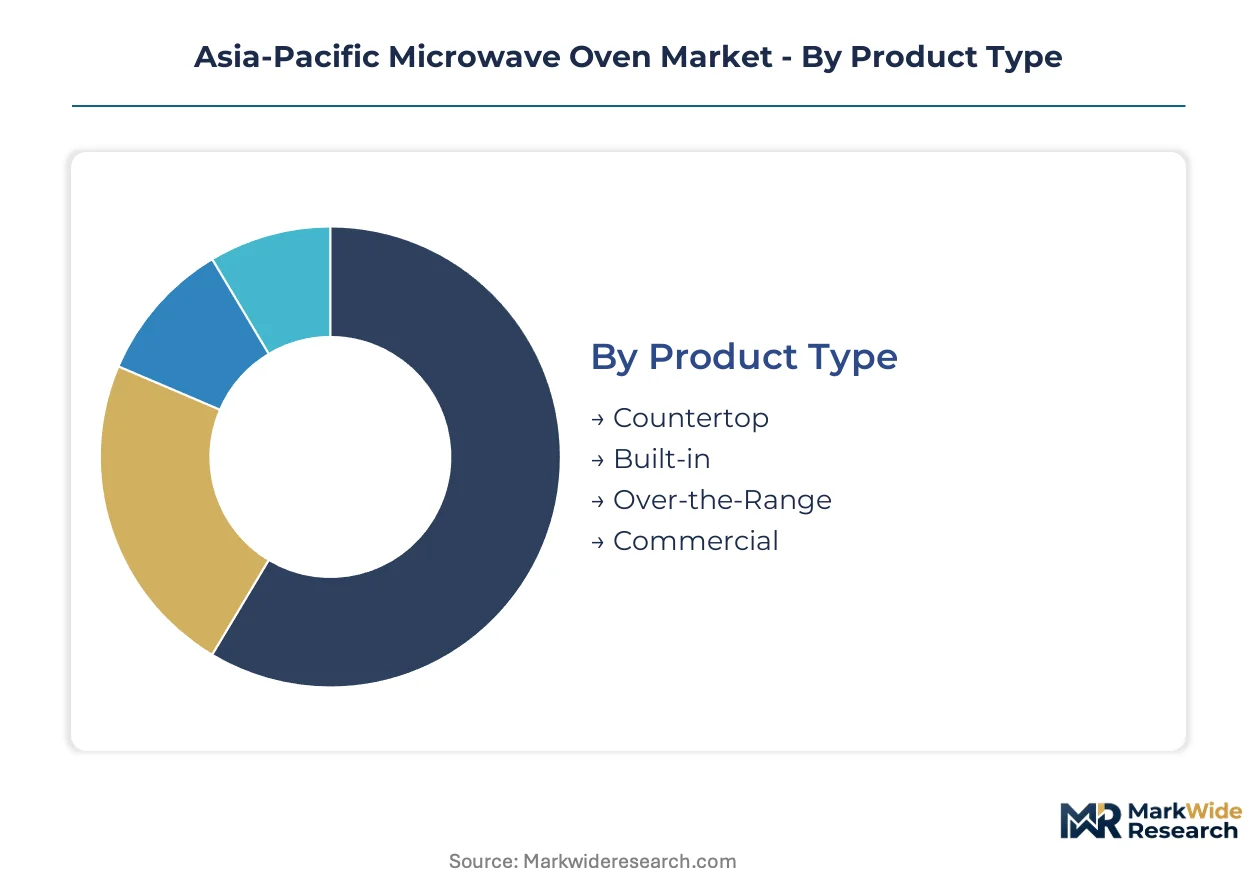
Microwave oven segmentation in the Asia-Pacific region reflects divergent replacement rhythms across product categories. Countertop units turn over every 5-7 years in mass-market households, while built-in configurations align with 12-15 year kitchen renovation cycles in premium residential developments.
Product Type:
Countertop models rotate through homes fastest, driven by price accessibility and portability, whereas built-in and commercial installations lock capital into longer depreciation schedules.
- Countertop:Freestanding units with external power cords dominate first-time purchases across India's tier-two cities and Indonesia's tier-three markets. Compact footprints under 30 liters address space constraints in Bangkok and Ho Chi Minh City apartments where kitchen areas average under 6 square meters.
- Built-in:Cabinet-integrated designs with trim kits command specification channels in Shanghai, Tokyo, and Seoul premium residential projects. METI Top Runner standby power requirements favor semiconductor-controlled inverter architectures in this segment, narrowing the supplier base to manufacturers with captive semiconductor capabilities.
- Over-the-Range:Combined ventilation-cooking units see concentrated demand in Australian and Japanese suburban housing with dedicated range hood infrastructure. Installation complexity limits penetration in Southeast Asian markets lacking standardized cabinet dimensions.
- Commercial:Heavy-duty stainless steel platforms with programmable memory slots serve cloud kitchens and ghost kitchen operators in Singapore and Sydney. Digitized cooking profiles allow menu standardization across distributed foodservice locations.
Countertop anchors the volume base while commercial gains share at the steepest rate.
Feature:
Cost tiers separate basic heating functions from multi-mode platforms, with price gaps widening as semiconductor-controlled precision becomes standard in premium positioning.
- Convection:Forced-air circulation systems with heating elements enable baking and roasting functions previously requiring separate ovens. Demand concentrates among Jakarta, Bangkok, and Manila apartment dwellers consolidating single-purpose appliances into multi-function units.
- Grill:Quartz or sheath heater elements deliver direct radiant heat for browning and crisping. This feature penetrates fastest among 25-40 year-old first-home purchasers in dense urban housing under 60 square meters.
- Sensor Cooking:Humidity and temperature probes with microprocessor-controlled power adjustment automate doneness detection. Seoul, Tokyo, and Shanghai households adopt these models at replacement rates twice those of basic units.
- Standard:Basic magnetron-based heating with mechanical timers and fixed power levels retains dominance in India's rural markets and Indonesia's price-sensitive tier-three cities. BIS energy-efficiency labeling mandates are accelerating replacement cycles in this segment.
Standard configurations retain the largest installed base while convection-grill combinations expand most quickly.
End User:
Application requirements dictate durability specifications and cycle intensity, with foodservice installations operating 10-15 times daily versus household units averaging 2-3 cycles.
- Household:Residential purchasers prioritize compact dimensions and multi-function consolidation in Southeast Asian cities, while Indian and Chinese interior provinces emphasize first-time affordability over feature depth.
- Restaurants:High-throughput establishments in Singapore and Sydney specify programmable commercial platforms with stainless steel cavities and rapid recovery times. Cloud kitchen digitization is opening specification channels bypassing traditional retail.
- Cafes:Beverage-focused operations with limited food preparation require smaller cavity volumes and lower wattage ratings. This segment shows preference for countertop convection units over full commercial platforms.
- Food Service:Institutional catering and centralized kitchen operations in Japan and South Korea demand heavy-duty platforms with certification to national electromagnetic compatibility standards. GB and JIS compliance requirements extend procurement timelines.
Household consumption anchors demand volume while food service applications climb the fastest.
Distribution Channel:
Customer type and purchase urgency shape channel selection, with replacement purchases favoring speed and new installations permitting longer evaluation windows.
- Online:E-commerce platforms capture growing share among urban millennials in Seoul, Tokyo, and Shanghai seeking specification comparison and doorstep delivery. Return logistics complexity limits penetration for built-in models requiring installation coordination.
- Supermarkets:Mass merchandisers with appliance sections serve immediate replacement needs in India's tier-two cities and Indonesia's Surabaya-Bandung corridor. Impulse-compatible price points under $150 dominate this channel.
- Specialty Stores:Kitchen design showrooms and appliance galleries specification-built-in configurations in premium residential developments across Shanghai, Tokyo, and Sydney. Design consultation bundling extends sales cycles.
- Wholesale:Project-based procurement channels serve commercial foodservice and institutional buyers in Singapore and Australia with volume pricing and extended payment terms. Direct manufacturer relationships bypass retail margin stacking.
Supermarkets retain the volume foundation while online channels gain traction at the steepest pace.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export inverter-based microwave platforms to Southeast Asian markets, while Japanese producers ship high-efficiency built-in units to premium residential projects across Australia and South Korea.
China
Guangdong Province hosts the world's largest microwave oven production clusters, with factories in Foshan and Zhongshan supplying countertop units to India's tier-two cities. SAMR enforces GB standards for electromagnetic compatibility that compress launch timelines for regional exporters. The Yangtze River Delta, particularly Shanghai and Suzhou, concentrates R&D facilities developing semiconductor-controlled inverter architectures for METI-compliant export models.
India
BIS compulsory registration for microwave ovens accelerates replacement cycles in Surat, Nagpur, and Lucknow where first-time ownership rates climb fastest. The BIS three-year revision cycle for energy-efficiency thresholds forces portfolio reconfiguration among importers. Maharashtra's Pune-Aurangabad industrial corridor houses assembly operations serving western and southern markets with localized voltage tolerance specifications.
Japan
METI's Top Runner program pushes manufacturers toward sub-one-watt standby power consumption, favoring semiconductor-controlled designs in Tokyo and Osaka premium housing. JIS compliance requirements extend procurement timelines for institutional foodservice buyers. The Kansai region, centered on Osaka and Kyoto, maintains concentrated expertise in RF engineering and electromagnetic compatibility testing.
Australia
Sydney and Melbourne cloud kitchen operators drive commercial microwave specification through programmable cooking profile requirements. TGA-equivalent electrical safety standards align closely with IEC frameworks, smoothing import pathways from Southeast Asian assembly hubs. The Sydney-Canberra corridor hosts ghost kitchen operators digitizing menu standardization across distributed locations.
South Korea
Seoul Capital Area apartment dwellers adopt sensor-equipped replacement models at rates twice those of basic units, compressing the traditional feature hierarchy. MFDS oversight of electromagnetic emissions overlaps with consumer electronics certification, creating streamlined compliance for domestic manufacturers. Busan-Ulsan industrial complexes supply magnetron components to integrated producers serving the premium built-in segment.
Asia-Pacific Microwave Oven Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base stratifies between integrated conglomerates with captive component production and independent assemblers sourcing magnetrons from concentrated supply networks. Three archetypes dominate: semiconductor-integrated manufacturers controlling inverter costs, scale-driven producers operating massive Guangdong facilities, and regional specialists leveraging localized certification expertise. Competitive moves center on backward integration into magnetron production and geographic expansion through Vietnam and India assembly bases.
Among Japan-based electronics conglomerates, Panasonic Corporation and Sharp Corporation occupy positions defined by semiconductor subsidiary control and captive RF engineering expertise. Samsung Electronics anchors the Korea-based tier through integrated supply chains spanning Vietnam and India. Midea Group represents the China-based scale archetype with production concentration in Guangdong Province.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Samsung Electronics |
| LG Electronics |
| Sharp Corporation |
| Midea Group |
| Robert Bosch GmbH |
| Haier Smart Home |
| IFB Industries Ltd |
| Galanz Enterprises |
| Others |
Pricing and Supply Chain Analysis
Guangdong Province's manufacturing clusters in Foshan and Zhongshan anchor regional capacity dynamics, with Midea Group and Galanz Enterprises operating facilities that shape downstream pricing power through captive magnetron production and scale economies. Their dominance in countertop unit supply creates asymmetric leverage over independent assemblers sourcing components from Vietnam and India, compressing margins for non-integrated competitors while sustaining pricing discipline in premium built-in segments.
Pricing Analysis
Inverter-based semiconductor control creates a technology-generation pricing gap that separates current-gen precision models from prior-gen mechanical cycling units and emerging next-gen sensor-automation platforms. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under BIS and GB standards alongside volume scale advantages. Cost compression in entry-level countertop segments is intensifying because unbranded Chinese assemblers face compulsory BIS registration burdens. Tier-two city households in India exhibit highest price sensitivity, while Tokyo and Seoul premium residential projects show lowest sensitivity due to METI Top Runner alignment preferences.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn and BYD Electronics holding substantial appliance assembly capacity across Shenzhen and Zhuhai corridors. Geographic supply concentration centers on China, Vietnam, and India, with magnetron production feeding from Busan-Ulsan industrial complexes in South Korea. Raw material dependencies include cold-rolled steel for cavities, copper windings for transformers, and ferrite cores for magnetrons. Single-source vulnerability concentrates in semiconductor-controlled inverter modules where Panasonic and Samsung maintain captive production. Distribution runs through project-based wholesale channels for commercial foodservice alongside supermarket retail for mass-market countertop replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Built-in induction hobs with integrated warming functions pose a direct substitution threat to microwave attachment rates in premium kitchen renovations across Japan and South Korea, forcing incumbents to articulate distinct value propositions around speed and convenience.
For Market Incumbents: Insulate specification channels in premium residential developments by deepening backward integration into magnetron production and accelerating semiconductor-controlled inverter R&D to meet METI Top Runner sub-one-watt standby requirements. Defend against induction cooktop substitution by bundling sensor-automation features that deliver cooking outcomes unavailable through radiant heat alternatives.
For New Entrants and Emerging Players: Indonesia's tier-three cities including Surabaya, Bandung, and Medan represent the most penetrable entry point, with first-time ownership rates lagging national averages by substantial margins and creating whitespace for basic countertop units with localized voltage tolerance. Cloud kitchen operators in Singapore and Sydney offer specification channels bypassing traditional retail, with programmable cooking profile requirements favoring digitized platform entrants over legacy appliance manufacturers.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because captive component production and multi-jurisdiction certification expertise are concentrating competitive advantage among integrated conglomerates while squeezing independent assemblers. Target manufacturers with established BIS, GB, and JIS compliance capabilities and existing Vietnam or India assembly footprints. Monitor BIS three-year revision cycles for energy-efficiency threshold escalations as inflection indicators for replacement demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetron Production | Captive supply of critical RF components reduces dependency on Busan-Ulsan suppliers and protects margin structure. |
| Multi-Jurisdiction Certification Investment | Simultaneous BIS, GB, and JIS compliance compresses launch timelines and unlocks pan-Asia portfolio strategies. |
| Commercial Foodservice Specification Channel | Direct relationships with Singapore and Sydney cloud kitchen operators bypass retail margin stacking and enable programmable profile monetization. |
| Semiconductor-Controlled Inverter R&D | METI Top Runner alignment rewards sub-one-watt standby achievement with premium positioning in Tokyo and Osaka housing. |
| Indonesia Tier-Three City Distribution Buildout | Localized voltage tolerance specifications address Surabaya-Bandung-Medan whitespace where first-time ownership rates trail national benchmarks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with microwave oven product managers, RF engineering specialists, BIS certification consultants, and commercial foodservice procurement officers; and secondary validation through SAMR GB standard filings, BIS compulsory registration databases, METI Top Runner program disclosures, and customs trade records. Bottom-up unit shipment modeling triangulated against top-down value estimates derived from manufacturer revenue disclosures and channel partner margin structures.
Forecast inputs included product type segmentation across countertop, built-in, over-the-range, and commercial configurations; feature tier differentiation between standard magnetron and inverter-based platforms; and end-user demand patterns spanning household replacement cycles and foodservice digitization trends. CAGRs were derived from fitted growth curves applied to historical shipment trajectories, adjusted for regulatory phase-in schedules and urban household formation projections across the analysis window.
Macroeconomic conditions sit as an overlay; deviation in regional construction activity, consumer durable spending indices, or raw material input costs would shift the trajectory. Forecasts reflect documented assumptions regarding BIS revision cycle timing and METI efficiency threshold stringency. Quarterly review of cloud kitchen operator expansion rates and tier-two city appliance penetration metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
France Household Side by Side Refrigerator Market
Appliances
Egypt Dishwashers Market
Appliances
Global Electric Water Heaters Market
Appliances
Colombia Laundry Appliances Market
Appliances
Saudi Arabia Microwave Ovens Market
Appliances
Electric Rice Cooker Market
Appliances
Middle East and Africa Commercial Dishwashers Market
Appliances
Electric Dryers Market
Appliances
Electric Yogurt Maker Market
Appliances
Asia Pacific Water Heater Market
Appliances
GCC Microwave Oven Market
Appliances
US Electric Rice Cooker Market
Appliances
Smart Dishwasher Market
Appliances
GCC Dishwashers Market
Appliances
United States Commercial Laundry Appliances Market
Appliances
Refrigerator Repair Service Market