
 Electric Yogurt Maker Market | 2026-2036
Electric Yogurt Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Yogurt Maker Market Foresight
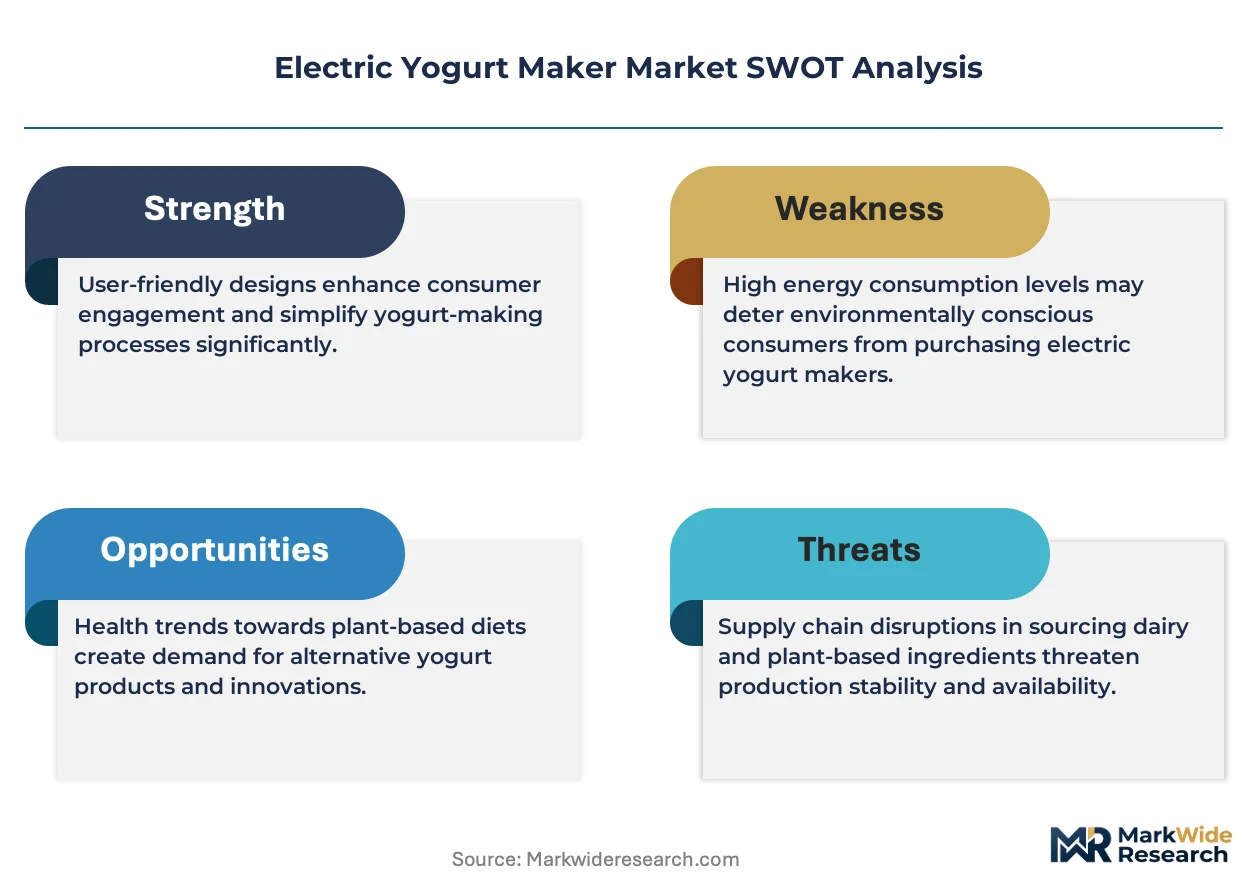
Online direct-to-consumer channels is fragmenting as specialty kitchen brands and mass-market retailers launch competing storefronts. Euro-Cuisine leverages its European heritage to anchor premium positioning in artisanal fermentation circles. Joyoung competes aggressively on programmable technology and price accessibility across Asian markets. Cuisinart sustains broad retail shelf presence through established relationships with big-box chains and culinary specialty stores.
An electric yogurt maker is a thermostatically controlled countertop appliance that maintains milk cultures at precise temperatures between 110°F and 115°F for sustained fermentation periods, producing consistent curd formation without manual monitoring. The device serves both household consumers seeking probiotic food autonomy and commercial kitchens requiring batch reliability. Automatic models with digital display technology capture the fastest growth trajectory as programmable settings reduce user error and expand demographic reach. Small capacity units dominate household penetration, while medium capacity variants command margin pools in café and health food store segments where batch frequency matters more than volume per cycle.
FDA food contact substance regulations govern plastic component safety in US-manufactured and imported units, while EU REACH compliance restricts certain phthalates in heating element housings sold across European markets. Ecodesign requirements under the EU framework mandate standby power thresholds that reshape internal component sourcing and R&D allocation. Stakeholders must track evolving appliance efficiency standards and probiotic health claim regulations to anticipate which feature sets will unlock market access in priority geographies.
Market Dynamics
The EU Ecodesign Directive is compressing standby power allowances for countertop appliances, forcing manufacturers to redesign heating elements and control boards while health food retailers expand fermentation appliance shelves to capture gut wellness spending.
Growth Catalysts
- REACH compliance in plastic housings:European phthalate restrictions are accelerating migration to glass and stainless steel fermentation vessels, opening premium material tiers.
- Programmable temperature control:Digital thermostats with 0.5°F precision are expanding demographic reach beyond hobbyists to time-constrained households.
- German artisanal dairy culture:Bavarian and Baden-Württemberg consumers maintain homemade yogurt traditions that sustain replacement demand for durable units.
Market Restraints
- Heating element supply concentration:Ceramic PTC thermistor production clusters in Guangdong province, creating single-source vulnerability for mid-tier assemblers.
- Copper and nickel price volatility:Wiring harness and resistor costs fluctuate with London Metal Exchange spot pricing, compressing margin on entry-level SKUs.
- Refrigerated ready-to-eat yogurt substitution:Chilled probiotic brands with live culture guarantees capture convenience-oriented buyers who abandon home fermentation.
Strategic Opportunities
- India FSSAI probiotic health claim pathway:Draft regulations recognizing live culture benefits would unlock institutional kitchen demand in Mumbai and Bangalore hospitality clusters.
- IoT-enabled fermentation logging:Bluetooth-enabled units syncing with nutrition apps are creating subscription revenue potential beyond hardware sales.
- Direct-to-consumer specialty channels:Microbiome wellness platforms and fermentation education sites are opening bypass routes around mass retail slotting fees.
Industry Challenges
- FDA food contact substance notification timelines:New polymer approvals for fermentation vessel liners require 120-day review cycles that delay product launches.
- Thermal engineer talent scarcity:Precision thermostat calibration expertise concentrates in appliance manufacturers with HVAC heritage, limiting new entrant R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Yogurt Maker Market |
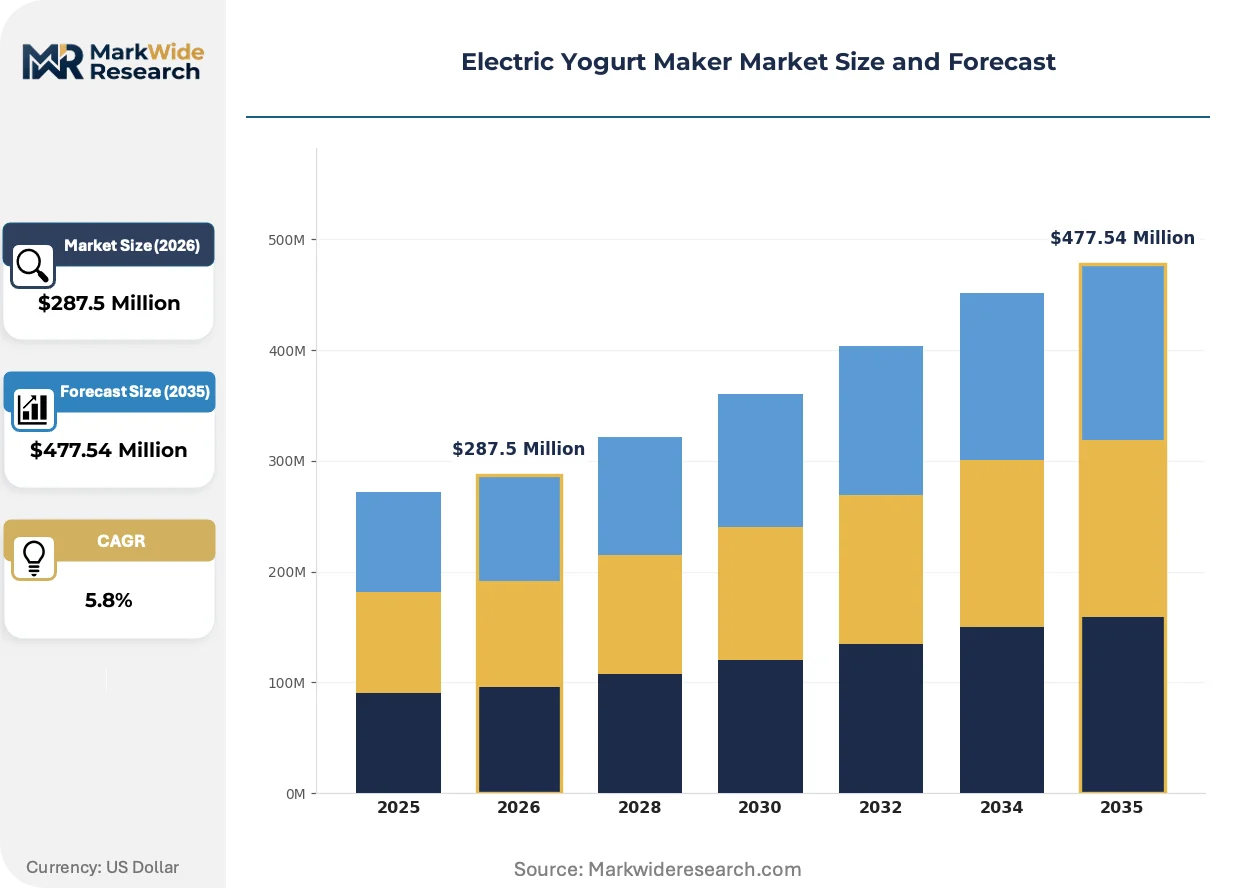
| Market Size in 2026 | $287.5 Million |
| Market Size in 2035 | $477.54 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Models, Automatic Models, Multi-Function Models, Portable Models End User: Households, Restaurants, Cafés, Health Food Stores Capacity: Small Capacity, Medium Capacity, Large Capacity, Extra-Large Capacity Technology: Thermal Control, Digital Display, Programmable Settings, Rapid Cooling |
| Companies Covered | Euro-Cuisine, Gourmia, Instant Brands, Cuisinart, Ningbo Hippo Electrical Appliance, Iris Ohyama, SEVERIN, WMF, Joyoung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Yogurt Maker Market Shifts & Advancements
Digital fermentation control systems are compressing the skill barrier that once limited homemade yogurt to dedicated enthusiasts, while regulatory energy thresholds and shifting retail access reshape competitive entry points.
Precision PID temperature controllers are collapsing the failure rate differential between novice and experienced users. Home cooks with no fermentation background now achieve batch consistency comparable to commercial kitchens. This technology compression is eroding the traditional advantage of premium brands that built loyalty on reliability promises.
EU Ecodesign standby power mandates are forcing component redesigns across the supplier base. Manufacturers must source sub-0.5W standby controllers or forfeit CE marking access. German and French importers are consolidating supplier relationships with firms that pre-certify compliance, squeezing smaller assemblers from distribution pipelines.
Health food store buyers are consolidating shelf space around fermentation appliances with visible probiotic education content. Packaging that explains live culture counts and strain benefits now determines placement priority over price positioning. This preference compression favors suppliers with registered dietitian partnerships and microbiome research backing, particularly in California and Pacific Northwest retail clusters.
Electric Yogurt Maker Market Segmentation
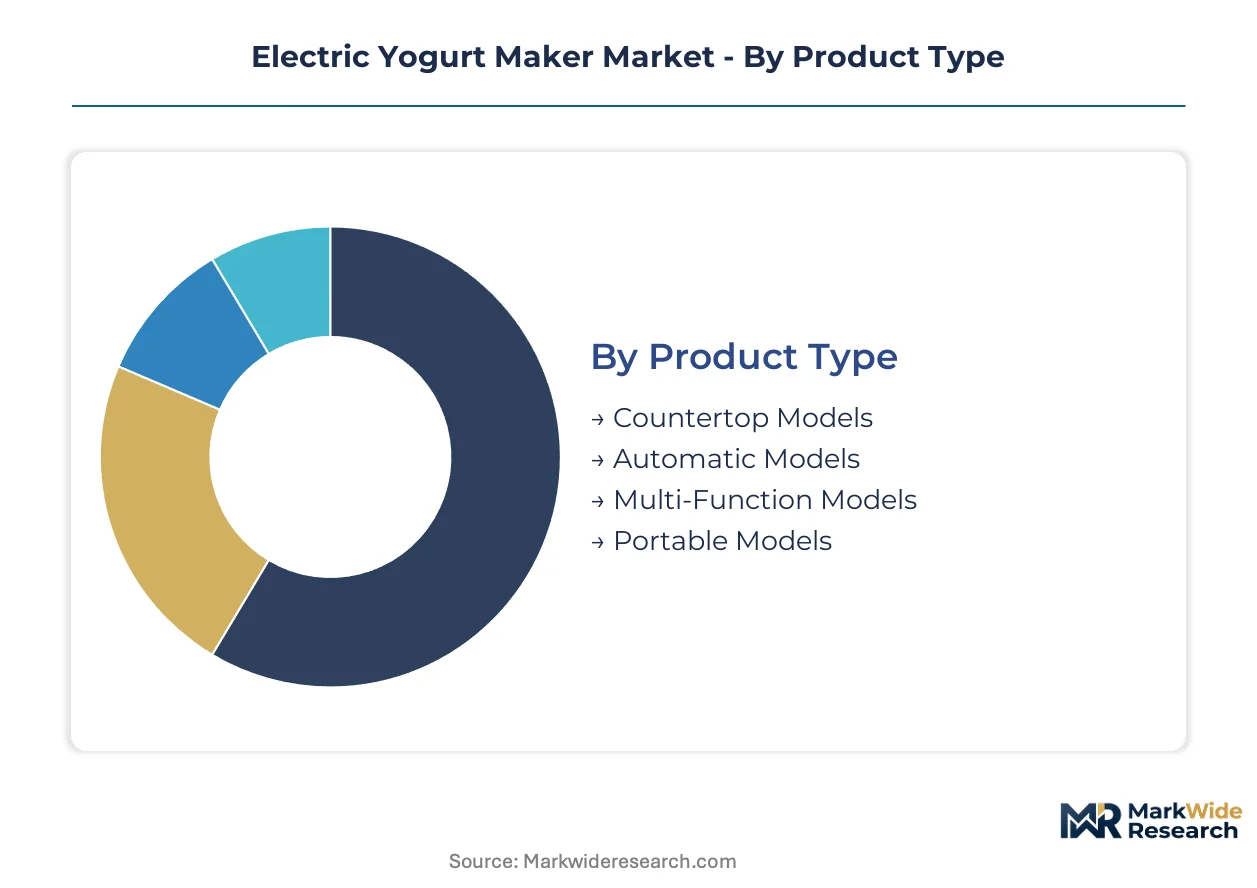
Electric yogurt maker segmentation reveals how fermentation technology stratifies across user sophistication, operational scale, and interface complexity. Manufacturers configure component stacks and price architecture around these divides.
Product Type:
Cost tier differentiation separates entry-level mechanical units from sensor-rich automatic systems with precision thermostats.
- Countertop Models:Basic thermostatic housings with analog dials dominate German and Austrian retail where artisanal dairy tradition sustains demand for simple, durable mechanics. Health food stores in Bavaria stock these units for consumers prioritizing reliability over digital features.
- Automatic Models:PID-controlled fermentation chambers with LCD feedback and timer automation are climbing fastest in Asian urban households where time-constrained professionals seek probiotic autonomy without monitoring. Programmable presets for Greek, Bulgarian, and Icelandic yogurt styles expand demographic reach beyond hobbyists.
- Multi-Function Models:Modular bases accepting fermentation jars, cheese presses, and kefir attachments serve specialty kitchen enthusiasts in California wellness clusters.
- Portable Models:Battery-operated units with insulated chambers target RV owners and remote workers in Australian and Canadian outdoor recreation markets.
Automatic Models hold installed capacity. Multi-Function Models are rotating up the share rankings.
End User:
Application context determines batch frequency requirements, durability specifications, and regulatory exposure for each buyer category.
- Households:Single and dual-jar units with dishwasher-safe glass vessels dominate residential penetration. German consumers in Baden-Württemberg maintain replacement cycles tied to energy efficiency upgrades under EU Ecodesign thresholds.
- Restaurants:NSF-certified stainless steel housings with HACCP documentation support commercial kitchen compliance. Mumbai and Bangalore hospitality clusters source medium-capacity units for breakfast service automation.
- Cafés:Front-of-house fermentation displays with transparent chambers serve probiotic education and experiential retail in Pacific Northwest urban markets.
- Health Food Stores:Demo units with strain-specific culture kits and microbiome education collateral anchor gut wellness merchandising in California retail clusters.
Households hold installed capacity. Health Food Stores are rotating up the share rankings.
Capacity:
Volume tiering aligns with usage intensity, space constraints, and per-batch labor economics across consumer and commercial contexts.
- Small Capacity:One to two quart vessels serve single-person households and trial users in Japanese urban apartments where counter space is severely constrained.
- Medium Capacity:Four to six quart chambers with dual-zone temperature control capture café and health food store segments where batch frequency matters more than volume per cycle. These units command margin pools through programmable reliability.
- Large Capacity:Eight to twelve quart systems with reinforced heating elements serve restaurant prep kitchens in German gastronomy clusters requiring consistent curd for sauce bases and marinades.
- Extra-Large Capacity:Fifteen-plus quart commercial chambers with stainless steel construction and ETL certification support institutional food service in Indian educational and corporate catering facilities.
Small Capacity holds installed capacity. Medium Capacity is rotating up the share rankings.
Technology:
Interface sophistication and thermal management precision create distinct user experience tiers with diverging R&D allocation requirements.
- Thermal Control:Bimetallic strip thermostats with ±2°F variance serve price-sensitive segments in emerging markets where basic fermentation functionality suffices.
- Digital Display:LCD temperature readouts with countdown timers are climbing fastest in European markets where CE marking and standby power compliance concentrate supplier relationships. German importers consolidate procurement around pre-certified controller boards.
- Programmable Settings:Microprocessor-driven profiles for yogurt type, firmness, and fermentation duration expand demographic reach to novice users. Bluetooth-enabled variants sync with nutrition apps for subscription revenue potential.
- Rapid Cooling:Thermoelectric cooling modules transitioning from fermentation to refrigeration phase reduce spoilage risk in warm climates. These systems target Indian and Southeast Asian households with intermittent power reliability.
Thermal Control holds installed capacity. Digital Display is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Ecodesign Directive mandates anchor European market structure, while German energy efficiency standards and artisanal dairy traditions concentrate demand in Bavaria and Baden-Württemberg. The report maps five national markets where regulatory frameworks and consumption patterns diverge sharply.
Germany
Artisanal dairy culture in Bavaria sustains replacement demand for durable mechanical units, while Baden-Württemberg consumers prioritize EU Ecodesign standby power compliance in upgrade cycles. German importers consolidate procurement relationships with pre-certified controller board suppliers. Stuttgart and Munich retail clusters stock fermentation appliances with visible energy efficiency labeling.
United States
FDA food contact substance regulations govern plastic component safety for countertop fermentation appliances sold through health food retail channels. California and Pacific Northwest wellness clusters drive demand for probiotic education content on packaging. Los Angeles and Seattle health food stores prioritize placement for units with registered dietitian partnerships.
India
FSSAI draft regulations on probiotic health claims would unlock institutional kitchen demand in Mumbai and Bangalore hospitality clusters. Medium-capacity units serve breakfast service automation in commercial kitchens. Copper and nickel price volatility from London Metal Exchange spot pricing compresses margins on entry-level SKUs assembled in Gujarat and Maharashtra manufacturing zones.
Japan
METI appliance efficiency standards and severe urban counter space constraints in Tokyo and Osaka sustain demand for small-capacity one-quart vessels. Japanese consumers prioritize programmable precision over mechanical simplicity. Kanto region retail clusters stock automatic models with LCD temperature readouts and countdown timer automation.
China
MIIT electronics manufacturing standards and Guangdong province ceramic PTC thermistor production concentration create supply chain leverage for mid-tier assemblers. Joyoung competes aggressively on programmable technology and price accessibility across domestic urban markets. Shenzhen and Shanghai households drive fastest adoption of Bluetooth-enabled units syncing with nutrition applications.
Electric Yogurt Maker Market Competitive Landscape
Heritage European kitchen brands and Asian programmable technology specialists split the market along premium-mechanical versus digital-automation fault lines. The vendor base concentrates around three strategic archetypes: established culinary appliance houses with retail shelf dominance, Asian electronics manufacturers with cost-engineered programmable systems, and specialty fermentation-focused microbrands with direct-to-consumer education platforms. Competitive moves center on supplier consolidation around pre-certified EU Ecodesign component boards and bypass route development around mass retail slotting fees through microbiome wellness platforms.
Within the heritage European tier, Euro-Cuisine anchors artisanal fermentation positioning through European provenance signaling, while SEVERIN and WMF occupy positions in precision-engineered small appliance segments. Among Asian programmable specialists, Joyoung exemplifies aggressive technology and price accessibility strategies across domestic and export markets. Cuisinart represents established culinary brand leverage through big-box and specialty retail channel relationships. These three archetypes—heritage European, Asian programmable, and mass retail culinary—structure competitive maneuvering across regulatory and channel access dimensions.
| Leading Market Players |
|---|
| Euro-Cuisine |
| Gourmia |
| Instant Brands |
| Cuisinart |
| Ningbo Hippo Electrical Appliance |
| Iris Ohyama |
| SEVERIN |
| WMF |
| Joyoung |
| Others |
Supply & Pricing Matrix
The Shenzhen-Rotterdam maritime corridor carries ceramic PTC thermistors and controller boards that feed German precision-engineering clusters, where freight cost volatility amplifies the spread between mass-market Asian assemblers and EU-certified premium suppliers. This logistics artery concentrates supply risk while enabling stark price differentiation across certification tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order units with programmable fermentation profiles from standard mechanical models. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Price differentiation hinges on CE marking pre-certification and registered dietitian partnership content. Cost compression in entry-level SKUs is intensifying because copper and nickel spot volatility from London Metal Exchange pricing compresses wiring harness margins. Household buyers in Japanese urban apartments exhibit highest price sensitivity; German Baden-Württemberg consumers upgrading under Ecodesign thresholds show lowest.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk for mid-tier assemblers dependent on Guangdong province ceramic PTC thermistor output. Component sourcing centers on China for controller boards, Germany for precision thermostat calibration expertise, and Vietnam for secondary plastic housing assembly. Raw material dependencies span copper wiring, nickel resistors, and food-grade polymer liners. Single-source vulnerability concentrates in Guangdong heating element production. Distribution runs through health food retail consolidation in California and Pacific Northwest clusters, mass-market big-box chains in North America, and direct-to-consumer microbiome wellness platforms bypassing slotting fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision thermal engineering talent scarcity constrains new entrant R&D velocity and consolidates advantage around incumbent manufacturers with HVAC heritage. This capability gap shapes competitive maneuvering across the forecast horizon.
For Market Incumbents: Build certification moats around pre-certified EU Ecodesign controller boards that squeeze smaller assemblers from German and French distribution pipelines. Deepen supplier consolidation with Guangdong ceramic PTC thermistor producers to lock in heating element allocation. Defend against Joyoung's programmable technology aggression by anchoring artisanal heritage positioning in Bavarian retail clusters. For New Entrants and Emerging Players: Pursue white-space penetration in Indian institutional kitchens awaiting FSSAI probiotic health claim finalization, where medium-capacity NSF-certified units serve Mumbai and Bangalore hospitality automation. Target Pacific Northwest health food store demo placement with visible microbiome education collateral. Lead with Bluetooth-enabled fermentation logging that syncs with nutrition apps for subscription revenue attachment. For Investors and Strategic Acquirers: Specialty fermentation-focused microbrands with direct-to-consumer education platforms and registered dietitian partnerships represent the priority acquisition archetype. Long-term viability favors suppliers with microbiome research backing and bypass route development around mass retail slotting fees. Watch FDA food contact substance notification timelines as inflection signal—120-day review cycles that delay polymer liner launches will consolidate advantage around pre-approved component inventories.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pre-Certification | Pre-certified controller boards unlock German and French distribution pipeline access under Ecodesign standby power mandates. |
| IoT Platform Integration | Bluetooth-enabled fermentation logging syncs with nutrition apps, creating subscription revenue beyond hardware sales. |
| Registered Dietitian Partnership | Microbiome research backing determines health food store shelf placement priority in California wellness clusters. |
| Direct-to-Consumer Launch | Microbiome wellness platforms bypass mass retail slotting fees and anchor gut wellness merchandising. |
| Backward Integration into Heating Elements | Captive supply of Guangdong ceramic PTC thermistors mitigates single-source vulnerability for mid-tier assemblers. |
Research Methodology
Cross-validation between primary interviews with appliance R&D directors, health food store category buyers, thermal engineering specialists, and commercial kitchen procurement managers and secondary validation from FDA food contact substance filings, EU Ecodesign directive documentation, and London Metal Exchange copper pricing data anchors the qualitative findings. Bottom-up demand modeling from household penetration rates and top-down market sizing from customs trade flows triangulate volume estimates.
Calibration against historical appliance adoption curves and energy efficiency upgrade cycles shapes the analytical framework across the projection horizon. Segmentation dimensions span product type, end user, capacity tier, and technology interface sophistication. CAGR derivation incorporates probiotic health claim regulatory progression, copper and nickel commodity volatility, and retail channel consolidation patterns.
Macroeconomic conditions sit as an overlay; deviation in freight rates along Asia-Europe maritime corridors and London Metal Exchange spot pricing would shift the trajectory. Forecasts reflect assumptions around FSSAI draft regulation finalization and EU Ecodesign standby power threshold enforcement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Domestic Food Preparation Appliances Market
Appliances
Europe Household Electric Grills Market
Appliances
Japan Massage Equipment Market
Appliances
Garments Steamer Market
Appliances
Automatic Dishwasher Market
Appliances
Electric Dryers Market
Appliances
Asia Pacific Compact Dishwasher Market
Appliances
Laundry Appliances Market
Appliances
France Household Side by Side Refrigerator Market
Appliances
Global Vended Laundry Equipment Market
Appliances
Europe Garment Steamers Market
Appliances
Gas Ranges Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
Under Counter Dishwasher Market
Appliances
Egypt Dishwashers Market
Appliances
Israel Laundry Appliances Market