
 Global Home Ice Maker Market | 2026-2036
Global Home Ice Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home Ice Maker Market Analysis
A shortage of certified refrigeration technicians is collapsing service-network expansion for aftermarket support, forcing manufacturers to rethink distribution models. Hoshizaki Corporation leverages its captive technician-training infrastructure to sustain premium-channel loyalty across Japanese and North American markets. Scotsman Industries, Inc. anchors its competitive stance through deep specialization in nugget-ice architectures that dominate residential beverage-prep segments. NewAir competes aggressively on direct-to-consumer pricing, while Changshu Lingke Electric Appliance Co., Ltd. dominates cost-engineered portable units through Shenzhen-adjacent manufacturing clusters.
Global home ice makers comprise self-contained refrigeration appliances designed to produce, store, and dispense ice cubes or specialized ice forms for domestic and light-commercial use, typically operating through vapor-compression cycles with refrigerants such as R-600a or R-134a and rated between 100 and 300 watts. These units serve primary functions in residential kitchens, home bars, and outdoor entertainment spaces where continuous ice availability supersedes conventional freezer-tray methods. Countertop configurations currently occupy the largest installed base due to zero-installation requirements and apartment-friendly footprints, while built-in segments command superior margin pools as they integrate with custom cabinetry workflows. Energy-efficient technology variants are gaining fastest traction as electricity tariffs escalate in key markets, though compressor-based systems still lead absolute volume due to proven reliability in high-ambient-temperature operation.
EPA refrigerant-phaseout timelines under SNAP regulations are compelling redesigns toward lower-GWP alternatives, while CE marking requirements under EU F-Gas Regulation constrain market access for non-compliant imports into European member states. China's GB standards for household refrigerating appliances enforce minimum energy-performance thresholds that filter out under-engineered competitors. FDA food-contact surface regulations apply indirectly through material-safety expectations for ice-storage zones. Stakeholders must monitor evolving refrigerant-policy convergence across Washington, Brussels, and Beijing to anticipate compliance-cost trajectories and retooling cycles.
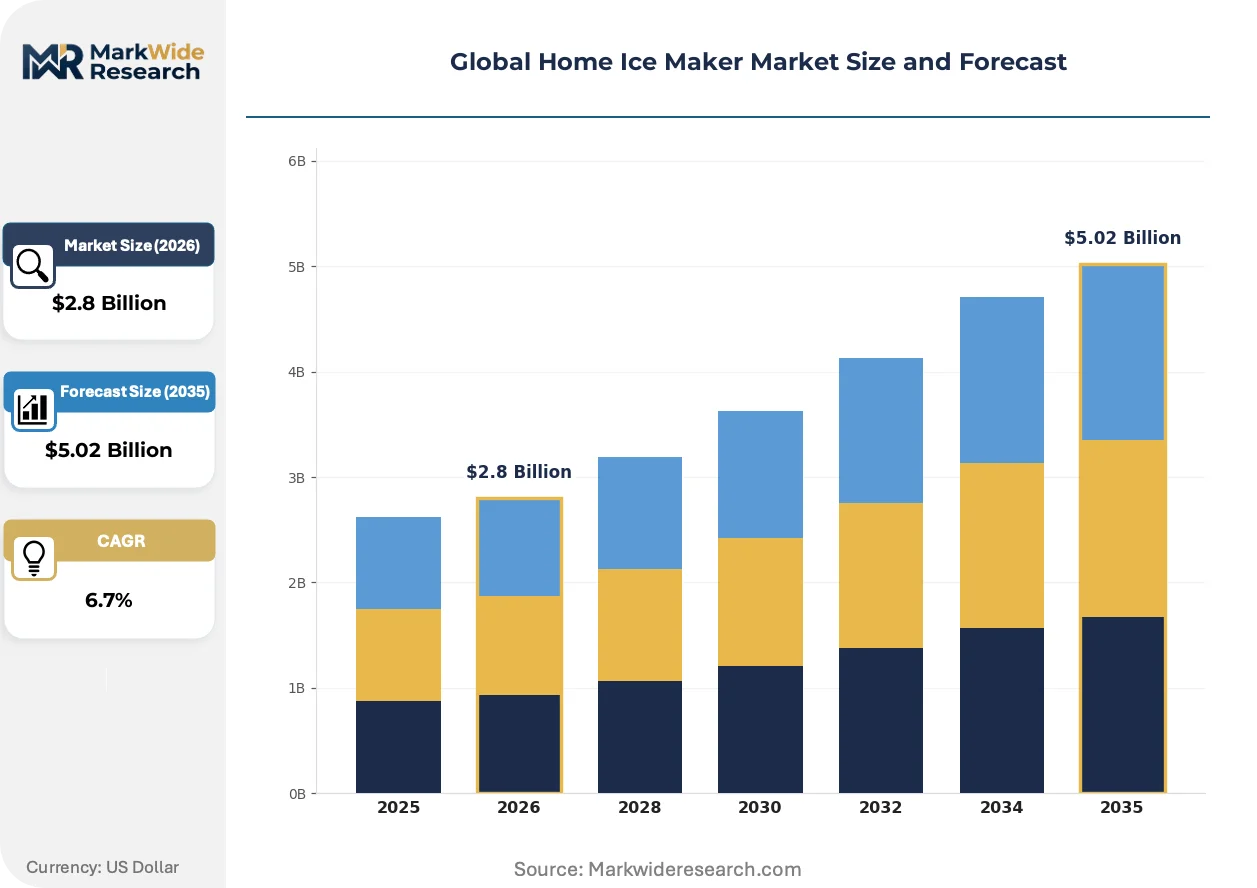
Market Dynamics
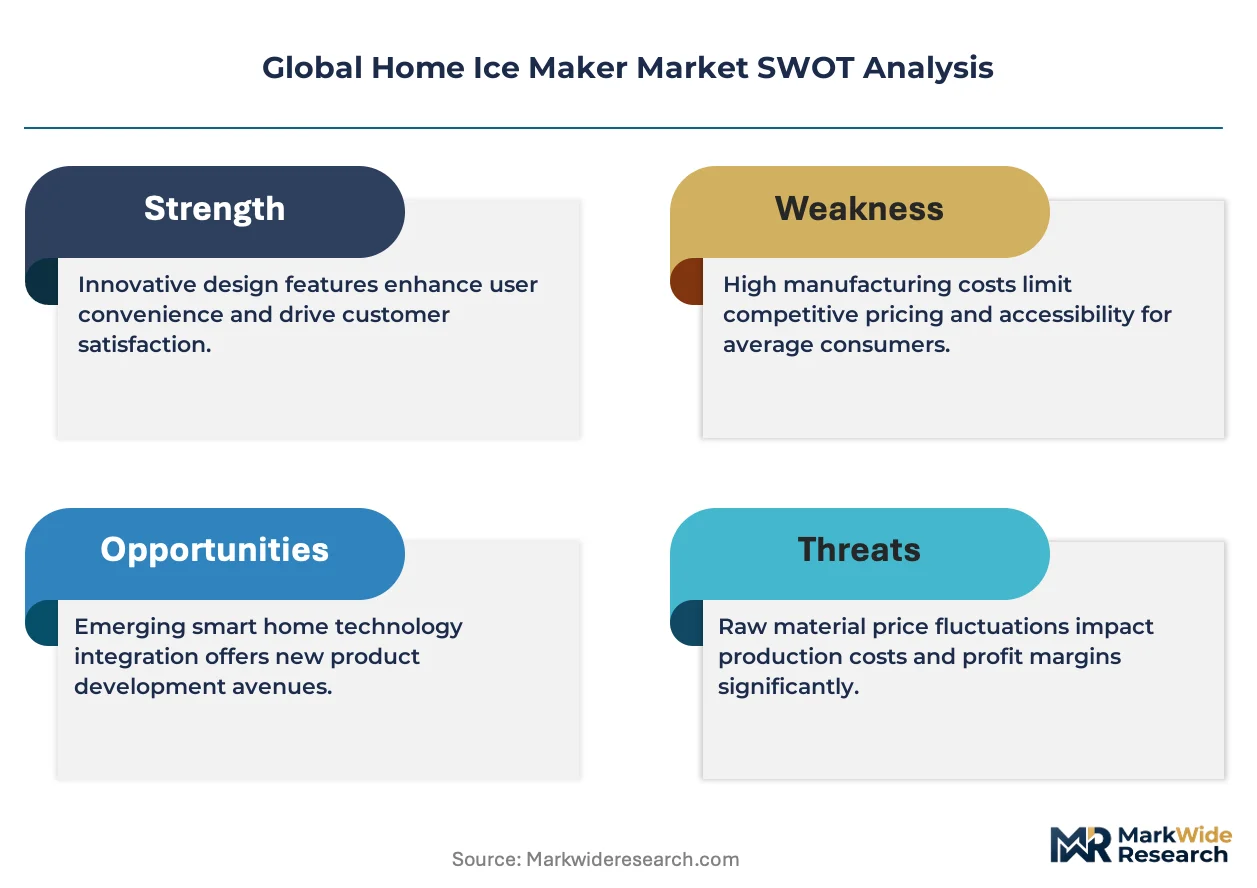
Refrigerant-phaseout mandates under EPA SNAP rules are compressing product redesign cycles while simultaneously fragmenting supplier bases as smaller manufacturers lack capital for compliance retooling.
Growth Catalysts
- Outdoor Entertainment Culture:Sun Belt states in the United States sustain year-round ice consumption for residential patios and poolside kitchens, creating durable replacement demand independent of seasonal fluctuations.
- EU F-Gas Regulation:CE marking requirements for lower-GWP refrigerants are accelerating R-600a adoption across European imports, rewarding early-compliant manufacturers with preferential market access.
- Countertop Zero-Installation Designs:Apartment-friendly footprints eliminate plumbing requirements, unlocking penetration in dense urban housing stock where built-in appliances face retrofit barriers.
Market Restraints
- Copper and Aluminum Input Volatility:Compressor housings and heat exchanger coils expose margins to London Metal Exchange price swings that manufacturers cannot fully pass through in mass-market segments.
- Technician Certification Bottlenecks:EPA Section 608 certification requirements for handling refrigerants restrict service-network expansion, particularly in secondary US metropolitan areas where training infrastructure remains thin.
- Freezer-Tray Substitution:Zero-cost alternatives in price-sensitive consumer segments cap willingness-to-pay for standalone ice production appliances during economic softness.
Strategic Opportunities
- India Urban Middle-Class Expansion:Rising disposable incomes in Mumbai and Bangalore metro corridors create first-time appliance purchase potential for compact countertop configurations.
- China Dual Carbon Goals:MIIT efficiency mandates and provincial green-consumption subsidies favor inverter-compressor variants that command premium positioning versus conventional fixed-speed units.
- Voice-Integration Convergence:Smart-home protocol compatibility with Amazon Alexa and Google Home ecosystems opens incremental channel placement through electronics retailers.
Industry Challenges
- Refrigerant Transition Capex Burden:Retooling production lines for R-290 and R-600a flammability-compliant manufacturing consumes capital that mid-tier competitors struggle to access.
- Cross-Border Certification Fragmentation:Divergent testing protocols between EPA SNAP, EU F-Gas, and China GB standards force parallel compliance investments without harmonized mutual recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home Ice Maker Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Built-In, Free-Standing, Portable Technology: Compressor, Rapid Ice, Energy Efficient, Traditional End User: Residential, Hospitality, Commercial, Catering Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Hoshizaki Corporation, The Manitowoc Company, Inc., Scotsman Industries, Inc., Whynter LLC, Ice-O-Matic, MaxxIce, NewAir, Sunpentown (SPT) Inc., Changshu Lingke Electric Appliance Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home Ice Maker Market Emerging Trajectories
Product architectures are pivoting around thermal efficiency and connected functionality as baseline expectations shift from simple ice production toward integrated kitchen-system compatibility.
Thermoelectric cooling modules are supplanting conventional compressor systems in sub-50-pound portable segments where noise suppression and vibration elimination outweigh production-speed priorities. RV owners and boat operators prioritize silent operation over daily output volume. This substitution pattern is compressing addressable market scope for traditional compressor manufacturers in the lightweight category.
EPA SNAP regulations governing hydrofluorocarbon phaseout timelines are mandating refrigerant transitions toward R-600a and R-290 alternatives with substantially lower global warming potential. Manufacturers face compressed redesign windows as 2025-2026 compliance deadlines approach for specific appliance categories. Built-in undercounter segments face the steepest retooling costs due to confined-space flammability-safety engineering requirements.
Direct-to-consumer channel migration is fragmenting traditional appliance-retailer relationships as Amazon and manufacturer-owned storefronts capture growing share of replacement purchases. Big-box kitchen specialists lose traffic to online comparison shopping for standardized countertop configurations. This displacement concentrates most acutely in United States suburban markets where delivery logistics infrastructure supports next-day fulfillment expectations.
Global Home Ice Maker Market Segmentation
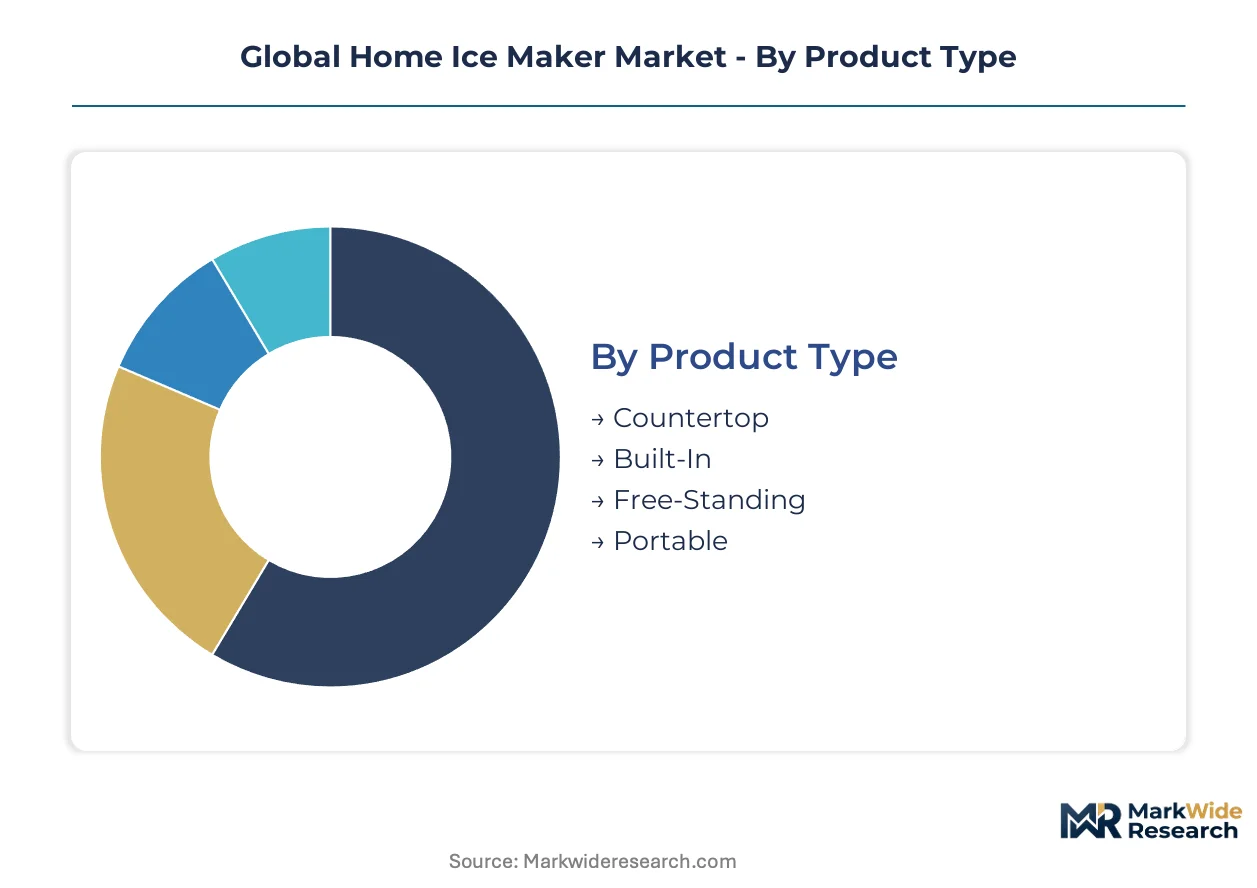
Segmentation reveals how ice maker architectures align with distinct installation constraints, energy priorities, and channel economics across domestic and export markets. Product configuration and technology choices determine whether manufacturers compete on upfront accessibility or long-term integration value.
Product Type:
Countertop units dominate domestic consumption in apartment-dense US coastal cities and European capitals where permanent installation faces landlord restrictions. Built-in and free-standing variants concentrate in export flows toward Middle Eastern villa markets and Southeast Asian hospitality fit-outs.
- Countertop:Self-contained units requiring zero plumbing connections operate through gravity-fed water reservoirs and external drainage. Demand clusters in US urban rental markets and Japanese compact housing where kitchen square footage commands premium valuations. Zero-installation portability sustains replacement cycles independent of property ownership transitions.
- Built-In:Undercounter appliances integrate with custom cabinetry through front-venting compressor architectures and dedicated water-line connections. US Sun Belt outdoor kitchen renovations and German basement bar conversions anchor volume, with margins compressing less severely than portable categories due to contractor-specified procurement.
- Free-Standing:Full-height units with integrated storage bins serve high-volume residential and light-commercial applications where daily output exceeds 50 pounds.
- Portable:Lightweight thermoelectric or small-compressor designs target RV, marine, and camping segments prioritizing mobility over production speed.
Countertop commands the established base. The steepest expansion runs through built-in configurations.
Technology:
Cost-tier stratification separates mass-market compressor dominance from premium rapid-cycling and inverter-based efficiency variants. Technology selection directly determines regulatory compliance pathways across EPA SNAP, EU F-Gas, and China GB jurisdictions.
- Compressor:Vapor-compression systems using R-600a or R-290 refrigerants deliver proven reliability in ambient temperatures exceeding 35°C. US southern states and Gulf Cooperation Council countries sustain volume despite phaseout-driven retooling costs.
- Energy Efficient:Inverter-driven variable-speed compressors and enhanced insulation packages reduce per-cycle consumption by 20-30% versus fixed-speed equivalents. China's MIIT efficiency labeling and provincial subsidy programs accelerate penetration in tier-one cities.
- Rapid Ice:Accelerated freezing cycles through enhanced heat exchanger surface area and boosted compressor duty cycles target hospitality prep environments.
- Traditional:Fixed-speed compressor architectures with conventional refrigerants face narrowing addressable markets as regulatory deadlines approach.
Compressor technology anchors current installed capacity. Inverter-based efficiency variants are climbing the fastest as electricity tariffs escalate and subsidy eligibility tightens.
End User:
Application context dictates performance specifications, with residential volume concentrating in replacement cycles and hospitality demand tied to new construction and renovation timelines.
- Residential:Home kitchen, bar, and outdoor entertainment installations prioritize noise suppression, aesthetic integration, and moderate daily output. US suburban households and EU single-family renovations sustain the core revenue pool.
- Hospitality:Boutique hotels and vacation rental operators specify undercounter units for guest-facing beverage stations where ice quality affects review scores.
- Commercial:Small restaurants and cafes utilize compact units for front-of-house service where full-scale industrial installations prove oversized.
- Catering:Mobile event operators demand portable, generator-compatible configurations for off-grid deployment.
Residential segments anchor manufacturer revenue stability. Hospitality procurement is expanding most quickly as short-term rental platform growth drives amenity investment.
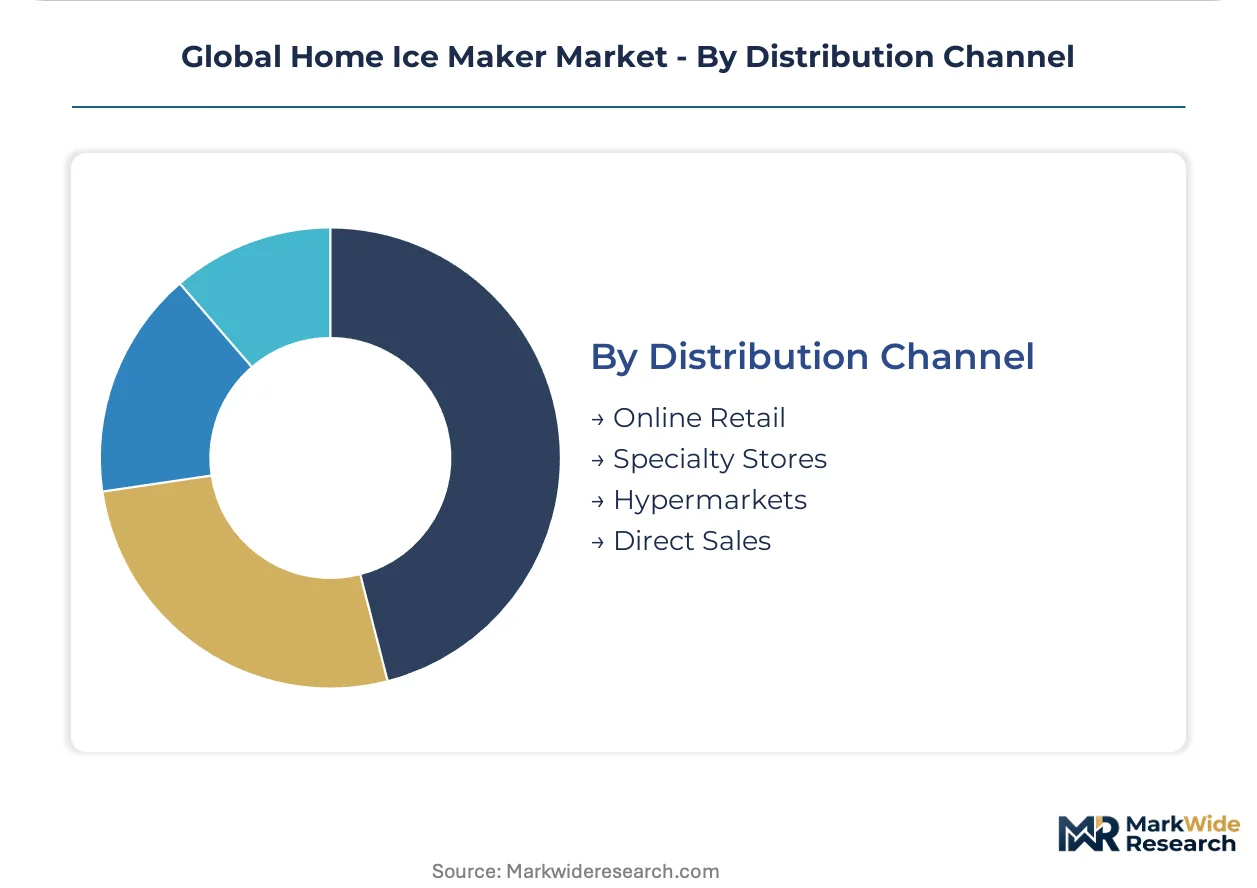
Distribution Channel:
Channel selection reflects customer journey fragmentation, with digital capture accelerating in standardized categories and specialist consultation retaining importance in integrated installations.
- Online Retail:Amazon and manufacturer-direct storefronts capture countertop and portable segments where specification comparison dominates purchase behavior. US next-day delivery infrastructure supports impulse replacement decisions.
- Specialty Stores:Kitchen design showrooms and appliance galleries provide specification consultation for built-in and free-standing categories requiring contractor coordination.
- Hypermarkets:Big-box retailers move volume in entry-level countertop configurations through seasonal promotional cycles.
- Direct Sales:Manufacturer-employed teams serve hospitality and commercial accounts with volume pricing and service bundling.
Online retail commands volume leadership in portable and countertop categories. Specialty store placement is gaining share fastest in built-in segments where installation complexity demands expert guidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: US households favor outdoor-integrated built-in units for poolside kitchens, while European and Asian markets concentrate demand in compact countertop formats constrained by apartment living.
United States
Outdoor entertainment culture in Florida, Texas, and Arizona sustains year-round replacement demand for undercounter ice production. EPA SNAP refrigerant phaseout deadlines compress manufacturer redesign cycles toward R-600a and R-290 alternatives. Dallas-Fort Worth and Phoenix metro corridors anchor distribution infrastructure for Sun Belt residential construction.
China
Urban middle-class expansion in Shanghai and Shenzhen drives first-time countertop purchases for compact housing. MIIT efficiency mandates and provincial green-consumption subsidies favor inverter-compressor variants over fixed-speed units. Guangdong manufacturing clusters around Shenzhen dominate cost-engineered portable production for export markets.
Germany
Basement bar renovations and outdoor kitchen retrofits concentrate demand in built-in configurations. EU F-Gas Regulation CE marking requirements accelerate lower-GWP refrigerant adoption across imports. North Rhine-Westphalia industrial zones host component suppliers for compressor housings and heat exchanger assemblies.
Japan
Compact housing in Tokyo and Osaka prioritizes zero-installation countertop units with noise suppression. METI energy-efficiency standards filter non-compliant imports from regional competitors. Nagoya manufacturing corridors retain captive technician-training infrastructure for aftermarket service networks.
India
Rising disposable incomes in Mumbai and Bangalore metro corridors create first-time appliance purchase potential for compact configurations. BIS energy-performance thresholds enforce minimum efficiency standards on household refrigerating appliances. Gujarat industrial zones supply compressor components for domestic assembly operations.
Global Home Ice Maker Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with mid-scale fabricators filling mass-market gaps. The structure rewards captive technician infrastructure and refrigerant-transition readiness over pure scale. Two strategic archetypes dominate: premium-channel specialists with training networks and cost-engineered portable producers leveraging manufacturing-cluster proximity. Competitive moves concentrate on geographic licensing partnerships and compliance-forward product redesigns ahead of regulatory deadlines.
Within the premium-channel tier, Hoshizaki Corporation exemplifies integrated service-network advantages through captive technician-training infrastructure. Scotsman Industries, Inc. occupies a specialization position in nugget-ice architectures for residential beverage-prep segments. At the cost-engineered end, Changshu Lingke Electric Appliance Co., Ltd. anchors portable-unit production through Shenzhen-adjacent manufacturing cluster access.
| Leading Market Players |
|---|
| Hoshizaki Corporation |
| The Manitowoc Company, Inc. |
| Scotsman Industries, Inc. |
| Whynter LLC |
| Ice-O-Matic |
| MaxxIce |
| NewAir |
| Sunpentown (SPT) Inc. |
| Changshu Lingke Electric Appliance Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
R-600a refrigerant substitution for R-134a across compressor architectures is simultaneously relocating production toward Shenzhen-adjacent manufacturing clusters and compressing margin structures for mid-tier competitors lacking flammability-compliant retooling capital. This input transition feeds directly into pricing power concentration among vertically integrated leaders with captive technician networks.
Pricing Analysis
Long-term offtake contracts between compressor manufacturers and Guangdong-based appliance assemblers anchor pricing stability for built-in segments, while spot-market copper and aluminum procurement governs countertop unit economics. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EPA SNAP and EU F-Gas frameworks, with after-sales service bundling widening spreads. Cost compression in portable categories intensifies because Changshu Lingke and Shenzhen-cluster competitors pass through metal exchange volatility immediately. Hospitality procurement teams show least price sensitivity due to contractor-specified installations, whereas urban apartment renters in US coastal markets exhibit maximum elasticity.
Supply Chain Analysis
Strait of Malacca transit underwrites refrigerant chemical feedstock flows from Middle Eastern petrochemical complexes to Guangdong compressor foundries. Manufacturing gravity centers on China, Vietnam, and Mexico, with component sourcing drawing from Japanese inverter-drive specialists and German heat-exchanger engineering. Single-source vulnerability concentrates in R-600a refrigerant supply from select chemical processors. Distribution runs through Amazon-direct and big-box seasonal cycles for countertop units, while built-in segments flow through kitchen-design showroom networks requiring contractor coordination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigerant-phaseout deadlines under EPA SNAP rules constitute a technological-regulatory inflection that will consolidate manufacturing capacity toward compliance-ready leaders within the analysis window.
For Market Incumbents: Shield premium-channel positioning by accelerating captive technician-training infrastructure deployment across Sun Belt service territories, countering independent repair network collapse. Deepen backward integration into compressor housing production to offset London Metal Exchange aluminum volatility exposure. For New Entrants and Emerging Players: Lead with voice-integration compatibility as a differentiated go-to-market angle targeting electronics retailer placement in US suburban markets. India's urban middle-class expansion in Mumbai and Bangalore corridors offers the most penetrable white-space for compact countertop configurations with zero-installation value propositions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed appliance platform companies holding regional distributor relationships but lacking refrigerant-transition engineering capabilities. Five-to-ten-year viability hinges on compliance-forward product portfolios; monitor EPA Section 608 certification expansion rates across secondary US metropolitan areas as the decisive inflection indicator for service-network scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Compliance Program | EPA SNAP deadlines force R-600a/R-290 adoption ahead of competitor redesign cycles. |
| Captive Technician Training Infrastructure | Hoshizaki-style service networks lock in premium-channel loyalty across North American markets. |
| Voice-Integration Platform Partnership | Amazon Alexa and Google Home compatibility opens incremental electronics retailer placement. |
| Direct-to-Consumer Channel Migration | Manufacturer-owned storefronts capture replacement demand shifting from big-box kitchen specialists. |
| Inverter-Compressor Efficiency Upgrade | MIIT labeling and provincial subsidies in China favor premium positioning over fixed-speed units. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA SNAP regulatory filings, EU F-Gas compliance databases, and China GB standard enforcement records. Interviews with appliance manufacturing executives, refrigeration compressor procurement leads, kitchen-design showroom operators, and aftermarket service technicians informed demand-side validation. Bottom-up unit shipment modeling triangulated against top-down consumer expenditure analysis across the projection horizon.
Segmentation dimensions modeled include product configuration, compressor technology tier, end-use application, and distribution channel structure throughout the forecast period. CAGRs derived from installed base replacement cycles, new construction correlations, and regulatory compliance-driven upgrade timelines. Electricity tariff trajectories and refrigerant phaseout deadlines served as critical forecast inputs.
The analysis sits within stated boundaries; outcomes outside EPA SNAP enforcement intensity or copper price stability assumptions would require recalibration. Practitioners should keep alternative scenarios live as EU F-Gas Regulation amendment cycles and China dual carbon policy implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Electric Rice Cooker Market
Appliances
Dishwasher Market
Appliances
Smart Ceiling Fan Market
Appliances
Global Massage Chairs Market
Appliances
Global Vended Laundry Equipment Market
Appliances
Cordless Vacuum Cleaner Market
Appliances
Bhutan and Nepal White Goods Market
Appliances
UAE Dishwasher Market
Appliances
French Door Refrigerator Market
Appliances
Kuwait Dishwasher Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
Large Cooking Appliance Market
Appliances
United States Multi-Functional Oven Market
Appliances
Asia Pacific Compact Dishwasher Market
Appliances
US Washing Machine Parts Market
Appliances
Turkey Washing Machine Market