
 India Smart Wearable Market | 2026-2036
India Smart Wearable Market Size, Share, and Industry Trends Forecast 2026-2036
India Smart Wearable Market Foresight
Edge AI processing on-device is reconfiguring how Indian OEMs architect wearable firmware, reducing cloud dependency for real-time health analytics. Xiaomi Corporation leverages its vertically integrated supply chain to dominate entry-level smartwatch pricing across Tier-2 and Tier-3 cities. Noise sustains aggressive R&D spending on indigenous operating systems, differentiating its portfolio from Android-dependent rivals. boAt Lifestyle anchors its position through celebrity-led marketing and deep offline distribution in metro retail corridors.
India smart wearables encompass wrist-worn, head-mounted, and body-integrated devices that combine MEMS sensors, low-power Bluetooth SoCs, and photoplethysmography modules to capture biometric and contextual data for consumer health, fitness, and notification management. These products typically operate on sub-1 GHz ARM Cortex architectures with 7-14 day battery cycles, serving both preventive healthcare monitoring and productivity augmentation use cases. Smart watches command the largest revenue pool as Indian consumers prioritize SpO2 and ECG features post-pandemic, while fitness trackers retain volume leadership among institutional buyers deploying employee wellness programs. Online retail channels capture disproportionate growth velocity, though brand outlets and specialty stores defend margin pools through experiential trials and after-sales service attachment.
BIS certification mandates for electronic products and CDSCO oversight on medical-grade wearable claims shape product development timelines and labeling requirements for manufacturers targeting the Indian market. India's PLI scheme for wearable electronics and state-level electronics manufacturing policies in Karnataka and Tamil Nadu are redirecting supply chain investments toward domestic assembly. Stakeholders must monitor how BIS expands its technical standards for hearables and smart clothing, as these categories sit at the regulatory boundary between consumer electronics and medical devices.
Market Dynamics
Edge AI inference on sub-1 GHz ARM Cortex-M4F cores is compressing cloud dependency for real-time health analytics, forcing Indian OEMs to rearchitect firmware stacks around on-device signal processing rather than API-heavy architectures.
Growth Catalysts
- PLI scheme for wearable electronics:Domestic assembly incentives in Karnataka and Tamil Nadu are redirecting supply chain investments toward local manufacturing, reducing import dependency for Bluetooth SoCs and MEMS sensors.
- Corporate wellness procurement:Institutional buyers in Bengaluru, Hyderabad, and Mumbai are expanding fitness tracker deployments for employee health monitoring, creating volume anchors independent of consumer cycles.
- Photoplethysmography module cost curves:Chinese component suppliers have driven SpO2 sensor prices below threshold levels, enabling mass-market ECG-capable smartwatches at entry-tier price points.
Market Restraints
- BIS certification timelines:Technical standards expansion for hearables and smart clothing creates labeling friction at the boundary between consumer electronics and medical device claims.
- Lithium-polymer cell supply:Battery chemistry sourcing concentrates in Guangdong and Jiangsu provinces, exposing Indian assemblers to shipping cost volatility and yuan-denominated input swings.
- Android Wear OS dependency:Indigenous operating system development lags force domestic brands into royalty-bearing licensing structures that compress gross margins on sub-INR 5,000 devices.
Strategic Opportunities
- Preventive healthcare integration:Ayushman Bharat data interoperability standards create openings for wearable-generated biometric streams to feed into public health screening workflows.
- Tier-3 city offline penetration:Brand-owned exclusive stores in Indore, Lucknow, and Kochi remain underpenetrated relative to metro saturation, offering first-mover experiential retail advantages.
- Low-power Bluetooth 5.3 SoCs:Convergence with energy harvesting from kinetic and thermoelectric sources is digitizing battery-free form factors for continuous glucose monitoring patches.
Industry Challenges
- Firmware talent scarcity:Embedded systems engineers with RTOS and signal processing expertise command premium compensation in Bengaluru and Hyderabad, constraining R&D headcount expansion for mid-tier OEMs.
- CDSCO medical-grade pathway complexity:Wearables claiming diagnostic accuracy must navigate clinical validation timelines that extend product launch windows by 14-18 months versus consumer-grade equivalents.
- After-sales service network density:Spare parts logistics for display assemblies and PPG sensors remain concentrated in Delhi NCR and Mumbai, creating service turnaround friction in eastern and northeastern states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Smart Wearable Market |
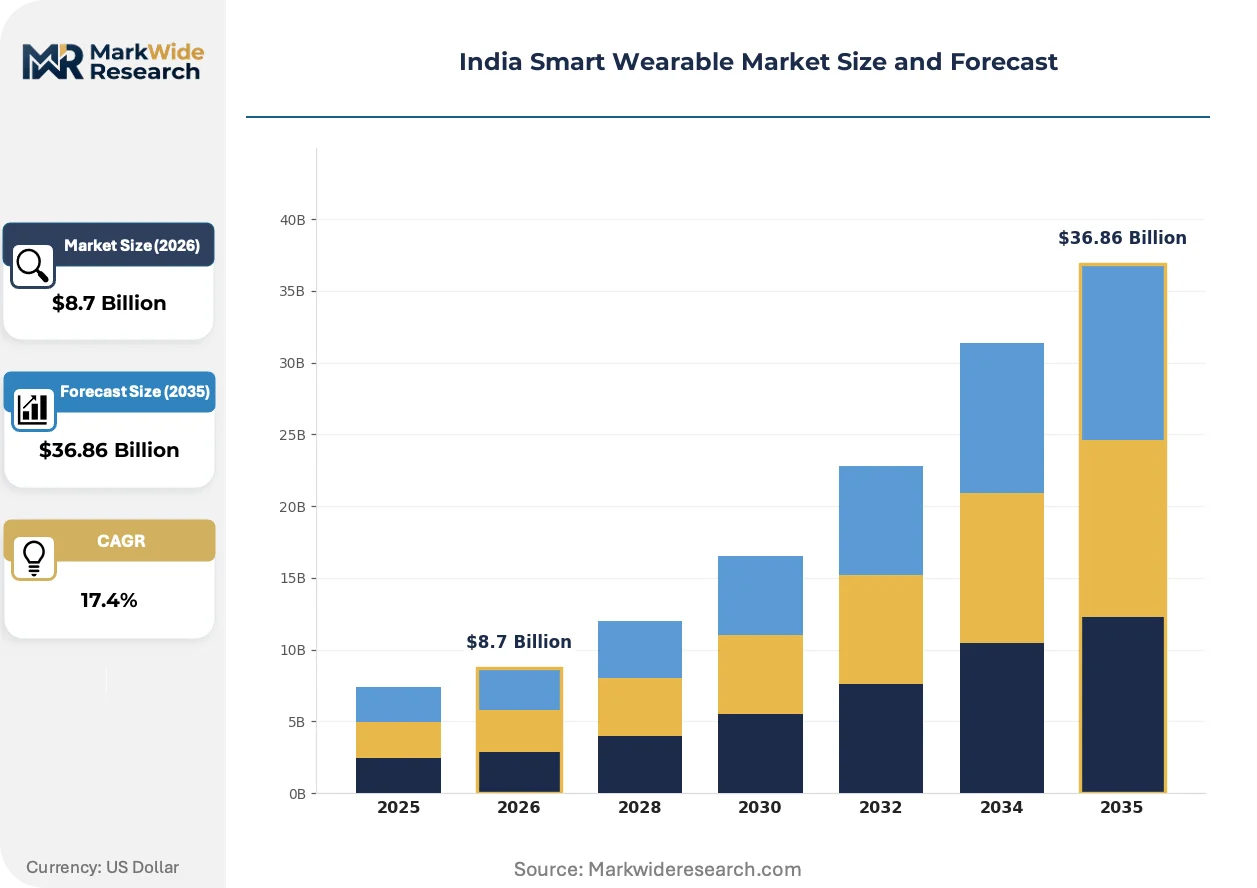
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $36.86 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Watches, Fitness Trackers, Smart Glasses, Smart Clothing Technology: Bluetooth, NFC, Wi-Fi, GPS End User: Fitness Enthusiasts, Tech Savvy Users, Elderly, Health Monitors Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Brand Outlets |
| Companies Covered | Xiaomi Corporation, Google LLC, Noise, GOQii Technologies Pvt Ltd, Garmin India Pvt Ltd, Apple Inc., boAt Lifestyle, Fitbit Inc, Samsung Electronics Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Smart Wearable Market Shifts & Advancements
Three interconnected shifts are restructuring how Indian wearable OEMs architect hardware-software interfaces: on-device inference, regulatory boundary-testing, and channel hybridization between D2C and experiential retail.
Neural network quantization for microcontrollers is digitizing health analytics at the network edge. Indian engineering teams at Noise and boAt are deploying TensorFlow Lite Micro runtimes on Cortex-M4F cores to process PPG and accelerometer streams without cloud round-trips. This compression of latency and data costs is enabling subscription-free feature sets that challenge Android-dependent rivals on total cost of ownership.
CDSCO's draft guidance on software-as-a-medical-device is tightening evidentiary requirements for heart rhythm irregularity detection claims. Manufacturers must now submit clinical validation data for algorithms classifying atrial fibrillation, extending development timelines but creating regulatory moats against uncertified imports. Maharashtra and Karnataka-based assemblers are responding by partnering with cardiology institutes for prospective validation cohorts.
Consumer purchasing for premium smartwatches is rotating toward brand-exclusive physical touchpoints where experiential trials drive conversion. Online discounting fatigue in Delhi NCR and Mumbai has elevated the importance of service attachment and extended warranty upsells at company-owned stores. This channel pivot is compressing pure-play e-commerce growth rates while defending margin pools through higher ASP realization and recurring revenue streams.
India Smart Wearable Market Segmentation
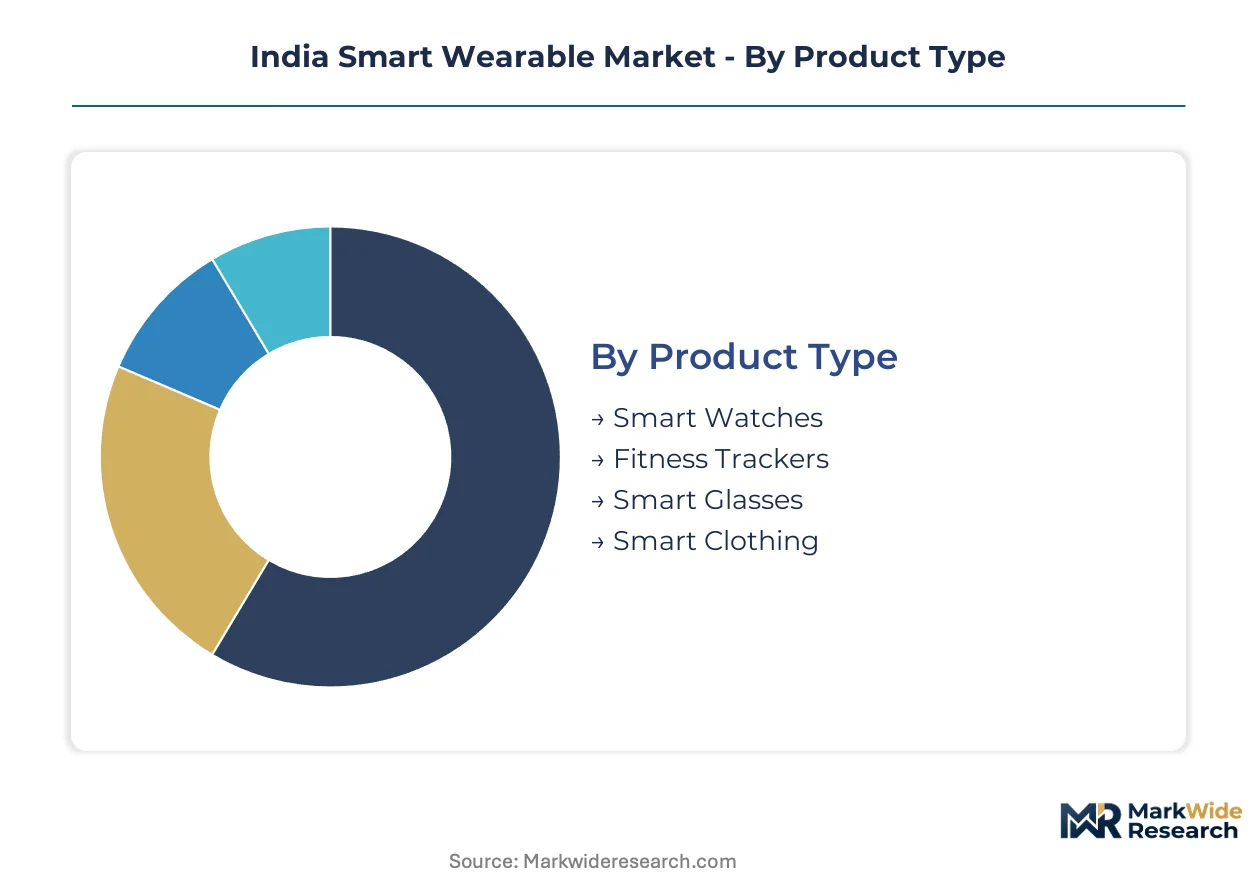
Segmentation in India's smart wearable market reveals how hardware specifications, connectivity protocols, and purchasing behaviors stratify across distinct consumer cohorts. Manufacturers must align firmware architectures and channel investments to these boundaries to capture margin pools effectively.
Product Type:
The use-case spectrum spans preventive health monitoring, fitness optimization, augmented productivity, and biometric-integrated apparel for industrial safety.
- Smart Watches:Full-featured wrist-worn devices integrate SpO2 sensors, ECG electrodes, and AMOLED displays for continuous cardiac monitoring. Maharashtra and Karnataka households with post-pandemic health anxiety drive premium adoption here, though battery life constraints limit always-on display deployment.
- Fitness Trackers:Stripped-down PPG and accelerometer modules deliver step counting and sleep staging at sub-INR 3,000 price points. Corporate wellness programs in Bengaluru and Hyderabad procure these in volume for employee cohorts, creating institutional demand anchors distinct from consumer cycles.
- Smart Glasses:Optical waveguide displays and bone-conduction audio enable heads-up notification delivery. Early pilots focus on warehouse logistics and field service technicians in Delhi NCR manufacturing corridors.
- Smart Clothing:Conductive thread-integrated textiles capture electromyography and respiratory rate for athletic performance optimization. Kerala's textile research clusters and Tamil Nadu garment exporters are prototyping moisture-resistant form factors for tropical climates.
Established volume favors fitness trackers; emerging adoption favors smart watches.
Technology:
Connectivity cost tiers determine whether devices operate as standalone health terminals or smartphone-tethered accessories.
- Bluetooth:Low-energy 5.3 SoCs dominate wrist-worn power budgets, enabling 7-14 day cycles on 200mAh lithium-polymer cells. Noise and boAt firmware teams optimize connection intervals specifically for Android fragmentation patterns in Tier-2 Indian cities.
- NFC:Contactless payment tokenization requires secure element integration that adds INR 400-600 to bill-of-materials. Mumbai and Delhi NCR metro commuters represent the concentrated addressable base for transit-credential wearables.
- Wi-Fi:Direct cloud synchronization bypasses smartphone intermediaries for elderly users uncomfortable with paired device management. Deployment concentrates in Kerala and Goa retirement communities with reliable fiber backhaul.
- GPS:Multi-constellation receivers enable breadcrumb tracking for marathon training and dementia patient wandering alerts. Ladakh trekking operators and Chennai dementia care facilities represent specialized procurement channels.
Bluetooth anchors current shipment volumes; GPS-enabled SKUs are climbing the fastest as safety-positioning applications proliferate.
End User:
Customer maturity and technical sophistication stratify feature requirements and price elasticity.
- Fitness Enthusiasts:Amateur marathoners and CrossFit practitioners demand VO2 max estimation and recovery metrics calibrated for Indian metabolic baselines. Bengaluru's Koramangala and Indiranagar fitness studio networks drive word-of-mouth premium adoption.
- Tech Savvy Users:Early adopters in Hyderabad's HITEC City and Pune's Magarpatta evaluate devices on developer API openness and third-party app ecosystem breadth. This cohort tolerates shorter battery life for customization depth.
- Elderly:Fall detection and medication reminder interfaces require large-format displays and simplified touch targets. Kerala's aging demographic and Coimbatore retirement colonies generate concentrated demand for caregiver-dashboard integration.
- Health Monitors:Post-surgical cardiac patients and diabetics require clinical-grade accuracy for physician-shared reports. CDSCO validation pathways currently restrict this segment to imported devices with 510(k) equivalency documentation.
Fitness enthusiasts dominate current revenue; health monitors represent the steepest expansion trajectory as BIS standards mature for medical-adjacent claims.
Distribution Channel:
Channel selection determines margin capture and after-sales service attachment rates.
- Online Retail:Amazon India and Flipkart capture disproportionate growth velocity through festival-season discounting and EMI financing penetration. Return rates run elevated for smart watches due to wrist-size fit mismatches.
- Specialty Stores:Croma and Reliance Digital outlets defend margin pools through experiential trials and extended warranty upsells. Mumbai Phoenix Marketcity and Bangalore Central mall locations prioritize premium brand visibility.
- Supermarkets:BigBasket and Reliance Smart Point-of-Sale displays introduce fitness trackers to grocery-trip impulse purchases. This channel excels in Tier-3 city penetration where dedicated electronics retail remains sparse.
- Brand Outlets:Noise and boAt exclusive stores in Delhi NCR and Mumbai enable direct customer relationship management and first-party data collection for R&D feedback loops.
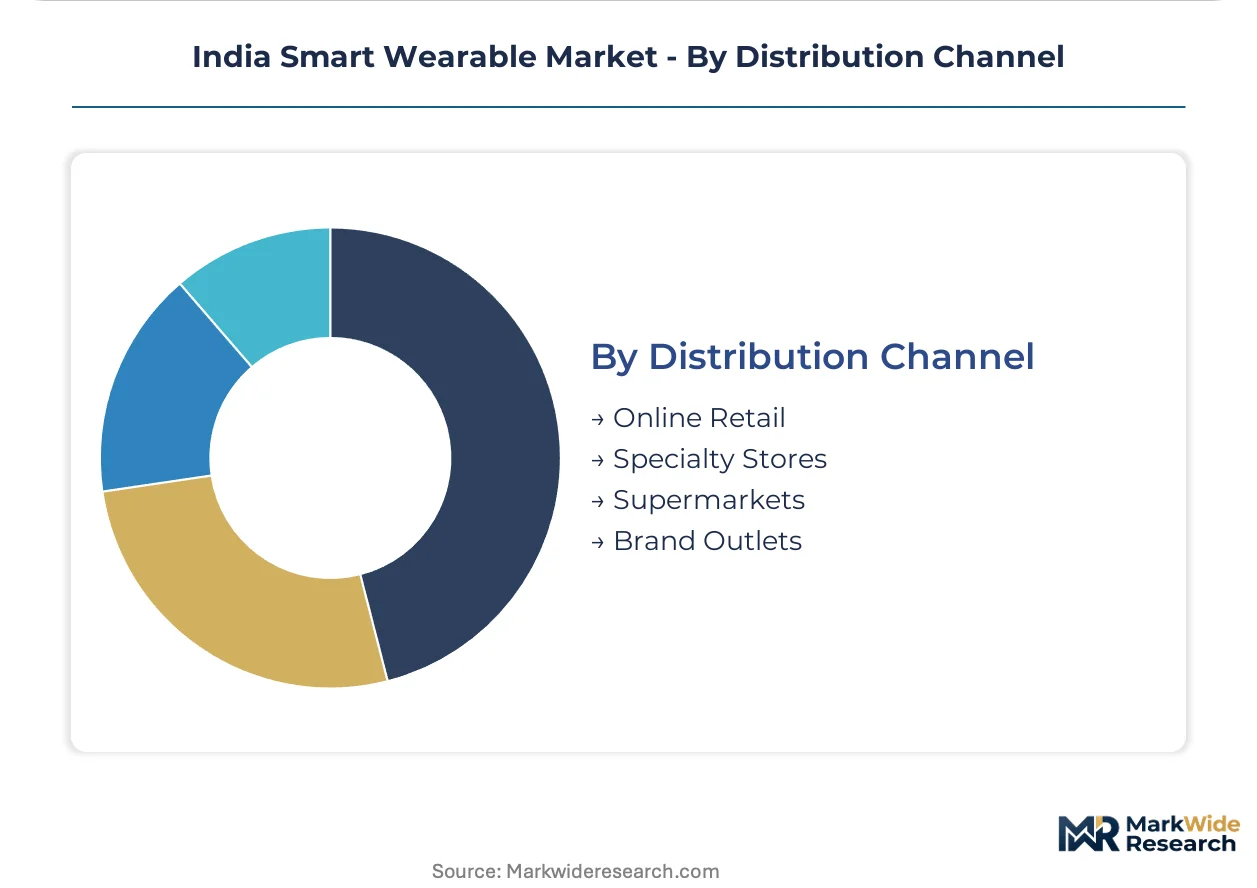
Online retail captures volume leadership; brand outlets are gaining share fastest as experiential differentiation counters discounting fatigue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese component suppliers export photoplethysmography modules and Bluetooth SoCs to Indian assemblers in Karnataka and Tamil Nadu, establishing the dominant trade corridor for wearable electronics manufacturing.
Maharashtra
Mumbai's corporate wellness programs procure fitness trackers in volume for employee health monitoring. BIS certification mandates for electronic products shape product development timelines for manufacturers targeting this market. Pune's automotive and IT corridors concentrate demand for premium smartwatches with SpO2 and ECG features among health-conscious professionals.
Karnataka
Bengaluru's tech workforce drives premium smartwatch adoption with emphasis on developer API openness and customization depth. The state's electronics manufacturing policy redirects supply chain investments toward domestic assembly of Bluetooth SoCs and MEMS sensors. Whitefield and Electronic City host engineering teams optimizing TensorFlow Lite Micro runtimes for on-device health analytics.
Telangana
Hyderabad's HITEC City early adopters evaluate devices on third-party app ecosystem breadth and tolerate shorter battery life for feature depth. CDSCO oversight on medical-grade wearable claims extends product launch windows for heart rhythm irregularity detection algorithms. The city's pharmaceutical corridor creates specialized procurement channels for clinical-grade accuracy devices.
Delhi NCR
Metro commuters in Delhi concentrate demand for NFC-enabled contactless payment wearables for transit credential integration. DGFT regulations on lithium-polymer cell imports expose assemblers to shipping cost volatility from Guangdong suppliers. Gurugram and Noida brand outlets defend margin pools through experiential trials and extended warranty upsells.
Kerala
The state's aging demographic generates concentrated demand for elderly-focused wearables with fall detection and caregiver-dashboard integration. Ayushman Bharat data interoperability standards create openings for wearable-generated biometric streams in public health screening workflows. Kochi's underpenetrated brand-owned exclusive stores offer first-mover experiential retail advantages for premium positioning.
India Smart Wearable Market Competitive Landscape
Channel-controlling players compete with product-specialist players across India's smart wearable market, creating a tiered structure where offline distribution depth and online velocity operate as distinct competitive vectors. The vendor base stratifies between vertically integrated electronics conglomerates, indigenous firmware developers, and celebrity-marketed lifestyle brands. Three archetypes dominate: supply-chain-integrated price leaders, indigenous operating system developers, and marketing-driven lifestyle positioners. Capacity expansion in Tamil Nadu and Karnataka assembly facilities and strategic partnerships for clinical validation cohorts represent the dominant competitive moves reshaping positioning.
Within the indigenous firmware development tier, Noise exemplifies aggressive R&D spending on proprietary operating systems that differentiate from Android-dependent rivals. Among supply-chain-integrated players, Xiaomi Corporation leverages vertically integrated procurement to anchor entry-level pricing across Tier-2 and Tier-3 cities. boAt Lifestyle occupies a position defined by celebrity-led marketing and deep offline distribution in metro retail corridors, representing the lifestyle-brand archetype.
| Leading Market Players |
|---|
| Xiaomi Corporation |
| Google LLC |
| Noise |
| GOQii Technologies Pvt Ltd |
| Garmin India Pvt Ltd |
| Apple Inc. |
| boAt Lifestyle |
| Fitbit Inc |
| Samsung Electronics Co., Ltd. |
| Others |
Supply & Pricing Matrix
Guangdong lithium-polymer cell export licensing volatility compresses both entry-tier smartwatch margins and Tier-3 city distribution reach, forcing Indian OEMs to arbitrage between yuan-denominated input exposure and domestic assembly incentives under the PLI scheme.
Pricing Analysis
Bluetooth 5.3 SoC pricing gaps separate current-gen ECG-capable smartwatches from prior-gen fitness trackers and emerging energy-harvesting form factors. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade differentiation and after-sales service bundling. Cost compression in sub-INR 3,000 fitness trackers intensifies because Chinese PPG module suppliers have collapsed SpO2 sensor costs. Corporate wellness buyers in Bengaluru and Hyderabad exhibit lowest price sensitivity; Tier-3 grocery-impulse purchasers show highest elasticity.
Supply Chain Analysis
DGFT restricted-technology controls on advanced Bluetooth SoC lithography limit flows from Taiwan and South Korea to Karnataka assembly facilities. Indian wearable manufacturing draws from Guangdong for lithium-polymer cells, Jiangsu for MEMS accelerometers, and Shenzhen for AMOLED display driver ICs. Single-source vulnerability concentrates in 200mAh battery chemistry sourcing. Distribution runs through Delhi NCR and Mumbai logistics hubs to brand outlets and Amazon India fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended warranty and subscription-based health analytics attach rates are expanding faster than hardware unit economics, repositioning margin capture toward recurring revenue layers.
For Market Incumbents: Build clinical validation moats through CDSCO medical-grade pathway completion for heart rhythm algorithms. Noise and boAt should expand Karnataka assembly capacity to capture PLI incentives before scheme sunset. Firmware talent scarcity in Bengaluru threatens R&D velocity; captive training partnerships with IISc and IIIT-Hyderabad defend engineering pipeline against poaching from Samsung India and Xiaomi. For New Entrants and Emerging Players: Pursue Kerala elderly-care wearables with fall detection and caregiver-dashboard integration as the most penetrable white space. Kochi and Thiruvananthapuram brand-exclusive stores remain underpenetrated relative to metro saturation. GOQii's preventive healthcare platform model offers a proven go-to-market template for Ayushman Bharat data interoperability positioning. For Investors and Strategic Acquirers: The market sits at a firmware-capability consolidation phase that favors indigenous OS developers over Android-dependent assemblers. Long-term viability across the projection horizon hinges on edge AI inference IP and clinical validation cohort access. Watch for BIS expansion into hearables and smart clothing standards as the inflection signal separating medical-adjacent claimants from consumer electronics pure-plays.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Medical-Grade Pathway Completion | Creates regulatory moats against uncertified imports from Shenzhen and Hong Kong traders. |
| Karnataka PLI Assembly Capacity Expansion | Captures domestic manufacturing incentives before lithium-polymer localization requirements tighten. |
| TensorFlow Lite Micro Runtime Optimization | Enables subscription-free health analytics that challenge Android Wear OS royalty structures. |
| Kerala Brand-Exclusive Store Rollout | Secures first-mover experiential retail positioning in elderly-focused wearable segments. |
| Cardiology Institute Validation Partnerships | Accelerates clinical evidence generation for atrial fibrillation detection algorithm claims. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of CDSCO guidance documents, BIS technical standards filings, and PLI scheme disbursement records. Primary interviews engaged wearable OEM product managers, Karnataka electronics manufacturing policy officers, and Reliance Digital category buyers. Secondary sources included DGFT import-export data, Karnataka Udyog Mitra investment tracking, and Amazon India marketplace velocity indices. Bottom-up SKU-level shipment estimates triangulate against top-down PLI incentive claims.
Forecast inputs span product type segmentation across smart watches, fitness trackers, and emerging hearables; technology tiers from Bluetooth 5.3 to NFC-enabled payment wearables; and distribution channel evolution from online retail to brand-exclusive stores. End-user cohorts modeled include fitness enthusiasts, elderly health monitors, and corporate wellness procurement. CAGRs derive from unit shipment trajectories and average selling price compression curves across the analysis window. Edge AI adoption rates and CDSCO validation timeline assumptions shape the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in yuan-rupee exchange rates or Guangdong shipping cost volatility would shift the trajectory. Forecasts reflect documented assumptions on PLI scheme continuity and BIS standards expansion timelines. Material shifts in CDSCO software-as-a-medical-device enforcement posture or lithium-polymer import licensing restrictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
3D Printed Wearables Market
Wearable Technology
Water Resistant Watch Market
Wearable Technology
Europe Watch Market
Wearable Technology
Consumer Grade Smart Wearable Device Market
Wearable Technology
Global Smart Shoes Market
Wearable Technology
Smart Audio Sunglasses Market
Wearable Technology
Pet Wearable Market
Wearable Technology
Global Smart Wearable Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
Android Wearable Computer Market
Wearable Technology
APAC Smart Watch Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
Wearable Computing Market
Wearable Technology
Wearable AI Devices Market
Wearable Technology
US Pet Wearable Market
Wearable Technology
Wearable Camera Market