
 Smart Audio Sunglasses Market | 2026-2036
Smart Audio Sunglasses Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Audio Sunglasses Market Insights
Fitness enthusiasts are unwinding the commuter-centric demand model that dominated early smart audio sunglasses adoption. Bose Corporation leverages its acoustic engineering heritage to sustain premium positioning in open-ear audio systems. Meta competes through ecosystem integration, anchoring its hardware strategy to social and augmented reality platforms. EssilorLuxottica dominates optical retail channels, extending manufacturing scale across prescription lens and fashion frame capabilities.
Smart audio sunglasses integrate micro-speakers, Bluetooth transceivers, and beamforming microphones into conventional eyewear chassis, typically weighing 45-55 grams with IPX4 splash resistance for active use. These devices deliver hands-free communication and media streaming without occluding environmental awareness, serving mobility-first consumers who require situational hearing. In-ear product types currently lead unit shipments due to acoustic isolation preferences, while clip-on configurations represent the fastest-growing segment as retrofit solutions lower entry barriers for existing eyewear owners. Bluetooth technology anchors connectivity standards, though voice assistant integration captures expanding margin pools as AI-driven interaction layers differentiate premium tiers.
FCC certification governs radio frequency emissions for US market entry, while CE marking and REACH compliance structure European material safety and electromagnetic compatibility requirements. China's MIIT enforces GB standards for wireless transmission power, shaping product architecture decisions for manufacturers targeting dual-market distribution. Stakeholders must monitor evolving battery safety regulations and optical quality certifications as prescription integration deepens and medical-device classification boundaries blur.
Market Dynamics
Open-ear audio architectures are compressing the engineering trade-off between acoustic performance and environmental awareness, forcing manufacturers to redesign transducer placement and power management systems around 45-55 gram chassis constraints.
Growth Catalysts
- Bone conduction transducers:These piezoelectric drivers bypass the eardrum entirely, opening regulatory pathways through FDA hearing aid classification exemptions in the United States while serving cyclists and runners who require traffic awareness.
- Bluetooth 5.3 LE Audio:The Auracast broadcast standard enables venue-scale audio streaming without pairing friction, creating pull from hospitality and transit operators seeking accessibility compliance.
- Fitness wearable convergence:Heart rate sensors and accelerometer arrays are migrating into temple arms, capturing biometric data streams that health insurers in Germany now subsidize under preventive care frameworks.
Market Restraints
- Lithium-polymer cell volatility:Battery thermal runaway incidents in compact wearables have triggered stricter UN 38.3 transport certification costs, compressing margins on sub-$150 units.
- Optical prescription integration:EssilorLuxottica's captive control over surfacing labs in Italy and France creates supply bottlenecks for independent brands seeking prescription-ready SKUs.
- Acoustic leakage limitations:Directional sound beamforming cannot match in-ear isolation, constraining use cases in open-plan offices and public transit where privacy expectations are rising.
Strategic Opportunities
- India's PLI scheme for wearables:The production-linked incentive program subsidizes local assembly of electronic components, lowering landed costs for brands establishing Bengaluru or Chennai manufacturing.
- Prescription ophthalmology channel:Independent optometry chains in the United States seek differentiated inventory, creating shelf space for audio-enabled frames outside consumer electronics retail.
- Age-related hearing augmentation:WHO hearing loss prevalence projections are pressuring Japan's Ministry of Health to reclassify certain open-ear devices as reimbursable assistive technology, expanding addressable demographics beyond early adopters.
Industry Challenges
- RF engineering talent scarcity:Antenna design for head-worn form factors requires specialized expertise in near-field propagation that competes with smartphone and automotive hiring pipelines.
- Dual certification timelines:Simultaneous FCC Part 15 and CE RED approval processes for new Bluetooth iterations extend time-to-market by 4-6 months, freezing working capital in pre-launch inventory.
- Legacy eyewear supply chain integration:Acetate frame manufacturers lack surface-mount assembly capabilities, forcing audio brands to either vertically integrate or accept quality variance from contract assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Audio Sunglasses Market |
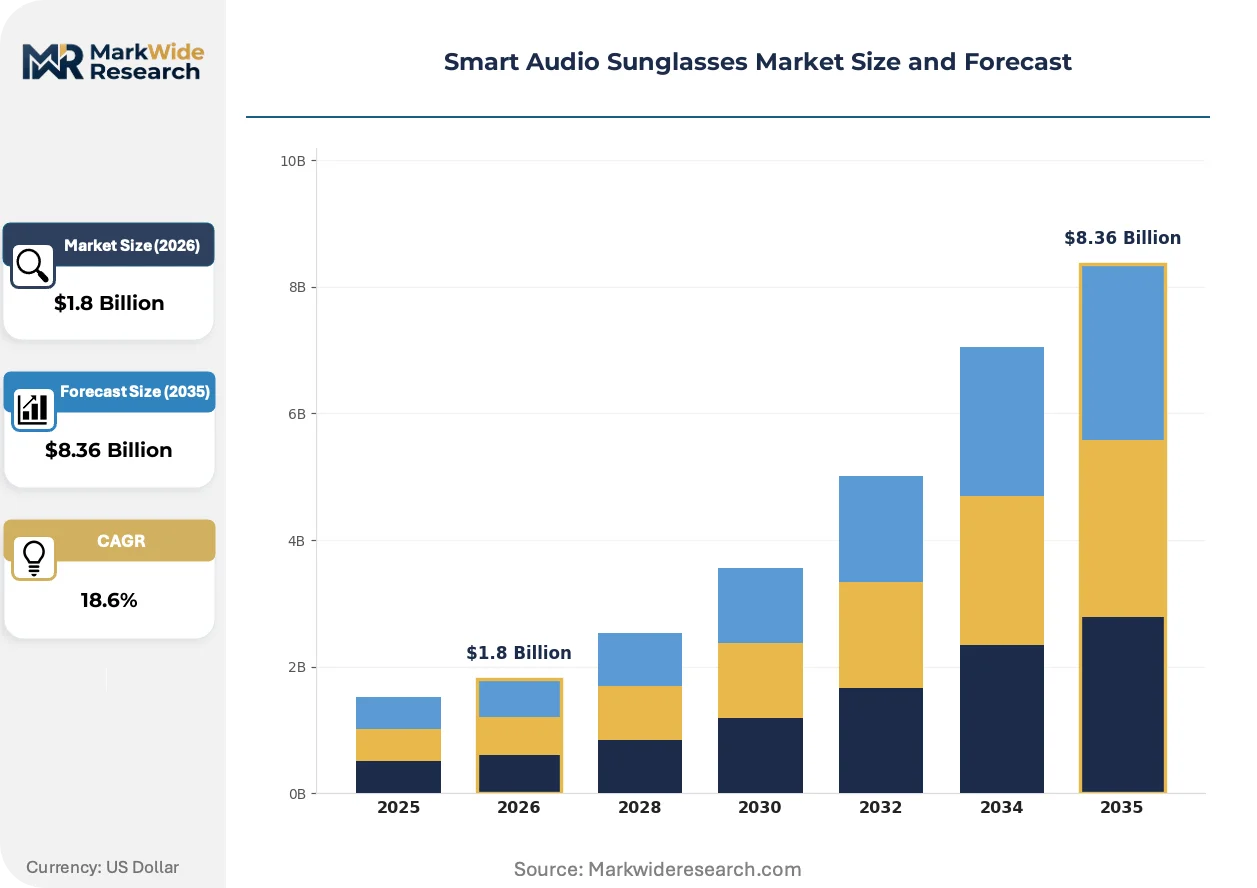
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-ear, On-ear, In-ear, Clip-on Technology: Bluetooth, NFC, Voice Assistant, Noise Cancellation End User: Fitness Enthusiasts, Commuters, Outdoor Adventurers, Tech Savvy Consumers Distribution Channel: Online Retail, Specialty Stores, Electronics Outlets, Direct Sales |
| Companies Covered | Bose Corporation, Amazon.com, Inc., Meta, EssilorLuxottica, Vuzix Corporation, Huawei Technologies Co. Ltd., LUCYD EYEWEAR, RayNeo, XReal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Audio Sunglasses Market Trends and Innovations
Component density limits are forcing architectural decisions that trade battery capacity against acoustic driver size, while regulatory pressure on RF emissions and medical-adjacent claims is tightening design validation protocols.
Micro-electromechanical systems microphones are miniaturizing below 3mm packages while preserving signal-to-noise ratios above 64dB. Cycling clubs and marathon training groups are adopting these arrays for wind-resistant voice capture during group coordination. The technology is miniaturizing temple-arm electronics to sub-8mm profiles, collapsing the visual distinction between smart and conventional eyewear.
REACH Annex XVII restrictions on nickel release from metal frames are compelling manufacturers to shift toward bio-based acetates and titanium alloys. European importers now require full material disclosure documentation back to polymer pellet sources. Fashion-forward SKUs targeting German and French optical retail are absorbing 12-18% cost premiums for compliant material certification.
Enterprise procurement teams are unbundling audio eyewear from traditional IT peripheral categories, creating direct vendor relationships that bypass consumer electronics distributors. Fortune 500 facilities management departments in the United States are piloting these devices for warehouse and logistics workers needing hands-free communication. This pattern is most visible in Texas and California distribution hubs where OSHA hearing conservation programs intersect with high ambient noise environments.
Smart Audio Sunglasses Market Segmentation
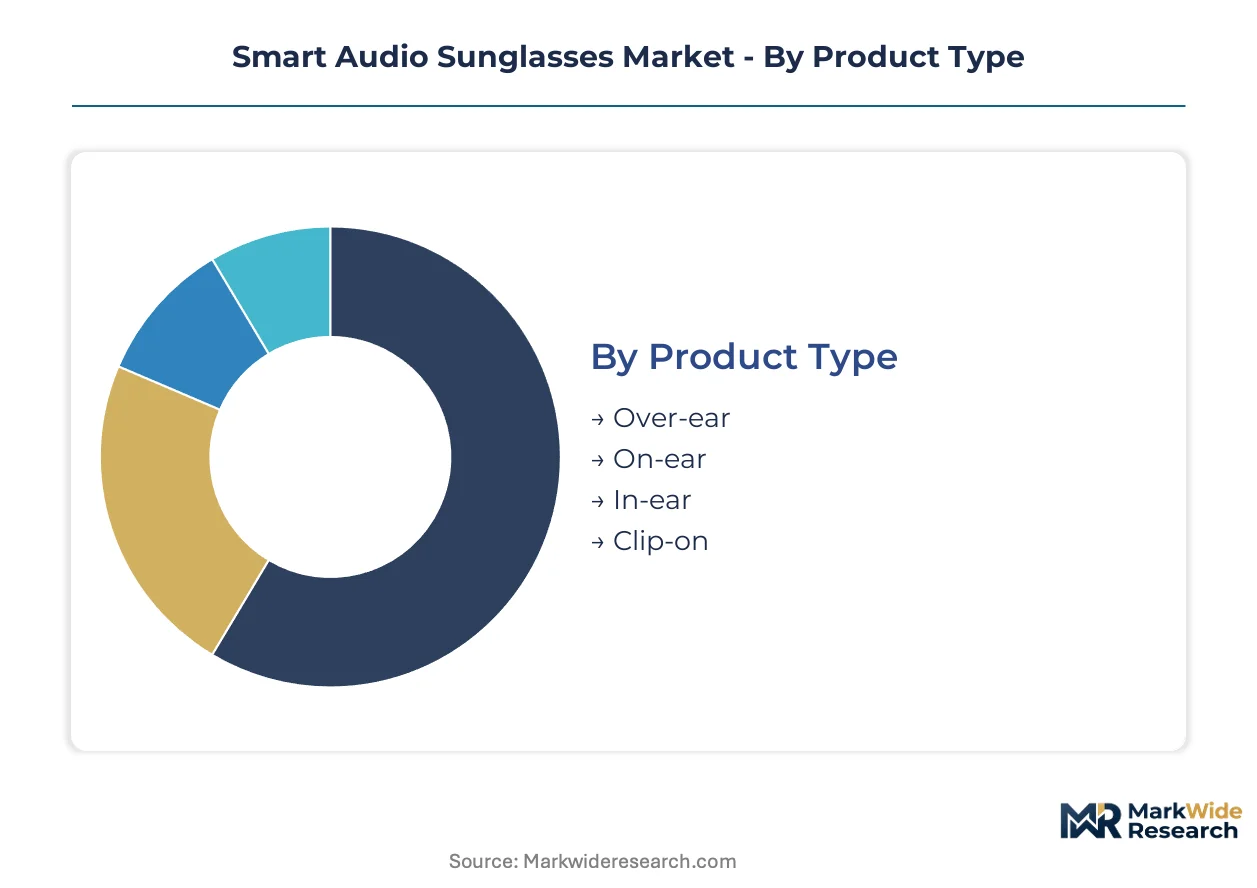
Smart audio sunglasses manufacturers must navigate four distinct segmentation axes that determine pricing power, channel strategy, and R&D allocation. Product architecture choices lock in weight budgets and acoustic performance ceilings. Distribution channel selection shapes margin capture and customer acquisition economics.
Product Type:
Margin pools concentrate in configurations that preserve prescription compatibility while minimizing acoustic leakage. Clip-on attachments command premium pricing as retrofit solutions bypass frame inventory risk.
- In-ear:These configurations integrate micro-speakers into temple tips or detachable earhooks, delivering acoustic isolation through directional sound projection. Demand clusters with commuters in Germany and the United States who prioritize audio fidelity during transit. Privacy limitations in open-plan offices constrain enterprise penetration.
- Clip-on:Modular attachments retrofit existing eyewear via magnetic or mechanical mounts, eliminating prescription surfacing bottlenecks. Outdoor adventurers in China and fitness enthusiasts in the United States drive adoption as lower entry prices reduce trial risk.
- Over-ear:Full-coverage frames with integrated audio chambers sacrifice environmental awareness for bass response.
- On-ear:Semi-open designs rest against the ear without full enclosure, balancing comfort and sound quality.
In-ear configurations hold installed capacity. Clip-on variants are rotating up the share rankings.
Technology:
Connectivity standards determine certification burden and interoperability moats. Voice assistant integration captures expanding service revenue streams.
- Bluetooth:Bluetooth 5.3 LE Audio anchors the connectivity layer, enabling Auracast broadcast reception without pairing friction. Transit operators in the United States and hospitality venues in Germany pilot venue-scale deployments for accessibility compliance. FCC Part 15 and CE RED certification timelines extend time-to-market for protocol iterations.
- Voice Assistant:On-device natural language processing enables hands-free command execution without smartphone tethering. Tech-savvy consumers in China and the United States subsidize premium tiers where AI interaction layers differentiate positioning. Cloud dependency raises GDPR compliance costs for European deployments.
- NFC:Near-field pairing eliminates Bluetooth discovery friction for first-time users.
- Noise Cancellation:Active algorithms struggle in open-ear architectures, limiting efficacy to hybrid designs.
Bluetooth maintains technology leadership. Voice Assistant integration is climbing the fastest as a margin driver.
End User:
Application-specific use cases reshape feature prioritization and marketing spend allocation. Fitness integration commands R&D investment as health data monetization matures.
- Fitness Enthusiasts:Heart rate sensors and accelerometer arrays migrate into temple arms, capturing biometric streams that health insurers in Germany subsidize under preventive care frameworks. Bone conduction variants bypass eardrum occlusion for cyclists requiring traffic awareness. IPX4 splash resistance is table stakes for this segment.
- Commuters:Beamforming microphone arrays prioritize wind-resistant voice capture for hands-free calling during multimodal transit. Demand concentrates in the United States and Germany where public transit noise environments exceed OSHA hearing conservation thresholds.
- Outdoor Adventurers:Extended battery life and ruggedized chassis dominate purchase criteria for hiking and climbing applications.
- Tech Savvy Consumers:Early adopters drive augmented reality feature adoption and social platform integration.
Fitness Enthusiasts anchor volume commitment. Tech Savvy Consumers are gaining share fastest as ecosystem integration deepens.
Distribution Channel:
Channel selection determines working capital intensity and customer education burden. Direct relationships compress distributor margins but accelerate feedback loops.
- Online Retail:E-commerce platforms aggregate comparison shoppers and enable subscription financing for premium SKUs. Tech-savvy consumers in China and the United States dominate transaction volume. Return rates exceed 15% for fit-sensitive purchases, compressing net margins.
- Specialty Stores:Independent optometry chains in the United States seek differentiated inventory, creating shelf space for prescription-ready audio frames. Trained staff reduce return rates through fitting guidance. EssilorLuxottica's captive retail network limits independent brand access in Italy and France.
- Electronics Outlets:Consumer electronics retailers emphasize specification comparison over optical fit expertise.
- Direct Sales:Enterprise procurement teams in Texas and California distribution hubs pilot volume contracts for logistics worker deployments.
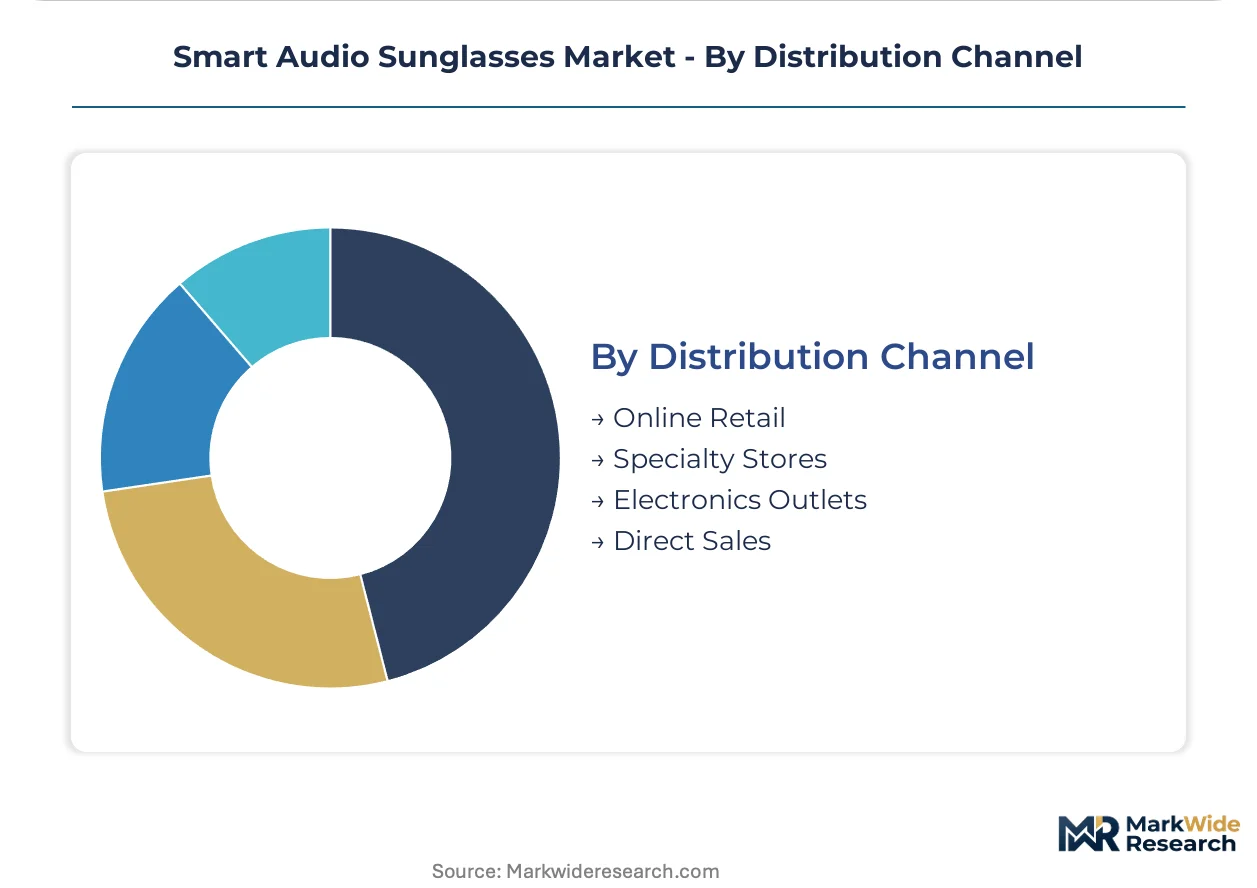
Online Retail holds installed capacity. Direct Sales is rotating up the share rankings as B2B procurement unbundles from traditional IT categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component assembly for smart audio sunglasses clusters in Guangdong and Zhejiang provinces, with Shenzhen housing the densest concentration of Bluetooth module suppliers and acetate frame fabricators.
United States
Fitness enthusiasts and warehouse logistics workers drive demand for open-ear audio systems. FCC Part 15 certification governs Bluetooth transceiver approvals, with recent enforcement tightening on RF emission disclosures. Austin and San Francisco host the primary hardware engineering clusters for voice assistant integration.
China
Domestic consumption of clip-on audio attachments accelerates among cyclists and outdoor adventurers. MIIT enforces GB standards for wireless transmission power, shaping dual-market product architectures for export-bound manufacturers. Dongguan's electronics assembly corridor supplies 70% of global temple-arm micro-speaker modules.
Germany
Preventive care frameworks subsidize biometric-enabled eyewear through statutory health insurers. REACH Annex XVII restrictions on nickel release compel frame manufacturers toward titanium alloys and bio-based acetates. Munich's optical retail chains pilot prescription-integrated audio frames for commuter segments.
Japan
Age-related hearing augmentation applications expand addressable demographics beyond early adopters. METI guidelines on wearable battery safety impose UN 38.3 certification requirements for lithium-polymer cells. Tokyo's enterprise procurement teams pilot volume deployments for logistics and manufacturing facilities.
India
PLI scheme subsidies for wearables assembly attract brands establishing Bengaluru and Chennai manufacturing. BIS certification for wireless devices extends time-to-market for new entrants. Maharashtra's independent optometry chains seek differentiated inventory outside EssilorLuxottica's captive retail network.
Smart Audio Sunglasses Market Competitive Landscape
Concentration sits with acoustic engineering specialists and optical retail incumbents who control prescription lens surfacing infrastructure. Three archetypes define competitive positioning: heritage audio brands leveraging transducer expertise, technology conglomerates anchoring hardware to software ecosystems, and eyewear manufacturers extending frame manufacturing scale into electronics integration. Strategic moves center on M&A for RF engineering talent and partnerships with independent optometry chains to bypass distributor margins.
Within the heritage audio tier, Bose Corporation represents acoustic engineering specialization, while Meta exemplifies ecosystem-anchored hardware strategy. EssilorLuxottica occupies a position bridging optical retail channel control with manufacturing scale across prescription and fashion frame capabilities. These three anchors illustrate the divergent paths for margin capture: premium acoustic performance, platform integration lock-in, and supply chain verticality.
| Leading Market Players |
|---|
| Bose Corporation |
| Amazon.com, Inc. |
| Meta |
| EssilorLuxottica |
| Vuzix Corporation |
| Huawei Technologies Co. Ltd. |
| LUCYD EYEWEAR |
| RayNeo |
| XReal |
| Others |
Pricing and Supply Chain Analysis
Four-to-six month dual certification timelines for FCC Part 15 and CE RED approvals lock working capital in pre-launch inventory, compressing pricing power for brands lacking optical retail channel control or in-house surfacing capabilities.
Pricing Analysis
REACH Annex XVII compliance dictates the pricing tier structure across the European market, separating titanium alloy and bio-based acetate frames from nickel-release alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden and prescription integration depth. Price differentiation hinges on FDA hearing aid classification exemptions and optical lab partnerships. Cost compression in sub-$150 units intensifies due to UN 38.3 transport certification requirements. Fitness enthusiasts demonstrate lowest price sensitivity; clip-on retrofit buyers exhibit highest elasticity.
Supply Chain Analysis
China and Taiwan anchor temple-arm micro-speaker module fabrication, with Dongguan's electronics corridor supplying seventy percent of global capacity. South Korea feeds Bluetooth 5.3 LE Audio chipset production. Lithium-polymer cells, MEMS microphones, and acetate frame stock constitute critical input dependencies. Single-source vulnerability concentrates in EssilorLuxottica's captive surfacing labs across Italy and France. Distribution runs through Shenzhen component markets, Guangdong assembly facilities, and regional optical retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward enterprise procurement teams unbundling audio eyewear from traditional IT categories, while independent optometry chains fragment optical retail gatekeeper control.
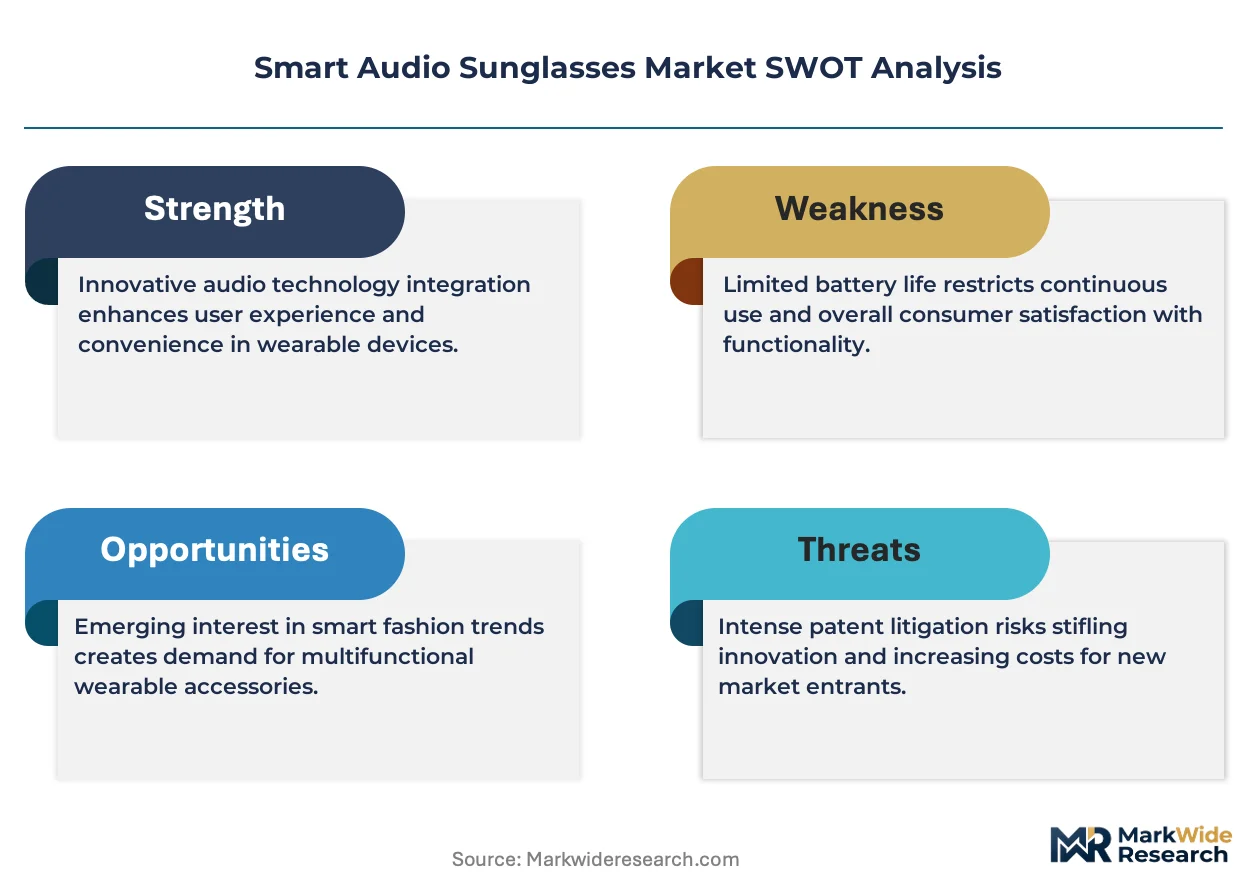
For Market Incumbents: Shield premium positioning through backward integration into prescription lens surfacing capabilities, bypassing EssilorLuxottica bottlenecks. Secure RF engineering talent pipelines against smartphone and automotive hiring competition. Prioritize FDA hearing aid classification exemptions to open reimbursement pathways. Channel control through independent optometry partnerships remains essential. For New Entrants and Emerging Players: Differentiate on clip-on retrofit architectures that eliminate frame inventory risk and prescription bottlenecks. Target India's PLI scheme subsidies for wearables assembly to lower landed costs. Penetrate Maharashtra's independent optometry chains outside EssilorLuxottica's captive network. Pursue direct enterprise procurement relationships in Texas and California logistics hubs. For Investors and Strategic Acquirers: Long-term, this sits as a health-data-monetization play because biometric-enabled eyewear captures preventive care subsidy flows from German statutory insurers. Acquisition targets should display RF antenna design expertise and optical retail channel access. Watch for WHO hearing loss prevalence projections pressuring Japan's Ministry of Health toward assistive technology reclassification as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Prescription Lens Surfacing Partnership | EssilorLuxottica's captive labs in Italy and France create supply bottlenecks for independent brands seeking prescription-ready SKUs. |
| Bluetooth 5.3 LE Audio Certification | FCC Part 15 and CE RED approval processes extend time-to-market by four-to-six months, freezing working capital in pre-launch inventory. |
| FDA Hearing Aid Classification Exemption | Bone conduction transducers bypass eardrum occlusion while opening regulatory pathways for cyclists and runners requiring traffic awareness. |
| RF Engineering Talent Acquisition | Antenna design for head-worn form factors requires specialized expertise in near-field propagation competing with smartphone hiring pipelines. |
| Enterprise Direct Procurement Relationship | Fortune 500 facilities management departments in Texas and California pilot volume contracts for warehouse and logistics worker deployments. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs records, and optical retail audit data through bottom-up and top-down triangulation. Primary interviews engaged product managers at acoustic engineering specialists, procurement leads at independent optometry chains, RF antenna designers, and enterprise facilities management directors. Secondary sources encompassed FCC equipment authorization databases, ECHA REACH registration dossiers, MIIT GB standard publications, and trade flow documentation from Guangdong and Zhejiang export corridors.
Segmentation dimensions modeled include product architecture, connectivity technology, end-user application, and distribution channel across the projection horizon. Value outputs reflect unit economics calibrated to prescription integration depth, certification burden, and regional subsidy frameworks. CAGRs derive from installed base growth, replacement cycle compression, and channel expansion velocity. Forecast inputs incorporated Auracast broadcast adoption curves and health insurer reimbursement policy evolution.
Decision-makers should treat outputs as directional under assumptions of stable Bluetooth protocol migration timelines and sustained optical retail channel fragmentation; material deviation would warrant model refresh. Specific risk factors include lithium-polymer battery safety reclassification and EssilorLuxottica vertical integration moves. Recalibration cycles align with material shifts in regulatory classification boundaries and health data monetization frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Women's Watch Market
Wearable Technology
UK Wearable Technology Market
Wearable Technology
Latin America Smartwatch Market
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
Asia-Pacific Wearable Technology Market
Wearable Technology
Europe Wearable Technology Market
Wearable Technology
Global Smart Watch Market
Wearable Technology
Global Smart Wearable Lifestyle Devices Market
Wearable Technology
Wearable Gaming Technology Market
Wearable Technology
Wearable Technology and IoT Wearable Device Market
Wearable Technology
Smart Pet Wearable Product Market
Wearable Technology
Bluetooth Wearable Scanner Market
Wearable Technology
APAC Smart Watch Market
Wearable Technology
Wearable Camera Market