
 Water Resistant Watch Market | 2026-2036
Water Resistant Watch Market Size, Share, and Industry Trends Forecast 2026-2036
Water Resistant Watch Market Insights
ISO 2281 and ISO 6425 certification tiers is rotating consumer preference toward professionally validated water resistance ratings. Rolex anchors the luxury dive segment through in-house case manufacturing and helium escape valve technology. Casio dominates the entry-professional tier with G-Shock sub-lines that leverage shock-resistant module architectures. Seiko specializes in accessible mechanical divers, sustaining volume through Prospex distribution across Asian retail networks.
A water resistant watch is a timepiece engineered with sealed case assemblies, gaskets, and screw-down crowns to prevent water ingress at specified pressure depths, typically rated from 30 meters to 300 meters or more. The primary commercial purpose is to protect internal movements during aquatic activities, occupational diving, and daily exposure to moisture while preserving chronometric accuracy. Mechanical technology leads the prestige tier where Swiss and Japanese manufacturers command margin pools through in-house escapements and extended service intervals. Smart technology represents the fastest-expanding segment as Garmin and Apple integrate depth sensors and dive computer algorithms into wrist-worn form factors. Stainless steel remains the dominant material for mid-tier professional watches, though titanium is gaining share among saturation divers seeking reduced wrist fatigue.
ISO standards govern water resistance testing protocols, while the EU REACH regulation restricts nickel release from case alloys in contact with skin. The US Federal Trade Commission monitors marketing claims around depth ratings to prevent consumer deception. Stakeholders must monitor how diver certification agencies align equipment requirements with emerging smartwatch depth-tracking capabilities.
Market Dynamics
Swiss Jura and Japanese manufacturing corridors concentrate ISO 6425-certified production capacity, creating supply-side bottlenecks as NATO military procurement programs expand validation requirements for professional dive equipment.
Growth Catalysts
- REACH nickel-release limits:EU case alloy restrictions accelerate ceramic bezel and titanium case adoption across European distribution channels.
- Saturation diving operations:Commercial diving contractors in the North Sea and Gulf of Mexico mandate helium escape valve technology for extended-depth occupational use.
- Silicon balance springs:Anti-magnetic properties and extended service intervals attract mechanical watch collectors seeking reduced maintenance costs.
Market Restraints
- Swiss movement component scarcity:Nivarox hairspring and escapement wheel supply concentrates among three component houses, creating input volatility for mid-tier assemblers.
- ISO 6425 certification costs:Pressure-testing equipment and third-party validation fees exceed $50,000 per reference, blocking small-batch manufacturers from professional-tier positioning.
- Smartwatch depth-tracking substitution:Garmin and Apple algorithms displace entry-level mechanical diver demand among recreational snorkelers and pool swimmers.
Strategic Opportunities
- Indian coastal patrol modernization:Indian Navy and Coast Guard equipment tenders specify ISO-certified dive watches for combat swimmer units, opening defense procurement channels.
- EU Green Deal material incentives:Recycled ocean plastic straps and solar-powered movements qualify for sustainable product labeling in German and French retail.
- Direct-to-collector platforms:Limited-edition drops through manufacturer-owned channels bypass wholesale margin compression and capture full retail value.
Industry Challenges
- Escapement finisher skill scarcity:Swiss établissage networks report 15-year training gaps for hairspring adjustment and chronometer regulation specialists.
- Dual certification timelines:Simultaneous ISO 2281 and ISO 6425 validation requires 18-24 month development cycles, delaying product launches against smartwatch refresh rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Resistant Watch Market |
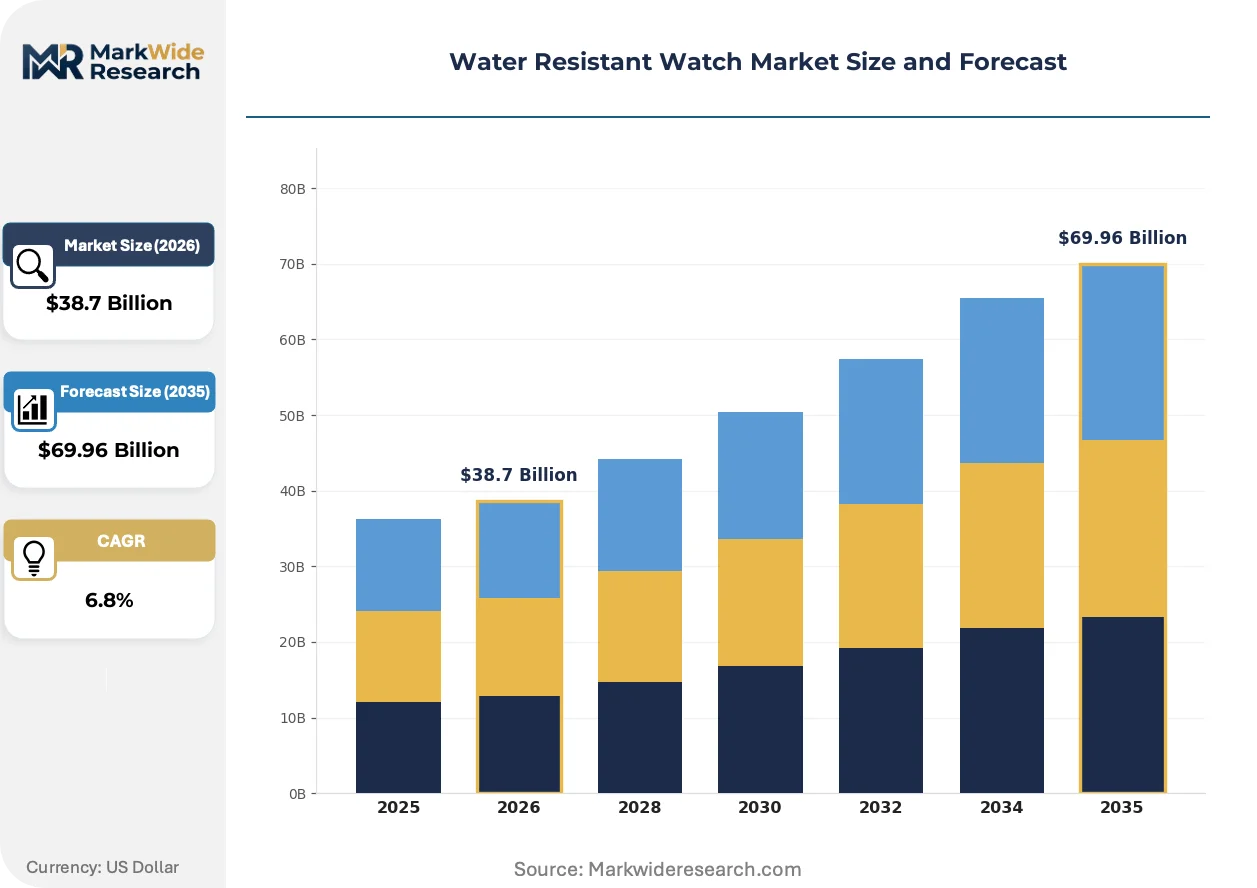
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Hybrid, Smartwatch Material: Stainless Steel, Plastic, Rubber, Titanium End User: Men, Women, Athletes, Divers Technology: Quartz, Mechanical, Solar, Smart |
| Companies Covered | Casio, Rolex, Omega, Seiko, Patek Philippe, Oris, Grand Seiko, Girard-Perregaux, IWC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Resistant Watch Market Trends and Innovations
Material science and connected depth sensing are fragmenting the traditional mechanical diver category into distinct performance tiers, with certification standards struggling to keep pace with hybrid functionality claims.
Ceramic bezel insert technology is bifurcating the professional watch segment. Scratch-resistant zirconium dioxide eliminates aluminum bezel fade in saturation environments. Commercial diving contractors and military procurement officers specify ceramic for mission-critical equipment. This material shift compresses margin pools for legacy aluminum bezel suppliers while opening premium positioning for integrated ceramic-case manufacturers.
EU REACH nickel-release enforcement tightens case alloy specifications for skin-contact components. ECHA compliance deadlines force reformulation of 316L stainless steel surface treatments. German and Austrian retailers now require material safety documentation for all watches sold through duty-free channels, shifting sourcing toward titanium and ceramic case architectures.
Collector purchasing patterns fragment across authentication-driven resale platforms. Chrono24 and WatchBox unbundle traditional authorized dealer relationships for discontinued references. Japanese and Singaporean buyers dominate transaction volume for vintage Seiko and Rolex Submariner variants, compressing geographic arbitrage opportunities that previously sustained European gray-market dealers.
Water Resistant Watch Market Segmentation
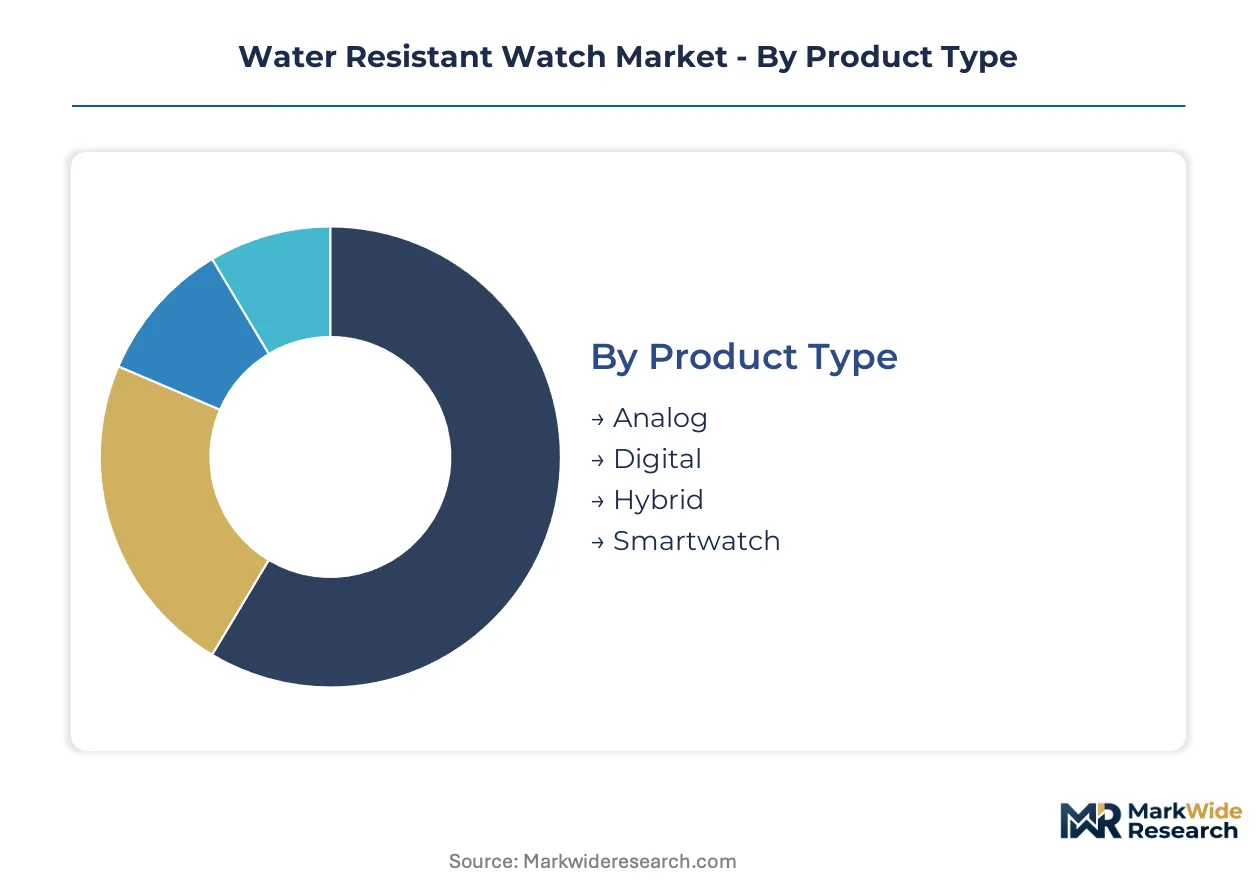
Water resistant watch segmentation reveals divergent margin architectures across mechanical prestige tiers and connected entry-professional categories. Certification standards and material costs fragment pricing power unevenly across product types and end-use applications.
Product Type:
Margin pools concentrate in mechanical analog references where Swiss and Japanese manufacturers command premium positioning through in-house escapements and extended service intervals.
- Analog:Mechanical and quartz-driven three-hand displays with sealed case assemblies dominate professional dive certification tiers. NATO military procurement programs in member states specify ISO 6425-certified analog references for combat swimmer equipment, sustaining volume through defense channels.
- Smartwatch:Integrated depth sensors and dive computer algorithms are displacing entry-level mechanical diver demand among recreational users. Garmin and Apple capture expanding share in recreational snorkeling and pool swimming segments through algorithmic depth-tracking capabilities.
- Digital:LCD and LED displays with module-based architectures serve price-sensitive recreational segments.
- Hybrid:Analog-digital combinations target transitional users seeking traditional aesthetics with connected functionality.
The dominant share belongs to Analog, while Smartwatch is closing the gap fastest.
Material:
Cost tier differentiation separates aerospace-grade titanium and ceramic constructions from commodity stainless steel mid-tier positioning.
- Stainless Steel:316L and 904L alloys remain the workhorse material for mid-tier professional watches, though EU REACH nickel-release enforcement tightens surface treatment specifications. German and Austrian retailers now require material safety documentation for skin-contact components, shifting formulation requirements.
- Titanium:Grade 2 and Grade 5 alloys reduce wrist fatigue for saturation divers in North Sea and Gulf of Mexico commercial operations. ECHA compliance deadlines accelerate titanium case adoption across European distribution channels seeking nickel-free alternatives.
- Plastic:Resin and polymer cases serve entry-level recreational and children's segments.
- Rubber:Silicone and natural rubber straps dominate aquatic sport applications for grip and comfort.
Stainless Steel retains volume leadership, though Titanium exhibits the steepest expansion trajectory among professional-tier suppliers.
End User:
Application intensity varies sharply between occupational diving contractors requiring helium escape valve technology and casual recreational users.
- Divers:Commercial saturation diving contractors and military combat swimmer units mandate ISO 6425-certified equipment with helium escape valve technology. Indian Navy and Coast Guard equipment tenders specify certified dive watches for modernization programs, opening defense procurement channels.
- Athletes:Triathletes and open-water swimmers drive demand for integrated GPS and heart rate depth compensation. Garmin dominates this segment through multi-sport algorithm architectures.
- Men:Traditional case sizing and lug-to-lug proportions anchor volume in established markets.
- Women:Smaller case diameters and fashion-forward aesthetics expand addressable market in Asian retail networks.
Divers command the highest per-unit margins, while Athletes deliver the fastest volume climb among end-user categories.
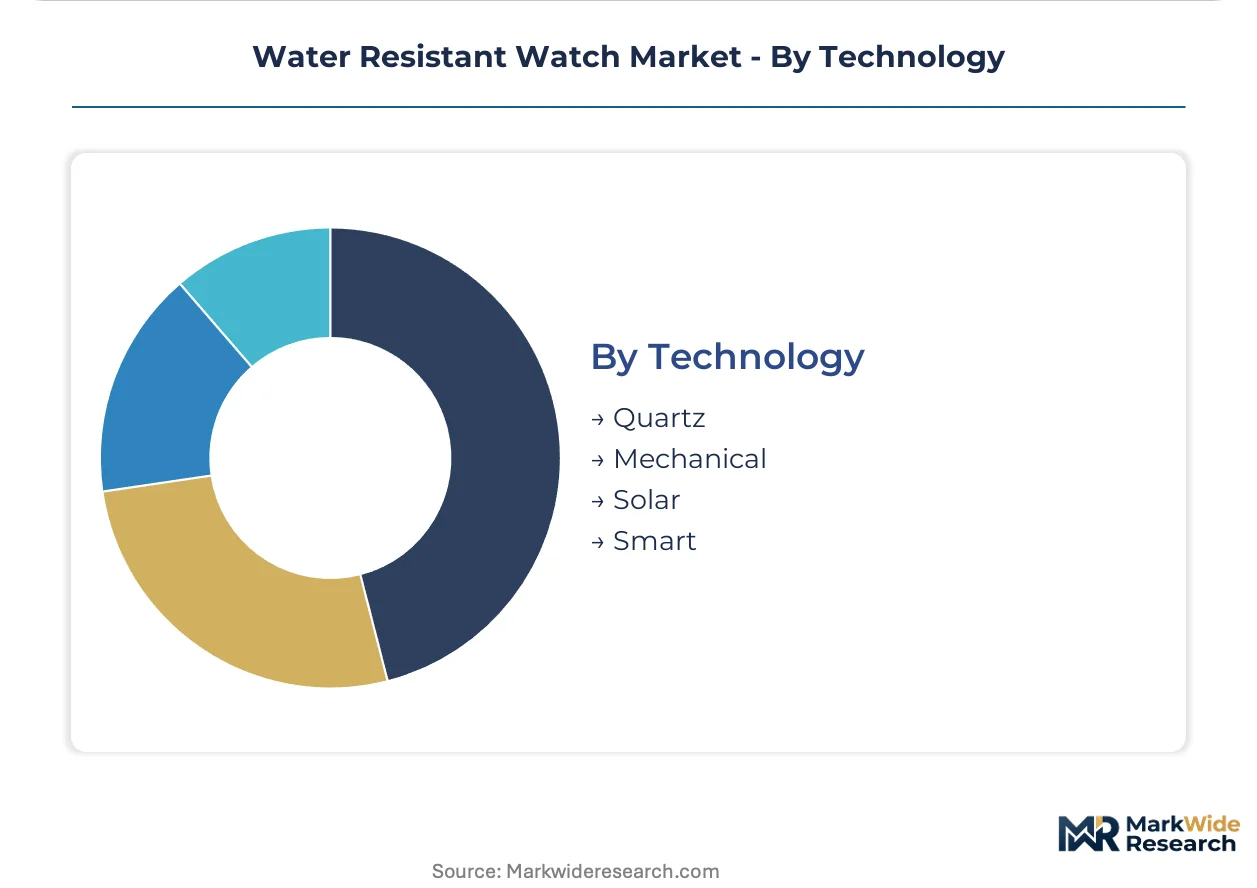
Technology:
Supply concentration in Swiss établissage networks creates bottlenecks for mechanical technology while smart technology scales through consumer electronics manufacturing corridors.
- Mechanical:In-house escapements and silicon balance springs attract collectors seeking anti-magnetic properties and reduced maintenance costs. Swiss Jura watchmaking clusters concentrate production capacity, creating 15-year training gaps for hairspring adjustment specialists.
- Smart:Depth sensors, dive computer algorithms, and cellular connectivity represent the fastest-expanding segment. Apple and Garmin integrate occupational-grade tracking into wrist-worn form factors, compressing development cycles against traditional mechanical certification timelines.
- Quartz:Battery-powered oscillators sustain accessible price points for mass-market distribution.
- Solar:Photovoltaic cells and extended power reserves qualify for EU Green Deal sustainable product labeling in German and French retail.
Mechanical technology retains prestige-tier dominance, yet Smart is gaining share fastest among recreational and fitness-oriented users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances favor established watchmaking economies with deep component ecosystems over assembly-only jurisdictions. Switzerland and Japan maintain substantial trade surpluses in finished timepieces, while emerging markets absorb imports to satisfy defense and recreational demand growth.
Switzerland
Swiss Jura watchmaking clusters concentrate ISO 6425-certified production capacity for NATO military procurement programs. Swissmedic oversees medical device adjacent regulations that influence occupational dive equipment standards. Geneva and Neuchâtel cantons anchor prestige-tier mechanical assembly, with component houses supplying hairsprings and escapements to domestic brands.
Japan
METI industrial policy supports precision manufacturing corridors in Nagoya and Tokyo where Seiko and Casio maintain integrated production. Japan's national regulator aligns consumer product safety frameworks with ISO dive watch testing protocols. Shizukuishi and Morioka host specialized mechanical movement workshops serving Prospex and Grand Seiko lines.
United States
FTC enforcement of depth-rating marketing claims shapes how brands position water resistance specifications for recreational divers. The US absorbs substantial Swiss and Japanese imports while domestic assembly concentrates in California and Florida for smartwatch integration. Garmin's Kansas operations exemplify algorithm-driven depth-tracking development displacing entry mechanical demand.
India
Indian Navy and Coast Guard equipment tenders specify ISO-certified dive watches for combat swimmer modernization programs. BIS standards govern import quality verification for professional diving equipment. Mumbai and Chennai distribution channels channel defense procurement while domestic assembly remains limited to basic quartz modules.
Germany
ECHA REACH nickel-release enforcement tightens case alloy specifications across German and Austrian retail networks. The KBA automotive regulator's materials testing protocols indirectly influence dive watch durability standards. Frankfurt and Munich duty-free channels now require material safety documentation, accelerating titanium and ceramic sourcing shifts.
Water Resistant Watch Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and material architectures. The vendor base separates into consolidated Swiss prestige houses, diversified Japanese electronics conglomerates with watch divisions, and independent mechanical specialists. Three archetypes dominate: vertically integrated manufactures controlling in-house escapement production, établissage assemblers sourcing from component houses, and consumer electronics platforms integrating dive algorithms. Competitive moves concentrate on ceramic bezel supply chain capture and direct-to-collector distribution platform construction.
Within the prestige mechanical tier, Rolex and Patek Philippe exemplify vertically integrated manufacturing archetypes with captive case and movement production. Casio represents the diversified electronics conglomerate model, leveraging shock-resistant module architectures across price tiers. Omega occupies a position bridging Swiss manufacture heritage with professional diving certification leadership. These three anchors demonstrate how certification depth, material innovation, and distribution control separate margin pools.
| Leading Market Players |
|---|
| Casio |
| Rolex |
| Omega |
| Seiko |
| Patek Philippe |
| Oris |
| Grand Seiko |
| Girard-Perregaux |
| IWC |
| Others |
Pricing and Supply Chain Analysis
ISO 6425 certification gates simultaneously constrain supply qualification and stratify price tiers, forcing manufacturers to absorb pressure-testing equipment costs while commanding premium positioning for validated references. This dual gating mechanism compresses margin pools for uncertified assemblers while amplifying pricing power for Swiss and Japanese houses with captive validation infrastructure.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification depth and material architecture, with helium escape valve technology and ceramic bezel construction commanding substantial premiums over aluminum-equipped references. Cost compression in the entry-professional tier is intensifying because Garmin and Apple algorithms displace mechanical demand among recreational users. Defense procurement officers exhibit the lowest price sensitivity, while pool swimmers and snorkelers drive aggressive discounting in mass retail channels.
Supply Chain Analysis
Swiss Jura component houses underwrite mechanical movement supply through concentrated hairspring and escapement production. Manufacturing draws from Swiss établissage networks, Japanese integrated corridors, and Chinese assembly operations for digital modules. Single-source vulnerability concentrates in Nivarox hairspring supply among three component houses. Distribution runs through authorized dealer networks, direct-to-collector platforms, and duty-free channels in Frankfurt and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water resistant watch demand sits in early-cycle expansion as NATO military procurement programs and Indian defense modernization accelerate ISO 6425-certified equipment adoption.
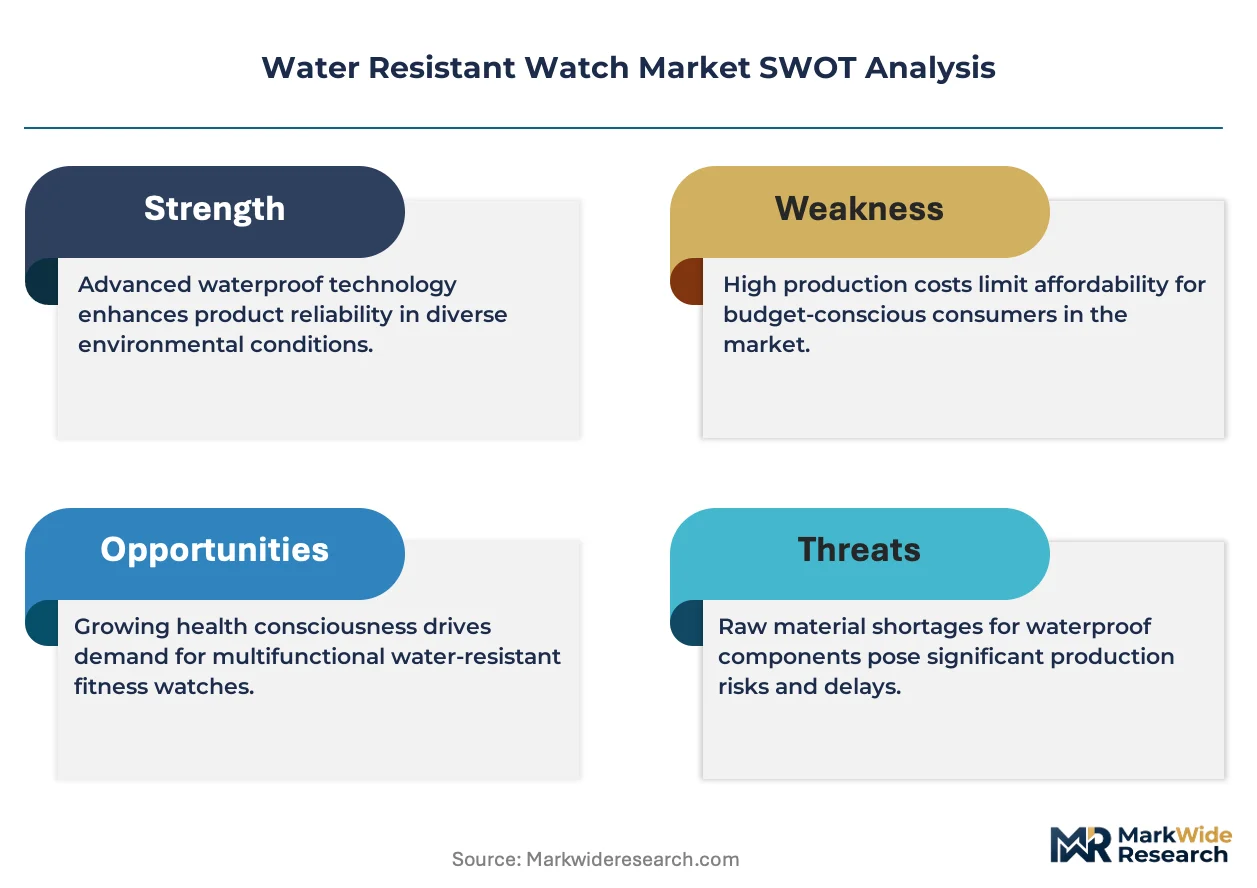
For Market Incumbents: Compound certification depth through helium escape valve technology investment and ceramic bezel supply chain capture. Smartwatch algorithm substitution threatens entry-professional mechanical volume, requiring incumbents to deepen backward integration into case manufacturing and tighten direct-to-collector channel control against gray-market erosion. For New Entrants and Emerging Players: ISO 6425 fast-track partnerships with established testing laboratories open defense procurement channels without 18-24 month validation cycles. White-space concentrates in Indian Navy and Coast Guard equipment tenders, EU Green Deal sustainable labeling qualification, and solar-powered movement integration for German retail. Go-to-market should leverage limited-edition drops through manufacturer-owned platforms to bypass wholesale margin compression. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed Swiss établissage assemblers lacking in-house escapement production. Long-term viability favors vertically integrated manufactures with captive case and movement capacity over component-dependent mid-tier positioning. Watch silicon balance spring adoption rates as inflection indicator for mechanical technology defensibility against smartwatch displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Bezel Supply Integration | Captures margin pool from aluminum legacy suppliers while satisfying NATO military procurement specifications. |
| ISO 6425 Certification Fast-Track | Accelerates defense channel entry against 18-24 month traditional validation timelines. |
| Direct-to-Collector Platform Launch | Bypasses wholesale compression and captures full retail value through limited-edition drops. |
| Helium Escape Valve Technology Investment | Qualifies equipment for North Sea and Gulf of Mexico saturation diving contractor mandates. |
| Solar-Powered Movement Development | Qualifies for EU Green Deal sustainable product labeling in German and French retail channels. |
Research Methodology
Desk research of trade customs data, SEC filings from listed watch groups, and ISO certification registries preceded structured interviews with Swiss établissage network managers, NATO defense procurement officers, commercial diving contractor equipment supervisors, and German duty-free retail buyers. Secondary validation drew from Swissmedic device-adjacent regulations, ECHA REACH compliance databases, and BIS import quality verification records. Bottom-up assembly cost modeling and top-down trade flow analysis were triangulated against primary field intelligence.
Variance decomposition across mechanical prestige, smart connected, and entry-professional tiers shaped volume and value outputs throughout the forecast period. Segmentation dimensions included product type, material architecture, end-use application intensity, and technology category. CAGRs were derived from trade flow trajectories and defense procurement pipeline analysis, with silicon balance spring adoption curves and smartwatch depth-tracking penetration rates serving as key technology displacement inputs.
The analysis sits within stated boundaries; outcomes outside sustained NATO military spending trajectories and EU REACH enforcement intensity would require recalibration. Forecasts reflect documented assumptions around certification timeline stability and component house supply continuity. Practitioners should keep alternative scenarios live as smartwatch algorithm accuracy and defense procurement budget allocations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Pet Wearable Market
Wearable Technology
Consumer Grade Smart Wearable Device Market
Wearable Technology
Global Smart Watch Market
Wearable Technology
Smart Necklace Market
Wearable Technology
India Smart Wearable Market
Wearable Technology
Electronic Underwear Market
Wearable Technology
Smart Pet Wearable Product Market
Wearable Technology
Android Wearable Computer Market
Wearable Technology
Asia-Pacific Wearable Technology Market
Wearable Technology
Wearable AI Devices Market
Wearable Technology
Wearable Technology and IoT Wearable Device Market
Wearable Technology
Wearable Computing Market
Wearable Technology
Smart Bra Market
Wearable Technology
Wearable Camera Market
Wearable Technology
Europe Smart Watches Market
Wearable Technology
Middle East and Africa Smartwatch Market