
 Android Wearable Computer Market | 2026-2036
Android Wearable Computer Market Size, Share, and Industry Trends Forecast 2026-2036
Android Wearable Computer Market Insights
On-device generative AI inference is rewriting how wearable architectures balance cloud dependency against battery life and latency. Samsung Electronics leverages its vertically integrated Exynos chipset and display divisions to sustain end-to-end control over smartwatch BOM costs. Google anchors the software layer through Wear OS, while Garmin differentiates in ruggedized outdoor segments where GPS precision and solar charging dominate purchasing criteria.
An Android wearable computer denotes a body-worn computing device running a Google-derived operating system, typically incorporating ARM-based SoCs with sub-1W thermal envelopes, MEMS accelerometers, and PPG optical sensors for continuous physiological monitoring, designed to deliver ambient information access and health telemetry without requiring handheld interaction. Smartwatches command the largest revenue pool as consumers replace traditional timepieces with notification-capable health companions, while health monitors capture the steepest growth trajectory as hypertension and glucose-monitoring wearables secure regulatory clearances for non-invasive use. Fitness trackers occupy a mature, price-compressed tier where Amazfit and Xiaomi compete on hardware margins below thirty dollars.
FDA software-as-medical-device oversight and the EU AI Act's risk-classification framework for health algorithms are forcing manufacturers to revalidate algorithmic outputs across skin-tone spectrums and activity contexts before commercial release. China's NMPA has accelerated review timelines for Class II wearable medical devices, creating parallel pathway complexity for multinationals seeking synchronized launches. Stakeholders must decide whether to architect single-SKU global platforms or fragment hardware variants around jurisdiction-specific sensor calibrations and certification requirements.
Market Dynamics
On-device generative AI inference is forcing a fundamental recalculation of how wearable architectures balance cloud dependency against battery life and latency, compelling SoC designers to reallocate die area toward neural processing units while maintaining sub-1W thermal envelopes.
Growth Catalysts
- FDA Software-as-Medical-Device Pathways:The FDA's streamlined oversight for algorithm-based diagnostics accelerates commercialization of clinical-grade biosensing wearables, enabling continuous glucose and blood pressure monitoring to migrate from hospitals to consumer wrists.
- MEMS Sensor Miniaturization:Advances in microelectromechanical systems allow multi-axis accelerometers and gyroscopes to occupy sub-10mm³ volumes, freeing physical space for larger battery cells and additional optical sensors.
- South Korean Display Manufacturing:Concentrated capacity in Gumi and Tangjeong for low-temperature polysilicon OLED panels reduces display module costs and shortens lead times for smartwatch OEMs.
Market Restraints
- ARM SoC Supply Concentration:Foundry dependency on TSMC's 4nm and 5nm nodes for sub-watt wearable processors creates vulnerability to geopolitical disruption and capacity allocation decisions favoring higher-margin smartphone chips.
- Lithium-Polymer Cell Chemistry:Energy density limitations in curved and ultra-thin battery form factors constrain multi-day runtime for always-on display configurations, forcing trade-offs between feature activation and charge cycles.
- EU AI Act Risk Classification:The European Union's tiered regulatory framework for health algorithms imposes pre-market conformity assessments that extend certification timelines and increase validation costs for biometric inference models.
Strategic Opportunities
- India's PLI Scheme for Wearables:Production-linked incentives for electronics manufacturing attract final assembly investment, creating localized supply capacity for price-sensitive entry-tier devices.
- Solar-Assisted Charging Integration:Convergence of photovoltaic cell efficiency gains with low-power display technologies enables indefinite field operation for outdoor-focused form factors.
- Telehealth Platform Integration:Direct API connections between wearable data streams and remote patient monitoring systems open recurring revenue models for chronic disease management outside traditional clinical settings.
Industry Challenges
- Multi-Jurisdiction Certification Parallelism:Simultaneous navigation of FDA 510(k), EU MDR, and China NMPA review timelines forces duplicate clinical validation studies and fragmented firmware versioning.
- Optical Sensor Calibration Talent:Scarce expertise in photoplethysmography signal processing across diverse skin tone and perfusion conditions limits algorithmic accuracy for melanin-rich populations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Android Wearable Computer Market |
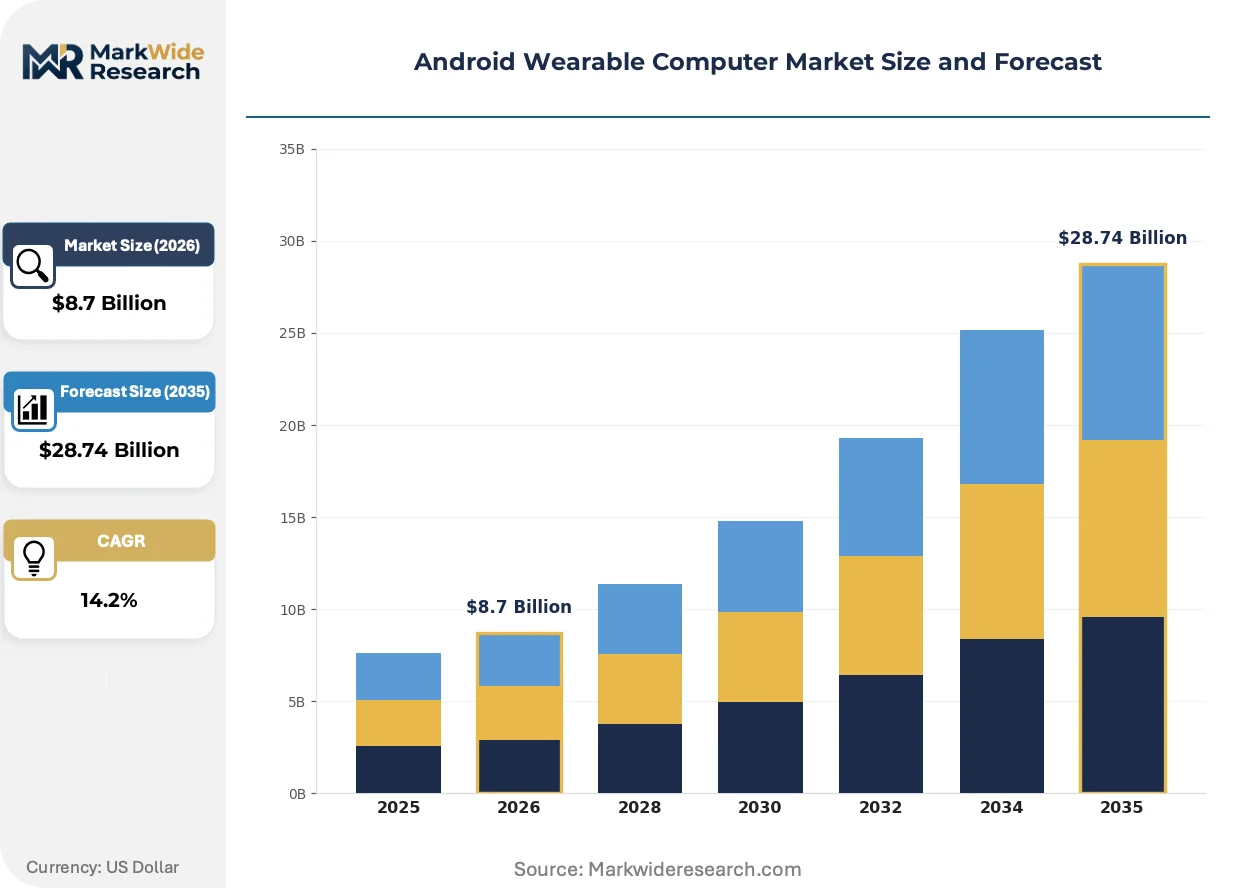
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Health Monitors, Smart Glasses End User: Fitness Enthusiasts, Healthcare Professionals, Tech Savvy Consumers, Enterprises Technology: Bluetooth, Wi-Fi, NFC, GPS Application: Health Monitoring, Communication, Navigation, Entertainment |
| Companies Covered | Samsung Electronics, Google, Huawei Technologies, Xiaomi Corporation, Garmin, Sony Corporation, LG Electronics, Imagine Marketing, Amazfit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Android Wearable Computer Market Trends and Innovations
Clinical-grade physiological monitoring is migrating from dedicated medical devices to ambient wrist-worn platforms, compressing the distinction between consumer wellness and regulated diagnostics while forcing new competency requirements upon consumer electronics supply chains.
Photoplethysmography-based blood pressure estimation is migrating from research prototypes to commercial wearables. Samsung and Huawei have secured regulatory clearances for cuffless hypertension monitoring in select Asian markets. The technology is migrating from laboratory oscillometric validation to continuous ambulatory measurement, enabling pharmaceutical trials and cardiovascular risk stratification without clinic visits.
The EU AI Act's risk-based classification framework for health algorithms is tightening validation requirements for biometric inference models deployed in European markets. Manufacturers must now document performance across demographic subgroups and activity contexts before CE marking. Wearables incorporating arrhythmia detection or fall-risk assessment face heightened scrutiny, prompting some OEMs to disable AI features in EU firmware builds pending compliance.
Enterprise procurement of wearable fleets for occupational safety and logistics workforce management is displacing individual consumer purchases as the dominant volume channel in industrialized economies. Amazon warehouse operations and DHL last-mile delivery networks deploy ruggedized Android wearables for task routing and biometric fatigue monitoring. Germany's KBA and France's labor inspectorates are developing guidelines for employer-mandated physiological tracking, creating regulatory precedents for workplace biometric consent frameworks.
Android Wearable Computer Market Segmentation
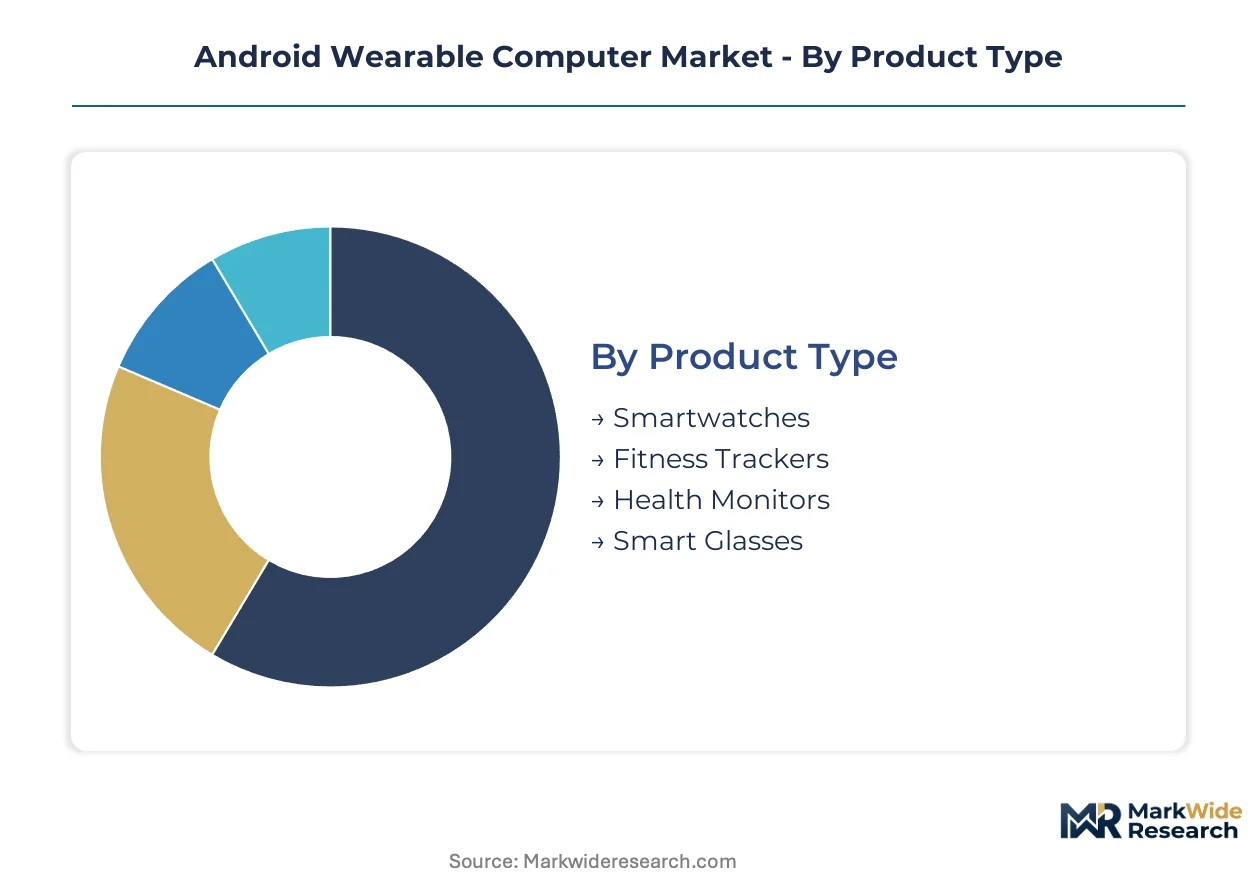
Segmentation in the Android wearable computer market reveals how hardware specifications, connectivity protocols, and use-case intensity create divergent margin profiles and replacement cycles across consumer and enterprise channels.
Product Type:
Replacement cycles stretch from annual smartwatch refreshes to multi-year enterprise deployments, compressing or extending revenue recognition windows depending on form factor durability and software support lifespans.
- Smartwatches:Full-featured wrist-worn computers with AMOLED displays, multi-day batteries, and cellular variants. Demand concentrates among tech-savvy consumers in the United States and South Korea where carrier-subsidized upgrades accelerate turnover. Samsung's Exynos W series and Qualcomm's Snapdragon Wear platforms define the silicon layer.
- Health Monitors:Clinical-grade biosensing devices with FDA-cleared algorithms for blood pressure and glucose estimation. Healthcare professionals in Germany and Japan drive procurement as remote patient monitoring reimburses under national insurance frameworks. Regulatory validation timelines extend development cycles versus consumer wearables.
- Fitness Trackers:Stripped-down activity sensors with sub-$50 price points and 7-14 day battery life. Xiaomi and Amazfit dominate volume in India and Southeast Asia where price sensitivity outweighs display quality demands.
- Smart Glasses:Optical see-through displays with waveguide optics and camera modules for hands-free data overlay. Enterprise logistics and field service applications in the United States pilot deployments for warehouse picking and remote assistance.
Smartwatches dominate installed base. Health monitors are where expansion concentrates.
End User:
Procurement authority separates individual purchasing decisions from enterprise IT departments with security compliance requirements and fleet management infrastructure.
- Tech Savvy Consumers:Early adopters prioritizing notification integration, third-party app ecosystems, and design aesthetics. Concentrated in urban United States and Chinese markets where smartphone brand loyalty transfers to wearable purchases.
- Healthcare Professionals:Physicians and nurses deploying clinical-grade wearables for patient monitoring and diagnostic augmentation. Germany's KBA and France's labor inspectorates are developing employer-mandated tracking guidelines that will shape procurement standards.
- Fitness Enthusiasts:Amateur and semi-professional athletes demanding GPS precision, heart rate variability, and training load metrics. Garmin and Polar capture this segment in Nordic countries and Alpine regions with strong outdoor recreation cultures.
- Enterprises:Logistics, manufacturing, and healthcare employers outfitting workforces with ruggedized Android wearables for task routing, biometric fatigue monitoring, and lone-worker safety. Amazon warehouse operations and DHL last-mile networks represent reference deployments.
Tech savvy consumers anchor volume shipments. Enterprises are climbing the fastest as occupational safety regulations legitimize workplace biometric tracking.
Technology:
Connectivity protocol selection determines power budget allocation, antenna integration complexity, and cloud dependency architecture.
- Bluetooth:Low-energy 5.3 standard enabling sub-10mW idle states for continuous smartphone tethering. Ubiquitous across all price tiers as the baseline connectivity layer.
- GPS:Multi-constellation positioning with GLONASS, Galileo, and BeiDou augmentation for meter-level accuracy without smartphone dependency. Outdoor-focused form factors in Switzerland and Austria demand this capability for trail navigation and emergency location.
- Wi-Fi:802.11n/ac streaming for music, voice assistant queries, and firmware updates when Bluetooth range is insufficient. Adds 15-25% to bill-of-materials cost versus Bluetooth-only variants.
- NFC:Contactless payment and access control with secure element isolation for tokenized transactions. Transit integration with Suica in Japan and OMNY in New York City drives regional feature prioritization.
Bluetooth anchors every SKU. GPS is where silicon vendors differentiate premium tiers.
Application:
Software workload intensity ranges from passive sensor logging to real-time inference, dictating neural processing unit requirements and thermal design constraints.
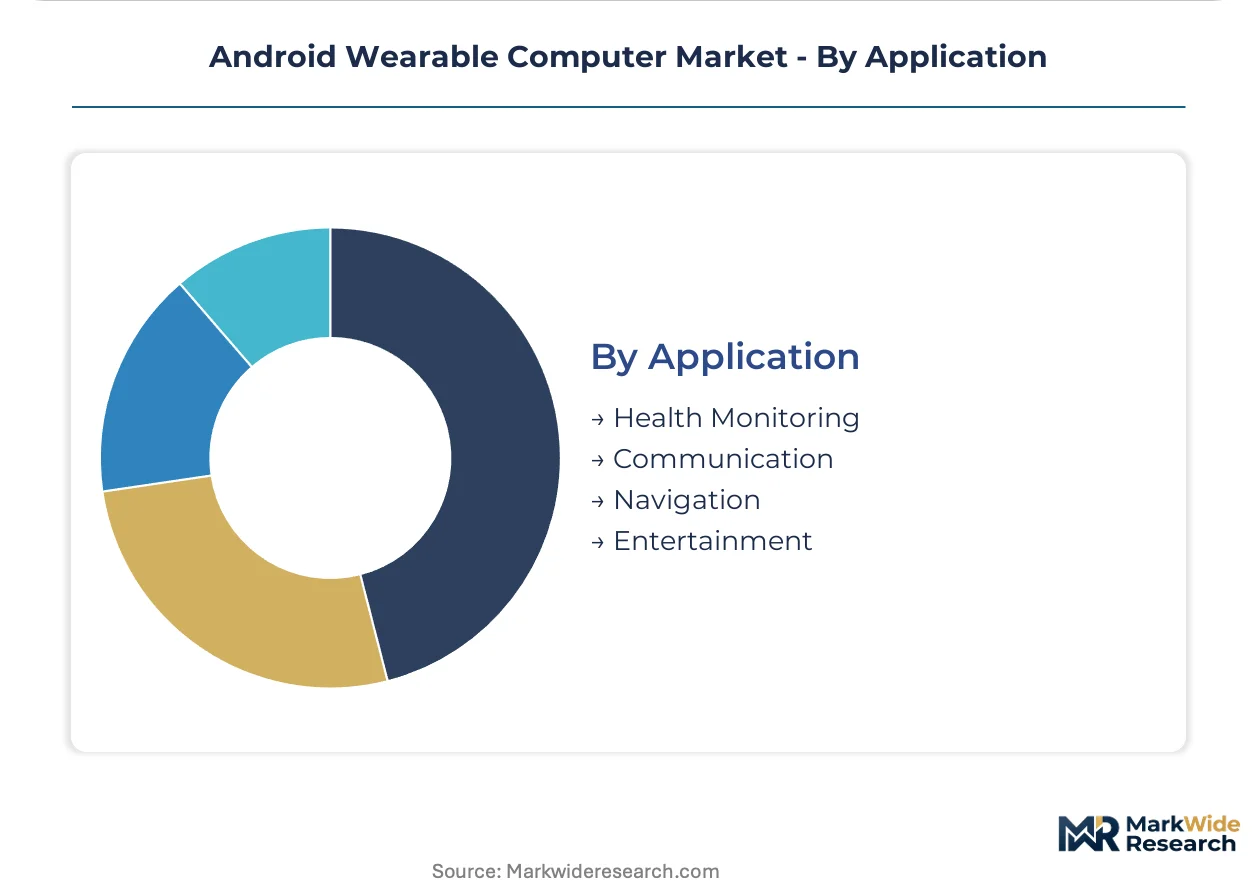
- Health Monitoring:Continuous photoplethysmography, accelerometry, and emerging bioimpedance sensing for cardiovascular and metabolic markers. FDA and EU MDR pathways govern algorithmic claims, fragmenting firmware builds by jurisdiction.
- Communication:Voice calls, messaging, and notification triage with on-device natural language processing. Google's Wear OS and Samsung's One UI Watch compete on assistant responsiveness and third-party messaging integration.
- Navigation:Turn-by-turn directions, offline map storage, and breadcrumb tracking for backcountry safety. Outdoor specialists in Colorado and Bavaria demand this functionality for ultramarathon and alpine applications.
- Entertainment:Offline music storage, podcast synchronization, and streaming audio with Bluetooth headphone pairing. Spotify and YouTube Music compete for default app placement on Wear OS devices.
Health monitoring dominates R&D investment. Communication retains the broadest daily active usage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare professionals and tech-savvy consumers concentrate purchasing power in the United States, Germany, China, South Korea, and Japan. Carrier-subsidized upgrades accelerate turnover in Seoul and San Francisco. Regulatory fragmentation forces firmware versioning across jurisdictions.
United States
Tech-savvy consumers drive smartwatch turnover through carrier-subsidized upgrade cycles. FDA software-as-medical-device pathways accelerate commercialization of clinical-grade biosensing wearables. Silicon Valley and Austin anchor development clusters for health algorithm validation.
Germany
Healthcare professionals procure clinical-grade wearables for remote patient monitoring under reimbursable national insurance frameworks. The KBA develops employer-mandated tracking guidelines for workplace biometric consent. Munich and Berlin concentrate medical device certification expertise.
China
Component sourcing and final assembly capacity concentrate in Shenzhen and Dongguan. The NMPA accelerates review timelines for Class II wearable medical devices. Shanghai and Beijing host algorithm development centers for photoplethysmography signal processing.
South Korea
Display manufacturing clusters in Gumi and Tangjeong supply low-temperature polysilicon OLED panels to global smartwatch OEMs. The MFDS regulates clinical-grade biosensing claims for domestic and export markets. Seoul anchors Exynos chipset design and vertically integrated supply chains.
Japan
Transit-integrated NFC payments through Suica drive feature prioritization for contactless wearables. METI oversees standards for biometric data handling in employer-mandated deployments. Tokyo and Osaka concentrate optical sensor calibration expertise for diverse skin tone populations.
Android Wearable Computer Market Competitive Landscape
Channel-controlling players compete with product-specialist players for positioning across premium and entry-tier segments. Samsung Electronics and Google anchor the consolidated tier through vertically integrated hardware-software stacks. Garmin and Amazfit occupy specialist niches in ruggedized outdoor and price-compressed fitness segments. Competitive moves concentrate on M&A for algorithm talent and capacity expansion in South Korean display manufacturing.
Within the vertically integrated tier, Samsung Electronics exemplifies end-to-end control over chipset and display supply. Google anchors software layer positioning through Wear OS licensing. Garmin occupies the specialist archetype in outdoor-focused form factors where GPS precision dominates purchasing criteria.
| Leading Market Players |
|---|
| Samsung Electronics |
| Huawei Technologies |
| Xiaomi Corporation |
| Garmin |
| Sony Corporation |
| LG Electronics |
| Imagine Marketing |
| Amazfit |
| Others |
Pricing and Supply Chain Analysis
Shenzhen and Dongguan manufacturing clusters anchor global component sourcing and final assembly capacity, concentrating cost leverage among vertically integrated OEMs while compressing margins for pure-play assemblers dependent on spot-market display and battery procurement.
Pricing Analysis
Cost-plus contracts with quarterly indexation to lithium-polymer cell and LTPS OLED wafer pricing dominate procurement between smartwatch OEMs and South Korean display suppliers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared health monitors from consumer wellness trackers and sub-thirty-dollar fitness bands. Price differentiation hinges on algorithmic certification tier and geographic delivery cost to carrier distribution channels. Cost compression in entry-tier fitness bands is intensifying because Xiaomi and Amazfit compete on hardware margins below component cost for market share capture. Enterprise fleet buyers exhibit lowest price sensitivity due to occupational safety compliance mandates, while Southeast Asian consumers drive highest elasticity.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn, Luxshare, and BYD Electronics holding final assembly capacity across Shenzhen, Dongguan, and Vietnam border zones. Component sourcing draws from South Korea for LTPS OLED panels, Taiwan for TSMC-fabricated 4nm and 5nm wearable SoCs, and China for MEMS sensors and lithium-polymer cells. Single-source vulnerability to TSMC capacity allocation decisions favoring higher-margin smartphone chips constrains sub-watt processor availability. Distribution runs through carrier-subsidized retail channels in the United States and South Korea, direct-to-consumer e-commerce in China and India, and enterprise IT procurement for occupational safety deployments in Germany and France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone-native health platforms and ambient sensing earbuds threaten to displace dedicated wrist-worn form factors, forcing incumbents to defend installed base through clinical-grade algorithm differentiation.
For Market Incumbents: Pre-empt smartphone ecosystem encroachment by securing FDA 510(k) and EU MDR clearances for continuous glucose and blood pressure estimation before Apple Health and Samsung Health consolidate remote patient monitoring data flows. Accelerate backward integration into photoplethysmography signal processing talent pools in Tokyo and Osaka to close algorithmic accuracy gaps across melanin-rich skin tones.
For New Entrants and Emerging Players: India's price-compressed wearable segment offers the most penetrable white space, where PLI scheme incentives and localized assembly capacity enable sub-twenty-dollar fitness trackers with seven-day battery life. Target enterprise occupational safety procurement in Germany's logistics and manufacturing sectors, where KBA-mandated biometric fatigue monitoring creates fleet-scale demand without consumer brand recognition requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors algorithm-specialist targets with EU AI Act compliance documentation and photoplethysmography calibration datasets spanning diverse demographics. Long-term viability rests on defensible regulatory moats rather than hardware margin capture. Monitor FDA software-as-medical-device submission velocity as inflection indicator for clinical-grade wearable commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Certification Investment | FDA 510(k) and EU MDR clearances for cuffless blood pressure monitoring enable reimbursement under German national insurance frameworks. |
| Photoplethysmography Talent Acquisition | Tokyo and Osaka calibration expertise closes accuracy gaps for melanin-rich populations under EU AI Act demographic performance requirements. |
| South Korean Display Capacity Expansion | Gumi and Tangjeong LTPS OLED investments reduce module costs and shorten lead times for smartwatch OEMs competing on refresh cycles. |
| Enterprise Fleet Management Integration | Direct API connections to Amazon warehouse and DHL last-mile dispatch systems open recurring revenue models outside consumer replacement cycles. |
| India PLI Scheme Localization | Production-linked incentives attract final assembly investment for price-sensitive entry-tier devices targeting Southeast Asian volume markets. |
Research Methodology
Operator-level perspectives from smartwatch platform engineers, FDA regulatory affairs specialists, hospital biomedical procurement managers, and carrier device portfolio directors anchored the qualitative base. Primary interviews combined with secondary validation from SEC 10-K filings, NMPA device registration databases, EU MDR notified body documentation, and customs trade data for lithium-polymer cell and MEMS sensor flows. Bottom-up unit shipment estimates by product tier and top-down revenue reconciliation against OEM reported segments enabled triangulation.
Scenario-bracketing around EU AI Act implementation timelines, FDA software-as-medical-device review velocity, and TSMC 4nm capacity allocation assumptions structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user procurement authority, connectivity protocol, and application workload intensity. CAGRs derived from logistic diffusion curves fitted to historical replacement cycle data and clinical-grade wearable regulatory approval trajectories. Forecast inputs incorporated photoplethysmography algorithm accuracy benchmarks and enterprise fleet deployment pipelines.
Practitioners should monitor FDA 510(k) submission backlogs, EU notified body MDR audit queue lengths, and TSMC quarterly earnings calls for foundry capacity reallocation signals as early revision triggers. Forecasts reflect assumptions around regulatory pathway stability and component supply continuity. Quarterly review of NMPA Class II device approval velocity and South Korean display panel pricing indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Smart Necklace Market
Wearable Technology
Battery for Children Smart Watch Market
Wearable Technology
Consumer Grade Smart Wearable Device Market
Wearable Technology
Wearable Computing Devices Market
Wearable Technology
3D Printed Wearables Market
Wearable Technology
US Pet Wearable Market
Wearable Technology
Europe Watch Market
Wearable Technology
Wearable Gaming Technology Market
Wearable Technology
Europe Smart Watches Market
Wearable Technology
UK Wearable Technology Market
Wearable Technology
APAC Smart Watch Market
Wearable Technology
Wearable Computing Market
Wearable Technology
Global Smart Watch Market
Wearable Technology
Global Smart Shoes Market
Wearable Technology
Smart Pet Wearable Product Market
Wearable Technology
Electronic Underwear Market