
 Global Smart Wearable Lifestyle Devices Market | 2026-2036
Global Smart Wearable Lifestyle Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart Wearable Lifestyle Devices Market Outlook
Embedded systems engineering talent is collapsing across Western Europe and North America, forcing brands to relocate hardware design centers to Shenzhen and Taipei. Apple Inc. leverages its vertical silicon stack to sustain margin control over premium smartwatch architectures. Samsung Electronics Co., Ltd. anchors global AMOLED display supply for wrist-worn form factors, while Garmin Ltd. dominates aviation-grade GPS integration in outdoor lifestyle wearables.
Smart wearable lifestyle devices encompass wrist-worn, head-mounted, and body-integrated electronics that capture biometrics, location data, and ambient environmental parameters through MEMS sensors, photoplethysmography optical arrays, and low-power Bluetooth SoCs operating below 10 milliwatts in standby. These systems primarily serve preventive health management, athletic performance optimization, and seamless digital identity authentication in consumer and enterprise settings. Smartwatches concentrate the largest installed base and recurring software revenue pools, whereas smart clothing represents the fastest-expanding frontier as conductive textile manufacturing matures. Fitness trackers occupy a contracting mid-tier position as feature convergence pushes consumers toward full-function smartwatches or ultra-low-cost bands.
FDA premarket notification requirements for pulse oximetry and ECG functions shape product development roadmaps for vendors seeking US market access, while EU MDR and GDPR impose parallel clinical validation and data sovereignty burdens across European distribution channels. China's NMPA and GB standards mandate domestic cybersecurity certification for biometric data collection, creating divergent compliance architectures. Stakeholders must monitor regulatory fragmentation between medical-grade and general wellness classifications to anticipate which feature sets unlock reimbursement pathways versus pure retail positioning.
Market Dynamics
Regulatory fragmentation between medical-grade and general wellness classifications is forcing vendors to maintain parallel product architectures, compressing R&D efficiency while expanding addressable reimbursement pools for continuous glucose monitoring and cardiac rhythm detection features.
Growth Catalysts
- Continuous glucose monitoring:Aging demographics in Japan and Germany are accelerating demand for non-invasive metabolic tracking wearables. FDA 510(k) clearance pathways for interoperable CGM systems are shortening commercialization timelines for Class II medical devices.
- Photoplethysmography optical arrays:Advances in multi-wavelength PPG sensors are enabling clinical-grade blood oxygen and blood pressure estimation without cuff inflation. Consumer adoption of SpO2-enabled smartwatches is expanding the preventive health data ecosystem.
- Shenzhen component clustering:Concentrated MEMS foundry and Bluetooth SoC packaging capacity in China's Pearl River Delta is reducing bill-of-materials costs for wrist-worn form factors. Taipei-based display driver IC design houses are accelerating AMOLED integration cycles.
Market Restraints
- Lithium-polymer cell volatility:Cobalt and lithium carbonate price swings are compressing gross margins on ultra-thin battery packs below 200 mAh capacity. Energy density limitations constrain multi-day runtime in full-function smartwatches.
- AMOLED supply concentration:Samsung Display Corporation controls approximately 85% of small-form-factor flexible OLED capacity, creating single-source dependency for premium smartwatch vendors seeking always-on display functionality.
- EU MDR clinical validation burdens:Expanded requirements for biocompatibility testing and post-market surveillance under the 2017/745 Medical Device Regulation are extending certification timelines for ECG and pulse oximetry features by 12-18 months.
Strategic Opportunities
- India budget fitness expansion:Price-sensitive consumers in tier-2 and tier-3 Indian cities are driving volume demand for sub-$25 connected bands with basic step counting and sleep staging. Domestic PLI scheme incentives for electronics manufacturing are attracting assembly investments.
- Conductive textile integration:Silver nanowire and graphene-coated fiber manufacturing maturity is enabling seamless biometric capture in athletic apparel. Garment-integrated EMG and hydration sensors are opening enterprise wellness program channels.
- FDA breakthrough device designation:Expedited review pathways for novel diagnostic algorithms are accelerating market access for AI-enabled arrhythmia detection. Reimbursement codes for remote patient monitoring are expanding B2B revenue streams.
Industry Challenges
- Embedded firmware engineering scarcity:Collapsing university pipeline for real-time operating systems and ultra-low-power Bluetooth stack optimization in Western Europe and North America is forcing hardware design center relocation to Shenzhen and Taipei.
- Multi-jurisdiction certification parallelism:Simultaneous pursuit of FDA 510(k), EU MDR, and China NMPA clearances for pulse oximetry features requires divergent clinical study designs and quality management system documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart Wearable Lifestyle Devices Market |
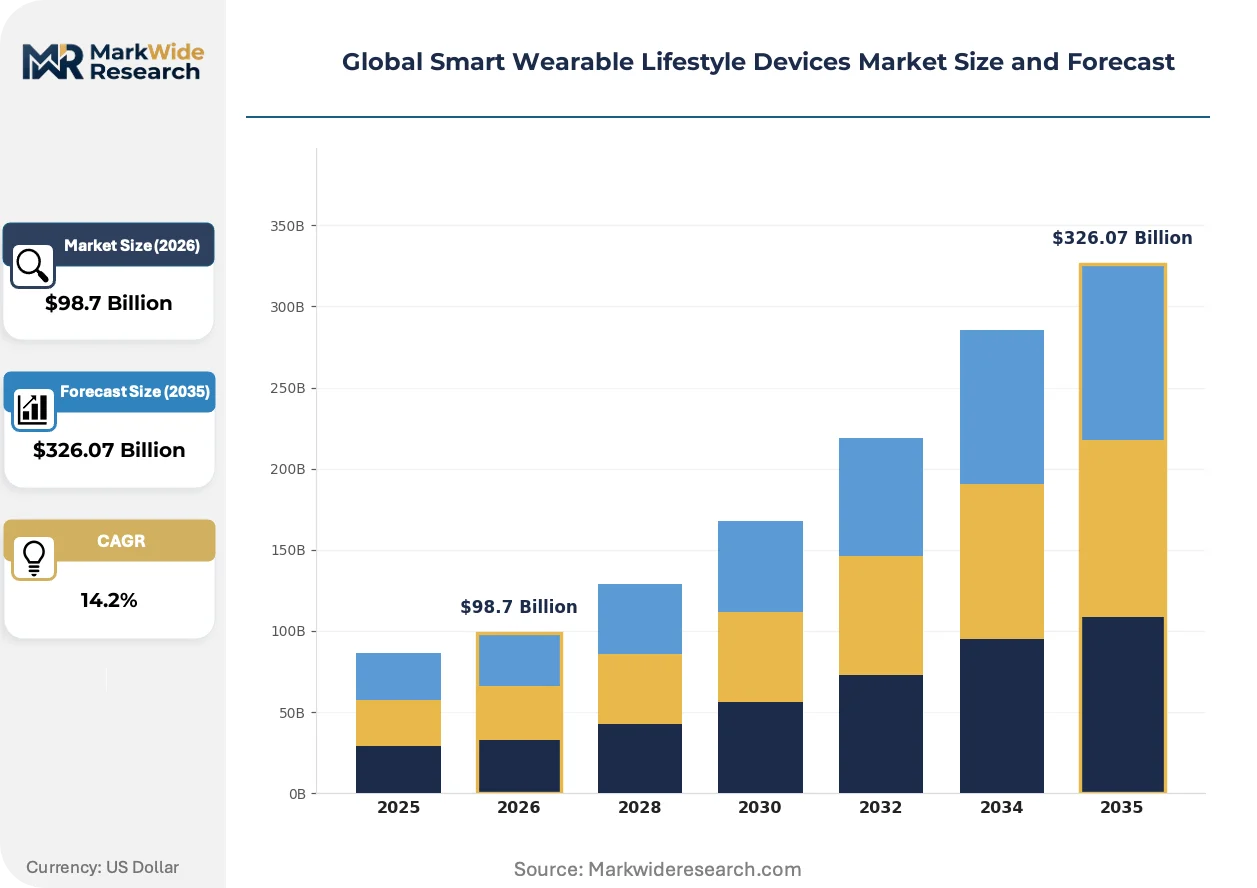
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $326.07 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Glasses, Smart Clothing Technology: Bluetooth, NFC, Wi-Fi, GPS End User: Fitness Enthusiasts, Health Monitors, Tech Consumers, Athletes Distribution Channel: Online Retail, Brick-and-Mortar, eCommerce, Direct Sales |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Garmin Ltd., Fitbit LLC, Huawei Technologies Co., Ltd., Xiaomi Corporation, Alphabet Inc., Zepp Health Corporation, Whoop, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart Wearable Lifestyle Devices Market Strategic Shifts
Silicon photonics integration and ambient energy harvesting are reshaping power architecture assumptions for always-worn biometric devices, while regulatory clarity on AI-enabled diagnostic algorithms is unlocking new reimbursement pathways.
Solid-state battery chemistries with lithium-metal anodes are miniaturizing energy storage footprints below 100 mm³ while maintaining 400+ mAh/g theoretical density. Premium smartwatch vendors are adopting these cells to enable multi-day always-on display operation without increasing chassis thickness. The structural consequence is compressing competitive differentiation around battery endurance metrics and enabling thinner industrial designs.
EU AI Act risk classification for biometric identification and emotion recognition systems is mandating conformity assessment procedures for wearables processing health data through cloud-based inference. Vendors must implement on-device processing architectures or establish EU-based data residency to avoid high-risk system designation. Smartwatch segments with facial analysis or stress detection features are most affected, accelerating edge AI accelerator integration in Nordic and Ambiq SoC roadmaps.
Employer-sponsored wellness program procurement is consolidating around integrated platform vendors rather than discrete hardware suppliers. Fortune 500 benefits administrators are demanding API interoperability with existing health plan infrastructure, displacing standalone fitness tracker vendors. This pattern is most visible in US self-insured employer markets where biometric data integration with claims analytics drives premium optimization.
Global Smart Wearable Lifestyle Devices Market Segmentation
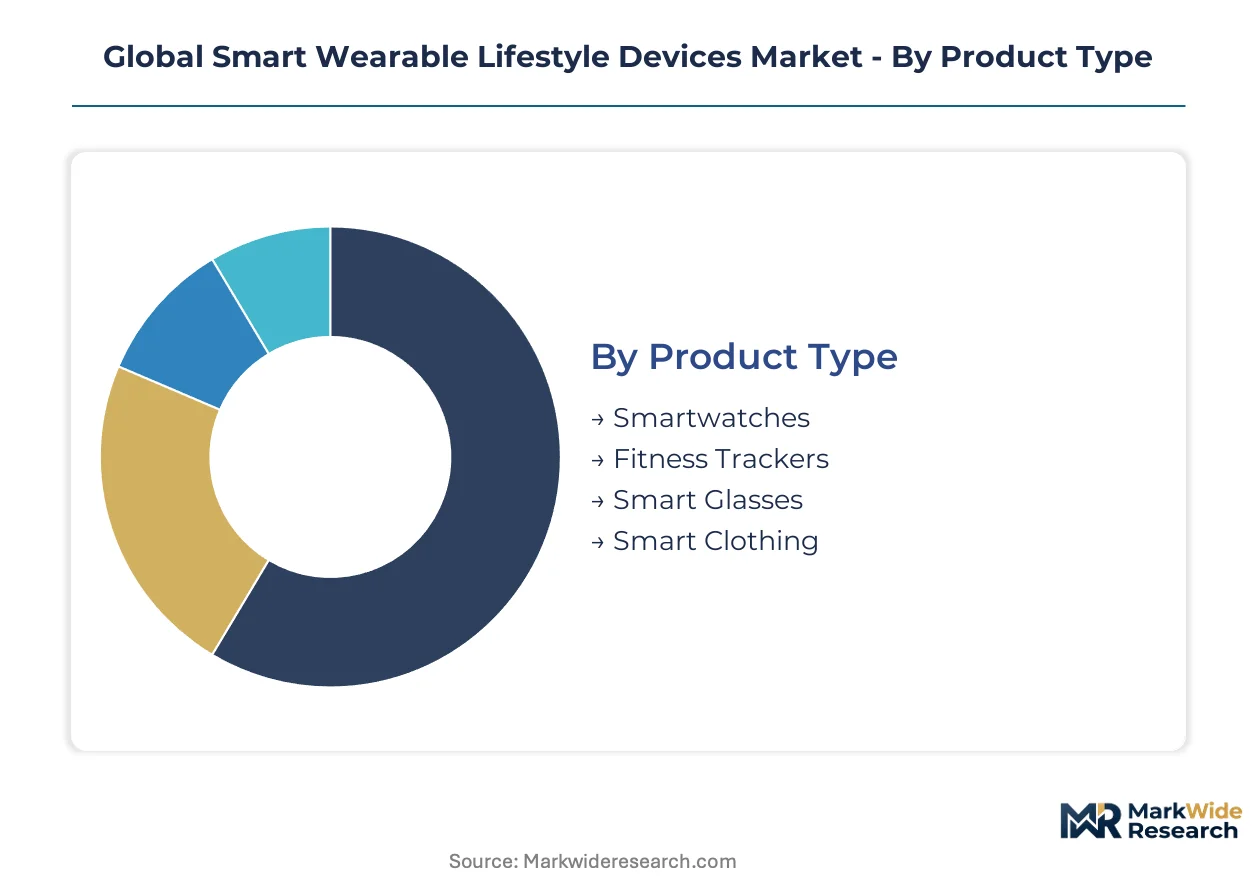
Segmentation in smart wearable lifestyle devices reveals distinct supply chain configurations, technology maturity curves, and regulatory exposure profiles. Understanding these divisions clarifies where component clustering, certification burdens, and pricing power concentrate across the value chain.
Product Type:
Smartwatches and fitness trackers flow through Shenzhen-dominated export manufacturing, while smart glasses and smart clothing retain heavier domestic engineering footprints in the US and Germany due to optical waveguide and conductive textile specialization.
- Smartwatches:Full-function wrist-worn computers integrating AMOLED displays, multi-wavelength PPG sensors, and application processors running real-time operating systems. Demand clusters in Japan and Germany for FDA-cleared ECG and blood glucose monitoring variants, where aging demographics seek preventive health integration. Samsung Display Corporation's near-monopoly on flexible OLED supply creates single-source dependency for always-on functionality.
- Smart Clothing:Garment-integrated electronics using silver nanowire or graphene-coated conductive fibers for EMG, hydration, and motion capture. Athletic apparel brands in the US and Germany are piloting enterprise wellness programs, though manufacturing scale remains constrained by textile-electronics assembly complexity.
- Fitness Trackers:Stripped-down biometric bands with basic accelerometry and optical heart rate, concentrated in sub-$25 price tiers for Indian tier-2 and tier-3 cities.
- Smart Glasses:Optical see-through and video-see-through head-mounted displays, currently enterprise-focused for logistics and field service applications.
Smartwatches hold the largest share; momentum sits with smart clothing.
Technology:
Connectivity architecture determines power budget allocation, with Bluetooth dominating sub-10 milliwatt standby requirements while GPS and Wi-Fi force larger battery footprints or reduced runtime.
- Bluetooth:Low-energy SoCs from Nordic Semiconductor and Ambiq enable sub-10 milliwatt standby operation for continuous biometric streaming. Shenzhen packaging houses drive bill-of-materials compression through concentrated MEMS foundry partnerships.
- GPS:Multi-constellation satellite receivers from u-blox and Broadcom enable meter-level positioning for outdoor activity tracking. Aviation-grade integration by Garmin anchors premium outdoor wearable positioning in US and German alpine recreation markets.
- NFC:Secure element integration for contactless payment and digital identity authentication, with tokenization requirements varying by jurisdiction.
- Wi-Fi:Higher throughput connectivity for music streaming and firmware updates, typically reserved for premium smartwatch tiers due to power consumption penalties.
Bluetooth dominates unit volume; GPS commands premium pricing power.
End User:
Health monitors and athletes drive medical-grade certification investments, while fitness enthusiasts and tech consumers absorb feature convergence from smartwatches displacing standalone trackers.
- Health Monitors:Aging populations in Japan and Germany requiring continuous glucose monitoring, atrial fibrillation detection, and blood pressure estimation. FDA 510(k) and EU MDR clearance pathways shape product roadmaps for pulse oximetry and ECG features.
- Fitness Enthusiasts:Recreational athletes tracking workout intensity, recovery metrics, and sleep staging through consumer-grade PPG and accelerometry.
- Athletes:Professional and semi-professional competitors demanding GPS precision, training load algorithms, and recovery analytics.
- Tech Consumers:Early adopters prioritizing notification mirroring, application ecosystems, and industrial design over specialized health metrics.
Health monitors drive regulatory complexity; fitness enthusiasts deliver volume scale.
Distribution Channel:
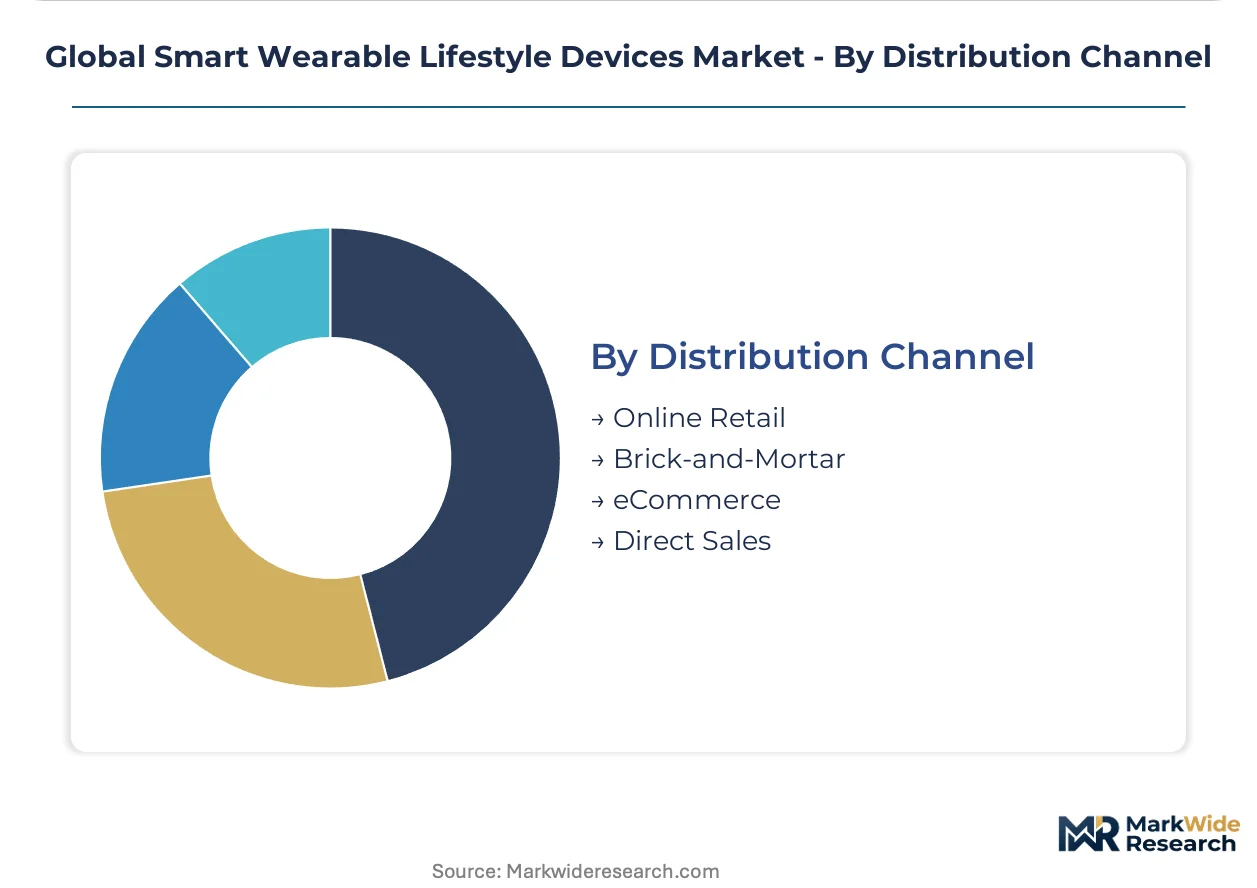
Channel selection reflects price tier and consumer education requirements, with direct sales capturing premium medical-grade configurations while online retail absorbs budget fitness tracker volume.
- Online Retail:Amazon, Flipkart, and Tmall dominate sub-$50 fitness tracker distribution in India and China, with price transparency compressing margins and accelerating replacement cycles.
- Direct Sales:Apple and Samsung flagship stores and branded e-commerce capture premium smartwatch volume, enabling controlled customer experience for complex health feature onboarding.
- Brick-and-Mortar:Electronics retailers and carrier stores in the US and Germany provide hands-on evaluation for AMOLED display quality and sizing.
- eCommerce:Brand-direct websites and specialty fitness retailers serving enthusiast segments with detailed technical specifications and comparison tools.
Online retail captures the highest unit volume; direct sales secures margin protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways for Class II medical devices position the United States as the regulatory anchor for premium smartwatch architectures. Divergent certification requirements across Japan, Germany, China, and India create parallel compliance architectures that reshape regional manufacturing footprints.
United States
Self-insured employers drive procurement consolidation for integrated wellness platforms with API interoperability demands. FDA premarket notification requirements for pulse oximetry and ECG functions compress development timelines for vendors seeking reimbursement pathways. Austin and San Francisco Bay Area clusters concentrate digital health startup density for remote patient monitoring algorithms.
Japan
Aging demographics in Tokyo and Osaka metropolitan areas accelerate demand for continuous glucose monitoring wearables with preventive health integration. METI and PMDA oversight of medical device software as a service creates distinct validation requirements for cloud-connected biometric systems. Kansai region manufacturing maintains precision MEMS sensor packaging capacity for domestic brands.
Germany
Health-conscious aging populations in Bavaria and North Rhine-Westphalia prioritize clinical-grade cardiac rhythm detection features. EU MDR and GDPR impose parallel biocompatibility testing and data sovereignty burdens across distribution channels. Stuttgart automotive engineering talent pools increasingly migrate to wearable sensor fusion development for industrial applications.
China
Shenzhen and Taipei hardware design centers absorb collapsing embedded systems engineering capacity from Western Europe. NMPA and GB standards mandate domestic cybersecurity certification for biometric data collection, creating divergent compliance architectures from FDA pathways. Pearl River Delta component clustering reduces bill-of-materials costs through concentrated MEMS foundry partnerships.
India
Price-sensitive consumers in Maharashtra and Karnataka tier-2 cities drive volume demand for sub-$25 connected fitness bands. PLI scheme incentives for electronics manufacturing attract assembly investments from Chinese component suppliers. Delhi-NCR emerges as distribution hub for online retail channels capturing budget wearable volume.
Global Smart Wearable Lifestyle Devices Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure with limited overlap. The vendor base separates into vertical silicon integrators, display supply gatekeepers, and specialist positioning system developers. Three strategic archetypes dominate: premium ecosystem orchestrators leveraging captive semiconductor design, component monopolists controlling critical AMOLED and GPS supply, and budget volume players optimizing Shenzhen assembly economics. Competitive moves concentrate on backward integration into sensor semiconductor design and geographic expansion into Indian tier-2 retail channels.
Among Cupertino-based and Suwon-based ecosystem architects, Apple Inc. and Samsung Electronics Co., Ltd. exemplify vertical silicon control strategies that sustain margin architecture in premium tiers. Garmin Ltd. anchors specialist positioning for aviation-grade GPS integration in outdoor lifestyle applications. These three entities represent distinct competitive vectors: ecosystem lock-in through application processor design, display supply gatekeeping through flexible OLED capacity control, and sensor fusion specialization for precision location services.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Garmin Ltd. |
| Fitbit LLC |
| Huawei Technologies Co., Ltd. |
| Xiaomi Corporation |
| Alphabet Inc. |
| Zepp Health Corporation |
| Whoop, Inc. |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance pathways for pulse oximetry and ECG functions simultaneously gate supply qualification for premium smartwatch vendors and enable three-tier pricing stratification across medical-grade, wellness-tier, and basic fitness configurations. This regulatory architecture concentrates margin protection with ecosystem orchestrators while compressing mid-tier positioning.
Pricing Analysis
Geographic price spreads separate premium smartwatches in Japan and Germany from sub-$25 fitness bands dominating Indian tier-2 and tier-3 cities. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and AMOLED display quality differentiation. Price differentiation stems from FDA clearance status and Samsung Display Corporation's flexible OLED supply control. Cost compression in economy tiers intensifies because Shenzhen assembly houses compete on bill-of-materials reduction. Health monitors in aging demographics show least price sensitivity; Indian budget consumers absorb highest elasticity.
Supply Chain Analysis
China and South Korea anchor component manufacturing for MEMS sensors and AMOLED displays respectively, while Taiwan concentrates Bluetooth SoC and display driver IC design. Raw material dependencies include lithium-metal anodes for solid-state batteries, cobalt for lithium-polymer cells, and silver nanowires for conductive textile integration. Single-source vulnerability concentrates in Samsung Display Corporation's 85% control of small-form-factor flexible OLED capacity. Distribution runs through direct sales for premium tiers and online retail platforms for budget volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software subscription revenue for health monitoring and remote patient monitoring expands faster than hardware unit sales, transforming procurement economics toward service-attach models. Recurring data platform fees now determine lifetime value calculations for vendor positioning.
For Market Incumbents: Shield margin architecture through backward integration into sensor semiconductor design and captive AMOLED supply negotiations. Embedded firmware engineering scarcity in Western Europe and North America threatens R&D efficiency; relocate hardware design centers to Shenzhen and Taipei to maintain development velocity. Certification investment in FDA breakthrough device designation unlocks reimbursement pathways that commodity competitors cannot replicate. For New Entrants and Emerging Players: Lead with conductive textile integration for enterprise wellness programs in US and German athletic apparel channels, where manufacturing complexity deters established smartwatch vendors. India's PLI scheme incentives for electronics manufacturing create white-space assembly capacity for sub-$25 connected bands. Target tier-2 and tier-3 Indian cities through Flipkart and Amazon distribution partnerships with localized feature sets. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital health platform vendors consolidating employer-sponsored wellness procurement. Long-term viability over a 5-10 year window favors vendors with FDA-cleared diagnostic algorithms and API interoperability with health plan infrastructure. Watch for inflection signals in remote patient monitoring reimbursement code expansion by CMS.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Semiconductor Backward Integration | Captive PPG optical array design reduces dependency on Nordic and Ambiq supply. |
| FDA Breakthrough Device Designation | Expedited review accelerates market access for AI-enabled arrhythmia detection algorithms. |
| Conductive Textile Manufacturing Scale-Up | Silver nanowire integration enables seamless EMG capture in enterprise athletic apparel. |
| India PLI Assembly Investment | Domestic electronics manufacturing incentives attract Chinese component supplier relocation. |
| Remote Patient Monitoring Platform Launch | API interoperability with US self-insured employer health plans drives B2B recurring revenue. |
Study Parameters
Cross-validation between primary interviews with device engineering leads, regulatory affairs specialists at FDA and EMA, hospital biomedical procurement managers, and enterprise wellness program administrators anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, EU MDR submission databases, NMPA certification records, and customs trade data for MEMS sensor and AMOLED display flows. Bottom-up bill-of-materials modeling and top-down category spend analysis triangulate market sizing.
Sensitivity analysis around solid-state battery adoption curves and EU AI Act compliance timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, connectivity architecture, end-user health monitoring intensity, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and software attach rate expansion. Forecast inputs incorporate AMOLED supply capacity constraints and embedded systems engineering pipeline collapse in Western markets.
The analysis sits within stated boundaries; outcomes outside FDA clearance acceleration or EU MDR timeline compression would require recalibration. Forecasts reflect assumptions about reimbursement pathway expansion and conductive textile manufacturing yield improvements. Specific risks that could revise projections include lithium-metal anode safety incidents triggering regulatory restriction and Samsung Display Corporation supply allocation disruption. Recalibration cycles align with material shifts in NMPA cybersecurity certification requirements and CMS remote monitoring reimbursement policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Consumer Grade Smart Wearable Device Market
Wearable Technology
3D Printed Wearables Market
Wearable Technology
Adult Smartwatch Market
Wearable Technology
US Pet Wearable Market
Wearable Technology
Battery for Children Smart Watch Market
Wearable Technology
Wearable Camera Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
Women's Watch Market
Wearable Technology
Europe Wearable Technology Market
Wearable Technology
Children Digital Watch Market
Wearable Technology
Wearable Smart Device Market
Wearable Technology
Global Smartwatch Battery Market
Wearable Technology
Smart Audio Sunglasses Market
Wearable Technology
Europe Watch Market
Wearable Technology
Europe Smart Watches Market
Wearable Technology
Kids Smart Watch Market