
 Pet Wearable Market | 2026-2036
Pet Wearable Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Wearable Market Analysis
The price-performance gap between premium veterinary-grade wearables and mass-market consumer trackers is hardening. Mars, Incorporated (Whistle) leverages its retail distribution network to sustain volume leadership in direct-to-consumer channels. Tractive anchors its European base while competing aggressively on cellular subscription pricing. Garmin Ltd dominates the working-dog segment with GPS precision that differentiates its units from lifestyle-oriented alternatives.
Pet wearables comprise electronic devices affixed to collars, harnesses, or implants that collect biometric, geospatial, or behavioral data through accelerometers, photoplethysmography sensors, and GNSS receivers for transmission to cloud-based analytics platforms. These systems serve commercial purposes spanning remote health surveillance, theft recovery, performance optimization for working animals, and insurance risk verification. GPS Trackers command the largest installed base among device types due to universal applicability across species and owner anxiety about pet loss. Health Monitors represent the fastest-expanding category as photoplethysmography and temperature sensing migrate from human consumer electronics into veterinary-calibrated form factors. Cellular connectivity captures the highest-margin subscription revenue pools despite Bluetooth's dominance in unit shipments.
FDA Center for Veterinary Medicine scrutiny of health-monitoring claims is reshaping product labeling requirements for devices marketed with diagnostic language. The USDA Animal and Plant Health Inspection Service influences interstate commerce standards for GPS-tracked livestock and working animals. FCC Part 15 and Part 27 certifications govern radio emission profiles, creating compliance barriers for new entrants. Stakeholders must decide whether to pursue veterinary-grade regulatory pathways that unlock prescription channels or accept consumer-electronics positioning that limits clinical integration.
Market Dynamics
Veterinary-grade photoplethysmography sensors are migrating from human consumer electronics into pet-calibrated form factors, compressing the price-performance gap between clinical and consumer devices while forcing manufacturers to choose between FDA Center for Veterinary Medicine pathways and consumer-electronics positioning.
Growth Catalysts
- USDA Interstate Commerce Standards:GPS-tracked livestock and working animals now require standardized data protocols, creating hardware refresh cycles among agricultural operators and K-9 units.
- Subscription Wellness Platforms:Pet insurance carriers in the United States bundle remote monitoring with policy premiums, embedding device distribution into recurring revenue infrastructure.
- Photoplethysmography Miniaturization:Wearable temperature and heart-rate sensing modules from human electronics supply chains are repurposing for veterinary biometrics at 40% lower unit costs.
Market Restraints
- Lithium-Polymer Cell Volatility:Battery chemistry costs fluctuate with electric vehicle demand, squeezing margins on GPS units requiring 72-hour continuous tracking.
- FCC Part 27 Certification Barriers:Cellular modem approvals for 4G/5G pet trackers impose 14-18 month lead times, freezing out capital-constrained entrants.
- Smartphone-Based Substitution:Bluetooth-tethered phone tracking satisfies cost-sensitive owners of indoor cats, capping addressable market expansion for standalone GPS hardware.
Strategic Opportunities
- German Working-Dog Procurement:Federal police and customs agencies standardize on performance-optimized wearables, creating institutional volume contracts absent in consumer channels.
- AI-Enabled Behavioral Diagnostics:Accelerometer pattern recognition converges with cloud-based veterinary triage, enabling early lameness detection in equine and canine athletes.
- Veterinary Clinic Channel Integration:Remote patient monitoring reimbursable under evolving practice management software protocols embeds devices into clinical workflows.
Industry Challenges
- Veterinary Data Science Talent Scarcity:Interpretation of biometric streams requires species-specific algorithm training, and qualified computational biologists command premiums that mid-tier manufacturers cannot absorb.
- Multi-Standard Certification Overlap:Devices claiming diagnostic utility must satisfy FDA Center for Veterinary Medicine, FCC Part 15, and ISO 10993 biocompatibility simultaneously, extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Wearable Market |
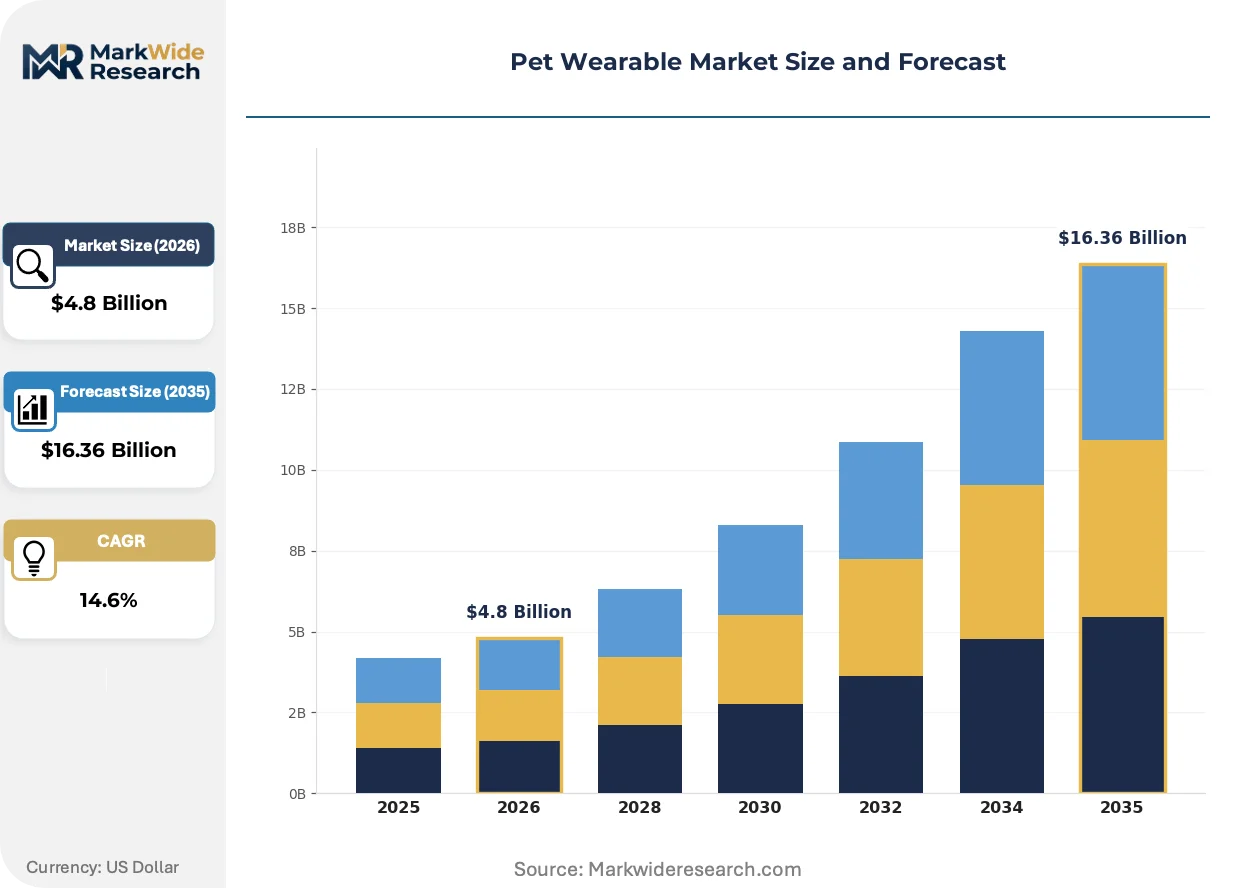
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: GPS Trackers, Health Monitors, Activity Trackers, Smart Collars End User: Pet Owners, Veterinarians, Pet Service Providers, Pet Retailers Connectivity: Bluetooth, Wi-Fi, Cellular, NFC Application: Health Monitoring, Location Tracking, Activity Tracking, Behavioral Analysis |
| Companies Covered | PetPace, Mars, Incorporated (Whistle), Tractive, Dogtra, Invoxia, FitBark Inc., Loc8tor Ltd., Petcube, Garmin Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Wearable Market Emerging Trajectories
Sensor fusion architectures and regulatory clarity around health claims are compressing product development cycles while segmenting the vendor base into clinical-grade and lifestyle-grade camps with incompatible distribution strategies.
Photoplethysmography modules calibrated for fur-penetrating light wavelengths are integrating with temperature arrays in single-chip packages. Large veterinary hospital chains are piloting these stacks for post-surgical remote monitoring. The technology is integrating clinical telemetry into collar-form devices previously limited to activity counting, enabling prescription-channel positioning that commands 3x hardware margins.
The FDA Center for Veterinary Medicine issued draft guidance distinguishing wellness monitoring from diagnostic claims in 2024. Device manufacturers marketing heart-rate variability for disease detection must now pursue 510(k) pathways or relabel. GPS tracker vendors with health-monitoring aspirations face the steepest compliance cost escalation, while pure-location players avoid regulatory exposure entirely.
Pet owners increasingly expect cellular-enabled devices to include veterinary telehealth access as a bundled service rather than a separate subscription. DTC brands are responding by unbundling hardware from service tiers, with base GPS tracking at lower monthly rates and premium tiers adding 24/7 veterinary chat. This shift is most pronounced in United States urban markets where pet insurance penetration exceeds 4% and subscription fatigue is forcing pricing transparency.
Pet Wearable Market Segmentation
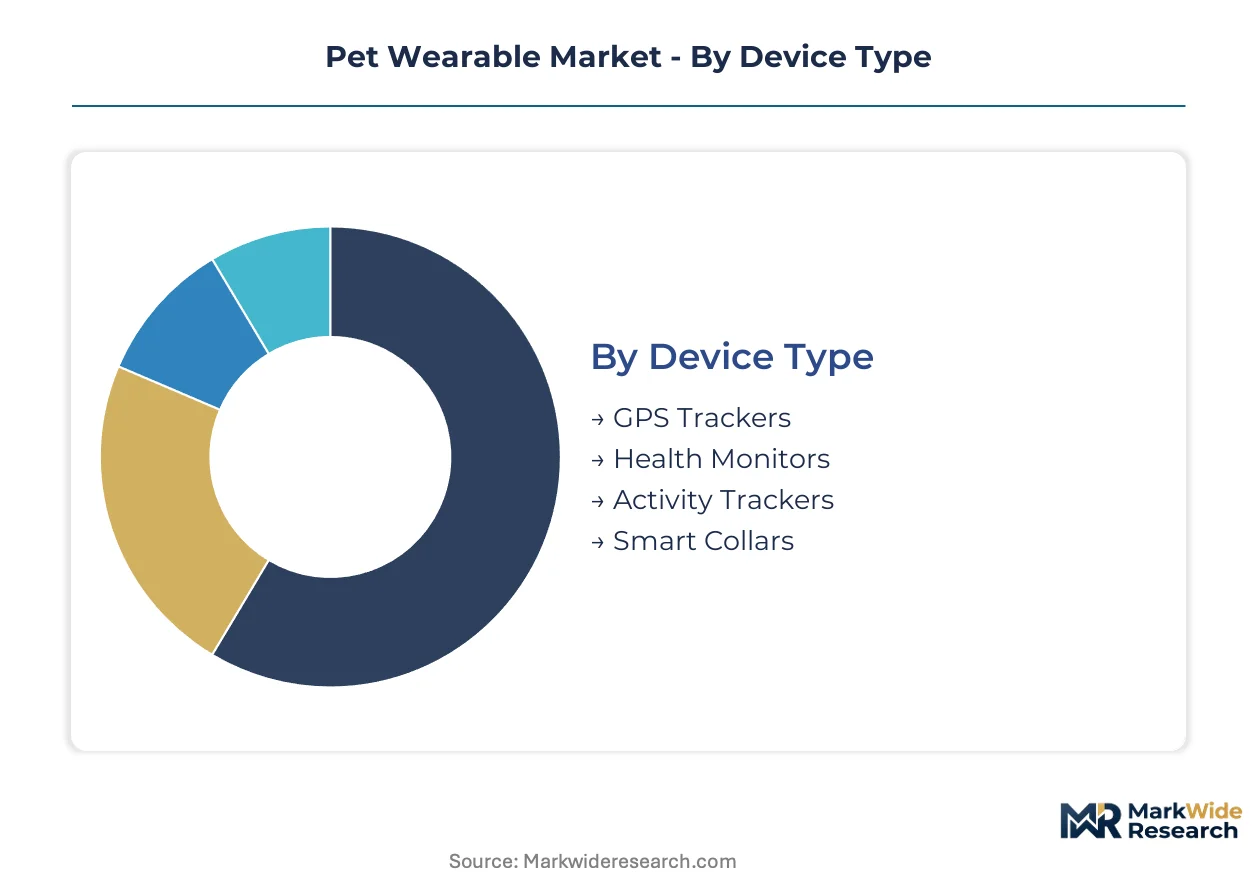
Device classification determines regulatory pathway and margin structure in pet wearables. Each segment carries distinct certification burdens and channel requirements that reshape competitive positioning.
Device Type:
FDA Center for Veterinary Medicine scrutiny falls heaviest on segments making diagnostic claims, while FCC Part 27 certification gates cellular-enabled hardware regardless of health functionality.
- GPS Trackers:GNSS receivers paired with cellular modems deliver real-time geofencing and theft recovery. Demand clusters among working-dog handlers in Germany and cattle operators across the United States Midwest, where USDA interstate commerce standards mandate traceable location data. FCC Part 27 certification imposes 14-18 month approval timelines that freeze out undercapitalized entrants.
- Health Monitors:Photoplethysmography sensors calibrated for fur-penetrating wavelengths track heart-rate variability and temperature. United States veterinary clinic chains pilot these for post-surgical remote monitoring, embedding devices into reimbursable care workflows. FDA 510(k) pathways unlock prescription channels commanding triple the hardware margins of consumer positioning.
- Activity Trackers:Accelerometer-based step counting and sleep scoring with Bluetooth tethering to smartphones.
- Smart Collars:Integrated sensor fusion architectures combining location, biometric, and behavioral data streams in single-form devices.
Leading the category by volume: GPS Trackers. Growing fastest: Health Monitors.
End User:
Channel economics vary sharply by purchaser sophistication, with institutional buyers demanding ISO 10993 biocompatibility and consumer channels prioritizing price accessibility.
- Pet Owners:Direct-to-consumer purchasers drive subscription attachment for cellular services. Urban United States markets with pet insurance penetration above 4% show strongest uptake of bundled wellness platforms. Smartphone-based Bluetooth tracking satisfies cost-sensitive indoor cat owners, capping standalone GPS addressable market expansion.
- Veterinarians:Clinical practitioners require FDA-compliant devices for diagnostic-adjacent monitoring. Large hospital chains in the United States negotiate enterprise pricing for remote patient monitoring integration. Reimbursement under evolving practice management software protocols embeds hardware into clinical workflows.
- Pet Service Providers:Boarding facilities and groomers deploying fleet tracking for liability management.
- Pet Retailers:Mass-market distributors pushing volume through private-label and co-branded SKUs.
Highest average revenue per user: Veterinarians. Steepest expansion trajectory: Pet Owners.
Connectivity:
Radio emission profiles governed by FCC Part 15 and Part 27 create tiered cost structures that segment the vendor base by capital intensity.
- Cellular:4G/5G modems enable standalone operation without smartphone proximity. Captures highest-margin subscription revenue pools despite capital-intensive certification. Lithium-polymer battery costs fluctuate with electric vehicle demand, squeezing margins on 72-hour continuous tracking specifications.
- Bluetooth:Low-energy protocols dominate unit shipments through smartphone tethering. Satisfies cost-sensitive owners of indoor cats, limiting addressable market for premium GPS alternatives. No FCC Part 27 barriers lower entry costs for new hardware vendors.
- Wi-Fi:Home-network-dependent tracking for indoor boundary enforcement.
- NFC:Proximity-based identification and veterinary record access.
Widest installed base: Bluetooth. Climbing the fastest: Cellular.
Application:
Use-case specificity determines sensor configuration and algorithm training requirements, with behavioral diagnostics demanding scarce veterinary data science talent.
- Health Monitoring:Continuous biometrics for early disease detection and chronic condition management. Photoplethysmography miniaturization from human electronics supply chains cuts unit costs 40% while compressing price-performance gaps between clinical and consumer grades. Species-specific algorithm training requires computational biologists commanding premiums mid-tier manufacturers cannot absorb.
- Location Tracking:Real-time positioning for theft recovery and wandering prevention. Universal applicability across species sustains largest installed base. German federal police and customs agencies standardize on performance-optimized units, creating institutional volume contracts absent in consumer channels.
- Activity Tracking:Exercise quantification and fitness goal-setting for companion animals.
- Behavioral Analysis:Accelerometer pattern recognition for anxiety and lameness detection.
Deepest revenue concentration: Location Tracking. Gaining share fastest: Health Monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors North American pet wearable innovation through venture-backed sensor startups and veterinary telehealth platforms. The concentration of pet insurance carriers and subscription wellness services in this corridor generates recurring revenue infrastructure that hardware manufacturers exploit.
United States
Pet insurance penetration exceeding 4% in urban coastal markets drives bundled remote monitoring adoption. FDA Center for Veterinary Medicine scrutiny of diagnostic claims reshapes product labeling requirements for health-monitoring devices. Austin and Seattle clusters host cellular-enabled tracker startups competing on subscription pricing transparency.
Germany
Federal police and customs agencies standardize on performance-optimized wearables for working dogs, creating institutional procurement absent in consumer channels. KBA influences device certification standards for GPS-tracked livestock crossing interstate borders. Munich engineering firms supply photoplethysmography modules repurposed from human electronics supply chains.
United Kingdom
Veterinary clinic chains pilot remote patient monitoring for post-surgical care, embedding devices into reimbursable workflows. EMA-adjacent regulatory frameworks influence biocompatibility standards for collar-mounted sensors. London fintech corridors enable subscription billing infrastructure for DTC wellness platforms.
Japan
METI-supported IoT initiatives accelerate miniaturization of fur-penetrating photoplethysmography sensors. Aging pet demographics drive demand for chronic condition monitoring among companion animals. Osaka electronics manufacturers supply temperature-sensing arrays at 40% lower unit costs than Western alternatives.
Australia
Livestock operators across Queensland and New South Wales deploy GPS trackers to satisfy traceability mandates for export markets. TGA-aligned biocompatibility standards govern implantable device development. Sydney veterinary data science clusters train species-specific algorithms for accelerometer-based lameness detection.
Pet Wearable Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and connectivity-tier dimensions. The vendor base stratifies into FDA-pursuing clinical-grade specialists, cellular-subscription aggregators, and Bluetooth-tethered volume manufacturers. Three archetypes dominate: veterinary-calibrated health monitors, GPS-precision working-dog suppliers, and mass-market lifestyle trackers. Dominant competitive moves include M&A for veterinary clinic channel access and strategic partnerships with pet insurance carriers for embedded distribution.
Within the cellular-subscription tier, Tractive and Mars, Incorporated (Whistle) exemplify divergent geographic anchoring strategies. Garmin Ltd occupies a position at the precision-GPS vector for working-animal applications. These three entities represent the spectrum from European base-building to retail network exploitation to performance-differentiated hardware.
| Leading Market Players |
|---|
| PetPace |
| Mars, Incorporated (Whistle) |
| Tractive |
| Dogtra |
| Invoxia |
| FitBark Inc. |
| Loc8tor Ltd. |
| Petcube |
| Garmin Ltd |
| Others |
Supply Flow & Price Mechanics
Lithium-polymer cell costs fluctuate with electric vehicle demand, cascading from upstream battery chemistry suppliers through to GPS tracker manufacturers and compressing margins on 72-hour continuous tracking specifications demanded by working-dog handlers and livestock operators.
Pricing Analysis
Subscription-based pricing anchors the revenue model, with cellular-enabled devices commanding recurring monthly fees that separate premium tiers bundling veterinary telehealth from base GPS tracking. Price differentiation rests on FDA Center for Veterinary Medicine certification status and cellular modem performance, with prescription-channel positioning capturing triple the hardware margins of consumer-grade alternatives. Pricing pressure stems from photoplethysmography miniaturization cutting sensor module costs, squeezing mid-tier manufacturers unable to absorb veterinary data science talent premiums. Pet owners in United States urban markets with pet insurance penetration above 4% show least price sensitivity, while Bluetooth-tethered smartphone tracking satisfies most cost-sensitive indoor cat owners.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese semiconductor foundries fabricating GNSS receiver chipsets and cellular modems for GPS tracker manufacturers. Munich engineering firms and Osaka electronics manufacturers supply photoplethysmography modules and temperature-sensing arrays, drawing from human consumer electronics supply chains repurposed for veterinary form factors. Tariff exposure on lithium-polymer cells and radio frequency components creates margin volatility for hardware vendors. Distribution runs through direct-to-consumer channels anchored by subscription wellness platforms, veterinary clinic procurement networks, and mass-market retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pet wearable sector sits in a technology-transition phase as photoplethysmography sensors displace accelerometer-only architectures, elevating clinical-grade monitoring over lifestyle tracking.
For Market Incumbents: Anchor defensive positioning through FDA 510(k) pathway investments that lock prescription-channel access against consumer-electronics entrants, while securing captive supply agreements for lithium-polymer cells to buffer electric vehicle demand volatility. Deepen veterinary clinic channel integration through remote patient monitoring reimbursement protocols that embed hardware into clinical workflows. For New Entrants and Emerging Players: Begin with Bluetooth-tethered activity trackers for cost-sensitive indoor cat owners, exploiting the absence of FCC Part 27 certification barriers to compress time-to-revenue. Target German working-dog procurement channels where federal police and customs agencies standardize on performance-optimized units, creating institutional volume contracts absent in saturated consumer channels. For Investors and Strategic Acquirers: FDA draft guidance distinguishing wellness from diagnostic claims is the leading indicator that regulatory clarity will consolidate the vendor base into clinical-grade and lifestyle-grade camps with incompatible distribution strategies. Long-term viability favors acquisition targets pursuing veterinary-calibrated certification pathways over pure-location players avoiding regulatory exposure entirely. Watch for photoplethysmography module suppliers achieving fur-penetrating wavelength calibration as the signal for hardware margin inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Investment | Unlocks prescription-channel positioning commanding triple consumer-grade hardware margins. |
| Veterinary Clinic Channel Integration | Embeds devices into reimbursable remote patient monitoring workflows through practice management software protocols. |
| Cellular Subscription Platform Unbundling | Separates base GPS tracking from premium veterinary telehealth tiers to address subscription fatigue in United States urban markets. |
| Photoplethysmography Module Sourcing | Secures supply from human electronics manufacturers repurposing sensors for veterinary biometrics at reduced unit costs. |
| Working-Dog Institutional Procurement | Captures volume contracts from German federal police and customs agencies absent in consumer channels. |
Methodological Framework
Multi-period observation of cellular subscription attachment rates, FDA regulatory filing patterns, and photoplethysmography sensor cost curves anchored the trend analysis, supplemented by interviews with veterinary clinic procurement managers, pet insurance carrier product directors, cellular module procurement leads at hardware manufacturers, and biomedical engineers at large veterinary hospital chains. Secondary validation drew from FDA Center for Veterinary Medicine guidance documents, FCC Part 27 certification databases, customs records for lithium-polymer cell imports, and SEC filings of publicly traded device manufacturers. Bottom-up unit shipment estimates triangulated against top-down subscription revenue projections.
Segment-weighting across device type, connectivity tier, and end-user channel shaped the analytical framework, with GPS trackers, health monitors, and smart collars modeled separately by cellular versus Bluetooth attachment rates. CAGRs derived from logistic diffusion curves fitted to veterinary clinic adoption patterns and pet insurance bundling penetration. Forecast inputs incorporated photoplethysmography miniaturization cost trajectories and FCC certification timeline distributions.
Regulatory enforcement intensity shifts, lithium-polymer cell commodity price spikes, and smartphone-based substitution acceleration are the dominant revision risks that could compress or extend adoption timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
Kids GPS Trackers and Wearables Market
Wearable Technology
Wearable Tech Devices Market
Wearable Technology
Wearable Smart Device Market
Wearable Technology
Wearable Gaming Devices Market
Wearable Technology
3D Printed Wearables Market
Wearable Technology
Wearable AI Devices Market
Wearable Technology
Wearable Communicator Market
Wearable Technology
Electronic Underwear Market
Wearable Technology
Wearable Computing Devices Market
Wearable Technology
Smart Band Market
Wearable Technology
Europe Watch Market
Wearable Technology
Wearable Electronics Market
Wearable Technology
Asia-Pacific Wearable Technology Market
Wearable Technology
Wearable Computing Market
Wearable Technology
Global Smart Ring Market
Wearable Technology
Water Resistant Watch Market