
 APAC Smart Watch Market | 2026-2036
APAC Smart Watch Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Smart Watch Market Outlook
Subscription-based financing and hardware-leasing programs is tilting competitive dynamics toward vendors with capital-market access. Apple leverages its ecosystem lock-in to sustain premium pricing power across Japan and Australia. Samsung Electronics Co. Ltd. anchors its position through in-house semiconductor production, reducing component dependency. Xiaomi Corporation competes on manufacturing scale, flooding Southeast Asian channels with economy-tier inventory.
An APAC smart watch is a wrist-worn computational device integrating biometric sensors, low-power microprocessors, and wireless connectivity protocols to deliver health telemetry, geolocation, and digital payment functionality. Manufacturing centers on system-in-package assembly where sensor fusion accuracy determines clinical utility. Wearable-type devices lead volume shipments, though hybrid formats are capturing professionals who demand analog aesthetics with covert digital tracking. Health monitoring features command the widest margin pools as insurers and employers subsidize wellness-linked procurement. GPS-enabled units dominate outdoor recreation segments across Australia's fitness culture.
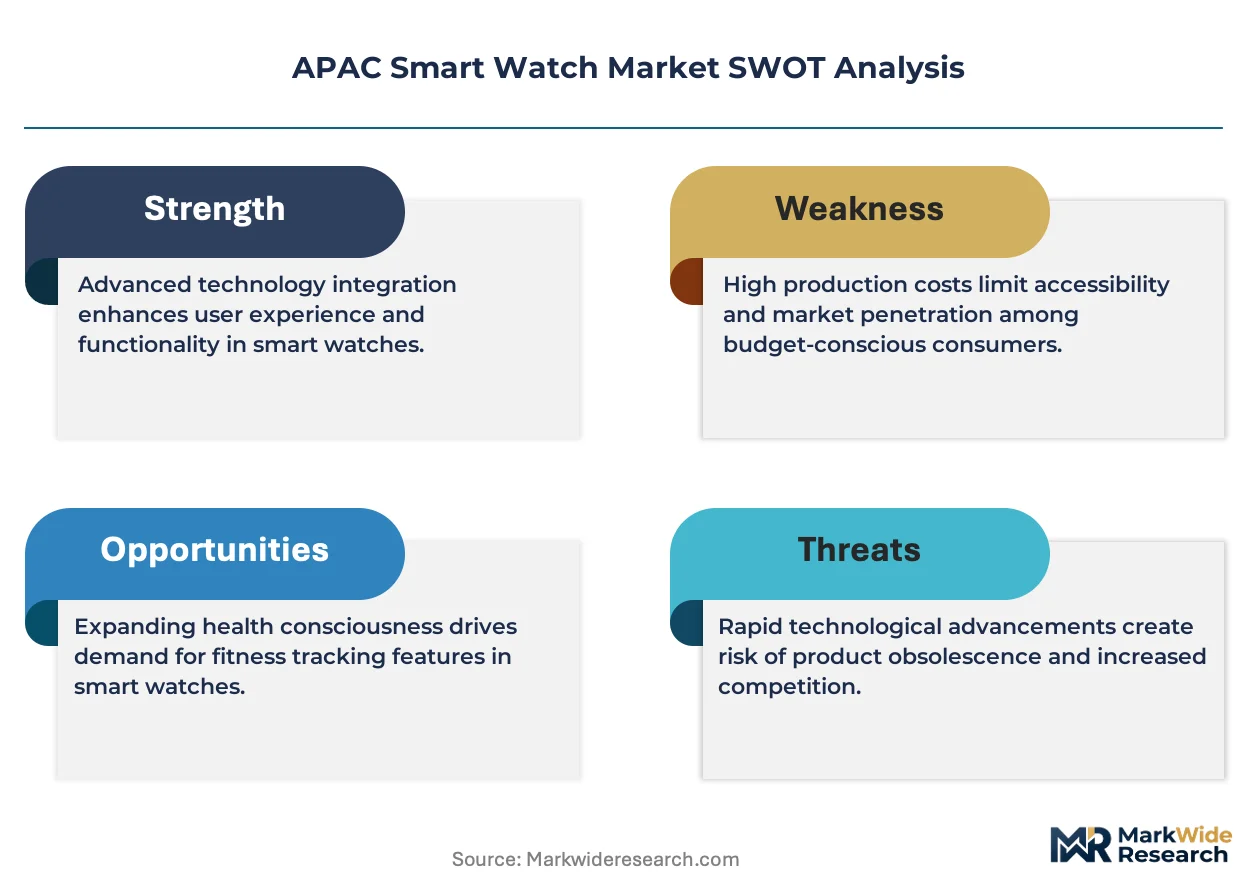
Japan's METI enforces radio equipment compliance through technical standards conformity certification, while China's MIIT mandates network access licenses for cellular-enabled devices. India's BIS marking requirement for electronic imports creates a bottleneck for unbranded entrants. Australia's TGA scrutiny of blood-oxygen and ECG claims is elevating clinical-validation costs for health-feature marketing. Stakeholders must weigh regulatory pre-clearance investments against the revenue premium from medically endorsed positioning.
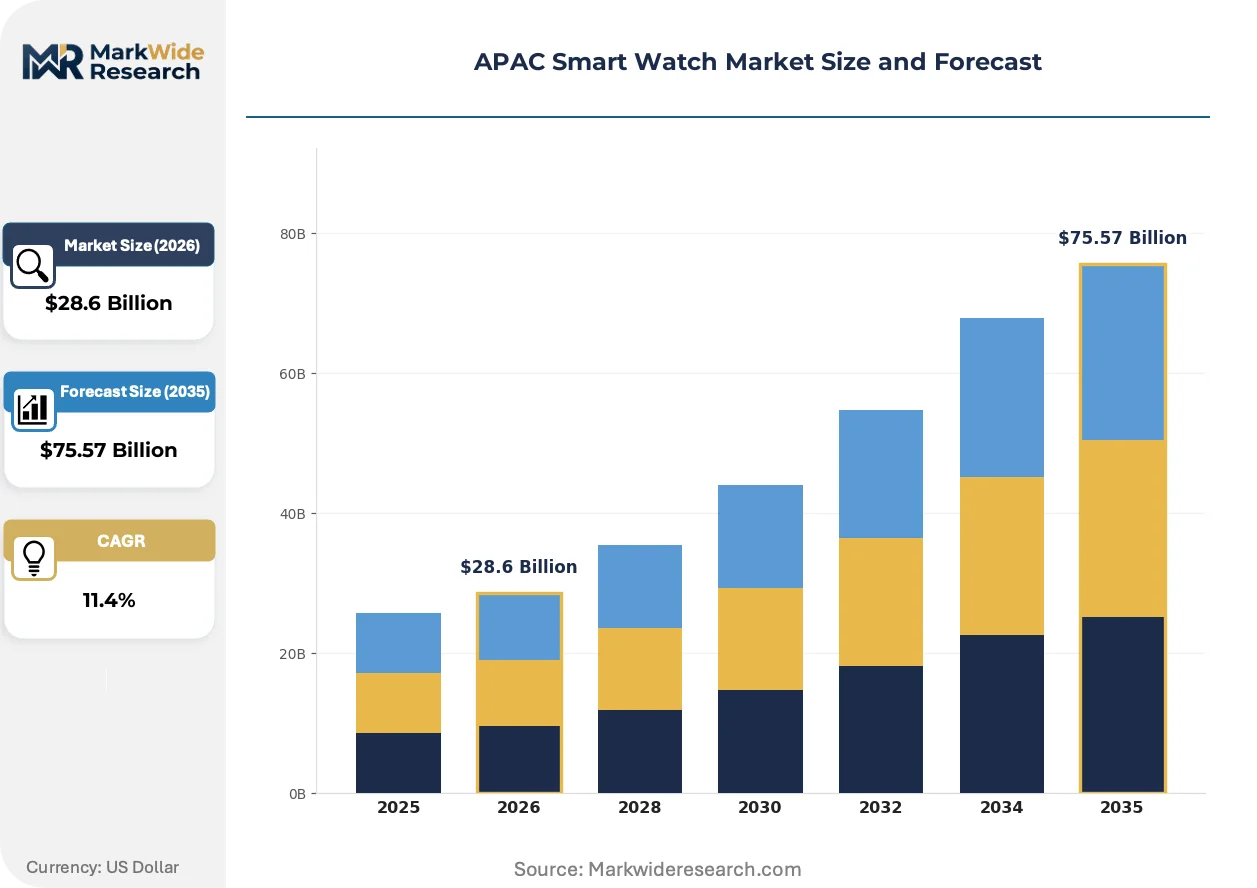
Market Dynamics
Health-tech integration is compressing replacement cycles in China's tier-one cities, where insurers and employers now subsidize wellness-linked procurement. This demand pull is restructuring vendor priorities across the entire value chain.
Growth Catalysts
- Fitness Enthusiast Demand:Australia's outdoor recreation culture drives GPS-enabled unit adoption. Wearable-type devices dominate volume shipments as hybrid formats capture professionals seeking analog aesthetics with covert digital tracking.
- Employer Subsidy Programs:Health monitoring features command the widest margin pools when corporate wellness budgets underwrite device procurement. Biometric sensor accuracy determines clinical utility in system-in-package assembly.
- MIIT Network Access Licensing:China's cellular-enabled device mandate creates compliant-product scarcity that benefits pre-cleared vendors. Network access licenses filter out unbranded entrants in the world's largest smart watch demand cluster.
Market Restraints
- BIS Import Bottleneck:India's BIS marking requirement for electronic imports delays unbranded product market entry. Wireless device certification timelines extend 8-14 weeks for first-time registrants.
- Sensor Fusion Accuracy Thresholds:Clinical-grade blood-oxygen and ECG validation requires TGA-level scrutiny in Australia. Elevation of health-feature marketing costs compresses margin for non-validated claims.
- Semiconductor Supply Concentration:In-house production capability separates integrated vendors from assembly-dependent competitors. Component dependency creates vulnerability when foundry capacity tightens.
Strategic Opportunities
- Southeast Asian Channel Flooding:Economy-tier inventory gaps exist in Indonesia, Vietnam, and Philippines manufacturing scale regions. Local assembly partnerships circumvent import duty structures.
- Subscription Financing Convergence:Hardware-leasing programs tilt competitive dynamics toward vendors with capital-market access. Monthly payment models reduce upfront purchase friction for mid-tier buyers.
- Dual Carbon Compliance:China's SAMR energy-efficiency labeling creates premium positioning for low-power microprocessor designs. Battery-life differentiation aligns with national decarbonization targets.
Industry Challenges
- Multi-Jurisdiction Certification Parallelism:Japan's METI radio equipment compliance, China's MIIT cellular licensing, and Australia's TGA health claims scrutiny require simultaneous pre-clearance investment. Stakeholders must sequence regulatory spend against revenue timing.
- Legacy Analog-Digital Integration Complexity:Hybrid format mechanical engineering demands horological expertise absent from pure electronics supply chains. Watch movement suppliers resist volume scaling for smart watch programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Smart Watch Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable, Hybrid, Digital, Analog End User: Fitness Enthusiasts, Professionals, Tech Savvy, General Consumers Feature: Health Monitoring, GPS, Notifications, NFC Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | Apple Inc., Samsung Electronics Co. Ltd., Huawei Technologies Co. Ltd., Xiaomi Corporation, Garmin Ltd., Fitbit Inc., Zepp Health Corporation, OPPO Electronics Corp., BBK Electronics Industry Co. Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Smart Watch Market Strategic Shifts
Sensor fusion architectures are migrating from discrete component layouts toward system-in-package designs. This integration wave is redrawing competitive boundaries between semiconductor vendors and finished-device assemblers.
Low-power microprocessor design is migrating from general-purpose ARM cores toward dedicated neural processing units for on-device health analytics. Fitness enthusiasts in Australia's outdoor recreation segments drive early adoption of continuous biometric monitoring. The structural consequence is that algorithm accuracy is displacing raw sensor specification as the primary purchasing criterion.
Japan's METI technical standards conformity certification is tightening radio equipment electromagnetic compatibility thresholds. Industrial consequence: pre-certified module sourcing is displacing custom RF design in vendor development roadmaps. Cellular-enabled devices face the steepest compliance cost escalation, forcing mid-tier players toward Bluetooth-only configurations.
Corporate wellness procurement is consolidating device selection authority under HR-benefits administrators rather than individual employees. Channel disintermediation is visible in China's tier-one cities, where direct insurer-vendor contracts bypass retail markup. This purchasing centralization is most advanced in employer-subsidized health-tech integration programs across Shanghai, Beijing, and Shenzhen.
APAC Smart Watch Market Segmentation
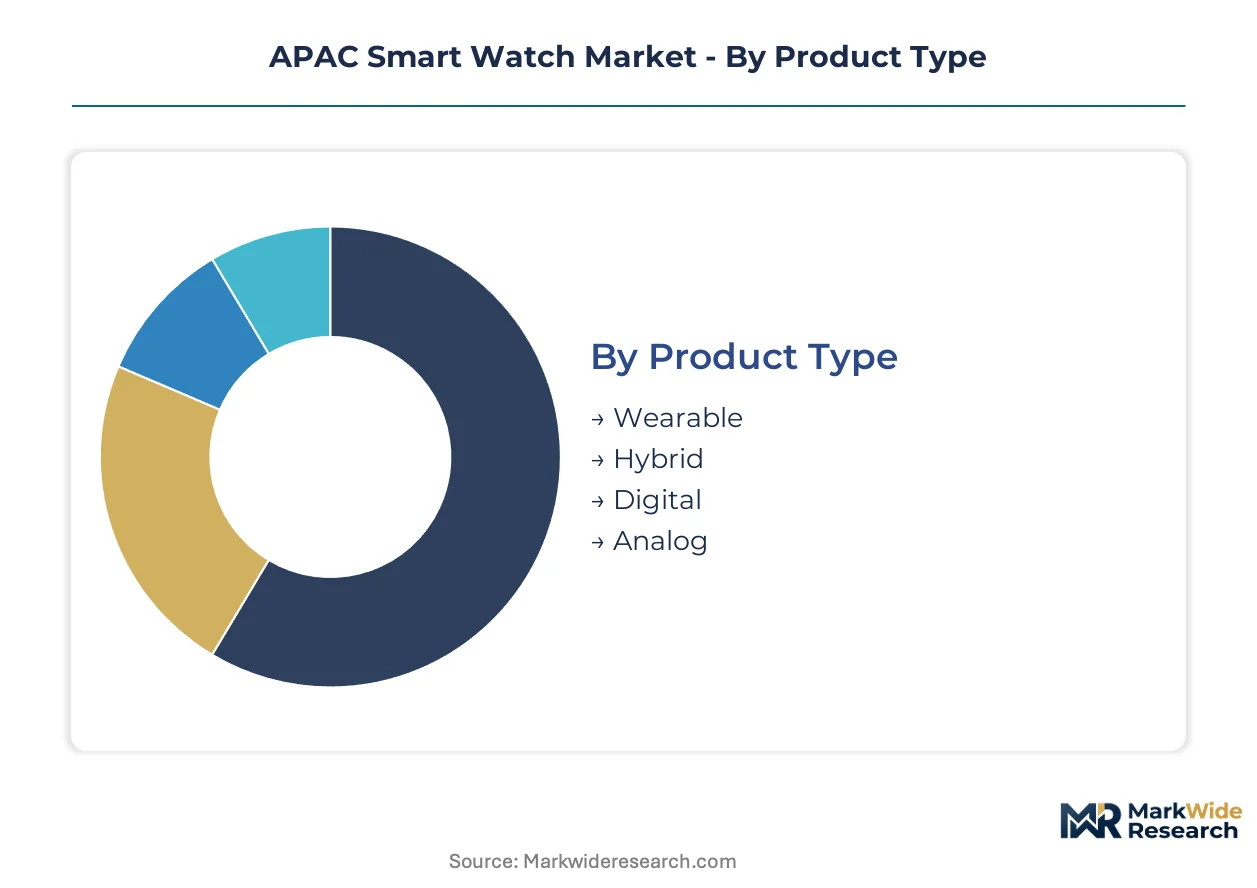
Segmentation in the APAC Smart Watch Market reveals divergent profit pools across hardware formats, user psychographics, and regulatory compliance tiers. Vendor positioning strategies must align with specific demand clusters rather than treating the region as a monolithic growth opportunity.
Product Type:
The use-case spectrum spans from continuous biometric monitoring to discrete professional accessorizing, with each format demanding distinct supply chain capabilities and certification pathways.
- Wearable:Full-digital wrist-worn devices integrate low-power microprocessors with system-in-package sensor fusion for clinical-grade health telemetry. Demand concentrates in China's tier-one cities where insurer-subsidized wellness programs underwrite replacement cycles.
- Hybrid:Mechanical watch movements conceal digital tracking modules beneath analog dials, appealing to professionals across Japan and Australia who resist overt technology signaling. Australia's outdoor recreation culture drives GPS-enabled hybrid adoption for covert activity logging.
- Digital:Touchscreen-dominant interfaces prioritize notification density and app ecosystem depth over battery longevity. Southeast Asian channel flooding by economy-tier inventory favors this format's manufacturing scale advantages.
- Analog:Minimal computational integration limits functionality to basic step counting and sleep staging, serving price-sensitive rural segments across India and Indonesia where BIS certification costs deter feature-rich alternatives.
The dominant share belongs to Wearable, while Hybrid is closing the gap fastest.
End User:
Cost tier stratification separates subsidized corporate procurement from individual discretionary purchases.
- Fitness Enthusiasts:Australia's outdoor recreation segments demand continuous biometric monitoring with GPS-enabled route tracking. TGA scrutiny of blood-oxygen and ECG claims elevates clinical-validation requirements for this cohort.
- Professionals:Analog-aesthetic preferences drive hybrid format selection across Japan's corporate workforce. METI radio equipment compliance creates pre-certified module sourcing advantages for vendors targeting this segment.
- Tech Savvy:Early adopters prioritize neural processing unit integration for on-device health analytics. China's MIIT cellular licensing filters unbranded entrants from this specification-sensitive demand cluster.
- General Consumers:Price elasticity dominates purchase decisions in India's BIS-regulated import environment. Economy-tier inventory gaps in Indonesia, Vietnam, and Philippines channel flooding opportunities target this mass base.
Fitness Enthusiasts command the widest margin pools through employer subsidy capture, while Tech Savvy users are expanding most quickly.
Feature:
Margin concentration tracks regulatory validation intensity across health claims versus commodity connectivity.
- Health Monitoring:Blood-oxygen, ECG, and continuous glucose estimation require TGA-level clinical validation in Australia. Corporate wellness procurement in China's tier-one cities centralizes authority under HR-benefits administrators for this feature set.
- GPS:Outdoor recreation positioning demands drive adoption across Australia's fitness culture. Dual carbon compliance through SAMR energy-efficiency labeling creates premium positioning for low-power geolocation designs.
- Notifications:Bluetooth-only configurations proliferate among mid-tier players avoiding MIIT cellular licensing costs. Manufacturing scale advantages favor this commoditized feature integration.
- NFC:Digital payment functionality requires payment-network certification separate from device regulatory clearance. Subscription financing convergence reduces upfront purchase friction for NFC-enabled mid-tier units.
Health Monitoring dominates procurement budgets, while GPS is gaining share fastest through outdoor recreation segment expansion.
Price Tier:
Supply concentration separates integrated semiconductor vendors from assembly-dependent competitors across tier boundaries.
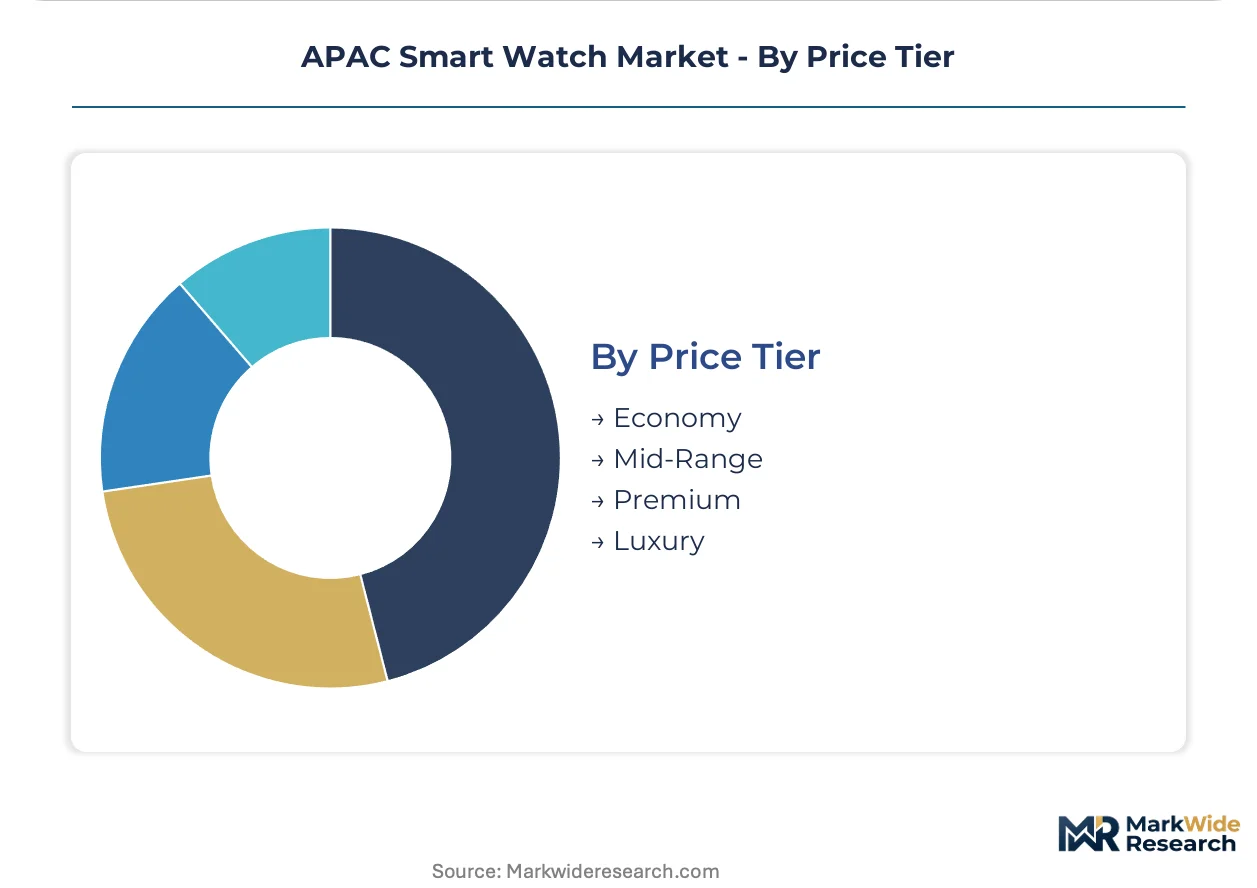
- Economy:System-in-package assembly prioritizes sensor fusion cost reduction over clinical accuracy. Xiaomi Corporation's manufacturing scale floods Southeast Asian channels with inventory targeting this tier.
- Mid-Range:Balanced feature sets incorporate health monitoring without TGA-level validation costs. Subscription-based financing programs tilt competitive dynamics toward vendors with capital-market access in this segment.
- Premium:Ecosystem lock-in sustains pricing power through integrated device-family connectivity. Apple's Japan and Australia positioning exemplifies this tier's platform-dependency model.
- Luxury:Horological heritage brands command scarcity premiums through mechanical movement expertise. Hybrid format mechanical engineering demands watch movement supplier relationships absent from pure electronics supply chains.
Premium holds the dominant share, while Economy is climbing the fastest through channel flooding in Indonesia, Vietnam, and Philippines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Japan and Australia where ecosystem lock-in sustains vendor margins, while economy-tier volume floods Southeast Asian channels at compressed price points. This asymmetry structures vendor portfolio allocation across the region.
China
Health-tech integration compresses replacement cycles in Shanghai, Beijing, and Shenzhen where insurer-subsidized wellness programs centralize procurement authority under HR-benefits administrators. MIIT network access licenses for cellular-enabled devices filter unbranded entrants from the world's largest smart watch demand cluster. The Yangtze River Delta manufacturing corridor anchors system-in-package assembly capacity.
Japan
Professionals across Tokyo and Osaka drive hybrid format adoption seeking analog aesthetics with covert digital tracking functionality. METI technical standards conformity certification tightens radio equipment electromagnetic compatibility thresholds, elevating pre-certified module sourcing advantages. Kanto region vendors leverage horological heritage relationships for mechanical movement integration.
India
BIS marking requirements for wireless device imports create 8-14 week certification bottlenecks that deter feature-rich alternatives from unbranded entrants. Price-sensitive demand concentrates in rural segments where minimal computational integration limits functionality to basic step counting. Maharashtra and Karnataka industrial corridors develop local assembly partnerships to circumvent import duty structures.
Australia
Fitness enthusiasts across New South Wales and Victoria demand GPS-enabled units for outdoor recreation route tracking with continuous biometric monitoring. TGA scrutiny of blood-oxygen and ECG claims elevates clinical-validation costs for health-feature marketing. Sydney and Melbourne corporate wellness programs drive employer-subsidized procurement at premium price tiers.
Southeast Asia
Economy-tier inventory gaps in Indonesia, Vietnam, and Philippines attract manufacturing scale players flooding channels with Bluetooth-only configurations avoiding cellular licensing costs. Local assembly partnerships in Jakarta, Ho Chi Minh City, and Manila circumvent import duty structures. Subscription financing convergence reduces upfront purchase friction for mid-tier buyers in these emerging demand clusters.
APAC Smart Watch Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream capturing value through sensor fusion accuracy and low-power microprocessor design. The vendor base stratifies across ecosystem-dependent premium positioning, semiconductor-integrated mid-tier anchoring, and manufacturing-scale economy flooding. Three archetypes dominate: ecosystem lock-in platforms, in-house production integrators, and channel-flooding scale players. Competitive moves concentrate on subscription financing program expansion and local assembly partnership formation to circumvent import duty structures.
Within the ecosystem lock-in tier, Apple Inc. and Samsung Electronics Co. Ltd. exemplify divergent margin defense strategies. Apple leverages integrated device-family connectivity to sustain premium pricing power across Japan and Australia. Samsung anchors positioning through captive semiconductor production reducing component dependency during foundry capacity constraints. Xiaomi Corporation occupies the scale-driven end, flooding Southeast Asian channels with economy-tier inventory targeting price-elastic general consumers in BIS-regulated import environments.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co. Ltd. |
| Huawei Technologies Co. Ltd. |
| Xiaomi Corporation |
| Garmin Ltd. |
| Fitbit Inc. |
| Zepp Health Corporation |
| OPPO Electronics Corp. |
| BBK Electronics Industry Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Yangtze River Delta system-in-package assembly is compressing component pricing while tightening margins for pure-play assemblers lacking captive semiconductor production. This utilization asymmetry rewards integrated vendors with in-house microprocessor design and squeezes assembly-dependent competitors into economy-tier positioning.
Pricing Analysis
The customization-premium spread separates TGA-validated health monitoring configurations from standard Bluetooth-only units, with clinical-grade sensor fusion commanding substantial positioning premiums. Three-tier pricing structure across premium, standard, and economy levels reflects ecosystem lock-in power, certification investment recovery, and manufacturing scale advantages respectively. Pricing pressure stems from Xiaomi Corporation's channel flooding across Southeast Asian markets, eroding mid-tier positioning. General consumers in BIS-regulated import environments exhibit highest price sensitivity, while employer-subsidized corporate wellness procurement demonstrates lowest elasticity.
Supply Chain Analysis
Supplier-financing facilities extended by Yangtze River Delta foundries are tethering mid-tier vendors to concentrated component sourcing, amplifying dependency risks. Supply concentrates in China, South Korea, and Taiwan for low-power microprocessors, biometric sensors, and RF modules. Raw material dependencies span lithium-ion battery cells, sapphire display substrates, and medical-grade silicone housings. Single-source vulnerability in neural processing unit design creates bottleneck exposure. Distribution runs through direct insurer-vendor contracts in China's tier-one cities alongside traditional electronics retail channels across Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The APAC Smart Watch Market rewards vendors controlling sensor fusion algorithm development and clinical validation pathways, while assembly-scale players face commoditization pressure from foundry overcapacity.
For Market Incumbents: Build ecosystem lock-in moats through integrated device-family connectivity spanning smartphones, earbuds, and home health hubs. Secure METI pre-certified module sourcing advantages ahead of Japan's tightening electromagnetic compatibility thresholds. Deepen backward integration into neural processing unit design to reduce ARM core licensing dependency. Channel control through direct corporate wellness contracts insulates against retail margin erosion. For New Entrants and Emerging Players: Pursue white-space opportunities in Indonesia, Vietnam, and Philippines economy-tier gaps where local assembly partnerships circumvent import duty structures. Target hybrid format mechanical engineering collaborations with Kanto region watch movement suppliers, exploiting horological expertise scarcity among pure electronics vendors. Penetrate Australia's outdoor recreation segments through GPS-enabled units with TGA-level clinical validation, bypassing saturated China tier-one city competition. Go-to-market through fitness specialty retail rather than consumer electronics mass channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cellular-enabled device sub-segments requiring simultaneous MIIT, METI, and TGA compliance investment. Long-term viability favors vendors with capital-market access to underwrite subscription financing programs and hardware-leasing infrastructure. Acquisition targets should demonstrate clinical-validation capabilities and insurer relationship depth. Signal to watch: employer subsidy program consolidation rate across Shanghai, Beijing, and Shenzhen HR-benefits administrators.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | TGA scrutiny of blood-oxygen claims elevates marketing costs for non-validated health features. |
| Local Assembly Partnership | Jakarta and Ho Chi Minh City facilities circumvent India's BIS import bottlenecks and duty structures. |
| Subscription Financing Launch | Monthly payment models reduce upfront friction for mid-tier buyers in Philippines and Vietnam. |
| Pre-Certified Module Sourcing | METI radio compliance advantages accelerate Japan hybrid format time-to-market for professionals. |
| Neural Processing Unit Integration | On-device health analytics displace raw sensor specifications as primary purchasing criterion. |
Study Parameters
Initial hypotheses were tested against primary input from smart watch platform engineers, health insurance benefits administrators, semiconductor procurement leads, and retail channel partners and refined through secondary validation. Sources included MIIT network access license filings, TGA medical device registration databases, SAMR energy-efficiency labeling records, and customs import data for wireless device categories. Bottom-up shipment estimates triangulated against top-down consumer electronics spending projections.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions spanning product format, end-user psychographic, feature certification tier, and price positioning. CAGRs were derived from replacement cycle compression rates in employer-subsidized procurement clusters and manufacturing capacity expansion trajectories. Forecast inputs incorporated BIS certification timeline distributions and foundry capacity utilization signals from Yangtze River Delta assembly corridors.
The forecast holds incumbent behavior within observed patterns; aggressive ecosystem expansion by platform integrators or rapid regulatory harmonization across METI, MIIT, and TGA frameworks would shift outcomes. Macroeconomic contraction in corporate wellness budgets, semiconductor supply disruption, or clinical validation requirement escalation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Technology
US Pet Wearable Market
Wearable Technology
Kids GPS Trackers and Wearables Market
Wearable Technology
Europe Smart Watches Market
Wearable Technology
Android Smartwatch Market
Wearable Technology
Kids Watch Market
Wearable Technology
Wearable Electronics Market
Wearable Technology
Wearable Technology and IoT Wearable Device Market
Wearable Technology
Smart Necklace Market
Wearable Technology
Bluetooth Wearable Scanner Market
Wearable Technology
Global Wearable Materials Market
Wearable Technology
Wearable Smart Device Market
Wearable Technology
Kids Smart Watch Market
Wearable Technology
Wearable Technology Market
Wearable Technology
Asia Pacific Smartwatch Market
Wearable Technology
Wearable Computing Devices Market
Wearable Technology
3D Printed Wearables Market